
 Resist Strip System Market | 2026-2036
Resist Strip System Market Size, Share, and Industry Trends Forecast 2026-2036
Resist Strip System Market Analytics
Market Context
South Korea is narrowing the equipment supply gap through aggressive fab expansion near Pyeongtaek. Lam Research Corp. leverages its plasma etch heritage to extend into adjacent strip applications. Applied Materials Inc. dominates backend integration with its broad process portfolio. SUSS MicroTec Group specializes in batch wet strip systems for compound semiconductor wafers.
Technical and Segment Structure
Resist strip systems remove photoresist layers from semiconductor wafers, MEMS devices, and printed circuit boards using solvent dissolution, plasma ashing, or chemical oxidation at temperatures typically ranging from 25°C to 250°C depending on process chemistry. Plasma strippers command the fastest expansion as advanced nodes below 7nm reject solvent residues that contaminate critical dimensions. Solvent strippers still anchor mature node production where cost-per-wafer sensitivity favors established chemistries. Semiconductor foundries represent the deepest margin pool, while photovoltaics applications compete primarily on throughput metrics.
Regulatory Environment
EPA hazardous air pollutant standards constrain perchloroethylene and N-methyl-2-pyrrolidone discharge from wet strip operations in US-based fabs. REACH substance restrictions in Europe accelerate substitution toward fluorinated and hydrogen peroxide-based chemistries. OSHA permissible exposure limits for glycol ethers shape equipment enclosure specifications and automated handling requirements. Stakeholders must monitor evolving chemical substance lists across EPA, ECHA, and national regulators to anticipate retrofit cycles and chemistry qualification timelines.
Market Dynamics
Plasma ashing technology is digitizing process control across semiconductor fabrication, compressing cycle times while EPA and REACH mandates accelerate chemistry substitution timelines. Foundry capital deployment in East Asia tightens equipment availability, reshaping vendor-customer contracting terms.
Growth Catalysts
- Node Migration Below 7nm:Advanced logic fabs reject solvent residues that distort critical dimensions, pulling single-wafer plasma stripper demand from Taiwan and South Korea contract manufacturers.
- EPA Hazardous Air Pollutant Standards:Perchloroethylene discharge limits force wet-to-dry process conversion in US-based fabs, expanding addressable market for closed-loop plasma systems.
- Compound Semiconductor Expansion:Silicon carbide and gallium nitride wafer processing for power electronics and RF applications requires specialized batch strip chemistries, opening adjacent equipment demand.
Market Restraints
- Fluorinated Chemistry Supply Concentration:Three Japanese chemical suppliers control high-purity NF3 and CF4 feedstock for plasma generation, exposing strip tool OEMs to input cost volatility and allocation risk.
- CAPEX Intensity at Mature Nodes:200mm and legacy 300mm fabs operate on decade-old depreciation schedules, delaying plasma stripper replacement despite chemistry compliance deadlines.
- Technical Limitation in MEMS Release:Plasma ashing damages delicate polysilicon structures in accelerometer and gyroscope manufacturing, constraining solvent substitution in this end-use.
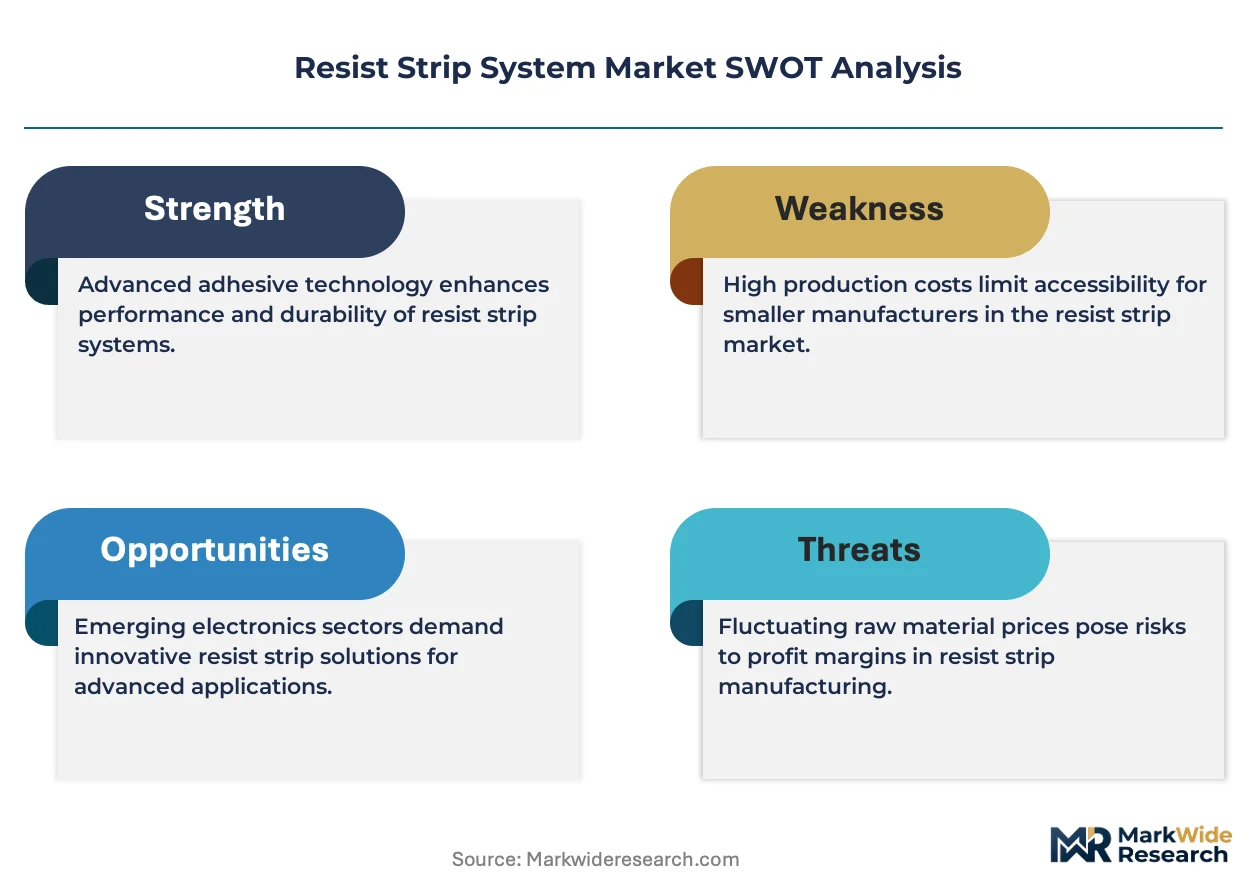
Strategic Opportunities
- India Semiconductor Mission Incentives:PLI scheme subsidies for domestic fab construction create first-mover advantage for strip tool vendors qualifying local service infrastructure.
- Photovoltaic Cell Metallization:Screen-printed silver paste removal from TOPCon and heterojunction cells represents throughput-sensitive strip application with distinct equipment specifications.
- Hydrogen Peroxide-Based Chemistry Convergence:REACH-registered peroxide formulations enable wet strip tool retrofit rather than full replacement, extending vendor aftermarket revenue streams.
Industry Challenges
- Process Engineer Talent Scarcity:Plasma physics and surface chemistry expertise concentrates at established fabs in Hsinchu and Pyeongtaek, complicating new site commissioning in greenfield locations.
- Multi-Tool Integration Complexity:Strip modules must synchronize with track, etch, and inspection equipment in cluster tool configurations, extending qualification timelines for new OEM entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resist Strip System Market |
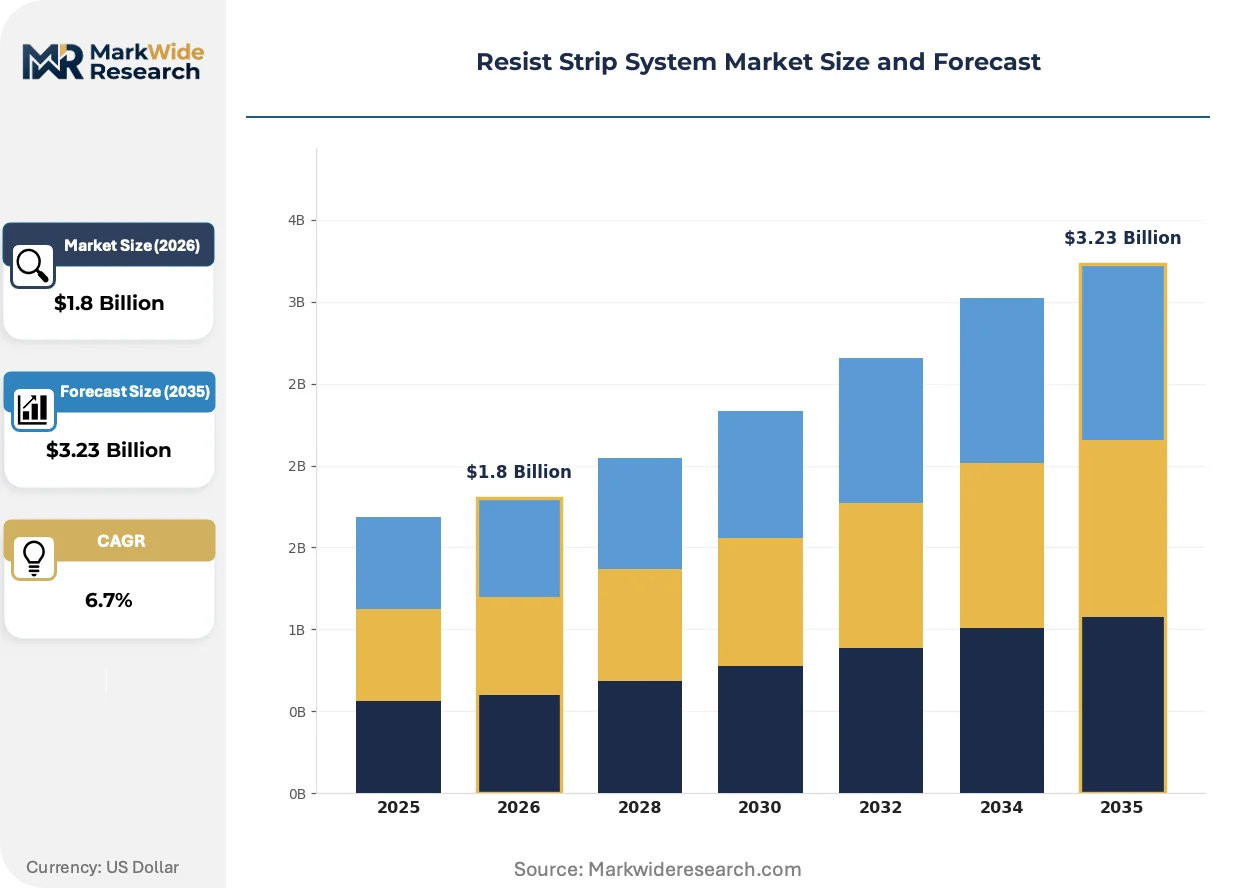
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Strippers, Plasma Strippers, Chemical Strippers, Physical Strippers Application: Semiconductors, MEMS, Printed Circuit Boards, Photovoltaics End User: Electronics Manufacturers, Semiconductor Foundries, Research Institutions, Aerospace Firms Distribution Channel: Online Retailers, Specialized Distributors, Direct Sales, Others |
| Companies Covered | Samco Inc., SUSS MicroTec Group, JST, PSK Inc., PVA TePla America, Mattson Technology Inc., DuPont, Applied Materials Inc., Lam Research Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resist Strip System Market Evolving Landscape
Real-time spectral endpoint detection and machine learning-based recipe optimization are compressing process development cycles. Equipment vendors embed predictive maintenance algorithms to reduce unplanned downtime in high-volume manufacturing environments.
Downstream mass spectrometry is digitizing residue detection during plasma strip operations. Memory fabs in South Korea deploy these systems to monitor fluorocarbon byproduct levels, preventing chamber conditioning drift that degrades wafer-to-wafer uniformity. The technology compresses qualification time for new chemistries by 40 percent.
REACH substance restriction updates are accelerating fluorinated gas substitution in European fabs. The F-Gas Regulation phase-down mandates hydrofluorocarbon emission reporting, pushing equipment buyers toward abatement-integrated strip tools. German automotive semiconductor suppliers now specify plasma systems with thermal oxidizer add-ons to secure supply chain sustainability certifications.
Consolidated procurement through foundry alliance purchasing desks is compressing vendor negotiation cycles. TSMC and Samsung Foundry centralize strip tool selection across multiple greenfield sites, replacing site-by-site technical evaluation with master equipment agreements. This pattern concentrates most acutely in Taiwan where contract manufacturers coordinate capacity expansion timelines.
Resist Strip System Market Segmentation
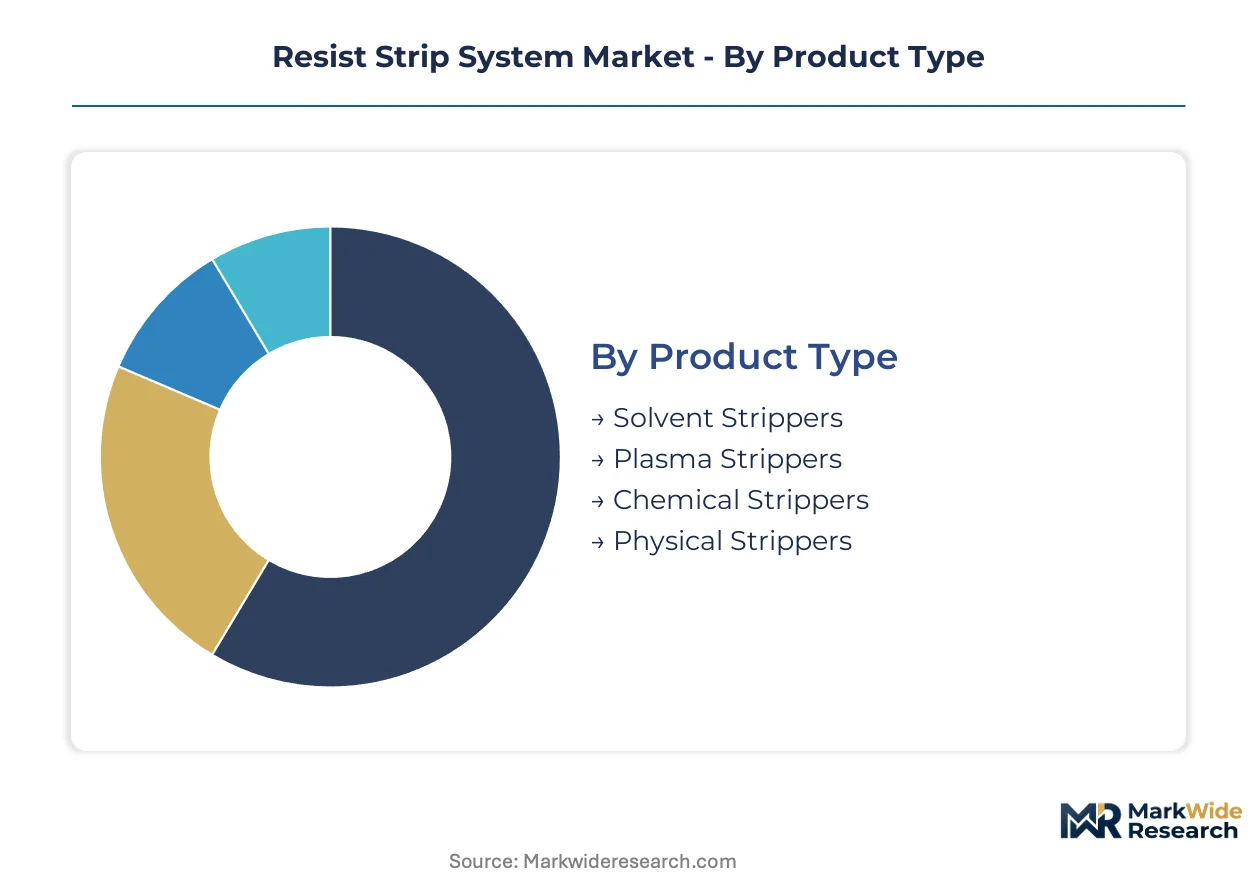
Equipment replacement cycles vary dramatically across strip system categories, with plasma tools refreshing every 4-5 years while solvent platforms persist for 8-12 years in cost-sensitive fabs. Understanding these differential turnover rates shapes vendor forecasting and aftermarket service planning.
Product Type:
Plasma strippers compress cycle times through digital process control while solvent systems extend depreciation schedules in mature node operations.
- Solvent Strippers:Wet chemistry platforms using N-methyl-2-pyrrolidone, dimethyl sulfoxide, or proprietary blends to dissolve photoresist through immersion or spray processing. Demand concentrates at 200mm fabs in Malaysia and legacy 300mm facilities where cost-per-wafer sensitivity overrides residue concerns, though EPA discharge limits are forcing accelerated replacement timelines.
- Plasma Strippers:Single-wafer or batch systems generating oxygen, fluorine, or hydrogen-based plasmas to ash organic residues through gas-phase oxidation. Taiwan and South Korea foundries drive procurement as advanced nodes below 7nm reject solvent contamination that distorts critical dimensions, pulling rapid upgrade cycles.
- Chemical Strippers:Sulfuric acid-hydrogen peroxide mixtures or ozonated water systems for specialized oxide-compatible removal.
- Physical Strippers:Megasonic or cryogenic aerosol methods for damage-sensitive compound semiconductor wafers.
Solvent strippers anchor the volume base while plasma strippers gain share at the steepest rate.
Application:
Process complexity and contamination tolerance create four distinct equipment specification tiers across downstream uses.
- Semiconductors:Logic and memory fabrication requiring sub-nanometer residue control, chamber-to-chamber matching, and real-time endpoint detection. Hsinchu and Pyeongtaek clusters concentrate demand as TSMC and Samsung Foundry expand 3nm and 2nm capacity, specifying single-wafer plasma systems with integrated metrology.
- MEMS:Accelerometer, gyroscope, and microphone manufacturing where plasma damage to polysilicon structures constrains solvent substitution despite regulatory pressure. Bosch and STMicroelectronics fabs in Germany and France maintain hybrid wet-dry configurations.
- Printed Circuit Boards:Dry film and liquid photoresist removal from copper-clad laminates using conveyorized spray or immersion systems.
- Photovoltaics:Screen-printed silver paste stripping from TOPCon and heterojunction cells where throughput metrics dominate equipment selection.
Semiconductor applications command premium pricing while photovoltaics compete on capital efficiency per wafer.
End User:
Procurement sophistication and technical specification depth separate four customer archetypes with diverging vendor engagement models.
- Semiconductor Foundries:TSMC, Samsung Foundry, and GlobalFoundries operate centralized purchasing desks negotiating master equipment agreements across multiple greenfield sites, replacing site-by-site qualification with standardized platform selection.
- Electronics Manufacturers:IDMs and OSATs managing heterogeneous process portfolios with fragmented tool procurement.
- Research Institutions:Universities and national laboratories prioritizing flexibility over throughput for process development.
- Aerospace Firms:Defense contractors with specialized radiation-hardened device requirements and extended qualification protocols.
Foundries concentrate purchasing power while research institutions generate technology pipeline opportunities.
Distribution Channel:
Equipment complexity and service intensity shape channel selection across customer segments and geographies.
- Direct Sales:Lam Research, Applied Materials, and Tokyo Electron maintain field application engineering teams co-located at major fabs, handling specification negotiation, installation, and process qualification. This channel captures high-value plasma stripper transactions in Taiwan and South Korea.
- Specialized Distributors:Regional technical distributors stocking wet chemistry systems and consumables for mid-tier electronics manufacturers in Southeast Asia and Eastern Europe.
- Online Retailers:Limited to standard components, spare parts, and refurbished equipment.
- Others:Auction houses and broker networks for decommissioned 200mm equipment.
Direct sales dominate high-complexity transactions while distributors extend geographic reach for standardized platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and REACH chemical restrictions are reshaping equipment procurement across major fabrication clusters, with East Asian contract manufacturers tightening supply availability through aggressive capacity expansion.
United States
Domestic logic and memory fabs in Arizona and Texas are accelerating wet-to-dry process conversions. EPA hazardous air pollutant standards for perchloroethylene discharge force retrofits of legacy solvent strip systems. Intel's expanding presence in Chandler and Samsung's Taylor facility anchor plasma stripper demand.
South Korea
Samsung Foundry and SK Hynix are scaling 3nm and 2nm capacity near Pyeongtaek, specifying single-wafer plasma systems with integrated metrology. MFDS chemical registration requirements shape feedstock qualification timelines. The Yongin semiconductor cluster is attracting strip tool vendor field service expansion.
Taiwan
TSMC's centralized purchasing desk negotiates master equipment agreements across greenfield sites in Tainan and Taichung. REACH-registered chemistry substitutions influence solvent platform replacement cycles. The Hsinchu Science Park concentrates process engineering talent and vendor application engineering teams.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor domestic supply chains for high-purity NF3 and CF4 feedstocks. METI semiconductor revitalization subsidies support 300mm legacy fab modernization. The Kyushu region hosts specialized batch strip system demand for compound semiconductor wafer processing.
Germany
Bosch and Infineon fabs in Dresden and Reutlingen maintain hybrid wet-dry configurations for MEMS and power semiconductor manufacturing. The F-Gas Regulation phase-down mandates hydrofluorocarbon emission reporting from plasma strip operations. Automotive semiconductor suppliers specify abatement-integrated tools for supply chain sustainability certifications.
Resist Strip System Market Competitive Landscape
Plasma technology specialists and solvent platform incumbents split the market along node migration boundaries. The vendor base concentrates around equipment integration capabilities and chemistry qualification speed. Three archetypes dominate: integrated process equipment conglomerates, batch wet strip specialists, and plasma physics-focused innovators. Consolidation pressure intensifies through foundry alliance purchasing desks and chemistry supply concentration.
Among Japanese precision equipment fabricators, Samco Inc. and PSK Inc. occupy positions within the plasma strip system tier. SUSS MicroTec Group exemplifies the batch wet strip specialist archetype for compound semiconductor applications. Lam Research Corp. and Applied Materials Inc. anchor the integrated conglomerate segment with broad process portfolios extending into adjacent strip applications.
| Leading Market Players |
|---|
| Samco Inc. |
| SUSS MicroTec Group |
| JST |
| PSK Inc. |
| PVA TePla America |
| Mattson Technology Inc. |
| DuPont |
| Applied Materials Inc. |
| Lam Research Corp. |
| Others |
Value Network & Pricing Analysis
Hsinchu Science Park capacity expansion dynamics compress equipment availability timelines, amplifying vendor pricing leverage in single-wafer plasma stripper negotiations. Foundry alliance purchasing desks at TSMC and Samsung Foundry counterbalance this through master equipment agreements that standardize platform selection across greenfield sites.
Pricing Analysis
East Asian contract manufacturers face 15-20% price premiums versus European and North American fabs due to logistics intensity and field service co-location requirements. Three-tier pricing structure across premium, standard, and economy levels separates integrated metrology plasma systems from batch wet chemistry platforms and refurbished 200mm solvent tools. Cost compression in mature node equipment is intensifying because EPA discharge compliance deadlines force premature depreciation of solvent platforms. Photovoltaic cell manufacturers exhibit highest price sensitivity, while semiconductor foundries prioritize chamber matching specifications over unit economics.
Supply Chain Analysis
High-purity NF3 and CF4 feedstock for plasma generation draws from Japanese chemical suppliers in Kawasaki and Oita prefectures, with Shin-Etsu Chemical and Kanto Denka Kogyo anchoring regional production. Specialty gas purification equipment and quartz chamber components hinge on Taiwan and South Korean fabrication capabilities. Single-source vulnerability in fluorinated chemistry feedstock exposes strip tool OEMs to allocation risk during fab ramp cycles. Distribution runs through direct field application engineering teams co-located at major fabs, with regional technical distributors extending reach for wet chemistry consumables in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma ashing technology digitization disrupts established wet chemistry depreciation schedules, while REACH and EPA mandates compress qualification timelines for alternative chemistries. This dual inflection creates asymmetric opportunity for vendors with rapid chemistry certification capabilities.
For Market Incumbents: Insulate plasma stripper margins through captive supply arrangements for high-purity fluorinated feedstocks, mitigating Japanese chemical supplier concentration risk. Accelerate hydrogen peroxide-based wet chemistry retrofit kits to extend solvent platform service revenue before EPA perchloroethylene deadlines force full replacement cycles. Prioritize field service infrastructure lock-in at emerging India Semiconductor Mission sites to preempt entrant challenges. For New Entrants and Emerging Players: Build out localized service capabilities in Gujarat and Karnataka to capture India PLI scheme fab construction demand before Lam Research and Applied Materials consolidate field engineering presence. Target photovoltaic cell metallization strip applications where throughput specifications differ from semiconductor residue control requirements, enabling equipment architecture differentiation. Pursue joint development agreements with TOPCon cell manufacturers to establish reference installations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial gas conglomerates with under-monetized semiconductor equipment divisions, particularly European suppliers with REACH-registered chemistry portfolios but limited strip tool integration. Long-term viability centers on chemistry qualification speed rather than equipment hardware differentiation, favoring targets with established ECHA and EPA regulatory affairs capabilities. Monitor MFDS chemical registration timelines in South Korea as inflection indicator for feedstock supply constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorinated Gas Substitution R&D | REACH F-Gas Regulation phase-down mandates hydrofluorocarbon emission reporting from plasma strip operations in European fabs. |
| India Service Infrastructure Buildout | PLI scheme subsidies for domestic fab construction create first-mover advantage for strip tool vendors qualifying local support. |
| Hydrogen Peroxide Chemistry Retrofit | REACH-registered peroxide formulations enable wet strip tool retrofit rather than full replacement, extending aftermarket revenue. |
| Real-Time Endpoint Detection Integration | Downstream mass spectrometry deployment in South Korean memory fabs compresses new chemistry qualification timelines by 40 percent. |
| Abatement-Integrated Tool Development | German automotive semiconductor suppliers now specify plasma systems with thermal oxidizer add-ons for sustainability certifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC equipment vendor filings, EPA hazardous air pollutant enforcement data, and ECHA REACH substance restriction updates. Process engineering directors at Taiwan and South Korean foundries, plasma strip tool procurement managers, and fluorinated gas supply specialists provided operational perspective. Customs trade data for NF3 and CF4 feedstock flows, METI semiconductor equipment production statistics, and MFDS chemical registration databases supplied quantitative anchors. Bottom-up equipment shipment tracking triangulates against top-down fab capex disclosure analysis.
Forecast inputs span wafer processing capacity expansion announcements, node migration timelines below 7nm, and regulatory compliance deadline schedules across the projection horizon. Segmentation dimensions include strip technology type, application complexity tier, end-user procurement sophistication, and regional regulatory framework cluster. CAGRs derive from equipment replacement cycle analysis differentially applied to plasma versus solvent platform persistence periods. Chemistry substitution velocity and foundry alliance purchasing desk consolidation patterns inform demand elasticity assumptions.
Stress conditions across fluorinated feedstock allocation disruption, EPA enforcement intensity variation, and India fab construction delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding node migration pace and regulatory deadline adherence. Quarterly review of ECHA substance restriction proposal timelines and MFDS chemical registration queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Global Bioelectronics Market
Electronic Systems and Devices
Stand-Alone Video Processors Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Embedded Controllers Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Global Embedded Systems Market