
 Head Up Display Market | 2026-2036
Head Up Display Market Size, Share, and Industry Trends Forecast 2026-2036
Head Up Display Market Intelligence
Expanded manufacturing capacity for advanced displays in South Korea is fragmenting the supply base for microelectronic components. Continental AG leverages its system integration expertise to secure contracts with major automotive OEMs in Europe and North America. Nippon Seiki Co., Ltd. sustains its leadership within the Japanese automotive cluster market. BAE Systems dominates the military segment with specialized display solutions for avionics.
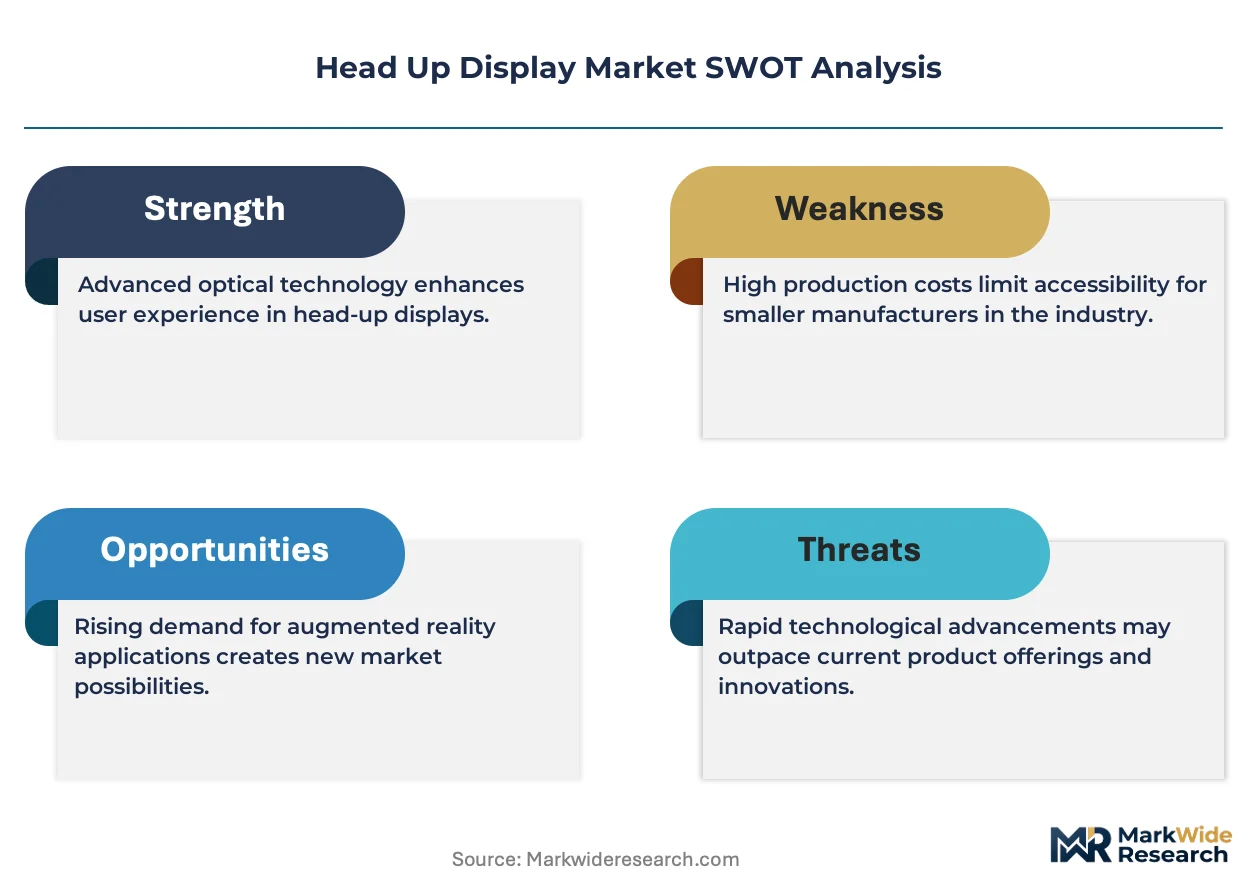
A head-up display is an optical system projecting data onto a transparent screen, such as a vehicle's windshield or a dedicated combiner, in the user's line of sight. Its primary purpose is to present critical information without requiring a downward glance from the operational environment. Augmented Reality models are displacing conventional units, particularly in the premium automotive OEM segment where enhanced features are a key differentiator. These systems are primarily driven by safety applications, integrating navigation and advanced driver-assistance system alerts.
Product development adheres to safety criteria from bodies like the US NHTSA and requires CE marking in Europe. Functional safety standards, including ISO 26262, are critical for automotive HUDs, influencing component selection and software validation. The key decision for developers is balancing AR features with the operator's cognitive load to ensure safety.
Market Dynamics
The market's trajectory is defined by the convergence of augmented reality software with advanced optical hardware. This integration, driven by automotive safety mandates and consumer demand for sophisticated in-cabin experiences, is shifting product development from simple data projection to immersive, context-aware interfaces.
Growth Catalysts
- Functional Safety Mandates:The enforcement of functional safety standards like ISO 26262, alongside guidance from bodies like the US NHTSA, compels the integration of ADAS alerts into the driver's primary field of view, directly benefiting HUD adoption.
- Micro-Display Technology:Advances in micro-LED and Digital Light Processing (DLP) technologies, particularly from manufacturing centers in South Korea and Taiwan, are improving brightness, resolution, and thermal performance while reducing component size.
- Automotive UX Differentiation:In established automotive hubs like Germany and Japan, premium automakers are increasingly using large, feature-rich AR HUDs as a primary differentiator to enhance the driver experience and justify premium pricing.
Market Restraints
- High System Cost:The bill of materials for AR HUDs, including complex projector units, powerful processing hardware, and specialized windshields, remains a significant barrier to adoption in high-volume, cost-sensitive economy and mid-range vehicle segments.
- Cognitive Load Concerns:There is a fundamental technical limit to the amount of information a driver can safely process. Developing AR interfaces that provide useful data without creating distraction or information overload is a persistent human-factors engineering challenge.
- Windshield Integration Complexity:Projecting a clear, distortion-free image requires a specialized windshield with a precise wedge angle and coating. This adds cost, complexity, and weight, and complicates aftermarket replacement logistics for insurers and service centers.
Strategic Opportunities
- Adjacent Mobility Applications:Significant opportunity exists in adapting HUD technology for other mobility sectors, including commercial trucking, public transit, and two-wheeler vehicles in markets like India, where rider safety is a major concern.
- V2X Integration:The convergence of HUDs with Vehicle-to-Everything (V2X) communication technology presents an opportunity to display real-time alerts about road hazards, traffic light timing, and vulnerable road users detected beyond the vehicle's onboard sensors.
- Aftermarket and Retrofit Solutions:Developing cost-effective combiner-based HUD units for the automotive aftermarket provides access to a large existing vehicle parc, especially for older models lacking factory-installed advanced safety features.
Industry Challenges
- Software Validation Cycles:The complexity of AR rendering software and its integration with multiple vehicle sensors requires extensive validation and verification to comply with automotive functional safety standards, significantly extending development timelines.
- Optical Engineering Talent:A scarcity of engineers with dual expertise in automotive-grade optical design and real-time embedded systems creates a talent bottleneck, slowing down innovation and increasing labor costs for system developers.
- Supply Chain Bottlenecks:Reliance on a concentrated number of suppliers for critical components like picture generation units (PGUs) and custom optical elements creates vulnerability to supply chain disruptions and limits negotiating power for smaller Tier 1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head Up Display Market |
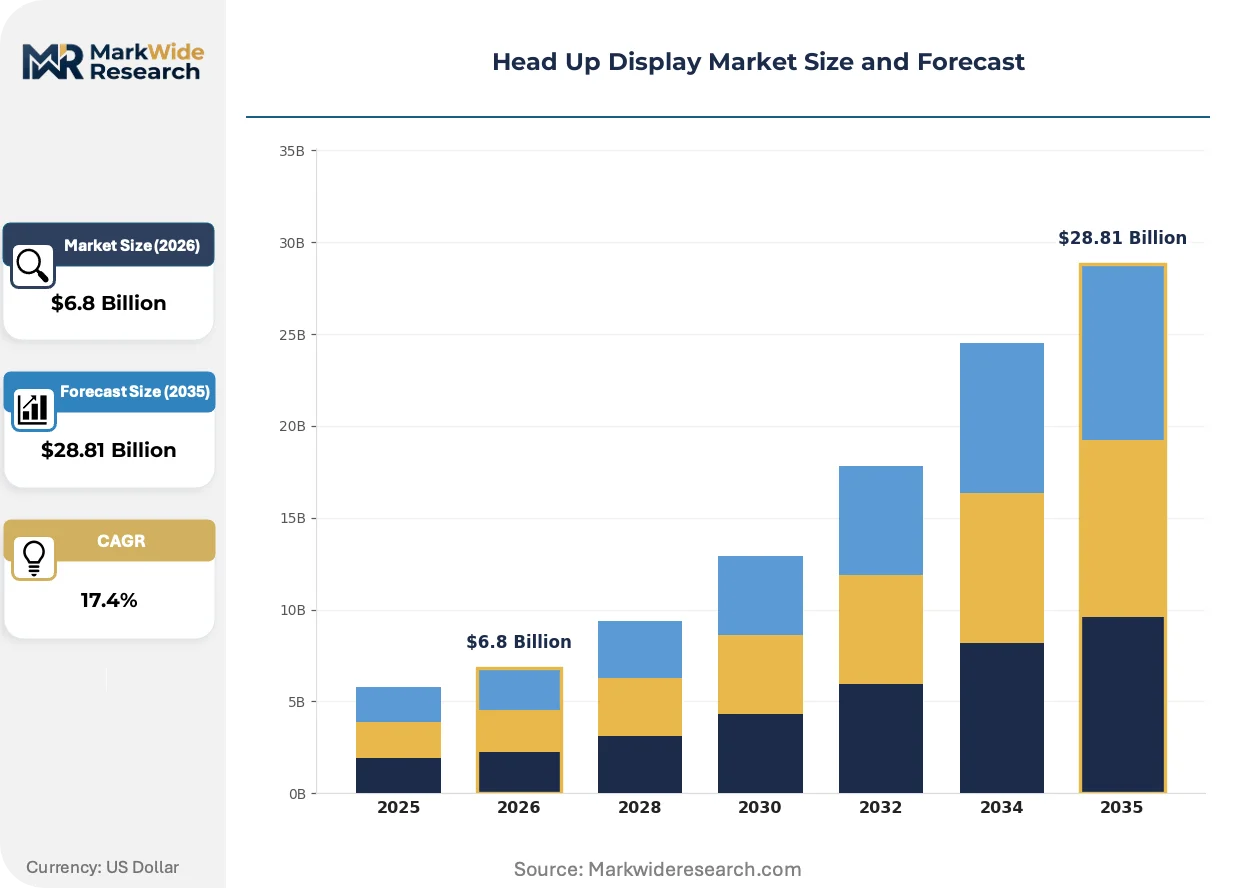
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Augmented Reality, OLED, LCD End User: Aerospace, Automotive OEMs, Military, Consumer Electronics Technology: Laser, Microelectronic, Projection, Digital Application: Navigation, Gaming, Training, Safety |
| Companies Covered | Nippon Seiki Co., Ltd., Continental AG, DENSO Corporation, Valeo, Panasonic Holdings Corporation, BAE Systems, Yazaki Corporation, Robert Bosch GmbH, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head Up Display Market Strategic Shifts & Innovations
Product evolution is moving beyond static information displays toward dynamic, environmentally-aware systems. This shift transforms the head-up display from a simple data repeater into a central component of the vehicle's human-machine interface, deeply integrated with sensor fusion and navigation platforms.
Waveguide and light-field projection are the core optical technologies enabling next-generation AR displays. The premium automotive segment is adopting these systems to create a larger virtual image distance and field of view. This advanced optical technology is hybridizing the driver's physical view of the road with a digital overlay of contextual navigation and safety information, creating a more intuitive and immersive experience.
Europe's General Safety Regulation (GSR) is accelerating the adoption of ADAS features across all new vehicle types. This regulation indirectly promotes HUDs as an effective means for presenting critical alerts from mandated systems, such as lane-keeping assist and intelligent speed assistance, without requiring driver distraction. The passenger car segment in the EU is most affected, with automakers integrating HUDs to meet safety targets and improve Euro NCAP ratings.
Consumer preference is shifting toward vehicles that offer a superior in-cabin technology experience, often prioritized over traditional performance metrics. This trend disrupts the fixed-function hardware model in favor of software-defined architectures where HUD features can be enhanced via over-the-air (OTA) updates. This demand for a rich user experience is most visible in the global electric vehicle segment, where new entrants compete on the strength of their digital interfaces.
Head Up Display Market Segmentation
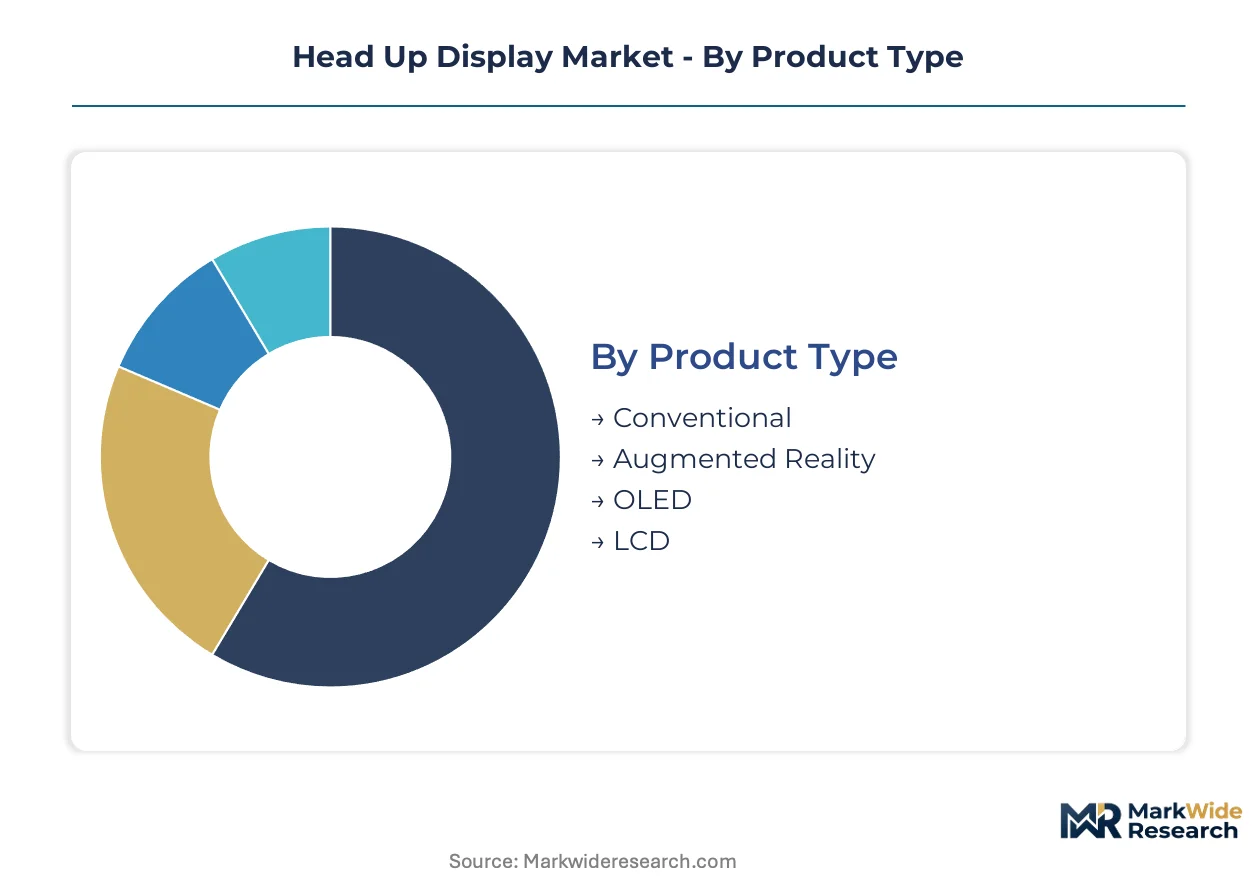
The segmentation analysis of the head-up display market reveals distinct value propositions and growth trajectories across various dimensions. Understanding these segments is critical for identifying specific market opportunities and tailoring product development strategies. Each category reflects unique technological requirements and end-user demands.
Product Type:
The product type spectrum for head-up displays spans from basic information projection to highly interactive environmental overlays.
- Augmented Reality:These systems superimpose digital information directly onto the real-world view, enhancing driver perception with contextual navigation and ADAS alerts. Demand is concentrating in premium automotive OEM segments in Germany and Japan, driven by differentiation and safety mandates.
- Conventional:Traditional head-up displays project static or semi-static data like speed and basic navigation cues onto a transparent surface. Demand remains steady in mid-range automotive models, where cost-effectiveness and basic safety enhancements are prioritized.
- OLED:Organic Light-Emitting Diode technology offers high contrast and true black levels for display units, primarily in combiner-based HUDs.
- LCD:Liquid Crystal Display units provide a cost-effective solution for displaying information in various HUD configurations, including some automotive applications.
Established volume favors Conventional units; emerging adoption favors Augmented Reality systems.
End User:
End-user segmentation highlights the diverse operational environments and regulatory requirements influencing head-up display deployment.
- Automotive OEMs:Vehicle manufacturers integrate HUDs directly into new car designs, primarily for driver safety, navigation, and in-cabin experience. Demand is concentrated in established automotive manufacturing hubs in Europe and North America.
- Military:Specialized HUDs provide critical flight and tactical data for pilots and ground personnel in demanding operational theaters. BAE Systems dominates this segment with advanced avionics solutions.
- Aerospace:Commercial and general aviation utilize HUDs to display essential flight parameters, improving pilot situational awareness during critical phases of flight.
- Consumer Electronics:This segment includes aftermarket devices and specialized smart glasses, offering data projection for personal use cases outside traditional vehicle applications.
Demand concentration shifts from specialized Military and Aerospace applications to high-volume Automotive OEMs.
Technology:
The underlying technology defines the performance characteristics and integration complexity of head-up display systems.
- Projection:This technology involves a light source, a picture generation unit, and optical elements to cast an image onto the display surface. Advances in micro-LED and DLP technologies are improving brightness and resolution.
- Microelectronic:Core microelectronic components, including ASICs and microcontrollers, are essential for processing sensor data and rendering digital content for the display. Supply chain fragmentation for these components affects display manufacturers.
- Laser:Laser-based systems offer high brightness and color gamut, suitable for specific high-performance or specialized display applications.
- Digital:This encompasses the software and digital processing units responsible for rendering graphics, integrating sensor fusion, and managing the user interface.
Innovation in Projection methods is driving advancements while Microelectronic components provide foundational support.
Application:
Application areas illustrate the primary functionalities and user benefits derived from head-up display integration.
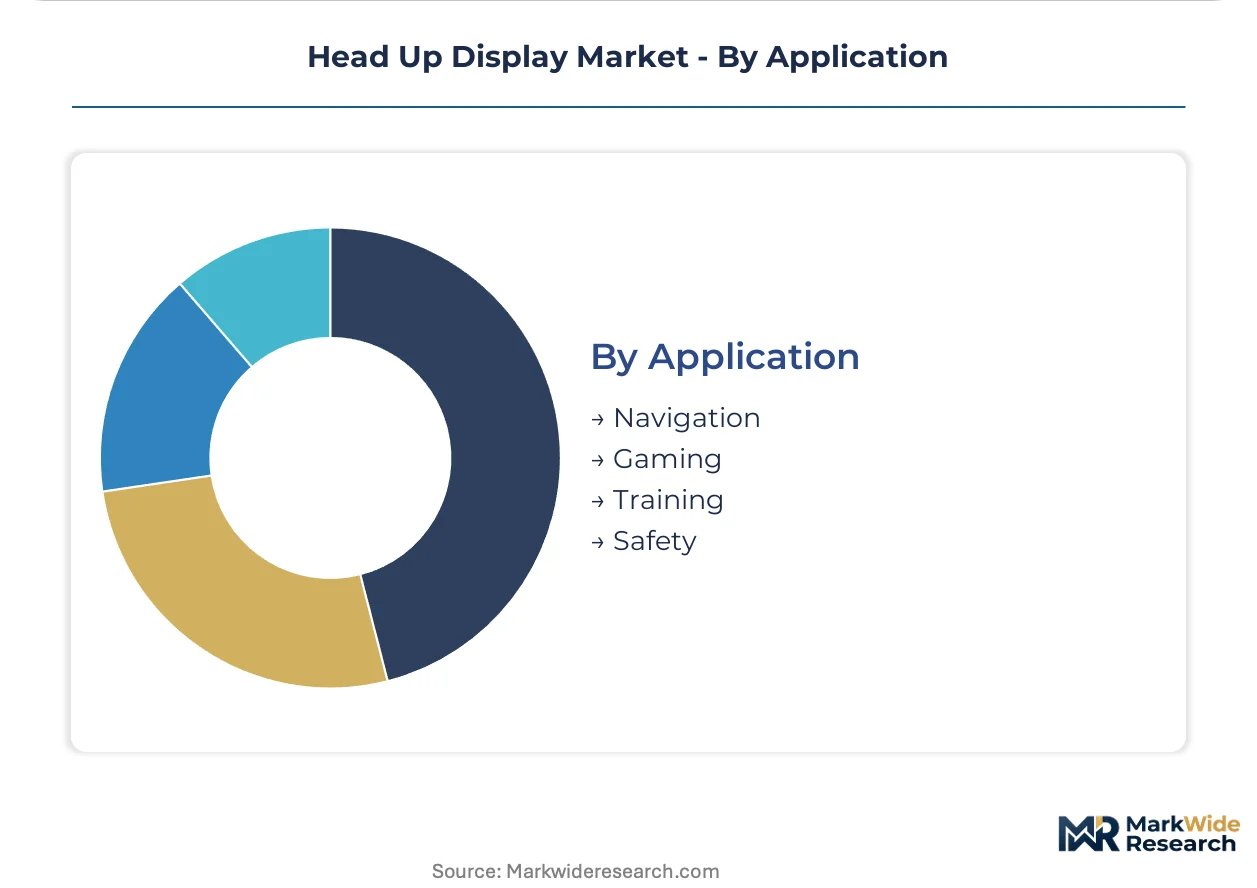
- Safety:HUDs display critical alerts from ADAS, navigation, and V2X systems directly in the driver's line of sight, reducing cognitive load. This application is a primary driver for adoption in the European passenger car segment due to GSR mandates.
- Navigation:These systems project turn-by-turn directions, lane guidance, and points of interest onto the windshield or combiner. Demand is strong in consumer vehicles seeking enhanced driving convenience.
- Training:HUDs are integrated into simulators and specialized training devices to provide immersive and realistic operational scenarios for pilots and vehicle operators.
- Gaming:Emerging applications leverage HUD technology for immersive gaming experiences, often in virtual or augmented reality headsets.
The integration of Safety features is expanding most quickly, complementing established Navigation functionalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for head-up displays varies significantly by region, with established automotive markets prioritizing advanced safety features and emerging markets focusing on basic navigation and aftermarket solutions. European and Asian automotive hubs drive demand for premium AR HUDs, while other regions explore adjacent mobility applications. This geographic differentiation influences product development and market penetration strategies.
Germany
Demand for advanced augmented reality head-up displays is strong among premium automotive OEMs in Germany, driven by a focus on in-cabin experience and vehicle differentiation. Functional safety standards, including ISO 26262, are critical for HUD integration, influencing component selection. The Bavaria region, home to major automakers, serves as a hub for advanced automotive display research and development.
Japan
Japanese automotive manufacturers prioritize the integration of HUDs for enhanced driver safety and navigation within their vehicle designs. The Ministry of Economy, Trade and Industry (METI) supports technological advancements in display components, fostering innovation. The Aichi Prefecture, a core automotive cluster, exhibits high demand for sophisticated display solutions in new vehicle models.
South Korea
Micro-display technology advancements, particularly in micro-LED and DLP, originate from South Korea, supporting high-resolution HUD systems. The country's robust electronics manufacturing sector, influenced by government R&D incentives, provides critical components for display units. Seoul and Gyeonggi Province house key suppliers of microelectronic components, contributing to the global HUD supply chain.
United States
Automotive OEMs in the United States integrate head-up displays primarily for safety applications, aligning with guidance from the US NHTSA for advanced driver-assistance systems. Consumer preference for sophisticated in-cabin technology also fuels demand for feature-rich HUDs. Michigan's automotive industry, centered around Detroit, is a significant market for new HUD installations in vehicles.
India
Adjacent mobility applications for HUD technology, especially in two-wheeler vehicles, present a significant opportunity in India due to rider safety concerns. The government's push for safer road infrastructure and vehicle technology encourages innovation in display solutions. Major metropolitan areas like Pune and Chennai, with their growing automotive and manufacturing bases, are exploring new HUD deployments.
Head Up Display Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure for head-up display systems. The market features a mix of established automotive suppliers, specialized display technology firms, and defense contractors. These players employ strategic partnerships and portfolio diversification to maintain their market positions.
Among the established automotive suppliers, Continental AG and Robert Bosch GmbH exemplify the integration of complex electronic systems and software into vehicle platforms. Nippon Seiki Co., Ltd. represents a specialist in display technology, anchoring its position within the Japanese automotive cluster market. BAE Systems, a defense contractor, occupies a distinct segment with specialized display solutions for military avionics.
| Leading Market Players |
|---|
| Nippon Seiki Co., Ltd. |
| Continental AG |
| DENSO Corporation |
| Valeo |
| Panasonic Holdings Corporation |
| BAE Systems |
| Yazaki Corporation |
| Robert Bosch GmbH |
| Thales Group |
| Others |
Cost & Logistics Intelligence
The Pacific shipping lanes' freight costs for micro-display components directly influence pricing power for Asian suppliers and create differentiation in premium AR HUD systems. This cost dynamic impacts downstream vehicle pricing.
Pricing Analysis
Geographic price spreads are notable between established automotive hubs in Germany and Japan, where premium AR HUDs command higher prices, and regions focusing on conventional units. Pricing stratifies across premium, standard, and economy tiers, reflecting customization levels and ISO 26262 certification requirements. Cost compression in mid-range vehicle segments is intensifying due to the high bill of materials for advanced systems. Premium automotive OEMs exhibit lower price sensitivity compared to economy segment buyers.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often support the concentrated microelectronic component suppliers in South Korea and Taiwan. The supply chain draws from these countries for micro-LEDs and DLP chips, alongside specialized optical elements from Germany and Japan. Single-source vulnerability for critical picture generation units presents a structural risk. Distribution runs through direct channels to automotive OEMs for factory-installed systems and via aftermarket distributors for retrofit solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Head Up Display market represents a high-growth disruption, driven by the convergence of augmented reality software with advanced optical hardware. Europe's General Safety Regulation acts as a key regulatory inflection point.
For Market Incumbents: Build intellectual property moats around advanced optical design and AR rendering algorithms to counter emerging specialist threats. Deepen system integration expertise to secure long-term contracts with major automotive OEMs in Europe and North America. Invest in R&D for next-generation waveguide technology to address cognitive load concerns. Pursue ISO 26262 certification to reinforce functional safety leadership.
For New Entrants and Emerging Players: Adjacent mobility applications in markets like India, particularly for two-wheeler vehicles, represent the most penetrable entry point due to rider safety concerns. Cost-effective combiner-based HUD units for the automotive aftermarket offer access to a large existing vehicle parc. Focus go-to-market strategies on delivering essential safety features with optimized system costs. Develop V2X integrated solutions for real-time hazard alerts.
For Investors and Strategic Acquirers: Carve-out targets emerge from established automotive Tier 1 suppliers seeking to divest non-core display technologies. The market shows strong long-term viability over the next 5-10 years, driven by safety mandates and consumer demand. Specialized optical engineering firms and AR rendering software developers represent attractive acquisition archetypes. Maturation of micro-LED production for high-volume automotive integration serves as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Optical R&D | Secures competitive advantage in premium AR HUD systems. |
| Functional Safety Certification | Ensures compliance with strict automotive safety standards. |
| V2X Integration Partnership | Expands real-time driver alert capabilities for enhanced safety. |
| Aftermarket Product Development | Accesses existing vehicle parc for cost-effective safety upgrades. |
| Micro-LED Supply Chain Diversification | Mitigates single-source vulnerability for critical display components. |
Research Approach
A standing panel of automotive OEM engineers, Tier 1 suppliers, optical design specialists, and regulatory compliance officers provided ongoing calibration. This analysis combines primary interviews with secondary validation from US NHTSA reports, Euro NCAP ratings, and METI publications. Bottom-up data aggregation and top-down market sizing triangulated market volume and value.
Scenario bracketing informed the analytical framework across the analysis window, accounting for varying adoption rates. The model segmented by product type, end user, technology, application, and regional production cluster. Compound annual growth rates were derived from historical trends and projected ADAS penetration rates. Vehicle production forecasts served as a critical input.
Macroeconomic conditions sit as an overlay; deviation in global chip supply or automotive OEM investment would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and functional safety regulatory stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Smart Screen Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Flexible Screens Market
Display Technologies
IGZO Display Market
Display Technologies
QLED Display Market
Display Technologies
Rugged Display Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Touch Screen Film Market
Display Technologies
Large Industrial Displays Market
Display Technologies
3D Holographic Display Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Gaming Monitors Market
Display Technologies
Touch Screen Module Market
Display Technologies
Global Wearable Display Market
Display Technologies
Multi-Function Display Market