
 Multimedia Projectors Market | 2026-2036
Multimedia Projectors Market Size, Share, and Industry Trends Forecast 2026-2036
Multimedia Projectors Market Foresight
All-in-one projector bundles integrating wireless casting, built-in speakers, and smart OS platforms is consolidating buyer preferences around simplified procurement. Epson sustains manufacturing scale across LCD panel production, while Sony leverages vertical integration into image sensor and laser light source technologies. Panasonic anchors geographic dominance in Asia-Pacific through localized distribution networks.
Multimedia projectors are electro-optical display devices that modulate light through digital micromirror arrays, liquid crystal panels, or liquid crystal on silicon chips to project enlarged images onto surfaces, with brightness ratings typically spanning 2,000 to 10,000 lumens for commercial viability. DLP technology leads in portable and gaming applications due to compact chip architecture, while LCoS occupies premium home cinema segments where contrast ratios determine buyer willingness to pay. Ultra short throw configurations represent the fastest-growing product type as residential and corporate buyers prioritize space-efficient installation.
EPA ENERGY STAR specifications and EU Ecodesign requirements constrain standby power consumption and lamp efficiency thresholds, directly shaping product development roadmaps for manufacturers seeking transatlantic market access. China's SAMR enforces GB standards for display energy performance, creating compliance differentiation between domestic and export-oriented product lines. Stakeholders must monitor regulatory convergence between efficiency mandates and emerging right-to-repair frameworks that could alter component sourcing and service revenue models.
Market Dynamics
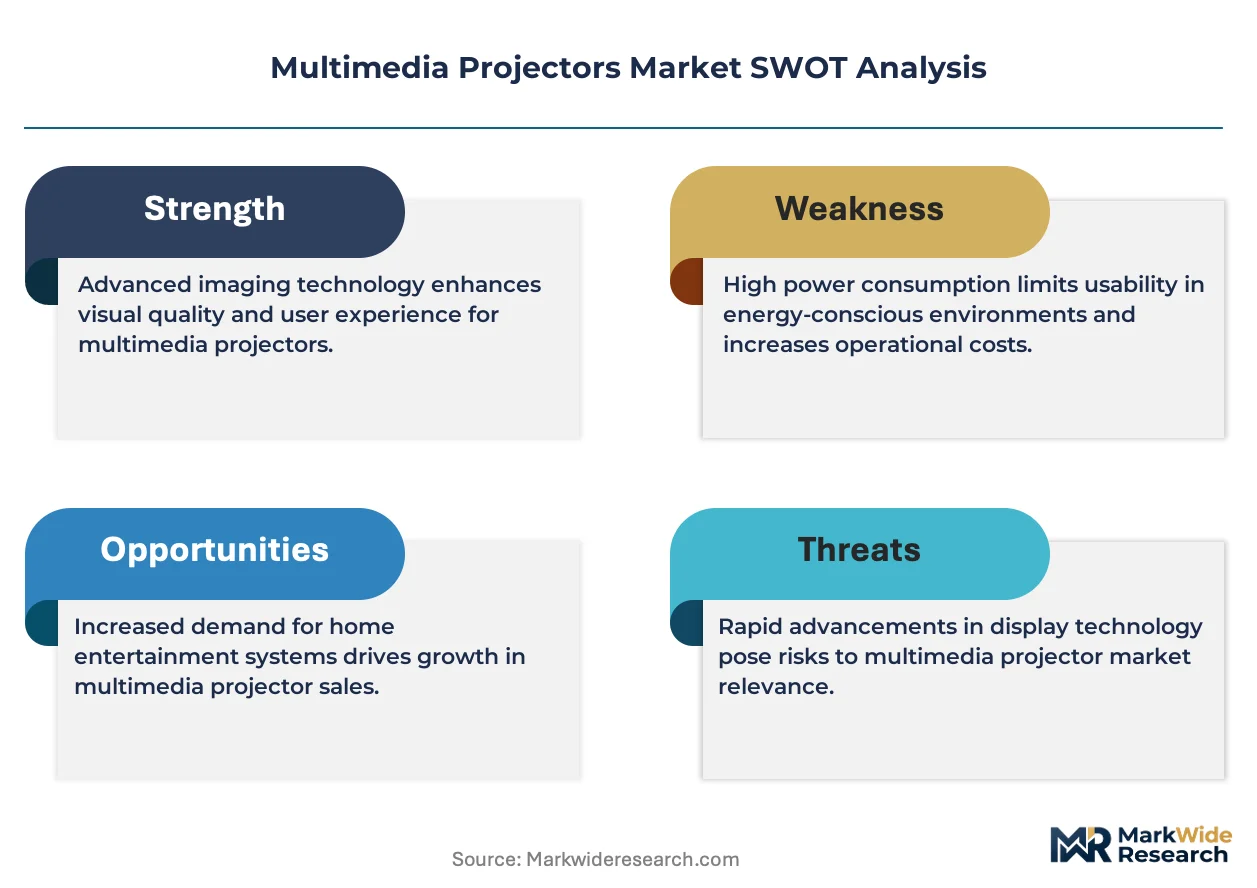
Laser phosphor illumination is compressing lamp replacement cycles while solid-state light engines extend operational lifespan, forcing manufacturers to pivot service revenue models toward software and connectivity subscriptions.
Growth Catalysts
- EU Ecodesign standby power limits:Manufacturers redesign power supplies to meet 0.5W thresholds, accelerating solid-state adoption across commercial installations.
- India education digitization:State procurement of interactive flat-panel alternatives drives unit volume in secondary and higher education institutions.
- Hybrid workplace AV refresh:Corporate facilities teams prioritize wireless casting and video conferencing integration in meeting room retrofits.
Market Restraints
- DMD chip supply concentration:Texas Instruments maintains captive production of digital micromirror devices, creating single-source vulnerability for DLP-based manufacturers.
- Rare earth phosphor cost volatility:Europium and terbium price swings destabilize laser engine bill-of-materials forecasting.
- Flat-panel display substitution:85-inch and larger direct-view LED and LCD panels capture conference room and classroom applications below 120-inch diagonal requirements.
Strategic Opportunities
- Indonesia SME digitization:Underpenetrated small business segment presents first-mover advantage for localized distribution partnerships.
- IRIA rental depreciation incentives:India's Income Tax Act Section 32 provisions accelerate projector fleet refresh cycles in the rental and staging sector.
- AI-driven auto-calibration:Machine vision convergence with projection mapping reduces installation labor costs in immersive experience venues.
Industry Challenges
- Optical engineer scarcity:Specialized lens design and thermal management expertise concentrates in Japan and Germany, constraining R&D expansion.
- Multi-protocol wireless certification:Miracast, AirPlay, and Chromecast compliance timelines extend product launch schedules by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multimedia Projectors Market |
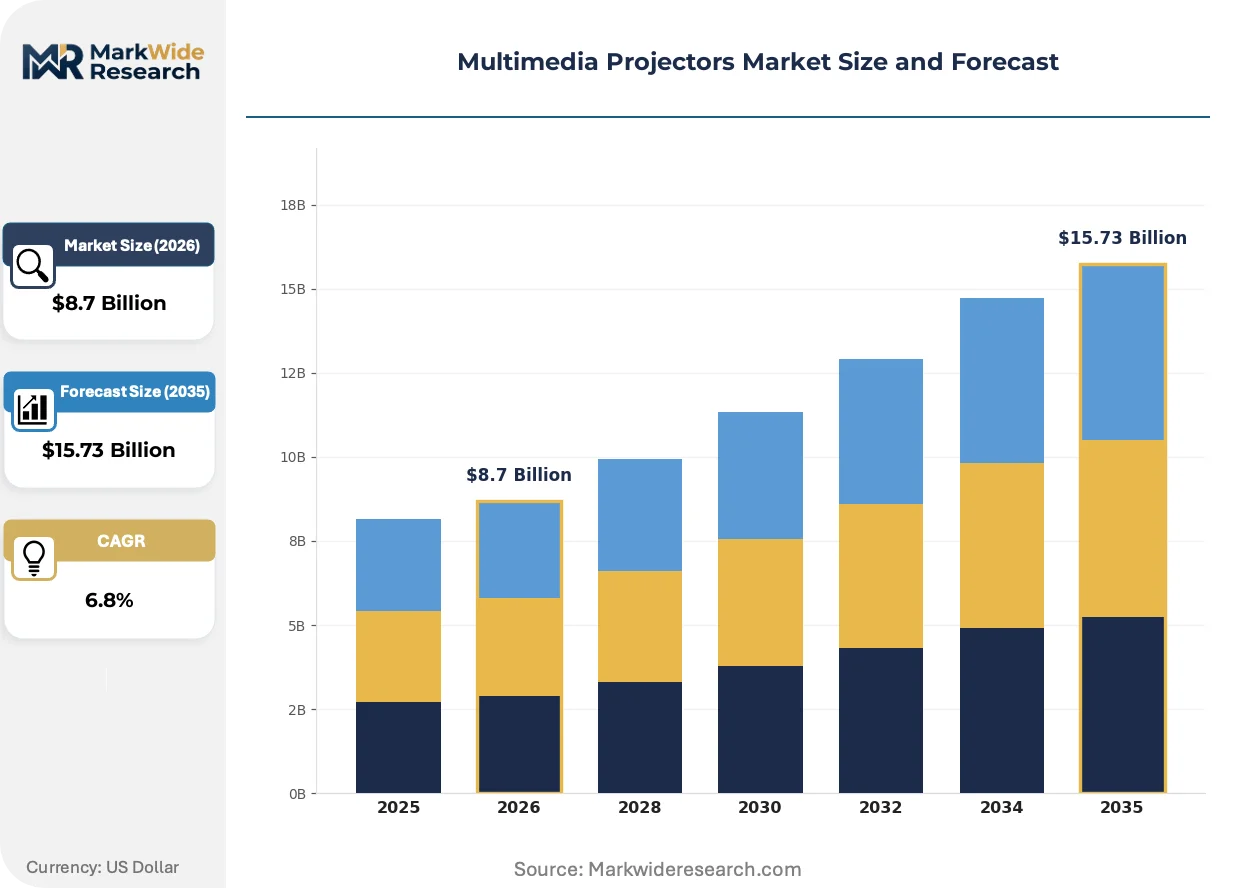
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Short Throw, Ultra Short Throw Technology: DLP, LCD, LCoS, LED End User: Education, Corporate, Home Theater, Entertainment Application: Presentations, Gaming, Home Cinema, Events |
| Companies Covered | Sony, Panasonic, Epson, LG, Canon, BenQ, ViewSonic, Christie Digital, Optoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multimedia Projectors Market Shifts & Advancements
Projection technology is fragmenting across illumination architectures while software-defined features compress hardware differentiation windows, forcing vendors to compete on integration depth rather than raw specifications.
Laser phosphor engines are decentralizing brightness delivery from centralized lamp architectures toward distributed diode arrays. Corporate AV buyers in North America and Western Europe are specifying 20,000-hour maintenance-free operation as standard. This shift is decentralizing service revenue from replacement parts toward remote diagnostics and firmware subscription tiers.
China's GB 21520 energy efficiency standards for display products are tightening luminous efficacy thresholds for imported units. SAMR enforcement actions in 2024 targeted non-compliant SKUs, redirecting manufacturer R&D toward localized product lines. Export-oriented factories now maintain parallel BOMs: one for domestic China sales, another for markets with less stringent thermal efficiency requirements.
Enterprise procurement teams are consolidating AV vendor lists and demanding unified endpoint management across projector fleets. Systems integrators respond with managed service bundles wrapping hardware, installation, and cloud-based device monitoring. This concentration is most visible in Germany and France, where facilities management outsourcing has penetrated mid-market corporate accounts.
Multimedia Projectors Market Segmentation
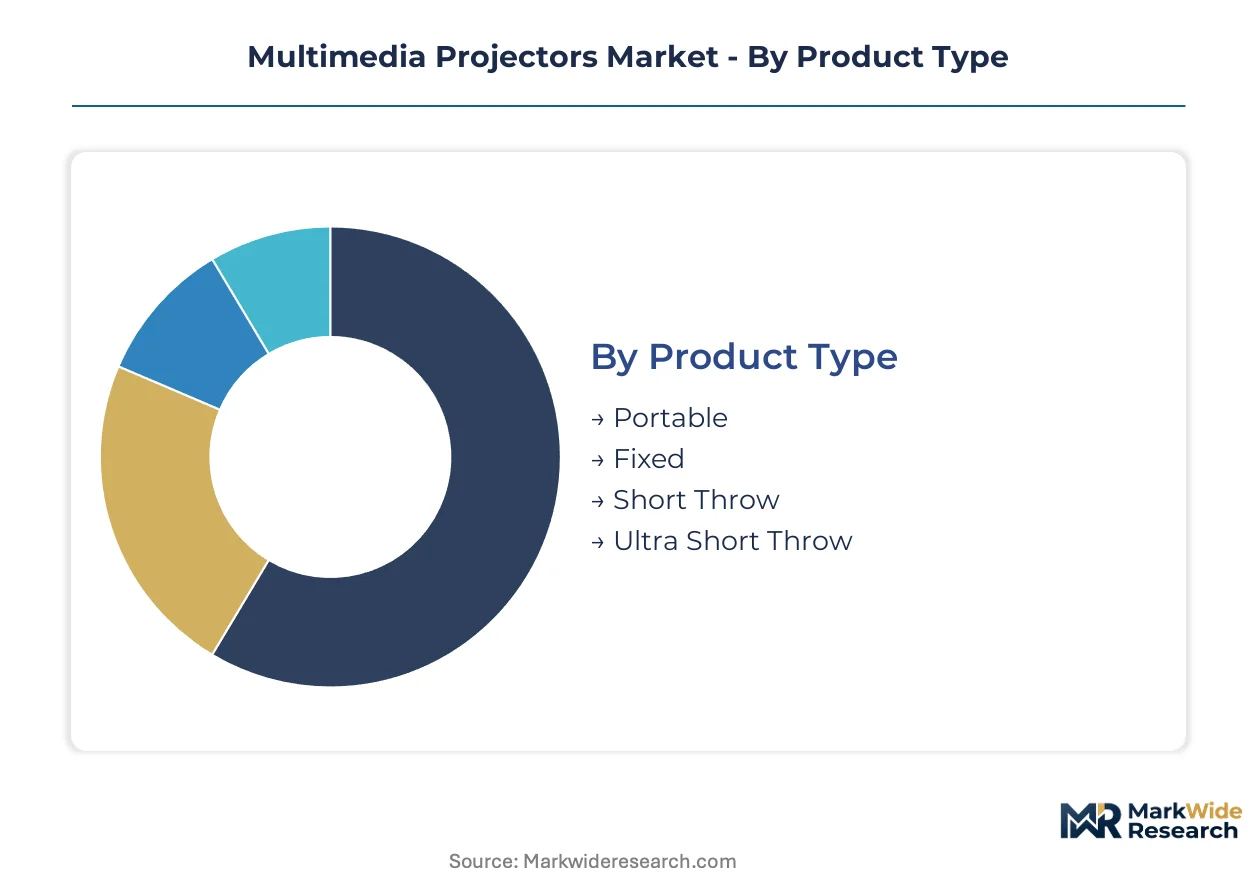
Multimedia projector purchasing decisions fragment across installation constraints, image quality requirements, and total cost of ownership calculations. Procurement teams weigh upfront hardware investment against lamp replacement cycles, installation labor, and wireless integration capabilities.
Product Type:
Capital intensity varies sharply across installation architectures, with fixed-mount systems requiring structural assessment and cabling infrastructure versus portable units demanding only power access.
- Portable:Battery-capable and lightweight designs under 5 pounds prioritize road warrior productivity and field sales presentations. Demand concentrates in North American consulting and professional services where employees carry projection capability between client sites and co-working spaces.
- Fixed:Ceiling-mounted installations with integrated control systems dominate museum and corporate boardroom deployments. These configurations require the highest upfront capital outlay for mounting hardware, extended warranty coverage, and professional calibration services.
- Short Throw:Projection ratios between 0.4 and 1.0 enable placement closer to screen surfaces, reducing shadow interference in K-12 classrooms.
- Ultra Short Throw:Sub-0.4 throw ratios position the projector inches from the wall, eliminating presenter shadow and reducing cable runs in space-constrained Mumbai and Singapore offices.
Most installed capacity flows through Fixed. Expansion is steepest in Ultra Short Throw.
Technology:
Manufacturing scale and patent licensing structures create divergent margin profiles across illumination and modulation architectures.
- DLP:Digital micromirror devices from Texas Instruments enable compact chassis designs with high ANSI contrast. Portable and gaming applications favor this technology for its thermal efficiency and pixel fill advantages in bright ambient conditions.
- LCD:Three-panel liquid crystal architectures deliver color brightness parity with white brightness, critical for data visualization in financial services and healthcare training environments. Epson and Sony maintain captive LCD panel production lines.
- LCoS:Liquid crystal on silicon chips achieve native 4K resolution without pixel shifting, commanding premium positioning in dedicated home cinema installations where contrast ratio drives willingness to pay.
- LED:Solid-state RGB LED illumination eliminates mercury lamp disposal requirements and extends operational lifespan to 30,000 hours, appealing to sustainability-focused European corporate procurement frameworks.
LCD dominates unit volume through manufacturing scale. LCoS captures the highest average selling prices in residential channels.
End User:
Budget authority and replacement cycle timing create distinct selling motions across institutional buyer categories.
- Education:State-level digitization initiatives in India and Brazil drive bulk procurement through competitive bidding processes. Interactive whiteboard integration requirements favor projectors with touch-enabled pen compatibility.
- Corporate:Hybrid workplace mandates in Germany and Japan accelerate meeting room refresh programs prioritizing wireless casting and video conferencing integration. Facilities teams consolidate vendor lists around unified endpoint management.
- Home Theater:Enthusiast buyers research contrast specifications and color gamut coverage extensively, driving online review engagement and specialty retailer relationships.
- Entertainment:Rental and staging companies in Dubai and Las Vegas prioritize rapid deployment features and ruggedized chassis for outdoor projection mapping events.
Education channels move the highest unit volumes through government tenders. Corporate segments generate the most predictable replacement revenue.
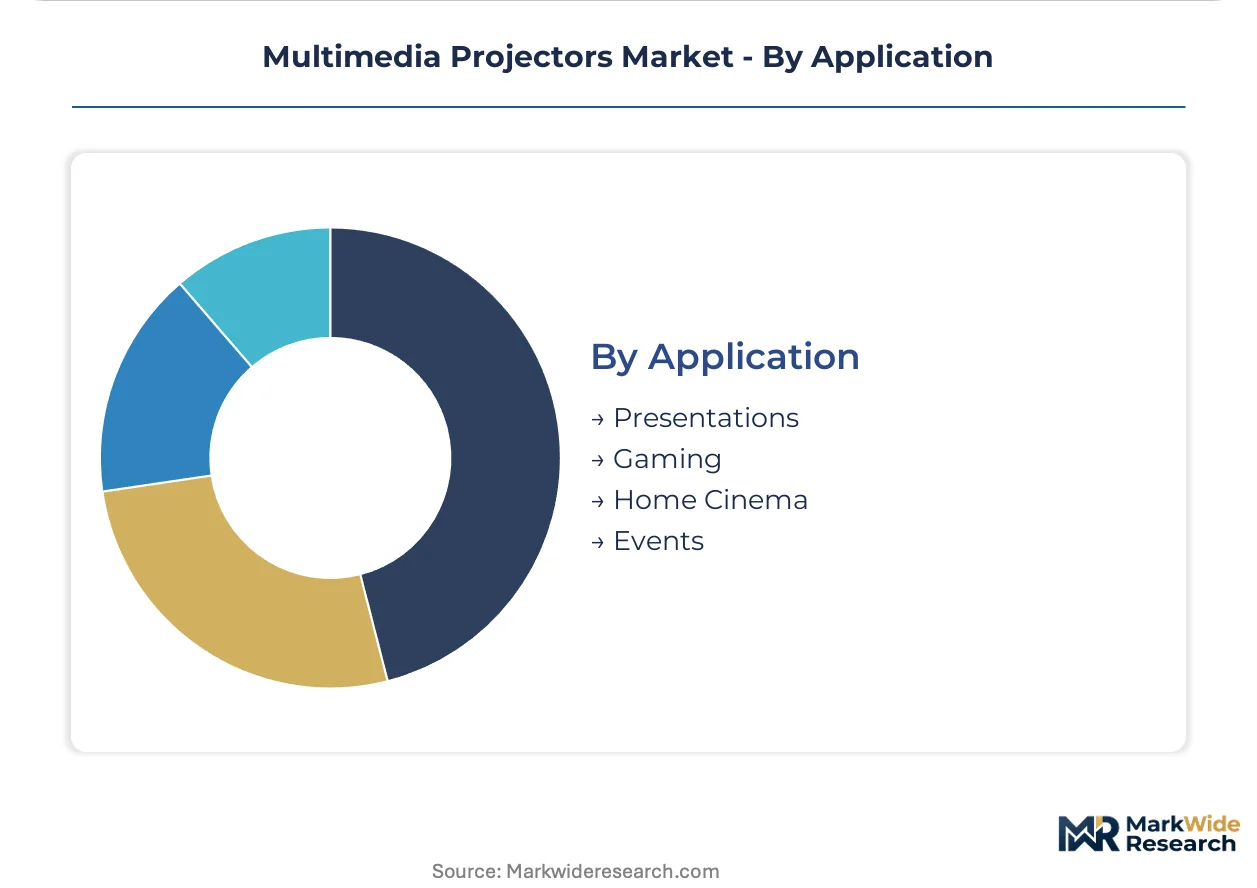
Application:
Use case specificity determines feature prioritization and pricing tolerance across buyer workflows.
- Presentations:Corporate and academic settings demand quick startup times, keystone correction, and compatibility with legacy VGA infrastructure alongside modern USB-C connectivity.
- Gaming:Input lag below 16 milliseconds and 120Hz refresh rates differentiate products for console and PC gaming applications where responsiveness trumps absolute brightness.
- Home Cinema:Dedicated theater rooms require whisper-quiet operation below 25 decibels, motorized lens shift, and HDR tone mapping for streaming content consumption.
- Events:Large-venue projection mapping and temporary installations prioritize edge blending, geometric correction, and high-lumen output above 10,000 ANSI lumens for acceptable visibility under ambient lighting.
Presentations account for the largest installed base. Gaming applications are climbing the fastest as display manufacturers target latency-sensitive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multimedia projector manufacturing originated in Japan during the 1980s, when Sony and Panasonic pioneered liquid crystal panel technologies for commercial projection systems. This Japanese foundation established the optical engineering expertise that now concentrates in East Asian supply chains.
United States
Corporate hybrid-work mandates drive meeting room refresh cycles across Fortune 500 facilities. EPA ENERGY STAR standby power limits of 0.5W reshape power supply designs for transatlantic market access. Dallas and Austin host the largest concentration of AV systems integrators deploying managed service bundles.
Germany
EU Ecodesign regulations enforce lamp efficiency thresholds and mercury-free illumination requirements. Facilities management outsourcing penetrates mid-market corporate accounts in Frankfurt and Munich. German procurement teams consolidate vendor lists around unified endpoint management platforms.
China
GB 21520 energy efficiency standards tighten luminous efficacy thresholds for display products. SAMR enforcement actions in 2024 targeted non-compliant SKUs, redirecting manufacturer R&D toward localized product lines. Shenzhen and Dongguan maintain parallel BOMs for domestic versus export-oriented production.
India
State government digitization initiatives drive bulk procurement through competitive bidding in secondary and higher education. IRIA rental depreciation incentives under Section 32 of the Income Tax Act accelerate projector fleet refresh cycles. Mumbai and Bangalore offices prioritize ultra-short-throw configurations for space-constrained installations.
Japan
METI industrial policy supports domestic retention of optical engineering capabilities and precision lens manufacturing. JIS standards govern display performance metrics for institutional procurement. Tokyo and Osaka maintain captive LCD panel production and laser light source development facilities.
Multimedia Projectors Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive component supply. Three to five conglomerates with display technology heritage control premium-tier positioning, while mid-scale specialists compete on price-accessible segments. Two dominant archetypes emerge: diversified electronics conglomerates leveraging backward integration into image sensors and light engines, and focused projection specialists optimizing distribution density in regional markets. Competitive moves concentrate on laser phosphor technology licensing and strategic partnerships with systems integrators for managed AV services.
Among diversified Japanese conglomerates, Sony and Panasonic occupy positions anchored in optical component manufacturing heritage. Epson represents the specialist archetype with manufacturing scale across LCD panel production. These three companies exemplify the structure where captive supply of critical subsystems creates differentiation against assembly-dependent competitors.
| Leading Market Players |
|---|
| Sony |
| Panasonic |
| Epson |
| LG |
| Canon |
| BenQ |
| ViewSonic |
| Christie Digital |
| Optoma |
| Others |
Supply & Pricing Matrix
Optical engineering talent concentration in Japan and Germany drives labor-cost differentials that widen pricing-tier spreads between premium LCoS home cinema systems and economy portable units sourced from Shenzhen assembly lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates laser phosphor home theater installations from lamp-based corporate meeting room refreshes from entry-level education tenders. Price differentiation rests on illumination architecture and wireless protocol certification complexity. Cost compression in the economy tier is intensifying because flat-panel substitution erodes volume scale. Education procurement teams exhibit highest price sensitivity, while home theater enthusiasts demonstrate lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Texas Instruments for DMD chips, constraining DLP-based manufacturers to captive pricing and allocation decisions. Manufacturing concentrates in China, Japan, and Taiwan for LCD panels, laser diodes, and precision optics respectively. Raw material dependencies include europium and terbium phosphors, liquid crystal substrates, and aluminum gallium nitride wafers. Tariff exposure on Chinese-assembled units threatens margin stability in North American distribution. Distribution runs through systems integrators and direct OEM relationships in corporate channels, with e-commerce platforms capturing consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser phosphor adoption compresses lamp replacement revenue while software subscription tiers expand recurring margin pools, creating a margin-expansion story anchored in solid-state illumination economics.
For Market Incumbents: Lock in service revenue migration by bundling remote diagnostics and firmware subscription tiers with hardware sales. Deepen backward integration into laser light source production to offset rare earth phosphor cost volatility. Defend against flat-panel substitution by emphasizing projection scale above 120-inch diagonal in corporate boardroom specifications. For New Entrants and Emerging Players: The price-point gap between premium laser home cinema and economy portable LCD creates white-space opportunity for mid-tier laser phosphor products targeting SME meeting rooms. Indonesia's underpenetrated small business segment offers first-mover positioning through localized distribution partnerships. Target wireless casting integration as the primary go-to-market angle against legacy lamp-based competitors. For Investors and Strategic Acquirers: Diversified electronics conglomerates with display technology heritage are the most active acquirers in this space, seeking captive optical component supply. Long-term viability favors specialists with manufacturing scale across LCD panel production and laser engine development. Monitor laser phosphor patent licensing terms as the inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Phosphor Technology Licensing | Texas Instruments' DMD patents and laser diode supply agreements determine manufacturing access for premium tiers. |
| Managed AV Service Bundles | Systems integrators in Germany and France wrap hardware, installation, and cloud monitoring into recurring revenue streams. |
| Wireless Protocol Certification Investment | Miracast, AirPlay, and Chromecast compliance timelines extend product launches by 4-6 months for multi-platform buyers. |
| Localized Distribution Partnerships | Panasonic's Asia-Pacific geographic dominance rests on regional warehousing and installer training networks. |
| AI-Driven Auto-Calibration Development | Machine vision convergence with projection mapping reduces installation labor costs in immersive experience venues. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged AV systems integrators, corporate facilities managers, education procurement officers, and optical component suppliers. Secondary validation drew from EPA ENERGY STAR specifications, EU Ecodesign regulatory filings, SAMR enforcement records, and customs trade data for display equipment. Bottom-up unit shipment modeling and top-down revenue triangulation anchored market size estimates.
Historical reference periods established baseline penetration rates for laser phosphor versus lamp illumination across corporate, education, and residential end uses. The projection horizon modeled technology type, installation architecture, brightness tier, and regional regulatory cluster as segmentation dimensions. CAGRs derived from installation cycle timing, replacement rate assumptions, and price trajectory analysis for solid-state versus legacy architectures. Forecast inputs incorporated hybrid workplace AV refresh mandates and India's education digitization procurement schedules.
Caveats apply where rare earth phosphor price volatility, DMD supply allocation decisions, or right-to-repair regulatory shifts could materially shift the outlook. Forecasts reflect documented assumptions about replacement cycle compression and wireless integration adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
OLED Microdisplay Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Portable Video Wall Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Global Embedded Display Market
Display Technologies
Flexible Screens Market
Display Technologies
Global Medical Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Screenless Display Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
United States Microdisplay Market
Display Technologies
Global Projector Market