
 Europe Transparent Conductive Films Market | 2026-2036
Europe Transparent Conductive Films Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Transparent Conductive Films Market Foresight
Photonics engineering talent is rotating toward roll-to-roll manufacturing competencies as European substrate producers scale flexible electronics output. CANATU leverages its dry deposition expertise to supply automotive-grade films for curved display stacks. TEIJIN LIMITED anchors supply continuity through in-house polymer substrate production that feeds transparent conductor lamination lines. GUNZE LTD. differentiates by controlling precision coating assets tuned to micrometer-thin optical layers.
Transparent conductive films are electrically active, optically clear thin-film materials—typically 50–250 nanometers thick—deposited on glass or polymer substrates to transmit visible light while conducting electrical signals for capacitive touch or electromagnetic shielding. Sputtering remains the dominant deposition method for ITO Films, though Chemical Vapor Deposition is gaining traction for graphene and carbon-nanotube variants that bypass indium supply constraints. Among End User segments, Automotive Displays now outpaces traditional Consumer Electronics in growth velocity as European OEMs integrate larger touch surfaces into cabin architectures. Printing technology occupies the emerging margin pool for conductive polymer applications where sheet resistance requirements relax below 100 ohms per square.
EMA material safety assessments and REACH substance restrictions are reshaping formulation choices for indium-based chemistries across European coating facilities. The EU Green Deal's circular economy mandates are forcing recyclability planning into film-substrate bonding decisions before products reach commercial scale. CSRD disclosure rules will soon require supply-chain carbon accounting that extends to Korean and Japanese raw material sources. Stakeholders must weigh substitution timelines for critical raw materials against qualification cycles already locked in by German automotive customers.
Market Dynamics
European coating facilities face mounting pressure from REACH substance restrictions and CSRD disclosure mandates that force early-stage recyclability planning into film-substrate bonding decisions before commercial scale.
Growth Catalysts
- Automotive Display Integration:European OEMs embed larger capacitive touch surfaces into cabin architectures, absorbing additional transparent conductive film capacity from substrate producers.
- EMA Material Safety Assessments:Accelerated safety clearances for indium-tin-oxide alternatives compress qualification timelines for graphene and carbon-nanotube variants.
- Roll-to-Roll Manufacturing Scale-Up:Photonics engineering talent migration toward flexible electronics output expands production throughput for polymer-based substrates.
Market Restraints
- Indium Supply Concentration:Critical raw material sourcing dependence on East Asian refiners exposes European coaters to geopolitical supply interruptions.
- REACH Compliance Friction:Substance disclosure rules for novel conductive chemistries extend formulation validation cycles by 12-18 months.
- Sheet Resistance Limitations:Printed conductive polymers fail to meet electromagnetic shielding specifications above 100 ohms per square, constraining aerospace adoption.
Strategic Opportunities
- Eastern European Manufacturing:Greenfield coating facilities in Poland and Czechia offer lower-cost substrate lamination capacity for German automotive suppliers.
- EU Green Deal Circular Economy Mandates:Design-for-recyclability requirements create first-mover advantage for film producers with solvent-free delamination processes.
- Sputtering-CVD Hybrid Deposition:Convergence of physical vapor deposition precision with chemical vapor deposition throughput enables single-pass multi-layer optical stacks.
Industry Challenges
- Photonics-to-Manufacturing Skill Transfer:Roll-to-roll competency gaps among legacy sputtering engineers slow flexible electronics line commissioning.
- Automotive Qualification Lock-In:German OEMs freeze supplier specifications 24-36 months ahead of production, trapping coaters in indium-based chemistries during substitution transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Transparent Conductive Films Market |
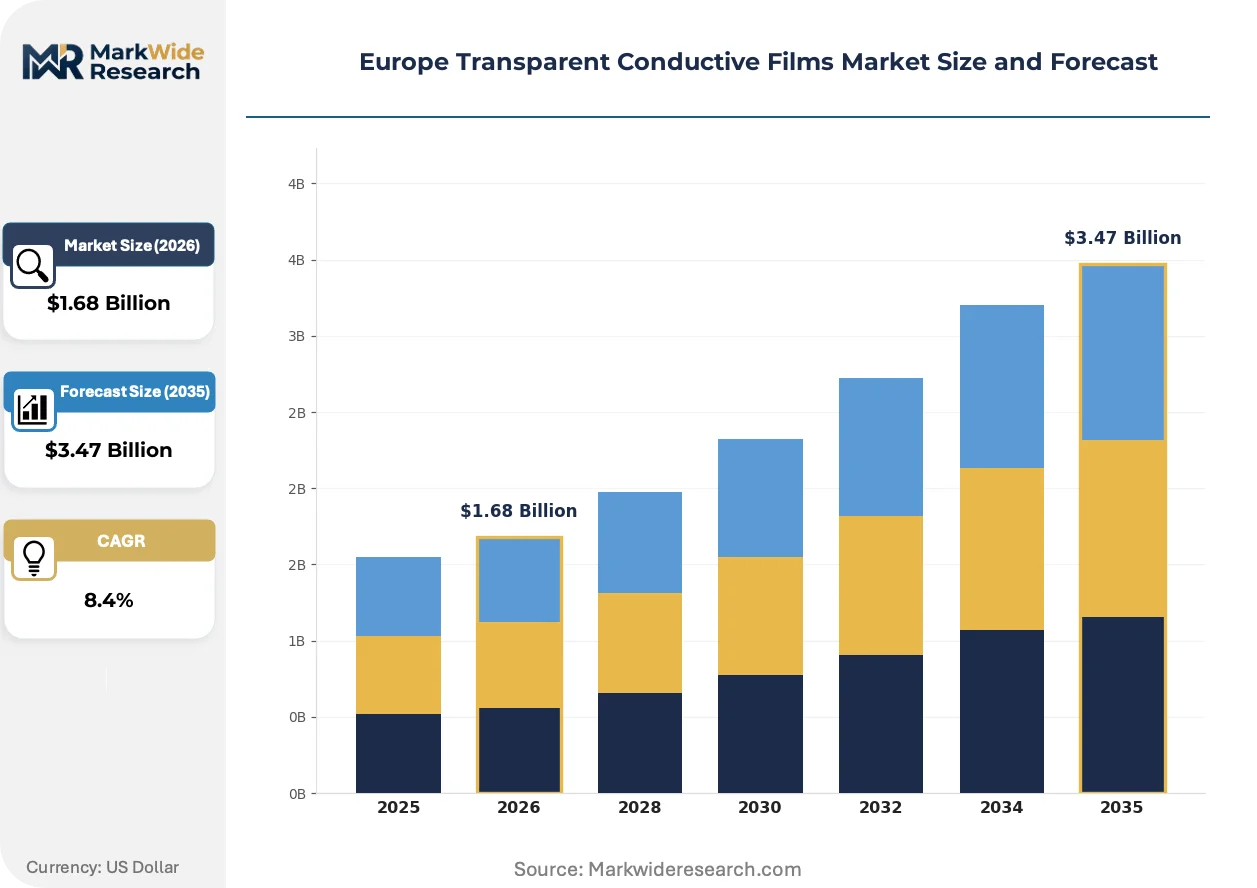
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
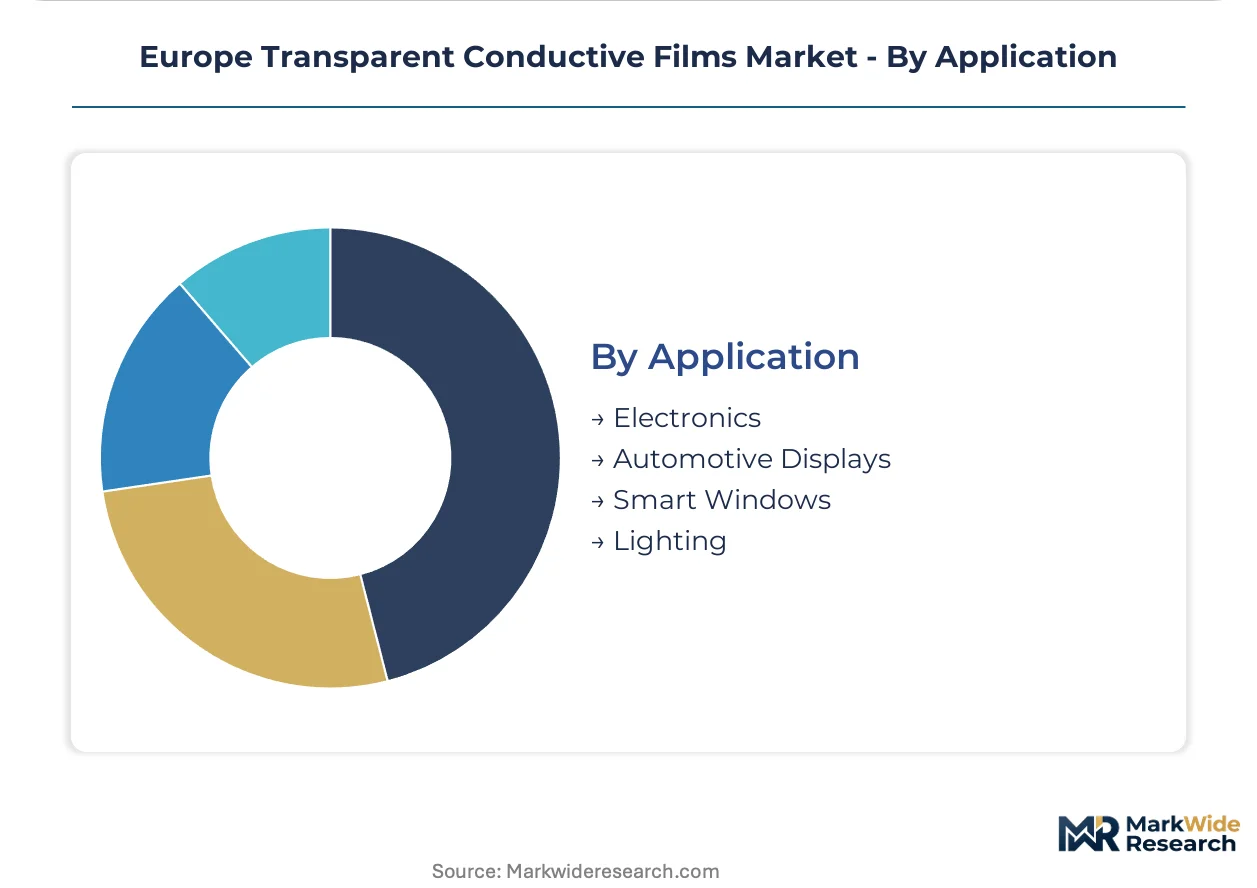
| Segmentation | Product Type: ITO Films, Ag Films, Graphene Films, Conductive Polymers End User: Consumer Electronics, Solar Cells, Touch Screens, Displays Technology: Sputtering, Chemical Vapor Deposition, Printing, Coating Application: Electronics, Automotive Displays, Smart Windows, Lighting |
| Companies Covered | CANATU, TOYOBO CO., LTD., CAMBRIOS, TEIJIN LIMITED, TDK Corporation, GUNZE LTD., DONTECH, INC., NITTO DENKO CORPORATION, C3Nano, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Transparent Conductive Films Market Shifts & Advancements
Deposition technology diversification and regulatory-driven material substitution are compressing the dominance of conventional indium-tin-oxide films across European electronics manufacturing.
Graphene-based transparent conductors are displacing sputtered ITO in mid-range touch applications where sheet resistance tolerances relax. Automotive tier-one suppliers in Stuttgart and Munich pilot graphene-coated polymer substrates for curved instrument clusters. The displacement is compressing capital allocation toward dry deposition equipment and away from legacy sputtering lines.
CSRD disclosure rules now mandate supply-chain carbon accounting extending to Korean and Japanese raw material sources. European coating facilities must document embodied emissions from indium refining through final film lamination. German automotive customers are responding by inserting emissions clauses into supplier contracts ahead of 2025 reporting deadlines.
Buyer consolidation among German OEMs concentrates procurement decisions into fewer technical sourcing committees. Tier-two substrate producers now sell directly to automotive electronics divisions rather than through distribution intermediaries. The channel compression is most visible in Baden-Württemberg, where Bosch and Continental have integrated film specification authority into centralized purchasing functions.
Europe Transparent Conductive Films Market Segmentation
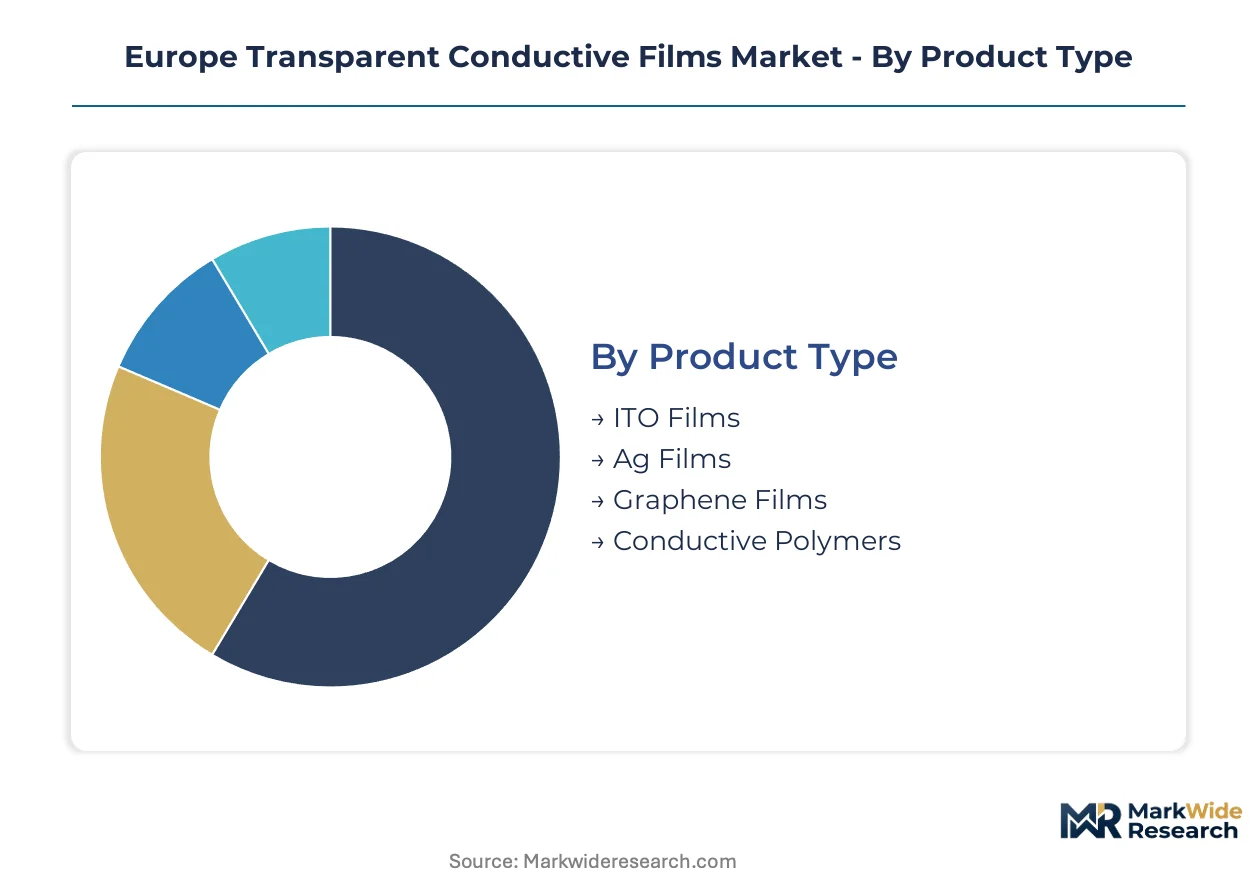
Segmentation reveals how substitution pressures and regulatory timelines concentrate value differently across material chemistries and deposition methods. Each dimension exposes distinct vulnerability points to indium supply constraints and REACH compliance costs.
Product Type:
ITO Films face the steepest substitution threat as graphene and silver nanowire alternatives achieve automotive qualification thresholds.
- ITO Films:Sputtered indium-tin-oxide layers deliver sheet resistance below 50 ohms per square with optical transparency exceeding 85%. German automotive electronics divisions in Baden-Württemberg anchor procurement volumes despite REACH-driven substitution timelines.
- Graphene Films:Carbon monolayers deposited via chemical vapor deposition bypass indium supply concentration entirely. Stuttgart-based tier-one suppliers pilot these films for curved instrument clusters where sheet resistance tolerances relax toward 100 ohms per square.
- Ag Films:Silver nanowire networks offer intermediate conductivity with reduced material criticality.
- Conductive Polymers:Printable organic formulations serve cost-sensitive touch applications with relaxed electromagnetic shielding requirements.
ITO Films anchors the volume base while Graphene Films gains share at the steepest rate.
End User:
Cost tier stratification separates premium automotive specifications from commoditized consumer electronics procurement.
- Automotive Displays:Curved touch surfaces for cabin architectures demand film-substrate bonding that survives thermal cycling from -40°C to 85°C. Bosch and Continental procurement committees in Germany freeze specifications 24-36 months ahead of production, locking suppliers into qualification cycles.
- Consumer Electronics:Smartphone and tablet touch panels absorb the largest absolute film volumes across European coating facilities. Polish and Czechia substrate laminators compete aggressively on unit cost for this segment.
- Touch Screens:Industrial and kiosk applications prioritize durability over optical precision.
- Solar Cells:Transparent electrode requirements for photovoltaic front contacts favor low-cost sputtered coatings.
Consumer Electronics commands the largest revenue pool while Automotive Displays expands most quickly.
Technology:
Volume concentration favors legacy sputtering assets even as capital allocation shifts toward vapor deposition alternatives.
- Sputtering:Physical vapor deposition from ceramic ITO targets remains the throughput leader for high-volume glass substrate coating. TEIJIN LIMITED and GUNZE LTD. operate established European lines optimized for automotive optical specifications.
- Chemical Vapor Deposition:CVD enables graphene and carbon-nanotube growth on polymer substrates without indium. CANATU leverages dry deposition expertise for roll-to-roll manufacturing of flexible films.
- Printing:Screen and inkjet methods serve conductive polymer applications where sheet resistance specifications relax below 100 ohms per square.
- Coating:Wet chemical methods occupy niche applications with minimal capital equipment requirements.
Sputtering dominates current installed capacity while Chemical Vapor Deposition attracts the fastest capital deployment.
Application:
Customer type segmentation separates regulated automotive specifications from discretionary electronics purchasing.
- Electronics:Capacitive touch modules for industrial control panels and medical devices demand consistent sheet resistance across batch production. REACH substance disclosure rules extend validation cycles for new conductive chemistries in this segment.
- Automotive Displays:Curved instrument clusters and center-stack touch surfaces integrate electromagnetic shielding with optical clarity. EU Green Deal circular economy mandates force recyclability planning into film-substrate bonding decisions before commercial scale.
- Smart Windows:Electrochromic glazing for architectural and transportation applications requires large-area film uniformity.
- Lighting:OLED and LED transparent electrodes prioritize cost minimization over extreme conductivity.
Electronics maintains the broadest customer base while Automotive Displays drives premium pricing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance restrictions and CSRD disclosure mandates anchor Germany's regulatory influence across European transparent conductive film supply chains. The EU Green Deal's circular economy requirements extend from Brussels through national implementations in automotive and electronics manufacturing clusters.
Germany
Automotive display integration at Bosch and Continental absorbs the largest film volumes for curved instrument clusters. REACH compliance friction extends formulation validation cycles for ITO alternatives by 12-18 months at Baden-Württemberg coating facilities. Stuttgart-based tier-one suppliers pilot graphene-coated polymer substrates for next-generation cabin architectures.
Poland
Greenfield substrate lamination capacity serves German automotive suppliers at lower operational cost than Western European alternatives. EU Green Deal recyclability mandates force solvent-free delamination process adoption at new Wrocław and Kraków facilities. The Silesian manufacturing corridor concentrates roll-to-roll equipment commissioning for flexible electronics output.
Czechia
Consumer electronics film volumes flow through Prague-region coating facilities competing aggressively on unit cost. EMA material safety assessments accelerate alternative chemistry clearances for export-oriented producers. The Ostrava industrial zone hosts polymer substrate production feeding transparent conductor lamination lines.
France
Aerospace electromagnetic shielding specifications drive premium film demand from Toulouse and Bordeaux aviation clusters. CSRD supply-chain carbon accounting extends to Korean and Japanese raw material sources for Paris-region electronics distributors. The Auvergne-Rhône-Alpes photonics corridor transfers engineering talent toward roll-to-roll manufacturing competencies.
United Kingdom
Medical device transparent electrode requirements sustain niche sputtering capacity despite broader manufacturing contraction. Post-Brexit REACH alignment delays novel conductive chemistry introductions at Cambridge-area coating facilities. The Midlands automotive electronics corridor maintains qualification relationships with German OEM specification committees.
Europe Transparent Conductive Films Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with polymer substrate control and precision coating assets separating premium positioning from commodity supply. Japanese and Korean conglomerates anchor the upper tier through captive material production, while European specialists compete on deposition technology differentiation. Strategic archetypes include integrated polymer-to-film producers, dry deposition technology licensors, and automotive-qualified coating specialists. Capacity expansion and strategic partnerships dominate competitive moves as qualification timelines lock suppliers into long-term relationships.
Among Japan-based fabricators, TEIJIN LIMITED and GUNZE LTD. exemplify the integrated archetype through in-house substrate production feeding lamination operations. CANATU occupies a specialist position within the dry deposition technology tier. These three companies represent distinct competitive vectors: polymer supply continuity, precision coating asset control, and roll-to-roll manufacturing expertise for automotive-grade specifications.
| Leading Market Players |
|---|
| CANATU |
| TOYOBO CO., LTD. |
| CAMBRIOS |
| TEIJIN LIMITED |
| TDK Corporation |
| GUNZE LTD. |
| DONTECH, INC. |
| NITTO DENKO CORPORATION |
| C3Nano |
| Others |
Supply & Pricing Matrix
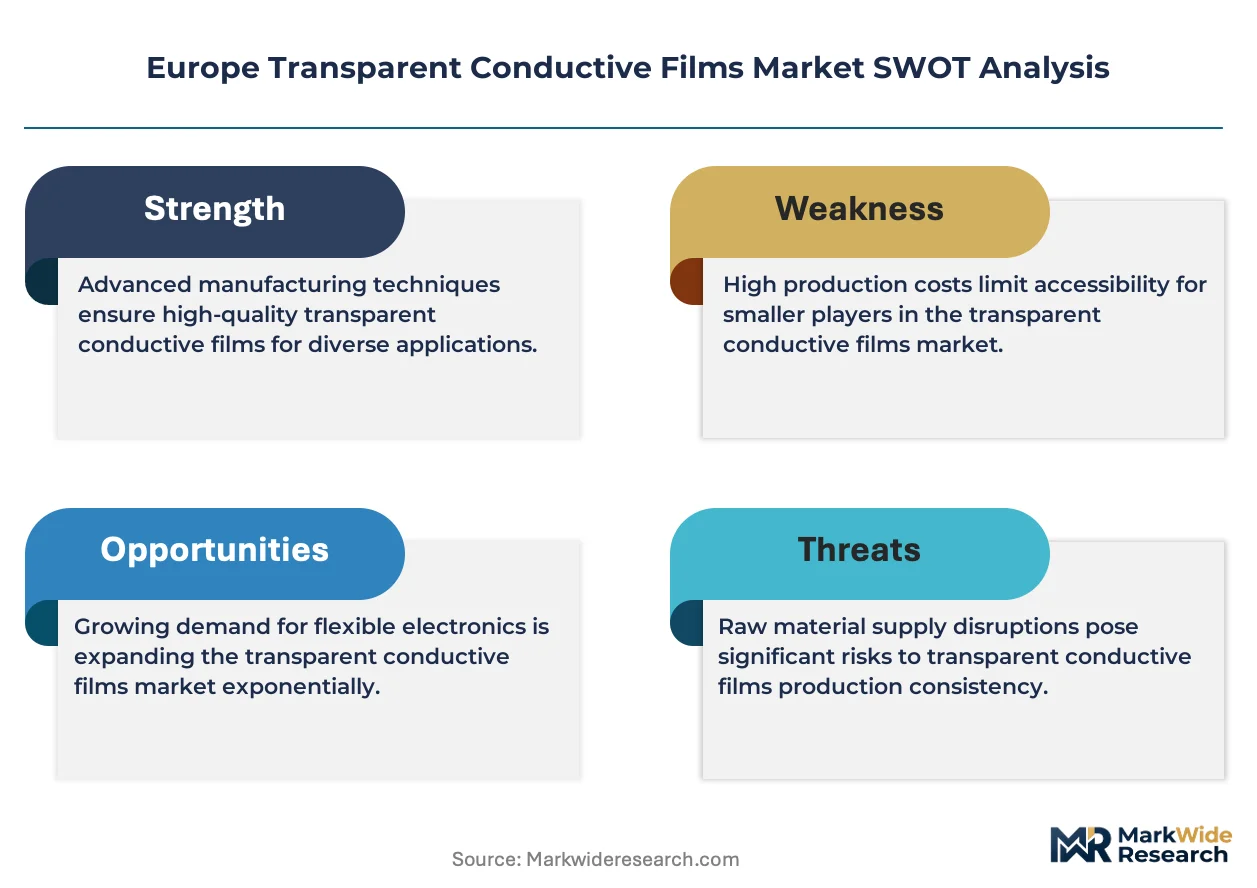
REACH substance disclosure rules gate both supplier qualification and price differentiation simultaneously, forcing European coaters to absorb extended validation costs while German automotive buyers segment procurement across performance tiers. The regulatory friction compresses margin pools for indium-tin-oxide alternatives and concentrates pricing power with integrated substrate producers.
Pricing Analysis
Long-term offtake contracts dominate procurement between German automotive electronics divisions and Japanese substrate producers, insulating qualified suppliers from spot volatility while locking in volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified films from consumer electronics laminates and commodity touch-panel supply. Cost compression in the consumer tier intensifies as Polish and Czechia facilities compete on unit economics. Consumer electronics buyers exhibit the highest price sensitivity, while German OEM procurement committees prioritize specification stability over marginal cost savings.
Supply Chain Analysis
South Korea and Japan anchor refined indium supply and polymer substrate production feeding European lamination lines. The supply chain draws from East Asian ceramic target manufacturers, German sputtering equipment fabricators, and Korean petrochemical feedstock for polymer bases. Single-source vulnerability concentrates around indium refining capacity controlled by a narrow supplier set. Distribution runs through direct technical sales relationships between tier-one substrate producers and German automotive electronics divisions, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roll-to-roll manufacturing expertise represents the critical capability gap constraining European flexible electronics scale-up, with photonics engineering talent migration lagging behind substrate production expansion. The scarcity compresses commissioning timelines and elevates acquisition premiums for deposition technology specialists.
For Market Incumbents: Shield automotive qualification relationships by accelerating graphene and carbon-nanotube alternative validation ahead of REACH-driven substitution deadlines. Deepen in-house polymer substrate production to secure supply continuity against Korean and Japanese feedstock concentration. Prioritize solvent-free delamination process development to capture EU Green Deal circular economy compliance premiums. For New Entrants and Emerging Players: EMA material safety assessment fast-tracks offer compressed entry pathways for novel conductive chemistries targeting mid-range touch applications. Polish and Czechia greenfield coating facilities represent the most penetrable geography for cost-competitive substrate lamination. Pursue direct technical partnerships with Stuttgart and Munich tier-one suppliers bypassing established distribution channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical vapor deposition equipment as graphene film production scales. The five-to-ten-year viability window favors acquisition targets with captive polymer substrate production and automotive qualification relationships. Watch for inflection signals in German OEM specification freezes that lock alternative chemistry adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Substrate Production | TEIJIN LIMITED and GUNZE LTD. secure supply continuity against Korean petrochemical feedstock volatility. |
| Dry Deposition Technology Licensing | CANATU monetizes roll-to-roll expertise for automotive-grade curved display stacks. |
| Eastern European Manufacturing Footprint Expansion | Greenfield Wrocław and Kraków facilities capture German automotive procurement at lower operational cost. |
| Solvent-Free Delamination Process Development | First-mover compliance with EU Green Deal circular economy mandates creates specification lock-in. |
| Graphene Alternative Chemistry Validation | Stuttgart-based tier-one suppliers pilot carbon monolayer films for curved instrument clusters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with coating facility managers, automotive electronics procurement leads, photonics engineering directors, and REACH compliance officers; and secondary validation through ECHA substance restriction databases, EU Green Deal implementation directives, SEC filings of Japanese substrate producers, and European customs trade records. Bottom-up capacity assessments and top-down demand projections triangulated volume estimates.
Across the projection horizon, the analytical framework modeled transparent conductive film demand through product type, end user segment, deposition technology, and application category dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Key forecast inputs included German automotive production schedules for curved display integration and REACH substitution timeline assumptions for indium-based chemistries.
Underlying assumptions cover regulatory implementation pace and automotive qualification cycle stability, with deviation risk concentrated in indium supply interruption scenarios and EMA safety clearance acceleration for alternative materials. Recalibration cycles align with material shifts in EU Green Deal circular economy mandate enforcement and German OEM specification freeze announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
TFT LCD Panel Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Computer Monitor Market
Display Technologies
Portable Video Wall Market
Display Technologies
8K Display Resolution Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
DLP Projector Market
Display Technologies
Global Medical Display Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Multi-Function Display Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Smart Screen Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Quantum Dot Display Market