
 Display Control and Management System Market | 2026-2036
Display Control and Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Display Control and Management System Market Outlook
Retail digital signage is rebalancing its technology stack away from standalone media players toward unified control and management platforms. Texas Instruments leverages its programmable DLP controller portfolio to anchor high-brightness projection signage in North American stadiums and arenas. Analog Devices sustains signal integrity leadership through integrated timing controllers that reduce electromagnetic interference in dense LED video walls.
A display control and management system orchestrates image rendering, color calibration, thermal regulation, and input synchronization across multi-panel arrays, typically employing embedded processors with real-time operating systems and FPGA-based timing engines to achieve sub-frame latency below 16 milliseconds for broadcast-grade applications. LED drivers and video wall processors capture expanding margin pools as pixel pitches shrink below 1 millimeter in premium installations, while touchscreen controllers face commoditization pressure from standardized capacitive sensing stacks. Cloud-based solutions within the technology dimension are pulling software licensing revenue away from hardware-centric local area network deployments.
The FCC in the United States enforces Part 15 emissions standards that constrain clock frequencies and shielding designs in display controller chipsets, while the EU's CE marking and RoHS directives restrict hazardous substances in printed circuit board assemblies sold across European member states. China's MIIT mandates GB standard compliance for wireless connectivity modules embedded in smart display controllers. Stakeholders must monitor how fragmented cybersecurity certification requirements across these jurisdictions reshape firmware development roadmaps and qualification timelines.
Market Dynamics
Retail procurement of digital signage is consolidating around unified control platforms, compressing margins for standalone media player vendors while expanding addressable revenue for integrated system orchestrators.
Growth Catalysts
- EU Ecodesign standby limits:The directive's tightening power thresholds for idle display systems are forcing hardware refresh cycles across European retail and hospitality chains.
- South Korean semiconductor cluster:Concentrated R&D investment around Seoul and Suwon accelerates development of low-latency timing controllers for broadcast-grade LED walls.
- Cloud-native control architectures:Software-as-a-service licensing models are overtaking perpetual hardware-centric deployments in North American stadium and arena installations.
Market Restraints
- FPGA supply concentration:Timing engine production depends on a narrow Taiwan-based foundry base, exposing lead times to geopolitical disruption.
- Sub-millimeter pixel pitch cost curves:Premium LED video wall densities below 1mm require specialized driver ICs that inflate BOM costs by 40-60% versus standard pitch alternatives.
- FCC Part 15 emissions compliance:Clock frequency constraints and shielding mandates extend chipset qualification timelines for North American market entry.
Strategic Opportunities
- India smart city infrastructure:Municipal digital signage networks remain underpenetrated by integrated control platforms, creating first-mover positioning for cloud-native vendors.
- AI-driven thermal regulation:Convergence of machine learning inference at the edge with embedded display controllers enables predictive fan control and extended panel lifespans.
- Japan METI energy efficiency incentives:Subsidy programs for low-power display systems accelerate adoption of advanced power management ICs in commercial signage.
Industry Challenges
- Real-time operating system certification:Broadcast-grade latency requirements below 16 milliseconds demand specialized firmware validation that extends development cycles.
- Legacy DVI/HDMI infrastructure:Stadium and arena retrofit projects face integration friction with existing signal distribution architectures, complicating unified control deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Control and Management System Market |
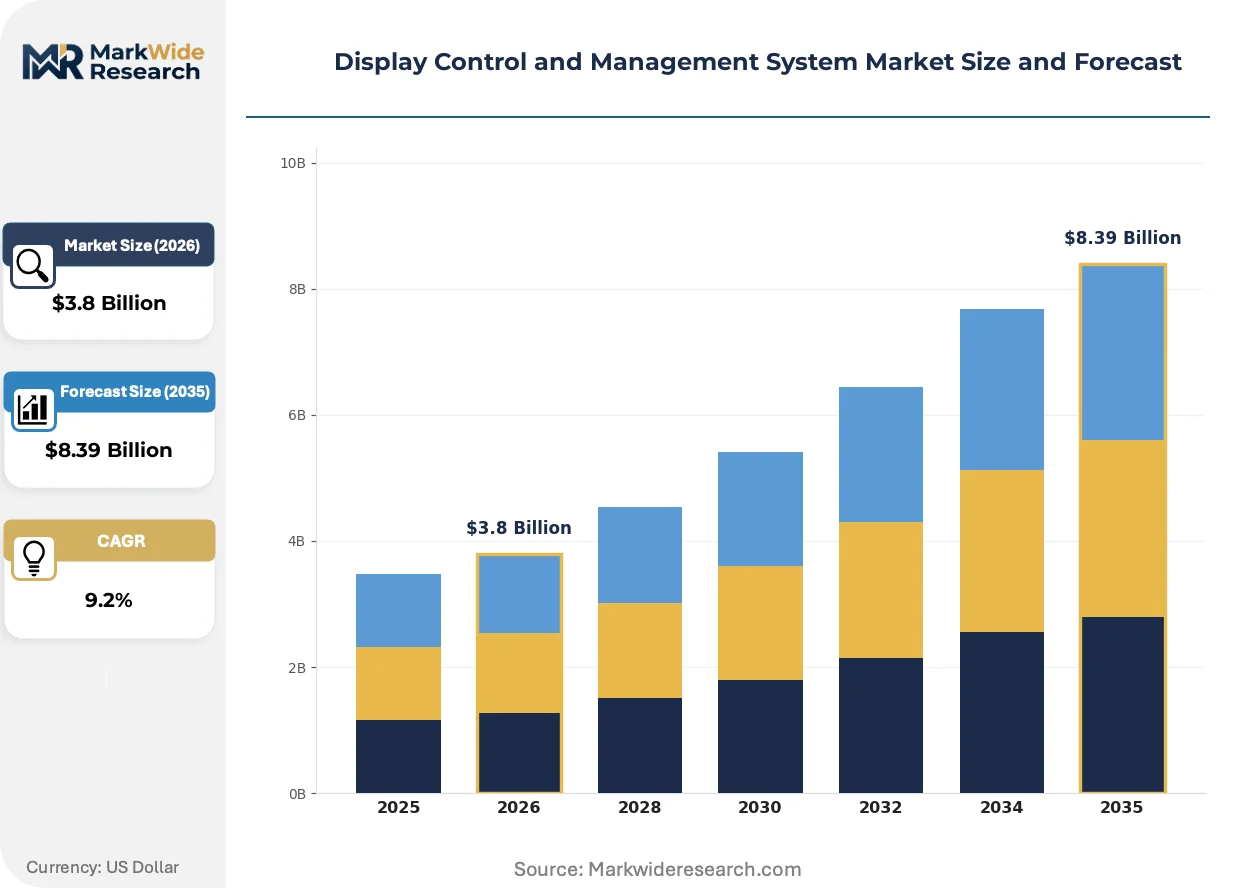
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD Controllers, LED Drivers, Touchscreen Controllers, Video Wall Processors Application: Digital Signage, Broadcast Communication, Retail Displays, Conference Rooms Technology: Wired Connectivity, Wireless Connectivity, Cloud-Based Solutions, Local Area Network End User: Advertising Agencies, Corporate Offices, Educational Institutions, Event Venues |
| Companies Covered | Texas Instruments, Analog Devices, STMicroelectronics, NXP Semiconductors, Qualcomm Technologies, Inc., Synaptics, Himax Technologies, Renesas Electronics, Novatek Microelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Control and Management System Market Strategic Shifts
Display control architectures are pivoting from hardware-centric timing engines toward software-defined orchestration, compressing traditional value capture points while opening new recurring revenue streams.
MicroLED driver integration is overtaking discrete component architectures in premium video wall installations. Advanced semiconductor packaging enables single-chip solutions combining timing control, power management, and thermal sensing. Sports venues and corporate lobbies in Germany and the United States are adopting these consolidated designs to reduce failure points and simplify field maintenance.
China's MIIT GB standards for wireless connectivity modules are tightening electromagnetic compatibility thresholds for smart display controllers. Manufacturers must redesign RF shielding and antenna configurations to maintain market access. Domestic Chinese brands are responding faster than multinational suppliers, compressing qualification timelines by three to six months in local procurement decisions.
Outcome-based service contracts are displacing capital expenditure models in North American retail digital signage networks. System integrators now bundle hardware, software licensing, and remote monitoring into per-display monthly fees. This shift concentrates buyer power among large-format retail chains while marginalizing smaller VARs dependent on transactional equipment sales.
Display Control and Management System Market Segmentation
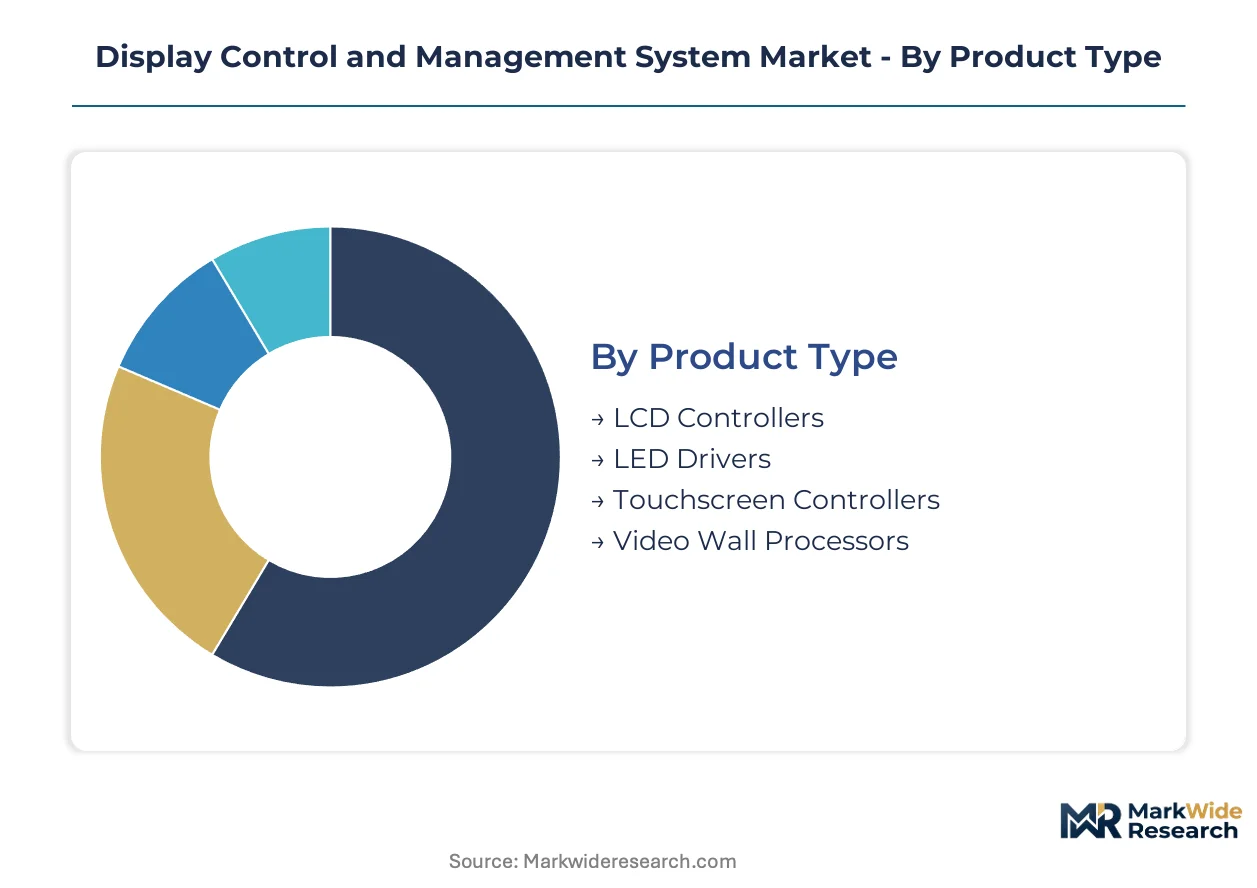
Display control architectures fragment across four distinct dimensions, each carrying unique certification burdens and margin profiles. Product type determines the hardware-software revenue mix, while technology choice increasingly dictates recurring licensing potential versus one-time equipment sales.
Product Type:
FCC Part 15 emissions compliance constrains clock frequencies in LCD controllers and video wall processors, while EU RoHS restrictions govern hazardous substance thresholds across all four hardware categories.
- LCD Controllers:These timing engines manage pixel addressing and backlight modulation for liquid-crystal panels, typically integrating TCON (timing controller) and gamma correction circuits on single-chip architectures. Demand concentrates in corporate conference room retrofits across Germany and the United States, where FCC shielding mandates extend qualification timelines by four to six months.
- LED Drivers:Power management ICs regulate current delivery to individual diodes in direct-view LED walls, with sub-millimeter pixel pitches requiring specialized multi-channel architectures. Broadcast communication installations in South Korea's Seoul-Suwon corridor absorb the highest volumes of premium driver ICs as pixel densities shrink below 1 millimeter.
- Touchscreen Controllers:Capacitive sensing processors translate touch coordinates into display commands, facing commoditization from standardized controller stacks.
- Video Wall Processors:Multi-input scalers and image composition engines synchronize content across panel arrays, requiring real-time operating systems certified below 16-millisecond latency thresholds.
Leading the category by volume: LED Drivers. Expanding most quickly: Video Wall Processors.
Application:
Cost stratification separates premium broadcast-grade systems from volume retail deployments, with procurement budgets diverging by an order of magnitude per display node.
- Digital Signage:Networked display orchestration for advertising and information dissemination, spanning transportation hubs and quick-service restaurants. Advertising agencies in India are consolidating procurement around cloud-native control platforms for municipal smart city networks.
- Broadcast Communication:Professional video infrastructure demanding sub-frame latency and redundant signal paths. Sports venues across Texas and California anchor North American demand for 4K HDR processing with SDI and 12G-SDI input compatibility.
- Retail Displays:Point-of-sale and in-store promotional screens, increasingly shifting from standalone media players to integrated control systems.
- Conference Rooms:Enterprise collaboration displays requiring wireless presentation and unified communications integration.
Retail Displays generate the highest unit volumes. Broadcast Communication commands the steepest average selling prices.
Technology:
Cloud-native architectures are displacing on-premise LAN deployments in North American stadium and arena installations, compressing hardware margins while expanding software recurring revenue.
- Wired Connectivity:Ethernet, HDBaseT, and fiber-optic distribution carrying uncompressed video over dedicated physical infrastructure. Corporate offices in Japan maintain preference for wired backbones under METI energy efficiency guidelines.
- Wireless Connectivity:Wi-Fi 6E and emerging Wi-Fi 7 modules enabling display mobility and simplified installation. China's MIIT GB standards tighten electromagnetic compatibility thresholds, advantaging domestic suppliers with faster certification cycles.
- Cloud-Based Solutions:Software-as-a-service orchestration with browser-based management portals and over-the-air firmware updates.
- Local Area Network:On-premise control servers with perpetual licensing and air-gapped security architectures.
Local Area Network retains the installed base majority. Cloud-Based Solutions are climbing the fastest by new deployment share.
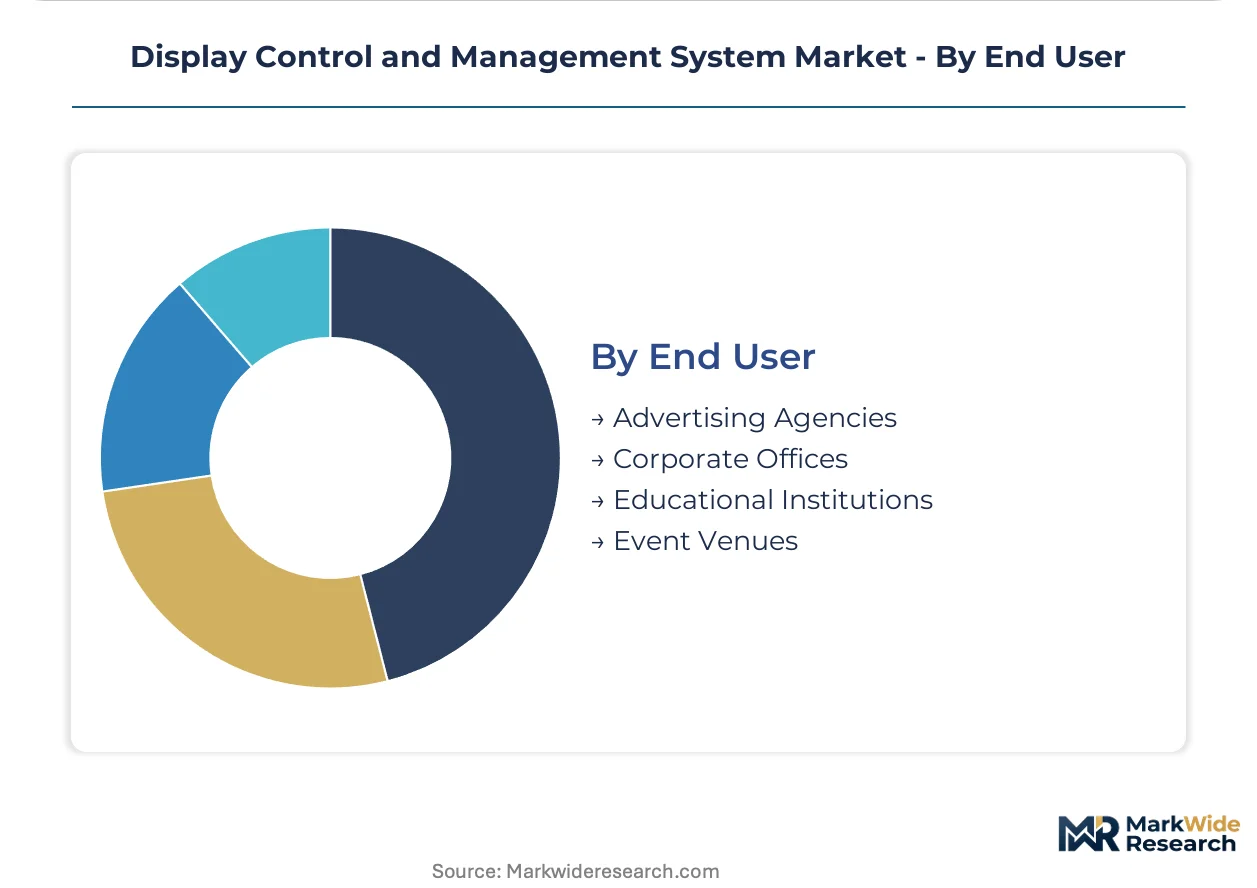
End User:
Customer sophistication spans from procurement departments optimizing total cost of ownership to production engineers demanding broadcast-grade reliability.
- Advertising Agencies:Media buyers managing brand campaigns across distributed digital signage networks, prioritizing remote content scheduling and impression analytics. Outcome-based service contracts are consolidating buyer power among the largest agency holding companies.
- Corporate Offices:Facilities and IT teams standardizing meeting room technology across global footprints. Educational institutions in the United Kingdom are accelerating refresh cycles under sustainability procurement mandates.
- Educational Institutions:Universities and K-12 districts deploying campus-wide digital communication and interactive learning displays.
- Event Venues:Stadiums, arenas, and convention centers requiring high-brightness projection and LED video walls with 24/7 operational reliability.
Corporate Offices represent the largest addressable spend pool. Event Venues are gaining share fastest through premium LED wall investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian semiconductor clusters while consumption spreads across retail, broadcast, and enterprise installations in North America and Europe. The United States and Germany anchor premium demand for broadcast-grade systems. South Korea and Taiwan supply timing controllers and driver ICs.
United States
Sports venues across Texas and California drive demand for 4K HDR video wall processors with SDI compatibility. FCC Part 15 emissions standards constrain clock frequencies and shielding designs in controller chipsets. Dallas-based semiconductor design houses collaborate with Austin fabrication facilities on low-latency timing engines.
Germany
Corporate conference room retrofits and industrial automation displays absorb high volumes of LCD controllers and embedded processors. EU Ecodesign standby power limits force hardware refresh cycles across retail and hospitality chains. Bavarian engineering firms around Munich specialize in ruggedized display controllers for manufacturing environments.
South Korea
Broadcast communication installations in the Seoul-Suwon corridor demand sub-millimeter pixel pitch LED walls with specialized driver ICs. The national regulator enforces electromagnetic compatibility certification for wireless display modules. Samsung and LG supply chain ecosystems in Gyeonggi Province accelerate development of integrated timing controllers.
China
Smart city digital signage networks and commercial LED installations generate volume demand for video wall processors and LED drivers. MIIT mandates GB standard compliance for wireless connectivity modules in smart display controllers. Shenzhen and Dongguan manufacturing clusters dominate PCB assembly and controller module production.
Japan
Corporate offices and educational institutions prioritize energy-efficient display systems under sustainability procurement guidelines. METI subsidy programs for low-power electronics accelerate adoption of advanced power management ICs. Nagoya-area semiconductor houses develop integrated thermal sensing solutions for commercial signage.
Display Control and Management System Market Competitive Environment
Top-tier vendors anchor integrated system orchestration, while mid-tier specialists concentrate on discrete timing controllers and LED drivers. The vendor base spans semiconductor conglomerates with programmable logic portfolios, analog specialists with signal integrity expertise, and fabless designers with display-specific IP. Two strategic archetypes dominate: vertically integrated chipmakers capturing driver IC margins, and modular platform vendors bundling hardware with cloud-native software licensing. Competitive moves center on FPGA-based timing engine partnerships and SaaS subscription models displacing perpetual hardware sales.
Within the programmable logic tier, Texas Instruments and Analog Devices exemplify divergent positioning strategies. Texas Instruments anchors high-brightness projection signage through its DLP controller portfolio, while Analog Devices sustains signal integrity leadership in dense LED video wall applications. STMicroelectronics occupies a position bridging automotive and industrial display controller segments, reflecting portfolio breadth across end-use verticals.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| STMicroelectronics |
| NXP Semiconductors |
| Qualcomm Technologies, Inc. |
| Synaptics |
| Himax Technologies |
| Renesas Electronics |
| Novatek Microelectronics |
| Others |
Value Chain & Pricing Dynamics
EU Ecodesign standby power mandates are compressing procurement budgets for European retail and hospitality chains, forcing controller vendors to absorb advanced power management IC costs while maintaining price parity with legacy hardware alternatives. This specification-driven cost compression reverberates upstream through Taiwan-based foundry negotiations and South Korean driver IC sourcing.
Pricing Analysis
Lead-time premiums now dominate transactional pricing across FPGA-based timing controllers, with spot inventory from Taiwan-based distributors commanding substantial markups over contract-scheduled deliveries. A three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade sub-16ms latency systems from commercial signage and entry-level retail deployments. Pricing pressure stems from cloud-native SaaS licensing displacing perpetual hardware sales in North American stadium installations. Advertising agencies exhibit the highest price sensitivity due to outcome-based contract structures, while broadcast communication operators prioritize latency certification over unit cost.
Supply Chain Analysis
Photoresist supply for advanced semiconductor packaging rests on Japanese specialty chemical producers in Tokyo and Osaka, creating input dependency for integrated timing controller fabrication. Controller chipset production concentrates in Taiwan, South Korea, and the United States, with raw material flows spanning silicon wafers, specialty substrates, and precision passive components. Single-source vulnerability in Taiwan-based foundry capacity exposes lead times to geopolitical disruption. Distribution runs through authorized distributors in Shenzhen and direct OEM relationships with German industrial automation firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated system orchestrators, with cloud-native licensing models and FPGA supply concentration squeezing standalone media player vendors into acquisition or exit.
For Market Incumbents: Hedge against timing controller commoditization by deepening backward integration into LED driver IC design and securing captive foundry capacity in South Korea's Seoul-Suwon corridor. Prioritize FCC Part 15 pre-certification investments to compress North American market entry timelines against emerging cloud-native competitors. For New Entrants and Emerging Players: Cloud-native platform routes offer the fastest penetration path into India's underdeveloped municipal smart city signage networks. Target advertising agencies with outcome-based service contracts bundling hardware, software licensing, and remote monitoring. Pursue white-label partnerships with Shenzhen-based PCB assemblers to bypass capital-intensive fabrication barriers. For Investors and Strategic Acquirers: The window for entry favors fabless designers with display-specific timing controller IP and established MIIT GB certification for Chinese wireless connectivity modules. Long-term viability hinges on software recurring revenue attaching to hardware deployments. Watch for inflection when cloud-native SaaS penetration in North American stadium installations crosses critical mass and triggers hardware margin compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Timing Engine Partnership | Secures sub-16ms latency certification for broadcast-grade LED wall processors in Texas sports venues. |
| Cloud-Native Platform Integration | Converts perpetual hardware sales into recurring SaaS revenue across North American retail chains. |
| MIIT GB Certification Investment | Accelerates wireless module qualification timelines against domestic Chinese competitors in Shenzhen. |
| Backward Integration into Driver ICs | Captures margin pools from sub-millimeter pixel pitch LED walls in South Korean broadcast installations. |
| Strategic Partnership with Foundry | Locks Taiwan-based capacity for timing controllers amid geopolitical supply risk exposure. |
Study Parameters
SEC 10-K filings, EIA energy consumption databases, and MIIT regulatory bulletins formed the secondary backbone, supplemented by customs records tracking controller chipset trade flows. Primary interviews with display controller procurement managers at German automotive OEMs, broadcast systems integrators in California, and LED driver IC design engineers in Gyeonggi Province validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down semiconductor revenue aggregation across the analysis window.
Historical trendline analysis of LCD controller and video wall processor shipments informed the projection framework, with CAGR derivation incorporating technology transition curves from wired to cloud-native architectures. Segmentation dimensions spanned product type, application tier, deployment technology, and end-user sophistication. Industry-specific inputs included EU Ecodesign compliance cost curves and FCC Part 15 qualification timeline distributions.
The model holds under stable foundry capacity allocation and regulatory enforcement continuity; deviation in Taiwan geopolitical conditions or MIIT GB standard acceleration would shift timing. Forecasts reflect these boundary assumptions with explicit sensitivity ranges. A small set of named triggers—FPGA supply disruption, cloud-native adoption inflection, and India smart city procurement acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Display Panel Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Backlit Displays Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Head Up Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Video Wall Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Wireless Display Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Display Port Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Commercial Display Market