
 Asia-Pacific E-Paper Display Market | 2026-2036
Asia-Pacific E-Paper Display Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific E-Paper Display Market Insights
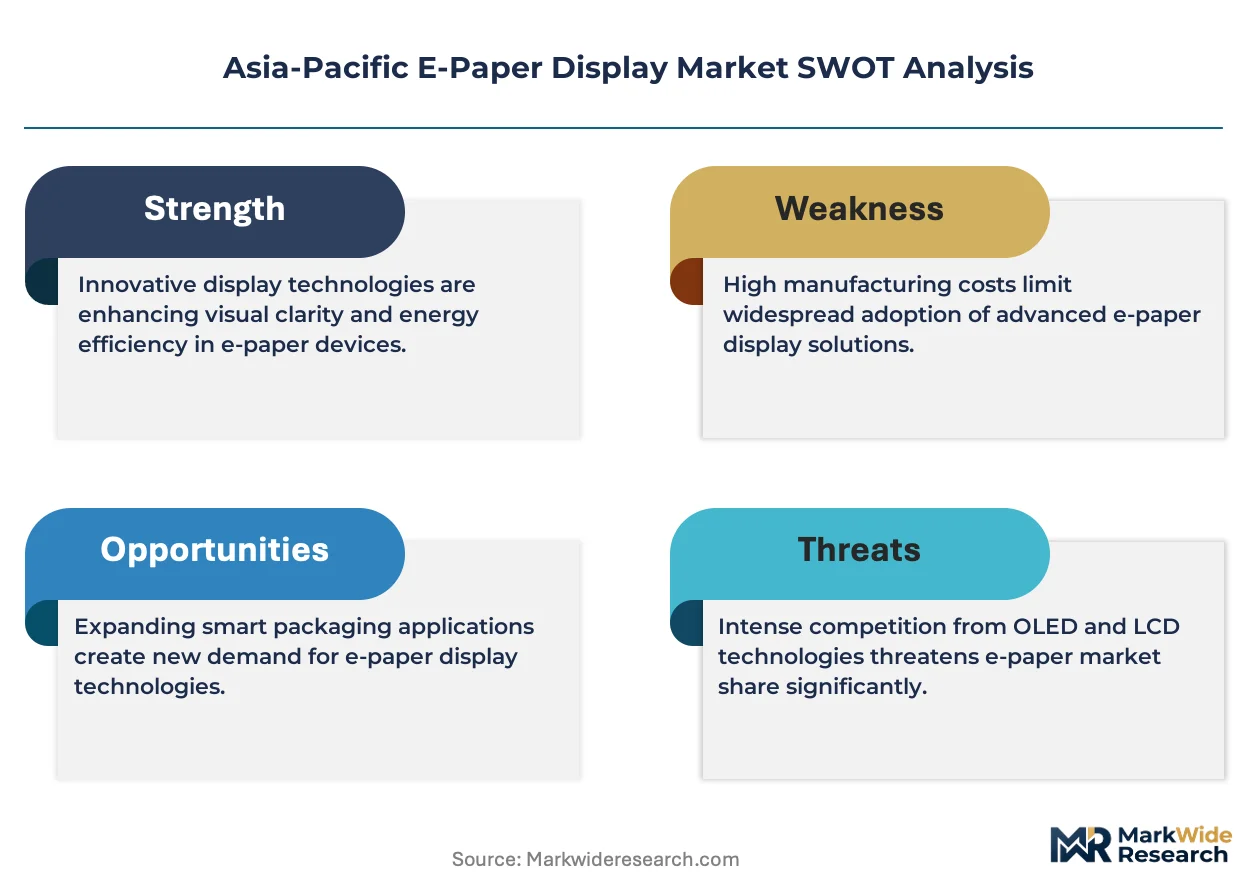
Modular display kits bundling electrophoretic panels with wireless controllers and cloud content management is broadening procurement options for mid-size retailers across the region. E Ink Holdings leverages captive microcapsule manufacturing to sustain margin control across its module shipments. BOE Technology Group anchors high-volume production through its G6 fab lines in Hefei. Guangzhou OED Technologies competes on cost-engineered flexible display variants for logistics tagging applications.
E-paper displays are non-emissive screens that rely on electrically charged pigment particles suspended in microcapsules to form images visible under ambient light, consuming power only during image updates. Their primary commercial purpose centers on static information presentation where battery longevity and daylight readability outweigh color fidelity requirements. Electrophoretic technology dominates installed capacity due to manufacturing maturity and bistable image retention, while flexible displays represent the fastest-expanding margin pool as rollable substrate processing improves. Digital signage applications capture disproportionate value per unit compared to commodity smart labels, though the latter ships at substantially higher volumes across Asia-Pacific logistics networks.
China's MIIT enforces GB standards on electronic display energy consumption that directly favor e-paper in public infrastructure tenders, while Japan's METI promotes low-power device deployment through its Green Innovation Fund procurement guidelines. South Korea's MFDS and KCC certification requirements for wearable medical displays create regulated entry pathways for health-monitoring e-paper wristbands. Stakeholders must track evolving substrate supply agreements between Japanese PET film suppliers and Chinese panel integrators to anticipate cost inflection points in flexible display manufacturing.
Market Dynamics
China's MIIT energy efficiency mandates are compressing procurement timelines for ultra-low-power display alternatives across public infrastructure tenders, while Japanese PET film suppliers negotiate substrate supply agreements that determine cost inflection points in flexible panel manufacturing.
Growth Catalysts
- Dual carbon policy enforcement:China's MIIT GB standards on electronic display energy consumption favor e-paper in government tenders for transit signage and municipal information boards.
- Convenience store digitization:Retail chains in Japan and South Korea deploy battery-free shelf labels to reduce wiring infrastructure in dense urban locations.
- Electrophoretic manufacturing maturity:Bistable image retention technology enables multi-year battery life in logistics tagging applications across Asia-Pacific distribution networks.
Market Restraints
- Liquid crystal substitution in dynamic content:LCD and OLED panels retain cost advantages for video-capable signage where refresh frequency exceeds e-paper technical limits.
- Microcapsule pigment supply concentration:Japanese chemical suppliers control electrophoretic particle formulations, exposing integrators to input cost volatility and allocation constraints.
- Color fidelity ceiling:Electrophoretic displays remain limited to 4,096 colors versus millions for emissive alternatives, restricting adoption in brand-critical retail environments.
Strategic Opportunities
- Indonesian retail modernization:Archipelago logistics complexity and grid reliability issues create white space for solar-powered e-paper signage in convenience store expansion.
- Medical wearable certification pathway:South Korea's MFDS and KCC requirements for health-monitoring wristbands establish regulated entry for low-power biometric displays.
- Flexible substrate convergence:Rollable PET film processing combined with thin-film transistor backplanes enables curved installation in automotive interior applications.
Industry Challenges
- Microelectronics integration talent scarcity:Panel integrators face shortages of engineers experienced in bonding electrophoretic films to active matrix backplanes at volume scale.
- Multi-jurisdiction certification timelines:Products must sequentially clear Japan's METI efficiency guidelines, China's MIIT GB standards, and South Korea's KCC electromagnetic compliance before regional rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific E-Paper Display Market |
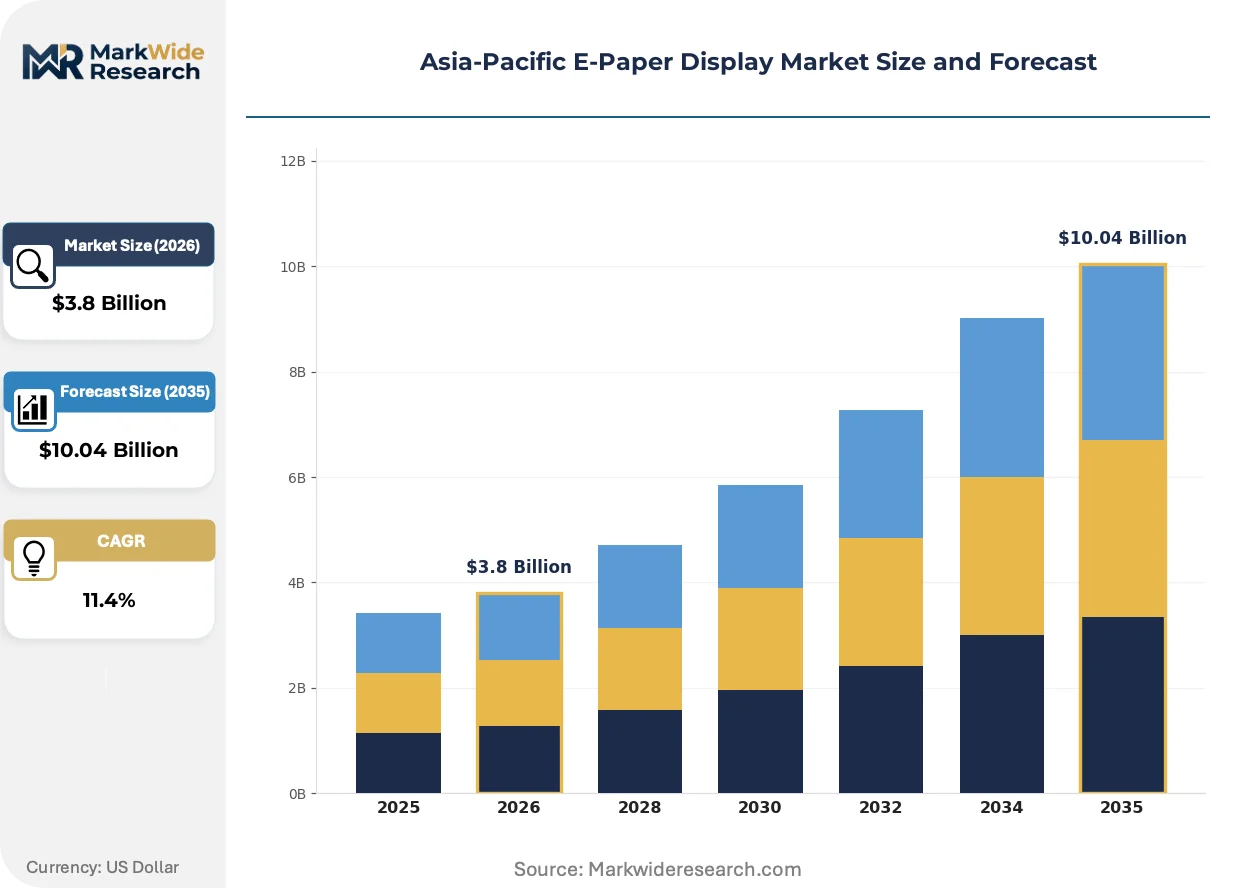
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Color Displays, Flexible Displays, Smart Labels, Digital Signage Application: Retail Signage, E-Readers, Wearable Devices, Transportation Technology: Electrophoretic, Electrochromic, Electrofluidic, Other Technologies End User: Consumer Electronics, Advertising, Logistics, Education |
| Companies Covered | E Ink Holdings Inc., Guangzhou OED Technologies Co., Ltd., Pervasive Displays Inc., LG Display Co., Ltd., Samsung Electronics Co., Ltd., Toppan Printing Co., Ltd., BOE Technology Group Co., Ltd., AUO Corporation, Sony Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific E-Paper Display Market Trends and Innovations
Electrophoretic technology is consolidating its position in static information display while flexible substrate processing opens adjacent application categories previously closed to rigid-panel formats.
Color electrophoretic film stacks are overtaking monochrome alternatives in retail shelf-edge applications where promotional content requires basic color differentiation without video capability. Japanese convenience store operators specify three-color panels for promotional pricing zones, compressing monochrome unit demand in high-visibility installations. This transition is overtaking legacy black-white-red configurations as the default specification in new chain-wide rollouts.
Japan's METI Green Innovation Fund procurement guidelines now require documented lifecycle power consumption in public infrastructure display tenders, directly advantaging electrophoretic technology over emissive alternatives. Municipal transit authorities in Osaka and Fukuoka have incorporated these metrics into technical evaluation scoring. South Korean local governments are adapting similar evaluation frameworks for bus shelter information systems.
Mid-size retailers across the region now source modular display kits bundling electrophoretic panels with wireless controllers and cloud content management rather than procuring components separately. Systems integrators in China's Yangtze River Delta electronics corridor are consolidating these bundles under single-SKU procurement contracts. This pattern is most visible in Vietnam's emerging convenience store sector, where foreign franchise operators specify turnkey digital signage packages to accelerate outlet commissioning timelines.
Asia-Pacific E-Paper Display Market Segmentation
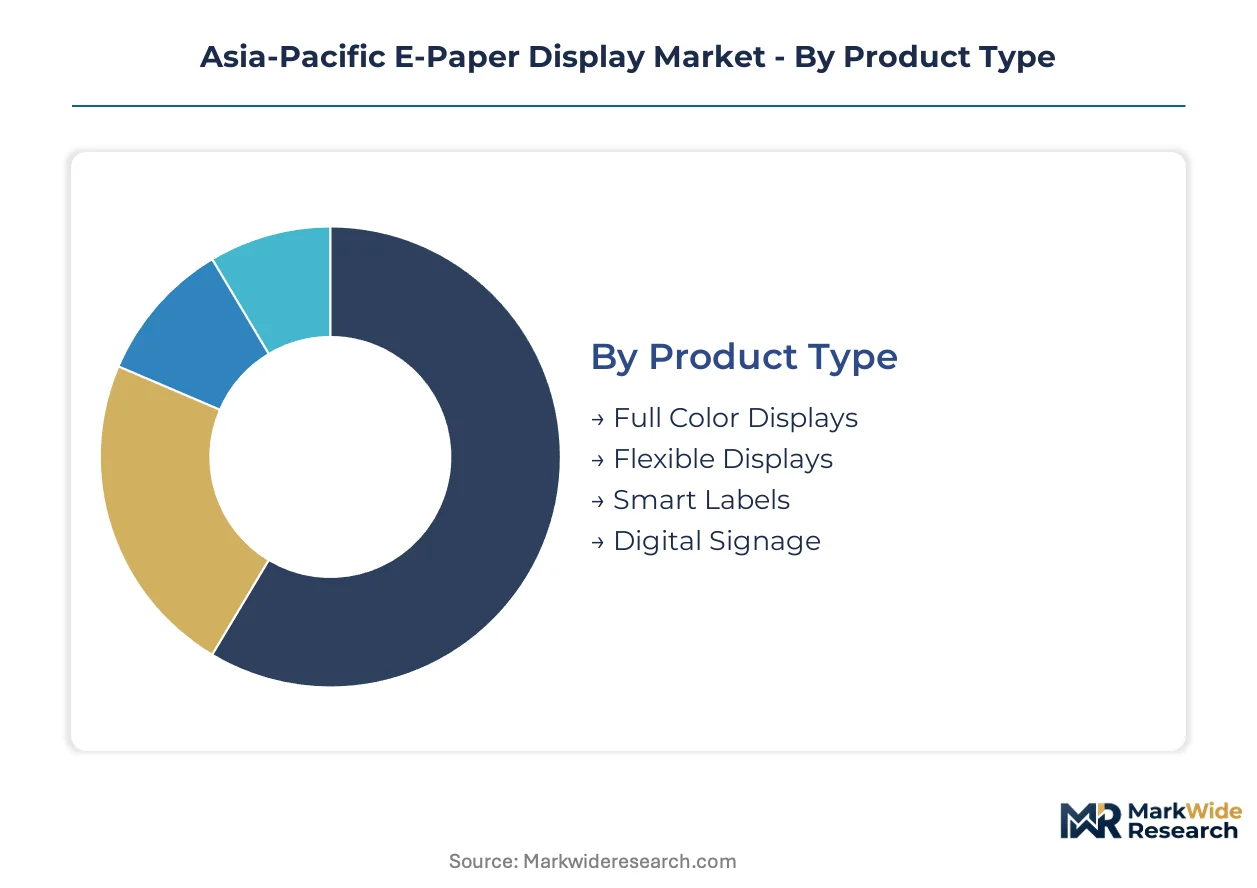
E-paper display procurement varies sharply across technical specifications and deployment contexts. Segment boundaries reflect capital requirements, regulatory pathways, and power-consumption tradeoffs that shape vendor positioning across the Asia-Pacific electronics corridor.
Product Type:
Capital intensity escalates from commodity smart labels through specialized flexible substrates to full-color electrophoretic stacks requiring precision film deposition equipment.
- Digital Signage:Large-format panels integrate active matrix thin-film transistor backplanes with electrophoretic film layers. Transit authorities in Osaka and municipal boards in China's Yangtze River Delta corridor specify these for outdoor information systems where MIIT energy efficiency standards apply.
- Flexible Displays:Rollable PET substrate processing demands bonding expertise between electrophoretic films and plastic backplanes. Japanese PET film suppliers negotiate substrate supply agreements that determine cost inflection points for logistics tagging applications across Asia-Pacific distribution networks.
- Full Color Displays:Advanced pigment microcapsule formulations enable 4,096-color rendering for promotional retail zones.
- Smart Labels:Battery-free passive designs dominate high-volume logistics tagging with multi-year operational lifespans.
Most installed capacity flows through Smart Labels. Expansion is steepest in Flexible Displays.
Application:
Demand patterns diverge between static information presentation and intermittent refresh use cases, with battery longevity requirements determining segment viability.
- Retail Signage:Shelf-edge and promotional displays exploit bistable image retention to eliminate wiring infrastructure. Convenience store chains in Japan and South Korea deploy three-color panels for promotional pricing zones, compressing monochrome unit demand in high-visibility installations.
- Transportation:Bus shelter information systems and transit platform displays must satisfy METI Green Innovation Fund procurement guidelines in Japan and emerging evaluation frameworks in South Korean local governments. Lifecycle power consumption metrics directly advantage electrophoretic technology over emissive alternatives in technical evaluation scoring.
- E-Readers:Monochrome electrophoretic panels serve dedicated reading devices with daylight-optimized contrast ratios.
- Wearable Devices:Low-power biometric displays face MFDS and KCC certification requirements in South Korea for health-monitoring wristbands.
Volume concentrates in Retail Signage. Value per unit peaks in Transportation.
Technology:
Manufacturing maturity and bistable image retention characteristics separate commercially viable approaches from emerging alternatives still seeking scale.
- Electrophoretic:Electrically charged pigment particles suspended in microcapsules form images visible under ambient light, consuming power only during updates. This technology dominates installed capacity due to manufacturing maturity and multi-year battery life in logistics tagging applications across Asia-Pacific distribution networks.
- Electrochromic:Solid-state thin-film systems enable switching between color states through ion intercalation, finding niche applications in automotive interior components where curved installation requirements favor flexible substrate convergence.
- Electrofluidic:Oil-and-water pixel architectures promise faster refresh rates for limited video capability.
- Other Technologies:Experimental approaches including electrowetting and interferometric modulator displays remain pre-commercial.
Production gravity centers on Electrophoretic. Electrochromic is gaining share fastest in automotive interior applications.
End User:
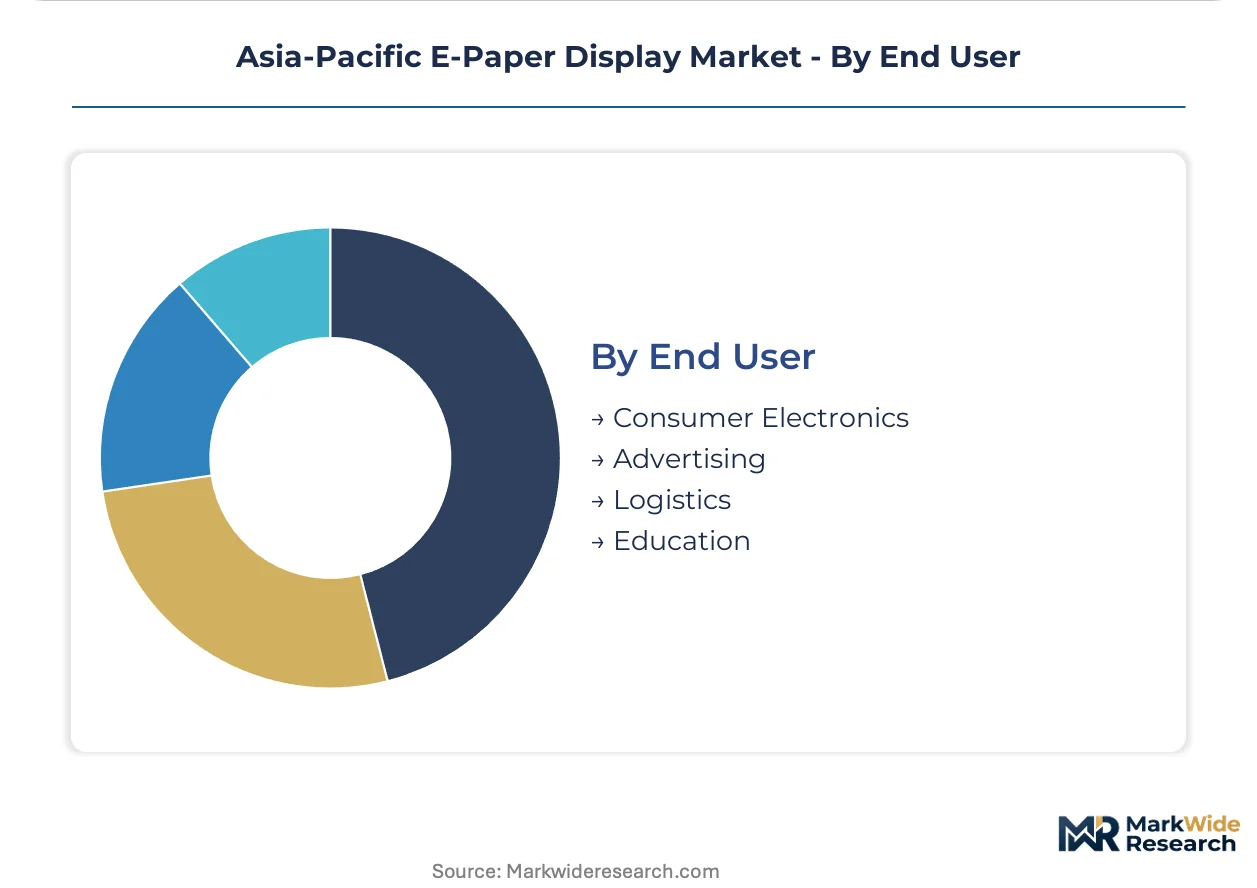
Procurement sophistication ranges from standardized component purchasing in logistics to turnkey systems integration in advertising and education.
- Logistics:High-volume tagging applications across Asia-Pacific distribution networks prioritize battery longevity and daylight readability over color fidelity. Mid-size retailers now source modular display kits bundling electrophoretic panels with wireless controllers and cloud content management rather than procuring components separately.
- Advertising:Brand-critical retail environments demand basic color differentiation without video capability, driving specification of three-color panels over legacy black-white-red configurations in new chain-wide rollouts.
- Consumer Electronics:Dedicated reading devices and niche wearables require specialized form factors.
- Education:E-textbook and classroom display applications face budget constraints favoring lower-cost monochrome alternatives.
Shipment volumes peak in Logistics. Margin expansion concentrates in Advertising.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-paper display manufacturing first achieved commercial scale in Japan during the early 2000s, with electrophoretic technology maturing through successive generations of e-reader applications before expanding into signage and logistics tagging across the Asia-Pacific electronics corridor.
China
MIIT energy efficiency mandates under GB standards favor ultra-low-power displays in government tenders for transit signage and municipal information boards. The Yangtze River Delta electronics manufacturing corridor concentrates panel integration capacity, with Hefei-based G6 fab lines anchoring high-volume production of active matrix thin-film transistor backplanes.
Japan
Convenience store chains deploy three-color shelf-edge panels to eliminate wiring infrastructure in dense urban locations. METI Green Innovation Fund procurement guidelines require documented lifecycle power consumption metrics, directly advantaging electrophoretic technology in municipal transit authority tenders across Osaka and Fukuoka.
South Korea
Battery-free retail signage adoption accelerates across convenience store chains seeking to reduce electrical infrastructure costs. MFDS and KCC certification requirements establish regulated entry pathways for health-monitoring e-paper wristbands, creating compliance barriers for non-domestic suppliers.
Taiwan
Specialized foundry services support electrophoretic film bonding to flexible plastic backplanes for logistics tagging applications. New Taipei City and Hsinchu Science Park host precision manufacturing clusters serving rollable substrate processing demands across Asia-Pacific distribution networks.
Vietnam
Emerging convenience store sector procurement specifies turnkey digital signage packages to accelerate outlet commissioning timelines. Foreign franchise operators source modular display kits bundling electrophoretic panels with wireless controllers through Yangtze River Delta systems integrators.
Asia-Pacific E-Paper Display Market Competitive Landscape
The competitive structure tilts toward vertically integrated electrophoretic film manufacturers with captive microcapsule production capabilities. Market concentration reflects high capital barriers in precision film deposition equipment and active matrix backplane bonding expertise. Two strategic archetypes dominate: diversified display conglomerates with internal module assembly lines, and specialized electrophoretic technology licensors controlling pigment formulation IP. Capacity expansion and strategic technology licensing represent the primary competitive vectors as regional demand diversifies beyond e-readers into signage and logistics applications.
Among Taiwan and China-based panel specialists, E Ink Holdings Inc., BOE Technology Group Co., Ltd., and AUO Corporation occupy distinct positions across the value chain. E Ink Holdings exemplifies the technology-licensor archetype with historical roots in electrophoretic microcapsule development. BOE Technology Group represents the scale-driven diversified conglomerate model with integrated G6 fab operations. AUO Corporation sits within the flexible substrate specialist tier, leveraging precision manufacturing capabilities for rollable display applications. Guangzhou OED Technologies Co., Ltd. anchors cost-engineered production for high-volume logistics tagging segments.
| Leading Market Players |
|---|
| E Ink Holdings Inc. |
| Guangzhou OED Technologies Co., Ltd. |
| Pervasive Displays Inc. |
| LG Display Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Toppan Printing Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| AUO Corporation |
| Sony Corporation |
| Others |
Pricing and Supply Chain Analysis
Japan's convenience store chains demanding three-color electrophoretic panels for promotional zones are forcing module integrators to absorb pigment microcapsule cost premiums from Japanese chemical suppliers, compressing margins on standardized monochrome units while elevating pricing power for color-capable manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates module procurement. Premium tiers command higher pricing from full-color electrophoretic stacks with MIIT GB standard compliance for transit signage tenders. Standard tiers serve monochrome digital shelf labels across South Korean retail chains. Economy tiers address battery-free passive smart labels for high-volume logistics tagging. Price differentiation hinges on certification grade for China public infrastructure and volume scale for convenience store rollouts. Cost compression in economy tiers is intensifying because BOE Technology Group's G6 fab lines in Hefei are expanding active matrix backplane supply. Logistics operators exhibit highest price sensitivity; municipal transit authorities in Osaka and Fukuoka show lowest sensitivity due to METI Green Innovation Fund lifecycle power consumption mandates.
Supply Chain Analysis
Refurbishment flows for electrophoretic display modules remain underdeveloped across the Asia-Pacific corridor, with end-of-life panels from Japanese convenience store rollouts typically discarded rather than recovered for secondary logistics applications. Manufacturing concentration rests on China, Japan, and Taiwan. Hefei anchors high-volume backplane production. Japanese PET film suppliers control flexible substrate supply. Taiwanese foundries specialize in electrophoretic film bonding. Raw material dependencies draw from electrophoretic pigment microcapsules, active matrix thin-film transistor glass, and rollable PET substrates. Single-source vulnerability in Japanese chemical supplier pigment formulations exposes integrators to allocation constraints. Distribution runs through Yangtze River Delta systems integrators bundling panels with wireless controllers and cloud content management for mid-size retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where South Korea's MFDS and KCC certification requirements for wearable medical displays create compliance barriers that domestic players exploit against Chinese cost-engineered alternatives.
For Market Incumbents: Lock in captive microcapsule supply agreements with Japanese chemical suppliers to defend against input cost volatility threatening margin structures. Expand G6 fab capacity in Hefei to capture MIIT-mandated public infrastructure tenders before LCD substitution pressures intensify in dynamic content applications. For New Entrants and Emerging Players: Launch via modular display kit partnerships with Yangtze River Delta systems integrators to bypass direct backplane bonding expertise requirements. Target Vietnam's emerging convenience store sector where foreign franchise operators seek turnkey digital signage packages with accelerated commissioning timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with flexible substrate specialists possessing rollable PET film processing capabilities for automotive interior applications. Long-term viability over the next decade hinges on substrate convergence enabling curved installations beyond traditional static signage. Watch for inflection signals in Japanese PET film supplier expansion announcements indicating cost inflection points in flexible panel manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microcapsule Manufacturing | E Ink Holdings' captive pigment production sustains margin control against Japanese chemical supplier concentration. |
| Flexible Substrate Capacity Expansion | AUO Corporation's rollable PET processing opens automotive interior applications previously closed to rigid formats. |
| MIIT GB Standard Certification Investment | Compliance with China's energy efficiency mandates secures transit signage and municipal board procurement preference. |
| Modular Display Kit Partnership | Systems integrators in the Yangtze River Delta consolidate single-SKU procurement for Vietnam convenience store expansion. |
| Wearable Medical Device Regulatory Pathway | MFDS and KCC certification investments unlock South Korean health-monitoring wristband market entry barriers. |
Research Methodology
Multiple input streams — primary interviews with electrophoretic module procurement managers, display technology R&D directors, and logistics operations heads; secondary validation through MIIT GB standard filings, METI Green Innovation Fund procurement guidelines, and customs trade data — were reconciled through bottom-up shipment tracking and top-down market sizing triangulation.
Historical capacity utilization rates from Hefei G6 fab operations were cross-referenced against panel input from Japanese PET film suppliers and Taiwanese bonding foundries. Segmentation dimensions modeled include product type, application, technology, and end user across the projection horizon. CAGRs were derived from shipment volume trajectories and value-per-unit expansion in color electrophoretic transitions. Forecast inputs incorporated MIIT dual carbon policy enforcement timelines and convenience store digitization capex cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt LCD cost compression or Japanese pigment microcapsule supply disruptions. Practitioners should monitor METI procurement guideline revisions and MFDS wearable certification pathway updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Smart Screen Market
Display Technologies
Portable Projector Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Head-Mounted Display Market
Display Technologies
PMOLED Display Market
Display Technologies
Rugged Display Market
Display Technologies
E-Paper Display Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Head Up Display Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Touch and Display Integration IC for Tablet Market