
 Global Strain Wave Gearing Devices Market | 2026-2036
Global Strain Wave Gearing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Strain Wave Gearing Devices Market Outlook
Collaborative robotics OEMs are redrawing demand patterns for strain wave gearing devices as cobot deployments displace legacy industrial robot architectures across assembly and material-handling lines. Harmonic Drive Systems Inc. leverages its Nagano manufacturing base to sustain premium positioning in zero-backlash harmonic drives for semiconductor wafer handling. Shenzhen Han's Motion Technology competes aggressively on cost-optimized cycloidal variants targeting domestic Chinese automation integrators. Leaderdrive anchors its growth on integrated servo-actuator modules that embed strain wave gearboxes for medical imaging equipment.
Strain wave gearing devices employ a flexible spline deformed by a wave generator to achieve high reduction ratios in compact envelopes, typically operating with positional accuracy below one arc-minute and torque densities exceeding conventional planetary systems by factors of three to five. Their primary purpose is delivering precise rotary motion in space-constrained mechanisms where backlash elimination and weight reduction prove critical. Harmonic drive configurations dominate installed value across semiconductor and aerospace applications where envelope constraints are most severe. Cycloidal drive formats are gaining fastest in industrial automation as Chinese suppliers improve surface finish tolerances on cam profiles. Precision gear segments concentrate margin pools in medical device applications where FDA-validated lot traceability commands pricing premiums over standard industrial grades.
Japan's METI enforces JIS B 8398 standards for harmonic drive fatigue life testing, while China's SAMR mandates GB/T compliance for precision reducer safety in collaborative robot installations under its robotics industry development guidelines. The EU Machinery Directive and CE marking requirements impose functional safety validation on strain wave gearboxes deployed in European automotive production lines. Stakeholders must monitor how Japan's PMDA and the FDA align their evolving expectations for surgical robot joint reliability as next-generation telesurgery platforms place unprecedented duty-cycle demands on miniature harmonic drive units.
Market Dynamics
Collaborative robotics OEMs are redrawing demand patterns for strain wave gearing devices as cobot deployments displace legacy industrial robot architectures across assembly and material-handling lines. China's MIIT precision component standards and Japan's METI fatigue testing protocols are compressing supplier margins while elevating technical barriers to entry.
Growth Catalysts
- Semiconductor wafer handling:Sub-micron positioning requirements in lithography and inspection equipment are mandating zero-backlash harmonic drives with arc-second repeatability.
- Japan's METI JIS B 8398 standards:Fatigue life certification protocols are filtering out low-reliability suppliers and consolidating procurement around validated manufacturers.
- Surgical robotics:Minimally invasive telesurgery platforms are demanding miniature harmonic drives with duty cycles exceeding 10 million input revolutions.
Market Restraints
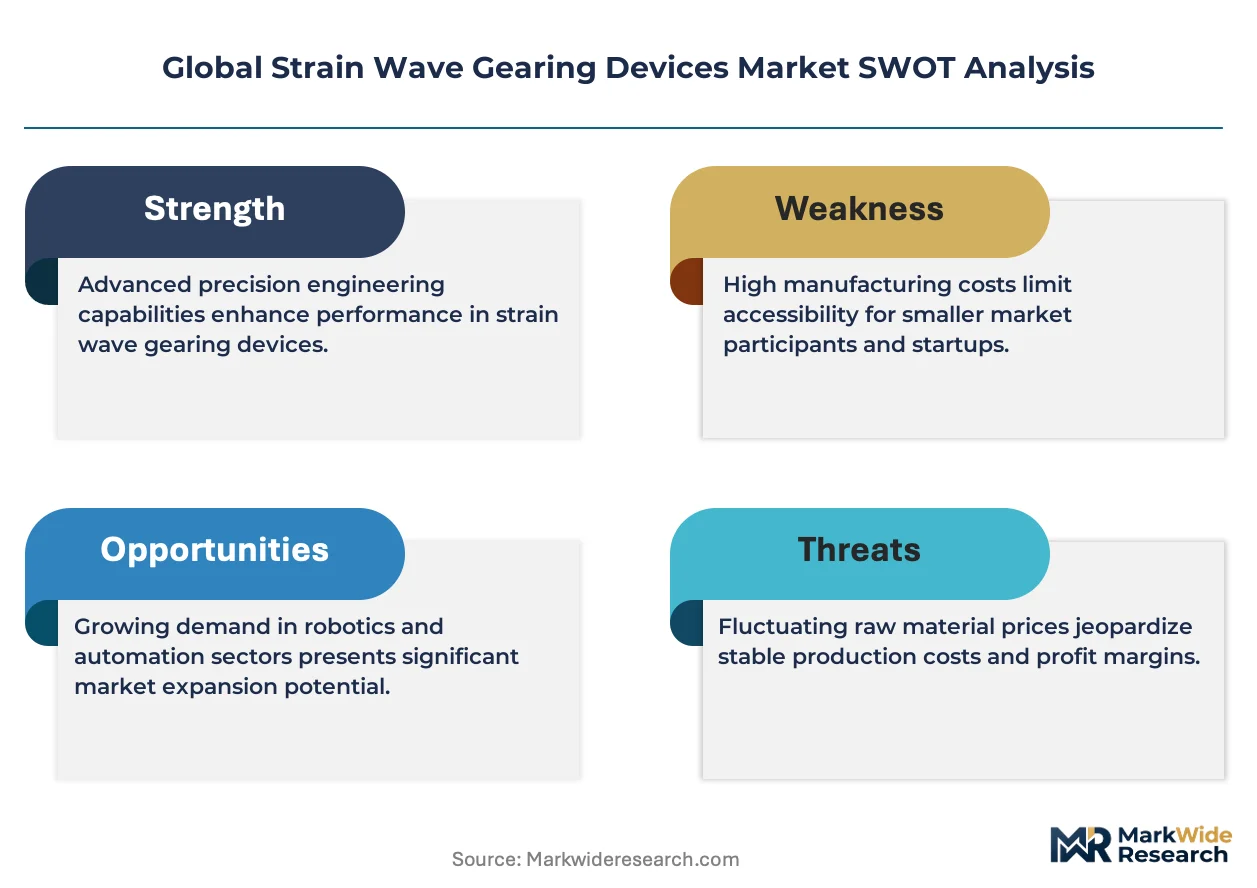
- Specialized steel alloys:Flexspline material costs fluctuate with nickel and high-purity steel spot markets, compressing gross margins on standard industrial grades.
- Nagano Prefecture supplier concentration:Overreliance on a single Japanese manufacturing cluster creates geographic risk exposure for global OEM procurement teams.
- Cycloidal drive substitution:Chinese manufacturers are improving cam profile tolerances, enabling lower-cost alternatives in non-precision automation segments.
Strategic Opportunities
- Integrated servo-actuator modules:Embedding strain wave gearboxes with hollow-shaft frameless motors is reducing assembly complexity for medical imaging OEMs.
- India's PLI scheme for robotics:Production-linked incentives are attracting component localization investments from Japanese and European suppliers.
- GB/T compliance pathways:China's precision reducer safety standards for collaborative robots are creating certified supplier qualification opportunities for foreign manufacturers.
Industry Challenges
- Wave generator bearing specialists:The shallow talent pool for precision bearing design and flexspline fatigue analysis is extending R&D timelines for new product introductions.
- FDA-PMDA alignment gaps:Divergent reliability documentation requirements for surgical robot joints are forcing dual-track validation programs that extend time-to-market by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Strain Wave Gearing Devices Market |
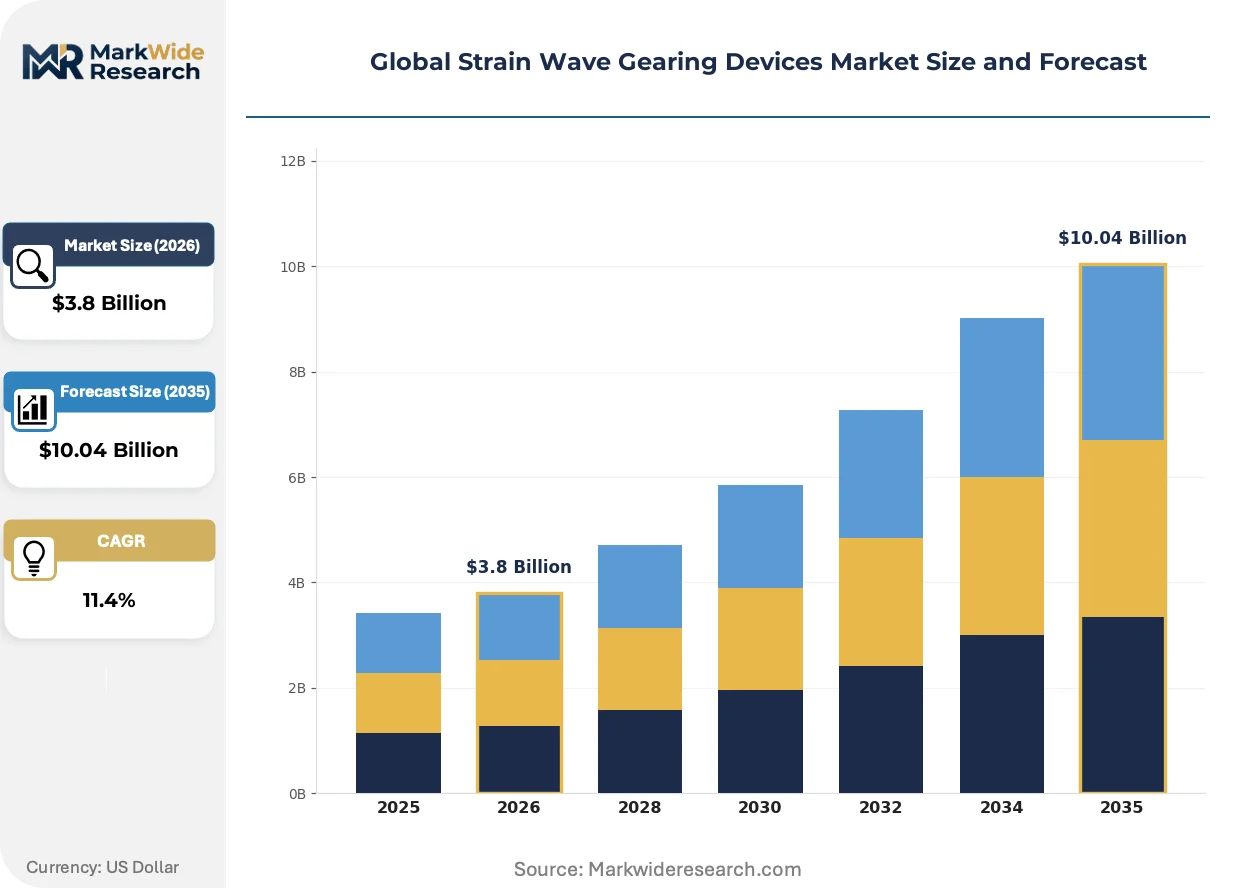
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harmonic Drive, Cycloidal Drive, Gearbox, Precision Gear End User: Aerospace, Robotics, Medical Devices, Automotive Application: Industrial Automation, Defense, Telecommunications, Motion Control Installation: Integrated, Standalone, Modular, Customizable |
| Companies Covered | Shenzhen Han's Motion Technology, HDSI, Harmonic Drive Systems Inc., BHDI, Beijing CTKM Harmonic Drive, Leaderdrive, Nidec-Shimpo, Cone Drive, Zhejiang Laifual, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Strain Wave Gearing Devices Market Strategic Shifts
Material science breakthroughs and regulatory harmonization pressures are restructuring competitive advantage in precision motion control. Three developments are reshaping how strain wave gearing devices are specified, manufactured, and deployed across high-value applications.
Advanced ceramic flexsplines employing silicon nitride matrix composites are displacing conventional steel alloys in vacuum and cleanroom environments where outgassing and magnetic permeability constraints exclude metallic alternatives. Semiconductor equipment OEMs in South Korea and Taiwan are qualifying these configurations for EUV lithography wafer stages. The shift is compressing addressable market share for traditional steel-flexspline suppliers in the most demanding precision segments.
The EU Machinery Directive's updated functional safety requirements for collaborative robot joints are mandating ISO 13849-1 Category 3 performance levels on strain wave gearboxes deployed in European automotive lines. German and Italian integrators are now requiring SIL 2/PL d documentation from drive suppliers as a condition of RFQ participation. This regulatory elevation is filtering out uncertified Asian suppliers from premium European automation procurement channels.
Direct-to-OEM technical specification platforms are fragmenting traditional distribution relationships as large robotics manufacturers build in-house gearing expertise and negotiate frame contracts with Nagano-based producers. Tier-one automotive and aerospace buyers are bypassing regional distributors to secure lot-traceable supply chains for FDA-validated and AS9100-certified components. This channel compression is most visible in North American medical device and defense applications where supply chain documentation requirements exceed distributor capabilities.
Global Strain Wave Gearing Devices Market Segmentation
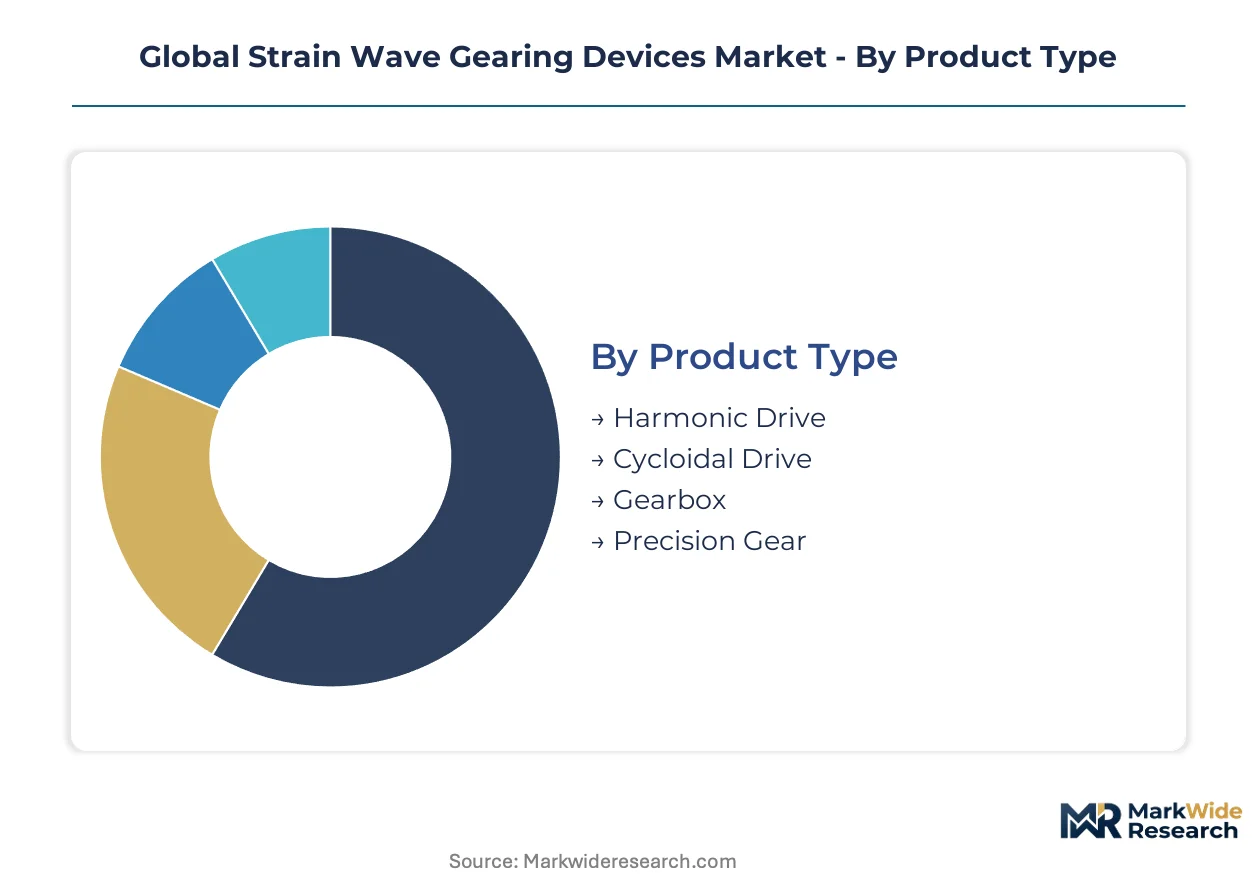
Strain wave gearing devices fragment across four dimensions that dictate procurement priorities and margin capture. Product type determines technical specifications and certification burdens, while end-user concentration shapes geographic demand clusters and regulatory exposure.
Product Type:
Margin pools concentrate in configurations demanding sub-arcminute repeatability and validated fatigue life documentation under JIS B 8398 protocols.
- Harmonic Drive:Employs a flexible spline deformed by an elliptical wave generator to achieve reduction ratios exceeding 100:1 in compact envelopes. Semiconductor wafer handling equipment in South Korea and Taiwan mandates these configurations for EUV lithography stages where zero backlash proves non-negotiable.
- Cycloidal Drive:Rolling element transmission using eccentric cam profiles and needle bearings to distribute load across multiple contact points. Chinese automation integrators in Shenzhen and Guangzhou are qualifying cost-optimized variants for material handling lines where arc-minute precision suffices.
- Gearbox:Enclosed reduction units integrating strain wave elements with input shafts and output flanges for drop-in installation.
- Precision Gear:Validated components with lot traceability and AS9100 or FDA-compliant documentation for aerospace and surgical robotics.
The dominant share belongs to Harmonic Drive, while Cycloidal Drive is closing the gap fastest.
End User:
Volume concentrates in sectors deploying collaborative robot architectures across assembly and logistics operations.
- Robotics:Collaborative robot OEMs specify compact harmonic drives for six-axis articulated arms and SCARA configurations. China's MIIT precision component standards and Japan's METI fatigue protocols are elevating technical barriers for suppliers serving this segment.
- Medical Devices:Surgical robotics manufacturers procure miniature harmonic drives with duty cycles exceeding 10 million input revolutions for telesurgery platforms. FDA and PMDA alignment gaps on joint reliability documentation extend validation timelines.
- Aerospace:Satellite positioning mechanisms and aircraft flight control systems demand lightweight, vacuum-compatible configurations.
- Automotive:European production lines under EU Machinery Directive requirements impose ISO 13849-1 Category 3 functional safety validation on gearbox suppliers.
Robotics commands the largest installed base, with Medical Devices expanding most quickly on surgical automation demand.
Application:
Specification intensity varies with positional accuracy requirements and environmental exposure.
- Industrial Automation:Assembly lines and material handling systems specify strain wave gearboxes for pick-and-place and packaging machinery. German and Italian integrators now require SIL 2/PL d documentation as a condition of RFQ participation under updated EU safety mandates.
- Motion Control:Medical imaging equipment and semiconductor inspection platforms demand integrated servo-actuator modules embedding hollow-shaft frameless motors.
- Defense:Gimbal stabilization and unmanned vehicle turrets prioritize shock resistance and extended temperature operation.
- Telecommunications:Antenna positioning and satellite ground station tracking mechanisms utilize compact reduction units.
Industrial Automation retains the deepest penetration, while Motion Control is gaining share fastest on medical and semiconductor equipment demand.
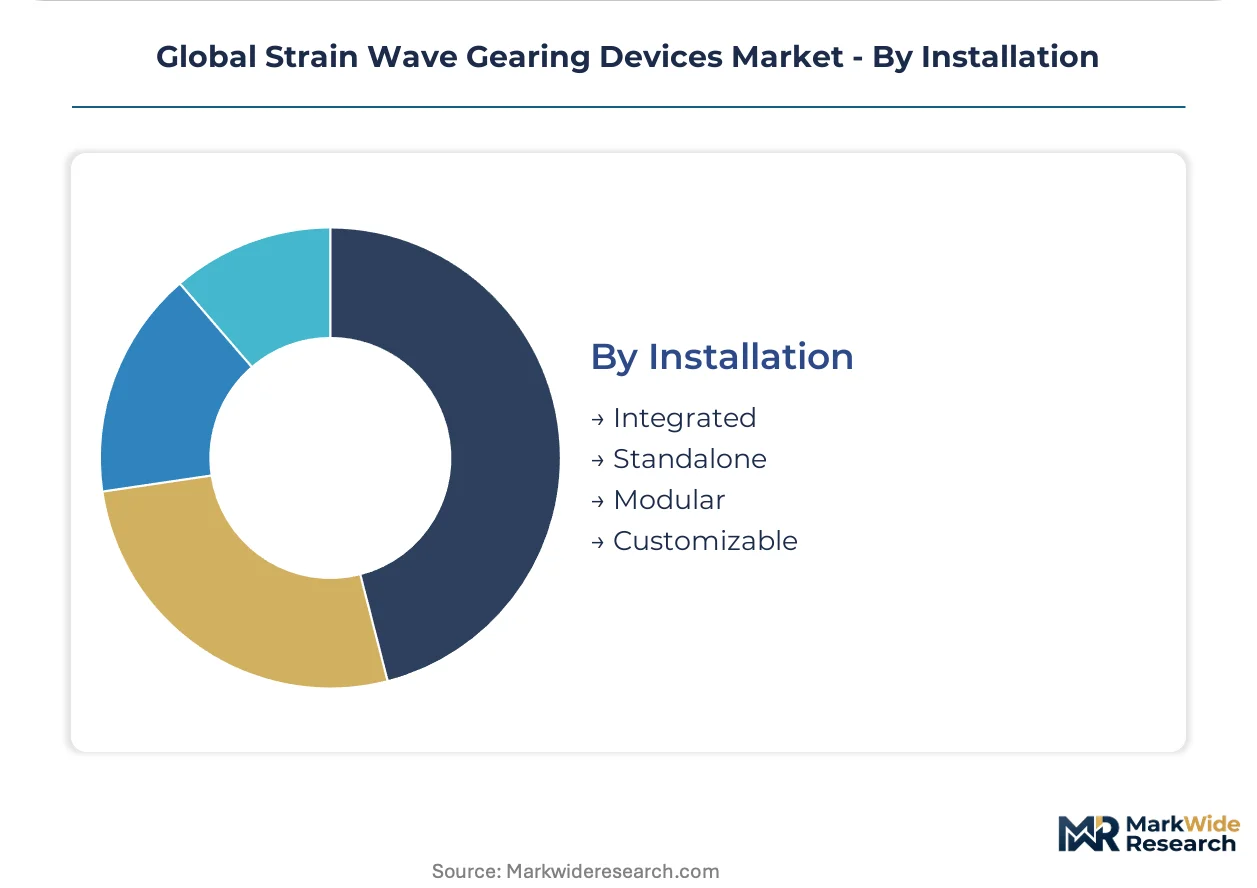
Installation:
Supply chain configuration determines assembly complexity and aftermarket service obligations.
- Integrated:Pre-assembled actuator modules combining strain wave gearboxes with motors, encoders, and controllers reduce OEM engineering overhead. Leaderdrive and similar suppliers anchor growth strategies on these configurations for medical imaging OEMs.
- Modular:Standardized interface dimensions enable rapid substitution across robot joint designs.
- Standalone:Discrete gearbox units for legacy system retrofits and custom mechanism integration.
- Customizable:Engineer-to-order configurations with modified shaft geometries, mounting patterns, and environmental sealing for defense and aerospace programs.
Integrated formats dominate new equipment procurement, with Customizable variants climbing fastest on defense and satellite program requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Nagoya anchors Japan's precision manufacturing corridor, channeling high-torque harmonic drive assemblies to semiconductor and aerospace OEMs across East Asia. This infrastructure asset underwrites the region's dominance in strain wave gearing supply chains.
Japan
Nagano Prefecture hosts concentrated production capacity for zero-backlash harmonic drives serving semiconductor wafer handling equipment. METI enforces JIS B 8398 fatigue life certification protocols that filter procurement toward validated manufacturers. Harmonic Drive Systems Inc. maintains premium positioning from its Nagano manufacturing base for EUV lithography stages.
China
Shenzhen and Guangzhou automation integrators drive demand for cost-optimized cycloidal variants in material handling lines. MIIT precision component standards under advanced manufacturing policy tighten tolerances on cam profile surface finishes. Leaderdrive anchors growth on integrated servo-actuator modules embedding strain wave gearboxes for domestic medical imaging OEMs.
South Korea
Semiconductor equipment manufacturers in Suwon and Pyeongtaek qualify advanced ceramic flexsplines for EUV lithography wafer stages. The national industrial regulator mandates alignment with ISO precision reducer safety frameworks for collaborative robot installations. Samsung and SK Hynix supply chain clusters concentrate specification authority in Gyeonggi Province.
Germany
Automotive production lines in Stuttgart and Munich impose ISO 13849-1 Category 3 functional safety validation on strain wave gearbox suppliers. The EU Machinery Directive and CE marking requirements filter uncertified Asian manufacturers from premium procurement channels. German integrators now require SIL 2/PL d documentation as a condition of RFQ participation.
United States
Surgical robotics OEMs in Boston and San Francisco procure miniature harmonic drives with duty cycles exceeding 10 million input revolutions. FDA reliability documentation requirements for telesurgery platforms extend validation timelines for joint components. Defense contractors in Southern California specify AS9100-certified precision gears for satellite positioning mechanisms.
Global Strain Wave Gearing Devices Market Competitive Environment
Concentration sits with Japanese precision manufacturers and Chinese cost-optimized suppliers competing across distinct tier positions. The vendor base separates into three strategic archetypes: Nagano-based premium harmonic drive specialists, Shenzhen-area cycloidal fabricators, and integrated servo-actuator module suppliers. M&A activity targets hollow-shaft motor technology assets, while capacity expansion concentrates in India's PLI scheme corridors.
Among Japanese specialists, Harmonic Drive Systems Inc. and Nidec-Shimpo exemplify the premium-tier archetype with established fatigue life certification protocols. Shenzhen Han's Motion Technology and Zhejiang Laifual occupy positions within China's cost-optimized cycloidal segment. Leaderdrive represents the integrated module strategy embedding gearboxes with frameless motors for medical imaging applications.
| Leading Market Players |
|---|
| Shenzhen Han's Motion Technology |
| HDSI |
| Harmonic Drive Systems Inc. |
| BHDI |
| Beijing CTKM Harmonic Drive |
| Leaderdrive |
| Nidec-Shimpo |
| Cone Drive |
| Zhejiang Laifual |
| Others |
Value Chain & Pricing Dynamics
Long-term frame contracts with Nagano-based producers lock in supply access for tier-one automotive and aerospace buyers while anchoring price visibility across multi-year procurement cycles. These arrangements concentrate volume commitments around JIS B 8398-certified manufacturers, compressing spot-market liquidity for standard industrial grades and amplifying cost differentials between validated and uncertified supply tiers.
Pricing Analysis
Volume-discount tiering structures separate FDA-validated precision gears from standard industrial grades and uncertified Chinese cycloidal variants. Price differentiation hinges on certification grade under JIS B 8398 and ISO 13849-1 Category 3 compliance, with European automotive buyers commanding steeper discounts at scale than medical device OEMs requiring lot traceability. Cost compression in standard industrial tiers is intensifying as Shenzhen-area suppliers improve cam profile tolerances and erode margin pools. Robotics integrators in material handling prove most price-sensitive, while semiconductor equipment OEMs prioritize arc-second repeatability over unit cost.
Supply Chain Analysis
Nagano Prefecture manufacturing clusters in Japan, Shenzhen-Guangzhou fabrication corridors in China, and Suwon-Pyeongtaek equipment hubs in South Korea concentrate global production capacity for strain wave gearing devices. Flexspline fabrication draws from specialized nickel-alloy steel mills, precision bearing specialists, and advanced ceramic matrix composite foundries. Single-source vulnerability around wave generator bearing design talent extends R&D timelines and concentrates supplier power. Distribution runs through direct-to-OEM frame contracts that bypass traditional distributors for AS9100-certified and FDA-validated components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shallow talent pool for precision bearing design and flexspline fatigue analysis concentrates capability scarcity with incumbent Nagano specialists, elevating acquisition premiums for hollow-shaft motor technology assets and extending competitive moats around validated manufacturing processes.
For Market Incumbents: Fortify JIS B 8398 certification barriers by embedding ceramic flexspline R&D capabilities and expanding capacity under India's PLI scheme corridors. Cycloidal drive substitution from Chinese suppliers threatens standard industrial margins, demanding upstream control over specialized nickel-alloy steel supply to defend cost positions in premium tiers. For New Entrants and Emerging Players: Lead with integrated servo-actuator modules targeting medical imaging OEMs in China's domestic market, where GB/T compliance pathways create certified supplier qualification opportunities. India's robotics production-linked incentives offer the most penetrable geography for component localization investments, with hollow-shaft frameless motor partnerships as the critical go-to-market angle. For Investors and Strategic Acquirers: Precision ceramic flexspline specialists with vacuum-compatible manufacturing capabilities represent the highest-value acquisition archetype as semiconductor equipment OEMs displace steel alloys. Long-term viability rests on positioning for EUV lithography wafer stage demand and surgical robotics duty-cycle requirements. Watch FDA-PMDA alignment progress on joint reliability documentation as the inflection indicator for miniature harmonic drive valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flexspline Material Supply | Captive nickel-alloy steel sourcing defends margin compression from spot market volatility. |
| Ceramic Flexspline Manufacturing Scale-Up | Silicon nitride matrix production qualifies suppliers for EUV lithography wafer stage procurement. |
| Integrated Servo-Actuator Module Development | Hollow-shaft frameless motor embedding reduces medical imaging OEM assembly complexity. |
| GB/T Compliance Certification Investment | China's precision reducer safety standards open certified supplier qualification for foreign manufacturers. |
| India PLI Scheme Manufacturing Footprint | Production-linked incentives attract Japanese and European component localization investments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork with collaborative robot OEM procurement teams, semiconductor equipment engineering directors, surgical robotics joint reliability specialists, and precision reducer distribution channel managers. Secondary validation incorporated METI regulatory filings, FDA 510(k) surgical robot submissions, MIIT advanced manufacturing policy documents, and EU Machinery Directive implementation guidance. Bottom-up unit demand modeling triangulated against top-down value chain analysis across the forecast period.
Across the analysis window, projections integrated product type segmentation by harmonic versus cycloidal configurations, end-user concentration across robotics and medical device verticals, application intensity in industrial automation versus motion control, and installation format preferences from integrated modules to customizable defense programs. CAGRs derived from elasticity-adjusted demand curves incorporating semiconductor capital expenditure cycles, surgical robotics FDA approval pipelines, and collaborative robot deployment trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EUV lithography investment cycles, harmonized FDA-PMDA reliability standards, or China's domestic substitution acceleration would require recalibration. Forecasts reflect documented assumptions regarding certification timeline trajectories and raw material supply continuity. Practitioners should keep alternative scenarios live as regulatory harmonization pressures and ceramic flexspline qualification rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Contour Measuring Machines Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Fusion Splicer Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market