
 North America Head-Up Display Market | 2026-2036
North America Head-Up Display Market Size, Share, and Industry Trends Forecast 2026-2036
North America Head-Up Display Market Analytics
Optical waveguide integration is fragmenting the traditional combiner-based HUD architecture into modular, software-defined display stacks. Continental AG leverages its captive optics manufacturing in Mexico to sustain cost advantages across Tier 1 supply contracts. Garmin Ltd. differentiates through aftermarket motorcycle and marine HUD modules that occupy niche verticals outside OEM automotive channels. BAE Systems dominates military aviation HUD programs with radiation-hardened display cores that extend operational lifecycles beyond commercial equivalents.
A Head-Up Display projects real-time operational data onto a transparent surface within the user's forward field of view, typically employing a projector unit, optical combiner, and video processing controller operating at luminance levels exceeding 15,000 candela per square meter to maintain readability in direct sunlight. The primary commercial purpose centers on reducing cognitive load and glance duration away from critical operational environments such as vehicle forward paths or aircraft approach vectors. Augmented Reality HUD configurations command the deepest engineering investment as automakers integrate ADAS overlay symbology with live environmental meshing. OLED display technology leads premium positioning due to contrast ratio superiority, though DLP maintains share in aviation where thermal tolerance requirements exceed liquid crystal operational thresholds.
The National Highway Traffic Safety Administration shapes automotive HUD deployment through Federal Motor Vehicle Safety Standard visibility and distraction criteria, while the Federal Aviation Administration mandates synthetic vision compatibility for certificated augmented flight displays. Canada's Transport Canada aligns with U.S. HUD performance benchmarks through bilateral automotive safety reciprocity agreements, creating contiguous North American compliance corridors. Stakeholders must monitor divergence between EPA fuel-economy display mandates and state-level autonomous vehicle interface regulations as these frameworks mature.
Market Dynamics
Optical waveguide architectures are fragmenting the traditional combiner-based HUD stack into modular, software-defined systems that separate display generation from projection hardware. This decoupling enables Tier 1 suppliers to source optics from captive Mexican manufacturing while integrating processing silicon from fabless semiconductor vendors.
Growth Catalysts
- NHTSA visibility mandates:Federal Motor Vehicle Safety Standard updates for advanced driver-assistance symbology are compelling OEM integration of windshield-projected systems across electric and internal combustion vehicle lines.
- Electric vehicle interface convergence:Battery-electric platforms in the United States are standardizing on augmented reality HUD configurations as primary instrumentation, eliminating traditional gauge clusters.
- Detroit engineering corridor concentration:Proximity of Tier 1 development centers to Michigan-based OEM headquarters is compressing prototype-to-production cycles for windshield-integrated systems.
Market Restraints
- Optics input cost volatility:Precision freeform mirror substrates and holographic optical elements face supply concentration among German and Japanese specialty glass manufacturers.
- Thermal management thresholds:DLP-based aviation HUD systems require active cooling architectures that add weight and maintenance burden incompatible with light sport aircraft budgets.
- State-level autonomous interface fragmentation:Divergent California and Texas regulations for self-driving vehicle passenger displays create compliance duplication for cross-border fleet deployments.
Strategic Opportunities
- Aftermarket marine vertical:Garmin's established distribution through West Marine and Bass Pro Shops creates channel infrastructure for recreational boating HUD adoption in the Great Lakes and Gulf Coast regions.
- Canada bilateral safety reciprocity:Transport Canada alignment with U.S. Federal Motor Vehicle Safety Standards enables single-certification entry into contiguous North American automotive supply chains.
- Motorcycle helmet integration:Bluetooth-enabled waveguide modules are penetrating powersports segments where handlebar-mounted displays face vibration and weather exposure limitations.
Industry Challenges
- Optomechanical engineering talent scarcity:Cross-disciplinary expertise combining freeform lens design with real-time video processing is concentrated among aging specialists in Rochester, New York and Tucson, Arizona optics clusters.
- FAA synthetic vision certification timelines:Augmented flight display approval for general aviation requires 18-24 month validation cycles that delay revenue recognition for avionics vendors.
- Windshield laminating process integration:HUD-compatible wedge-angle interlayers demand reconfiguration of existing automotive glass fabrication lines at Pilkington and AGC facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Head-Up Display Market |
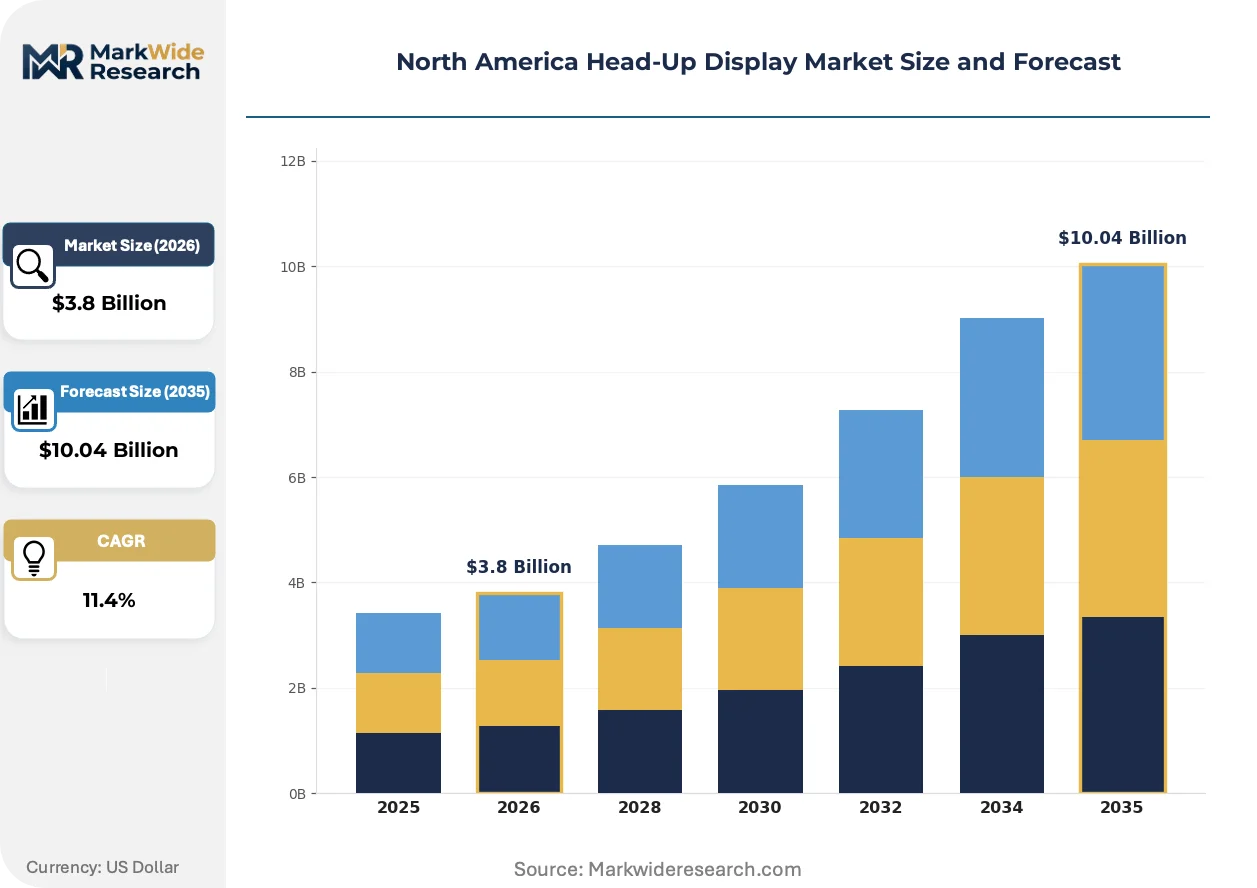
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Augmented Reality, Virtual Reality, Hybrid End User: Automotive, Aviation, Consumer Electronics, Military Display Technology: LCD, OLED, DLP, Laser Application: Navigation, Sports, Entertainment, Driver Assistance |
| Companies Covered | Nippon Seiki Co., Ltd., Continental AG, DENSO Corporation, BAE Systems, Yazaki Corporation, Visteon Corporation, Robert Bosch GmbH, Panasonic Holdings Corporation, Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Head-Up Display Market Evolving Landscape
Waveguide-based display architectures are compressing the physical envelope of automotive HUD systems while enabling field-of-view expansion beyond traditional combiner limitations. Three concurrent developments are restructuring competitive positioning across the value chain.
Surface-relief grating waveguides manufactured through nanoimprint lithography are replacing bulk optical combiners in premium automotive programs. Mercedes-Benz and BMW are qualifying these architectures for 2026 model year augmented reality HUD deployments. The technology is rendering obsolete the discrete mirror-and-lens assemblies that previously defined HUD bill-of-materials structures.
The National Highway Traffic Safety Administration's pending update to Federal Motor Vehicle Safety Standard 101 will mandate minimum luminance thresholds and glare limits for projected driver information. This regulatory pressure is accelerating OLED adoption over DLP in passenger vehicles while preserving digital micromirror technology in FAA-certificated aviation applications where thermal tolerance requirements exceed liquid crystal operational thresholds.
Fleet procurement managers at rental car and logistics operators are unbundling HUD specification from trim-level packaging, creating direct sourcing relationships with Tier 1 suppliers. This disintermediation is most visible in California's autonomous vehicle testing hubs where Waymo and Cruise are specifying custom symbology sets outside OEM standard configurations.
North America Head-Up Display Market Segmentation
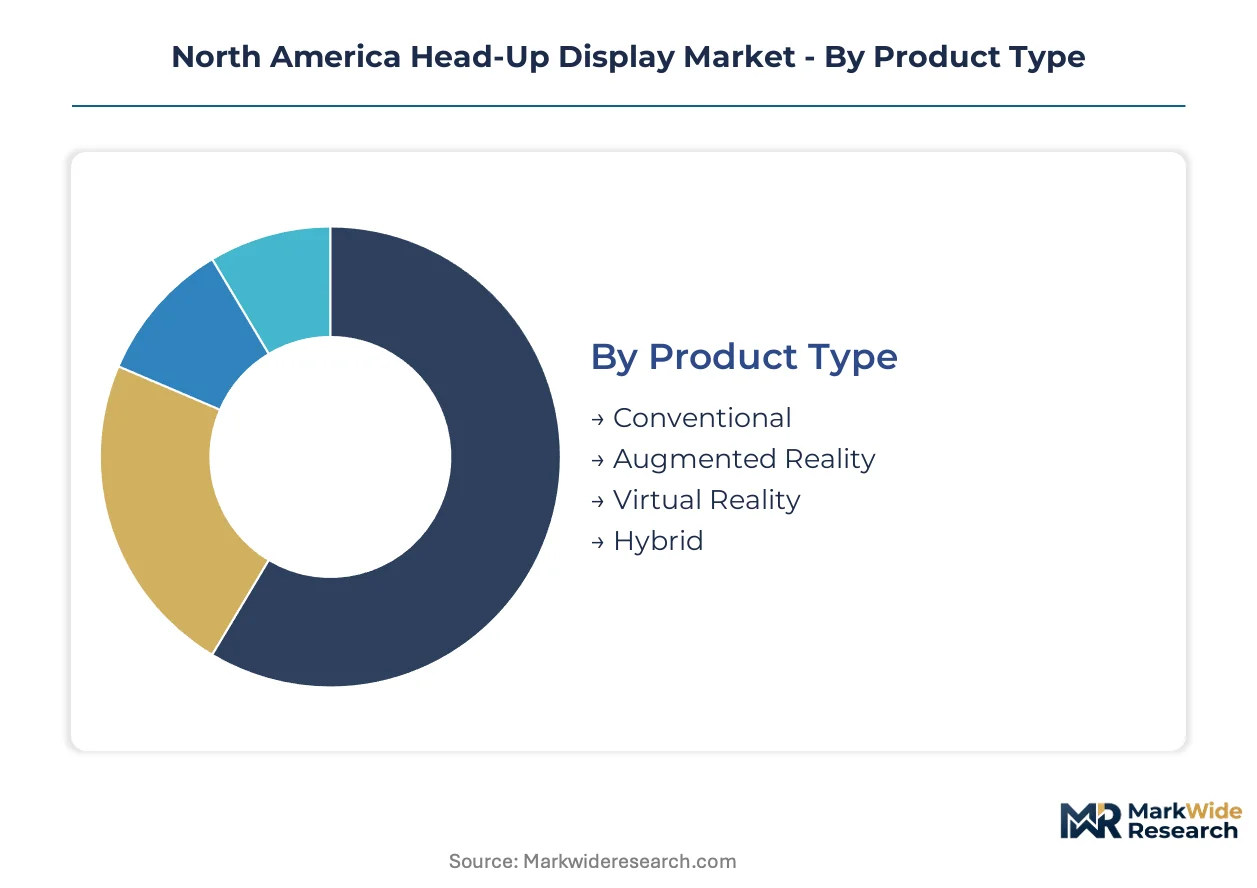
HUD market segmentation reveals divergent refresh cycles across product architectures, with automotive platforms demanding 3-5 year redesigns while military aviation programs extend to 15-year lifecycles. Understanding these temporal patterns enables suppliers to align R&D pipelines with revenue recognition timelines and inventory financing structures.
Product Type:
Conventional HUDs turn inventory fastest through standardized automotive platform integrations, while augmented reality variants face extended validation cycles for optical waveguide qualification.
- Conventional:Combines discrete projector units with freeform mirror combiners operating at 10,000-15,000 candela per square meter luminance. Michigan-based OEMs specify these for mid-trim pickup trucks and crossovers where cost containment outweighs field-of-view expansion.
- Augmented Reality:Integrates ADAS overlay symbology with real-time environmental meshing through holographic optical waveguides. California autonomous vehicle testing hubs are driving qualification timelines as Waymo and Cruise specify custom symbology sets outside standard OEM configurations.
- Virtual Reality:Enclosed field-of-view systems with full scene replacement; niche deployment in military simulation training at Fort Rucker and Naval Air Station Patuxent River.
- Hybrid:Combines partial transparency with selective occlusion zones; emerging in premium electric vehicle lines where battery-electric platforms eliminate traditional gauge clusters.
Conventional architectures dominate installed base across Detroit's manufacturing footprint. Augmented reality configurations are where expansion concentrates as NHTSA visibility mandates tighten.
End User:
Cost tier stratification separates military aviation programs with radiation-hardened requirements from consumer electronics where price elasticity compresses margins.
- Automotive:Windshield-projected systems integrated at Tier 1 supplier facilities in Mexico and Michigan. NHTSA Federal Motor Vehicle Safety Standard updates are compelling OEM integration across electric and internal combustion vehicle lines.
- Aviation:Synthetic vision compatibility mandates from the FAA extend certification timelines to 18-24 months for general aviation augmented flight displays.
- Consumer Electronics:Bluetooth-enabled waveguide modules penetrating powersports segments; Garmin leverages West Marine distribution for Great Lakes recreational boating adoption.
- Military:Radiation-hardened display cores with operational lifecycles exceeding commercial equivalents; BAE Systems dominates programs requiring extended mean-time-between-failures.
Automotive applications command volume leadership. Military programs are climbing the fastest through sole-source procurement structures.
Display Technology:
Volume concentration favors LCD for cost-sensitive automotive tiers while margin capture concentrates in OLED premium positioning.
- LCD:Liquid crystal matrices with LED backlighting; standard specification for fleet procurement managers unbundling HUD from trim-level packaging.
- OLED:Organic electroluminescent layers delivering contrast ratio superiority; Mercedes-Benz and BMW qualification for augmented reality HUD deployments.
- DLP:Digital micromirror devices with thermal tolerance exceeding liquid crystal thresholds; preserved in FAA-certificated aviation where active cooling architectures add acceptable weight.
- Laser:Scanning laser projection with infinite depth of field; emerging in motorcycle helmet integration where vibration resistance outweighs cost premiums.
LCD maintains installed base dominance through scale economies. OLED is gaining share fastest as luminance mandates from NHTSA accelerate adoption over DLP in passenger vehicles.
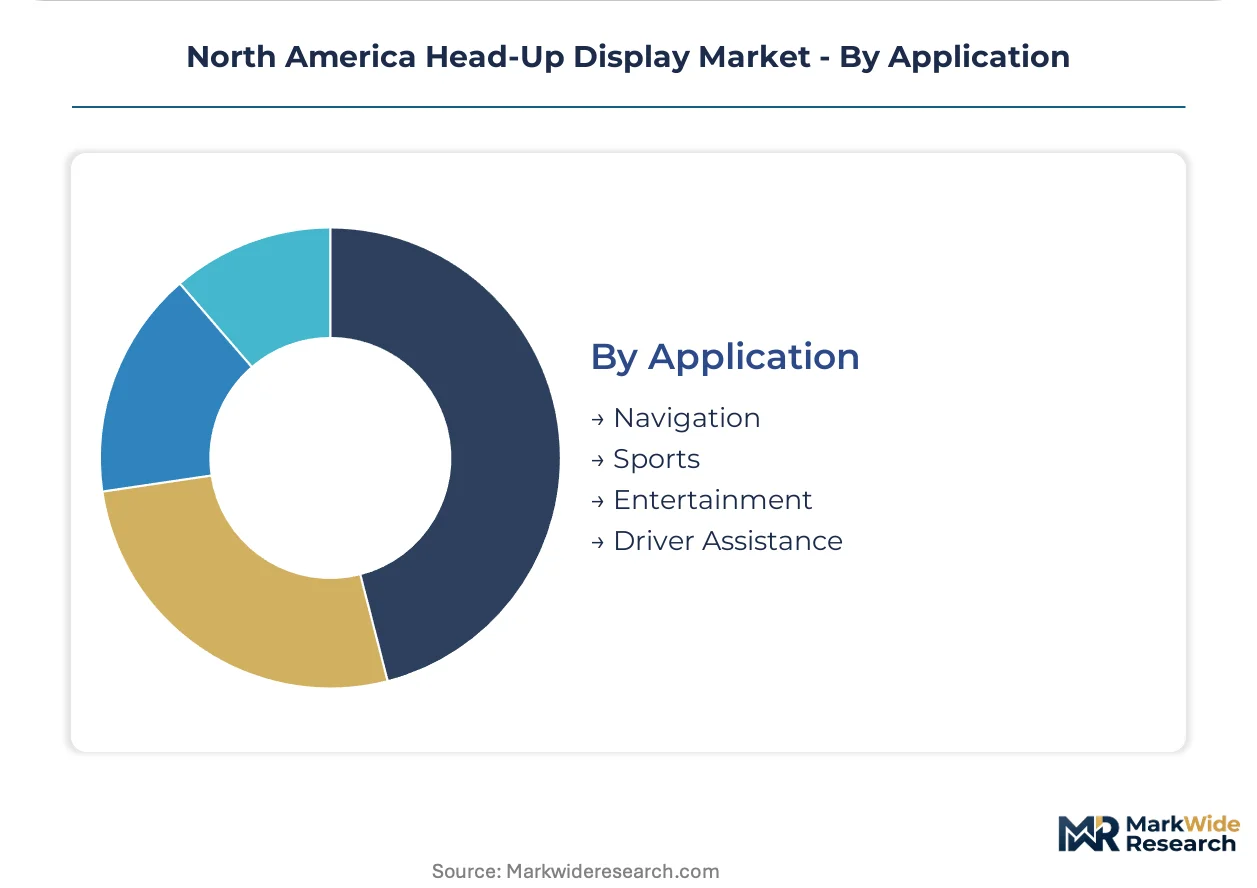
Application:
Customer type fragmentation separates enterprise fleet procurement from individual consumer preference in aftermarket channels.
- Navigation:Turn-by-turn overlay symbology with real-time traffic integration; standard feature in California autonomous vehicle testing corridors.
- Sports:Performance telemetry for marine and powersports verticals; Garmin's aftermarket modules occupy niches outside OEM automotive channels.
- Entertainment:Media projection with passenger-view occlusion; constrained by NHTSA glare limits and distraction criteria.
- Driver Assistance:ADAS symbology including lane-keeping and collision warnings; expanding field-of-view requirements are displacing conventional combiner architectures.
Driver assistance applications anchor current deployment. Sports and marine verticals are expanding most quickly through specialty distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican manufacturing corridors export precision optical components to Tier 1 integration facilities across the United States and Canada, sustaining contiguous North American supply chain flows for windshield-projected display systems.
United States
Detroit's automotive engineering corridor compresses prototype-to-production cycles for windshield-integrated HUD systems, while California's autonomous vehicle testing hubs drive qualification timelines for augmented reality configurations. The National Highway Traffic Safety Administration updates Federal Motor Vehicle Safety Standard 101 to mandate minimum luminance thresholds for projected driver information. Michigan-based OEM headquarters concentrate specification authority for mid-trim pickup trucks and crossovers.
Canada
Transport Canada maintains bilateral automotive safety reciprocity agreements with U.S. regulators, enabling single-certification entry for HUD suppliers into contiguous North American supply chains. The country's national transportation regulator aligns performance benchmarks with NHTSA visibility and distraction criteria. Ontario-based glass fabrication facilities reconfigure laminating processes to accommodate HUD-compatible wedge-angle interlayers for cross-border OEM contracts.
Mexico
Continental AG leverages captive optics manufacturing in Mexican industrial zones to sustain cost advantages across Tier 1 supply contracts for windshield-projected systems. The country's federal economic development programs incentivize automotive component localization under the United States-Mexico-Canada Agreement. Nuevo León and Bajío Region production clusters supply precision freeform mirror substrates to Michigan-based integration facilities.
North America Head-Up Display Market Competitive Landscape
On the supply side, the industry is tiered between diversified automotive electronics conglomerates and specialized optical component fabricators. Tier 1 suppliers dominate volume contracts through backward integration into captive Mexican manufacturing, while niche players occupy aftermarket verticals outside OEM channels. Two strategic archetypes define competitive positioning: diversified automotive electronics suppliers with multi-platform integration capabilities, and specialized avionics vendors with radiation-hardened display cores. Dominant competitive moves include strategic partnerships for waveguide technology licensing and portfolio diversification into powersports and marine aftermarket segments.
Among diversified automotive electronics suppliers, Continental AG and Robert Bosch GmbH exemplify the Tier 1 integration archetype through multi-platform supply relationships. Garmin Ltd. occupies a distinct position within specialized aftermarket distribution, leveraging established channels for recreational boating and powersports applications outside standard OEM procurement structures.
| Leading Market Players |
|---|
| Nippon Seiki Co., Ltd. |
| Continental AG |
| DENSO Corporation |
| BAE Systems |
| Yazaki Corporation |
| Visteon Corporation |
| Robert Bosch GmbH |
| Panasonic Holdings Corporation |
| Garmin Ltd. |
| Others |
Value Network & Pricing Analysis
Nuevo León's precision optics manufacturing clusters feed Tier 1 integration facilities across Michigan and Ontario, concentrating cost leverage among suppliers with captive waveguide production while compressing margins for fabless competitors dependent on merchant foundry access.
Pricing Analysis
Current-generation OLED waveguide modules command substantial premiums over prior-generation DLP combiner assemblies, while next-generation laser-scanning architectures remain pre-commercial with undefined pricing. Three-tier pricing structure across premium, standard, and economy levels separates augmented reality HUD configurations from conventional combiner systems and aftermarket motorcycle modules. Pricing pressure stems from fleet procurement managers unbundling HUD specification from trim-level packaging, forcing direct negotiation with Tier 1 suppliers. Automotive OEMs exhibit highest price sensitivity through volume consolidation tactics, while military aviation programs demonstrate lowest sensitivity due to radiation-hardening requirements and sole-source procurement structures.
Supply Chain Analysis
Export controls on holographic optical element manufacturing equipment limit technology transfer to Chinese and Russian entities, constraining supplier diversification for precision waveguide substrates. Geographic supply concentration centers on Germany and Japan for specialty glass substrates, Mexico for freeform mirror fabrication, and Taiwan for display driver silicon. Raw material dependencies include rare-earth phosphors for high-luminance projection, precision aluminum alloys for thermal management housings, and photoresist chemicals for nanoimprint lithography. Single-source vulnerability persists for holographic optical element masters produced at Rochester, New York facilities. Distribution runs through Tier 1 supplier integration at OEM assembly plants rather than aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waveguide technology maturation combined with NHTSA luminance mandates creates a regulatory-technology inflection accelerating HUD adoption across electric vehicle platforms.
For Market Incumbents: Insulate core optical engineering capabilities through backward integration into captive Mexican manufacturing while accelerating certification investment for FAA synthetic vision programs. Threat substitution from fabless semiconductor vendors entering waveguide controller silicon demands defensive patent portfolio expansion. Priority lever rests on channel control through exclusive supply agreements with Detroit-based OEM platform engineers. For New Entrants and Emerging Players: Canada's single-certification entry pathway under Transport Canada reciprocity agreements offers the most penetrable geographic expansion corridor for HUD suppliers lacking established U.S. Tier 1 relationships. Aftermarket marine verticals through Great Lakes recreational boating channels present adjacent white-space with lower competitive density than automotive OEM procurement. Go-to-market angle should emphasize Bluetooth-enabled helmet integration for powersports segments where vibration tolerance requirements exceed incumbent product specifications. For Investors and Strategic Acquirers: Long-term, this sits as a automotive-electrification-cyclical play because battery-electric platform standardization on augmented reality HUD configurations eliminates traditional gauge cluster suppliers while creating sustained content-per-vehicle expansion. Acquisition target archetype: specialized waveguide design houses with aging founder-technologists in Rochester or Tucson optics clusters. Signal to watch: FAA certification timeline compression for general aviation augmented flight displays as indicator of regulatory friction easing.| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Technology Licensing | Enables Tier 1 suppliers to source optics from fabless vendors while retaining integration control. |
| Captive Manufacturing Expansion | Continental AG leverages Nuevo León facilities to sustain cost advantages across supply contracts. |
| Aftermarket Channel Diversification | Garmin penetrates marine verticals through West Marine distribution outside OEM procurement structures. |
| FAA Certification Investment | BAE Systems extends military aviation dominance through synthetic vision compatibility mandates. |
| Fleet Procurement Direct Sourcing | Waymo and Cruise specify custom symbology sets disintermediating traditional OEM trim packaging. |
Research Methodology
A spread of perspectives from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and avionics certification specialists converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with secondary validation against NHTSA Federal Motor Vehicle Safety Standard filings, FAA certification databases, vehicle production registries, and SEC disclosures from listed automotive electronics suppliers. Bottom-up unit economics modeling triangulated against top-down market sizing from regional production cluster analysis.
Demand-supply-balance framing anchored the forecast framework across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included NHTSA regulatory timeline assumptions, electric vehicle platform rollout schedules, and waveguide manufacturing yield curves from precision optics facilities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese display technology entrants or accelerated FAA certification timeline compression would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Thin Display Technology Market
Display Technologies
Interactive Display Market
Display Technologies
OLED Laptops Market
Display Technologies
Smart Display Market
Display Technologies
Microdisplay Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
PMOLED Display Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Commercial Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Flexible OLED Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Global Next Generation Display Market