
 Global Display Controllers Market | 2026-2036
Global Display Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Display Controllers Market Analysis
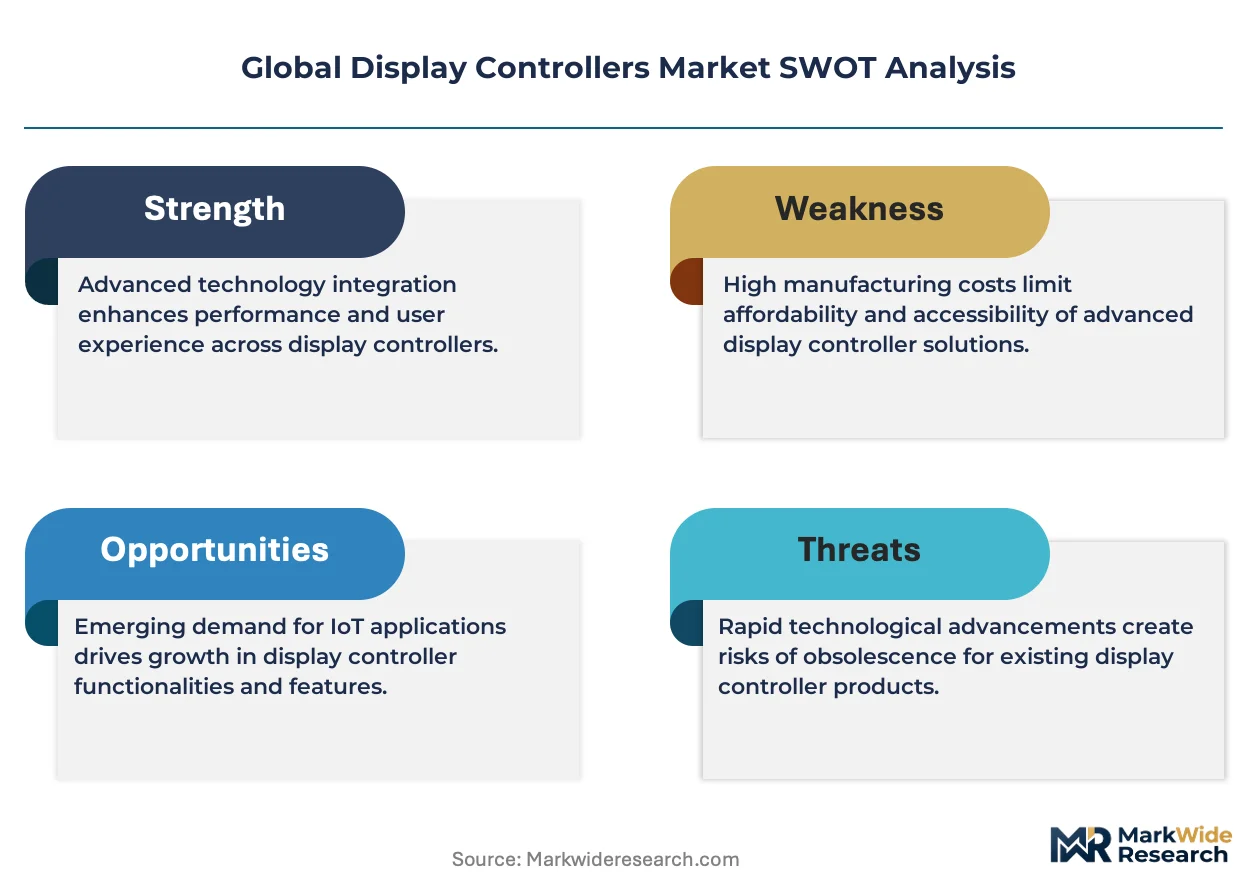
Korean semiconductor foundry expansion is realigning supply availability for high-resolution display controller chips. Samsung Electronics leverages captive wafer capacity to anchor supply security for internal display panel operations. Texas Instruments Incorporated competes through analog-digital hybrid architectures optimized for automotive instrument clusters. Novatek Microelectronics Corp. specializes in timing controller ICs for large-format LCD television panels.
Display controllers are integrated circuits that manage signal processing, timing synchronization, and pixel data routing between host processors and display panels, typically supporting resolutions from HD through 8K with refresh rates up to 240Hz. These devices translate raw video data into standardized panel-driving protocols such as LVDS, eDP, or MIPI DSI to ensure accurate color reproduction and motion clarity across electronic screens. OLED controllers command premium positioning due to complex per-pixel current regulation requirements and foldable form factor compatibility. Digital technology segments sustain the broadest addressable base across consumer electronics and automotive applications, while medical end-use applications concentrate margin pools through extended product qualification cycles and stringent reliability standards.
EU REACH and RoHS frameworks restrict hazardous substance content in display controller packaging and substrate materials, compelling suppliers to reformulate lead-free solder compositions and halogen-free laminates. FDA 21 CFR Part 820 quality system requirements govern medical display controller validation for diagnostic imaging equipment sold in the United States. China's GB standards and MIIT technical specifications mandate electromagnetic compatibility testing for controllers deployed in domestic telecommunications infrastructure displays. Stakeholders must monitor evolving automotive functional safety standards and regional semiconductor subsidy programs to anticipate qualification burdens and capacity allocation shifts.
Market Dynamics
Automotive OEMs are mandating higher-resolution instrument clusters and center-stack displays, forcing controller suppliers to recalibrate roadmaps toward functional safety certification and extended temperature operation. This demand pull is compressing development cycles while expanding the addressable silicon content per vehicle.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating transitions to low-global-warming-potential cooling systems in display manufacturing equipment, indirectly stimulating controller demand for next-generation panel technologies.
- Automotive ADAS displays:Camera-mirror replacement systems and augmented-reality head-up displays require specialized timing controllers with sub-frame latency, opening premium sockets in electric vehicle platforms.
- China semiconductor subsidies:MIIT-directed capacity expansion in 12-inch wafer fabrication is improving foundry access for fabless controller designers serving domestic panel makers.
Market Restraints
- Foundry concentration in East Asia:Taiwan and South Korea collectively control advanced-node capacity for high-resolution controller ICs, creating geographic supply vulnerability during regional disruptions.
- EU RoHS substance restrictions:Lead-free solder mandates and halogen-free laminate requirements elevate material costs and complicate qualification of automotive-grade packages.
- OLED current-drive complexity:Per-pixel compensation circuits demand larger die sizes and more sophisticated analog design, limiting the supplier base capable of cost-competitive solutions.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for display module assembly are creating controller demand from first-time domestic television and smartphone brands.
- Medical imaging displays:Diagnostic radiology workstations require extended color gamut controllers with FDA 21 CFR Part 820 traceability, supporting margin expansion through specialized qualification.
- MIPI DSI-2 and VESA DSC convergence:Unified interface standards are enabling controller designs that serve multiple panel technologies with common silicon, reducing SKU fragmentation.
Industry Challenges
- ISO 26262 functional safety certification:Automotive instrument cluster controllers require ASIL-B or higher ratings, extending validation timelines and engineering headcount requirements.
- Legacy LVDS infrastructure:Industrial and medical equipment with decade-long service lives maintains demand for obsolete interface protocols, forcing suppliers to sustain multi-generation product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Display Controllers Market |
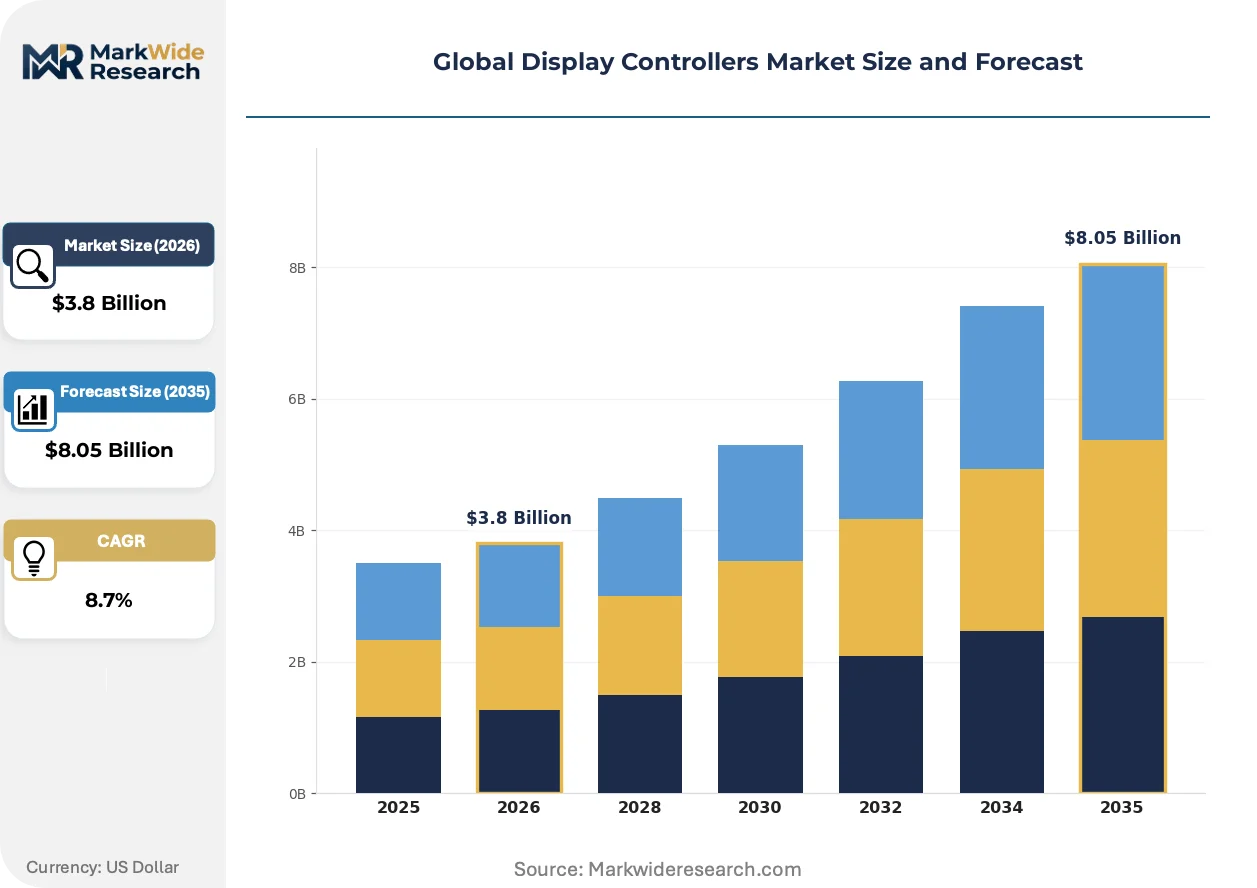
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
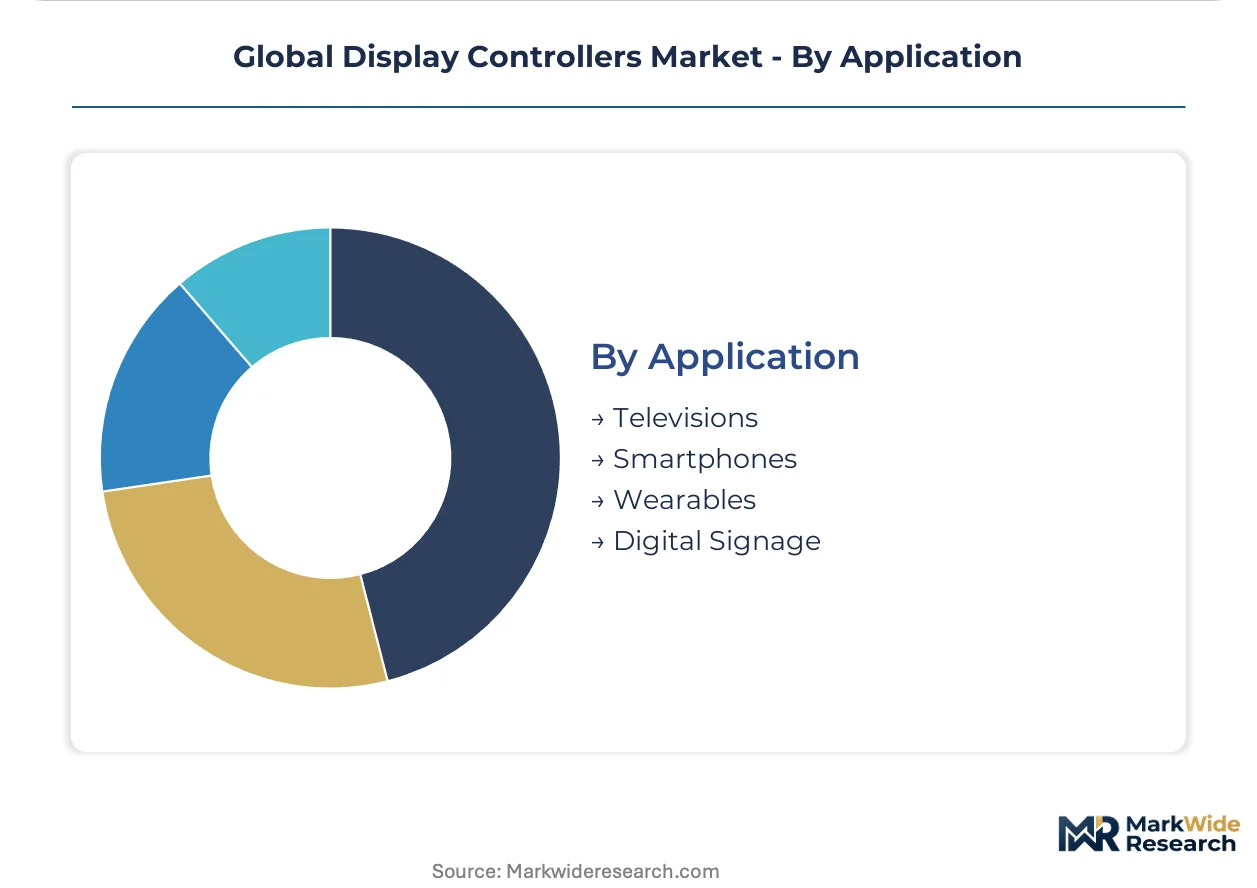
| Segmentation | Product Type: LCD Controllers, LED Controllers, OLED Controllers, DLP Controllers Technology: Analog, Digital, Hybrid, Wireless End User: Consumer Electronics, Automotive, Industrial, Medical Application: Televisions, Smartphones, Wearables, Digital Signage |
| Companies Covered | Analog Devices, Inc., Renesas Electronics Corporation, Samsung Electronics, Toshiba Infrastructure Systems & Solutions Corporation, Novatek Microelectronics Corp., LG Display Co., Ltd., NXP Semiconductors, Microchip Technology Inc., Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Display Controllers Market Emerging Trajectories
Silicon architectures are bifurcating between highly integrated SoC approaches for cost-sensitive volume markets and discrete timing-controller plus scaler combinations for premium segments demanding maximum flexibility. This divergence is reshaping R&D allocation and partnership strategies across the supply base.
Local dimming algorithms with zone counts exceeding 1000 are overtaking conventional global backlight control in mini-LED television panels. Samsung Electronics and domestic Chinese brands are adopting these controllers at accelerated cadences for 2024-2025 product cycles. The shift is overtaking traditional timing-controller ASP structures by demanding integrated image-processing capabilities previously resident in separate scaler ICs.
EU REACH substance restrictions are tightening disclosure requirements for persistent organic pollutants in semiconductor packaging materials. Controller suppliers must now document full material composition down to the sub-100 ppm level for high-volume automotive contracts. German automotive OEMs are responding by pre-qualifying packaging subcontractors with demonstrated hazardous-substance management systems.
Fleet operators and digital signage deployers are compressing procurement cycles from annual blanket orders to quarterly consumption-based replenishment. Distributors are responding with bonded inventory programs and value-added programming services for field-upgradable controller firmware. North American outdoor signage networks and European retail chains are most visibly adopting these arrangements to manage working capital against panel technology transition risk.
Global Display Controllers Market Segmentation
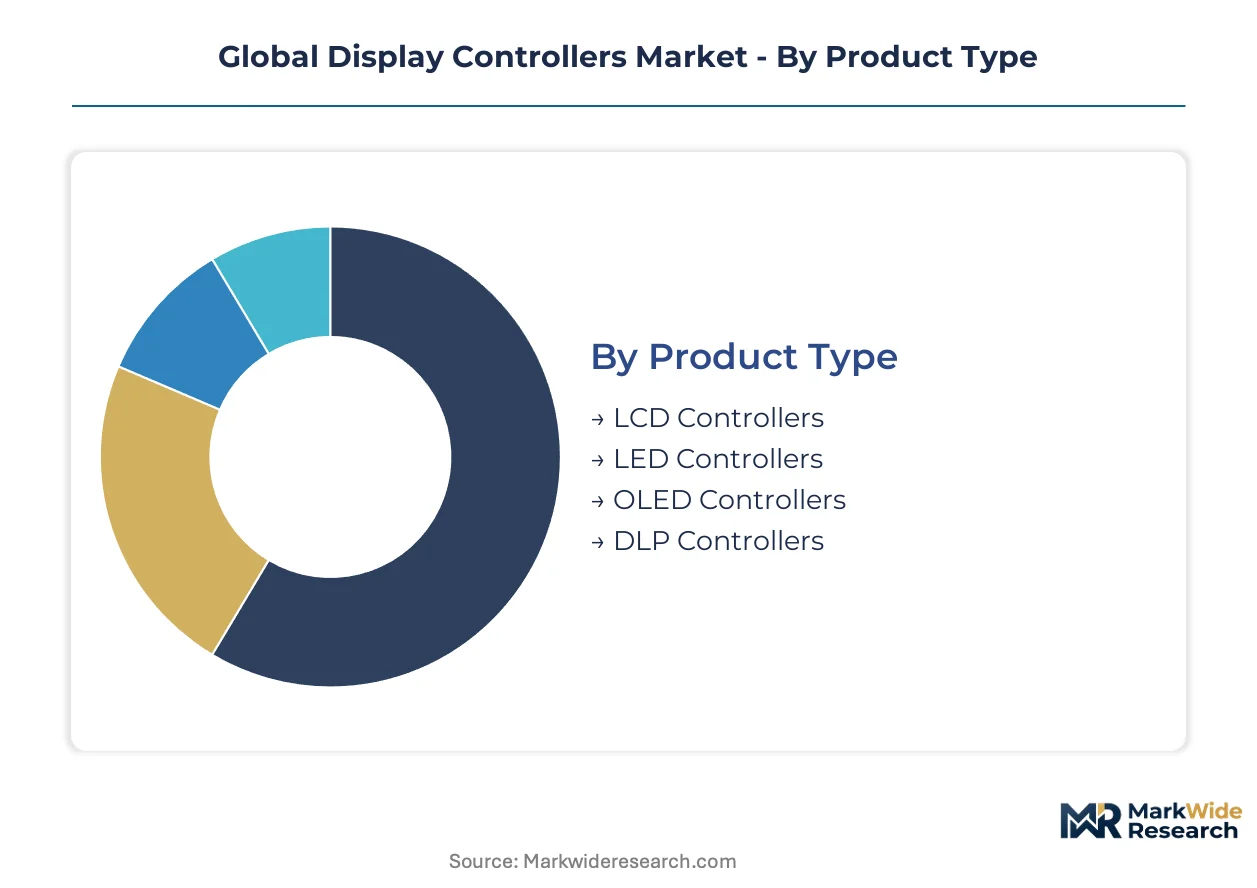
Display controller architectures diverge sharply across interface protocols, pixel-driving methodologies, and thermal envelopes. Segmentation reveals where silicon content concentrates and which qualification barriers protect margin pools.
Product Type:
Capital intensity escalates with pixel-level compensation complexity and substrate material requirements.
- OLED Controllers:Per-pixel current regulation circuits demand multi-domain analog design and foldable-form-factor mechanical compliance. Samsung Electronics and Chinese panel makers absorb the majority of supply for smartphone and premium television applications, with die sizes running 40% larger than equivalent LCD solutions.
- LCD Controllers:Mature timing-controller architectures dominate volume production through standardized LVDS and eDP interfaces. Taiwan-based semiconductor houses and Chinese fabless designers compete aggressively on cost for television and monitor panels, compressing ASPs in sub-4K resolution tiers.
- LED Controllers:Direct-drive and local-dimming variants serve mini-LED backlight modules with zone counts exceeding 1000.
- DLP Controllers:Micromirror array management for projection systems retains niche positioning in cinema and industrial inspection.
Most installed capacity flows through LCD Controllers. Expansion is steepest in OLED Controllers.
Technology:
Architecture choices determine qualification burden and foundry node requirements across customer segments.
- Digital:Fully integrated signal processing cores enable software-configurable timing parameters and field-upgradable firmware. Consumer electronics and automotive instrument clusters drive procurement, with MIIT-directed Chinese foundry expansion improving domestic supply security for high-resolution smartphone panels.
- Hybrid:Analog-digital partitioning optimizes power efficiency in battery-constrained wearables and automotive head-up displays. Texas Instruments leverages proprietary process nodes for automotive-grade temperature operation.
- Analog:Legacy architectures persist in industrial equipment with decade-long service lives.
- Wireless:Emerging protocols for cable-free display links target digital signage and temporary installation markets.
Digital architectures carry the broadest addressable base. Hybrid designs are climbing the fastest in automotive qualification pipelines.
End User:
Customer-type segmentation exposes divergent margin structures and validation timeline risks.
- Automotive:Functional safety certification under ISO 26262 extends development cycles to 36-48 months for ASIL-B rated instrument cluster controllers. German and Japanese OEMs mandate extended temperature operation and electromagnetic compatibility validation, concentrating procurement among qualified tier-one semiconductor suppliers.
- Medical:FDA 21 CFR Part 820 traceability and extended color gamut requirements protect margin pools through specialized qualification barriers. Diagnostic radiology workstations demand controllers with 10-bit or higher color depth and failure-mode analysis documentation.
- Consumer Electronics:Volume concentration in television and smartphone panels drives aggressive cost engineering.
- Industrial:Long service-life requirements sustain demand for obsolete interface protocols and legacy package types.
Automotive commands the highest silicon content per vehicle. Medical maintains the steepest margin premiums.
Application:
Form-factor constraints and resolution trajectories reshape controller specification requirements.
- Smartphones:Foldable displays and under-panel camera integration demand flexible substrate compatibility and dynamic refresh rate switching. Korean and Chinese OEMs specify MIPI DSI-2 interfaces with VESA DSC compression for 120Hz+ operation.
- Televisions:8K resolution and mini-LED local dimming converge timing-controller and scaler functions into single-chip solutions. Samsung Electronics and domestic Chinese brands accelerated adoption of 1000+ zone controllers for 2024-2025 product cycles.
- Wearables:Circular displays and always-on operation prioritize sub-milliwatt standby power.
- Digital Signage:Outdoor brightness requirements and network-managed firmware updates distinguish commercial from consumer specifications.
Television applications absorb the largest controller volume. Smartphone specifications are expanding most quickly in interface bandwidth requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting display controller assembly toward jurisdictions with streamlined substance-compliance pathways. Foundry-capital subsidies in East Asia and tariff-differentiated electronics zones in North America are reshaping where silicon content accumulates.
China
Domestic panel makers and fabless controller designers are scaling 12-inch wafer partnerships through MIIT-directed capacity expansion. GB standards mandate electromagnetic compatibility testing for telecommunications infrastructure displays, tightening qualification protocols for local deployment. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates timing-controller packaging operations serving Korean and Chinese television brands.
South Korea
Samsung Electronics leverages captive wafer capacity to secure supply for internal OLED panel operations while serving external smartphone OEMs. The Korea MFDS maintains medical-device quality benchmarks that Korean controller suppliers reference for diagnostic imaging exports. The Seoul Capital Area anchors advanced-node foundry output for foldable-display driver ICs with 40% larger die sizes than LCD equivalents.
United States
Automotive OEMs in Michigan and California specify ASIL-B rated instrument cluster controllers with extended temperature operation. FDA 21 CFR Part 820 governs medical display controller validation for diagnostic radiology workstations sold domestically. Texas Instruments exemplifies hybrid analog-digital architectures optimized for automotive head-up displays through proprietary process nodes.
Germany
German automotive OEMs pre-qualify packaging subcontractors with demonstrated hazardous-substance management systems under EU REACH disclosure requirements. The KBA enforces electromagnetic compatibility standards for vehicle-integrated displays. Bavaria's automotive electronics corridor concentrates tier-one semiconductor procurement for instrument cluster and center-stack applications.
India
PLI scheme incentives for display module assembly are generating first-time controller demand from domestic television and smartphone brands. BIS certification requirements apply to imported semiconductor components for consumer electronics. The Maharashtra-Gujarat industrial corridor hosts emerging electronics manufacturing services adding controller programming and testing capabilities.
Global Display Controllers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive functional-safety certification and medical imaging specialization. The market structure reflects moderate consolidation among analog-digital hybrid architects alongside fragmentation in cost-optimized digital timing controllers. Three archetypes dominate: captive foundry-integrated panel makers, fabless specialists in interface protocols, and diversified analog semiconductor houses. Capacity expansion and strategic partnerships represent the dominant competitive vectors as suppliers secure qualified packaging capacity for automotive-grade reliability.
Within the diversified analog tier, Texas Instruments Incorporated and Analog Devices, Inc. exemplify process-node differentiation for extended-temperature automotive applications. Samsung Electronics anchors the captive-integration archetype through internal wafer capacity serving proprietary display panel operations. Novatek Microelectronics Corp. occupies a position among timing-controller specialists addressing large-format LCD television requirements.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| Renesas Electronics Corporation |
| Samsung Electronics |
| Toshiba Infrastructure Systems & Solutions Corporation |
| Novatek Microelectronics Corp. |
| LG Display Co., Ltd. |
| NXP Semiconductors |
| Microchip Technology Inc. |
| Texas Instruments Incorporated |
| Others |
Supply Flow & Price Mechanics
Captive wafer capacity at Korean and Chinese panel makers anchors supply security while compressing pricing power for independent controller designers serving external accounts. This integration pattern concentrates procurement leverage among vertically integrated OEMs and forces fabless competitors toward cost-engineered digital architectures to defend socket access.
Pricing Analysis
Distributor margins on automotive-grade controllers run 12-18 points above consumer electronics tiers due to bonded inventory programs and field-programming services. Pricing stratifies across ASIL-certified automotive, FDA-traceable medical, and commodity consumer tiers with differentiation driven by certification burden and volume scale. Cost compression in sub-4K LCD timing controllers is intensifying because Taiwanese and Chinese fabless houses compete aggressively on foundry access. Consumer electronics brands exhibit highest price sensitivity; German automotive OEMs accept premium positioning for demonstrated hazardous-substance management systems.
Supply Chain Analysis
Advanced-node wafer supply rests on Taiwanese and South Korean foundry capacity, with 12-inch fabrication for high-resolution controllers concentrated in the Hsinchu Science Park and Seoul Capital Area. Silicon feedstock and specialty photoresist draw from Japanese chemical producers, while lead-free solder compositions and halogen-free laminates source from qualified packaging subcontractors in China and Southeast Asia. Single-source vulnerability in EUV lithography equipment creates chokepoint exposure for next-generation OLED driver ICs. Distribution runs through tier-one semiconductor distributors serving panel makers in the Yangtze River Delta and bonded inventory programs for North American automotive tier ones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between EU REACH compliance costs elevating European procurement prices and Chinese MIIT-directed foundry subsidies compressing domestic supply costs. Controllers qualified under FDA 21 CFR Part 820 command 40-60 point margin premiums over consumer tiers, creating relocation incentives for medical-specialist designers.
For Market Incumbents: Extend functional safety certification pipelines toward ASIL-D ratings for autonomous vehicle displays before emerging Chinese fabless competitors complete automotive qualification. Secure captive packaging capacity in Germany and Japan to defend against EU REACH substance disclosure tightening. Vertical integration into 12-inch wafer partnerships insulates against Taiwan foundry concentration risk. For New Entrants and Emerging Players: Diagnostic radiology workstation buyers remain underserved by specialized 10-bit color depth controllers with full failure-mode documentation, presenting white-space entry through FDA 21 CFR Part 820 pre-certification investment. India's PLI-subsidized display module assembly lines offer first-mover positioning for domestic television and smartphone brands specifying BIS-certified components. Go-to-market leverage rests on programming partnerships with Maharashtra-Gujarat electronics manufacturing services adding controller testing capabilities. For Investors and Strategic Acquirers: Roll-up economics work for automotive-grade analog-digital hybrid specialists because ISO 26262 validation timelines and engineering headcount requirements prevent rapid organic replication. Long-term viability hinges on qualified foundry relationships extending through the next process node transition. Watch Korean foundry expansion announcements as inflection signal for supply availability shifts affecting valuation multiples across the fabless tier.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-B Functional Safety Certification | German automotive OEMs mandate extended temperature operation for instrument cluster controllers. |
| MIIT-Directed Foundry Partnership | Domestic Chinese panel makers secure 12-inch wafer access for high-resolution smartphone controllers. |
| FDA 21 CFR Part 820 Pre-Qualification | Diagnostic imaging equipment suppliers require traceability documentation protecting margin pools. |
| EU REACH Packaging Subcontractor Pre-Approval | German OEMs demand hazardous-substance management systems down to sub-100 ppm disclosure. |
| MIPI DSI-2 Interface Standardization | Korean and Chinese smartphone OEMs specify VESA DSC compression for 120Hz+ foldable displays. |
Methodological Framework
Coverage spans China, South Korea, Taiwan, Germany, and the United States, with primary inputs from each market cluster combining interviews with semiconductor procurement managers at panel makers, automotive tier-one supplier quality engineers, and medical device regulatory affairs leads. Secondary validation draws from MIIT technical specifications, FDA 510(k) filings for diagnostic imaging equipment, EU REACH substance disclosure databases, and SEC 10-K filings from diversified analog semiconductor houses. Bottom-up unit demand estimates triangulate against top-down foundry capacity allocation data.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, technology architecture, end-user qualification tier, and application form factor, with additional resolution on interface protocol adoption trajectories. CAGRs derive from segment-level growth rate convergence analysis applied to historical foundry utilization patterns and OEM platform rollout schedules. Automotive content-per-vehicle expansion and mini-LED local dimming zone counts serve as key forecast inputs.
Underlying measurement precision varies by segment; automotive and medical end-use categories carry tighter precision than consumer electronics given longer qualification visibility. Forecasts reflect assumptions on foundry capacity expansion timing, EU F-Gas Regulation phase-down schedules, and automotive platform electrification trajectories that could revise projections. A small set of triggers—Korean foundry capex announcements, EU REACH substance list updates, and China semiconductor subsidy program renewals—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Smartwatch Display Panel Market
Display Technologies
4K VR Displays Market
Display Technologies
Plasma Display Module Market
Display Technologies
Smartphone Display Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Low Power Display Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Foldable Screens Market
Display Technologies
Collaboration Display Market
Display Technologies
Interactive Display Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Volumetric Display Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
PMOLED Display Market
Display Technologies
Global Embedded Display Market
Display Technologies
Display Mask Market