
 VR Gaming Hardware Chipsets Market | 2026-2036
VR Gaming Hardware Chipsets Market Size, Share, and Industry Trends Forecast 2026-2036
VR Gaming Hardware Chipsets Market Insights
The EU F-Gas Regulation is hardening requirements for fluorinated gas containment in semiconductor manufacturing, pushing chipset vendors toward alternative thermal interface materials. Qualcomm Technologies leverages its Snapdragon XR platform to dominate mobile VR SoC design. NVIDIA Corporation anchors high-end PC-tethered VR through its GeForce RTX silicon with dedicated ray-tracing cores. MediaTek competes aggressively in cost-optimized segments for emerging-market headsets.
VR gaming hardware chipsets comprise integrated circuits engineered to process stereoscopic rendering, sensor fusion, and low-latency display output at sub-20ms motion-to-photon intervals, typically fabricated on 5nm or 4nm process nodes. GPUs lead value capture in premium tethered systems where parallel compute throughput determines visual fidelity, while SoCs represent the fastest-expanding category as wireless standalone headsets displace PC-dependent configurations. AI Processing capabilities now differentiate mid-tier silicon, with dedicated neural engines handling foveated rendering and predictive tracking to extend battery life.
FCC equipment authorization rules govern wireless radio emissions for VR headsets sold in the United States, while REACH compliance in Europe restricts hazardous substances in chipset substrates and solder materials. China's MIIT enforces domestic cybersecurity review for connected VR devices utilizing local 5G spectrum. Stakeholders must monitor how divergent electromagnetic compatibility testing regimes between jurisdictions affect platform development costs and regional product launch sequencing.
Market Dynamics
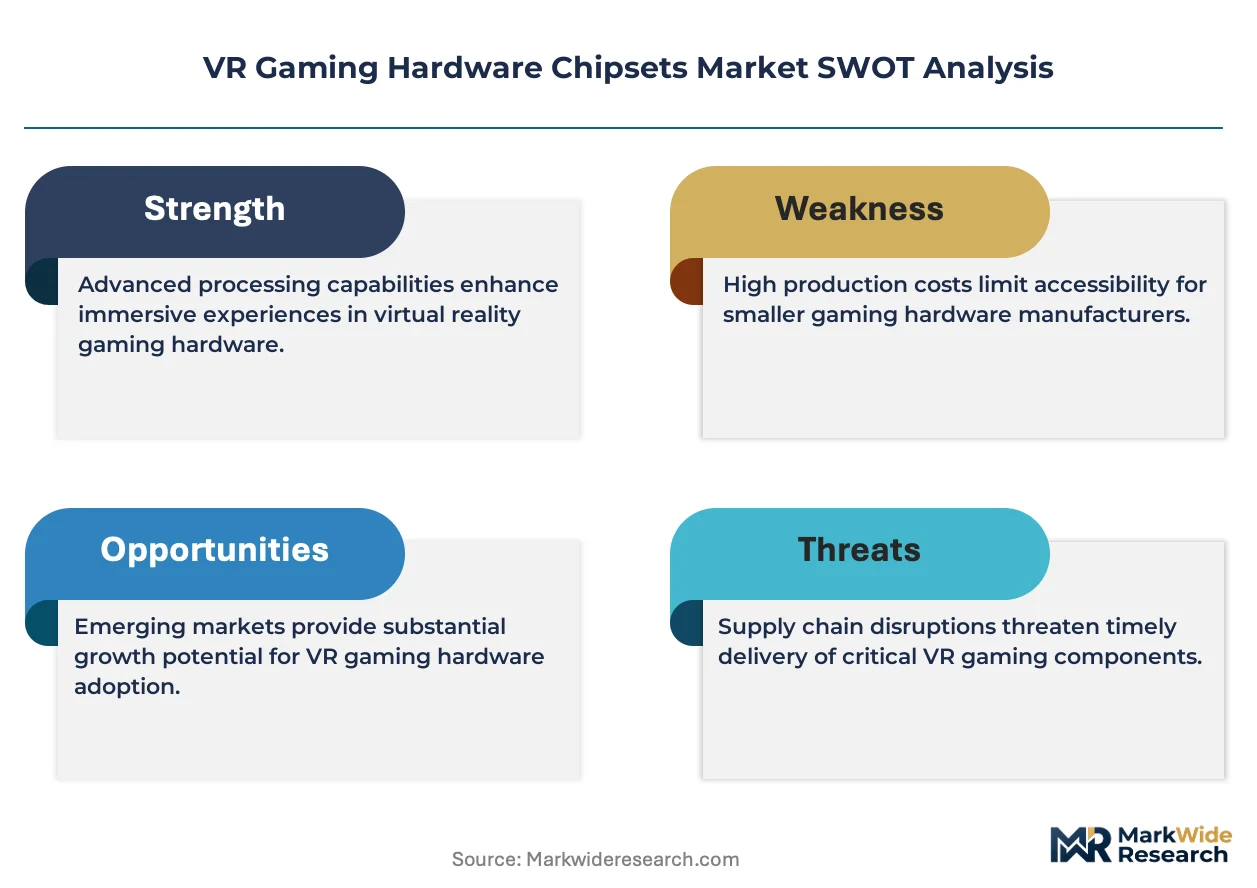
Standalone VR headset adoption is consolidating demand around power-efficient SoCs, compressing the addressable market for discrete GPU-dependent tethered systems and forcing chipset vendors to reallocate R&D toward integrated neural engines and thermal packaging innovations.
Growth Catalysts
- EU F-Gas Regulation:Tightening refrigerant standards for thermal interface materials in semiconductor packaging is accelerating vendor migration toward graphene-based and phase-change alternatives that improve heat dissipation in compact VR form factors.
- Shenzhen Manufacturing Corridor:Concentration of contract assemblers and customized silicon sourcing creates ecosystem density that reduces procurement lead times and enables rapid prototyping cycles for domestic and export-bound VR devices.
- Foveated Rendering:AI-driven gaze-tracking algorithms running on dedicated neural engines reduce per-frame pixel shading workloads, extending battery life in wireless headsets and enabling higher effective resolutions without commensurate power draw.
Market Restraints
- Advanced Node Access:Foundry capacity constraints at 4nm and 3nm process nodes limit production scaling for premium VR SoCs, creating allocation bottlenecks for second-tier headset manufacturers.
- Raw Material Concentration:High-purity gallium and germanium refining capacity concentrates in specific East Asian supply zones, exposing chipset packaging operations to export restriction volatility and price spikes.
- Motion-to-Photon Latency Floor:Sub-20ms rendering pipelines require deterministic memory architectures that resist cost reduction through standard DRAM commoditization, pressuring margin structures in mid-tier silicon.
Strategic Opportunities
- Enterprise Training Verticals:Industrial safety simulation and medical procedure rehearsal applications in Germany and France are driving demand for pass-through mixed-reality chipsets with simultaneous localization and mapping capabilities.
- India PLI Scheme:Production-linked incentives for electronics manufacturing are attracting chipset packaging and testing investments that could establish South Asian assembly alternatives to Shenzhen-centric sourcing.
- 5G-Edge Convergence:Split-rendering architectures distributing compute between headset SoCs and network edge nodes enable lighter headset designs while preserving visual fidelity, opening subscription-based hardware-as-service models.
Industry Challenges
- Multi-Jurisdictional Certification:Divergent electromagnetic compatibility testing regimes between FCC equipment authorization rules, EU CE marking requirements, and China's MIIT cybersecurity review create redundant validation cycles that delay regional product launches.
- Silicon-Photonics Integration:Co-packaging optical interconnects with traditional CMOS logic for next-generation display bandwidth demands specialized cleanroom capabilities and talent pools that remain geographically constrained.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Gaming Hardware Chipsets Market |
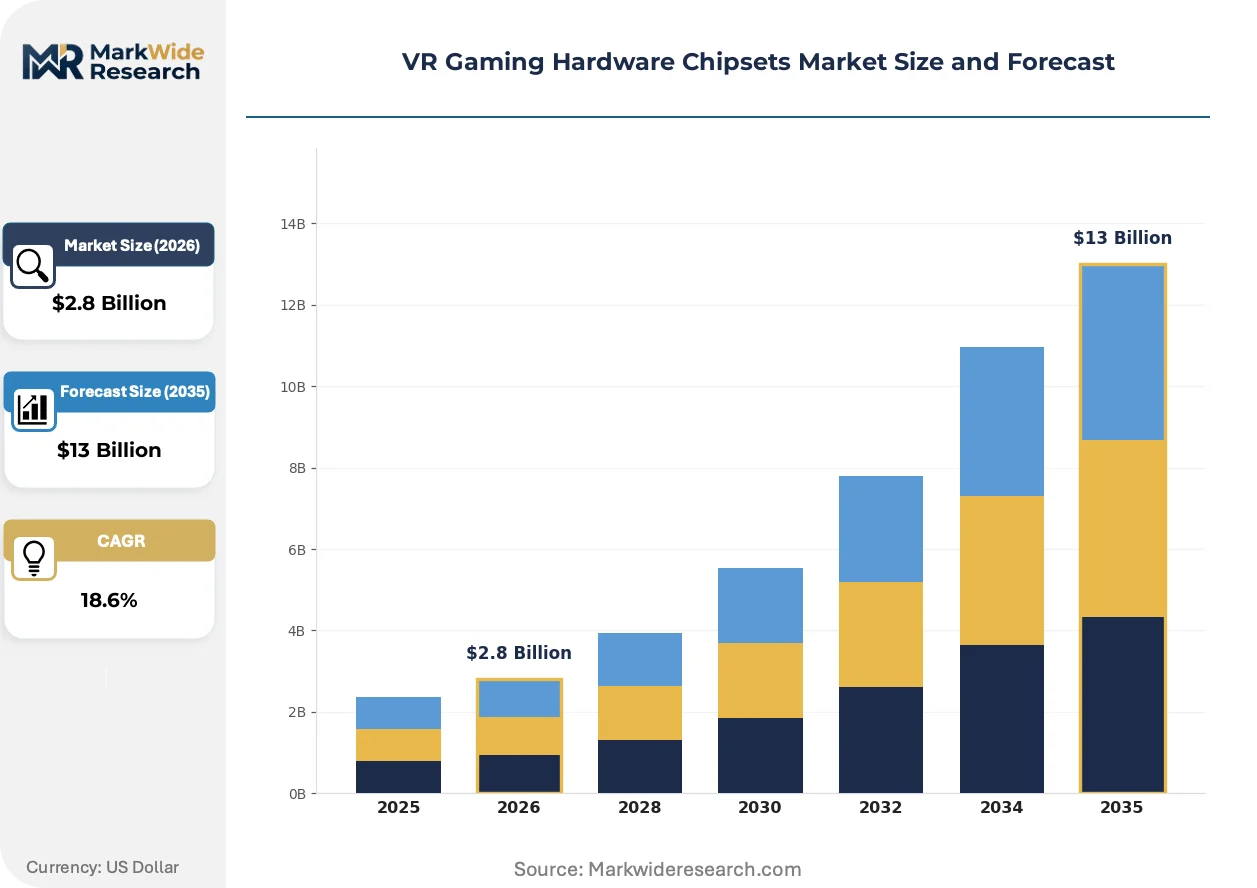
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPUs, CPUS, SoCs, FPGAs Technology: Ray Tracing, AI Processing, Motion Sensing, 3D Audio End User: Developers, Hardware Manufacturers, Consumers, Arcades Application: Gaming, Simulation, Education, Training |
| Companies Covered | Qualcomm Technologies, Intel Corporation, Samsung Electronics, NVIDIA Corporation, Advanced Micro Devices, MediaTek, Broadcom, NXP Semiconductors, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Gaming Hardware Chipsets Market Trends and Innovations
Chipset architecture decisions are increasingly dictated by thermal constraints and AI inference requirements rather than raw polygon throughput, compressing the traditional GPU performance hierarchy and elevating system-level integration capabilities as the primary competitive differentiator.
Chiplet-based designs with disaggregated compute, memory, and I/O dies interconnected through 2.5D packaging are consolidating the high-end VR silicon landscape. Premium headset manufacturers are adopting these modular architectures to customize performance-per-watt profiles without full mask respins. The structural consequence is that vertically integrated IDM competitors are losing ground to fabless vendors with advanced packaging partnerships.
REACH compliance restrictions on hazardous substances in substrate materials and solder compositions are forcing foundries to qualify lead-free and halogen-free process variants. European contract manufacturers face extended qualification timelines as they validate alternative underfill compounds and bonding wire alloys. High-frequency RF front-end modules within VR headsets are experiencing the most severe reformulation delays due to signal integrity sensitivity.
Direct-to-consumer headset brands are bypassing traditional retail channel markups through subscription bundling with cloud gaming services and productivity software suites. This disintermediation compresses distributor margins while shifting chipset procurement decisions toward platform-integrated vendors capable of multi-year supply commitments. The United States and United Kingdom markets exhibit the most pronounced channel restructuring, with big-box electronics retailers losing shelf space to manufacturer-direct fulfillment networks.
VR Gaming Hardware Chipsets Market Segmentation
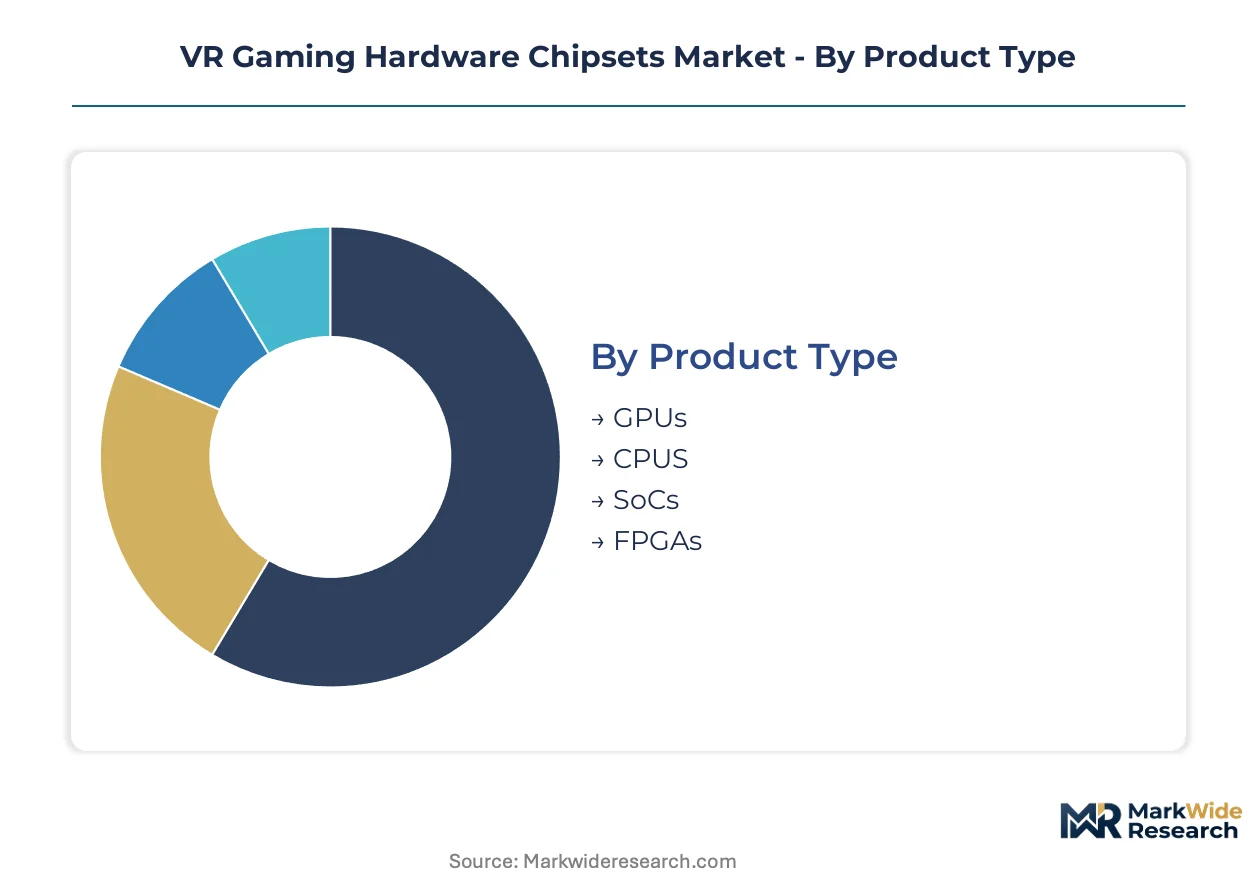
Segmentation in VR gaming hardware chipsets reveals how architectural choices cascade through manufacturing economics and procurement patterns. Product type and technology decisions determine thermal budgets, foundry access, and margin structures across tethered and standalone headset categories.
Product Type:
Customization intensity varies sharply across this spectrum, with fully integrated SoCs demanding the most co-design investment while discrete GPUs permit off-the-shelf procurement.
- GPUs:Discrete graphics processors fabricated on advanced nodes deliver parallel compute throughput for high-fidelity ray-traced rendering in PC-tethered VR systems. Demand concentrates among enthusiast-grade headset buyers in the United States and Germany where visual fidelity commands price premiums. NVIDIA's GeForce RTX silicon anchors this tier with dedicated RT cores.
- SoCs:Systems-on-chip integrate CPU, GPU, and neural processing units into single-die or chiplet architectures optimized for thermal-constrained standalone headsets. Qualcomm's Snapdragon XR platform dominates design wins here as Meta and Pico shift volume toward wireless configurations. Battery life extension drives procurement decisions more than raw shader performance.
- CPUs:General-purpose processors handle game logic, physics simulation, and OS management in hybrid architectures where discrete GPUs manage rendering pipelines. Intel and AMD x86 cores serve PC-tethered configurations while ARM-based designs anchor mobile VR platforms.
- FPGAs:Field-programmable gate arrays enable rapid prototyping of custom sensor fusion algorithms and display interface protocols before silicon commitment. Smaller headset manufacturers leverage Xilinx and Altera devices for low-volume specialty applications.
Most installed capacity flows through SoCs. Expansion is steepest in GPUs as enterprise simulation applications demand uncompromised visual fidelity.
Technology:
Cost tier stratification separates premium silicon with dedicated acceleration blocks from mid-tier implementations relying on software emulation.
- Ray Tracing:Hardware-accelerated light transport simulation enables realistic reflections, global illumination, and shadows in real-time VR environments. Implementation requires substantial die area for bounding volume hierarchies and intersection engines, limiting deployment to flagship-tier silicon.
- AI Processing:Dedicated neural engines execute foveated rendering, predictive tracking, and voice recognition at sub-watt power budgets. MediaTek and Qualcomm compete aggressively here for mid-tier standalone headset sockets where inference efficiency determines battery endurance.
- Motion Sensing:Inertial measurement unit fusion algorithms and visual-inertial odometry pipelines demand deterministic latency guarantees from chipset memory subsystems. Sensor hub architectures offload this processing from main application processors.
- 3D Audio:Spatial audio rendering with head-related transfer function convolution requires dedicated DSP blocks or GPU shader capacity for real-time binaural synthesis. Implementation quality differentiates premium-tier immersive experiences.
Volume concentrates in AI Processing as gaze-tracking becomes standard across price tiers. Ray Tracing claims the steepest expansion trajectory as content libraries mature.
End User:
Customer type determines procurement scale, technical support requirements, and lifecycle commitment horizons across the value chain.
- Hardware Manufacturers:Contract assemblers and original design manufacturers in Shenzhen source customized silicon with modified pinouts, thermal specifications, and firmware loads for specific headset industrial designs. Long-term supply agreements with Qualcomm and MediaTek lock in allocation priority.
- Developers:Engine and middleware creators require reference platforms with unlocked debugging capabilities and early-access silicon stepping for optimization work. NVIDIA and Qualcomm maintain dedicated developer program infrastructures with subsidized hardware distribution.
- Consumers:End-user demand flows indirectly through retail channel inventory decisions and subscription bundling arrangements with cloud gaming services. Direct-to-consumer brands bypass distributor markups, compressing chipset procurement lead times.
- Arcades:Location-based entertainment operators prioritize ruggedized thermal solutions and remote fleet management capabilities over peak performance specifications. Volume procurement concentrates in Chinese and Japanese markets.
Most chipset volume ships to Hardware Manufacturers. Developers represent the fastest-climbing customer category as independent studio formation accelerates.
Application:
Geography shapes demand concentration as regulatory environments and industrial structure vary across use cases.
- Gaming:Interactive entertainment remains the volume anchor, with consumer headset adoption driving SoC procurement at scale. Content monetization through in-game purchases and subscription services subsidizes hardware margin compression.
- Simulation:Industrial safety training and medical procedure rehearsal applications in Germany and France demand pass-through mixed-reality capabilities with simultaneous localization and mapping. Enterprise procurement cycles extend 18-36 months but command premium pricing.
- Education:Institutional deployments in K-12 and higher education prioritize durability, content curation, and manageability over peak specifications. India's national digital education initiatives are stimulating regional procurement volume.
- Training:Military and first-responder applications in the United States require hardened supply chains, domestic packaging where possible, and compliance with ITAR export controls. Custom silicon modifications support secure boot and encrypted telemetry.
Gaming absorbs the majority of installed capacity. Simulation is expanding most quickly as enterprise pilot programs convert to production deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
VR gaming hardware chipsets trace their commercial lineage to Silicon Valley's graphics processor innovations of the 1990s, later migrating fabrication and assembly gravity toward East Asian manufacturing corridors. Today, demand concentrates across five distinct national markets where regulatory frameworks and industrial clusters shape procurement patterns.
United States
Enterprise simulation contracts from defense and medical training sectors drive high-margin GPU demand for tethered systems. FCC equipment authorization rules govern wireless radio emissions, adding compliance costs for headset launches. Austin and San Diego host design centers where fabless vendors prototype neural engine architectures for next-generation standalone devices.
China
Shenzhen's contract assemblers source customized silicon for domestic brands like Pico and export-bound Meta hardware at massive scale. MIIT enforces cybersecurity review for connected VR devices utilizing local 5G spectrum, creating domestic certification bottlenecks. The Pearl River Delta corridor compresses procurement lead times through vertically integrated PCB, lens, and chipset packaging facilities.
Germany
Industrial safety simulation and automotive design visualization anchor enterprise VR demand, requiring pass-through mixed-reality chipsets with SLAM capabilities. REACH compliance restricts hazardous substances in substrate materials, forcing foundries to qualify lead-free process variants. Bavaria's Munich-Stuttgart axis concentrates system integrators serving automotive OEMs and aerospace suppliers.
South Korea
Display panel leadership from Samsung and LG creates captive demand for high-bandwidth display driver ICs and timing controllers. MFDS medical device regulations govern VR-based surgical training hardware, extending validation timelines for clinical applications. Seoul's Pangyo Techno Valley clusters content studios and hardware labs developing foveated rendering algorithms.
Japan
Location-based entertainment arcades and corporate training facilities sustain demand for ruggedized thermal solutions. METI's technology roadmaps prioritize energy-efficient semiconductor packaging aligned with national carbon neutrality targets. Tokyo-Osaka corridor hosts precision equipment manufacturers supplying die-bonding and wire-bonding machinery to regional packaging houses.
VR Gaming Hardware Chipsets Market Competitive Landscape
Capital-heavy foundry operators compete with asset-light fabless designers across divergent margin structures. The vendor landscape consolidates around three tiers: integrated device manufacturers with captive fabrication, fabless specialists with advanced packaging partnerships, and diversified electronics conglomerates leveraging display or memory synergies. Strategic moves center on chiplet architecture licensing and multi-year supply agreements that lock in allocation priority at constrained 4nm nodes.
Within the fabless tier, Qualcomm Technologies and MediaTek occupy positions defined by power-efficiency optimization for wireless headsets. NVIDIA Corporation anchors the discrete GPU segment where ray-tracing silicon commands premium positioning. These three entities exemplify how architectural specialization—neural engines, thermal packaging, or parallel compute throughput—determines competitive boundaries more than manufacturing scale alone.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| Intel Corporation |
| Samsung Electronics |
| NVIDIA Corporation |
| Advanced Micro Devices |
| MediaTek |
| Broadcom |
| NXP Semiconductors |
| Analog Devices |
| Others |
Pricing and Supply Chain Analysis
Specialized thermal packaging engineers in Taiwan's Hsinchu Science Park command premium compensation that compresses margin structures for mid-tier VR chipset vendors while widening spreads between premium neural-engine SoCs and cost-optimized alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ray-tracing-enabled discrete GPUs from AI-optimized standalone SoCs and bare-bones sensor hub architectures. Price differentiation rests on foundry node access and REACH-compliant substrate certification tiers. Pricing pressure stems from foundry allocation bottlenecks at 4nm nodes that force second-tier headset manufacturers toward older process generations. Hardware manufacturers in Shenzhen exhibit highest price sensitivity, while enterprise simulation buyers in Germany accept substantial premiums for ITAR-compliant supply chains.
Supply Chain Analysis
Single-source vulnerability sits with high-purity gallium refining capacity concentrated in China, South Korea, and Japan. Raw material dependencies encompass germanium substrates, EUV photoresists, and lead-free solder alloys. Tariff exposure on semiconductor fabrication equipment creates procurement uncertainty for fabless vendors expanding packaging partnerships. Distribution runs through vertically integrated contract assemblers in Shenzhen's Pearl River Delta corridor that compress lead times through co-located PCB, lens, and chipset packaging facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VR gaming hardware chipsets market functions as a stable compounder, with foveated rendering adoption driving steady silicon refresh cycles across consumer and enterprise segments.
For Market Incumbents: Cement allocation priority at TSMC's 4nm and 3nm nodes through multi-year supply commitments that lock in capacity ahead of second-tier competitors. Deepen backward integration into custom thermal interface material formulations to offset EU F-Gas Regulation compliance costs and defend margin structures against MediaTek's cost-optimized assault on mid-tier standalone sockets.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription bundling with cloud gaming services to bypass distributor markups and compress procurement lead times. India's PLI scheme for electronics manufacturing offers the most penetrable geography for packaging and testing investments, with government incentives offsetting capital requirements for South Asian assembly alternatives to Shenzhen-centric sourcing.
For Investors and Strategic Acquirers: Cloud gaming platform operators are the most active acquirer in this space, seeking silicon design capabilities to optimize split-rendering architectures. The acquisition target archetype is fabless vendors with advanced packaging partnerships and neural engine IP portfolios. Watch foveated rendering content library maturity as the inflection indicator for premium silicon demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Licensing | Enables customization of performance-per-watt profiles without full mask respins for headset OEMs. |
| Multi-year Foundry Allocation Agreements | Secures 4nm capacity priority at TSMC against second-tier competitors facing allocation bottlenecks. |
| REACH-compliant Material Qualification | Qualifies lead-free solder alloys and halogen-free substrates for European contract manufacturers. |
| Neural Engine IP Acquisition | Accelerates foveated rendering and predictive tracking capabilities for battery-constrained standalone headsets. |
| India PLI Scheme Participation | Establishes South Asian packaging and testing footprint as alternative to Shenzhen-centric sourcing. |
Research Methodology
Bottom-up headset shipment modeling reconciled against top-down foundry wafer tracking forms the analytical core. Primary interviews with fabless semiconductor executives, thermal packaging engineers, contract assembler procurement leads, and VR headset platform architects combined with secondary validation against SEC 10-K filings, MIIT equipment certification databases, and EU F-Gas Regulation implementation reports. Triangulation across supply-side capacity announcements and demand-side design win disclosures ensures cross-verification.
Input-output matrices map chipset unit volumes through process node tiers, thermal packaging configurations, and end-use applications across the analysis window. Segmentation dimensions span product type, technology acceleration blocks, and regional regulatory clusters. CAGRs derive from fitted growth curves calibrated against historical foundry utilization rates and content monetization trajectories. Forecast inputs include foveated rendering adoption curves and enterprise simulation procurement cycle lengths.
Several conditions sit outside the modeled scope, including geopolitical export restrictions on semiconductor manufacturing equipment and unforeseen breakthroughs in silicon-photonics integration. Forecasts reflect documented assumptions regarding foundry capacity expansion timelines and REACH compliance implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
5G Processor Market
Chipset and Processors
Spain Data Center Processor Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Application Processor Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
Battery Monitoring IC Market