
 Plasma Display Module Market | 2026-2036
Plasma Display Module Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Display Module Market Analytics
Multi-source panel procurement is decoupling from the captive supply chains that once defined this sector. Panasonic sustains manufacturing depth through in-house plasma cell fabrication, while Samsung SDI competes by extending its phosphor material expertise across adjacent display technologies. Changhong anchors volume production for industrial-grade modules serving Chinese domestic broadcast infrastructure.
A plasma display module is an emissive flat-panel device comprising an array of tiny cells containing ionized gases that emit ultraviolet light to excite phosphors, producing visible images with sub-millisecond response times. These modules historically served large-format television and professional monitor applications where high contrast ratios and wide viewing angles outweighed power consumption penalties. High Definition Plasma dominates remaining consumer replacement demand, while Digital Signage applications occupy the most durable margin pool as commercial buyers prioritize screen longevity over resolution upgrades. Medical Displays represent a contracting but technically sticky segment where grayscale calibration standards preserve niche procurement.
FCC equipment authorization rules govern plasma module electromagnetic emissions in the United States, while REACH compliance in Europe restricts hazardous substance content in phosphor coatings and glass substrates. Japan's METI enforces Top Runner energy efficiency standards that progressively tighten allowable power draw for display equipment sold domestically. Stakeholders must weigh phosphor material substitution costs against regulatory compliance timelines as jurisdictions tighten substance restrictions without synchronizing implementation schedules.

Market Dynamics
China's GB standards for electronic display energy efficiency are compressing product development timelines as manufacturers must recertify legacy plasma architectures against tightening power-draw thresholds before accessing domestic procurement channels.
Growth Catalysts
- Transit Infrastructure Modernization:Digital signage networks in rail hubs and airports sustain procurement volumes for high-brightness plasma panels where ambient light rejection outperforms liquid-crystal alternatives.
- Japan's Top Runner Standards:METI's progressive efficiency mandates preserve domestic manufacturing incentives for display technologies meeting stringent power-performance ratios.
- Phosphor Material Advances:Rare-earth doping improvements extend panel luminance decay curves, stretching replacement cycles in broadcast studio environments where color calibration stability commands premium positioning.
Market Restraints
- Input Cost Volatility:Neodymium and europium oxide prices fluctuate with Chinese export quota adjustments, directly pressuring phosphor coating costs that comprise substantial module bill-of-materials exposure.
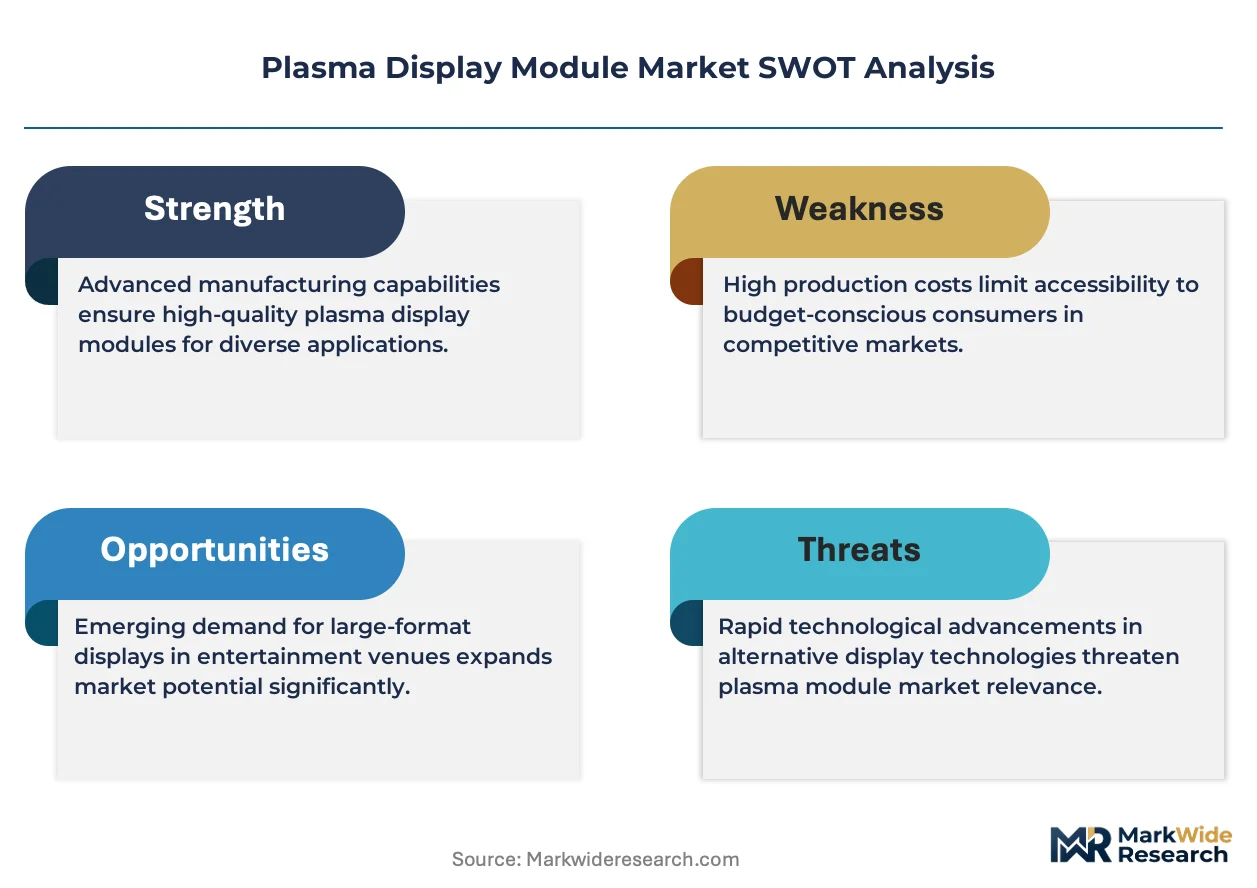
- Substitution Acceleration:MicroLED and OLED large-format panels displace plasma in digital signage refresh cycles as buyers prioritize millimeter-thin form factors over emissive display heritage.
- REACH Compliance Burden:ECHA substance restrictions on heavy metals in glass substrates and phosphor layers force dual-track inventory management for European-bound shipments.
Strategic Opportunities
- Medical Imaging Retention:Diagnostic monitor segments where DICOM grayscale standard compliance preserves plasma procurement for radiology workstations seeking absolute black-level performance.
- Industrial HMI Integration:Factory automation interfaces in heavy manufacturing environments value plasma's wide operating temperature range and immunity to image retention under static dashboard displays.
- Refurbishment Channel Development:Secondary market module reconditioning for broadcast equipment extends serviceable life in Japan's legacy studio infrastructure where capital replacement cycles lag consumer segments.
Industry Challenges
- Specialized Technician Scarcity:Gas cell fabrication and high-voltage driver calibration expertise concentrates among aging workforces in Osaka and Tianjin manufacturing clusters.
- Certification Timeline Compression:Asynchronous implementation of China's GB standards against Japan's JIS revisions forces parallel testing protocols that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Display Module Market |
| Market Size in 2026 | $1.20 Billion |
| Market Size in 2035 | $1.31 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Plasma, High Definition Plasma, Ultra High Definition Plasma, 3D Plasma Application: Consumer Electronics, Digital Signage, Military Applications, Medical Displays End User: Retail Outlets, Home Users, Healthcare Providers, Broadcasting Companies Technology: Nanotechnology, Electroluminescence, Surface Mount Technology, Low-Temperature Polycrystalline Silicon |
| Companies Covered | Panasonic, Samsung, LG, Pioneer, Hitachi, Fujitsu, Changhong, Samsung SDI, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Display Module Market Evolving Landscape
Plasma display module evolution now centers on phosphor chemistry refinements and driver electronics miniaturization rather than panel scaling, as the technology retreats into specialized applications where emissive physics outweigh efficiency penalties.
Neodymium-doped yttrium aluminum garnet phosphors are electrifying color gamut performance in broadcast-grade panels. Japanese studio operators adopt these formulations for 4K monitoring applications where Rec. 2020 coverage determines equipment selection. The technology is electrifying competitive positioning against quantum-dot LCD alternatives in professional color-critical workflows.
China's GB 21520-2023 energy efficiency standard for computer monitors and displays tightens allowable active-mode power consumption by tiered implementation schedules. Manufacturers serving domestic procurement must redesign driver circuits and gas mixtures to maintain brightness-per-watt ratios. Industrial-grade module suppliers in Sichuan province face compressed margins as compliance investments outpace price realization in volume segments.
Broadcast equipment buyers increasingly specify outcome-based service contracts bundling panel supply with calibration maintenance and end-of-life reclamation. Japanese network operators lead this shift, unbundling capital expenditure from operational technology management. The model concentrates procurement authority among systems integrators in Tokyo and Osaka, displacing direct manufacturer relationships that defined prior replacement cycles.
Plasma Display Module Market Segmentation
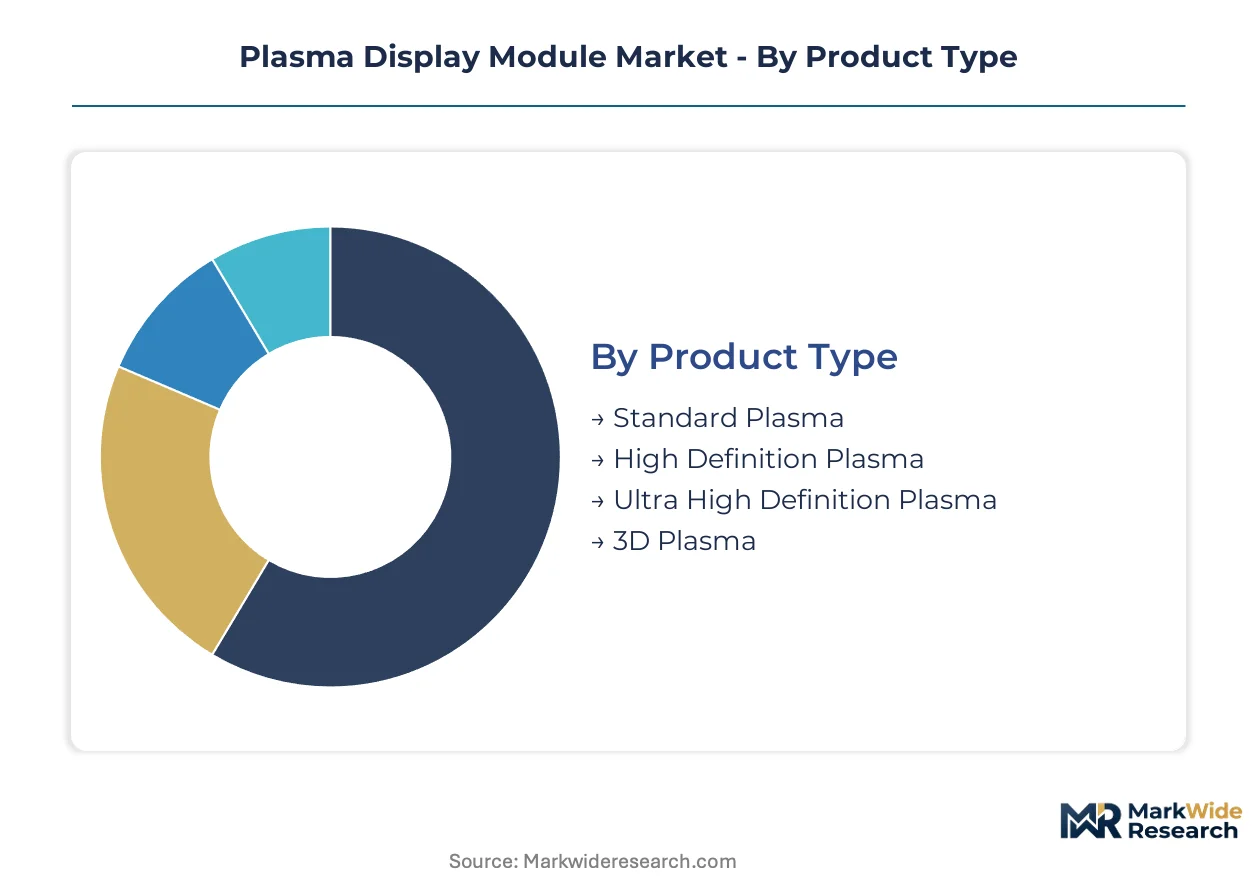
Plasma display module procurement patterns diverge sharply across technical specifications and end-use environments. Buyers in broadcast infrastructure prioritize color calibration stability over resolution metrics, while transit operators select panels based on ambient light rejection rather than pixel density.
Product Type:
Standardization dominates at the commodity end where panel interchangeability reduces spare inventory costs, while high-performance variants command bespoke phosphor formulations and extended calibration protocols.
- High Definition Plasma:1080p resolution panels with optimized gas mixtures for studio monitoring applications. Japanese broadcasters specify these for control room installations where Rec. 709 color accuracy determines procurement. METI efficiency standards compress allowable power envelopes for domestic shipments.
- Ultra High Definition Plasma:4K-capable architectures employing refined cell pitch geometries and enhanced driver electronics. China's GB 21520-2023 certification requirements force redesigns of backlighting subsystems to meet tiered power consumption thresholds.
- Standard Plasma:Legacy 720p configurations serving replacement demand in industrial HMI installations where resolution upgrades provide marginal operational benefit.
- 3D Plasma:Stereoscopic-capable panels with active shutter synchronization, now largely confined to specialized simulation and training environments.
Most installed capacity flows through High Definition Plasma. Expansion is steepest in Ultra High Definition Plasma.
Application:
Cost tier stratification separates consumer replacement cycles from commercial procurement where total cost of ownership calculations extend evaluation horizons.
- Digital Signage:High-brightness panels with anti-reflective coatings for rail hubs and airport terminals. Transit operators in Osaka and Shanghai prioritize luminance maintenance over 50,000-hour service intervals. FCC equipment authorization governs electromagnetic emissions for US infrastructure deployments.
- Medical Displays:Diagnostic-grade panels with DICOM grayscale standard compliance for radiology workstations. Absolute black-level performance preserves procurement in PACS environments despite LCD alternatives. ECHA REACH restrictions on phosphor heavy metals force dual-track inventory management for European-bound shipments.
- Consumer Electronics:Replacement demand for legacy television installations, concentrated in secondary markets where refurbishment economics outweigh new panel acquisition.
- Military Applications:Ruggedized modules with wide temperature operating ranges for command and control consoles.
Volume concentrates in Digital Signage. Margin expansion is most pronounced in Medical Displays.
End User:
Customer type determines procurement authority concentration, with systems integrators displacing direct manufacturer relationships in broadcast segments.
- Broadcasting Companies:Network operators in Tokyo and Osaka specifying outcome-based service contracts bundling panel supply with calibration maintenance. Capital expenditure unbundling from operational technology management shifts procurement authority to systems integrators.
- Healthcare Providers:Hospital radiology departments prioritizing grayscale calibration stability over resolution specifications. DICOM compliance requirements create technical stickiness in diagnostic monitor procurement.
- Retail Outlets:Digital signage deployers evaluating total cost of ownership across 7-10 year operational horizons.
- Home Users:Replacement demand from legacy plasma television owners seeking panel longevity over smart feature integration.
Procurement value concentrates with Broadcasting Companies. Technical specification tightening is most acute among Healthcare Providers.
Technology:
Supply concentration in phosphor material processing and driver electronics fabrication shapes competitive positioning across technical approaches.
- Electroluminescence:Phosphor excitation through direct electric field application, enabling sub-millisecond response times critical for broadcast monitoring. Rare-earth doping improvements extend luminance decay curves in Japanese studio environments.
- Nanotechnology:Phosphor particle engineering for enhanced color gamut performance. Neodymium-doped yttrium aluminum garnet formulations achieve Rec. 2020 coverage in 4K monitoring applications.
- Surface Mount Technology:Driver electronics miniaturization for reduced bezel widths in multi-panel video wall configurations.
- Low-Temperature Polycrystalline Silicon:Thin-film transistor substrates enabling higher electron mobility in driver circuitry.
Manufacturing depth concentrates in Electroluminescence. Technical differentiation is advancing most quickly in Nanotechnology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka anchors global manufacturing depth for plasma display modules through specialized gas cell fabrication clusters. Japanese broadcast infrastructure sustains premium-tier procurement where color calibration stability commands equipment selection. Transit operators in Shanghai and Dubai drive commercial volume for high-brightness panel deployments.
Japan
Broadcast equipment buyers in Tokyo and Osaka specify outcome-based service contracts bundling panel supply with calibration maintenance. METI enforces Top Runner energy efficiency standards that progressively tighten allowable power draw for domestic display equipment. The Kansai manufacturing corridor concentrates specialized technician expertise for high-voltage driver calibration.
China
Industrial-grade module demand concentrates in Sichuan province for domestic broadcast infrastructure refresh cycles. GB 21520-2023 standards tighten allowable active-mode power consumption through tiered implementation schedules. Changhong anchors volume production in Sichuan while Beijing-Tianjin-Hebei clusters focus on driver electronics miniaturization.
United States
Transit infrastructure operators in Chicago and Atlanta procure high-brightness panels for rail hub digital signage networks. FCC equipment authorization rules govern electromagnetic emissions for plasma module deployments. Southwest manufacturing clusters specialize in ruggedized modules for military command console applications.
Germany
Industrial HMI integrators in Bavaria and North Rhine-Westphalia value plasma's wide operating temperature range for factory automation interfaces. ECHA REACH compliance restricts hazardous substance content in phosphor coatings and glass substrates for European-bound shipments. The Baden-Württemberg precision electronics corridor concentrates driver circuit fabrication expertise.
South Korea
Phosphor material processing capabilities in Suwon and Gwangju extend across adjacent display technologies. The national semiconductor regulator enforces substance disclosure requirements for rare-earth doping formulations in export-bound modules. Seoul-based systems integrators displace direct manufacturer relationships in regional procurement channels.
Plasma Display Module Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue phosphor chemistry specialization and driver electronics miniaturization. The vendor base concentrates around three archetypes: integrated plasma cell fabricators, phosphor material specialists, and industrial-grade volume suppliers. Panasonic exemplifies captive manufacturing depth through in-house gas cell production. Samsung SDI competes by extending phosphor expertise across adjacent technologies. Competitive moves center on rare-earth supply chain positioning and dual-track certification management for asynchronous regulatory timelines.
Among East Asian integrated manufacturers, Panasonic, Samsung SDI, and Changhong occupy distinct positioning vectors. Panasonic represents the archetype of captive plasma cell fabrication with broadcast-grade calibration protocols. Samsung SDI exemplifies phosphor material specialization that transfers across display technology generations. Changhong anchors the industrial-grade volume tier serving domestic Chinese procurement channels with cost-optimized module architectures. Each sits within a regulatory compliance framework shaped by their home jurisdiction's energy efficiency mandates and substance restrictions.
| Leading Market Players |
|---|
| Panasonic |
| Samsung |
| LG |
| Pioneer |
| Hitachi |
| Fujitsu |
| Changhong |
| Samsung SDI |
| LG Electronics |
| Others |
Value Network & Pricing Analysis
Japan's METI Top Runner energy efficiency standards gate qualified supply access and preserve premium-tier pricing power for certified plasma display modules serving domestic broadcast procurement channels.
Pricing Analysis
Neodymium and europium oxide cost pass-through directly pressures phosphor coating expenses that comprise substantial module bill-of-materials exposure. Three-tier pricing structure across premium broadcast-grade, standard industrial-grade, and economy replacement-tier levels separates panels by calibration protocol sophistication and certification grade. Pricing pressure stems from rare-earth export quota volatility compressing margins in volume segments. Broadcast equipment buyers exhibit lowest price sensitivity while industrial HMI procurement demonstrates acute cost consciousness.
Supply Chain Analysis
Container freight rate fluctuations from Osaka and Tianjin manufacturing clusters amplify landed cost variance for European and North American-bound shipments. Gas cell fabrication concentrates in Japan, phosphor material processing in South Korea, and driver electronics assembly in China's Beijing-Tianjin-Hebei corridor. Supply chains draw from rare-earth oxide feedstock, borosilicate glass substrates, and high-voltage driver ICs. Single-source vulnerability concentrates in neodymium supply from Chinese processing facilities. Distribution runs through systems integrators in Tokyo and Seoul displacing direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium-tier broadcast segments where phosphor chemistry specialization and service bundling offset input cost volatility.
For Market Incumbents: Anchor manufacturing depth through captive gas cell fabrication and rare-earth supply agreements that insulate against Chinese export quota disruptions. Deepen backward integration into phosphor material processing to defend positioning against Samsung SDI's cross-technology expertise. Prioritize dual-track certification investment for asynchronous GB standards and JIS revisions.
For New Entrants and Emerging Players: Capture refurbishment channel economics in Japan's legacy studio infrastructure where capital replacement cycles lag consumer segments. Target medical imaging white-space where DICOM grayscale compliance creates technical stickiness against LCD substitution. Pursue outcome-based service contract positioning through systems integrator partnerships in Osaka and Tokyo.
For Investors and Strategic Acquirers: Roll-up economics work for specialized phosphor chemistry specialists because rare-earth doping expertise concentrates among aging workforces in Suwon and Gwangju without generational succession. Five-to-ten year viability hinges on broadcast infrastructure refresh durability and medical display retention. Target acquisition archetypes: industrial-grade volume suppliers with GB 21520-2023 certification completion and established Sichuan province manufacturing presence. Monitor OLED large-format pricing trajectories as inflection signal for digital signage substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Supply Agreement | Long-term neodymium offtake contracts with Chinese processors stabilize phosphor coating cost exposure. |
| Dual-Track Certification Investment | Parallel GB standards and JIS revision compliance extends product launch windows for multi-jurisdiction shipments. |
| Refurbishment Channel Development | Secondary market module reconditioning captures service revenue in Japan's legacy broadcast infrastructure. |
| Phosphor Chemistry Specialization | Neodymium-doped yttrium aluminum garnet formulation investment achieves Rec. 2020 coverage for 4K monitoring. |
| Outcome-Based Service Contracting | Calibration maintenance bundling shifts procurement authority to systems integrators in Tokyo and Osaka. |
Research Methodology
Bottom-up broadcast equipment and digital signage procurement modeling reconciled against top-down plasma cell fabrication capacity tracking forms the analytical core. Primary interviews with broadcast engineering directors, hospital radiology procurement managers, transit authority technology officers, and phosphor material R&D leads combined with secondary validation against METI efficiency standard filings, ECHA REACH substance restriction updates, and Chinese customs trade data. Top-down supply-side verification triangulates against bottom-up demand aggregation.
Historical trendline analysis of replacement cycle durations and certification timeline compression patterns informs projection construction across the analysis window. Segmentation dimensions modeled include resolution tier, application environment, end-user procurement authority concentration, and phosphor chemistry approach. CAGRs derive from installed base depreciation curves and refresh cycle elasticity estimates. Forecast inputs incorporate rare-earth oxide price trajectory assumptions and regulatory implementation schedule asynchrony.
Input cost volatility, substitution technology pricing inflections, and regulatory timeline delays are the dominant revision risks. Forecasts reflect documented assumptions about broadcast infrastructure capital expenditure durability and medical display technical stickiness. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electrochromic Window Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
IGZO Display Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Commercial Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
Microdisplay Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
North America Computer Monitor Market
Display Technologies
AMOLED Substrate Market