
 Display Material Market | 2026-2036
Display Material Market Size, Share, and Industry Trends Forecast 2026-2036
Display Material Market Analysis
Mini-LED backlight diffusion is narrowing the performance gap between premium LCD and entry-level OLED panels across television and monitor applications. Corning Incorporated leverages its fusion-draw glass expertise to dominate Gen 10.5 substrate supply for large-format panels. Samsung SDI anchors South Korea's OLED material ecosystem through phosphorescent emitter and quantum dot ink development. Universal Display Corporation sustains its competitive position through extensive patent coverage in phosphorescent OLED emitter chemistry.
Display materials encompass substrates, polarizers, color filters, liquid crystals, organic emitters, and encapsulation layers engineered to transmit, modulate, or emit light in pixelated configurations. Glass substrates typically measure 0.3 mm to 0.7 mm in thickness for mobile applications and up to 0.5 mm for large-area televisions, with thermal expansion coefficients below 3.8 × 10⁻⁶/°C to maintain dimensional stability during high-temperature TFT fabrication. LCD panels retain dominant volume share in digital signage and industrial monitors where cost sensitivity and supply maturity outweigh contrast-ratio advantages. OLED materials command premium positioning in smartphones and emerging automotive displays due to self-emissive architecture enabling thinner form factors and flexible substrate compatibility. Quantum dot technology is gaining traction in high-end televisions by converting blue LED emission into narrow-band red and green light for expanded color gamut coverage.
The EPA regulates fluorinated greenhouse gas emissions from semiconductor and display manufacturing facilities under the American Innovation and Manufacturing Act, while REACH restricts hazardous substances in imported electronic components across European supply chains. South Korea's Ministry of Environment enforces K-REACH for chemical registration in display material production, creating compliance complexity for non-domestic suppliers seeking access to Samsung and LG ecosystems. Stakeholders must monitor evolving chemical restriction lists and substrate recycling mandates to anticipate material substitution cycles and qualification timelines.
Market Dynamics
Automotive cockpit electrification is compressing qualification cycles for curved and flexible display substrates, forcing material suppliers to synchronize thermal expansion specifications with Tier 1 integrators ahead of standard vehicle development timelines.
Growth Catalysts
- EU F-Gas Regulation:Tightening controls on fluorinated greenhouse gases are accelerating investment in alternative etching chemistries for TFT array fabrication, expanding addressable demand for low-global-warming-potential process materials.
- Electric vehicle displays:OEM integration of pillar-to-pillar curved screens is pulling specialized glass substrate and polarizer film volumes into automotive qualification pipelines previously reserved for consumer electronics.
- Phosphorescent emitter chemistry:Advances in blue emitter stability are extending OLED panel lifetimes sufficiently for commercial monitor adoption, opening material supply contracts beyond smartphone-centric demand.
Market Restraints
- Gen 10.5 glass concentration:Fusion-draw manufacturing for large-format television substrates remains captive to a handful of facilities, creating single-source vulnerability for panel makers scaling 65-inch and larger products.
- Indium supply sensitivity:ITO transparent electrode deposition depends on concentrate availability from zinc mining byproduct streams, exposing touch-panel and OLED anode costs to base metal market volatility.
- REACH substance restrictions:ECHA candidate list expansion for SVHCs is forcing reformulation of photoresist strippers and edge-seal adhesives, extending qualification timelines for European-bound shipments.
Strategic Opportunities
- India display manufacturing:PLI scheme incentives for semiconductor and display fabrication are attracting substrate and chemical suppliers to establish localized blending and finishing operations near emerging panel fabs.
- Micro-LED transfer:Mass transfer yield improvements for chiplet placement onto TFT backplanes are creating material demand for temporary bonding adhesives and laser-release layers in pilot production lines.
- K-REACH alignment:South Korea's chemical registration reciprocity agreements with EU REACH are streamlining market entry for European specialty material suppliers targeting Samsung and LG ecosystems.
Industry Challenges
- Cleanroom engineering talent:Expansion of Gen 8.6 and larger substrate fabs is outpacing availability of process engineers experienced in particle control for sub-micron TFT patterning.
- Multi-generation equipment reuse:Retrofitting legacy LCD wet-etch lines for OLED-compatible chemistries requires capital outlays that strain mid-tier chemical distributors' balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Material Market |
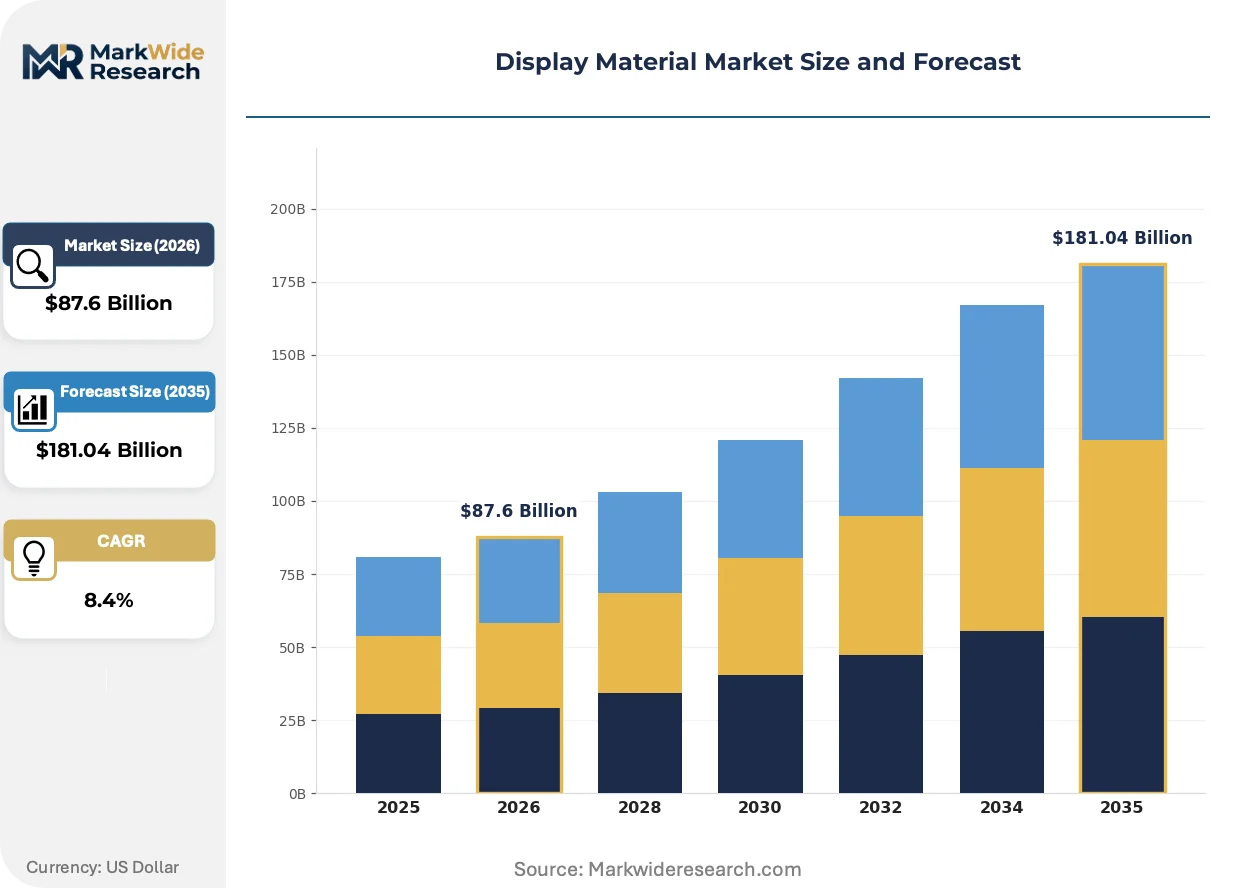
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $181.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, LED, Plasma Application: Televisions, Smartphones, Monitors, Automotive Displays Technology: Flat Panel, Flexible, Microdisplay, Quantum Dot End User: Consumer Electronics, Industrial Use, Healthcare, Digital Signage |
| Companies Covered | Corning Incorporated, Nitto Denko Corporation, LG Chem, Samsung SDI Co., Ltd., AGC Inc., DIC Corporation, Sumitomo Chemical, Merck KGaA, Universal Display Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Material Market Emerging Trajectories
Material architectures are fragmenting across competing display technologies, with substrate and emitter chemistries diverging rather than converging as LCD, OLED, and micro-LED each optimize for distinct performance-cost tradeoffs.
Mini-LED backlight diffusion films are migrating from premium television stacks into mainstream monitor and automotive applications as die cost curves compress and local dimming zone counts proliferate. Panel brands in the PC and commercial display segments are adopting these films to bridge contrast performance gaps without absorbing full OLED panel premiums. The technology is migrating from television-centric supply chains into diversified fabrication networks serving multiple end-use verticals simultaneously.
EPA enforcement under the American Innovation and Manufacturing Act is tightening reporting thresholds for fluorinated gas emissions at display manufacturing facilities, particularly affecting etching and chamber-cleaning operations. Facility operators are retrofitting abatement systems or substituting process chemistries to maintain operating permits. California and Texas-based fabs face the most immediate compliance deadlines, driving regional variation in material specification requirements.
Automotive OEMs are unbundling display subsystem procurement from traditional Tier 1 infotainment integrators, establishing direct material qualification relationships with glass substrate and optical film suppliers. This disintermediation compresses specification feedback loops but fragments order volumes across more direct supplier relationships. German and South Korean vehicle programs exhibit the most advanced direct-procurement structures, with North American OEMs following in 2024-2025 model year platforms.
Display Material Market Segmentation
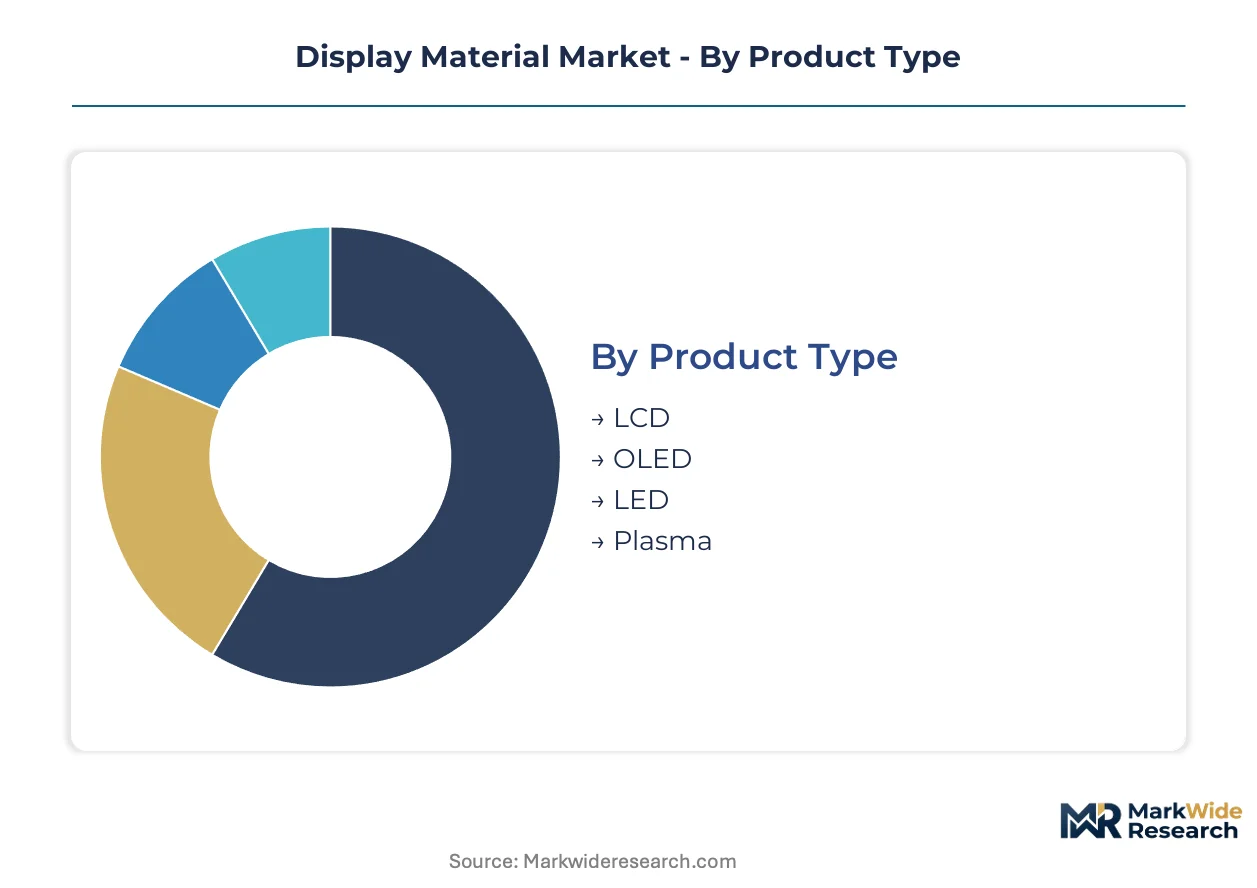
Display material procurement patterns diverge sharply across technology generations and end-use durability requirements. Understanding these fault lines enables suppliers to align formulation investments with qualification timelines that vary from six months for consumer electronics to three years for automotive programs.
Product Type:
Cost tier positioning determines substrate thickness specifications, emitter chemistry complexity, and encapsulation barrier requirements across display architectures.
- LCD:Liquid crystal cells modulate backlight transmission through voltage-controlled molecular orientation. Television and industrial monitor procurement in China and Taiwan sustains polarizer film and color filter demand despite OLED encroachment in premium tiers.
- OLED:Organic electroluminescent layers enable self-emissive pixels without backlight assemblies. Samsung SDI and LG Chem in South Korea concentrate phosphorescent emitter and quantum dot ink supply for smartphone and emerging automotive applications.
- LED:Direct-emission diodes serve backlighting and direct-view applications with gallium nitride epitaxy on sapphire substrates. Mini-LED diffusion into mainstream monitors is compressing die cost curves.
- Plasma:Ionized gas discharge technology persists in specialized industrial signage requiring extreme viewing angles. Replacement parts procurement sustains limited phosphor and electrode material demand.
LCD commands the established base. The steepest expansion runs through OLED.
Application:
Volume concentration varies by substrate generation, with Gen 10.5 glass serving television fabs while Gen 6 lines feed mobile and automotive qualification pipelines.
- Televisions:Large-format panels demand fusion-draw glass substrates measuring 0.5 mm thickness with thermal expansion coefficients below 3.8 × 10⁻⁶/°C. Corning's Gen 10.5 supply dominance in China and Japan anchors regional fabrication networks for 65-inch and larger products.
- Smartphones:Mobile displays prioritize thin-film encapsulation and flexible polyimide substrates for foldable form factors. South Korean and Chinese panel makers drive phosphorescent emitter procurement for high-resolution OLED stacks.
- Monitors:Commercial and gaming displays adopt mini-LED backlight diffusion to bridge contrast performance gaps without absorbing full OLED panel premiums.
- Automotive Displays:Pillar-to-pillar curved screens in electric vehicle cockpits require specialized glass thermal expansion matching with Tier 1 integrator specifications. German and South Korean OEMs lead direct material qualification relationships.
Televisions anchor volume demand. Automotive displays are climbing the fastest.
Technology:
Maturity gradients separate mass-production-ready architectures from pilot-line technologies awaiting yield breakthroughs.
- Flat Panel:Rigid glass substrate construction dominates established television and monitor fabrication with mature supply chains for TFT backplane deposition.
- Flexible:Polyimide and ultra-thin glass substrates enable curved and foldable form factors through thin-film encapsulation barriers. Samsung and BOE in China and South Korea concentrate pilot-to-mass-production scaling.
- Microdisplay:Silicon backplane integration for augmented reality headsets demands sub-micron pixel pitch lithography. Compound semiconductor epitaxy supply constraints limit near-term volume scaling.
- Quantum Dot:Nanocrystal color conversion layers expand gamut coverage in high-end televisions. Cadmium-free formulations satisfy EU REACH and South Korea K-REACH registration requirements.
Flat panel retains the installed base. Flexible technology is gaining share fastest.
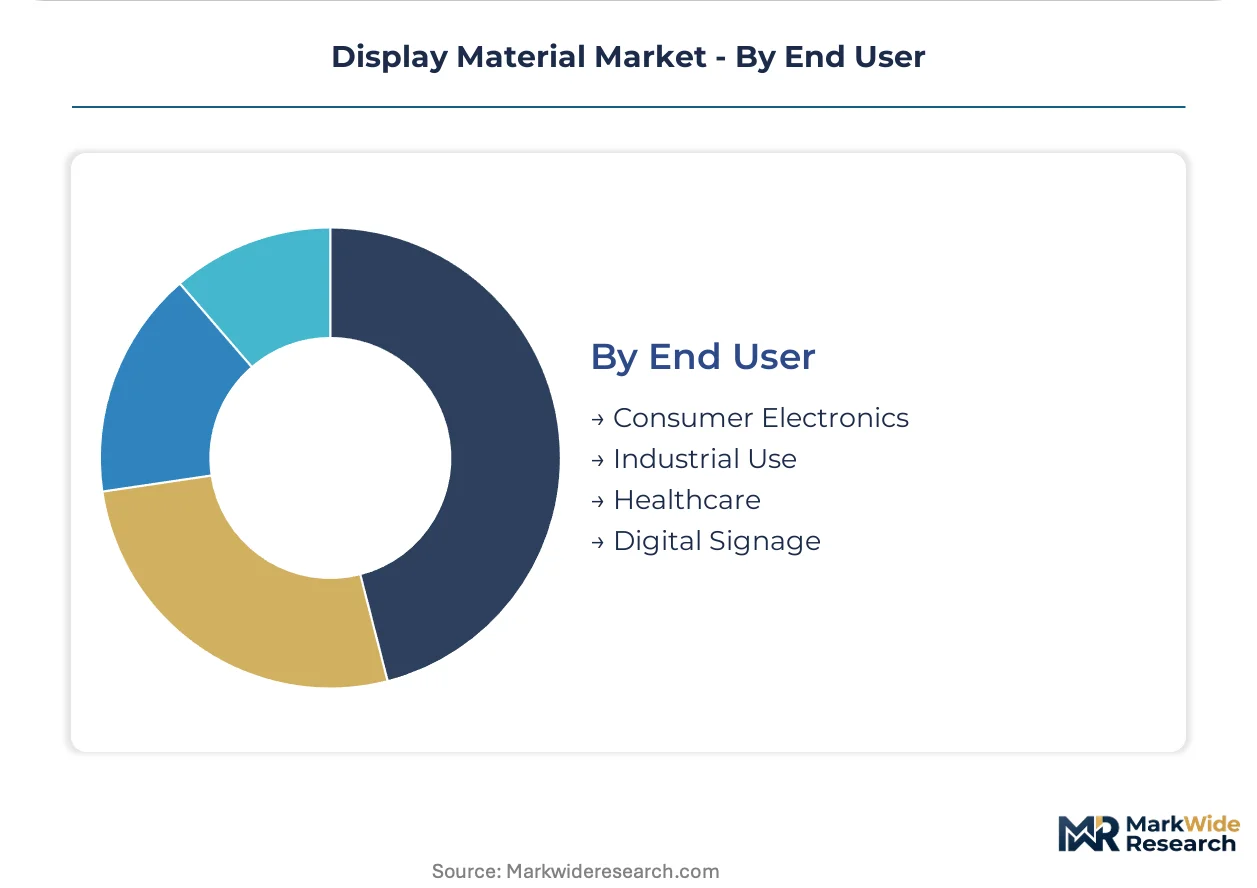
End User:
Customer type dictates certification rigor, with healthcare and industrial segments imposing durability testing that consumer electronics bypass.
- Consumer Electronics:Smartphone and television procurement cycles drive annual material demand volatility with six-month qualification windows. Brand concentration in China and South Korea shapes regional chemical supplier access.
- Industrial Use:Harsh-environment displays for manufacturing automation require extended-temperature liquid crystal formulations and reinforced edge seals. Japan's METI standards influence regional specification adoption.
- Healthcare:Diagnostic imaging displays demand color calibration stability and antimicrobial surface treatments. FDA and EU MDR compliance extends qualification timelines beyond consumer tiers.
- Digital Signage:Outdoor and retail installations prioritize brightness retention and vandal-resistant cover glass. India PLI scheme incentives are attracting substrate finishing operations for emerging regional demand.
Consumer electronics commands volume leadership. Healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display material procurement concentrates with panel makers in South Korea, China, and Japan, with automotive OEMs in Germany and the United States establishing direct supplier relationships for curved cockpit screens.
South Korea
Samsung SDI and LG Chem anchor phosphorescent emitter and quantum dot ink supply for smartphone and emerging automotive OLED stacks. K-REACH chemical registration reciprocity with EU REACH streamlines European specialty material supplier access to domestic panel ecosystems. The Seoul Capital Area concentrates thin-film encapsulation and flexible substrate pilot-to-mass-production scaling.
China
BOE and CSOT drive Gen 10.5 glass substrate consumption for 65-inch and larger television fabrication, sustaining polarizer film and color filter demand despite OLED premium-tier encroachment. MIIT dual carbon goals pressure display fabs to retrofit abatement systems for fluorinated process gas emissions. The Yangtze River Delta and Pearl River Delta cluster fusion-draw glass finishing and TFT backplane deposition capacity.
Japan
Nitto Denko and AGC supply polarizer films and display glass to domestic and export panel makers, with METI standards influencing regional specification adoption for industrial and automotive durability tiers. Extended-temperature liquid crystal formulations face qualification timelines exceeding consumer electronics cycles. The Kanto and Kansai regions concentrate optical film coating and precision glass processing operations.
United States
EPA enforcement under the American Innovation and Manufacturing Act tightens reporting thresholds for fluorinated gas emissions at display manufacturing facilities, particularly affecting etching and chamber-cleaning operations in California and Texas fabs. Automotive OEMs are disintermediating Tier 1 infotainment integrators to establish direct material qualification relationships. The Pacific Northwest and Southwest host substrate and chemical supplier technical service operations.
Germany
EU F-Gas Regulation and ECHA REACH SVHC candidate list expansion force reformulation of photoresist strippers and edge-seal adhesives for European-bound shipments, extending qualification timelines. German OEMs lead direct procurement of curved glass substrates for pillar-to-pillar electric vehicle cockpits. Bavaria and Baden-Württemberg concentrate automotive display subsystem engineering and Tier 1 integrator specification development.
Display Material Market Vendor Landscape
Channel-controlling players compete with product-specialist players across substrate, emitter, and optical film tiers. The structure consolidates around glass substrate and polarizer film supply, with fragmentation in specialty chemical and encapsulation material segments. Three archetypes dominate: fusion-draw glass specialists, phosphorescent emitter chemistry developers, and optical film coaters. Capacity expansion and strategic partnerships constitute the dominant competitive moves as panel makers seek to secure Gen 10.5 glass volumes and alternative etching chemistry supply.
Among Japanese material suppliers, Nitto Denko Corporation and AGC Inc. occupy positions within the optical film and display glass archetypes respectively. Corning Incorporated anchors the fusion-draw glass substrate tier for large-format panel fabrication. Samsung SDI Co., Ltd. exemplifies the vertically integrated Korean chemical supplier model spanning emitters to quantum dot formulations.
| Leading Market Players |
|---|
| Corning Incorporated |
| Nitto Denko Corporation |
| LG Chem |
| Samsung SDI Co., Ltd. |
| AGC Inc. |
| DIC Corporation |
| Sumitomo Chemical |
| Merck KGaA |
| Universal Display Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta cluster concentrates Gen 10.5 fusion-draw glass capacity for large-format television substrates, concentrating pricing power with Corning and AGC while panel makers absorb pass-through costs for thermal expansion coefficient specifications. This geographic lock-in forces downstream buyers into long-term offtake contracts with limited spot-market alternatives, amplifying cost volatility transmission from energy-intensive melting operations.
Pricing Analysis
Cost-plus contracts with indium price indexation dominate ITO transparent electrode procurement, tying touch-panel and OLED anode costs to zinc mining byproduct concentrate markets. Price differentiation rests on glass thickness tolerances and phosphorescent emitter purity grades, with automotive qualification tiers commanding premiums over consumer electronics volumes. Cost compression in standard-grade polarizer films is intensifying because Chinese domestic suppliers are scaling coating capacity. Smartphone OEMs exhibit the highest price sensitivity, while German automotive OEMs prioritize thermal expansion matching over unit cost.
Supply Chain Analysis
Export control regimes restricting phosphorescent OLED emitter chemistry and quantum dot precursor synthesis limit technology transfer to non-allied manufacturing bases. Supply concentrates in South Korea, Japan, and China for glass substrates, polarizer films, and organic emitter materials. Raw material dependencies draw from rare earth concentrate streams, high-purity indium metal, and fluorinated etching gas precursors. Single-source vulnerability for Gen 10.5 fusion-draw glass creates chokepoint exposure for 65-inch and larger panel scaling. Distribution runs through vertically integrated panel maker procurement arms with direct qualification relationships replacing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Display material demand follows semiconductor capital expenditure cycles, with the current upswing in Gen 8.6 and Gen 10.5 fab buildouts driving substrate and chemical volume recovery through the analysis window.
For Market Incumbents: Insulate phosphorescent emitter margins by deepening backward integration into iridium and platinum organometallic precursor synthesis, countering Chinese domestic supplier encroachment in standard-grade OLED materials. Secure captive indium concentrate offtake from zinc smelter partnerships to hedge transparent electrode cost volatility. Prioritize K-REACH and EU REACH dual-registration investments to maintain access to Samsung and LG ecosystems against regulatory fragmentation threats. For New Entrants and Emerging Players: India PLI scheme incentives for semiconductor and display fabrication represent the most penetrable entry point for substrate finishing and chemical blending operations, with tariff-advantaged access to emerging BOE and Vedanta panel fabs. Cadmium-free quantum dot ink formulations for EU-bound television shipments offer a technical differentiation wedge against established nanocrystal suppliers. Pursue direct qualification relationships with German automotive OEMs disintermediating Tier 1 integrators for curved glass substrate procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical developers with phosphorescent blue emitter stability patents, as commercial monitor adoption extends OLED material demand beyond smartphone-centric volumes. Long-term viability hinges on micro-LED mass transfer adhesive and laser-release layer supply contracts scaling from pilot to mass production. Watch mini-LED backlight diffusion film procurement patterns as the inflection signal—migration into mainstream monitor and automotive applications would validate expanded coating capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive iridium organometallic production secures phosphorescent emitter margins against concentrate price volatility. |
| K-REACH Dual Registration Investment | Streamlined EU REACH reciprocity opens Samsung and LG procurement channels for European specialty chemical suppliers. |
| India PLI-Aligned Capacity Buildout | Localized substrate finishing near emerging Vedanta and BOE fabs captures tariff-advantaged regional demand growth. |
| Automotive Direct Qualification Pipeline | Bypassing Tier 1 integrators for German OEM curved glass specifications compresses feedback loops and secures volume commitments. |
| Cadmium-Free Quantum Dot Formulation | ECHA REACH and K-REACH compliance enables premium television color conversion layer supply to EU and South Korean panel makers. |
Methodological Framework
Desk research of SEC 10-K filings, customs trade databases, and MIIT dual carbon policy documents preceded structured interviews with TFT backplane process engineers, display material procurement managers at BOE and CSOT, phosphorescent emitter R&D directors, and automotive Tier 1 integrator sourcing leads. Primary fieldwork captured qualification timeline dynamics, thermal expansion coefficient specification evolution, and fluorinated gas abatement retrofit capital planning. Secondary validation drew from EPA American Innovation and Manufacturing Act enforcement guidance, ECHA SVHC candidate list updates, and Korea Display Industry Association capacity announcements. Bottom-up substrate consumption modeling triangulated against top-down panel shipment forecasts by generation and application.
Assumptions held fixed include continuation of EU F-Gas Regulation tightening trajectories, K-REACH-EU REACH reciprocity maintenance, and indium byproduct recovery rates from zinc mining operations. Variables stress-tested across the projection horizon encompassed Gen 10.5 glass capacity expansion timing, micro-LED mass transfer yield improvement curves, and automotive display direct procurement adoption rates. Segmentation modeling incorporated product type, application, technology maturity, and end-user durability tier dimensions. CAGR derivation synthesized historical capacity utilization patterns with announced fab buildout schedules and emitter chemistry substitution elasticities.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, electric vehicle penetration rates, or display panel area per vehicle would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in phosphorescent blue emitter stability breakthroughs, export control regime expansion, or indium supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Phosphor Screen Market
Display Technologies
Portable Projector Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Holographic Display Market
Display Technologies
Video Projector Market
Display Technologies
PMOLED Display Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Paper-Thin Display Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Visual Computing Market
Display Technologies
Global Transparent Display Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Europe Computer Monitor Market