
 Light Field Display Market | 2026-2036
Light Field Display Market Size, Share, and Industry Trends Forecast 2026-2036
Light Field Display Market Outlook
Subscription-based software-defined rendering is hardening as the dominant commercial model in light field display deployments. NVIDIA Corporation leverages its CUDA ecosystem to lock in developer workflows across simulation and entertainment verticals. Light Field Lab, Inc. anchors the premium hardware tier through proprietary solid-light panel manufacturing. Leia, Inc. differentiates by embedding diffractive lightfield optics directly into mobile and automotive display stacks.
Light field display systems capture and reproduce both the intensity and directional vector of light rays, enabling naked-eye depth perception without head-mounted apparatus through microlens arrays or holographic optical elements. These systems serve primary commercial purposes in surgical visualization, autonomous vehicle sensor fusion debugging, and immersive broadcast entertainment where binocular disparity alone proves insufficient. Holographic displays command the highest margin pools due to fabrication complexity and patent-protected optical architectures, while simulation applications across aviation and defense absorb the largest absolute volume of installed units. Gaming end users represent the fastest-expanding addressable base as cloud-rendered light field streaming reduces local compute requirements.
FDA software-as-medical-device oversight and EU MDR Class IIa certification pathways are elevating validation costs for holographic surgical planning entrants, effectively filtering subscale vendors from hospital procurement lists. FCC Part 15 emissions compliance and IEC 62471 photobiological safety standards govern consumer-facing installation density in retail and entertainment venues. Stakeholders must monitor convergence between real-time neural radiance field rendering and emerging display hardware refresh specifications to time capital allocation across content pipeline and panel manufacturing bets.
Market Dynamics
Neural radiance field rendering pipelines are compressing content production cycles for holographic display systems, forcing hardware manufacturers to synchronize refresh specifications with real-time inference capabilities or lose developer mindshare to GPU-native ecosystems.
Growth Catalysts
- FDA software-as-medical-device pathways:Hospital procurement committees now mandate holographic surgical planning tools carry Class IIa-equivalent validation, filtering out subscale vendors and concentrating purchase authority around certified integrators in Boston's surgical robotics cluster.
- Autonomous vehicle sensor fusion debugging:Automotive OEMs in Stuttgart and Detroit deploy volumetric displays to visualize LiDAR-camera-radar alignment discrepancies without head-mounted apparatus, accelerating validation timelines for SAE Level 3+ systems.
- Cloud-rendered light field streaming:Edge compute offloading is reducing local GPU requirements for gaming deployments, expanding addressable hardware tiers to mid-range consumer panels previously excluded by thermal constraints.
Market Restraints
- Proprietary solid-light panel fabrication:Manufacturing yields for holographic optical elements remain concentrated among single-source suppliers in California and Bavaria, creating supply vulnerability for premium-tier installations.
- IEC 62471 photobiological safety compliance:Retail and entertainment venue operators face installation density restrictions that cap screen-to-viewer ratios below conventional flat-panel deployments, constraining revenue-per-square-foot economics.
- Conventional stereoscopic VR headsets:Lower-cost binocular disparity systems continue displacing light field displays in price-sensitive training and simulation segments where depth fidelity requirements remain unenforced.
Strategic Opportunities
- EU AI Act conformity assessment:Holographic surgical planning tools validated under the Act's high-risk system requirements gain automatic mutual recognition across member state procurement frameworks, accelerating hospital network expansion.
- Neural radiance field-to-panel convergence:Real-time NeRF inference paired with emerging 240Hz+ refresh specifications enables broadcast sports volumetric replay without pre-rendered asset pipelines, opening live entertainment workflows.
- Direct-to-consumer mobile integration:Diffractive optics embedded in automotive HUD and smartphone form factors bypass specialty retail channels entirely, capturing pre-purchase trial behavior during commute and casual gaming moments.
Industry Challenges
- Computational optics talent scarcity:The intersection of wave optics simulation and machine learning deployment requires hybrid skill sets concentrated at fewer than twelve academic programs worldwide, inflating compensation premiums for qualified hires.
- Legacy PACS integration complexity:Hospital IT departments face eighteen-to-twenty-four-month certification timelines to bridge DICOM-compliant imaging archives with holographic visualization stacks, delaying procurement approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Field Display Market |
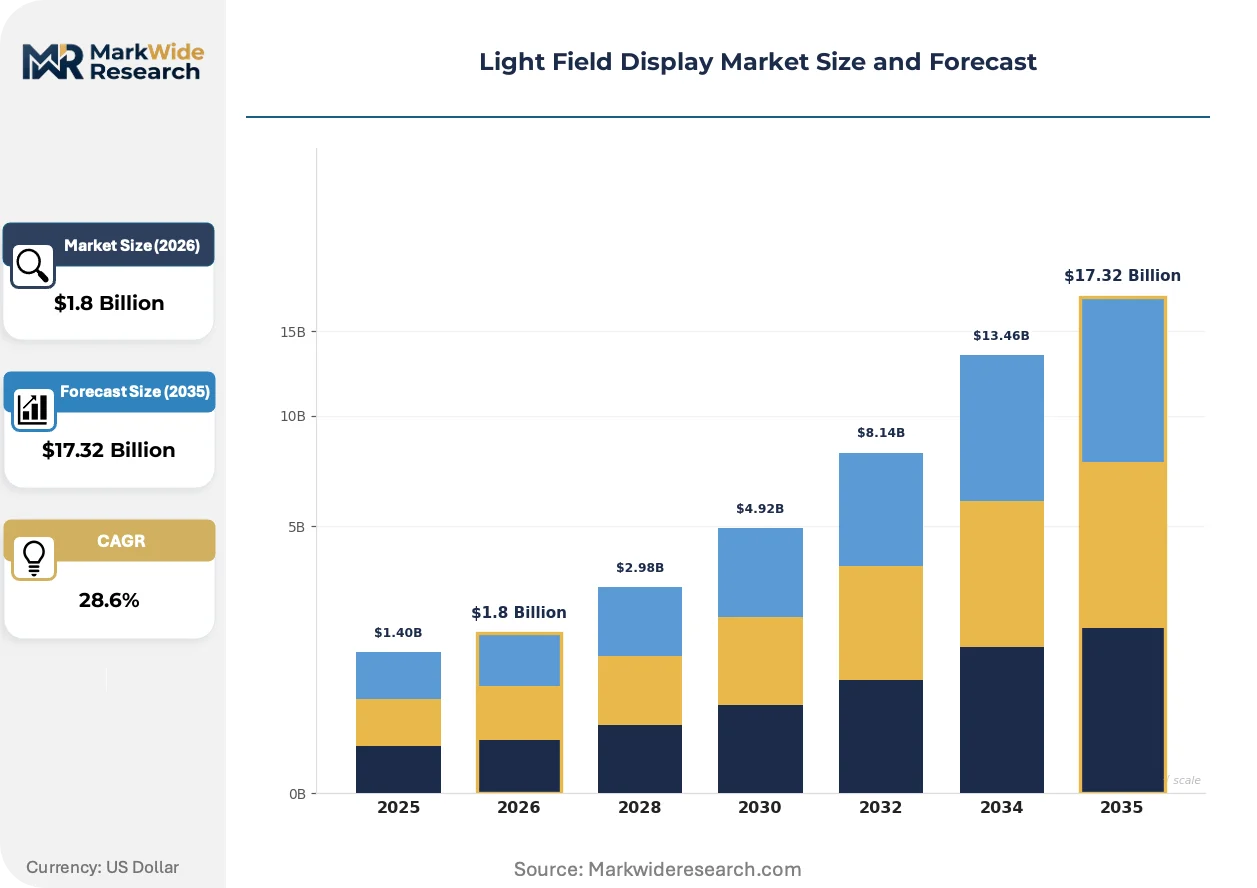
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Displays, 3D Displays, Virtual Reality Models, Holographic Displays Technology: LCD, OLED, Digital Light Processing, Laser End User: Gaming, Education, Advertising, Medical Imaging Application: Simulation, Entertainment, Visualization, Training |
| Companies Covered | Holografika, NVIDIA Corporation, Light Field Lab, Inc., Avegant Co., Japan Display, Inc., FoVi3D, Inc., Leia, Inc., OTOY Inc., Raytrix GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Field Display Market Strategic Shifts
Real-time neural rendering architectures are collapsing the boundary between content creation and display hardware, forcing synchronized innovation cycles across GPU, panel, and compression codec suppliers.
Neural radiance field inference engines are decentralizing holographic content production from specialized studio pipelines to edge devices. Medical imaging departments in Munich and Los Angeles now generate patient-specific volumetric visualizations from standard CT/MRI stacks without outsourced rendering farms. This compression of production geography is eliminating the twenty-four-to-forty-eight-hour turnaround that previously constrained surgical planning workflows.
The EU AI Act's high-risk system classification for holographic surgical guidance is mandating third-party conformity assessment before CE marking. German notified bodies have established specialized review tracks for volumetric visualization software, creating a six-to-nine-month validation backlog that favors pre-submitted vendors. Japanese PMDA regulators are observing the EU framework for potential harmonization, affecting export strategies for Osaka-based optical component suppliers.
Subscription-based software-defined rendering is displacing perpetual license models across simulation and entertainment verticals. Defense contractors in Arlington and Burbank studios now contract compute capacity by render-hour rather than maintaining captive GPU clusters. This unbundling of hardware from software procurement concentrates purchasing authority with CTOs rather than capital expenditure committees, compressing vendor selection cycles from annual to quarterly rhythms.
Light Field Display Market Segmentation
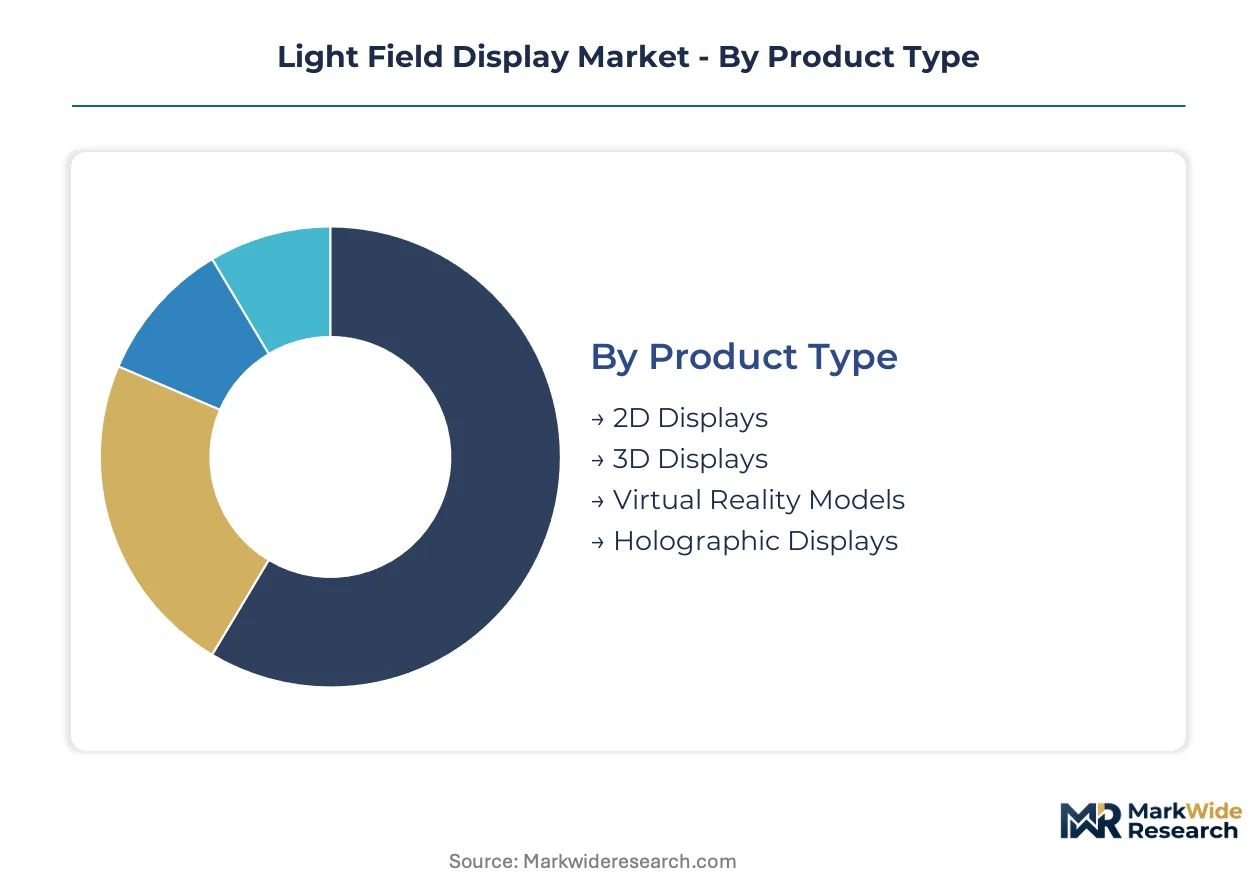
Light field display procurement patterns diverge sharply across hardware tiers and content pipelines. Product architecture determines whether deployments emphasize standardized volume manufacturing or bespoke optical engineering. Application context dictates refresh specifications, compute offloading requirements, and regulatory validation burdens.
Product Type:
Customization versus standardization tension runs deepest here, with fabrication complexity determining whether vendors pursue captive manufacturing or modular assembly strategies.
- Holographic Displays:Proprietary solid-light panels with holographic optical elements command premium positioning through patent-protected architectures. Hospital networks in Boston and Los Angeles concentrate procurement for surgical planning workflows where FDA Class IIa-equivalent validation filters subscale competitors.
- 3D Displays:Microlens array architectures enable naked-eye depth perception without head-mounted apparatus. Stuttgart automotive OEMs deploy these for LiDAR-camera-radar alignment debugging, accelerating SAE Level 3+ validation timelines.
- 2D Displays:Conventional flat-panel substrates adapted with directional backlighting serve cost-sensitive training segments where depth fidelity requirements remain unenforced.
- Virtual Reality Models:Cloud-rendered light field streaming reduces local GPU requirements, expanding addressable tiers to mid-range consumer panels previously excluded by thermal constraints.
Leading the category by volume: 3D Displays. Growing fastest: Holographic Displays.
Technology:
Cost tier stratification separates premium emissive architectures from legacy transmissive systems, with laser-based solutions anchoring the highest performance tier.
- OLED:Self-emissive pixel control enables microsecond response times critical for real-time neural radiance field rendering. Los Angeles entertainment studios and Arlington defense contractors prioritize these panels for simulation workloads requiring sub-frame latency.
- Laser:Coherent light sources deliver the luminance and color gamut necessary for large-format holographic installations. Manufacturing yields remain concentrated among single-source suppliers in California and Bavaria, creating supply vulnerability for premium-tier deployments.
- LCD:Mature backlighting architectures serve price-sensitive education and training segments where refresh specifications below 120Hz prove acceptable.
- Digital Light Processing:MEMS mirror arrays enable high-brightness projection for temporary installations and mobile volumetric displays.
Dominating by installed base: LCD. Steepest expansion trajectory: Laser.
End User:
Customer type determines procurement authority structures, with hospital committees imposing validation requirements that consumer channels ignore entirely.
- Medical Imaging:DICOM-compliant volumetric visualization requires eighteen-to-twenty-four-month PACS integration timelines. Munich and Los Angeles departments now generate patient-specific holographic renders from standard CT/MRI stacks without outsourced farms.
- Gaming:Edge compute offloading enables subscription-based software-defined rendering, compressing vendor selection cycles from annual to quarterly rhythms as CTOs displace capital expenditure committees.
- Advertising:IEC 62471 photobiological safety compliance caps installation density in retail venues, constraining revenue-per-square-foot economics below conventional flat-panel deployments.
- Education:Lower-cost binocular disparity systems continue displacing light field displays in price-sensitive training segments.
Highest absolute spend: Medical Imaging. Expanding most quickly: Gaming.
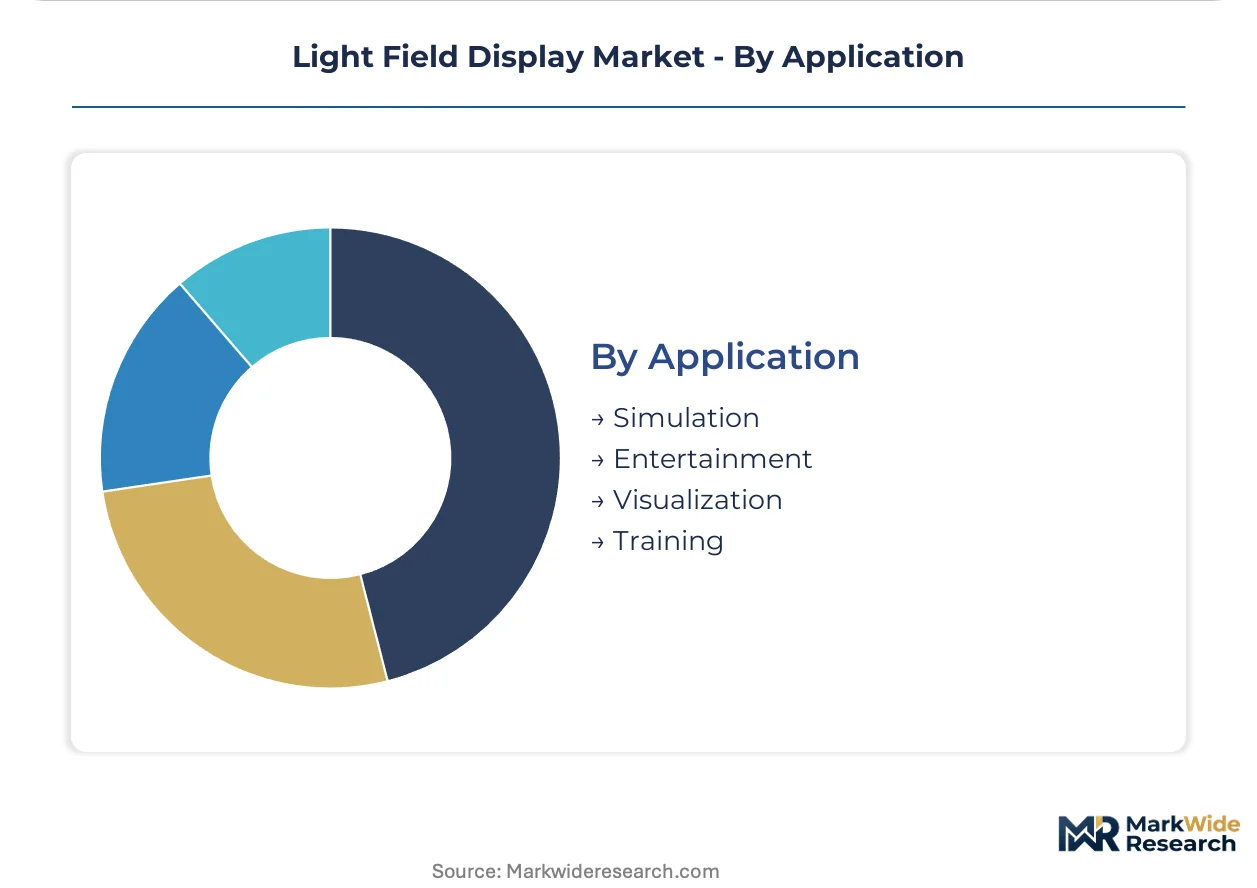
Application:
Volume concentration versus margin capture splits this category, with simulation absorbing unit volume while entertainment commands content licensing premiums.
- Simulation:Aviation and defense contractors contract compute capacity by render-hour rather than maintaining captive GPU clusters. Burbank studios and Arlington training facilities absorb the largest absolute volume of installed light field units.
- Entertainment:Real-time NeRF inference paired with 240Hz+ refresh specifications enables broadcast sports volumetric replay without pre-rendered asset pipelines, opening live entertainment workflows.
- Visualization:Autonomous vehicle sensor fusion debugging accelerates validation timelines for SAE Level 3+ systems in Detroit and Stuttgart development centers.
- Training:Cloud-rendered streaming reduces local compute requirements, expanding hardware addressability to mid-range consumer tiers.
Leading by unit shipments: Simulation. Gaining share fastest: Entertainment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing yields for holographic optical elements concentrate in California and Bavaria, while consumption clusters around surgical robotics corridors in Boston and entertainment technology hubs in Los Angeles. This production-consumption divide shapes regional procurement strategies and regulatory compliance burdens.
United States
FDA software-as-medical-device pathways filter subscale vendors from hospital procurement lists, concentrating purchase authority around certified integrators. FCC Part 15 emissions compliance governs consumer-facing installation density in retail venues. Boston's surgical robotics cluster and Los Angeles entertainment technology corridors absorb the highest absolute volumes of premium-tier deployments.
Germany
EU MDR Class IIa certification requirements elevate validation costs for holographic surgical planning entrants. German notified bodies have established specialized review tracks for volumetric visualization software, creating validation backlogs that favor pre-submitted vendors. Stuttgart automotive OEMs deploy volumetric displays for LiDAR-camera-radar alignment debugging.
Japan
PMDA regulators observe the EU AI Act framework for potential harmonization, affecting export strategies for Osaka-based optical component suppliers. METI standards guide photobiological safety compliance for consumer installations. Tokyo and Osaka medical imaging departments generate patient-specific volumetric visualizations from standard CT/MRI stacks.
China
MIIT standards govern display hardware refresh specifications and electromagnetic compatibility for domestic manufacturing. NMPA pathways for software-as-medical-device oversight remain under development, creating regulatory uncertainty for surgical visualization entrants. Yangtze River Delta fabrication clusters supply microlens array substrates for mid-tier 3D displays.
United Kingdom
CE marking requirements under EU MDR create post-Brexit compliance complexity for exporters serving continental hospital networks. MHRA consultation tracks diverge from EU notified body timelines for holographic surgical guidance systems. London defense contractors contract compute capacity by render-hour for simulation workloads.
Light Field Display Market Competitive Environment
Top-tier vendors anchor premium holographic hardware tiers through patent-protected optical architectures, while mid-tier specialists compete on microlens array standardization and cost-efficient manufacturing. The vendor base stratifies across three archetypes: CUDA-locked GPU ecosystem players, proprietary solid-light panel fabricators, and diffractive optics integrators targeting mobile form factors. Competitive moves concentrate on strategic partnerships with cloud render farms and backward integration into holographic optical element supply.
Within the ecosystem-locked tier, NVIDIA Corporation anchors developer workflow capture through CUDA-based rendering pipelines. Light Field Lab, Inc. and Leia, Inc. occupy distinct positioning vectors—one representing captive manufacturing of solid-light panels, the other exemplifying diffractive optics embedding for automotive and mobile stacks. These three entities collectively illustrate how competitive advantage separates hardware-captive from software-dominant and integration-focused archetypes.
| Leading Market Players |
|---|
| Holografika |
| NVIDIA Corporation |
| Light Field Lab, Inc. |
| Avegant Co. |
| Japan Display, Inc. |
| FoVi3D, Inc. |
| Leia, Inc. |
| OTOY Inc. |
| Raytrix GmbH |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA-validated surgical tiers and consumer entertainment tiers splits pricing power along validation depth, with holographic optical element yields in California and Bavaria anchoring premium cost structures while microlens array commoditization in East Asian fabrication clusters compresses mid-tier margins.
Pricing Analysis
Margin tightening in holographic surgical tiers reflects eighteen-to-twenty-four-month PACS integration timelines that hospital procurement committees translate into vendor lock-in premiums. Subscription-based software-defined rendering now dominates simulation and entertainment verticals, compressing vendor selection cycles from annual to quarterly rhythms as CTOs displace capital expenditure committees. Price differentiation hinges on FDA Class IIa-equivalent validation status and proprietary solid-light panel fabrication depth, with Boston hospital networks exhibiting lowest price sensitivity and education training segments absorbing maximum cost-down pressure.
Supply Chain Analysis
Dual-sourcing requirements for holographic optical elements remain unenforceable given single-source concentration in California and Bavaria, forcing automotive OEMs and defense contractors to accept supply vulnerability for premium-tier deployments. Manufacturing draws from laser diode substrates, microlens array masters, and diffractive optical element photoresists. Tariff exposure on precision optics imports from German notified body jurisdictions threatens cost predictability. Distribution runs through direct OEM integration for medical and automotive tiers, with cloud render farms disintermediating hardware for gaming deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in holographic optical element fabrication prop pricing power for validated vendors, with yield bottlenecks at California and Bavaria manufacturing sites creating durable margin pools for certified integrators.
For Market Incumbents: Extend backward integration into holographic optical element supply to defend against single-source vulnerability in California and Bavaria, while accelerating FDA pre-submission pathways to exploit German notified body validation backlogs that filter subscale competitors from hospital procurement lists. For New Entrants and Emerging Players: Launch via cloud-rendered light field streaming partnerships to bypass captive GPU cluster requirements, targeting mid-range consumer gaming tiers where thermal constraints previously excluded addressable hardware and subscription models compress incumbent switching costs. For Investors and Strategic Acquirers: Re-rating potential sits with diffractive optics integrators given automotive HUD and smartphone embedding catalysts, with five-to-ten-year viability hinging on neural radiance field-to-panel convergence timelines; acquisition targets should demonstrate real-time inference capability paired with emerging 240Hz+ refresh specifications, with the signal to watch being PMDA harmonization with EU AI Act frameworks affecting Osaka-based component supplier export strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Holographic Optical Elements | Captive supply of solid-light panels insulates California and Bavaria vendors from single-source yield vulnerability. |
| FDA Software-as-Medical-Device Pre-Submission | Early engagement with Boston surgical robotics clusters secures Class IIa-equivalent validation ahead of German notified body backlogs. |
| Neural Radiance Field Rendering Partnership | Real-time inference alliances with GPU-native ecosystems lock in developer workflows across Arlington defense contractors. |
| Automotive HUD Diffractive Optics Embedding | Direct-to-consumer mobile integration bypasses retail channel density caps imposed by IEC 62471 photobiological restrictions. |
| Cloud Render Farm Capacity Expansion | Edge compute offloading enables subscription-based software-defined rendering for mid-tier gaming hardware previously excluded by thermal constraints. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with holographic display engineers, hospital procurement committee chairs, automotive sensor fusion leads, and cloud render farm operators. FDA 510(k) submissions, EU MDR notified body decisions, and MIIT display hardware standards provided regulatory validation anchors. Bottom-up panel shipment tallies triangulated against top-down entertainment studio and defense contractor compute capacity contracts.
Granularity-level modeling distinguished holographic from 3D and 2D display architectures, with technology tiers segmented by OLED, laser, LCD, and digital light processing backplanes. End-user categories captured medical imaging, gaming, advertising, and education procurement patterns. Application splits tracked simulation, entertainment, visualization, and training workflows. CAGRs derived from installed base growth curves and content pipeline expansion rates, with neural radiance field inference capability and refresh specification convergence treated as demand elasticity drivers across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for real-time neural radiance field rendering would alter the outlook if GPU-native ecosystems fail to synchronize with emerging panel refresh specifications. Deviation in holographic optical element manufacturing yields or EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
IGZO Display Market
Display Technologies
4K VR Displays Market
Display Technologies
Multi-Function Display Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Interactive Display Market
Display Technologies
Global Embedded Display Market
Display Technologies
Rugged Display Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Wireless Display Market
Display Technologies
Electroluminescent Display Market