
 Electronic Display Signs Market | 2026-2036
Electronic Display Signs Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Display Signs Market Foresight
The EU Green Deal's energy-efficiency mandates for public infrastructure is consolidating demand around low-power LED architectures in European municipal procurement. Samsung Electronics leverages its semiconductor foundry capacity to captive-produce driver ICs for high-resolution outdoor modules. LG Display anchors premium OLED signage supply through Gen 8.5 wafer-scale manufacturing in Korea. Daktronics dominates North American sports and transit installations with vertically integrated assembly in South Dakota.
Electronic display signs are electro-optical devices that render visual information through pixel arrays composed of light-emitting diodes, liquid crystals, or organic compounds, typically measured by nit brightness, pixel pitch, and refresh rate, designed to communicate dynamic content in commercial, civic, or transportation environments. LED product types now command the largest installed base due to lumen-per-watt efficiency and modular repairability, while OLED segments capture margin pools in premium indoor retail and corporate lobby deployments where contrast ratio and form factor justify unit premiums. Application demand skews toward advertising displays in private-sector deployment, though traffic signs and public information displays absorb sustained government capital allocation across aging infrastructure replacement cycles.
The US EPA ENERGY STAR program and FCC Part 15 emissions standards shape product certification requirements for domestic deployment, while the EU F-Gas Regulation restricts refrigerant-based thermal management in outdoor cabinets, pushing manufacturers toward passive and liquid-cooled architectures. China's GB standards for electromagnetic compatibility and MIIT certification for networked displays create layered compliance thresholds for import and domestic sale. Stakeholders must monitor divergence between regional efficiency benchmarks and connectivity protocols as procurement specifications harden around interoperability and lifecycle carbon accounting.
Market Dynamics
The Electronic Display Signs Market is undergoing structural compression as municipal procurement specifications harden around lifecycle carbon accounting and interoperability mandates, forcing manufacturers to re-architect product roadmaps around passive thermal management and open connectivity protocols.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Public infrastructure retrofits across France, Germany, and Italy are consolidating demand for low-power LED architectures in street-level and transit deployments.
- Smart city budgets in China:Tier-one municipalities including Beijing, Shanghai, and Shenzhen are prioritizing intelligent traffic and transit displays with networked remote-management capabilities.
- LED lumen-per-watt efficiency gains:Solid-state lighting advances are reducing operational expenditure for retail chains replacing static signage with dynamic digital screens.
Market Restraints
- Driver IC supply concentration:Semiconductor foundry capacity constraints in East Asia are creating bottlenecks for high-resolution outdoor module production.
- F-Gas Regulation thermal management restrictions:The EU framework is banning refrigerant-based cooling in outdoor cabinets, forcing costly redesigns toward liquid-cooled architectures.
- OLED material cost volatility:Organic compound supply instability is compressing margin pools in premium indoor retail segments.
Strategic Opportunities
- India smart city mission:Underpenetrated municipal digitization programs in Mumbai, Delhi, and Bangalore are creating deployment white space for traffic and public information displays.
- GB standards compliance services:China's electromagnetic compatibility certification requirements are generating adjacent revenue streams for testing and integration consultancies.
- Edge-AI content personalization:On-device computer vision is converging with display hardware to enable real-time audience analytics in retail and transit environments.
Industry Challenges
- MIIT certification timeline compression:China's networked display approval processes are extending product launch cycles by six to nine months for import-dependent vendors.
- Legacy analog infrastructure integration:Municipal transit authorities in aging European and North American systems are requiring costly protocol bridges for IP-native displays.
- Field service technician scarcity:Specialized skills for micro-LED repair and calibration are concentrating in Korean and Taiwanese labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Display Signs Market |
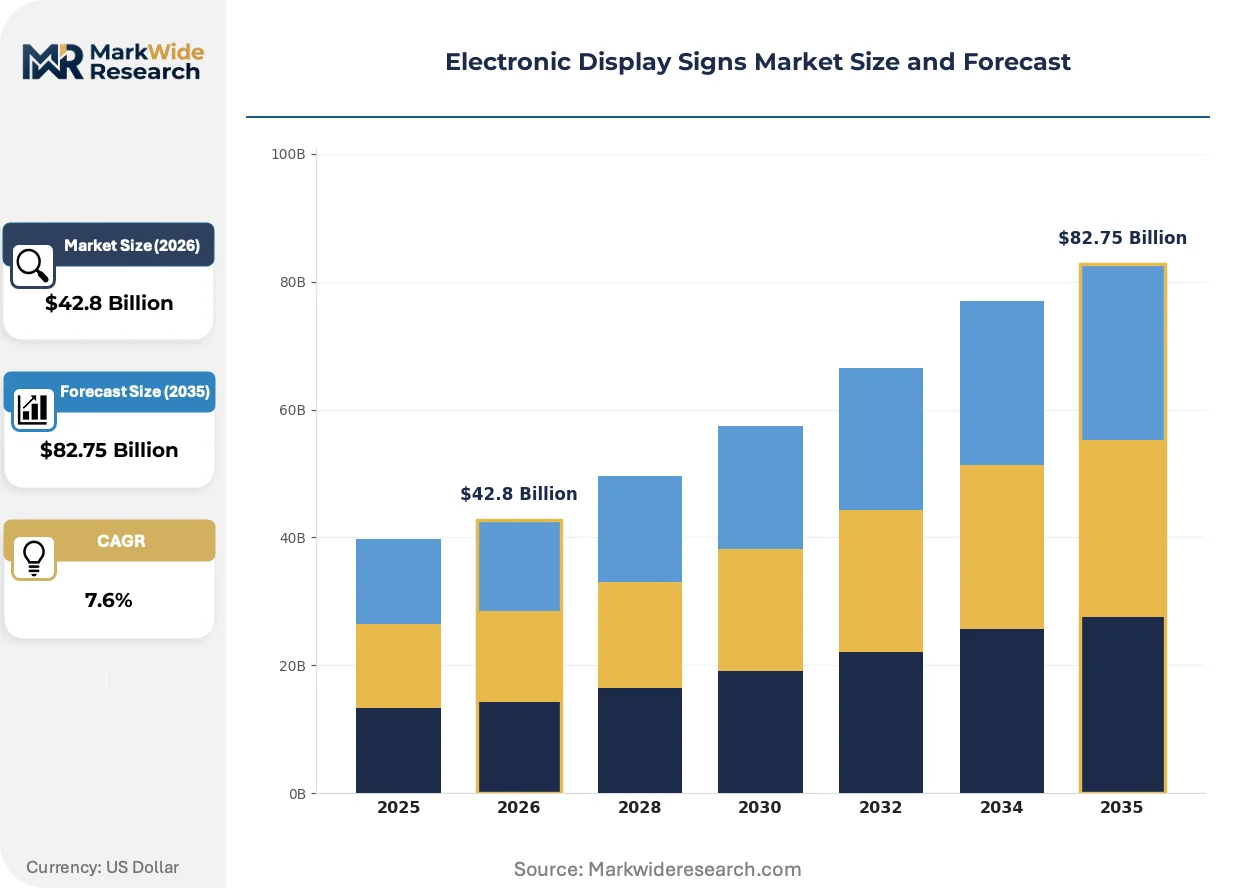
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $82.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, Projection Application: Billboards, Traffic Signs, Advertising Displays, Public Information Displays Customer Type: Retail, Transportation, Education, Government Installation Type: Outdoor, Indoor, Wall-mounted, Freestanding |
| Companies Covered | Samsung Electronics, LG Display, NEC Display Solutions, Daktronics, Sony Corporation, Leyard Optoelectronic, Panasonic Corporation, Sharp Corporation, Barco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Display Signs Market Shifts & Advancements
Active matrix addressing architectures and system-on-panel integration are compressing module thickness while expanding deployment contexts. These shifts are redefining competitive differentiation around thermal performance and content-management openness.
Mini-LED backlighting is converging with quantum dot color enhancement to deliver cinema-grade contrast in daylight-readable outdoor formats. Large-format retail and sports venue operators in Texas, Florida, and California are specifying these hybrid architectures for flagship installations. The technology is converging with passive cooling designs to meet EPA ENERGY STAR thermal efficiency thresholds without mechanical refrigeration.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon refrigerants in outdoor display cabinets from 2027, accelerating engineering investment in vapor-chamber and liquid-loop thermal management. Manufacturers with captive semiconductor packaging capabilities are capturing specification advantages in German and French municipal tenders. Dutch and Belgian transit authorities are now requiring F-Gas-free certification as a mandatory evaluation criterion.
Content-as-a-service subscription models are displacing perpetual-license software in North American retail chain deployments. Brand marketers in New York, Chicago, and Los Angeles are unbundling creative production from hardware procurement, favoring vendors with API-first content management platforms. This reconfiguration is concentrating recurring revenue with display-agnostic software providers while compressing upfront hardware margins.
Electronic Display Signs Market Segmentation
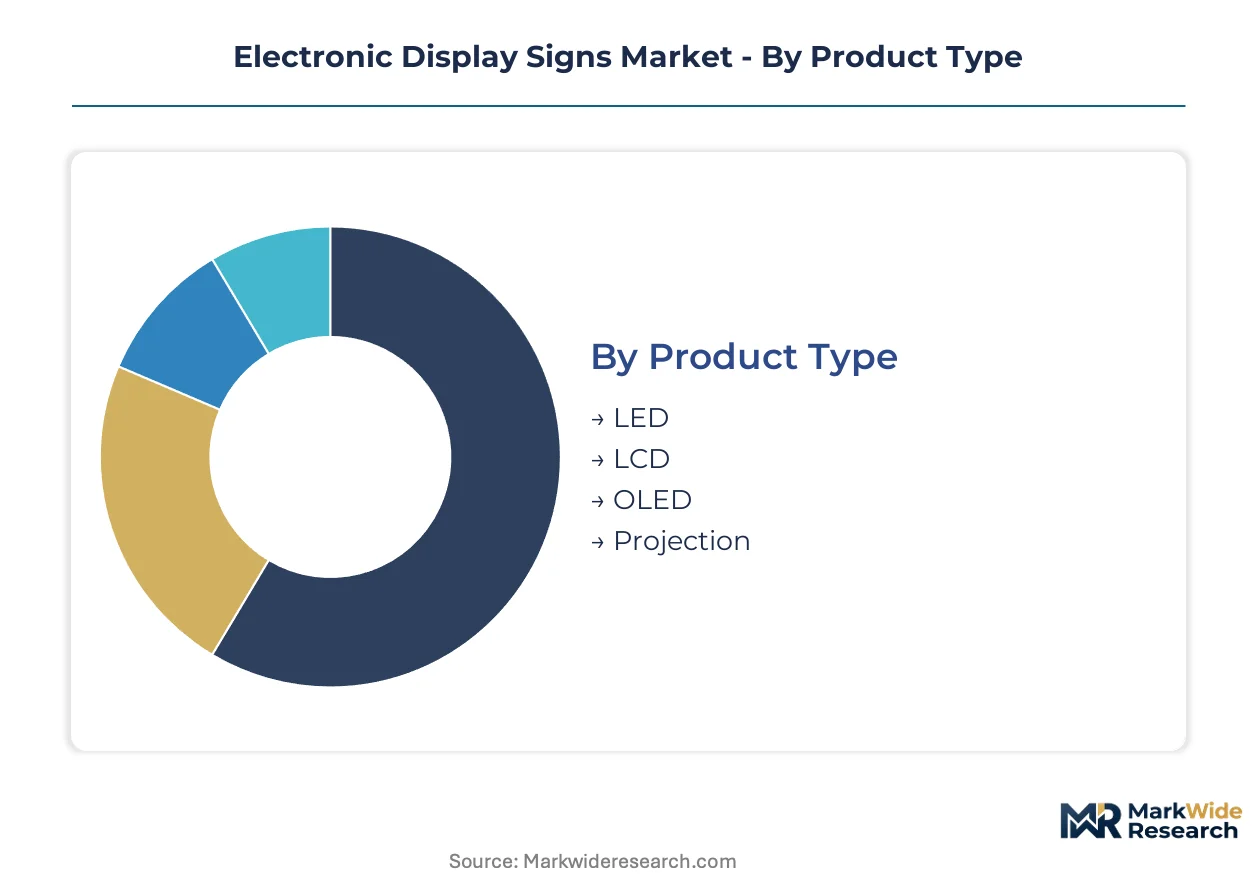
Electronic display signs fragment across four distinct taxonomies that shape procurement patterns and margin structures. Product type determines thermal architecture and power consumption profiles. Application context dictates brightness specifications and regulatory compliance burdens.
Product Type:
LED modules dominate installed base through lumen-per-watt efficiency and field-repairability, while OLED commands unit premiums in contrast-sensitive indoor environments.
- LED:Solid-state diode arrays deliver 120+ nits per watt with modular pixel replacement. Municipal transit authorities in France and Germany specify these for F-Gas-compliant outdoor cabinets. Demand concentrates in street-level advertising and intelligent traffic systems where operational longevity outweighs upfront capital.
- LCD:Liquid-crystal panels with edge-lit or direct-lit LED backlights occupy mid-brightness indoor applications. Corporate lobbies and quick-service restaurants in Texas and Florida deploy these for menu boards and wayfinding where ambient light control permits lower nit output.
- OLED:Organic electroluminescent compounds enable sub-3mm form factors and infinite contrast ratios. Premium retail flagships in New York and Los Angeles absorb these for brand storytelling where viewing angle and color fidelity justify 3-5x unit premiums over LCD alternatives.
- Projection:Laser-phosphor and LED-illuminated projectors render temporary or oversized surfaces without fixed hardware. Event venues and pop-up retail in Chicago and London favor these for seasonal campaigns requiring rapid deployment and removal.
Today's leader: LED. Tomorrow's challenger: OLED.
Application:
Advertising displays generate the largest revenue pool through private-sector replacement cycles, while traffic signs absorb sustained government infrastructure allocation.
- Billboards:Large-format roadside structures exceeding 14 feet by 48 feet demand weather-sealed cabinets and 10,000+ nit brightness for daylight readability. Highway corridors in California and Arizona drive specification innovation around thermal management and remote content distribution.
- Traffic Signs:Variable message signs and lane control signals require MIL-STD-810G vibration resistance and NEMA 4X ingress protection. State DOTs in Texas and Florida prioritize these for congestion management and emergency alert dissemination.
- Advertising Displays:Retail and transit network screens ranging from 32-inch shelf-edge to 85-inch portrait formats. Programmatic buying platforms in London and Paris are consolidating inventory aggregation around these assets.
- Public Information Displays:Wayfinding and civic communication screens in airports, hospitals, and municipal buildings. Wayfinding deployments in Dubai International Airport and Singapore Changi set benchmark specifications for multi-language support and accessibility compliance.
Advertising displays expand most quickly through programmatic monetization. Public information displays offer the steadiest procurement visibility.
Customer Type:
Retail chains drive volume through networked rollout programs, while transportation authorities impose the most demanding certification requirements.
- Retail:Grocery, fashion, and quick-service chains replacing static signage with centrally managed digital networks. Walmart and Target specifications for 24/7 operational reliability are de facto industry standards for indoor durability.
- Transportation:Airports, rail operators, and municipal transit authorities requiring IEC 62368-1 safety certification and EN 50155 railway compliance. London Underground and New York MTA tenders set electromagnetic compatibility benchmarks.
- Education:K-12 and university campuses deploying interactive flat panels and digital bulletin systems. Campus IT departments in California and Massachusetts prioritize API accessibility for learning management system integration.
- Government:Federal, state, and municipal agencies procuring through GSA schedules and EU public procurement directives. EPA ENERGY STAR and EU Green Deal compliance are mandatory evaluation criteria.
Retail customers scale fastest. Government customers pay most predictably.
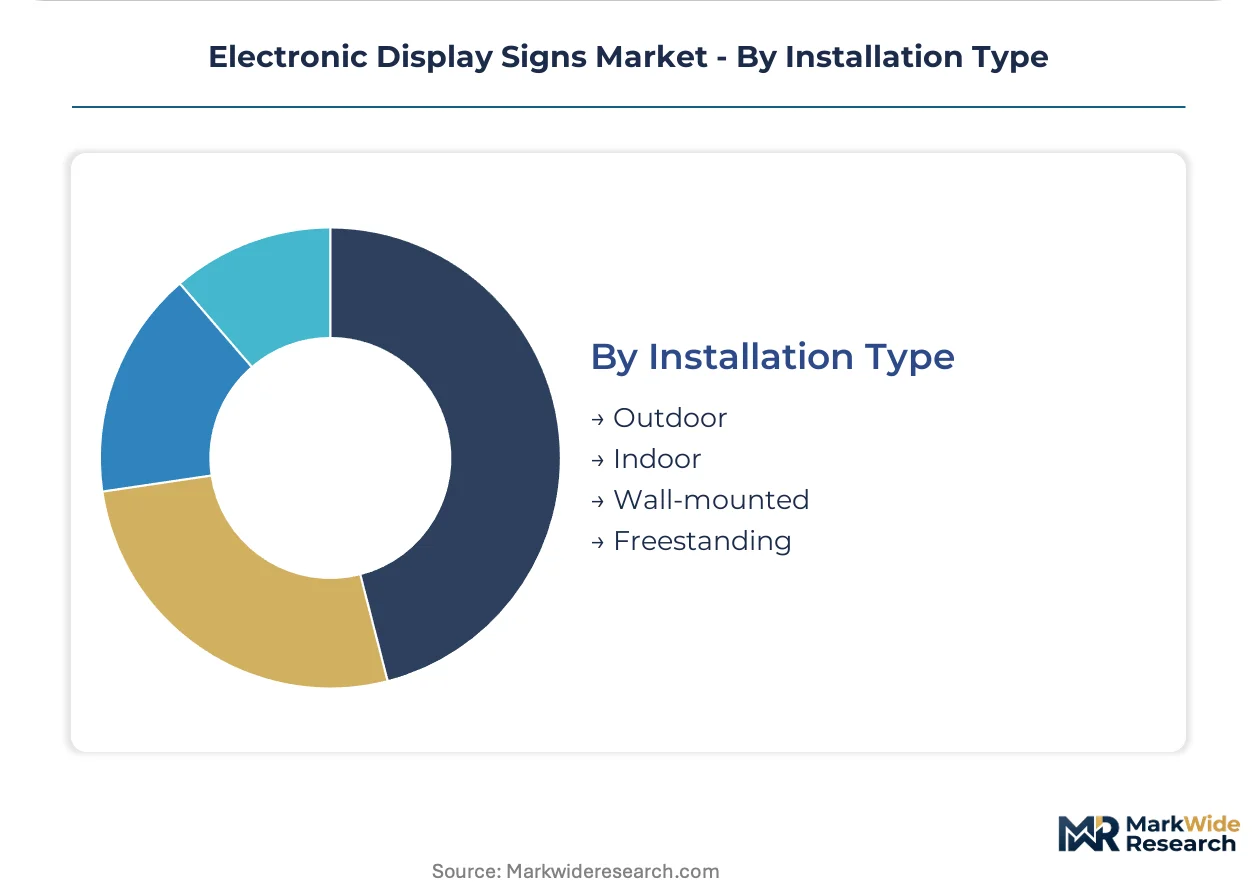
Installation Type:
Outdoor deployments command thermal engineering premiums, while indoor installations emphasize aesthetic integration and acoustic discretion.
- Outdoor:Pole-mounted, building-integrated, and ground-supported structures facing temperature extremes from -40°C to 50°C. Passive cooling and liquid-loop thermal management are displacing refrigerant-based systems under EU F-Gas Regulation timelines.
- Indoor:Climate-controlled environments permitting fanless operation and thinner chassis profiles. Corporate headquarters in Manhattan and Frankfurt specify these for lobby and conference room integration.
- Wall-mounted:Fixed installations requiring VESA or custom bracketry with concealed cable management. Healthcare facilities in Boston and Munich favor these for patient room information displays where floor space is constrained.
- Freestanding:Kiosk and totem formats with integrated media players and touch interactivity. Shopping malls in Dubai and Singapore deploy these for directory and promotional content with 360-degree visibility.
Outdoor installations capture the highest per-unit value. Wall-mounted formats are gaining share fastest in healthcare and education verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electronic display signs industry traces its commercial origins to Japanese and South Korean manufacturing clusters that pioneered LED packaging and TFT-LCD fabrication during the 1990s. These East Asian production centers established the process architectures and supply chain templates that subsequent regional entrants adapted for local market conditions.
United States
State DOTs in Texas and Florida drive demand for variable message signs with MIL-STD-810G vibration ratings. The EPA ENERGY STAR program mandates thermal efficiency thresholds for federal procurement. Daktronics anchors production in South Dakota for sports venue and transit installations across the Sun Belt corridor.
Germany
French and Italian municipal authorities source compliant outdoor cabinets through cross-border procurement frameworks. The EU F-Gas Regulation bans hydrofluorocarbon refrigerants from 2027, forcing liquid-cooled redesigns. Bavarian engineering firms supply vapor-chamber thermal management systems to transit operators in Munich and Nuremberg.
China
Beijing, Shanghai, and Shenzhen smart city budgets prioritize intelligent traffic displays with networked remote-management capabilities. MIIT certification requirements extend product launch cycles for import-dependent vendors. Leyard Optoelectronic concentrates manufacturing capacity in Beijing for domestic and export module assembly.
South Korea
Premium OLED signage demand concentrates in Seoul corporate lobbies and Incheon International Airport retail. Samsung Electronics and LG Display anchor Gen 8.5 wafer-scale manufacturing in Gumi and Paju. Korean semiconductor foundries captive-produce driver ICs for high-resolution outdoor modules.
India
Mumbai, Delhi, and Bangalore smart city missions create deployment white space for traffic and public information displays. BIS electromagnetic compatibility standards layer compliance thresholds for domestic sale. Domestic system integrators in Hyderabad and Chennai assemble imported LED modules for municipal tenders.
Electronic Display Signs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent cost structures in the electronic display signs market. Foundry-dependent module assemblers face margin compression when semiconductor capacity tightens, while vertically integrated electronics conglomerates buffer supply shocks through captive driver IC production. Three archetypes dominate: diversified conglomerates with semiconductor packaging capabilities, specialized outdoor display fabricators with municipal certification expertise, and software-anchored platform vendors unbundling content management from hardware. Competitive moves concentrate on thermal architecture redesigns for F-Gas compliance and API-first content platform development for recurring revenue capture.
Among diversified conglomerates, Samsung Electronics and LG Display exemplify the foundry-integrated archetype with in-house semiconductor production. Daktronics occupies a position within the specialized outdoor fabrication tier, anchored in North American sports and transit verticals. Sony Corporation represents the premium-tier vector where broadcast-grade color science migrates into commercial signage applications.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| NEC Display Solutions |
| Daktronics |
| Sony Corporation |
| Leyard Optoelectronic |
| Panasonic Corporation |
| Sharp Corporation |
| Barco |
| Others |
Supply & Pricing Matrix
Municipal procurement authorities in Germany and France anchor pricing power through consolidated tender volumes for F-Gas-compliant outdoor cabinets. Their specification mandates for passive thermal management and networked remote-management capabilities compress margin pools for module assemblers while rewarding vertically integrated electronics conglomerates with captive driver IC production.
Pricing Analysis
Project-based contracting with lifecycle service bundling dominates municipal and large-format retail deployments. Three-tier pricing structure across premium, standard, and economy levels separates OLED corporate lobby installations from LED transit displays and LCD quick-service menu boards. Cost compression in standard-tier LED modules is intensifying because semiconductor foundry capacity constraints in East Asia limit driver IC availability. Government transportation authorities exhibit lowest price sensitivity due to IEC 62368-1 and EN 50155 certification requirements, while independent retail chains negotiate aggressively on upfront hardware costs.
Supply Chain Analysis
Ocean freight rates from South Korean and Chinese ports to Rotterdam and Long Beach directly impact landed costs for finished modules and bare driver ICs. Manufacturing concentration centers on South Korea, China, and Taiwan for LED packaging, TFT-LCD fabrication, and semiconductor foundry output. The supply chain draws from gallium nitride substrates, indium tin oxide sputtering targets, and organic emitter compounds for OLED stacks. Single-source vulnerability in East Asian driver IC foundries creates procurement risk for European and North American assemblers. Distribution runs through specialized AV integrators and direct municipal contracting channels rather than commodity electronics wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electronic Display Signs Market compounds steadily through infrastructure replacement cycles and smart city digitization mandates that guarantee recurring procurement visibility across decade-long horizons.
For Market Incumbents: Anchor defensive positioning through captive semiconductor packaging capabilities that buffer driver IC supply shocks. Deepen backward integration into LED die and driver IC production to capture specification advantages in German and French municipal tenders. Prioritize F-Gas-free thermal architecture R&D to meet 2027 regulatory deadlines before competitors complete redesign cycles. For New Entrants and Emerging Players: Begin with India's underpenetrated smart city missions in Mumbai, Delhi, and Bangalore where domestic system integrators lack high-resolution outdoor module expertise. Target traffic and public information display verticals where BIS electromagnetic compatibility certification creates service-layer revenue rather than capital-intensive manufacturing. Pursue GB standards compliance consulting as a low-capital entry vector before scaling to hardware assembly. For Investors and Strategic Acquirers: Diversified electronics conglomerates with semiconductor foundry assets are the most active acquirers in this space, seeking to consolidate driver IC supply chains. Long-term viability hinges on thermal architecture IP and content-management platform recurring revenue rather than commoditized module assembly. Monitor EU F-Gas Regulation enforcement timelines as the inflection signal for competitive repositioning toward liquid-cooled and vapor-chamber designs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Production | Samsung Electronics and LG Display leverage Gumi and Paju foundries to captive-supply high-resolution outdoor modules. |
| F-Gas-Free Thermal Architecture Development | Bavarian engineering firms supply vapor-chamber systems to Munich and Nuremberg transit operators ahead of 2027 bans. |
| API-First Content Management Platform Launch | Retail chains in New York and Chicago unbundle creative production from hardware procurement to capture recurring SaaS revenue. |
| MIIT Certification Compliance Service Expansion | Testing consultancies in Beijing and Shanghai reduce launch cycle delays for import-dependent vendors by six to nine months. |
| Edge-AI Computer Vision Integration | On-device audience analytics in Dubai and Singapore shopping malls enable real-time content personalization for programmatic monetization. |
Research Methodology
Bottom-up municipal and retail deployment modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core of this study. Primary interviews with transit authority procurement officers, LED module plant managers, AV systems integrators, and smart city program directors combined with secondary validation from EPA ENERGY STAR certification databases, EU public procurement directive filings, MIIT networked display registrations, and SEC 10-K disclosures from diversified electronics conglomerates. Triangulation between end-use demand signals and supply-side manufacturing constraints ensures statistical integrity across market sizing.
Input-output matrices map driver IC wafer starts to finished module shipments across product type, application context, installation environment, and customer vertical dimensions throughout the forecast period. CAGRs derive from regression analysis against smart city budget appropriations, retail chain replacement cycles, and regulatory compliance deadlines rather than extrapolation of historical growth rates. Industry-specific forecast inputs include F-Gas Regulation phase-out timelines and MIIT certification approval velocity.
Several conditions sit outside the modeled scope, including potential relaxation of China's electromagnetic compatibility enforcement, accelerated OLED material cost volatility from organic compound supply disruptions, and municipal budget freezes from macroeconomic contraction. Forecasts reflect documented assumptions about procurement specification hardening and interoperability mandate adoption. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Dot Matrix Display Market
Display Technologies
Foldable Display Market
Display Technologies
Smart Screen Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Backlit Displays Market
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
4K Technology Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Field Emission Display Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Microdisplay Market