
 Bluetooth Audio Soc Chips Market | 2026-2036
Bluetooth Audio Soc Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Audio Soc Chips Market Insights
Silicon is pivoting toward 22nm and 12nm process nodes as foundry economics reshape die cost structures for mid-tier Bluetooth audio SoCs. Qualcomm leverages its codec patent portfolio to sustain premium-tier positioning in wireless headphone platforms. Nordic Semiconductor anchors its growth on Bluetooth Low Energy SoC specialization for wearable devices with ultra-low power budgets. Texas Instruments competes through integrated analog front-ends that reduce external component count for smart speaker OEMs.
A Bluetooth audio SoC integrates a baseband processor, radio transceiver, audio DSP, and power management unit onto a single die, typically fabricated at nodes between 40nm and 12nm with operating voltages below 1.2V for active states. The device enables wireless audio streaming, voice capture, and hands-free calling across battery-powered consumer electronics. Dual Mode SoC architectures now lead shipment volumes by supporting both classic Bluetooth audio and LE Audio protocols within unified silicon. Bluetooth 5.3 technology is gaining fastest among new designs for its enhanced connection stability and Auracast broadcast audio capabilities. Consumer Electronics Manufacturers represent the deepest margin pool as they negotiate volume commitments across annual smartphone and accessory refresh cycles.
FCC Part 15 rules in the United States govern unintentional radiators and restrict out-of-band emissions for 2.4 GHz Bluetooth devices, directly influencing RF front-end design and shielding requirements. ETSI EN 300 328 in Europe mandates adaptive frequency hopping and channel occupancy detection, pushing vendors to invest in coexistence algorithms. China's MIIT radio regulations enforce transmit power caps and spurious emission limits that shape product variants for the domestic market. Stakeholders must monitor LE Audio certification timelines and Auracast deployment momentum to calibrate R&D allocation between legacy codec support and next-generation broadcast audio architectures.
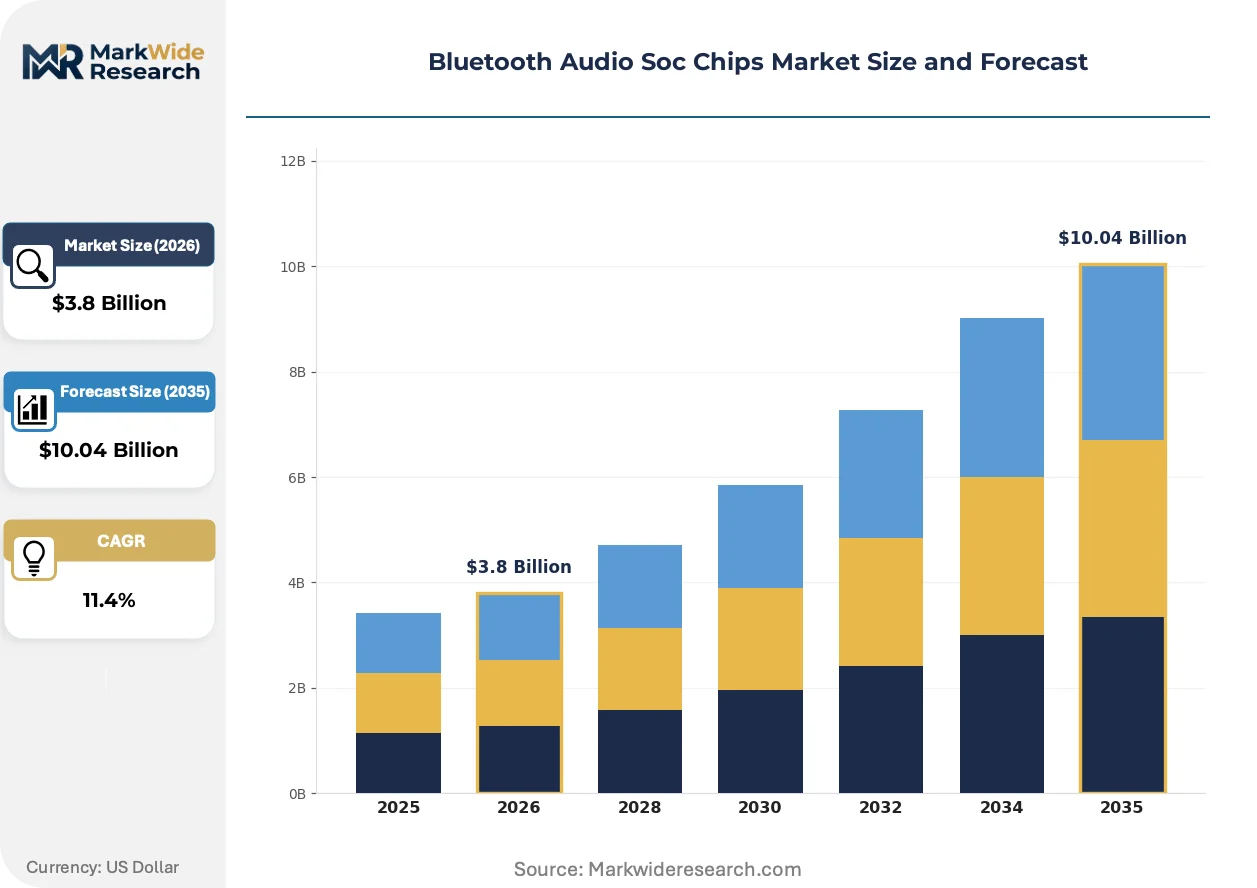
Market Dynamics
The transition from 40nm to 12nm process nodes is compressing die costs and enabling dual-mode architectures that merge Classic Bluetooth with LE Audio protocols on unified silicon, forcing incumbent vendors to retool foundry relationships.
Growth Catalysts
- LE Audio protocol proliferation:Auracast broadcast capabilities are driving replacement cycles in hearing aid and public venue installations, creating fresh silicon demand beyond traditional stereo headphones.
- Shenzhen manufacturing corridor concentration:Proximity to ODMs and EMS providers accelerates design-to-volume timelines for consumer electronics brands targeting annual refresh cycles.
- MIIT transmit-power compliance:China's tightened radio-frequency certification rules favor integrated SoC vendors with in-house RF calibration over discrete chipset assemblers.
Market Restraints
- Advanced node foundry allocation:22nm and 12nm capacity at TSMC and Samsung Foundry prioritizes smartphone APs, constraining Bluetooth audio SoC wafer starts during supply crunches.
- Codec licensing stack costs:Qualcomm's patent portfolio on aptX and LDAC forces mid-tier vendors into royalty-bearing agreements that erode gross margins below 35 percent.
- Silicon analog front-end integration limits:Discrete PA and LNA components persist in premium-tier designs, preventing full single-chip realization and inflating BOM complexity.
Strategic Opportunities
- Auracast deployment in transit infrastructure:Airports and rail systems in Germany and France are piloting broadcast audio systems that require LE Audio-certified SoCs with multi-language stream support.
- Wearable health convergence:Bluetooth Low Energy SoCs with integrated bio-sensing front-ends are capturing design wins in continuous glucose monitors and pulse oximetry patches.
- India PLI scheme for electronics manufacturing:Production-linked incentives for mobile phone and component assembly are drawing SoC vendors to establish local technical support and reference design centers.
Industry Challenges
- RF validation engineer scarcity:The specialized skill set for 2.4 GHz coexistence testing and antenna tuning commands premium compensation in Shenzhen and Taipei hiring markets.
- LE Audio certification backlog:Bluetooth SIG qualification queues for Auracast and LC3 codec implementations are stretching product launch timelines by four to six months.
- Legacy Classic Bluetooth support obligations:Maintaining backward compatibility with billions of installed headphones is fragmenting firmware development resources across dual protocol stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Audio Soc Chips Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Bluetooth SoC, Bluetooth Low Energy SoC, Dual Mode SoC, Audio SoC Technology: Bluetooth 4.0, Bluetooth 4.2, Bluetooth 5.0, Bluetooth 5.2, Bluetooth 5.3 Application: Wireless Headphones, Smart Speakers, Automotive Infotainment, Wearable Devices, Gaming Consoles End User: Consumer Electronics Manufacturers, Automotive Tier-1s, Gaming Hardware OEMs, Wearable Device Makers |
| Companies Covered | Nordic Semiconductor, Qualcomm, Texas Instruments, STMicroelectronics, Silicon Labs, Renesas, Realtek, Infineon, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Audio Soc Chips Market Trends and Innovations
Silicon architects are embedding machine learning accelerators and neural network engines directly onto Bluetooth audio SoCs to enable on-device voice recognition and adaptive noise cancellation without cloud dependency.
On-chip neural processing units are integrating dedicated inference engines for keyword spotting and ambient sound classification. TWS earbud OEMs in South Korea and Taiwan are qualifying these designs for 2024 product generations. The capability is integrating always-listening functionality while holding active power below 5 milliwatts, compressing the discrete DSP market.
ETSI EN 300 328 adaptive frequency hopping mandates are tightening channel occupancy detection thresholds across European markets. Vendors must now implement real-time spectrum sensing algorithms that add 15-20 percent to baseband die area. Smart speaker OEMs serving EU distribution channels are absorbing these silicon costs rather than risking market exclusion.
Direct-to-consumer audio brands are bypassing traditional retail distribution through crowdfunding platforms and TikTok-native commerce. Shenzhen-based ODMs are responding with minimum-order-quantity reductions and faster tooling amortization schedules. The shift is most visible in North American and Western European markets where incumbent retail margins of 40-50 percent are being disintermediated.
Bluetooth Audio Soc Chips Market Segmentation
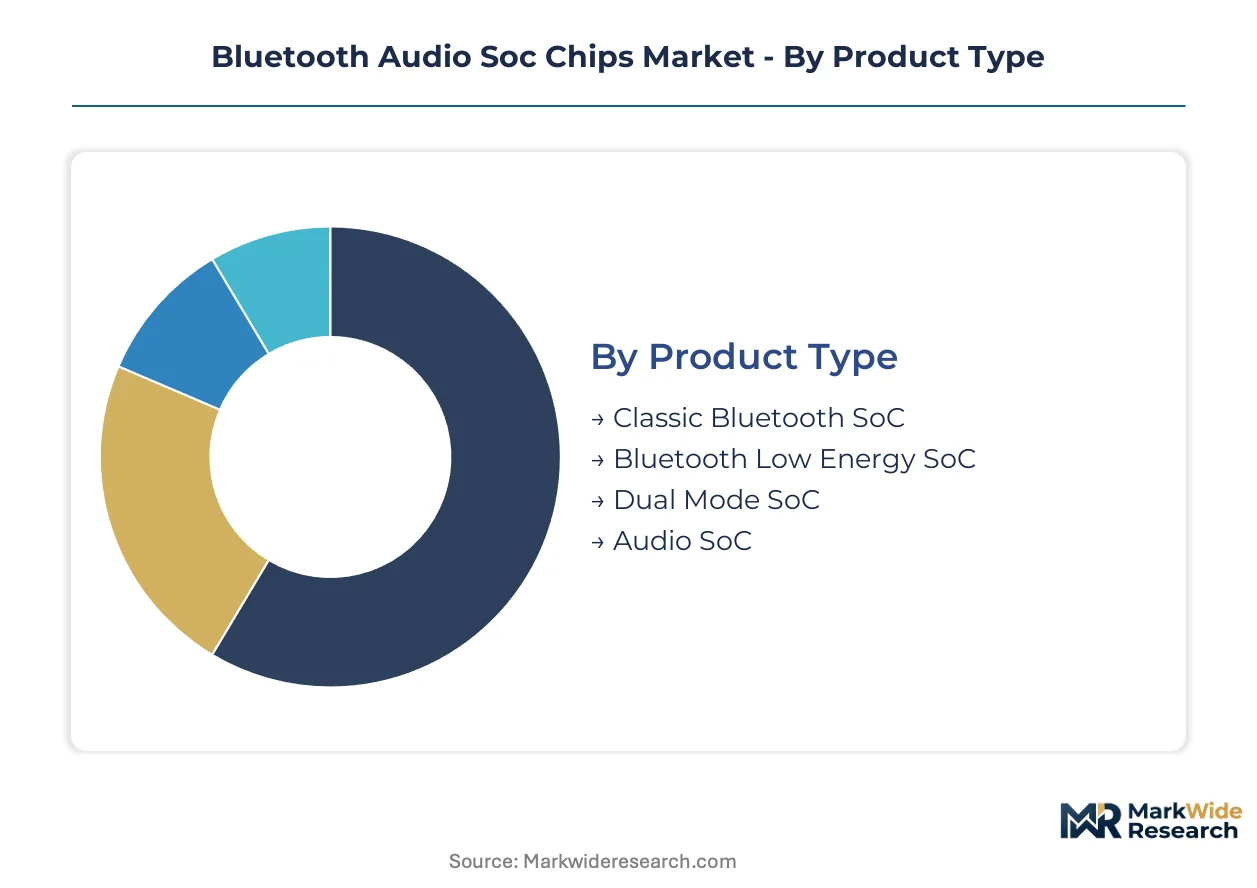
Bluetooth audio SoC segmentation reveals how protocol generations, power budgets, and end-use requirements fragment silicon architectures across consumer and industrial applications. Vendors calibrate die size, RF front-end integration, and DSP capability against specific customer procurement criteria.
Product Type:
Process node selection and protocol support define the competitive positioning of each silicon variant.
- Dual Mode SoC:Unified silicon architectures merge Classic Bluetooth audio and LE Audio protocols on single dies fabricated at 22nm and 12nm nodes. Shenzhen-based ODMs are absorbing these designs for TWS earbud platforms targeting annual smartphone refresh cycles. MIIT transmit-power compliance favors integrated vendors with in-house RF calibration over discrete assemblers.
- Bluetooth Low Energy SoC:Ultra-low power architectures operate below 5 milliwatts active consumption for wearable health applications including continuous glucose monitors and pulse oximetry patches. Nordic Semiconductor anchors its growth on this specialization.
- Classic Bluetooth SoC:Legacy protocol support maintains backward compatibility with billions of installed headphones, fragmenting firmware resources across dual stack obligations.
- Audio SoC:Dedicated audio DSP integration targets smart speaker OEMs requiring multi-channel processing and voice assistant wake-word detection.
Mature deployment sits with Classic Bluetooth SoC. Newer deployment is concentrated in Dual Mode SoC.
Technology:
Bluetooth specification generations determine coexistence algorithms, broadcast audio capabilities, and certification timelines.
- Bluetooth 5.3:Enhanced connection stability and Auracast broadcast audio capabilities are gaining fastest among new designs. ETSI EN 300 328 adaptive frequency hopping mandates push real-time spectrum sensing algorithms that add 15-20 percent to baseband die area for EU-bound products.
- Bluetooth 5.2:LE Audio protocol support with LC3 codec implementation enables hearing aid and public venue installations in Germany and France.
- Bluetooth 5.0:Extended range and higher data throughput serve automotive infotainment systems requiring stable cabin connectivity.
- Bluetooth 4.2:Legacy integration persists in cost-optimized wearable devices with minimal data payload requirements.
- Bluetooth 4.0:Basic rate and enhanced data rate support remains in industrial sensor applications with decade-long product lifecycles.
Bluetooth 4.0 and 4.2 anchor replacement-phase volume. Bluetooth 5.3 commands the steepest expansion trajectory.
Application:
Acoustic environments and battery constraints shape RF front-end and DSP specifications.
- Wireless Headphones:Active noise cancellation and spatial audio processing demand neural network accelerators embedded directly onto SoC dies. South Korean and Taiwanese OEMs are qualifying these designs for next-generation TWS platforms.
- Smart Speakers:Far-field voice capture and multi-room synchronization require integrated analog front-ends that reduce external component count.
- Wearable Devices:Continuous health monitoring convergence drives Bluetooth Low Energy SoC adoption with bio-sensing front-end integration.
- Automotive Infotainment:Cabin-wide audio distribution and hands-free calling prioritize connection stability over power efficiency.
- Gaming Consoles:Low-latency audio streaming for wireless headsets demands dedicated packet prioritization in baseband processors.
Wireless Headphones concentrate the deepest margin pool. Wearable Devices are climbing the fastest.
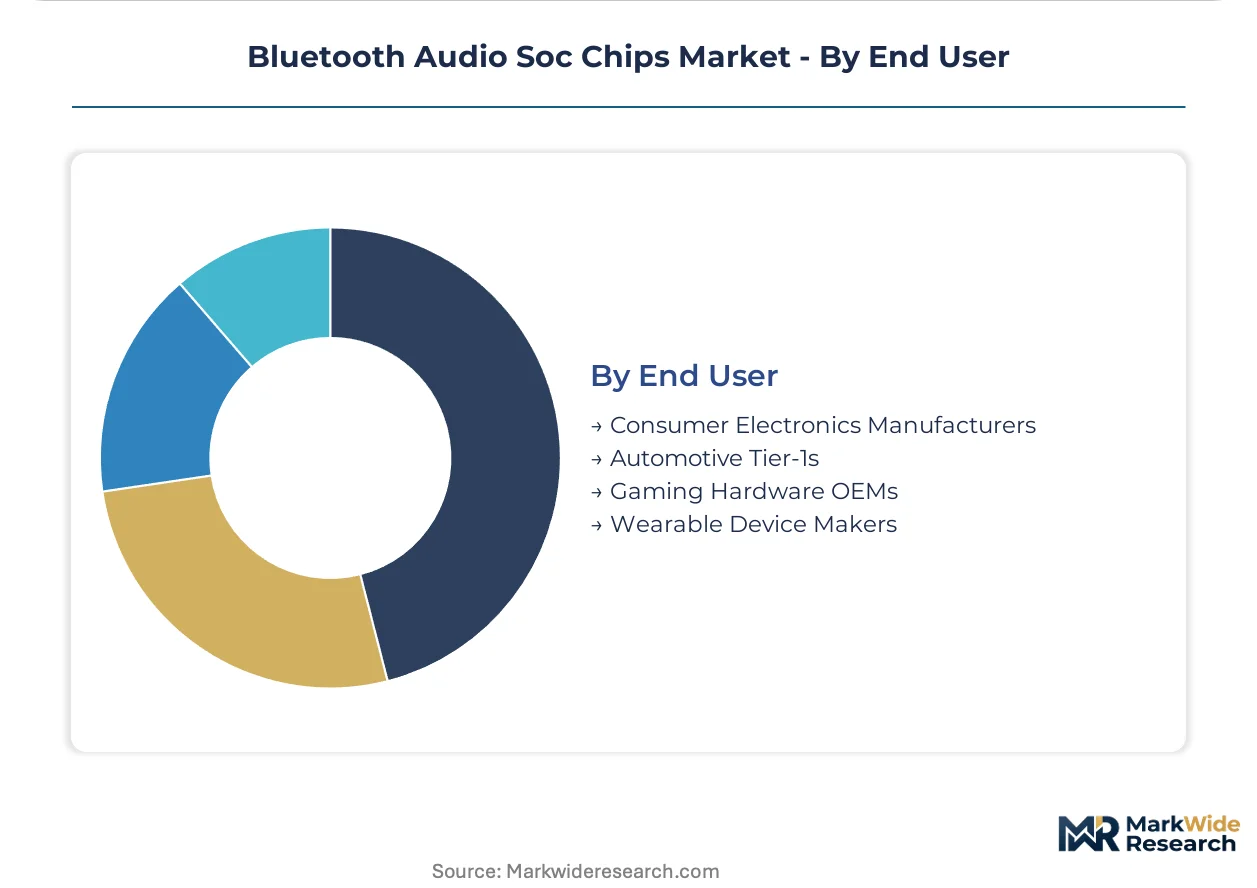
End User:
Procurement scale and technical support requirements separate high-volume contract manufacturers from specialized integrators.
- Consumer Electronics Manufacturers:Annual smartphone and accessory refresh cycles generate the largest volume commitments, negotiating die costs at 40nm through 12nm nodes across foundry relationships.
- Wearable Device Makers:Ultra-low power budgets and miniaturization requirements favor specialized BLE SoC vendors with dedicated application engineering support.
- Automotive Tier-1s:AEC-Q100 qualification and 15-year supply guarantees dominate supplier selection criteria.
- Gaming Hardware OEMs:Low-latency performance specifications and custom firmware requirements drive direct silicon vendor relationships.
Consumer Electronics Manufacturers command the highest volume leverage. Wearable Device Makers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless headphone brands concentrate procurement decisions in Shenzhen's electronics manufacturing corridor, while regulatory divergence across major economies fragments certification requirements for Bluetooth audio SoC vendors.
United States
Consumer electronics OEMs in California and Texas drive volume for TWS earbud platforms with active noise cancellation. FCC Part 15 rules restrict out-of-band emissions for 2.4 GHz devices, compelling RF front-end redesigns. Austin and San Diego host design centers where vendors calibrate shielding specifications for domestic certification.
China
MIIT radio-frequency certification rules tightened transmit-power limits for unlicensed spectrum devices, favoring integrated SoC vendors with in-house RF calibration. The Pearl River Delta manufacturing cluster in Shenzhen accelerates design-to-volume timelines for global consumer brands. Local foundry partnerships at 22nm and 12nm nodes secure wafer allocation for mid-tier silicon.
Germany
ETSI EN 300 328 mandates adaptive frequency hopping and channel occupancy detection for European-bound products. Auracast broadcast audio pilots in Frankfurt and Munich airports create demand for LE Audio-certified SoCs with multi-language stream support. Bavaria-based automotive Tier-1s integrate Bluetooth 5.3 silicon for cabin-wide audio distribution.
South Korea
Seoul-headquartered TWS OEMs qualify neural network accelerator designs for 2024 product generations with on-device voice recognition. The national radio regulator enforces spurious emission limits aligned with ETSI frameworks. Suwon and Pangyo technology corridors concentrate firmware development for spatial audio processing.
India
The PLI scheme for electronics manufacturing draws SoC vendors to establish local technical support centers in Karnataka and Tamil Nadu. BIS certification requirements for wireless devices extend product launch timelines by three to four months. Bengaluru and Chennai host reference design facilities serving domestic mobile phone assemblers.
Bluetooth Audio Soc Chips Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier codec licensors commanding margin pools while integrated analog vendors capture smart speaker design wins. The vendor base concentrates around three strategic archetypes: patent-anchored premium specialists, ultra-low-power wearable-focused vendors, and broad-line analog integrators. Competitive moves center on foundry node migration partnerships and LE Audio certification acceleration to compress product launch timelines.
Within the patent-anchored tier, Qualcomm represents the premium positioning archetype through its codec portfolio. Nordic Semiconductor exemplifies the ultra-low-power specialization archetype for wearable health applications. Texas Instruments occupies a position among analog-integrated vendors targeting smart speaker OEMs with reduced external component count solutions.
| Leading Market Players |
|---|
| Nordic Semiconductor |
| Qualcomm |
| Texas Instruments |
| STMicroelectronics |
| Silicon Labs |
| Renesas |
| Realtek |
| Infineon |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Codec licensing bifurcation separates premium-tier vendors holding patent portfolios from mid-tier competitors paying royalty stacks, compressing gross margins below 35 percent for the latter while concentrating pricing power among integrated licensors with in-house DSP architectures. This divergence manifests in supply chain configurations where royalty-bearing vendors source from 40nm legacy foundry nodes to preserve die economics, while premium licensors secure 12nm wafer allocation through smartphone AP bundling relationships.
Pricing Analysis
Volume-midpoint vendors face the steepest margin compression as per-unit transactional pricing stratifies across premium, standard, and economy tiers. Price differentiation hinges on certification grade—Bluetooth SIG LE Audio qualification commands 15-20 percent premiums—and volume scale commitments from Shenzhen-based ODMs. Pricing pressure stems from foundry node migration costs as 22nm and 12nm capacity prioritizes smartphone APs. Consumer electronics manufacturers exhibit highest price sensitivity due to annual refresh cycle procurement, while automotive Tier-1s absorb premiums for AEC-Q100 qualification.
Supply Chain Analysis
Bluetooth SIG certification and MIIT radio-frequency approval gate market access for unqualified vendors, creating qualification backlogs that stretch launch timelines. Wafer fabrication concentrates in Taiwan, South Korea, and China, with TSMC and Samsung Foundry anchoring advanced node supply. Silicon feedstock draws from Japanese polysilicon suppliers and German wafer processing equipment. Single-source vulnerability sits with TSMC's 12nm capacity allocation during smartphone AP demand surges. Distribution runs through Shenzhen ODMs and EMS providers directly to consumer electronics brands, bypassing traditional component distributors for volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over RF calibration IP and foundry node access determines margin capture, with downstream winners securing captive supply through smartphone platform bundling.
For Market Incumbents: To counter foundry capacity diversion to smartphone APs, secure long-term wafer allocation agreements at 22nm and 12nm nodes through platform bundling with consumer electronics OEMs. Accelerate in-house RF calibration IP development to reduce reliance on discrete PA and LNA components that inflate BOM complexity. Prioritize LE Audio certification pipeline investment to compress four-to-six month Bluetooth SIG qualification queues.
For New Entrants and Emerging Players: Begin with Auracast broadcast audio deployments in German and French transit infrastructure, where multi-language stream support requirements create specification gaps incumbent vendors have underinvested in. Target wearable health convergence applications—continuous glucose monitors and pulse oximetry patches—where Nordic Semiconductor's specialization leaves room for bio-sensing front-end integration plays. Pursue direct-to-consumer audio brands on TikTok-native commerce channels that bypass incumbent retail margin structures.
For Investors and Strategic Acquirers: Re-rating potential sits with analog-integrated vendors possessing smart speaker design wins given far-field voice capture convergence and multi-room synchronization demand. Long-term viability favors vendors with backward-compatible firmware stacks spanning Classic Bluetooth and LE Audio protocols. Watch LE Audio certification velocity as the inflection indicator—vendors compressing Bluetooth SIG qualification timelines by 30 percent or more will capture 2024-2025 TWS platform design wins.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Node Migration Partnership | 12nm wafer allocation through TSMC or Samsung Foundry secures die cost compression for dual-mode architectures. |
| LE Audio Certification Acceleration | Bluetooth SIG qualification pipeline investment compresses Auracast and LC3 codec implementation timelines. |
| RF Front-End Integration | In-house PA and LNA calibration reduces discrete component count and BOM complexity for TWS OEMs. |
| Neural Network Accelerator Embedding | On-chip NPU integration for keyword spotting captures South Korean and Taiwanese TWS platform qualifications. |
| India Technical Support Center | Karnataka and Tamil Nadu facilities serve PLI scheme mobile phone assemblers with localized reference designs. |
Research Methodology
Document review covered Bluetooth SIG certification databases, MIIT radio-frequency filing records, and foundry capacity utilization disclosures, complemented by interviews with SoC vendor product managers, Shenzhen ODM procurement directors, and RF validation engineers. Secondary validation drew from FCC Part 15 equipment authorization filings, ETSI EN 300 328 compliance declarations, and TSMC investor materials. Bottom-up triangulation across foundry wafer allocation estimates and top-down reconciliation against TWS platform shipment data anchored volume and value outputs.
Unit and revenue projections across the analysis window reflect segmentation by process node, protocol generation, and end-use application, with CAGRs derived from foundry node adoption curves and LE Audio certification velocity. Modeled inputs included Bluetooth 5.3 penetration rates in new designs, Auracast pilot deployment timelines in German transit infrastructure, and MIIT transmit-power compliance cost absorption by integrated versus discrete vendors.
Foundry capacity reallocation to smartphone APs, LE Audio certification queue extensions, and MIIT regulatory tightening are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in TSMC or Samsung Foundry Bluetooth audio SoC wafer allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
I2C Bus Market