
 Flexible Screens Market | 2026-2036
Flexible Screens Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Screens Market Analysis
Multi-source procurement from dedicated display foundries is repositioning how consumer electronics brands secure flexible panel supply. Samsung Display Co. Ltd. leverages captive vertical integration to dominate premium foldable shipments for affiliated handset divisions. BOE Technology Group Co. Ltd. sustains aggressive capacity builds in Chengdu and Chongqing to anchor Chinese OEM supply. LG Display Co. Ltd. competes through automotive-qualified flexible OLED lines targeting curved cockpit displays.
Flexible screens are electroluminescent or liquid-crystal displays fabricated on polymer substrates such as polyimide, enabling bend radii below 5 millimeters for commercial devices. They replace rigid glass in applications requiring conformal mounting, reduced weight, or mechanical durability against repeated deformation. OLED product types command the dominant value share due to superior contrast ratios and simpler encapsulation requirements for curved form factors. Rollable technology variants within the technology dimension represent the fastest-expanding segment, though foldable implementations currently occupy the largest installed base and margin pool across smartphone applications.
RoHS and REACH compliance in Europe restrict hazardous substances in display manufacturing, while CE marking mandates electromagnetic compatibility for consumer electronics incorporating flexible panels. South Korea's KOSHA standards and China's GB/T display quality specifications shape product certification requirements for regional market access. Stakeholders must monitor substrate material cost curves and deposition equipment lead times as determinants of capacity deployment timing.
Market Dynamics
Display substrate chemistry is pivoting from rigid glass to polyimide films, compressing manufacturing timelines while demanding entirely new encapsulation and deposition equipment footprints across panel fabrication facilities.
Growth Catalysts
- Rollable form factors:Automotive OEMs are specifying curved cockpit displays for premium vehicle lines, creating pull-through demand for polyimide-based OLED panels with sub-5mm bend radii.
- South Korea's industrial policy:The Ministry of Trade, Industry and Energy has directed subsidy flows into domestic OLED supply chains, accelerating captive production capacity for affiliated handset divisions.
- REACH substance restrictions:European RoHS and REACH compliance mandates are filtering hazardous materials from display manufacturing, advantaging polymer substrate producers with certified clean chemistries.
Market Restraints
- Deposition equipment lead times:Vacuum thermal evaporation and inkjet printing systems for flexible OLED fabrication carry 18-24 month delivery windows, constraining capacity deployment velocity.
- Substrate cost volatility:High-purity polyimide film pricing fluctuates with petrochemical feedstock markets, compressing margin predictability for panel makers at scale.
- Encapsulation complexity:Multi-layer barrier films against oxygen and moisture ingress add processing steps that rigid glass displays eliminate entirely.
Strategic Opportunities
- Chinese domestic handset brands:BOE Technology and Visionox are expanding Chengdu and Hefei capacity to serve Huawei, Xiaomi, and OPPO procurement programs with localized supply.
- Medical wearable integration:Conformal displays for continuous glucose monitors and cardiac patches represent an underpenetrated application with distinct certification pathways.
- GB/T display quality alignment:China's national standardization push creates regulatory tailwind for domestic panel makers achieving certified brightness and color accuracy benchmarks.
Industry Challenges
- Thin-film transistor engineering:Low-temperature polysilicon and oxide semiconductor backplane fabrication requires rare process engineering talent concentrated in South Korea and Taiwan.
- Automotive qualification timelines:AEC-Q100 and OEM-specific reliability testing extends product validation to 36-48 months, delaying revenue recognition for new display lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Screens Market |
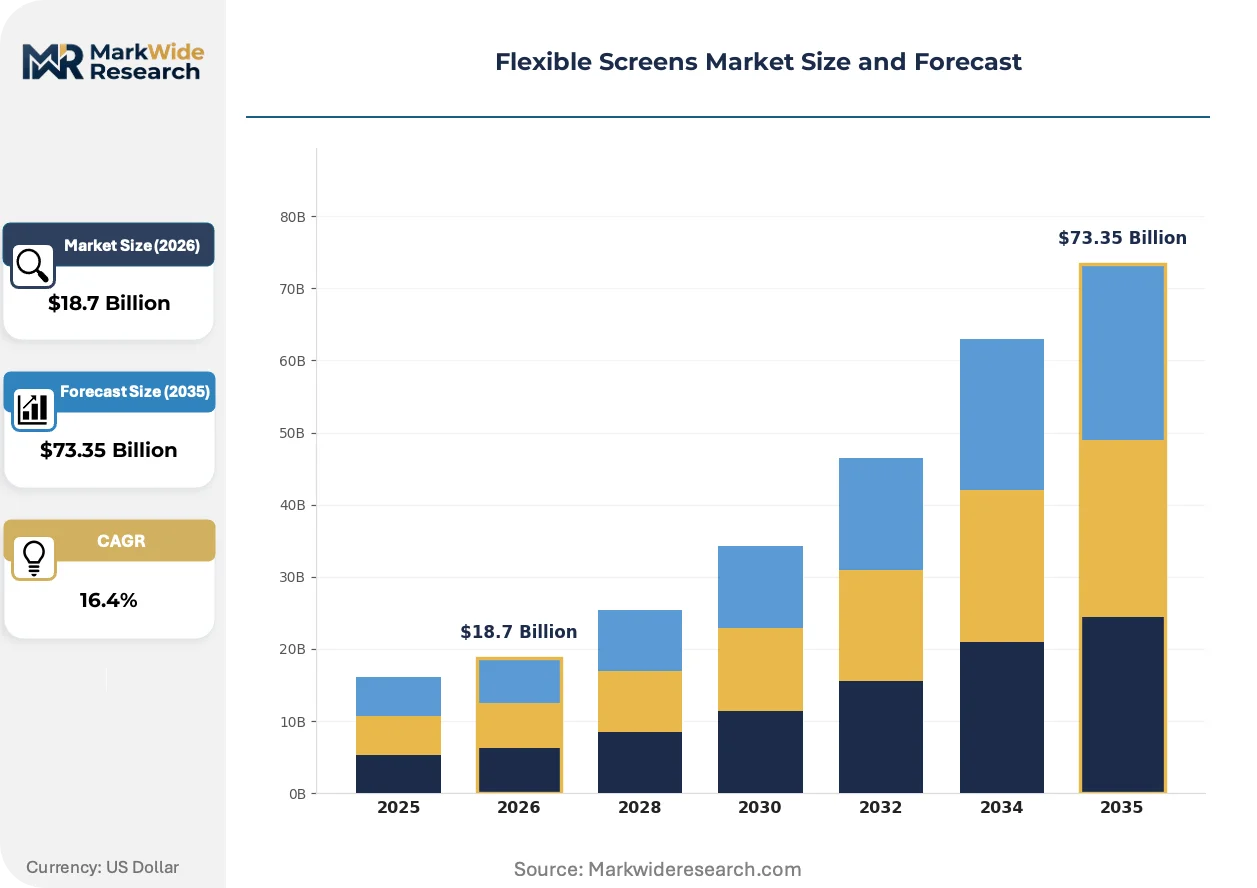
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LCD, E Ink, MicroLED End User: Smartphones, Tablets, Laptops, Wearables Application: Consumer Electronics, Automotive Displays, Wearable Tech, Advertising Technology: Touchscreen, Foldable, Rollable, Transparent |
| Companies Covered | Samsung Display Co. Ltd., LG Display Co. Ltd., BOE Technology Group Co. Ltd., Royole Corporation, AU Optronics Corp., Sharp Corporation, Japan Display Inc., Visionox Co. Ltd., TCL China Star Optoelectronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Screens Market Emerging Trajectories
Hybrid manufacturing processes are collapsing the boundary between semiconductor precision and roll-to-roll polymer processing, enabling substrate formats that were technically infeasible five years ago.
Ultra-thin glass lamination is converging with polyimide substrates to create hybrid barrier structures. Samsung Display has deployed this architecture for its latest foldable handset panels, achieving scratch resistance comparable to conventional Gorilla Glass while maintaining sub-3mm bend capability. The structural consequence is convergence with legacy cover glass supply chains, pulling Corning and Schott into flexible ecosystem partnerships previously dominated by chemical polymer suppliers.
Europe's Ecodesign for Sustainable Products Regulation is mandating repairability scoring and recycled content disclosure for consumer electronics incorporating displays. Panel makers must now document substrate material provenance and end-of-life disassembly protocols to maintain CE marking eligibility. Smartphone OEMs with European distribution exposure are responding by specifying modular display assemblies that separate the flexible panel from protective housing.
Brand procurement teams are consolidating supplier relationships around dedicated display foundries with captive backend integration. Chinese handset makers have moved from spot-market purchasing to multi-year volume commitments with BOE and TCL CSOT, exchanging forecast visibility for capacity reservation and priority allocation during supply constraints. This concentration is most visible in Guangdong province, where OPPO, vivo, and Xiaomi maintain engineering co-location with panel development centers.
Flexible Screens Market Segmentation
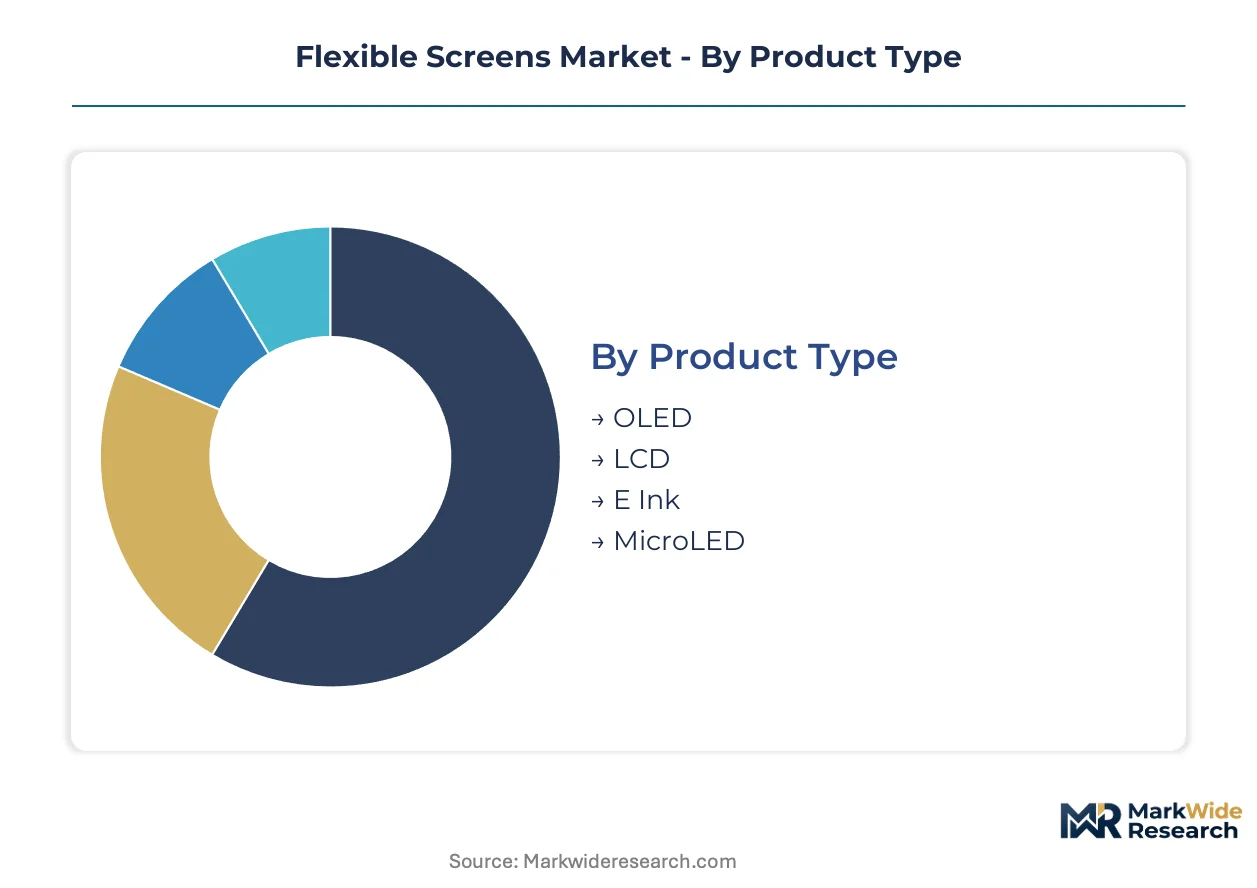
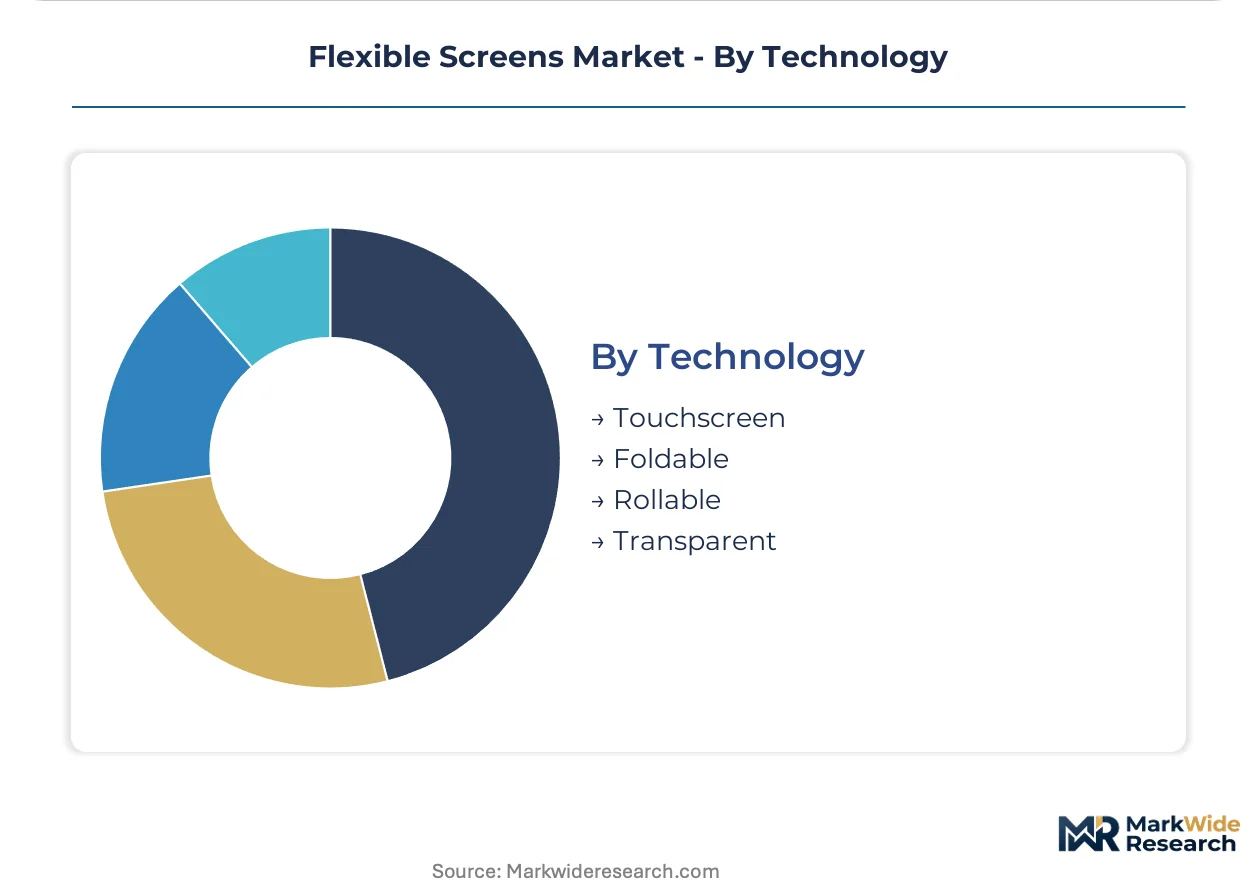
Flexible screen segmentation reveals divergent capital requirements across substrate technologies and form factors. Each dimension carries distinct equipment footprints, qualification timelines, and margin structures that shape how panel makers allocate fabrication capacity.
Product Type:
Capital intensity varies sharply across display chemistries, with organic semiconductor deposition demanding the heaviest upfront equipment investment.
- OLED:Organic light-emitting diode stacks require vacuum thermal evaporation chambers and precision shadow masks for RGB pixel patterning. Samsung Display and LG Display have concentrated multi-billion dollar investments in Gen 6 and Gen 8.5 OLED lines across South Korea, where Ministry of Trade, Industry and Energy subsidies offset equipment depreciation cycles.
- LCD:Liquid crystal displays on polyimide substrates leverage existing TFT-LCD infrastructure with modified cell assembly processes. Chinese panel makers in Guangdong province are repurposing legacy Gen 8.5 fabs for flexible LCD production to serve cost-sensitive tablet and automotive applications.
- E Ink:Electrophoretic displays utilize microcapsule deposition on plastic substrates with minimal encapsulation requirements.
- MicroLED:Chiplet transfer and mass repair equipment for microLED on flexible carriers remains prohibitively expensive for most panel makers.
OLED absorbs the bulk of installed capacity; MicroLED is expanding most quickly among emerging chemistries.
End User:
Customer scale and qualification rigor create tiered margin profiles across device categories.
- Smartphones:Foldable handsets from Samsung Electronics and Chinese OEMs command premium panel pricing due to sub-5mm bend radius specifications and million-unit annual procurement volumes. BOE Technology and Visionox have dedicated Chengdu and Hefei lines to capture this demand.
- Tablets:Larger active areas strain yield rates for flexible substrates, constraining supply to Apple and select Android brands with validated supply chains.
- Laptops:PC OEMs specify hybrid cover glass-polyimide laminates for convertible form factors.
- Wearables:Smartwatch displays prioritize power efficiency and conformal mounting over resolution.
Smartphone procurement dominates current fab loading; wearable specifications are diversifying fastest as medical applications emerge.
Application:
End-use environments dictate barrier film performance and reliability testing intensity.
- Consumer Electronics:Handset and tablet displays face the most demanding cost-performance tradeoffs, with Chinese brands driving specifications toward thinner substrates and narrower bezels.
- Automotive Displays:Curved cockpit implementations from German and Japanese OEMs require AEC-Q100 qualification and operational temperature ranges spanning -40°C to 85°C.
- Wearable Tech:Continuous glucose monitors and cardiac patches demand biocompatible encapsulation.
- Advertising:Digital signage rollables prioritize luminance uniformity over pixel density.
Consumer electronics channels the greatest panel volume; automotive qualification is lengthening fastest as safety-critical standards tighten.
Technology:
Mechanical deformation capability separates manufacturing complexity tiers.
- Foldable:Hinge-compatible panels with sub-3mm bend radii require neutral plane engineering and crease-resistant cover layers. Samsung Display has shipped over twenty million units annually through vertical integration with affiliated handset divisions.
- Rollable:Cylindrical form factors enable television and signage applications with theoretically infinite extension ratios. LG Display has demonstrated 65-inch rollable OLED prototypes using sliding backplane architectures.
- Touchscreen:Capacitive sensor integration on curved surfaces demands transparent conductive oxide patterning.
- Transparent:See-through displays for automotive HUD and retail applications sacrifice aperture ratio for optical clarity.
Foldable implementations retain the largest installed base; rollable form factors are gaining share fastest as deposition equipment scales to larger substrate formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity polyimide film production clusters in South Korea, Japan, and eastern China anchor flexible screen manufacturing geography. These feedstock localities concentrate deposition equipment, encapsulation chemistry expertise, and handset OEM procurement offices within tight radius.
South Korea
Foldable smartphone demand from Samsung Electronics and LG Electronics pulls OLED panel procurement through domestic supply chains. The Ministry of Trade, Industry and Energy channels subsidy flows into Gen 6 and Gen 8.5 deposition lines. Gyeonggi-do province hosts Samsung Display's Tangjeong complex, where captive vertical integration binds panel fabrication to handset assembly.
China
Huawei, Xiaomi, and OPPO procurement programs drive capacity expansion in Chengdu, Chongqing, and Hefei. MIIT's GB/T display quality specifications shape certification requirements for domestic market access. Guangdong province concentrates TCL CSOT and Visionox engineering co-location with handset brand development centers.
Japan
Automotive cockpit display specifications from Toyota and Honda create demand for curved OLED panels with AEC-Q100 qualification. METI's technology roadmaps coordinate consortia around low-temperature polysilicon backplane engineering. Kyushu region hosts Sharp Corporation and Japan Display Inc. fabrication lines serving both consumer and automotive qualified supply.
United States
Apple's procurement specifications for foldable tablet and laptop displays influence substrate thickness and bend radius requirements. FCC electromagnetic compatibility mandates govern consumer electronics incorporating flexible panels. California's Bay Area concentrates display startup engineering talent and venture capital deployment for microLED transfer technology.
Germany
BMW and Mercedes-Benz curved cockpit specifications drive automotive OLED qualification timelines. REACH substance restrictions and CE marking requirements filter hazardous materials from display manufacturing destined for European distribution. Baden-Württemberg hosts Bosch and Continental engineering centers specifying display integration for instrument clusters.
Flexible Screens Market Vendor Landscape
Global majors compete with regional champions across substrate chemistry and deposition equipment access. The vendor base separates into three tiers: Korean and Japanese incumbents with captive handset relationships, Chinese state-supported capacity builders, and specialized automotive-qualified suppliers. Strategic archetypes include vertically integrated electronics conglomerates, government-backed national champions, and automotive-focused display specialists. Competitive moves concentrate on multi-year volume commitments exchanged for capacity reservation, and hybrid barrier technology partnerships pulling glass suppliers into polymer ecosystems.
Among Korean incumbents, Samsung Display Co. Ltd. and LG Display Co. Ltd. occupy positions defined by captive supply to affiliated handset divisions and automotive qualification expertise respectively. BOE Technology Group Co. Ltd. represents the state-backed capacity builder archetype, with fabrication presence in Chengdu and Chongqing serving Chinese domestic OEM procurement programs. These three companies exemplify how geographic feedstock access and government industrial policy combine to determine competitive positioning in flexible panel supply.
| Leading Market Players |
|---|
| Samsung Display Co. Ltd. |
| LG Display Co. Ltd. |
| BOE Technology Group Co. Ltd. |
| Royole Corporation |
| AU Optronics Corp. |
| Sharp Corporation |
| Japan Display Inc. |
| Visionox Co. Ltd. |
| TCL China Star Optoelectronics Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
High-purity polyimide film spot prices in Asian petrochemical markets cascade through three distinct pricing tiers for flexible OLED panels, compressing margins for non-integrated fabricators while rewarding captive substrate producers with cost pass-through advantages.
Pricing Analysis
Warranty bundling separates premium panel tiers from standard offerings, with automotive-qualified OLED lines commanding extended coverage against pixel degradation and hinge fatigue. Pricing stratifies across automotive-certified, consumer foldable, and industrial-grade tiers based on AEC-Q100 qualification status and volume commitment scale. Cost compression in consumer-grade segments intensifies as Chinese OEMs consolidate procurement around BOE and Visionox multi-year contracts. Price-sensitive smartphone brands drive the steepest discount negotiations, while German and Japanese automotive OEMs absorb premium pricing for reliability-tested cockpit displays.
Supply Chain Analysis
AEC-Q100 and OEM-specific reliability certifications gate entry for automotive display supply, filtering panel makers to Samsung Display, LG Display, and Japan Display Inc. Production concentrates in South Korea, China, and Japan where polyimide substrate manufacturing clusters with deposition equipment vendors. Raw material dependencies include high-purity polyimide films, vacuum thermal evaporation chambers, and precision shadow masks. Single-source vulnerability runs through Japanese and Korean equipment vendors for low-temperature polysilicon backplane tools. Distribution runs through dedicated display foundries with captive backend integration, bypassing spot markets for multi-year volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where substrate cost control and deposition equipment access determine competitive survival, with panel makers pursuing backward integration into polyimide film production to escape petrochemical feedstock volatility.
For Market Incumbents: Extend certification moats by accelerating AEC-Q100 qualification timelines for automotive curved cockpit lines before Chinese capacity builders achieve comparable reliability benchmarks. Deepen substrate integration through captive polyimide film production or exclusive supply agreements with Korean and Japanese chemical suppliers. Samsung Display and LG Display must defend automotive positioning against BOE's Chengdu expansion by leveraging existing OEM validation relationships with BMW and Mercedes-Benz engineering centers. For New Entrants and Emerging Players: MicroLED transfer technology offers a technology-first wedge into medical wearable displays where biocompatible encapsulation requirements and lower volume thresholds reduce capital barriers versus smartphone panel competition. Target continuous glucose monitor and cardiac patch applications with conformal display specifications that bypass Samsung's foldable handset dominance. Pursue regulatory-first go-to-market strategies securing FDA and CE marking for biocompatible flexible displays before scaling manufacturing capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor automotive-qualified display specialists in Japan and South Korea facing temporary handset demand softness but holding irreplaceable AEC-Q100 validation expertise. Long-term viability hinges on five-to-ten year positioning for rollable television and curved cockpit inflections rather than near-term foldable smartphone share. Monitor BOE's Hefei and Chengdu utilization rates as the signal indicating Chinese oversupply pressure and incumbent margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polyimide Film Integration | Backward integration into substrate production insulates Samsung Display from petrochemical price swings. |
| Automotive Qualification Acceleration | AEC-Q100 certification for LG Display enables Mercedes-Benz curved cockpit procurement programs. |
| Medical Wearable Regulatory Pathway | FDA submission for biocompatible encapsulation opens cardiac patch display revenue streams. |
| Rollable Deposition Equipment Scale-Up | Gen 8.5 line expansion at BOE Chengdu targets LG Display's television rollable technology lead. |
| Hybrid Barrier Technology Partnership | Corning ultra-thin glass lamination with Samsung Display merges scratch resistance with sub-3mm bend capability. |
Methodological Framework
Multi-period observation of deposition equipment lead times, polyimide film pricing indices, and panel maker capacity utilization anchored the trend analysis, supplemented by interviews with OLED fabrication engineers, automotive display procurement managers at German and Japanese OEMs, smartphone supply chain directors at Chinese handset brands, and regulatory affairs specialists navigating REACH and GB/T compliance. Secondary validation drew from MIIT capacity disclosure filings, Korean Ministry of Trade subsidy announcements, SEC 10-K equipment depreciation disclosures, and customs data tracking vacuum thermal evaporation chamber imports. Bottom-up fab capacity modeling triangulated against top-down smartphone and automotive display demand forecasts.
Input-output matrices mapped polyimide substrate supply through encapsulation chemistry to finished panel output across the projection horizon, with segmentation dimensions spanning OLED versus LCD chemistry, foldable versus rollable mechanical architecture, and consumer electronics versus automotive versus medical end-use environments. CAGRs derived from equipment depreciation cycles, substrate cost curve trajectories, and replacement demand modeling for existing foldable handset installed base. Industry-specific forecast inputs included low-temperature polysilicon backplane yield improvement rates and AEC-Q100 qualification timeline compression potential.
Several conditions sit outside the modeled scope, including abrupt trade restriction imposition on Korean or Japanese equipment exports, breakthrough microLED transfer technology achieving commercial viability ahead of deposition equipment scale constraints, and automotive OEM platform cancellations delaying curved cockpit deployment. Forecasts reflect documented assumptions regarding substrate material cost stabilization and deposition equipment delivery normalization. A model refresh is warranted upon material change in Chinese domestic handset procurement volume commitments or Korean industrial policy subsidy recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Collaboration Display Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Light Field Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Touch and Display Integration IC for Tablet Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
4K VR Displays Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Global Display Panel Market
Display Technologies
Global Monochrome Display Market