
 Global Projector Market | 2026-2036
Global Projector Market Size, Share, and Industry Trends Forecast 2026-2036
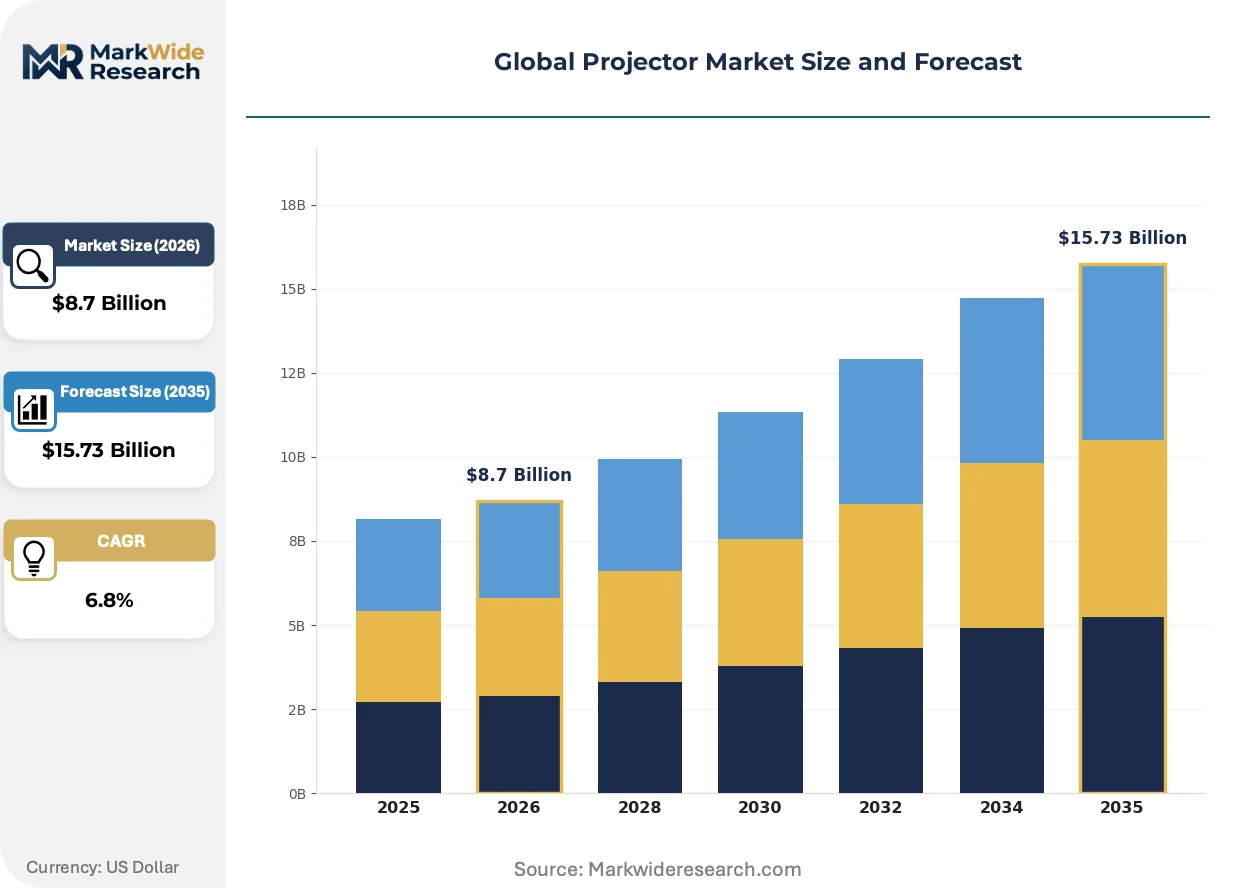
Global Projector Market Outlook
A wide capability gap in in-house light-source fabrication is rotating strategic capital toward integrated component ecosystems. Seiko Epson Corporation leverages its proprietary 3LCD engine architecture to sustain margin control across education and enterprise verticals. Sony Group Corporation anchors its position through premium LCoS cinema and home theater platforms. Delta Electronics Inc. competes aggressively in the laser-phosphor segment for large-venue installations across Asia-Pacific.
A projector is an optoelectronic display device that modulates light through digital micromirror arrays, liquid crystal panels, or reflective silicon substrates to project magnified images onto external surfaces, typically operating between 2,000 and 10,000 lumens for commercial environments. Its primary purpose is to enable scalable visual presentation in settings where direct-view displays prove impractical due to size or cost constraints. Portable and ultra short-throw product types are capturing disproportionate growth as hybrid work and residential entertainment reshape space constraints. DLP and LCD technologies dominate volume, though LED and laser alternatives are carving out premium tiers where operational longevity and color gamut performance command price premiums. Cinema and home theater applications concentrate the highest absolute margins, while education and business segments provide baseline volume stability.
The EU Ecodesign Directive and REACH frameworks constrain mercury-lamp architectures and mandate recyclable material thresholds, compelling manufacturers to accelerate solid-state light-source transitions. Japan's METI enforces standby power limits that filter lower-efficiency imports from residential channels. China's GB standards and NMPA-equivalent certification bodies govern display safety and electromagnetic compatibility for domestic commercial deployment. Stakeholders must monitor regulatory divergence between solid-state transition timelines in Europe and Asia to avoid stranded inventory in cross-border distribution networks.
Market Dynamics
The projector market is being fundamentally restructured by the EU Ecodesign Directive's mercury-lamp phase-out mandates, which are compressing product lifecycles and forcing manufacturers to retool entire light-source supply chains toward solid-state alternatives.
Growth Catalysts
- EU Ecodesign Directive:The mercury-lamp ban is compelling rapid LED and laser transitions across European commercial installations, creating replacement demand in education and corporate verticals.
- Hybrid workspace normalization:Enterprise facilities in the United States and Japan are deploying ultra short-throw systems for flexible meeting environments, expanding addressable square footage per device.
- Laser-phosphor maturation:This solid-state architecture now delivers 20,000-hour operational lifespans without filter maintenance, reducing total cost of ownership for large-venue operators in China and South Korea.
Market Restraints
- DMD chip supply concentration:Texas Instruments' dominance in digital micromirror device fabrication creates single-source vulnerability for DLP projector assemblers worldwide.
- Rare-earth phosphor cost volatility:Cerium and europium-doped yttrium aluminum garnet prices fluctuate with Chinese export quotas, squeezing laser-phosphor module margins.
- Direct-view LED wall substitution:Fine-pitch LED displays are capturing 150-inch-plus applications in broadcast and control rooms, eroding high-lumen projector addressable market.
Strategic Opportunities
- India education digitization:The country's Smart Cities Mission and NCERT curriculum modernization are driving projector deployment in tier-2 and tier-3 municipal schools.
- Immersive entertainment convergence:Projection mapping combined with spatial audio and haptic feedback is creating premium experiential venues in Saudi Arabia and UAE.
- Japan METI standby power incentives:Subsidies for sub-0.5-watt idle consumption are accelerating solid-state adoption in residential channels previously dominated by lamp-based home theater.
Industry Challenges
- Optical engineering talent scarcity:Compound lens design and thermal management expertise for high-brightness solid-state systems is concentrated among aging specialists in Germany and Japan.
- Multi-regional certification complexity:Simultaneous FCC Part 15, CE EMC, and China CCC approvals extend product launch timelines by 8-14 months for new laser-illuminated platforms.
- Legacy AV infrastructure interoperability:Corporate and education buyers require backward compatibility with VGA and HDMI 1.4 switching matrices, constraining feature roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Projector Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Short-Throw, Ultra Short-Throw Technology: DLP, LCD, LED, LCoS Application: Education, Business, Home Theater, Cinema End User: Corporates, Schools, Households, Event Venues |
| Companies Covered | Seiko Epson Corporation, Sony Group Corporation, BenQ Corporation, Canon Inc., Panasonic Corporation, Optoma Technology Corp, ViewSonic Corporation, Delta Electronics Inc., Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Projector Market Strategic Shifts
Solid-state illumination architectures are compressing device form factors while extending operational lifespans, creating new deployment scenarios that lamp-based systems could never address.
Micro-LED and laser-diode array light engines are miniaturizing. These solid-state sources eliminate color wheels and mercury vapor arcs, enabling sub-2-kilogram portable projectors for mobile professionals. Corporate road warriors and field technicians in the United States and Germany are adopting these devices at triple-digit annual rates. The technology is miniaturizing projection from fixed-installation infrastructure to personal carry-on equipment.
REACH substance restrictions are tightening cadmium and lead thresholds in optical components and printed circuit boards. The European Chemicals Agency's 2024 candidate list expansion is forcing redesigns of phosphor wheels and solder alloys. Cinema projector manufacturers serving European exhibition chains are accelerating halide-free material qualification to avoid market exclusion.
Enterprise purchasing departments are consolidating AV procurement under facilities management rather than IT or departmental budgets. This centralization is compressing vendor lists and demanding five-year total cost of ownership guarantees with predictive maintenance analytics. The shift is most visible in North American Fortune 500 headquarters and European pharmaceutical campus rollouts.
Global Projector Market Segmentation
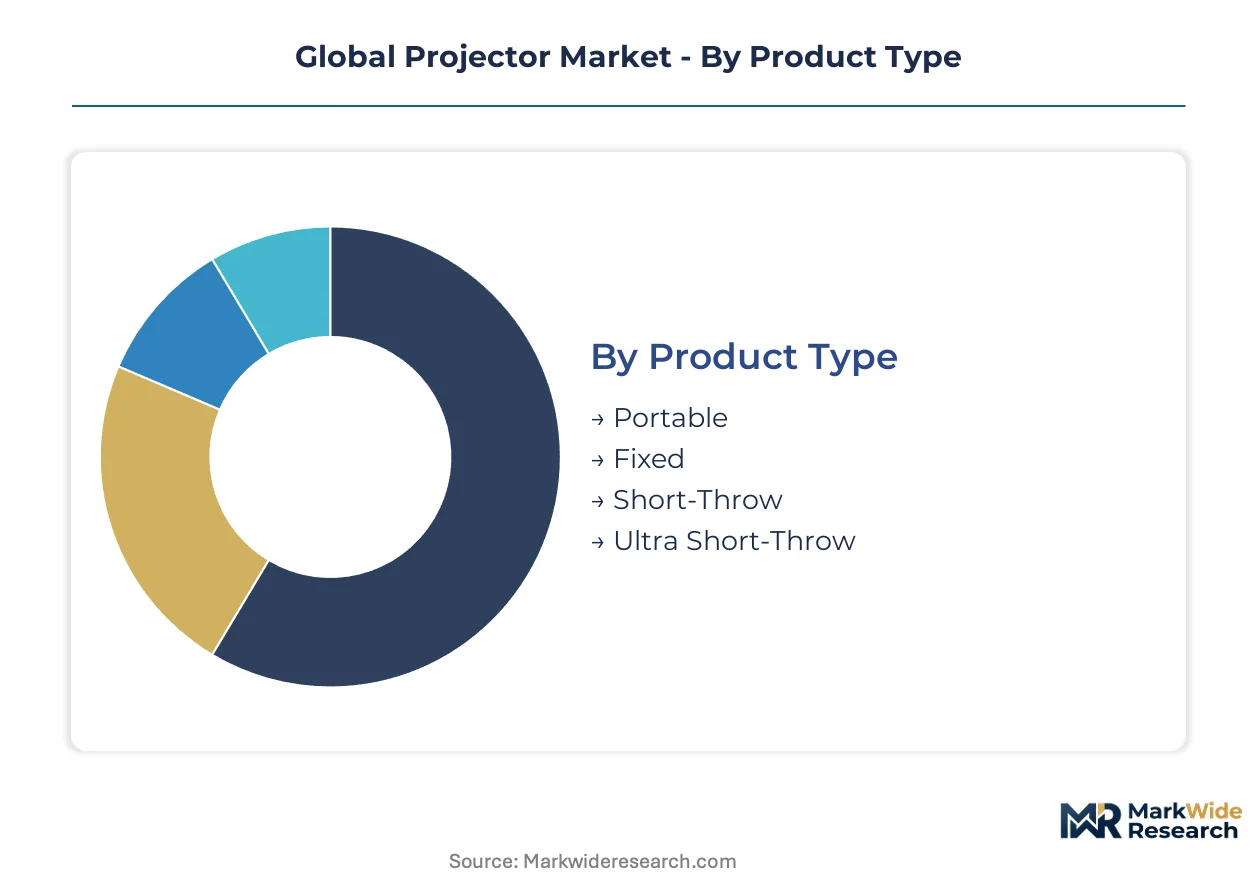
Projector segmentation reveals how regulatory timelines, workspace geometries, and content consumption patterns split demand across incompatible hardware architectures. Manufacturers must align R&D roadmaps with the diverging certification requirements and use-case specifications that govern each category.
Product Type:
EU Ecodesign Directive mercury-lamp phase-outs and Japan METI standby power limits are reshaping form-factor priorities across portable and fixed-installation categories.
- Portable:Sub-2-kilogram solid-state devices eliminate filter maintenance and mercury disposal liabilities. Mobile professionals in Germany and the United States are adopting these for client presentations and field diagnostics, though battery thermal constraints limit brightness to sub-3,000-lumen outputs.
- Fixed:Ceiling-mounted installations dominate corporate boardrooms and university lecture halls in China and South Korea. These systems prioritize 5,000-10,000-lumen laser-phosphor engines with 20,000-hour lifespans to minimize facilities management overhead.
- Short-Throw:Projection ratios between 0.4 and 0.7 enable mid-size classroom deployments without shadow interference. India's NCERT curriculum modernization is driving procurement in tier-2 municipal schools.
- Ultra Short-Throw:Sub-0.25 projection ratios position these as direct-view display substitutes for hybrid workspaces in Japan and the United States. Wall-mount designs eliminate ceiling infrastructure requirements.
Fixed installations handle the majority of throughput; portable systems are expanding most quickly on share as solid-state miniaturization accelerates.
Technology:
Cost tier differentiation separates premium cinema platforms from volume education and enterprise deployments, with light-source architecture as the primary margin determinant.
- DLP:Texas Instruments' digital micromirror devices enable high-contrast, sealed optical engines for dusty environments. The technology dominates large-venue rental fleets in Saudi Arabia and UAE event markets where rapid deployment reliability matters.
- LCD:3LCD architectures from Seiko Epson Corporation deliver color brightness parity with white brightness, critical for education applications in Japan and Germany where accurate color reproduction supports STEM visualization.
- LED:Solid-state RGB arrays eliminate color wheels and mercury arcs, enabling sub-1,000-lumen pico-projectors for residential casual viewing in South Korean apartments.
- LCoS:Liquid crystal on silicon substrates deliver cinema-grade 4K resolution with minimal pixel gap. Sony Group Corporation anchors premium home theater and commercial exhibition positions where absolute black levels command price premiums.
DLP and LCD split volume leadership; LCoS captures the steepest expansion trajectory in premium residential channels as 4K content libraries mature.
Application:
Customer type concentration varies sharply by procurement authority, with facilities management centralization favoring standardized platforms in enterprise and fragmented purchasing sustaining vendor diversity in residential.
- Education:K-12 and higher education institutions in India and China prioritize 3,000-4,000-lumen XGA and WXGA resolution for whiteboard compatibility. India's Smart Cities Mission is accelerating tier-3 school digitization.
- Business:Fortune 500 headquarters in the United States and pharmaceutical campuses in Switzerland are consolidating AV procurement under five-year total cost of ownership contracts with predictive maintenance clauses.
- Home Theater:Enthusiast segments in Japan and Germany demand HDR10 compatibility and sub-30ms input lag for gaming. Japan METI standby power subsidies are accelerating solid-state transitions in this channel.
- Cinema:Exhibition chains in Europe face REACH substance restrictions on optical components, forcing halide-free phosphor wheel qualification to avoid market exclusion.
Education handles the majority of throughput; home theater is climbing the fastest as residential entertainment budgets reallocate from commercial cinema attendance.
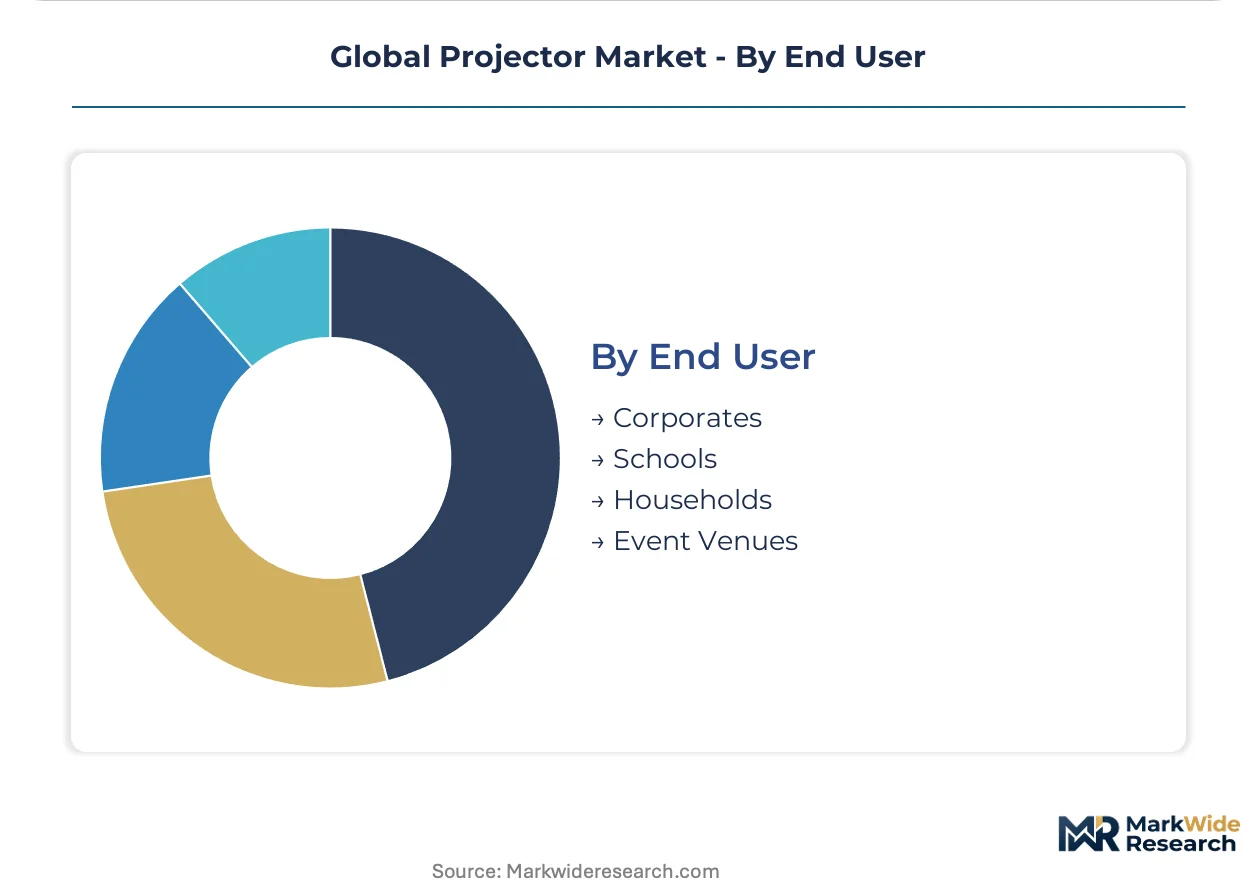
End User:
Geography determines volume concentration, with manufacturing proximity to China and South Korea supply bases influencing procurement economics for Asian institutional buyers.
- Corporates:Hybrid workspace normalization in the United States and Japan is expanding addressable square footage per device through ultra short-throw deployment in huddle rooms and phone booths.
- Schools:Municipal procurement in India and China's tier-2 cities prioritizes dust-resistant sealed optics and extended warranty terms over peak brightness specifications.
- Households:Residential buyers in Germany and South Korea favor laser-illuminated platforms for living room replacement of direct-view televisions above 85 inches.
- Event Venues:Immersive entertainment convergence in Saudi Arabia and UAE is combining projection mapping with spatial audio for premium experiential destinations.
Schools handle the majority of throughput; event venues are gaining share fastest as experiential entertainment investments accelerate in Gulf markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers command pricing leverage in laser-phosphor components, while German and Japanese buyers extract premium specifications through technical compliance requirements that filter lower-tier imports.
United States
Fortune 500 headquarters in Chicago and New York Metro are consolidating AV procurement under facilities management with five-year total cost of ownership contracts. FCC Part 15 EMC certification filters non-compliant imports from residential channels. Austin and Seattle tech campuses are deploying ultra short-throw systems for hybrid workspace normalization.
China
Tier-2 municipal schools in Sichuan and Shandong are driving volume procurement of 3,000-4,000-lumen sealed-optic systems. GB standards and NMPA-equivalent certification govern display safety for commercial deployment. Shenzhen and Suzhou manufacturing clusters concentrate laser-diode array fabrication capacity for export markets.
Germany
Pharmaceutical campuses in Bavaria and Baden-Württemberg demand predictive maintenance analytics under centralized procurement. REACH substance restrictions and EU Ecodesign Directive mercury-lamp bans accelerate solid-state transitions. Berlin-Brandenburg education authorities prioritize color-accurate 3LCD architectures for STEM visualization.
Japan
Residential buyers in Tokyo and Osaka are replacing direct-view televisions above 85 inches with laser-illuminated platforms. METI standby power subsidies for sub-0.5-watt idle consumption filter lamp-based home theater imports. Nagoya industrial clusters maintain specialized optical engineering talent for compound lens design.
India
Tier-3 municipal schools under the Smart Cities Mission and NCERT curriculum modernization are accelerating projector deployment. Central and state education budgets prioritize dust-resistant sealed optics over peak brightness specifications. Bangalore and Hyderabad technology corridors are emerging as distribution hubs for South Asian institutional procurement.
Global Projector Market Competitive Environment
Concentration sits with diversified electronics conglomerates that control captive light-source supply chains and optical engine fabrication. Market structure tilts toward tiered competition where proprietary display technologies create defendable positions in premium cinema and home theater verticals. Three archetypes dominate: integrated component ecosystem operators, premium LCoS platform specialists, and aggressive laser-phosphor challengers in large-venue installation. Competitive moves center on backward integration into phosphor wheel manufacturing and strategic patent licensing around solid-state illumination architectures.
Among Japan-based diversified electronics manufacturers, Seiko Epson Corporation and Sony Group Corporation occupy positions at opposite ends of the technology spectrum, with the former exemplifying integrated 3LCD ecosystem control and the latter anchoring premium LCoS cinema platforms. Delta Electronics Inc., a Taiwan-based power electronics conglomerate, sits within the aggressive expansion archetype for laser-phosphor large-venue systems across Asia-Pacific.
| Leading Market Players |
|---|
| Seiko Epson Corporation |
| Sony Group Corporation |
| BenQ Corporation |
| Canon Inc. |
| Panasonic Corporation |
| Optoma Technology Corp |
| ViewSonic Corporation |
| Delta Electronics Inc. |
| Sharp Corporation |
| Others |
Value Chain & Pricing Dynamics
Laser-phosphor light engines displacing mercury-arc systems are redrawing procurement geography toward China and South Korea while collapsing the historical lamp-replacement revenue streams that subsidized hardware margins. Solid-state transitions concentrate component purchasing power among buyers with direct access to Shenzhen and Suzhou fabrication clusters, compressing pricing leverage for distributors serving European and North American education channels.
Pricing Analysis
The customization-premium spread separates configured-to-order laser-phosphor installations from standard LCD education projectors. Three-tier pricing structure across premium, standard, and economy levels reflects lumen output, light-source architecture, and warranty bundling. Cost compression in entry-level sealed-optic systems intensifies because Indian municipal procurement prioritizes dust resistance over peak brightness. Education buyers in tier-2 Chinese cities exhibit highest price sensitivity; cinema exhibition chains in Europe demonstrate lowest sensitivity due to REACH compliance premiums.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Busan corridors fluctuate with container availability and semiconductor equipment backlogs. Manufacturing gravity centers on China, South Korea, and Japan for DMD chips, laser diode arrays, and precision optics. The supply chain rests on rare-earth phosphor feedstocks from Chinese processing facilities and Texas Instruments' digital micromirror monopoly. Single-source vulnerability in DMD fabrication constrains DLP assembler flexibility. Distribution runs through AV integrators and direct enterprise contracts rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized optical engineering talent for compound lens thermal management has contracted to aging specialist pools in Nagoya and Stuttgart, creating acquisition premiums for teams with solid-state illumination expertise.
For Market Incumbents: Secure captive phosphor wheel manufacturing to defend laser-phosphor margins against rare-earth cost volatility. Consolidate certification testing infrastructure across FCC Part 15, CE EMC, and China CCC to compress 8-14 month approval timelines for new platforms. Direct-view LED wall substitution in broadcast control rooms threatens high-lumen projector addressable market; counter with immersive experiential venue partnerships in Gulf markets. For New Entrants and Emerging Players: Certification fast-tracks through India's BIS streamlined procedures for education procurement open tier-3 municipal school deployment. White-space targets include dust-resistant sealed-optic systems for Indian Smart Cities Mission schools and sub-2-kilogram portable devices for German mobile professionals. Target ultra short-throw hybrid workspace applications in Japan and United States through facilities management channel partnerships rather than IT procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Taiwan-based power electronics conglomerates holding laser-phosphor large-venue positions. Five-to-ten year viability favors integrated component ecosystem operators with backward control over light-source fabrication. Watch Texas Instruments DMD supply allocation decisions as inflection indicator for DLP assembler margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Wheel Manufacturing | Captures margin from rare-earth processing and insulates against Chinese export quota volatility. |
| Multi-Regional Certification Pre-Qualification | Compresses FCC, CE EMC, and China CCC timelines to accelerate solid-state platform launches. |
| Immersive Experiential Venue Partnerships | Captures premium installation demand in Saudi Arabia and UAE projection mapping markets. |
| Optical Engineering Talent Acquisition | Addresses scarcity of compound lens thermal management expertise in Germany and Japan. |
| Facilities Management Channel Direct Contracts | Bypasses fragmented IT procurement to capture Fortune 500 five-year TCO consolidation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and component supplier disclosures. Primary interviews engaged product managers at laser-phosphor engine manufacturers, procurement directors at European exhibition chains, facilities management executives at North American Fortune 500 headquarters, and optical engineering specialists in Japanese industrial clusters. Secondary sources include EU Ecodesign Directive implementation reports, Japan METI standby power compliance databases, China GB standards documentation, and SEC filings from diversified electronics conglomerates. Bottom-up unit demand modeling triangulates against top-down value estimates.
Segmentation dimensions modeled span product type, technology architecture, application vertical, and end-user category across the projection horizon. The analytical framework incorporates light-source transition timelines, regional regulatory phase-out schedules, and workspace geometry evolution in hybrid environments. CAGRs derive from installed base replacement cycles, solid-state adoption curves, and education digitization program budgets. Industry-specific inputs include laser-diode cost learning curves and rare-earth phosphor price elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EU Ecodesign enforcement, continued China rare-earth export stability, or Texas Instruments DMD supply continuity would require recalibration. Forecasts reflect documented assumptions regarding hybrid workspace normalization velocity and immersive entertainment venue investment trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Projector Screen Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Microdisplay Market
Display Technologies
Light Field Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
Electronic Display Market
Display Technologies
Smartphone Display Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Volumetric Display Market
Display Technologies
Seven Segment Display Market
Display Technologies
Vietnam Displays Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Interferometric Modulator Display Market