
 Europe E-Paper Display Market | 2026-2036
Europe E-Paper Display Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Paper Display Market Insights
East Asian module assembly capacity is hardening into a bottleneck for European OEMs seeking faster delivery cycles. Plastic Logic GmbH leverages organic thin-film transistor expertise to differentiate its flexible display offerings for industrial wearable applications. SOLUM Europe Gmbh anchors the electronic shelf label segment through dense retail channel relationships across the DACH region. E Ink Holdings Inc. dominates upstream electrophoretic film supply, forcing downstream competitors to navigate material allocation cycles.
Europe E-Paper Display refers to reflective display panels that utilize microencapsulated charged pigments suspended in fluid, requiring power only during image transitions and achieving bi-stable states with near-zero standby consumption. These panels serve commercial applications demanding sunlight readability and extended battery autonomy in field-deployed endpoints. Flexible displays occupy the highest margin pool due to manufacturing complexity and limited qualified substrate suppliers. Black and white displays sustain volume leadership in retail and logistics tagging, while full-color electrowetting prototypes from CLEARink are redirecting R&D budgets toward next-generation signage. Digital signage applications concentrate demand in transportation hubs and quick-service restaurant chains seeking low-maintenance outdoor readability.
The EU Green Deal and REACH framework restrict hazardous substance use in electronic component manufacturing, compelling display assemblers to certify supply chains against Substances of Very High Concern thresholds. ECHA's evolving candidate list pressures pigment and encapsulant suppliers to reformulate core materials. CE marking under the Radio Equipment Directive governs wireless-enabled shelf labels and transit signage units. Stakeholders must monitor electrowetting color fidelity benchmarks against electrophoretic cost curves to time portfolio transitions.
Market Dynamics
East Asian electrophoretic film concentration is forcing European OEMs into allocation-driven procurement cycles, compressing their ability to commit to retail rollout timelines. This supply asymmetry reshapes competitive positioning across the value chain.
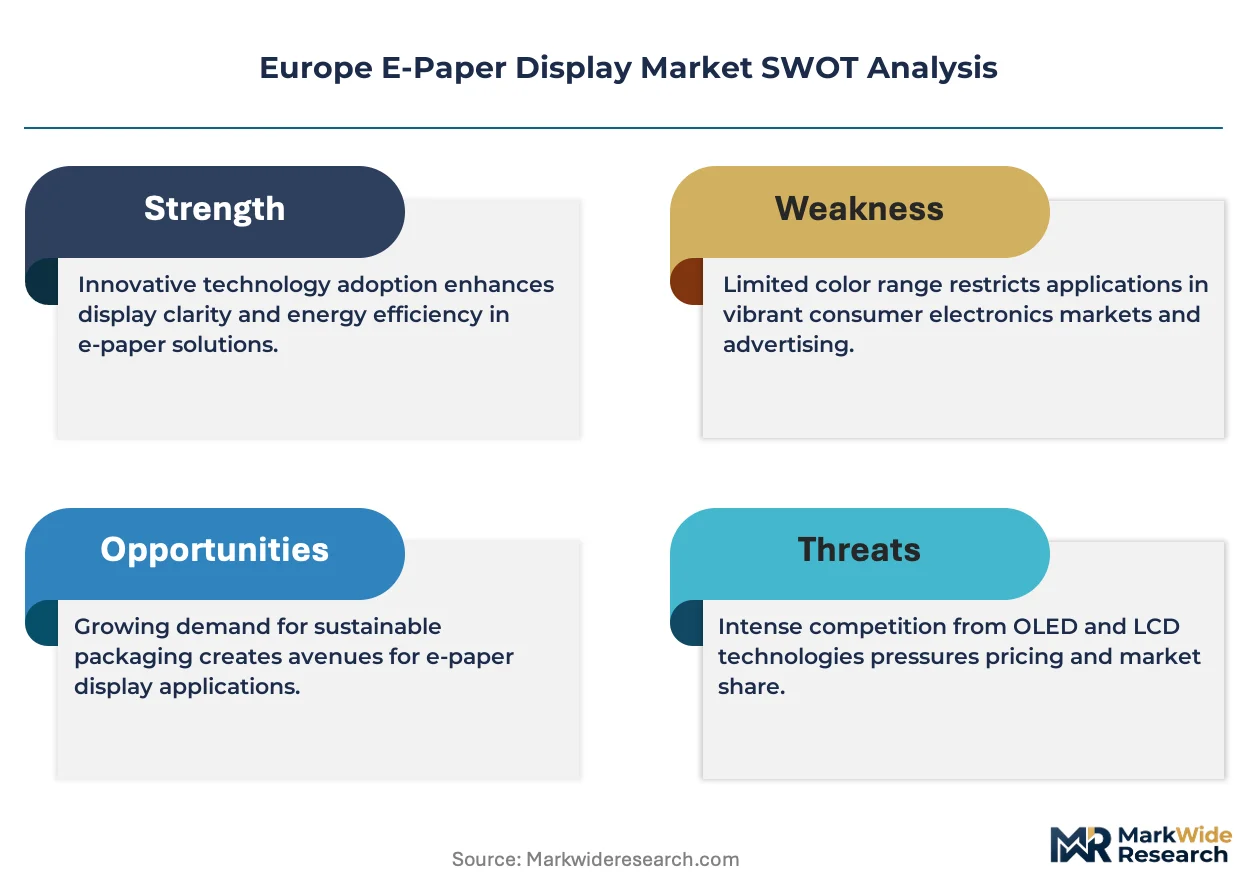
Growth Catalysts
- EU Green Deal procurement mandates:Public sector signage tenders now prioritize near-zero standby consumption, accelerating municipal adoption of bi-stable displays in transit infrastructure.
- German retail digitization:Dense electronic shelf label deployment in grocery and electronics chains sustains volume demand for monochrome panels.
- Electrowetting color fidelity advances:Laboratory prototypes achieving print-quality gamut are redirecting R&D budgets toward next-generation full-color signage applications.
Market Restraints
- Upstream film supply concentration:Single-source dependency on East Asian electrophoretic film manufacturers exposes European assemblers to allocation cycles and extended lead times.
- REACH SVHC compliance costs:ECHA's evolving candidate list forces pigment and encapsulant suppliers into continuous reformulation, elevating material qualification expenses.
- Refresh rate limitations:Electrophoretic technology's inherent latency constrains adoption in interactive or video-capable applications, capping addressable market scope.
Strategic Opportunities
- Flexible substrate penetration in wearables:Organic thin-film transistor expertise enables differentiated industrial wearable offerings with curved form factors.
- Polish and Romanian retail modernization:Underpenetrated markets in Central and Eastern Europe present whitespace for dense electronic shelf label deployment.
- CSRD-driven sustainability reporting:Corporate sustainability disclosure requirements incentivize low-power display adoption as Scope 2 reduction instruments.
Industry Challenges
- OTFT process engineering scarcity:Qualified organic semiconductor fabrication talent remains concentrated in Cambridge and Dresden, constraining flexible display scaling.
- CE marking timeline compression:Radio Equipment Directive certification for wireless-enabled shelf labels extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Paper Display Market |
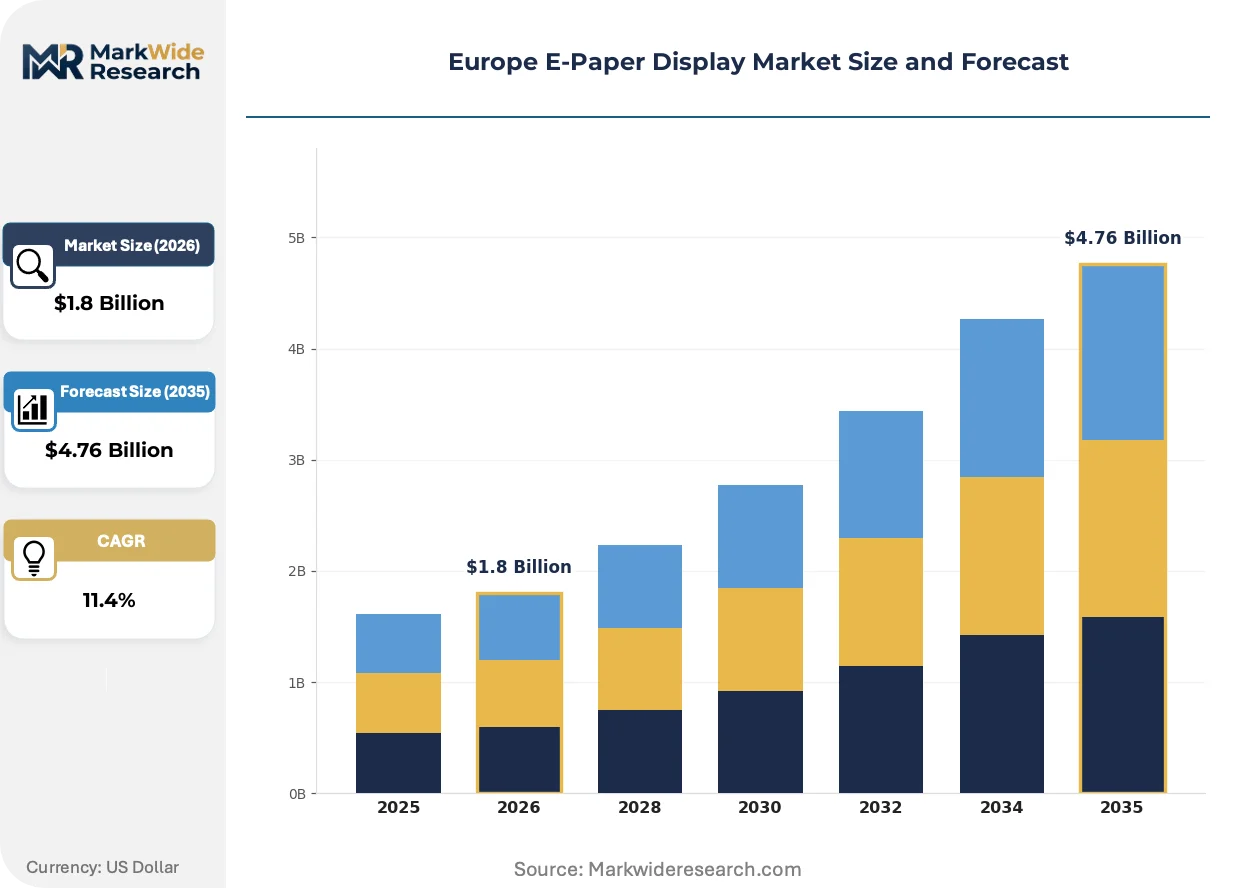
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Segmented Displays, Flexible Displays, Full-Color Displays, Black & White Displays End User: Retail, Transportation, Smart Cards, Consumer Electronics Technology: Reflective, Electrophoretic, Electrowetting, Bi-stable Application: Advertising, Inventory Management, Wearable Devices, Digital Signage |
| Companies Covered | CLEARink Displays Inc., LANCOM Systems GmbH, Plastic Logic GmbH, FlexEnable Limited, SOLUM Europe Gmbh, Pervasive Displays Inc., Visionect, SES-imagotag, E Ink Holdings Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Paper Display Market Trends and Innovations
Color fidelity breakthroughs and regulatory sustainability mandates are converging to redefine competitive differentiation in European display procurement. Technology evolution and policy frameworks now operate as intertwined selection criteria.
Electrowetting display technology is automating the transition from static monochrome signage toward full-color outdoor-readable systems. Quick-service restaurant chains and transportation authorities are piloting these panels for menu boards and passenger information displays. The technology is automating color reproduction benchmarks previously unattainable under electrophoretic constraints, compressing the performance gap with emissive alternatives.
REACH Substances of Very High Concern thresholds are tightening material specifications across the supply chain. ECHA's candidate list expansion compels pigment suppliers to substitute legacy encapsulants with compliant alternatives. Electronic shelf label manufacturers serving French and German retail chains are accelerating supply chain audits to preempt regulatory disqualification.
Retail procurement teams are consolidating vendor relationships around full-service platform providers. Legacy component sourcing through fragmented distributors is yielding to direct partnerships with module assemblers offering integrated wireless and content management capabilities. This concentration is most visible in the DACH region, where dense retail networks prioritize single-source accountability over price optimization.
Europe E-Paper Display Market Segmentation
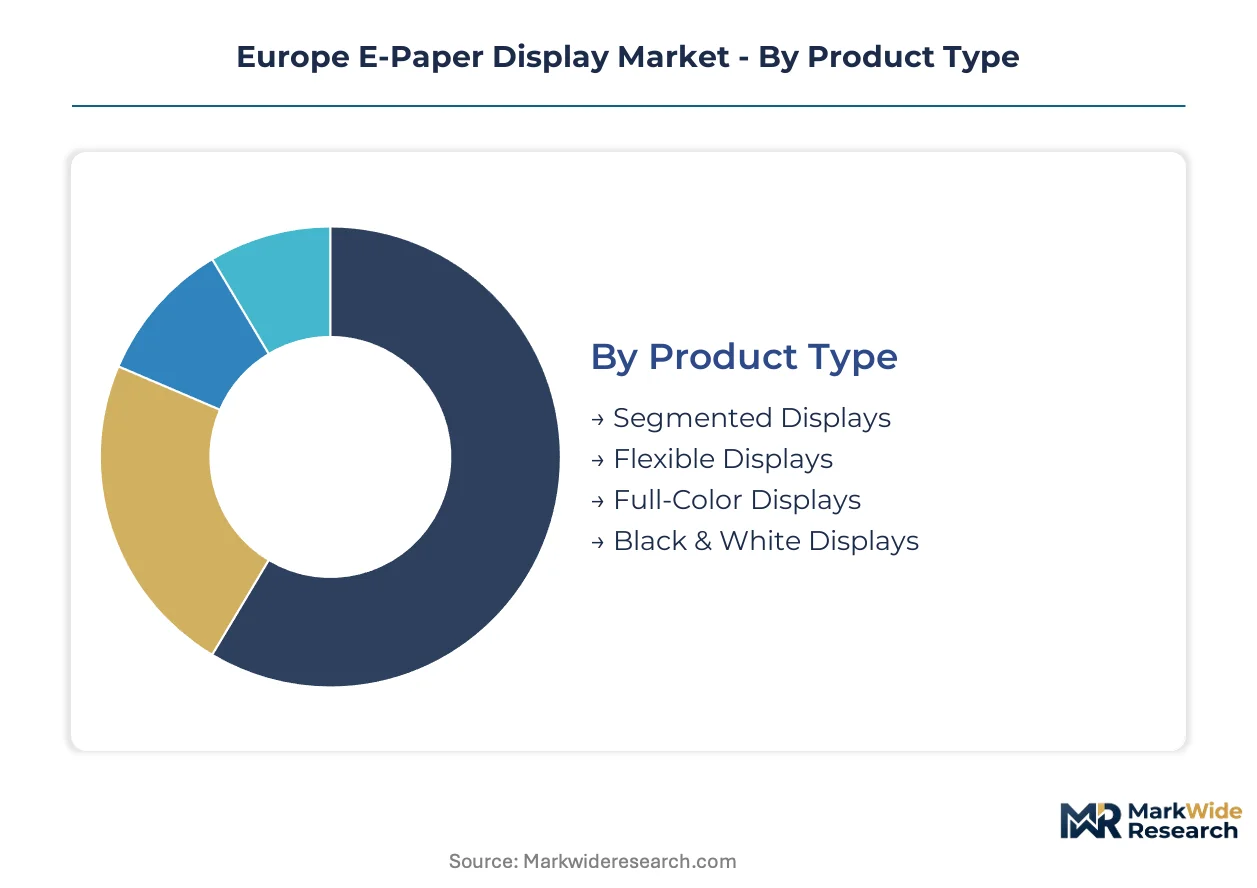
E-paper display segmentation reveals how technology maturity and integration depth shape procurement patterns across European markets. Standalone signage systems demand different specifications than embedded retail infrastructure, creating distinct competitive arenas.
Product Type:
Integration depth varies sharply across product categories, with standalone panels serving transit infrastructure while embedded modules dominate retail shelf systems.
- Black & White Displays:Electrophoretic microcapsule arrays deliver 16-level grayscale at sub-watt power draw. German grocery chains and French hypermarkets anchor volume demand through dense electronic shelf label rollouts, constrained only by East Asian film allocation cycles.
- Flexible Displays:Organic thin-film transistor backplanes on polyimide substrates enable curved form factors for industrial wearables. Dresden and Cambridge manufacturing clusters supply European OEMs seeking differentiation against rigid-panel competitors.
- Segmented Displays:Pre-patterned electrode arrays drive simple numeric indicators in smart metering and logistics tagging applications.
- Full-Color Displays:Electrowetting prototypes from CLEARink and electrophoretic Gallery systems target quick-service restaurant menu boards and transit advertising panels.
Black & White Displays lead volumes today; Flexible Displays are gaining share fastest.
End User:
Customer procurement sophistication separates volume buyers from pilot-stage adopters, with retail consolidation creating platform-level vendor relationships.
- Retail:Electronic shelf label networks across DACH region grocery and electronics chains sustain monochrome panel demand. SES-imagotag and SOLUM Europe Gmbh anchor supplier relationships through integrated wireless and content management platforms.
- Transportation:Passenger information displays at German rail hubs and Dutch transit terminals prioritize sunlight readability and near-zero standby consumption under EU Green Deal procurement mandates.
- Smart Cards:Bi-stable displays enable dynamic CVV codes and balance readouts on payment credentials without battery replacement.
- Consumer Electronics:E-readers and secondary smartphone displays remain a niche segment constrained by refresh rate limitations against LCD and OLED alternatives.
Retail commands absolute volume leadership; Transportation is climbing the fastest as municipal tenders accelerate.
Technology:
Core physics principles determine where each technology can compete, with bi-stability remaining the non-negotiable threshold for battery-constrained deployments.
- Electrophoretic:Microencapsulated charged pigment particles suspended in fluid achieve image retention without power. E Ink Holdings dominates upstream film supply, forcing European assemblers into allocation-driven procurement cycles.
- Bi-stable:Image retention without refresh current defines the fundamental value proposition for field-deployed endpoints across logistics and infrastructure applications.
- Electrowetting:Voltage-controlled surface tension modulation enables video-rate color switching. Laboratory prototypes are redirecting R&D budgets toward next-generation signage as color fidelity benchmarks improve.
- Reflective:Ambient light dependence without backlighting underpins outdoor readability claims across all outdoor signage tenders.
Electrophoretic systems anchor installed base; Electrowetting shows steepest expansion trajectory in pilot deployments.
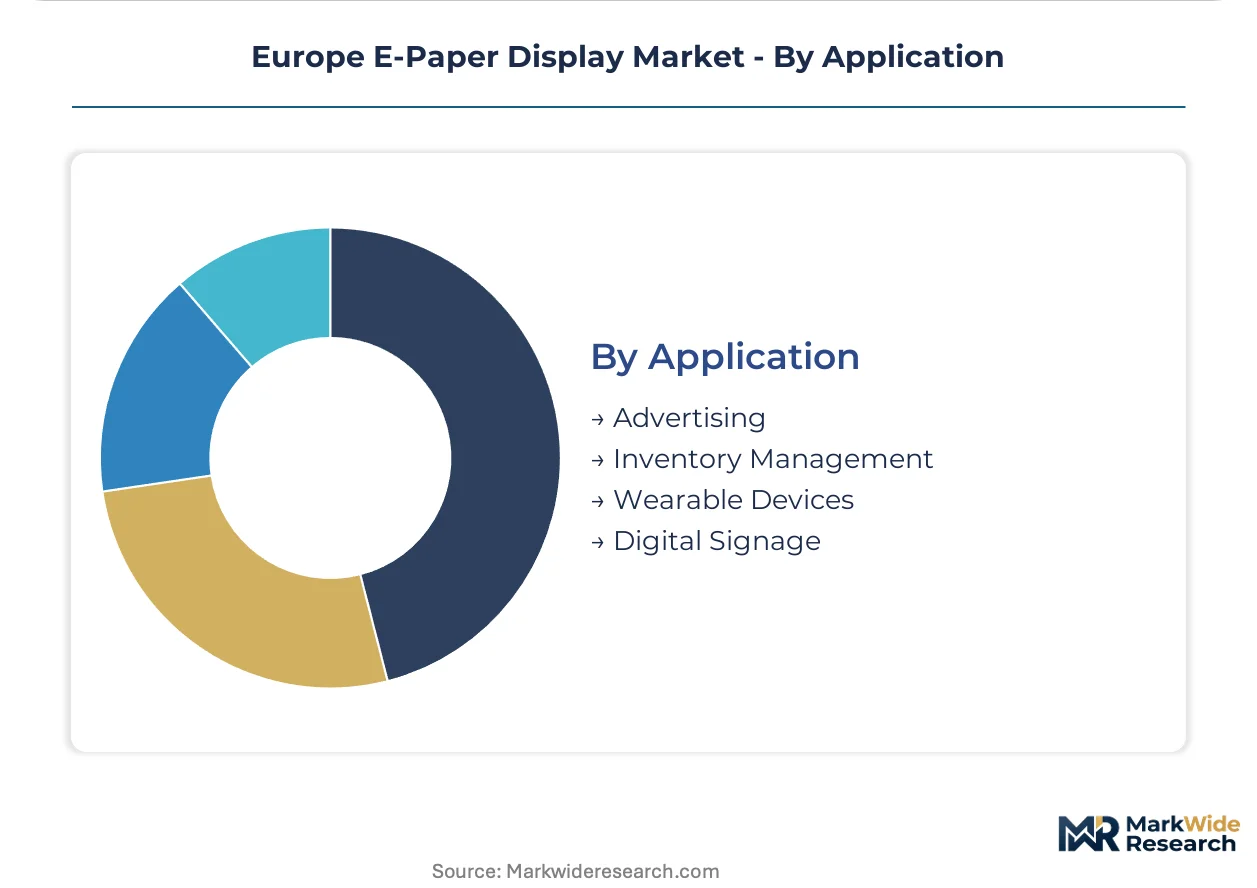
Application:
Use case requirements separate static information displays from systems demanding intermittent update cycles, with advertising applications pushing color performance boundaries.
- Digital Signage:Transit hubs and quick-service restaurant chains deploy large-format panels for passenger information and menu boards. EU Green Deal procurement mandates prioritize near-zero standby consumption in municipal tenders.
- Inventory Management:Warehouse picking systems and logistics yards leverage barcode-compatible displays for dynamic location labeling without wired power infrastructure.
- Advertising:Outdoor-readable panels compete against emissive alternatives through sunlight visibility and eliminated thermal management costs.
- Wearable Devices:Industrial smartwatches and logistics armbands exploit flexible substrate form factors for curved wrist integration.
Digital Signage leads application volumes; Inventory Management is expanding most quickly through logistics automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is driving module assembly migration toward jurisdictions with streamlined REACH compliance pathways. German and French assemblers absorb elevated certification costs while Polish and Romanian facilities capture volume production through simplified ECHA reporting thresholds.
Germany
Dense electronic shelf label networks in Rewe and MediaMarkt chains sustain monochrome panel procurement. The EU Green Deal procurement mandates prioritize near-zero standby consumption in municipal transit tenders. Dresden's organic thin-film transistor cluster supplies flexible display backplanes for industrial wearable OEMs.
France
Hypermarket digitization through integrated wireless shelf-label platforms anchors volume demand. ANSM and CNIL oversight on data-bearing retail endpoints tightens wireless certification timelines. The Paris-Saclay corridor concentrates electrowetting R&D facilities for next-generation color signage prototypes.
United Kingdom
Transport for London's passenger information display refresh programs prioritize sunlight-readable bi-stable panels. The UK's post-Brexit UKCA marking regime runs parallel to retained CE requirements, extending dual-certification burdens. Cambridge's organic semiconductor fabrication cluster supplies flexible substrate expertise to European OEMs.
Poland
Underpenetrated grocery retail chains present whitespace for dense electronic shelf label deployment. Simplified REACH SVHC reporting thresholds reduce material qualification overhead versus Western European facilities. The Wrocław-Katowice manufacturing corridor attracts module assembly investment from German supply chain partners.
Netherlands
Rotterdam and Amsterdam transit authorities pilot large-format electrowetting displays for passenger information systems. The Radio Equipment Directive's CE marking requirements govern wireless-enabled signage deployments across Dutch rail hubs. Eindhoven's high-tech systems cluster supports display driver IC design for low-power endpoints.
Europe E-Paper Display Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrowetting color fidelity and flexible substrate differentiation. The market structures around upstream film supply concentration and downstream platform integration capabilities. Three archetypes dominate: East Asian electrophoretic film suppliers, European module assemblers with wireless integration expertise, and organic thin-film transistor specialists. Competitive moves center on supply chain partnerships to secure film allocation and vertical integration into content management platforms.
Within the European module assembly tier, SOLUM Europe Gmbh and SES-imagotag exemplify platform-integrated vendors anchoring retail relationships through combined hardware and wireless infrastructure offerings. Plastic Logic GmbH occupies a specialist position leveraging organic thin-film transistor expertise for curved-form-factor industrial applications. E Ink Holdings Inc. anchors the upstream electrophoretic film supply, forcing downstream competitors into allocation-driven procurement cycles. CLEARink Displays Inc. represents the emerging electrowetting archetype pursuing full-color signage displacement of monochrome installations.
| Leading Market Players |
|---|
| CLEARink Displays Inc. |
| LANCOM Systems GmbH |
| Plastic Logic GmbH |
| FlexEnable Limited |
| SOLUM Europe Gmbh |
| Pervasive Displays Inc. |
| Visionect |
| SES-imagotag |
| E Ink Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
OTFT fabrication specialists concentrated in Cambridge and Dresden widen the pricing-tier spread between flexible-display premiums and standard monochrome panels, as labor-cost differentials between these clusters and Eastern European assembly zones compound with REACH compliance overhead.
Pricing Analysis
Distributor margins on electrophoretic film compress as E Ink Holdings tightens allocation protocols, forcing module assemblers toward direct-to-retail partnerships. Pricing stratifies across premium flexible substrates, standard monochrome ESL panels, and economy-grade segmented indicators. Cost compression in the standard tier intensifies because Polish and Romanian facilities exploit simplified ECHA reporting thresholds. Hypermarket procurement teams exhibit highest price sensitivity, while industrial wearable OEMs absorb premiums for curved-form-factor differentiation.
Supply Chain Analysis
Refurbishment flows for wireless-enabled shelf labels remain underdeveloped, creating stranded asset risk as retailers refresh ESL networks. Upstream film supply concentrates in Taiwan and China, with module assembly drawing from Germany, Poland, and Romania. Microencapsulated pigment suspensions, polyimide substrates, and organic semiconductor inks constitute critical input dependencies. Single-source vulnerability on electrophoretic film exposes European assemblers to allocation-driven disruption. Distribution runs through integrated platform providers rather than fragmented component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe E-Paper Display Market functions as a regulatory compounder, where EU Green Deal procurement mandates on near-zero standby consumption are accelerating municipal transit tenders beyond organic demand curves.
For Market Incumbents: Extend platform integration depth by embedding content management and wireless infrastructure into hardware offerings, countering electrowetting entrants pursuing color-signage displacement. Secure captive supply of compliant encapsulants ahead of ECHA candidate list expansions. Reinforce channel control through direct retail partnerships that bypass legacy distributor layers. For New Entrants and Emerging Players: Direct-to-industrial-wearable channels offer the lowest competitive density, as OTFT process engineering scarcity constrains incumbent scaling. Polish and Romanian grocery retail presents the most penetrable geography for ESL deployment. Position around electrowetting color fidelity benchmarks to intercept quick-service restaurant menu-board refresh cycles. For Investors and Strategic Acquirers: Display driver semiconductor specialists are the most active acquirer in this space, seeking OTFT backplane capabilities for automotive and industrial portfolios. Long-term viability hinges on timing the transition from monochrome electrophoretic dominance toward full-color electrowetting adoption. Monitor CLEARink prototype certification timelines against E Ink Gallery Plus rollout schedules as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Supply | Reduces allocation vulnerability to E Ink Holdings concentration. |
| REACH-Compliant Encapsulant Qualification | Preempts ECHA SVHC disqualification in French and German retail channels. |
| Flexible Substrate Capacity Expansion | Captures industrial wearable premiums from Dresden and Cambridge OTFT clusters. |
| Direct Retail Platform Partnerships | Bypasses distributor margin compression in DACH region ESL rollouts. |
| Electrowetting Color Prototype Certification | Positions for quick-service restaurant menu-board displacement of monochrome panels. |
Research Methodology
Coverage spans Western Europe, Central and Eastern Europe, and the United Kingdom, with primary inputs from each. The analysis combines structured interviews with ESL procurement managers at grocery chains, OTFT process engineers at Dresden fabrication facilities, and regulatory affairs specialists navigating ECHA compliance, validated against secondary sources including ECHA candidate list publications, EU Green Deal tender databases, and SEC filings from upstream film suppliers. Bottom-up demand modeling from retail deployment pipelines triangulates with top-down market sizing across the analysis window.
Granularity extends to individual country-level adoption curves, technology-type diffusion rates, and end-use procurement sophistication tiers. The analytical framework projects volume and value across product type, end user, technology, and application dimensions, with CAGRs derived from segment-level growth trajectory blending. Electrowetting color fidelity benchmarks, REACH SVHC list evolution, and municipal tender award velocities constitute key forecast inputs.
Upstream film allocation disruption, ECHA candidate list acceleration, and electrowetting prototype commercialization delays are the dominant revision risks to modeled outcomes. Forecasts embed assumptions on regulatory timeline adherence and technology substitution elasticity. Practitioners should monitor ECHA publication schedules, E Ink Holdings capacity announcements, and CLEARink certification milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Head-Mounted Display Market
Display Technologies
8K Display Resolution Market
Display Technologies
4K Technology Market
Display Technologies
Smartphone Display Market
Display Technologies
Field Emission Display Market
Display Technologies
E-Paper Display Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Foldable Display Market
Display Technologies
Screenless Display Market
Display Technologies
Touch Screen Display Market
Display Technologies
3D Holographic Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Electrochromic Window Market
Display Technologies
Electronic Display Market
Display Technologies
Global LED Digital Signage Market