
 Privacy Screens Market | 2026-2036
Privacy Screens Market Size, Share, and Industry Trends Forecast 2026-2036
Privacy Screens Market Analytics
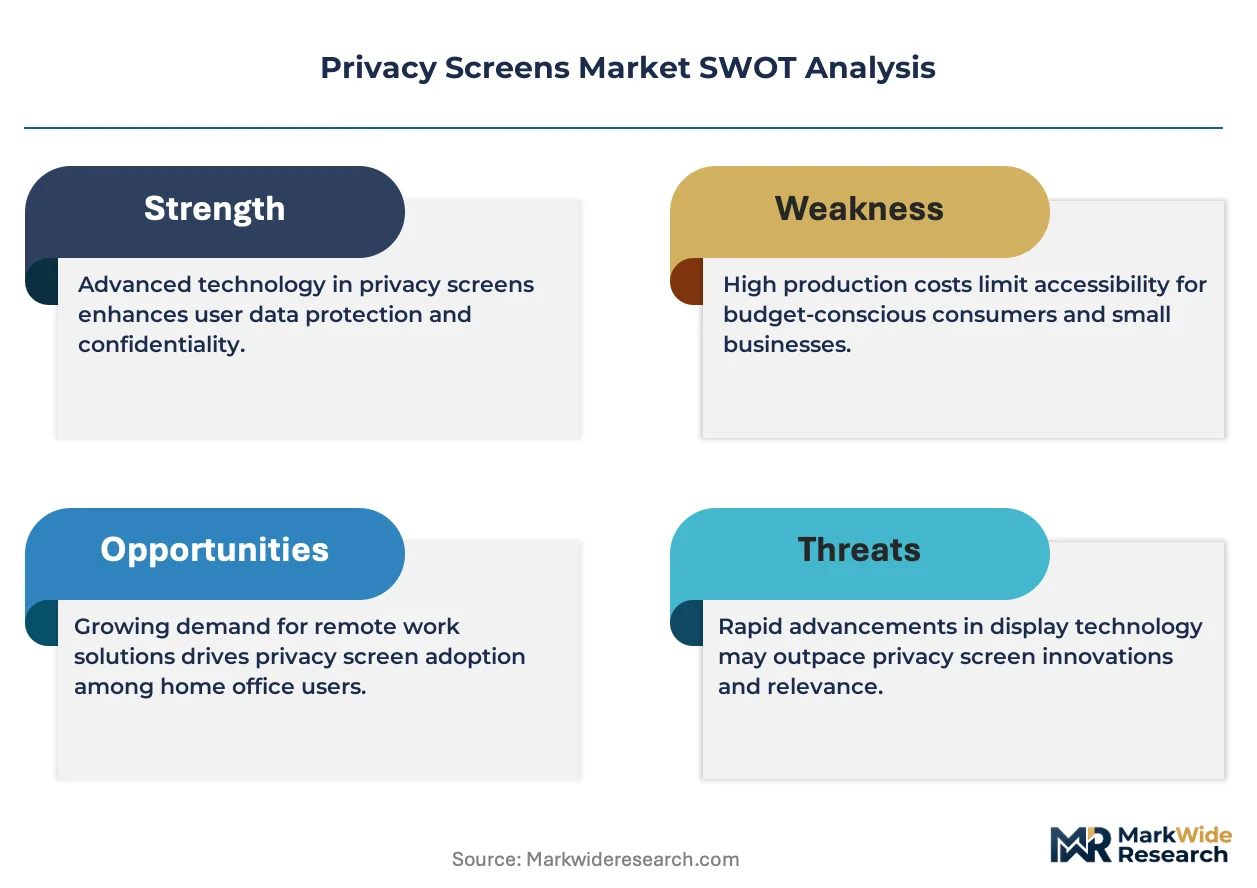
Anti-glare and blue-light-filtering specification tiers is reorganizing procurement priorities across enterprise buyers. 3M Company leverages its optical film expertise to sustain premium positioning in corporate channel partnerships. Kensington Computer Products Group anchors its portfolio in compliance-driven healthcare and government segments. Fellowes Brands competes through broad retail distribution and ergonomic workspace bundling.
Privacy screens are physical filters applied to electronic displays that use micro-louver or polarizing film technology to restrict viewing angles beyond approximately 30-60 degrees from center, typically constructed from polycarbonate or tempered glass substrates with anti-reflective coatings to protect visual data in shared environments. The application dimension tilts toward office environments where hybrid work policies have normalized hot-desking and open-floor layouts that amplify shoulder-surfing risks. The material dimension shows polycarbonate sustaining volume leadership due to its impact resistance and lighter weight for laptop portability, while glass substrates command margin pools in premium desktop monitors and medical imaging stations. The end-user dimension positions corporate offices as the mature baseline segment and educational institutions as an emerging growth corridor where one-to-one device programs expand the installed base requiring protection.
The Federal Trade Commission in the United States enforces data protection expectations that extend to physical safeguards in sectors handling consumer financial information, while the EU Green Deal and REACH frameworks in Europe restrict hazardous substances in polymer substrates and mandate recyclability pathways that reshape material selection. The National Institute of Standards and Technology guidelines and state-level breach notification laws collectively elevate privacy screens from peripheral accessories to components of comprehensive information security postures. Stakeholders must monitor how zero-trust security architectures integrate physical layer protections alongside digital controls as organizations reassess endpoint defense spending.
Market Dynamics
The Privacy Screens Market pivots on the collision between open-floor workstation proliferation and escalating data breach liability, where physical-layer protection now sits adjacent to cybersecurity budgets rather than facilities procurement.
Growth Catalysts
- EU Green Deal recyclability mandates:Manufacturers redesign polycarbonate substrates to meet e-waste directives, creating specification tiers that favor compliant suppliers in European tenders.
- Hot-desking normalization:Corporate offices with hybrid work policies amplify shoulder-surfing risks, expanding optical-grade filter procurement across financial services and legal sectors.
- Micro-louver film advances:Polarizing technology improvements tighten viewing-angle restrictions below 30 degrees, satisfying healthcare HIPAA requirements for patient data visibility control.
Market Restraints
- Polycarbonate price volatility:Petrochemical feedstock fluctuations compress margins for mid-tier manufacturers lacking long-term resin contracts.
- Asian substrate concentration:Optical film production clusters in East Asian manufacturing hubs expose buyers to shipping disruptions and tariff exposure.
- Built-in display privacy:Laptop OEMs integrate electronic privacy filters at factory level, threatening aftermarket accessory demand in enterprise segments.
Strategic Opportunities
- Educational one-to-one programs:K-12 and university device deployments create installed-base expansion for removable privacy filters in North American and European institutions.
- Medical imaging stations:Tempered glass substrates command premium positioning in radiology and diagnostic environments where sterilization durability matters.
- Anti-blue-light bundling:Ergonomic wellness programs integrate spectral filtering specifications into corporate wellness budgets alongside privacy functionality.
Industry Challenges
- REACH compliance timelines:European chemical substance restrictions delay new product introductions as manufacturers reformulate adhesive and coating chemistries.
- Installation standardization gaps:Inconsistent bezel dimensions across monitor OEMs fragment aftermarket sizing, forcing SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Privacy Screens Market |
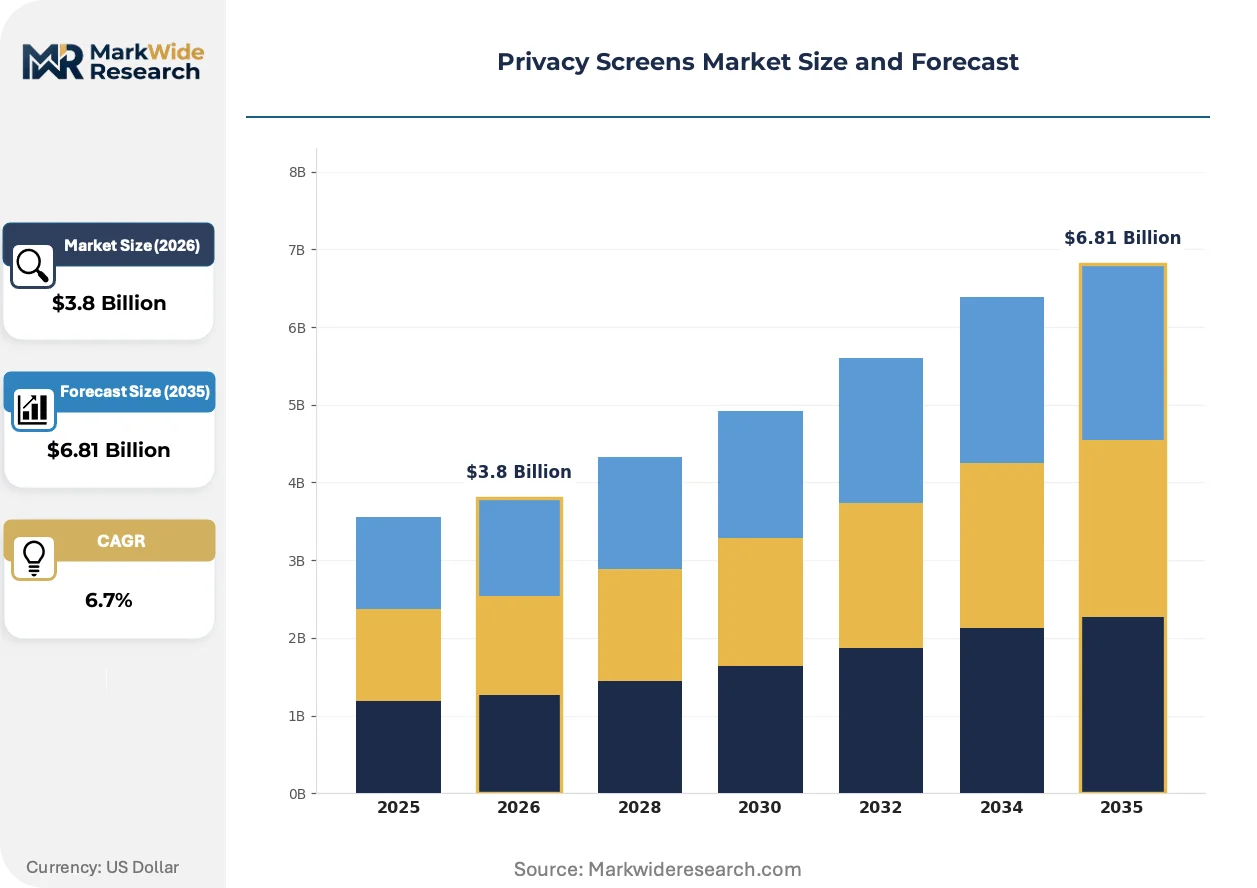
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
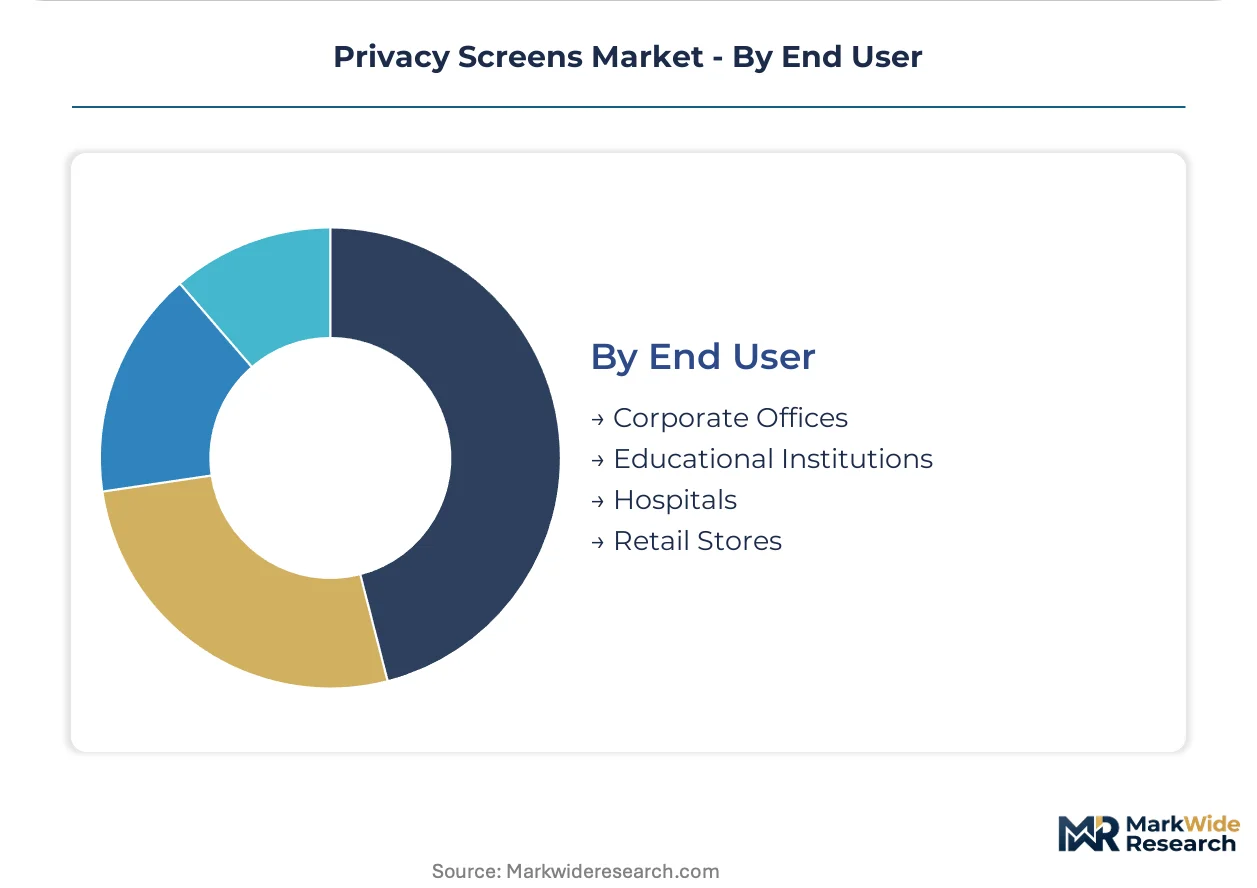
| Segmentation | Product Type: Fixed Screens, Portable Screens, Roll-Up Screens, Desktop Screens Material: Acrylic, Polycarbonate, Glass, Fabric Application: Office Environment, Home Office, Healthcare Facilities, Public Spaces End User: Corporate Offices, Educational Institutions, Hospitals, Retail Stores |
| Companies Covered | 3M Company, Targus, Kensington Computer Products Group, HP Inc., Dell Technologies Inc., Fellowes Brands, ZAGG Inc., Belkin International, PanzerGlass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Privacy Screens Market Evolving Landscape
Active developments across material science, regulatory chemistry, and procurement architecture are compressing product lifecycles and redrawing competitive boundaries in physical display protection.
Micro-louver optical film is miniaturizing louver pitch below 50 microns, enabling thinner form factors that preserve laptop lid closure tolerance. Enterprise buyers in financial services specify these sub-millimeter profiles for executive device fleets. The technology is miniaturizing the trade-off between privacy angle restriction and display brightness loss that previously limited adoption in high-ambient-light environments.
REACH substance restrictions in Europe now cover additional phthalate plasticizers and flame retardants used in polycarbonate compounding. Manufacturers reformulate substrate recipes or shift to alternative polymer bases to maintain CE marking eligibility. Medical device and government segments face the steepest compliance verification burdens, extending qualification cycles by 6-12 months.
Enterprise sourcing teams consolidate privacy screen procurement into endpoint security bundles rather than peripheral accessory categories. Value-added resellers displace pure retail channels in Fortune 500 accounts by attaching installation services and bulk imaging compatibility testing. Germany and the United Kingdom exhibit the most advanced procurement centralization, with dedicated workplace privacy officers emerging in banking and insurance headquarters.
Privacy Screens Market Segmentation
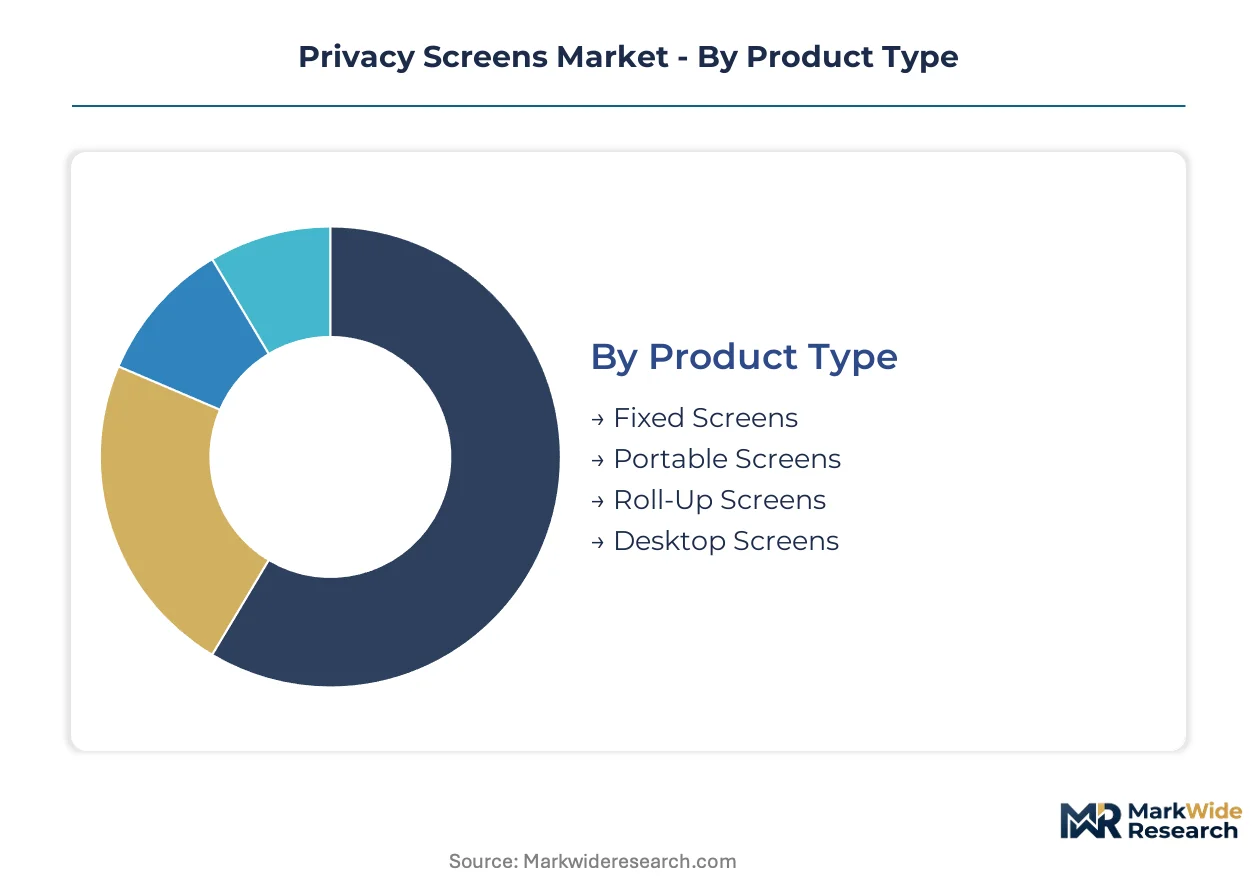
Segmentation in privacy screens reflects divergent compliance burdens across jurisdictions. Material choices trigger REACH substance restrictions in Europe. Application settings determine whether HIPAA, FTC guidelines, or EU Green Deal recyclability mandates dominate specification requirements.
Product Type:
Regulatory differentiation shapes procurement architecture across installation formats. Fixed and permanent mounting solutions face distinct building code and workplace safety inspections compared to removable alternatives.
- Fixed Screens:Permanent mounting hardware integrates with workstation furniture systems. Corporate offices in Germany specify these for open-floor financial services floors where BaFin workplace privacy mandates apply. REACH-compliant adhesive chemistries extend qualification cycles.
- Portable Screens:Clip-on and magnetic attachment systems serve hot-desking environments. Educational institutions in the United States deploy these across one-to-one device programs where FERPA student data protections elevate physical safeguards.
- Roll-Up Screens:Retractable mechanisms suit shared workstations with intermittent privacy needs.
- Desktop Screens:Freestanding panels partition individual work zones in open layouts.
Fixed screens handle the majority of throughput; portable screens are expanding most quickly on share.
Material:
Cost tier differentiation separates premium optical performance from economy positioning. Substrate selection directly determines recyclability pathways under EU Green Deal timelines and REACH substance restrictions.
- Polycarbonate:Impact-resistant polymer dominates laptop and mobile device applications due to weight advantages. Corporate procurement in the United Kingdom concentrates here for hybrid work fleets. Petrochemical feedstock volatility compresses margins for manufacturers lacking long-term resin contracts.
- Glass:Tempered substrates command premium positioning in medical imaging and diagnostic stations. Hospitals in Switzerland specify these for sterilization durability and optical clarity requirements under Swissmedic device standards. Weight penalties limit portable deployment.
- Acrylic:Lower-cost alternative for budget-conscious educational deployments.
- Fabric:textile-based solutions serve acoustic and visual partitioning in collaborative spaces.
Polycarbonate absorbs the largest volume position; glass is climbing the fastest on margin contribution.
Application:
Customer type concentration varies sharply across deployment environments. Healthcare and financial services face the steepest compliance verification burdens.
- Office Environment:Open-floor workstations and hot-desking layouts drive baseline demand. Financial services headquarters in Frankfurt specify optical-grade filters under stringent workplace privacy mandates. Hybrid work normalization sustains replacement cycles.
- Healthcare Facilities:Patient data visibility control requirements under HIPAA in the United States and GDPR in Europe elevate specification tiers. Radiology departments in France demand sterilization-compatible substrates meeting ANSM medical device standards.
- Home Office:Remote work arrangements expand consumer channel demand.
- Public Spaces:Libraries and co-working locations deploy communal protection solutions.
Office environments anchor volume throughput; healthcare facilities are gaining share fastest on specification premium.
End User:
Volume concentration versus margin capture splits across institutional buyer types. Procurement centralization maturity determines channel access requirements.
- Corporate Offices:Enterprise sourcing teams consolidate procurement into endpoint security bundles. Banking and insurance headquarters in London and Frankfurt employ dedicated workplace privacy officers. Bulk imaging compatibility testing extends sales cycles.
- Educational Institutions:K-12 and university one-to-one device programs create installed-base expansion. School districts in Texas and California deploy removable filters under state student data privacy laws. Budget constraints favor polycarbonate over glass substrates.
- Hospitals:Clinical environments prioritize sterilization durability and optical precision.
- Retail Stores:Point-of-sale and back-office deployments follow PCI-DSS physical safeguard expectations.
Corporate offices maintain the dominant throughput position; educational institutions show the steepest expansion trajectory on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports optical-grade micro-louver films to enterprise buyers in Germany and the United States, while polycarbonate substrate producers in South Korea supply European manufacturers adapting to EU Green Deal recyclability mandates.
United States
Financial services headquarters in New York and Chicago drive optical-grade filter procurement for open-floor trading floors. The FTC enforces data protection expectations extending to physical safeguards under consumer financial protection frameworks. Silicon Valley technology campuses in California deploy privacy screens across hybrid work fleets.
Germany
BaFin workplace privacy mandates compel banking headquarters in Frankfurt to specify fixed-mount privacy solutions for compliance. The EU Green Deal and REACH frameworks restrict hazardous substances in polymer substrates and mandate recyclability pathways. Industrial clusters in Bavaria host manufacturers reformulating adhesive chemistries to maintain CE marking eligibility.
United Kingdom
Corporate procurement teams in London consolidate privacy screen purchasing into endpoint security bundles for financial services and insurance sectors. GDPR patient data protections elevate specification tiers in National Health Service deployments. The Midlands manufacturing corridor supplies polycarbonate components to European assembly operations.
Japan
METI industrial standards and corporate governance codes drive privacy screen adoption in Tokyo financial districts and Osaka manufacturing headquarters. JIS standards govern optical performance specifications for enterprise procurement. Precision electronics clusters in Nagoya produce micro-louver film components for regional device assembly.
France
ANSM medical device standards and CNIL data protection guidance shape hospital procurement in Paris and Lyon healthcare systems. GDPR compliance extends to patient data visibility control in radiology departments. The Île-de-France region concentrates enterprise buyers in banking and insurance sectors specifying optical-grade filters.
Privacy Screens Market Competitive Landscape
Listed leaders compete with private specialists across material technology and distribution architecture. The vendor base separates into consolidated optical film producers, diversified electronics accessory platforms, and regional fabrication specialists. Three archetypes dominate: multinational chemical conglomerates leveraging polymer science, branded peripheral distributors commanding retail shelf space, and compliance-focused specialists serving healthcare and government segments. Capacity expansion in East Asian micro-louver production and strategic partnerships bundling installation services represent the dominant competitive moves.
Within the diversified technology conglomerate tier, 3M Company and HP Inc. occupy positions anchored by optical film expertise and enterprise device ecosystem integration respectively. Among branded peripheral specialists, Kensington Computer Products Group and Fellowes Brands exemplify distinct channel strategies—Kensington anchoring compliance-driven healthcare and government procurement, Fellowes competing through broad retail distribution and ergonomic workspace bundling. Belkin International sits within the consumer electronics accessory archetype, representing private-label and direct-to-consumer positioning.
| Leading Market Players |
|---|
| 3M Company |
| Targus |
| Kensington Computer Products Group |
| HP Inc. |
| Dell Technologies Inc. |
| Fellowes Brands |
| ZAGG Inc. |
| Belkin International |
| PanzerGlass |
| Others |
Value Network & Pricing Analysis
REACH substance restrictions gate both supplier qualification and price differentiation simultaneously, as European chemical compliance timelines force manufacturers to reformulate polycarbonate substrates and adhesive chemistries before CE marking eligibility unlocks premium positioning in German banking tenders.
Pricing Analysis
Enterprise sourcing teams anchor pricing stratification across premium, standard, and economy tiers, with optical-grade micro-louver specifications and REACH-compliant substrate certification driving spreads between healthcare-grade glass and educational polycarbonate deployments. Price erosion runs through mid-tier manufacturers lacking long-term petrochemical resin contracts, while corporate offices in Frankfurt and London exhibit lowest price sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
East Asian optical film production clusters underwrite substrate availability for European and North American assembly operations, with micro-louver manufacturing concentrating in China and South Korea while polycarbonate resin production feeds from South Korean petrochemical complexes. Raw material dependencies center on bisphenol-A feedstocks, optical-grade polyethylene terephthalate films, and specialized adhesive polymers. Single-source vulnerability in micro-louver film supply exposes buyers to shipping disruption risks. Distribution runs through value-added resellers displacing pure retail channels in Fortune 500 accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation services and bulk imaging compatibility testing represent the fastest-expanding recurring-revenue layer, outpacing hardware unit growth as enterprise sourcing teams consolidate procurement into endpoint security bundles with attached deployment support.
For Market Incumbents: Fortify channel control through exclusive partnerships with workstation furniture OEMs, locking in fixed-mount specification pathways before built-in electronic privacy filters from laptop manufacturers erode aftermarket demand. Backward integration into REACH-compliant adhesive formulation protects margin pools in European tenders. Capacity addition in Bavarian industrial clusters shortens qualification cycles for BaFin-mandated banking deployments. For New Entrants and Emerging Players: Differentiate on educational one-to-one device program penetration, where removable filter deployment across Texas and California school districts faces lower incumbent saturation than corporate segments. K-12 procurement cycles favor polycarbonate cost structures over glass premiums. Direct district-level contracting bypasses value-added reseller markups. For Investors and Strategic Acquirers: EU Green Deal recyclability mandate timelines reshape the acquisition landscape toward substrate reformulation capabilities and circular economy certification assets. Five-to-ten year viability favors targets with in-house polymer science expertise over pure distribution plays. Monitor REACH substance list expansion announcements as inflection indicators for qualification cycle extensions.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Substrate Reformulation | CE marking eligibility unlocks German banking and French hospital procurement channels. |
| Installation Services Bundling | Value-added resellers capture enterprise accounts through bulk imaging compatibility testing. |
| Educational Channel Direct Contracting | K-12 one-to-one programs in Texas and California bypass incumbent retail distribution. |
| Micro-Louver Film Miniaturization | Sub-50 micron pitch specifications satisfy financial services executive fleet requirements. |
| Glass Substrate Sterilization Certification | Swissmedic and ANSM compliance commands premium positioning in radiology departments. |
Research Methodology
The analysis maps fixed-mount, portable, roll-up, and desktop screen formats, each validated through procurement directors at financial services headquarters, privacy officers in German banking, biomedical engineers in French hospitals, and K-12 technology coordinators across North American school districts. Primary interview insights triangulate against customs trade data, SEC filings from diversified electronics accessory platforms, EU ECHA substance restriction databases, and hospital procurement contract disclosures. Bottom-up unit deployment estimates cross-check with top-down addressable device base calculations.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product installation format, substrate material tier, application environment, and end-user procurement centralization maturity. CAGRs derive from installed base expansion rates, replacement cycle compression in hybrid work environments, and specification tier shifts toward healthcare and financial services compliance segments. Forecast inputs incorporate petrochemical feedstock volatility assumptions and REACH substance list revision probabilities.
Forecasts assume regulatory continuity in EU REACH, EU Green Deal recyclability mandates, and FTC data protection enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as laptop OEM built-in privacy filter adoption rates and polycarbonate resin supply disruption frequencies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Port Market
Display Technologies
Laptop Panels Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Multi-Function Display Market
Display Technologies
3LCD Projector Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
DLP Projector Market
Display Technologies
Industrial Display Market
Display Technologies
Global Center Stack Display Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Flexible Display Market
Display Technologies
Low Power Display Market
Display Technologies
Global UHD Display Market
Display Technologies
Smartphone Display Market