
 Europe Electric Vehicle Chargers Market | 2026-2036
Europe Electric Vehicle Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Chargers Market Analytics
Silicon carbide is consolidating its position as the dominant semiconductor material in high-power charging modules, displacing traditional silicon IGBTs across European DC fast charger designs. ABB leverages its Swiss manufacturing base to sustain vertical integration in power electronics assembly. Siemens anchors its market presence through grid-integration software that manages bi-directional charging protocols. Schneider Electric differentiates via wall-mounted residential units that dominate the French and Benelux installer channels.
Europe electric vehicle chargers are electromechanical systems that convert grid alternating current to direct current matched to battery chemistry, with DC fast chargers delivering outputs from 50 kW to 350 kW through liquid-cooled cable assemblies. Their primary purpose is to replenish battery electric vehicle storage within timeframes calibrated to driver dwell patterns and fleet duty cycles. AC chargers retain the largest installed base across residential parking applications, though DC fast chargers capture the fastest expansion in margin pools along highway corridors and fleet depots. Wall-mounted installation types lead in unit volume across multi-unit dwellings, while pedestal-mounted configurations command premium positioning in commercial parking environments where dual-port simultaneous service generates higher throughput.
The EU Green Deal mandates binding infrastructure density targets that EEA member states must transpose into national building codes and energy network planning. ECHA REACH compliance governs substance restrictions in cable sheathing and contact materials, while CE marking under the EU AI Act extends to smart charging algorithms that manage grid load balancing. Stakeholders must monitor how the F-Gas Regulation affects cooling system refrigerant selections in high-power charging cabinets as thermal management requirements intensify.
Market Dynamics
Silicon carbide power semiconductors are compressing thermal management costs in DC fast chargers, enabling 350 kW output densities that reshape highway corridor economics and fleet depot planning across European member states.
Growth Catalysts
- EU Green Deal infrastructure mandates:Binding density targets for charging points in national building codes force real estate developers and highway operators to pre-wire parking structures and service stations for high-power connections.
- Silicon carbide module adoption:Wide-bandgap semiconductors cut switching losses by half compared to silicon IGBTs, allowing compact cabinet designs that reduce installation footprint in constrained urban sites.
- Germany's autobahn corridor buildout:Federal transport ministry funding prioritizes 150 kW-plus charging parks every 50 kilometers along major trunk routes, creating anchor demand for liquid-cooled cable systems.
Market Restraints
- Copper and rare earth price volatility:Liquid-cooled cable assemblies contain substantial copper conductor mass, exposing manufacturer margins to London Metal Exchange price swings that resist pass-through in fixed infrastructure contracts.
- Power electronics supply concentration:Silicon carbide wafer fabrication concentrates in a handful of European and Asian foundries, creating bottleneck risk for charger OEMs scaling output beyond captive module capacity.
- Grid connection lead times:Distribution network operators in France and Benelux face 18-to-24-month queues for medium-voltage substation upgrades, delaying commercial activation of commissioned charging sites.
Strategic Opportunities
- Poland and Romania highway corridors:EU cohesion fund allocations for trans-European transport networks prioritize first-mover charging infrastructure in member states with lowest current DC fast charger density per kilometer.
- Vehicle-to-grid integration:Bi-directional charging protocols enable fleet operators to monetize parked bus and van batteries as grid stabilization assets, creating new revenue streams beyond energy retail.
- CE marking under EU AI Act:Smart charging algorithms that manage load balancing face mandatory conformity assessment, opening compliance consulting and certification services for software-integrated hardware vendors.
Industry Challenges
- Power electronics engineering talent scarcity:Design of 350 kW liquid-cooled inverters requires specialized expertise in electromagnetic compatibility and thermal modeling that outstrips graduate pipeline output in continental Europe.
- F-Gas Regulation refrigerant transitions:High-power charging cabinets using conventional hydrofluorocarbon coolants must retool for low-global-warming-potential alternatives before phasedown deadlines, complicating thermal system validation.
- Multi-standard connector fragmentation:Simultaneous support for CCS, CHAdeMO, and emerging MCS protocols increases hardware complexity and inventory carrying costs for operators serving mixed fleet populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Chargers Market |
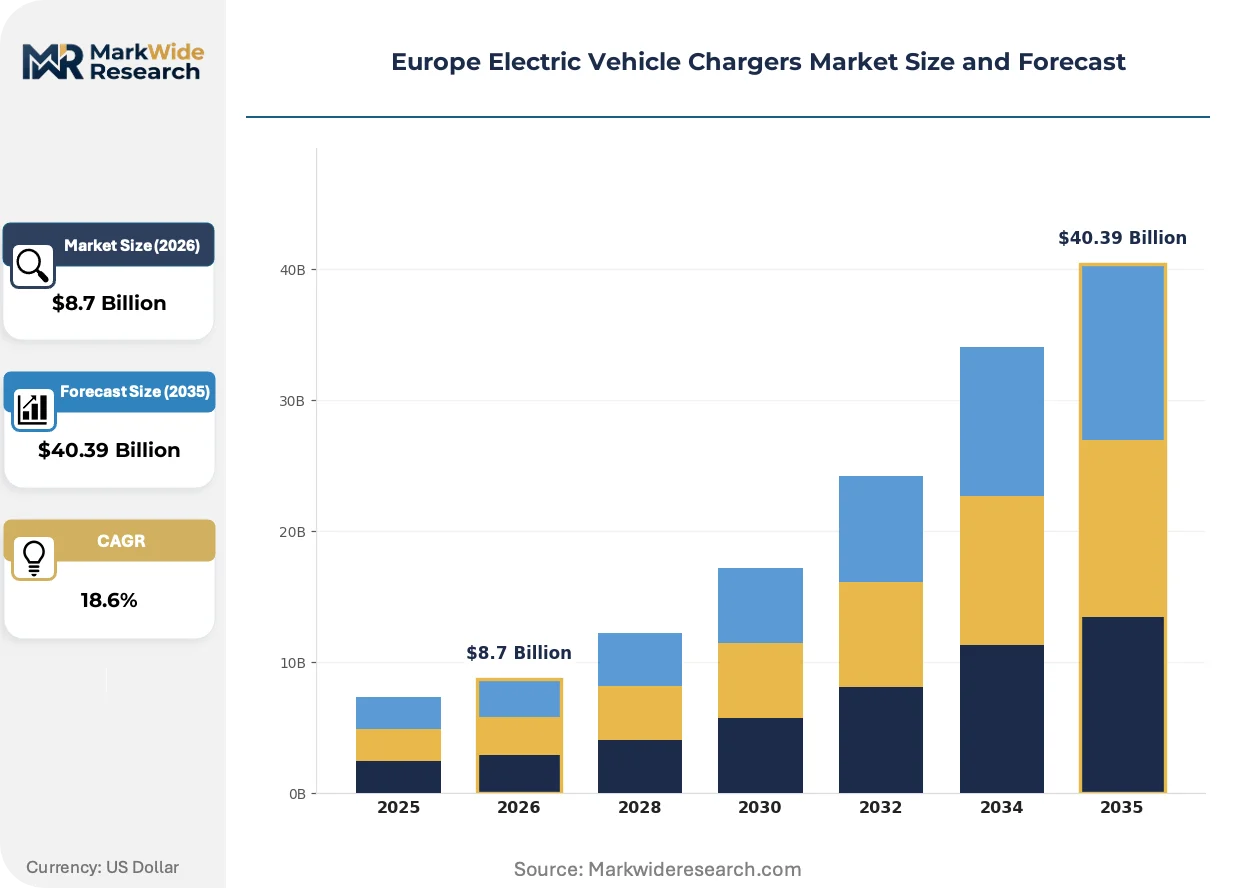
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers Application: Residential Parking, Commercial Parking, Public Charging Stations, Fleet Depots Installation Type: Wall-mounted, Pedestal-mounted, Pole-mounted, Mobile Units Customer Type: Vehicle Manufacturers, Property Developers, Fleet Operators, Local Authorities |
| Companies Covered | ABB, EVBox, Siemens, Webasto, Schneider Electric, EFACEC, Allego, Wallbox, ChargePoint, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Chargers Market Evolving Landscape
Hardware-software convergence in charging systems is rewriting competitive boundaries, as grid-integration capabilities and energy management algorithms become primary differentiators alongside raw power output specifications.
Silicon carbide MOSFETs are consolidating their position as the dominant switching technology in high-power charging modules. Fleet operators and highway service providers specify SiC-based designs for new 150 kW-plus installations. This semiconductor transition is consolidating supplier power among vertically integrated power electronics manufacturers with captive wafer supply.
The EU F-Gas Regulation is accelerating refrigerant transitions in thermal management systems. Cooling circuit redesigns for low-global-warming-potential alternatives extend product validation cycles by six to nine months. Charger OEMs serving Nordic markets with extreme ambient temperature ranges face the steepest re-engineering burden.
Fleet procurement of charging-as-a-service contracts is displacing capital purchase models among municipal bus operators and logistics providers. Energy retailers and infrastructure funds underwrite asset ownership, transferring utilization risk from transport operators to financial sponsors. This financing shift is most advanced in the Netherlands, where aggregated fleet demand enables long-term power purchase agreements.
Europe Electric Vehicle Chargers Market Segmentation
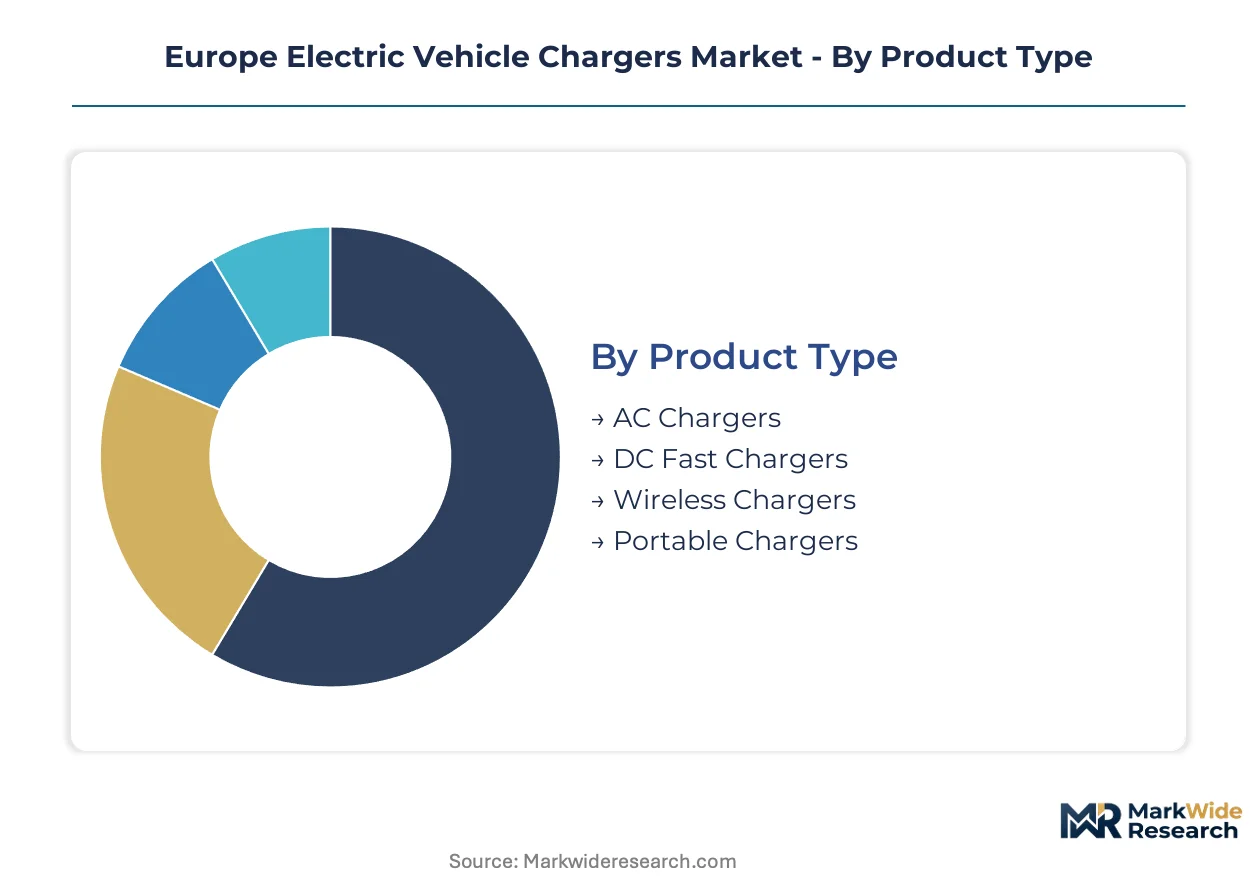
Segmentation in Europe's electric vehicle charging market reveals divergent margin profiles and procurement patterns across power levels and deployment contexts. Each dimension—product type, application, installation format, and customer category—carries distinct regulatory exposure and technology adoption timelines that reshape vendor go-to-market priorities.
Product Type:
Purchasing decisions pivot on dwell-time economics and grid connection capacity at specific deployment sites.
- AC Chargers:These units deliver alternating current at 7 kW to 22 kW through onboard vehicle rectifiers, requiring minimal installation infrastructure. Demand concentrates in Germany's multi-unit residential developments and France's suburban housing estates where overnight charging aligns with residential dwell patterns and building code pre-wiring mandates drive bulk procurement.
- DC Fast Chargers:Direct current systems bypass onboard conversion to deliver 50 kW to 350 kW through liquid-cooled cable assemblies. Highway corridor operators in the Netherlands and Belgium specify these for service station deployments where silicon carbide power modules compress thermal management footprints and reduce cabinet installation costs.
- Wireless Chargers:Inductive pad systems transfer power across air gaps to vehicle-mounted receiver coils. Pilot deployments focus on German premium vehicle manufacturer test fleets and Norwegian taxi rank demonstrations.
- Portable Chargers:Mobile cable and control units plug into standard domestic sockets for emergency top-ups. French and Italian aftermarket channels stock these for rural drivers lacking fixed parking infrastructure.
Volume sits with AC Chargers; growth tilts toward DC Fast Chargers.
Application:
Site ownership models and utilization guarantees determine capital recovery horizons and financing structures.
- Residential Parking:Fixed installations in single-family driveways and apartment building garages. German building energy codes mandate pre-wiring for new construction, concentrating retrofit demand in Benelux urban renewal zones.
- Commercial Parking:Workplace and retail location deployments where dwell times span 4-8 hours. French hypermarket chains and Dutch office park developers dominate procurement through charging-as-a-service contracts.
- Public Charging Stations:Curbside and destination installations serving transient users. Poland and Romania absorb EU cohesion fund allocations for trans-European network corridor buildouts with lowest existing density.
- Fleet Depots:Centralized charging for bus and delivery van operators with predictable return-to-base patterns. Municipal procurement in the Netherlands aggregates demand through long-term power purchase agreements.
Commercial Parking commands current unit volume; Fleet Depots show steepest expansion trajectory as charging-as-a-service financing displaces capital purchase models.
Installation Type:
Physical mounting constraints and dual-port service requirements shape hardware specifications and labor cost structures.
- Wall-mounted:Bracket-fixed units for indoor parking structures and building facades. French and Benelux installer channels favor compact residential designs that minimize conduit runs in retrofit applications.
- Pedestal-mounted:Freestanding cabinets supporting dual-port simultaneous service in commercial environments. Highway service stations across Germany specify these for 150 kW-plus outputs where liquid-cooled cable management demands ground-level cabinet access.
- Pole-mounted:Streetlight and utility pole attachments for curbside urban deployment. Nordic municipalities trial these to exploit existing electrical infrastructure and reduce sidewalk obstruction.
- Mobile Units:Trailer-mounted temporary systems for construction sites and event venues. Eastern European rental fleets acquire these for seasonal tourism corridor deployment.
Wall-mounted units dominate residential volume; Pedestal-mounted configurations gain share fastest in commercial and highway segments.
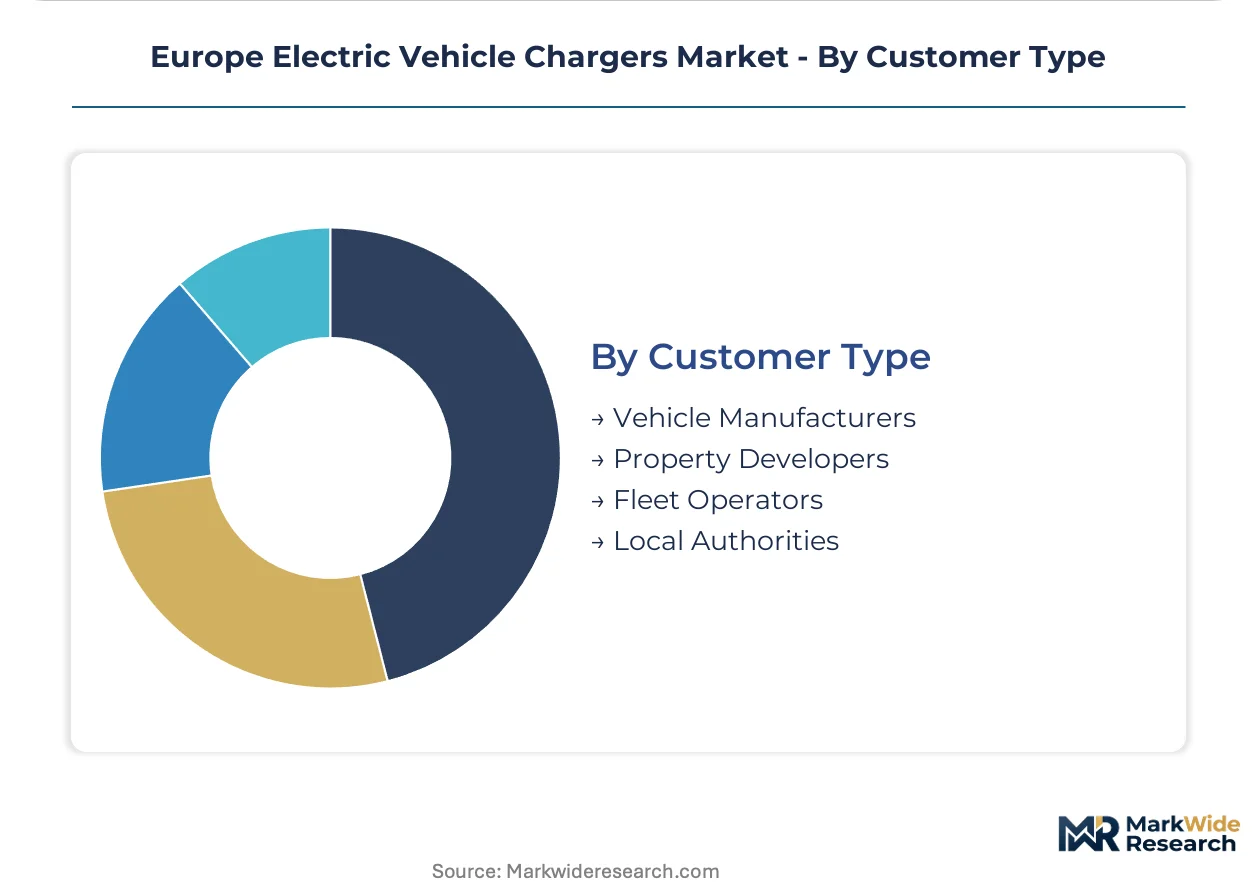
Customer Type:
Procurement sophistication varies from standardized OEM supply agreements to fragmented municipal tender processes.
- Vehicle Manufacturers:Bundled charger supply with new vehicle sales and dealership network equipment. German premium brands specify branded wallboxes for customer home installation packages.
- Property Developers:Bulk pre-installation during construction phase to meet EU Green Deal building code transpositions. French residential developers face binding charging point density targets in new multi-unit projects.
- Fleet Operators:Municipal bus companies and logistics providers with predictable duty cycles. Dutch aggregated procurement enables long-term energy hedging through infrastructure fund partnerships.
- Local Authorities:Curbside and public realm installations subject to public procurement rules. Polish and Romanian regional governments access EU cohesion funding for first-mover highway corridor infrastructure.
Property Developers drive current installation volume; Fleet Operators are expanding most quickly as charging-as-a-service transfers utilization risk to financial sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along Germany's autobahn corridors and the Netherlands' Randstad logistics belt concentrate charging infrastructure investment. EU cohesion fund allocations are redirecting capital toward Poland and Romania's trans-European transport networks.
Germany
Federal transport ministry funding prioritizes 150 kW-plus charging parks every 50 kilometers along major trunk routes. The EU Green Deal's binding infrastructure density targets transposed into national building codes mandate pre-wiring in new construction. Bavaria's industrial corridor hosts manufacturing clusters for silicon carbide power modules serving DC fast charger OEMs.
Netherlands
Aggregated fleet demand from municipal bus operators enables long-term power purchase agreements with infrastructure funds. ECHA REACH compliance governs substance restrictions in cable sheathing materials deployed across Randstad charging networks. The Eindhoven Region anchors hardware-software convergence R&D for bi-directional charging protocols.
France
Urban rapid-charging hubs concentrate deployment around Île-de-France hypermarket chains and office park developers. French building energy codes impose binding charging point density targets on new multi-unit residential projects. Auvergne-Rhône-Alpes hosts manufacturing clusters for wall-mounted residential units dominating installer channels.
Poland
EU cohesion fund allocations prioritize first-mover charging infrastructure along trans-European network corridors with lowest existing DC fast charger density. CE marking under the EU AI Act extends conformity assessment requirements to smart charging algorithms. Warsaw's metropolitan zone absorbs infrastructure investment for highway service station electrification.
Belgium
Distribution network operators face compressed lead times for medium-voltage substation upgrades in Flanders logistics corridors. The F-Gas Regulation accelerates refrigerant transitions in thermal management systems for high-power charging cabinets. Antwerp's port zone clusters fleet depot installations serving delivery van electrification programs.
Europe Electric Vehicle Chargers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration in power electronics assembly conferring cost advantages in high-output DC systems. The vendor base concentrates among Swiss and German industrial conglomerates with captive semiconductor supply, alongside specialized charging infrastructure pure-plays. Three archetypes dominate: diversified industrial technology groups, dedicated EV charging specialists, and grid-integration software providers. Capacity expansion in silicon carbide wafer fabrication and strategic partnerships for charging-as-a-service financing represent the primary competitive vectors reshaping positioning.
Among diversified industrial technology groups, ABB leverages its Swiss manufacturing footprint to sustain backward integration in power electronics assembly. Siemens anchors its market presence through grid-integration software managing bi-directional charging protocols. Schneider Electric occupies a position exemplifying wall-mounted residential specialization that dominates French and Benelux installer channels.
| Leading Market Players |
|---|
| ABB |
| EVBox |
| Siemens |
| Webasto |
| Schneider Electric |
| EFACEC |
| Allego |
| Wallbox |
| ChargePoint |
| Others |
Value Network & Pricing Analysis
Captive silicon carbide wafer fabrication in Bavaria and Switzerland anchors both supply security and pricing power for European DC fast charger OEMs, compressing thermal management costs while insulating margins from Asian foundry bottlenecks. This backward integration into power semiconductors allows manufacturers to command premium positioning in Germany's autobahn corridor tenders while maintaining cost discipline against contract assemblers dependent on spot-market module procurement.
Pricing Analysis
Volume concentrates in AC wallbox units where Schneider Electric and Webasto compete on installer channel rebates, while margin pools accrue to DC fast charger OEMs with silicon carbide module supply. Price differentiation rests on CE marking tier under the EU AI Act and liquid-cooled cable assembly specifications. Cost compression in residential tiers stems from copper conductor price volatility that resists pass-through in fixed infrastructure contracts. Municipal fleet operators show lowest price sensitivity due to charging-as-a-service financing structures.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German premium vehicle manufacturers bundling branded wallboxes with new vehicle sales. Manufacturing concentrates in Germany, Switzerland, and the Netherlands for power electronics assembly, with silicon carbide substrates drawn from Bavarian foundries and cable sheathing materials sourced under ECHA REACH compliance. Single-source vulnerability sits with European wafer fabrication capacity for wide-bandgap semiconductors. Distribution runs through certified installer networks in France and Benelux for residential units, while highway corridor deployments bypass intermediaries via EPC contractor direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide MOSFETs are displacing silicon IGBTs across high-power charging architectures, forcing incumbents and entrants alike to secure semiconductor supply or cede highway corridor and fleet depot segments to vertically integrated competitors.
For Market Incumbents: Anticipate margin compression from contract manufacturers acquiring silicon carbide module design capabilities by deepening backward integration into wafer supply or securing long-term offtake agreements with Bavarian foundries. Prioritize CE marking investment under the EU AI Act for smart charging algorithms to defend positioning in grid-integration software segments where Siemens has established protocol dominance. For New Entrants and Emerging Players: Enter via Poland and Romania's trans-European network corridors where EU cohesion fund allocations support first-mover infrastructure with lowest existing DC fast charger density per kilometer. Target municipal fleet operators in the Netherlands through charging-as-a-service financing partnerships that transfer utilization risk to infrastructure funds. Differentiate via bi-directional charging protocol certification for vehicle-to-grid revenue streams. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure fund acquisition of charging-as-a-service platforms with aggregated fleet demand and long-term power purchase agreements. Five-to-ten-year viability hinges on silicon carbide supply security and F-Gas Regulation compliance for thermal management retrofits. Monitor CE marking approval queues under the EU AI Act as inflection indicator for software-integrated hardware vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Supply Agreement | Captive wafer access insulates margins from foundry bottlenecks in Bavarian manufacturing clusters. |
| CE Marking Under EU AI Act | Conformity assessment for smart charging algorithms opens compliance consulting revenue streams. |
| Charging-as-a-Service Platform Launch | Aggregated fleet demand in the Netherlands enables long-term power purchase agreement underwriting. |
| Bi-Directional Charging Protocol Certification | Grid-integration capabilities monetize parked bus batteries as stabilization assets beyond energy retail. |
| F-Gas Regulation Thermal Retrofit | Low-global-warming-potential coolant transitions extend product validation cycles for Nordic market access. |
Research Methodology
Document review covered ECHA REACH substance restriction filings, EU Green Deal infrastructure density transpositions, and F-Gas Regulation phasedown schedules, complemented by interviews with power electronics engineering directors at DC fast charger OEMs, procurement leads at German municipal fleet operators, distribution network operators in France and Belgium, and certified installer network managers in the Netherlands. Secondary validation drew from SEC filings of listed charging infrastructure funds, IEA electric vehicle outlooks, and customs data on silicon carbide wafer trade flows. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment allocations.
Installed base and revenue outputs were generated through segmented modeling across power level tiers, installation format categories, and customer type archetypes over the projection horizon. CAGRs were derived from elasticity-adjusted deployment curves incorporating EU cohesion fund absorption rates and national ICE phase-out timelines. Industry-specific inputs included silicon carbide module cost-down trajectories, medium-voltage grid connection queue durations, and charging-as-a-service contract penetration rates.
Revisions become necessary when silicon carbide foundry capacity expansions materially exceed or fall short of modeled assumptions, or when EU AI Act conformity assessment timelines extend beyond regulatory guidance. Forecasts reflect documented assumptions regarding fleet electrification mandates and F-Gas Regulation refrigerant transition deadlines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market