
 Kuwait Oil and Gas Downstream Market | 2026-2036
Kuwait Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Oil and Gas Downstream Market Foresight
Domestic wholesale distribution is rewriting access patterns for refined fuels and petrochemical intermediates within Kuwait. Kuwait National Petroleum Company leverages its integrated refinery network to sustain captive supply chains across the Al-Zour and Mina Abdullah complexes. Petrochemical Industries Company anchors aromatics and olefins production, while Kuwait Integrated Petroleum Industries Company competes through its control over the Al-Zour refinery's high-conversion capacity.
Kuwait oil and gas downstream operations encompass refining, petrochemical conversion, lubricant blending, and asphalt processing of crude oil and associated feedstocks, with refining units typically operating at complexity indices above 10 to maximize middle-distillate yields. The primary purpose centers on transforming Kuwait's heavy sour crude slate into transportation fuels, polymer feedstocks, and industrial-grade bitumen for domestic consumption and re-export. Refinery products command the largest revenue share given Kuwait's four-operating-refinery base, while petrochemicals represent the fastest-expanding margin pool as PIC and EQUATE partners expand aromatics capacity. The lubricants segment remains mature, with demand tied to Kuwait's vehicle fleet and industrial machinery maintenance cycles.
Kuwait Environment Public Authority standards and the Ministry of Oil's fuel quality specifications shape product slate decisions and capital allocation across downstream assets. The national regulator's sulfur recovery mandates and the country's commitment to net-zero emissions by 2050 are forcing upgrades to hydroprocessing and carbon capture units. Stakeholders must monitor how Kuwait Petroleum Corporation's 2040 strategy reconciles refining expansion with petrochemical integration priorities.
Market Dynamics
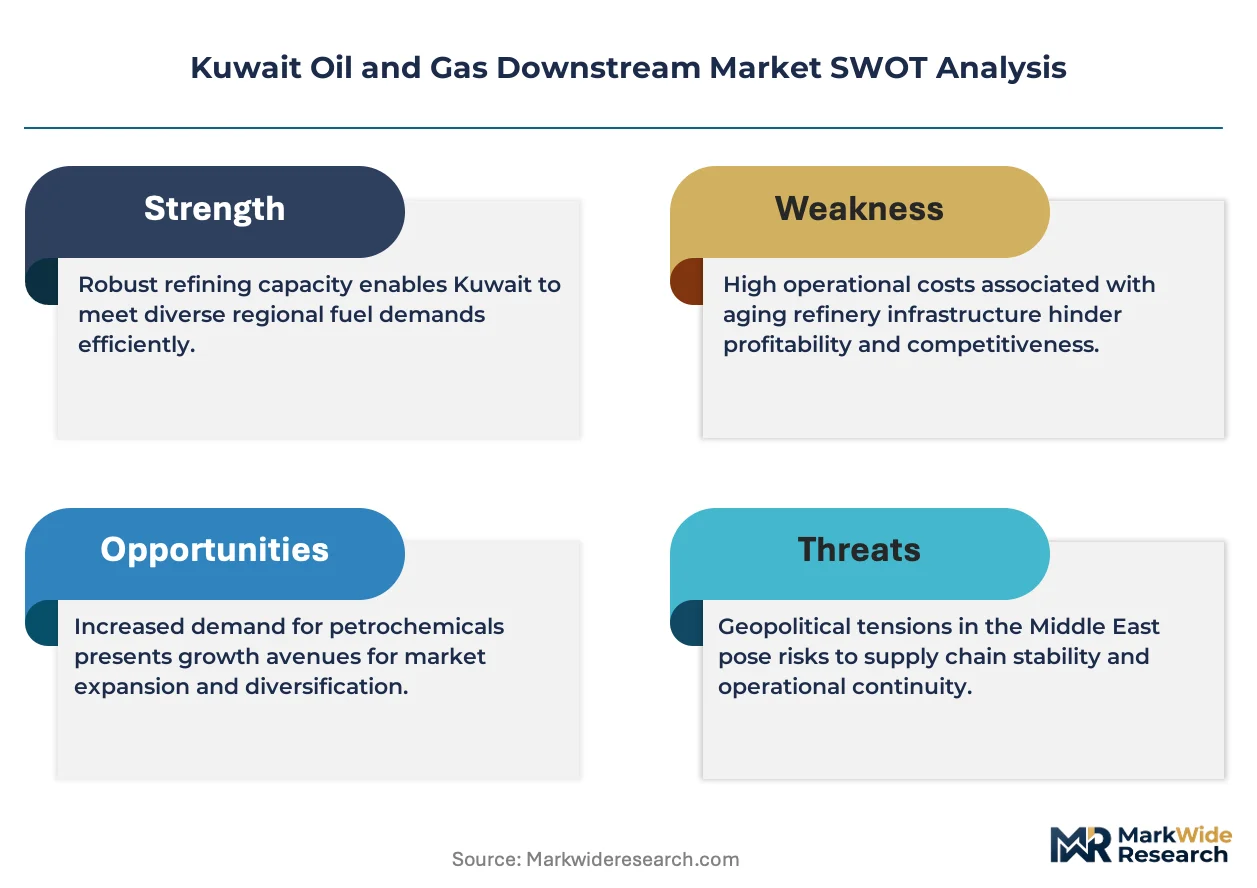
Kuwait's downstream sector faces structural pressure from the Environment Public Authority's sulfur recovery mandates, which force capital reallocation toward hydroprocessing upgrades while the Al-Zour refinery ramps to full conversion capacity.
Growth Catalysts
- Power generation diversification:Kuwait's national grid is expanding gas and liquid fuel flexibility, pulling additional refinery product offtake from Mina Abdullah and Al-Zour complexes.
- Al-Ahmadi Governorate clustering:Concentrated refining and petrochemical capacity in this industrial corridor generates feedstock synergies and shared infrastructure economies.
- Net-zero 2050 pathway:Kuwait Petroleum Corporation's decarbonization commitment is accelerating carbon capture unit deployment across downstream assets.
Market Restraints
- Heavy sour crude dependency:Kuwait's fixed crude slate limits product flexibility and requires higher complexity indices to yield middle-distillate grades.
- Single-buyer concentration:Kuwait National Petroleum Company dominates offtake, compressing third-party access to wholesale fuel markets.
- Sulfur recovery capex intensity:Environment Public Authority mandates demand continuous hydroprocessing investment without commensurate product premium capture.
Strategic Opportunities
- Al-Zour aromatics expansion:Petrochemical Industries Company can leverage the refinery's naphtha output to deepen olefins and aromatics integration.
- Lubricant export positioning:Kuwait's mature blending capacity serves regional maritime and industrial machinery markets across the Gulf.
- Carbon capture integration:Enhanced oil recovery partnerships offer offtake pathways for captured CO2 from refinery operations.
Industry Challenges
- Specialized process engineering talent:Hydroprocessing and sulfur recovery unit operation requires scarce technical expertise concentrated among international contractors.
- Legacy system integration:Kuwait Integrated Petroleum Industries Company's Al-Zour asset must synchronize with Kuwait National Petroleum Company's established distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Oil and Gas Downstream Market |
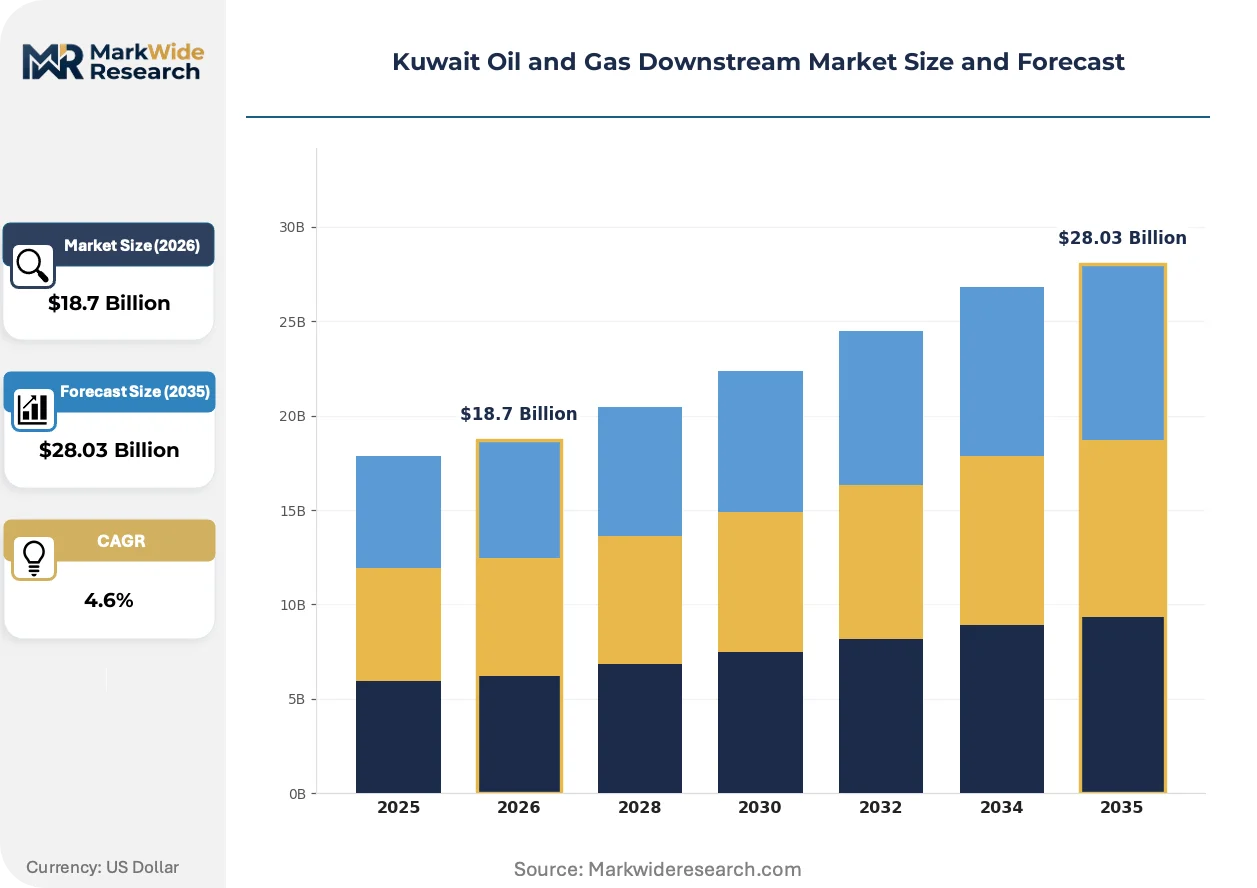
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refinery Products, Petrochemicals, Lubricants, Asphalt End User: Automotive, Industrial, Commercial, Residential Distribution Channel: Retail Outlets, Wholesale Distributors, Online Platforms, Direct Sales Service Type: Maintenance Services, Installation Services, Consulting Services, Engineering Services |
| Companies Covered | Petrochemical Industries Company, Qurain Petrochemical Industries Company, Kuwait National Petroleum Company, BP, Total, Kuwait Integrated Petroleum Industries Company, Boubyan Petrochemical Company, Shell, Petrochemicals Industries Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Oil and Gas Downstream Market Shifts & Advancements
Digital process control and emissions monitoring systems are reshaping how Kuwait's refineries optimize conversion yields while maintaining Environment Public Authority compliance across the Al-Ahmadi industrial corridor.
Residue hydrocracking technology is hybridizing vacuum residue processing with integrated aromatics extraction, allowing Kuwait Integrated Petroleum Industries Company to stretch heavy sour barrels into higher-margin chemical feedstocks. Kuwait National Petroleum Company is piloting these configurations at Mina Abdullah. The technology is hybridizing traditional refining margins with petrochemical economics.
Environment Public Authority flaring standards are tightening real-time emissions monitoring requirements across downstream units. Refinery operators must deploy continuous emissions monitoring systems or face operational penalties. Al-Zour's newbuild configuration incorporates these systems natively, while older Mina Al-Ahmadi units require retrofit capital.
Buyers in Kuwait's power and industrial sectors are consolidating fuel procurement through annual tender structures rather than spot market purchases. Kuwait National Petroleum Company's integrated supply chain is absorbing this volume concentration. The shift is most visible in long-term fuel oil and diesel contracts with the Ministry of Electricity and Water.
Kuwait Oil and Gas Downstream Market Segmentation
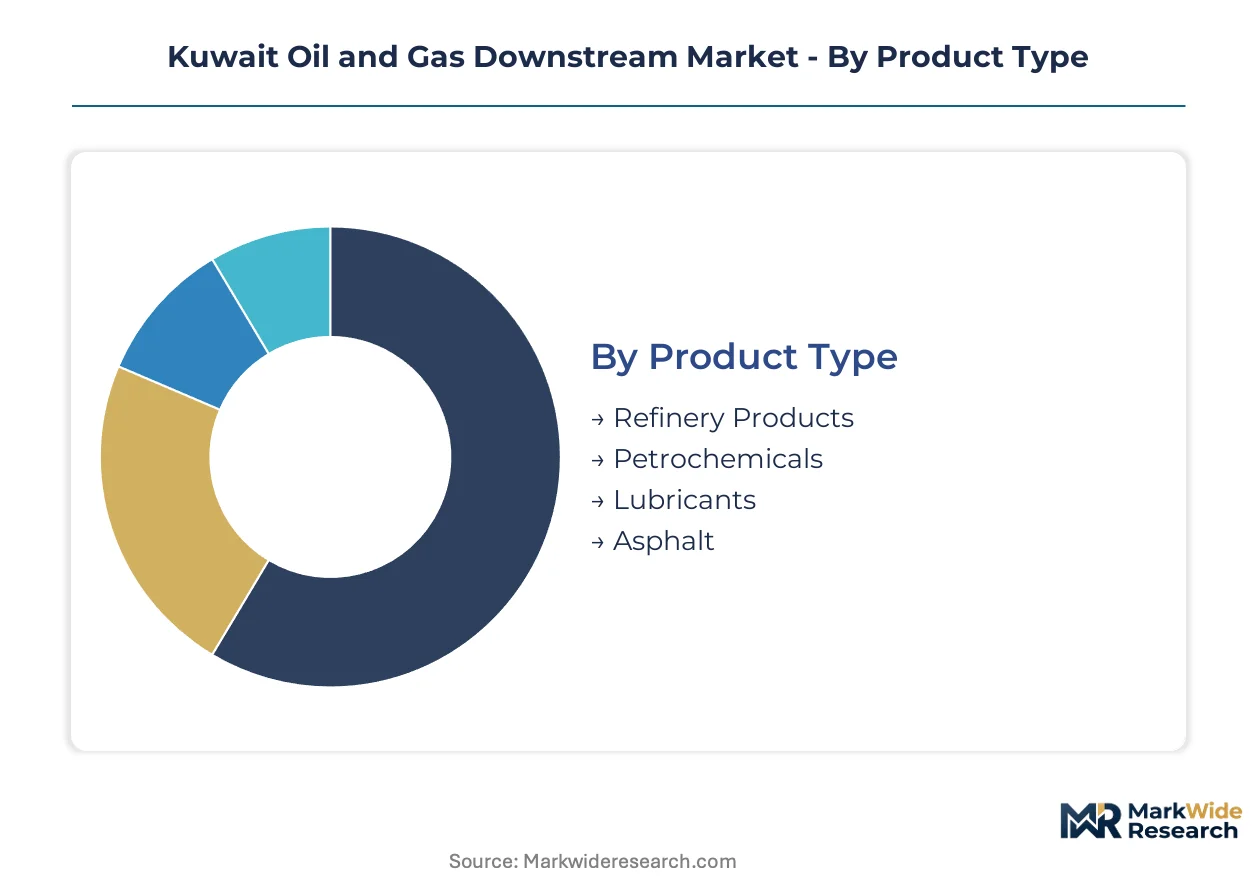
Segmentation in Kuwait's downstream market reveals how product specifications, customer procurement patterns, and service bundling create distinct margin pools. Each category exposes where Kuwait Petroleum Corporation's integrated operations concentrate value capture versus where third-party competition penetrates.
Product Type:
Mature refining operations anchor revenue while petrochemical conversion emerges as the margin expansion frontier across Kuwait's Al-Ahmadi industrial corridor.
- Refinery Products:Transportation fuels and fuel oils processed through hydrocracking and catalytic reforming units at Mina Abdullah and Al-Zour complexes. Demand concentrates in power generation offtake from the Ministry of Electricity and Water as the national grid diversifies fuel sources.
- Petrochemicals:Aromatics and olefins derived from naphtha cracking and residue conversion, with Petrochemical Industries Company expanding capacity to capture higher margins from polymer feedstock exports.
- Lubricants:Blended base oils and additives serving Kuwait's vehicle fleet and industrial machinery maintenance cycles through established distribution networks.
- Asphalt:Industrial-grade bitumen for domestic road construction and regional re-export markets, tied to Gulf infrastructure spending cycles.
Refinery products retain volume leadership; petrochemicals hold the steepest expansion curve.
End User:
Customer type determines pricing power, with industrial buyers commanding term contracts while automotive segments absorb retail premiums.
- Automotive:Retail fuel demand and lubricant consumption from Kuwait's passenger vehicle fleet, channeled through service station networks operated by Kuwait National Petroleum Company.
- Industrial:Manufacturing and process industries procuring diesel, fuel oil, and petrochemical feedstocks through annual tender structures rather than spot purchases.
- Commercial:Fleet operators and construction firms sourcing middle-distillate grades and asphalt through wholesale distributors in the Al-Ahmadi Governorate.
- Residential:LPG and heating fuel demand concentrated in northern Kuwait housing developments, served through cylinder distribution and piped gas infrastructure.
Industrial offtake dominates contract value; commercial segments are climbing the fastest as construction activity accelerates.
Distribution Channel:
Channel economics reflect captive infrastructure versus open-market access, with state-controlled wholesale networks limiting third-party penetration.
- Retail Outlets:Company-owned and franchised service stations across Kuwait's highway corridors and urban centers, capturing transportation fuel margins.
- Wholesale Distributors:Bulk fuel and petrochemical intermediates moved through integrated supply chains controlled by Kuwait National Petroleum Company, compressing independent trader access.
- Online Platforms:Emerging digital procurement for lubricants and specialty chemicals, particularly among small and mid-sized industrial buyers seeking price transparency.
- Direct Sales:Long-term supply agreements between refiners and major industrial consumers, including Ministry of Electricity and Water fuel oil contracts.
Wholesale distributors command throughput scale; online platforms are gaining share fastest among fragmented buyer bases.
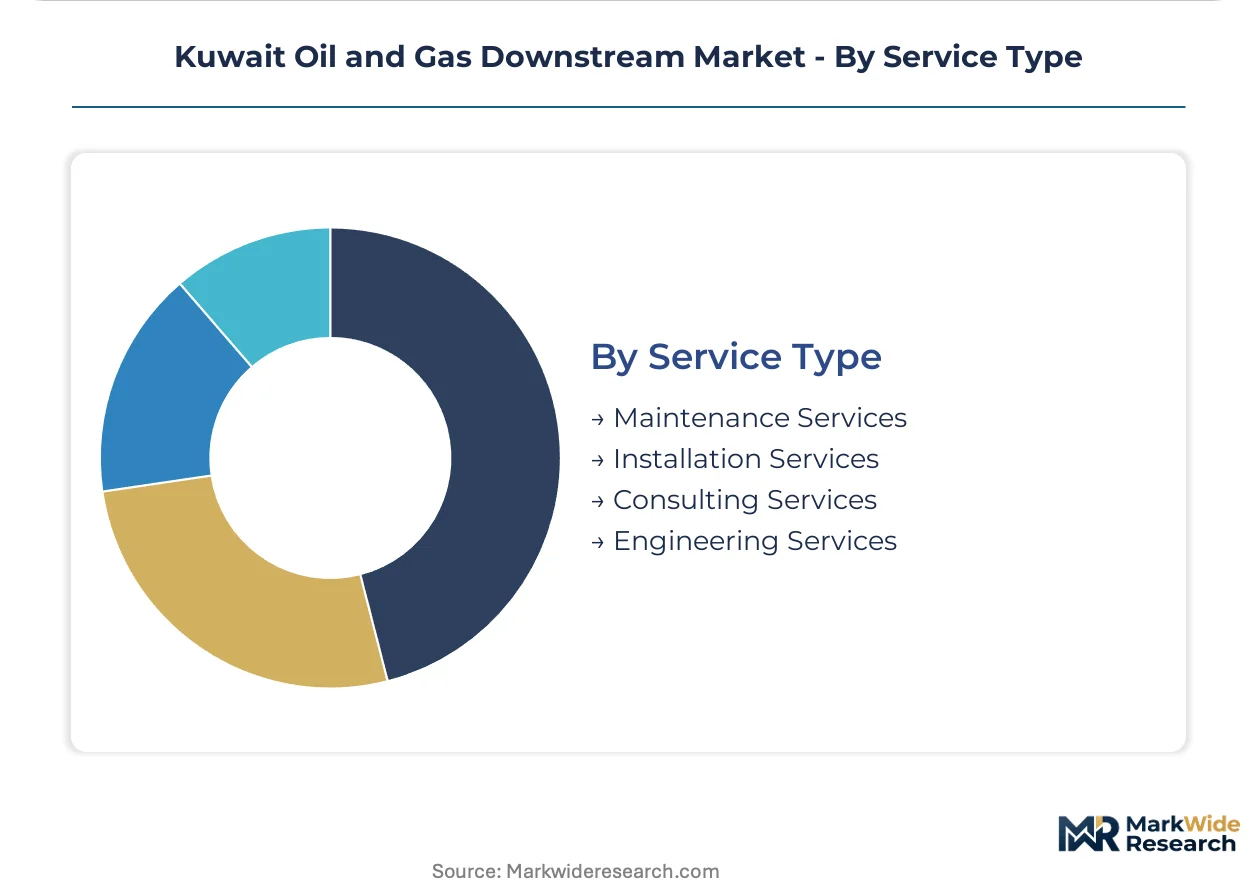
Service Type:
Service bundling creates stickiness in equipment-intensive segments where specialized engineering talent commands premium pricing.
- Maintenance Services:Turnaround management, catalyst replacement, and vessel inspection for hydroprocessing and sulfur recovery units, requiring scarce technical expertise concentrated among international contractors.
- Installation Services:New unit commissioning and emissions monitoring system deployment, driven by Kuwait Environment Public Authority flaring standards tightening across downstream assets.
- Consulting Services:Process optimization and regulatory compliance advisory, particularly for carbon capture integration and net-zero pathway planning under Kuwait Petroleum Corporation's 2040 strategy.
- Engineering Services:Front-end design and project management for refinery upgrades and petrochemical expansion, dominated by global EPC firms with local partnerships.
Maintenance services retain recurring revenue dominance; consulting services are expanding most quickly as decarbonization mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuwait Petroleum Corporation's 2040 strategy is redirecting capital toward petrochemical integration across the Al-Ahmadi Governorate industrial corridor. The Environment Public Authority's sulfur recovery mandates are forcing parallel hydroprocessing upgrades at legacy refinery assets. This policy-driven investment cycle is reshaping downstream capacity distribution across Kuwait's governorates.
Al-Ahmadi Governorate
Power generation diversification is pulling additional fuel oil offtake from the Mina Abdullah and Al-Zour refinery complexes into the national grid. The Environment Public Authority's flaring standards are tightening real-time emissions monitoring requirements across downstream units. The Al-Ahmadi industrial corridor concentrates Kuwait's refining and petrochemical capacity, where residue hydrocracking pilots are stretching heavy sour barrels into chemical feedstocks.
Al-Jahra Governorate
Residential LPG and heating fuel demand concentrates in northern Kuwait housing developments served through cylinder distribution networks. The Ministry of Oil's fuel quality specifications are shaping product slate decisions for northern supply infrastructure. Mina Al-Ahmadi's older units require retrofit capital to meet tightening sulfur recovery mandates, diverting maintenance resources from this region.
Hawalli Governorate
Retail fuel demand from Kuwait's densest passenger vehicle fleet channels through service station networks across urban highway corridors. The Environment Public Authority's net-zero 2050 pathway is accelerating carbon capture planning discussions for distributed assets. The governorate's commercial construction activity is climbing fastest, pulling middle-distillate grades and asphalt through wholesale distributors.
Al-Farwaniyah Governorate
Industrial buyers in manufacturing and process industries are consolidating fuel procurement through annual tender structures rather than spot purchases. Kuwait National Petroleum Company's integrated supply chain is absorbing this volume concentration. The governorate sits at the distribution nexus between Al-Ahmadi production assets and northern residential demand centers.
Mubarak Al-Kabeer Governorate
Emerging digital procurement platforms for lubricants and specialty chemicals are gaining traction among small and mid-sized industrial buyers seeking price transparency. The Ministry of Electricity and Water's long-term fuel oil contracts are bypassing spot market mechanisms entirely. The governorate's industrial zones are expanding as overflow capacity from the congested Al-Ahmadi corridor.
Kuwait Oil and Gas Downstream Market Competitive Landscape
On the supply side, the industry is consolidated around state-controlled integrated operators with limited third-party wholesale access. Kuwait National Petroleum Company dominates offtake through captive supply chains, compressing independent trader penetration. Two strategic archetypes define competitive positioning: integrated refinery-petrochemical operators leveraging feedstock synergies, and international joint venture partners contributing technology licensing for complex conversion units. Dominant competitive moves include capacity expansion at Al-Zour and strategic partnerships for carbon capture integration.
Within the state-controlled tier, Kuwait National Petroleum Company, Kuwait Integrated Petroleum Industries Company, and Petrochemical Industries Company anchor downstream operations. Kuwait National Petroleum Company exemplifies the integrated refinery operator archetype through its control of established distribution infrastructure. Kuwait Integrated Petroleum Industries Company occupies the high-conversion capacity position via the Al-Zour refinery's newbuild configuration. Petrochemical Industries Company represents the petrochemical integration vector, expanding aromatics capacity to capture polymer feedstock margins.
| Leading Market Players |
|---|
| Petrochemical Industries Company |
| Qurain Petrochemical Industries Company |
| Kuwait National Petroleum Company |
| BP |
| Total |
| Kuwait Integrated Petroleum Industries Company |
| Boubyan Petrochemical Company |
| Shell |
| Petrochemicals Industries Company |
| Others |
Supply & Pricing Matrix
Al-Ahmadi Governorate's concentrated refining and petrochemical capacity generates feedstock synergies that translate directly into pricing power for integrated operators controlling the Mina Abdullah and Al-Zour complexes. Kuwait National Petroleum Company's captive wholesale networks compress third-party trader margins while Environment Public Authority sulfur recovery mandates add compliance cost layers to product specifications.
Pricing Analysis
Certification level under Kuwait Environment Public Authority emissions standards creates the primary spread between compliant and non-compliant product grades. Contract-based long-term offtake dominates as industrial buyers consolidate procurement through annual tender structures with the Ministry of Electricity and Water. Price differentiation hinges on sulfur content grades and carbon intensity certifications, with hydroprocessed middle-distillates commanding premiums. Cost compression in fuel oil tiers is intensifying because power generation diversification pulls volume toward gas flexibility, making industrial buyers the most price-sensitive segment while direct state contracts show lowest sensitivity.
Supply Chain Analysis
Upstream heavy sour crude feedstock from Kuwait's Burgan and Ratqa fields anchors the entire downstream value chain, with gravity centers on domestic extraction rather than import dependency. The supply chain draws from captive crude production, specialized catalyst imports from the United States and Japan, and continuous emissions monitoring equipment from European suppliers. Single-source vulnerability concentrates in hydroprocessing catalyst supply, where technical specifications limit qualified vendors. Distribution runs through Kuwait National Petroleum Company's integrated wholesale infrastructure, with retail service stations and direct industrial offtake as downstream endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's downstream sector is approaching a platform-economics inflection where carbon capture integration and petrochemical feedstock interoperability will determine competitive survival. The Al-Zour refinery's newbuild configuration establishes the technical baseline for this ecosystem shift.
For Market Incumbents: Entrench control over Al-Ahmadi industrial corridor feedstock synergies by accelerating residue hydrocracking deployment at Mina Abdullah before international joint venture partners capture aromatics margin expansion. Prioritize backward integration into carbon capture unit operation to defend against emerging technology licensors positioning for enhanced oil recovery partnerships. Environment Public Authority compliance cost escalation represents the primary threat requiring continuous hydroprocessing investment. For New Entrants and Emerging Players: Digital procurement platforms for lubricants and specialty chemicals among small and mid-sized industrial buyers in Mubarak Al-Kabeer Governorate represent the most penetrable entry point. Target online channel development for fragmented buyer bases seeking price transparency outside Kuwait National Petroleum Company's wholesale concentration. A go-to-market angle anchored on emissions monitoring software-as-a-service bypasses capital-intensive asset ownership. For Investors and Strategic Acquirers: Carve-out targets emerge from international engineering contractors holding specialized process expertise for sulfur recovery and hydroprocessing unit operation. Long-term viability over the coming decade rests on positioning for Kuwait Petroleum Corporation's 2040 strategy execution, particularly petrochemical integration capex cycles. The signal to watch is Environment Public Authority mandate acceleration tightening product specifications faster than legacy asset retrofit timelines permit.| Strategic Initiative | Industry Significance |
|---|---|
| Residue Hydrocracking Deployment | Stretches heavy sour barrels into higher-margin aromatics at Mina Abdullah complex. |
| Carbon Capture Unit Integration | Supports Kuwait Petroleum Corporation's net-zero pathway while enabling enhanced oil recovery partnerships. |
| Digital Procurement Platform Launch | Captures fragmented industrial buyer demand outside Kuwait National Petroleum Company's wholesale control. |
| Aromatics Capacity Expansion | Leverages Al-Zour naphtha output for polymer feedstock export positioning. |
| Long-term Fuel Supply Agreement | Locks Ministry of Electricity and Water offtake amid power generation diversification. |
Research Methodology
A standing panel of refinery operations directors, petrochemical plant managers, Environment Public Authority compliance officers, and Ministry of Oil fuel specification engineers provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against customs and trade data, Kuwait Petroleum Corporation strategy disclosures, and international energy agency downstream capacity reports. Bottom-up unit economics modeling and top-down sector sizing triangulation ensured convergence across estimation approaches.
Scenario-bracketing around regulatory mandate timing and crude slate flexibility anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, distribution channel configuration, and service bundling complexity. CAGRs were derived from historical capacity utilization trends projected against announced capital expansion timelines, with specific inputs for sulfur recovery capex intensity and petrochemical margin expansion curves.
Practitioners should monitor Environment Public Authority enforcement acceleration and Kuwait Petroleum Corporation 2040 strategy milestone announcements for early signals requiring forecast revision. Cross-checking against International Energy Agency Middle East downstream capacity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Enhanced Oil Recovery Market