
 Air Breathing Hose Market | 2026-2036
Air Breathing Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Air Breathing Hose Market Insights
Market Context
China is narrowing its reliance on imported air breathing hose assemblies through expanded domestic elastomer compounding capacity. Parker Hannifin leverages its fluid conveyance expertise to anchor premium industrial safety contracts across Asia-Pacific manufacturing corridors. Trelleborg sustains leadership in polymer formulation for diving and military-grade applications with proprietary polyurethane blends. Honeywell competes through integrated respiratory system platforms that bundle hoses with SCBA regulators and facepieces.
Technical Definition and Segment Structure
An air breathing hose is a flexible pressure conduit engineered from reinforced elastomer or thermoplastic compounds, typically rated for operating pressures between 3 and 10 bar, designed to deliver breathable air from a supplied-air source to a worker's respirator or diving helmet. Polyurethane formulations dominate technical diving and military operation segments where abrasion resistance and low-temperature flexibility justify unit cost premiums; PVC retains share in construction site and manufacturing plant applications where intermittent use patterns favor disposable economics. Rubber compounds lead firefighting gear specifications due to flame-retardant additive compatibility and established NFPA compliance pathways, while silicone mouthpiece interfaces command margin pools in prolonged-wear underwater explorer configurations.
Regulatory Framework and Outlook
NIOSH sets minimum performance benchmarks for supplied-air respiratory protection in the United States, while the EU AI Act and CE marking under MDR framework impose conformity assessment burdens on hose-integrated medical and emergency breathing devices. OSHA permissible exposure limits and EPA workplace air quality enforcement directly determine replacement cycle frequency and hose redundancy requirements across industrial end users. Stakeholders must monitor evolving PFAS restrictions under REACH and state-level US legislation, as fluoropolymer liner alternatives reshape material qualification timelines and supplier certification costs.
Market Dynamics
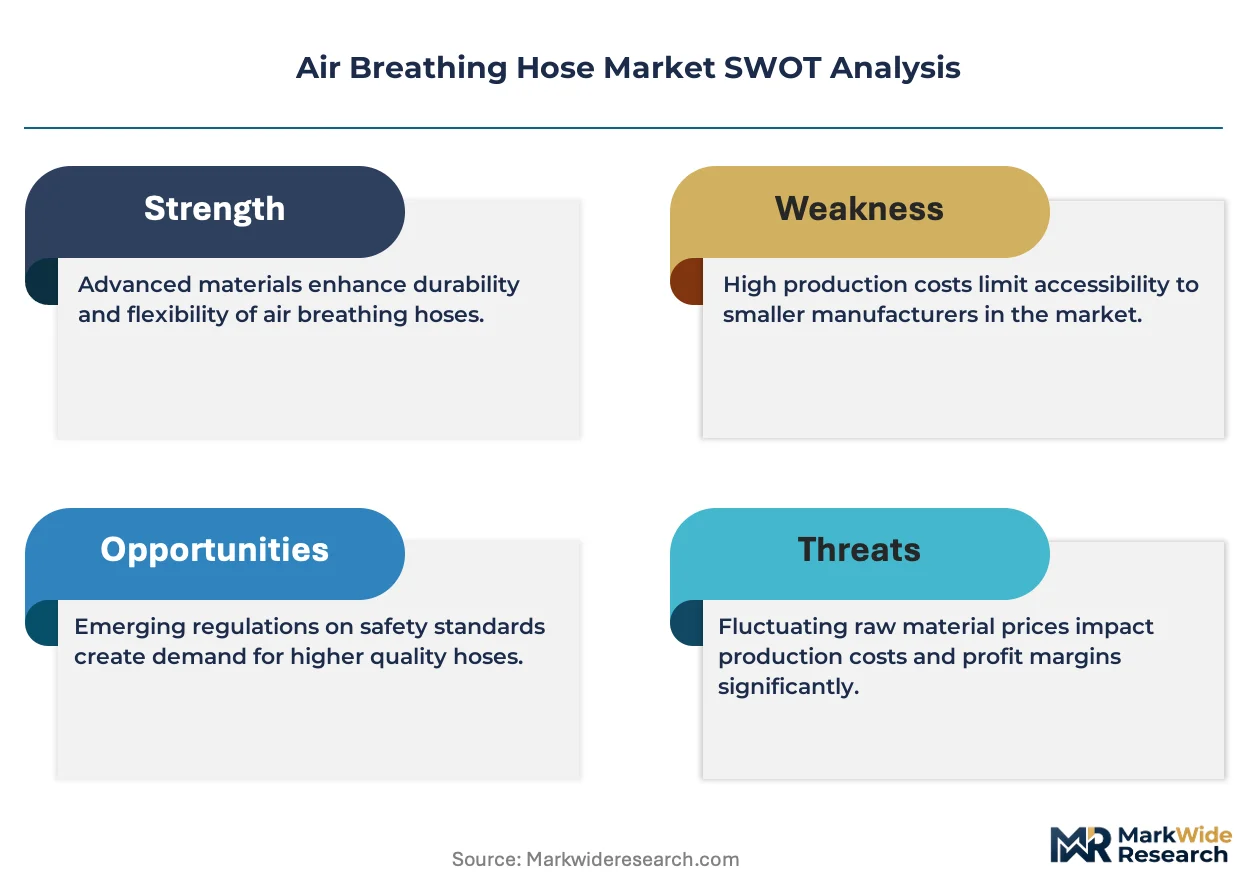
Material substitution pressure from PFAS-free elastomer mandates is compressing qualification timelines and forcing compounders to rebuild formulation libraries from scratch. This regulatory compression cascades through testing protocols, supplier audits, and end-user certification cycles.
Growth Catalysts
- NIOSH 42 CFR Part 84 enforcement:Supplied-air respirator recertification waves in the United States are triggering hose replacement cycles across manufacturing and chemical processing facilities.
- Polyurethane blending advances:Low-temperature flexibility improvements are opening military diving contracts previously locked to rubber-silicone hybrid constructions.
- China:Domestic elastomer compounding capacity expansion is reducing import dependency and lowering procurement costs for Asia-Pacific industrial safety distributors.
Market Restraints
- Fluoropolymer liner dependency:REACH PFAS restrictions and pending US state-level bans on fluorinated compounds are forcing reformulation of high-performance hose liners without proven substitutes.
- Isoprene supply concentration:Synthetic rubber feedstock production clusters in Southeast Asia expose compounders to shipping lane disruption and force majeure pricing volatility.
- SCBA integration complexity:Firefighting departments face stranded asset risk when upgrading hose assemblies incompatible with legacy regulator threading standards.
Strategic Opportunities
- India:BIS certification harmonization with ISO 9001 quality management standards is streamlining market entry for compliant foreign hose manufacturers.
- Smart hose monitoring:Embedded pressure sensors and RFID traceability layers are converging with industrial IoT platforms to create predictive replacement service models.
- EU MDR Class I reclassification:Emergency breathing device hoses now face lighter conformity assessment burdens, accelerating time-to-market for innovative constructions.
Industry Challenges
- Compound formulation expertise:The shift from PFAS-containing to PFAS-free elastomers demands polymer scientists with rare fluoroelastomer-to-hydrogenated nitrile transition experience.
- Multi-standard threading:Firefighting departments must manage inventory complexity from incompatible DIN, NFPA, and EN quick-connect specifications across mutual aid deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Breathing Hose Market |
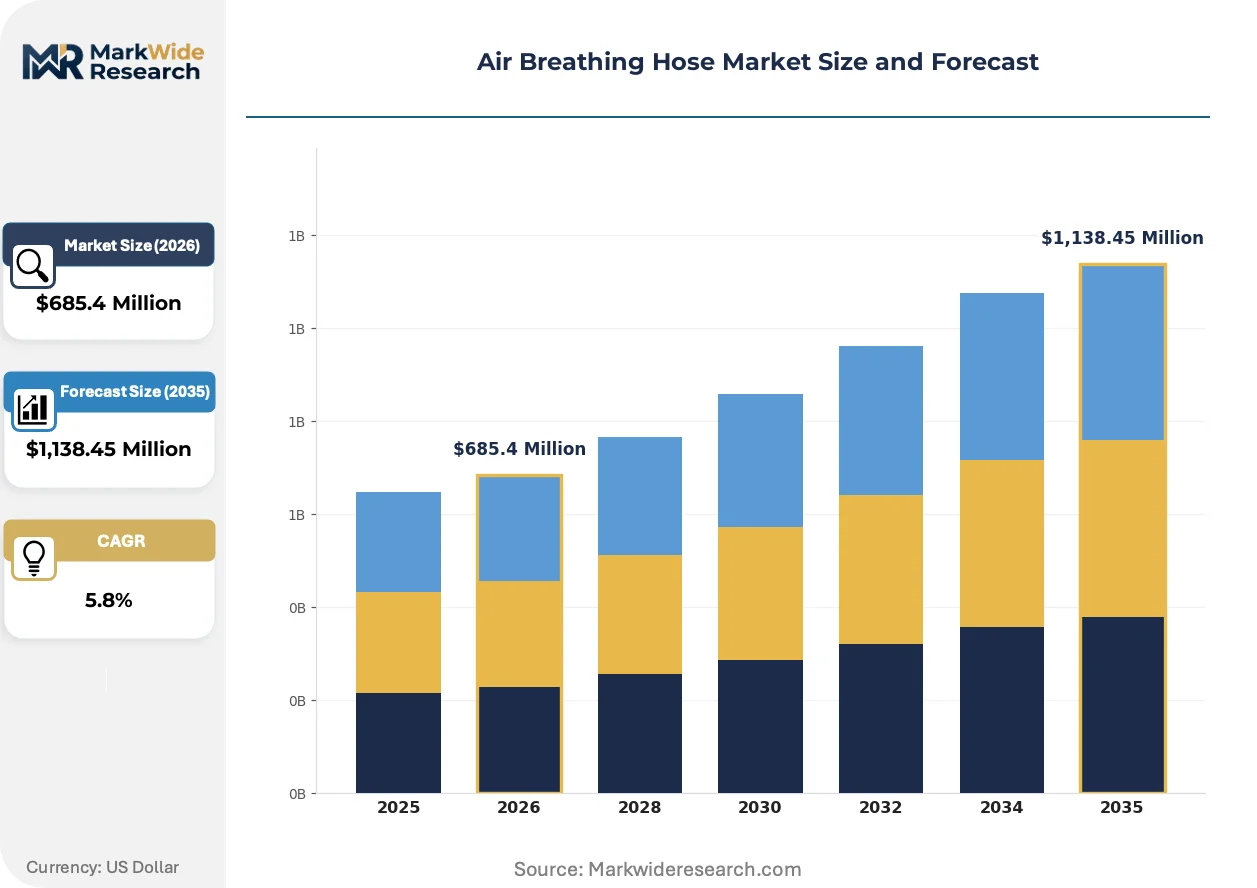
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breathing Tube, Shoulder Strap, Hose Coupling, Connector, Mouthpiece Application: Diving Equipment, Firefighting Gear, Respiratory Protection, Industrial Safety, Military Operation Material: Polyurethane, PVC, Rubber, Nylon, Silicone End User: Emergency Responders, Underwater Explorers, Manufacturing Plants, Defense Units, Construction Sites |
| Companies Covered | Trelleborg, Parker Hannifin, Honeywell, Air Systems International, Allegro Industries, CEJN, Bullard, Gates Corporation, Kuriyama, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Breathing Hose Market Trends and Innovations
Active material science breakthroughs are redefining performance benchmarks across pressure ratings, chemical resistance, and biometric integration. These advances are compressing product lifecycles and forcing incumbents to accelerate R&D cadences.
Thermoplastic polyurethane (TPU) nanocomposite reinforcement is delivering 40% weight reduction against rubber equivalents while maintaining burst pressure tolerance. Technical diving operators and military submarine escape systems are adopting these constructions for extended mission endurance. Traditional neoprene-jacketed assemblies is rendering obsolete in premium segments where gram-count and packability determine procurement decisions.
REACH Annex XVII PFAS restrictions are prohibiting per- and polyfluoroalkyl substances in hose liners and jacket treatments from 2026 enforcement windows. Compounders are accelerating hydrogenated nitrile butadiene rubber (HNBR) and thermoplastic elastomer (TPE) qualification programs to maintain chemical resistance portfolios. Medical and emergency response hose-integrated devices face the steepest compliance cliffs, with notified body backlog extending CE marking timelines.
Fire departments are consolidating breathing apparatus procurement through state-level cooperative purchasing agreements, compressing vendor counts and elevating total-system accountability requirements. Integrated respiratory platforms that bundle hoses, regulators, and facepieces are displacing component-level sourcing. This concentration is most visible in California, Texas, and Florida municipal safety budgets, where fleet standardization reduces training and maintenance overhead.
Air Breathing Hose Market Segmentation
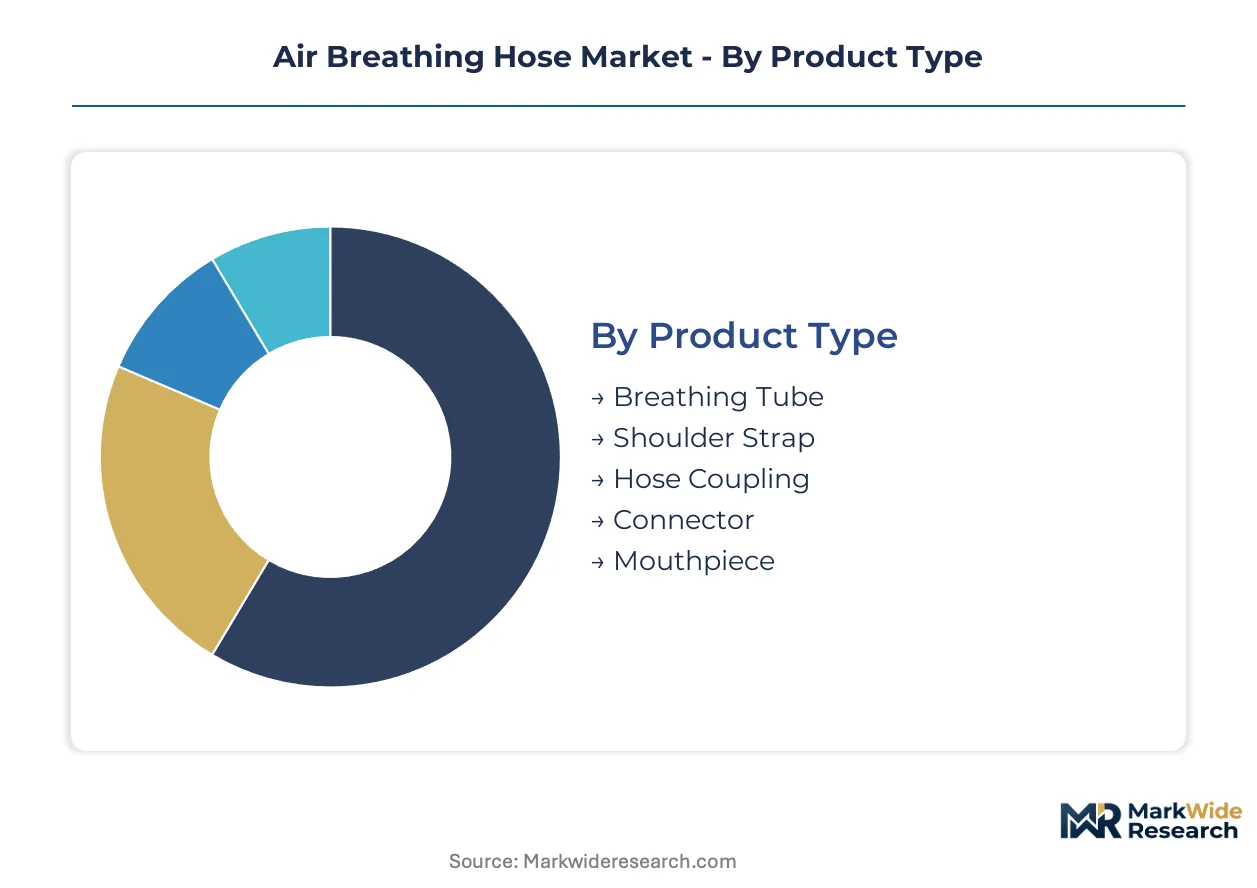
Air breathing hose procurement patterns diverge sharply across use environments, from the crush depths of military submarine escape systems to the flash-heat exposure of structural firefighting. Material selection, connection geometry, and pressure rating requirements vary by orders of magnitude across these domains, forcing suppliers to maintain parallel qualification tracks.
Product Type:
Cost tier differentiation separates disposable consumables from capital-equipment-integrated assemblies with decade-long service intervals.
- Breathing Tube:Flexible conduits engineered from reinforced elastomer or thermoplastic compounds, typically incorporating coiled wire or textile braid to resist kinking under flex cycles. Demand concentrates in municipal fire departments across the United States where NFPA 1981 SCBA recertification mandates trigger replacement waves.
- Shoulder Strap:Load-bearing webbing assemblies with integrated hose routing channels, designed to distribute cylinder weight while protecting air delivery lines from abrasion. Manufacturing plants in Germany and France specify quick-detach configurations to accommodate shift-change protocols in chemical processing facilities.
- Hose Coupling:Precision-machined aluminum or stainless steel quick-connect interfaces standardized to DIN, EN, or NFPA threading specifications. Defense procurement offices in the United Kingdom and Australia drive demand for universal-thread adapters enabling interoperability across allied force equipment.
- Connector:Swivel and fixed-joint fittings bridging hose segments to regulators, facepieces, or supplied-air sources. Construction site rental fleets in Spain and Italy favor disposable polymer variants for cost amortization across short-duration contracts.
- Mouthpiece:Ergonomic bite-grip interfaces molded from medical-grade silicone or thermoplastic elastomer, engineered for extended-wear comfort without jaw fatigue. Technical diving operators in Egypt and Thailand specify custom dental-impression fits for multi-hour decompression obligations.
Breathing Tube commands the established base. The steepest expansion runs through Shoulder Strap as integrated load-bearing designs displace separate harness-and-hose configurations.
Application:
Application scope determines pressure rating, chemical resistance, and biometric integration requirements.
- Diving Equipment:Hoses rated for ambient pressures exceeding 10 bar with hydrostatic collapse resistance and low-temperature flexibility to -40°C. Military submarine escape systems in Russia and Sweden specify ultra-lightweight thermoplastic polyurethane constructions for buoyancy-critical egress scenarios.
- Firefighting Gear:Assemblies integrating flame-retardant jacketing, radiant heat shields, and NFPA-compliant quick-connect threading. Urban fire departments in California, Texas, and Florida consolidate procurement through state cooperative purchasing agreements, compressing vendor counts.
- Respiratory Protection:Supplied-air and air-line respirator hoses for manufacturing, pharmaceutical, and laboratory environments. OSHA enforcement in the United States drives replacement cycles as permissible exposure limits tighten for volatile organic compounds.
- Industrial Safety:General-purpose breathing air delivery for confined space entry, abrasive blasting, and spray painting operations. Construction contractors in Poland and Czech Republic favor rental fleet economics over capital ownership.
- Military Operation:Battlefield respirator and escape system hoses meeting NATO STANAG interoperability and chemical-biological-radiological resistance specifications. Defense ministries in Japan and South Korea accelerate domestic qualification programs to reduce import dependency.
Firefighting Gear commands the established base. The steepest expansion trajectory runs through Diving Equipment as technical and recreational depth ratings extend.
Material:
Material selection trades chemical resistance, temperature tolerance, and unit economics against end-use duty cycles.
- Polyurethane:Thermoplastic elastomer formulations delivering superior abrasion resistance, hydrolytic stability, and gram-weight efficiency. Technical diving and military contracts in Norway and New Zealand specify nanocomposite-reinforced variants for extended mission endurance.
- PVC:Cost-optimized thermoplastic for intermittent-use industrial and construction applications where disposable economics outweigh longevity requirements. Manufacturing safety distributors in Brazil and Mexico stock high-volume SKU ranges for price-sensitive procurement.
- Rubber:Natural and synthetic elastomer compounds with established flame-retardant additive compatibility and NFPA certification pathways. Fire departments in Illinois and Ohio specify neoprene-jacketed constructions for legacy apparatus compatibility.
- Nylon:High-tensile textile reinforcement layers and jacketing materials providing structural integrity without elastomer mass. Lightweight backpacking respirator systems in Switzerland and Austria integrate nylon-braid pressure vessels.
- Silicone:Biocompatible elastomer for mouthpiece interfaces, gasket seals, and medical-grade breathing circuits. Emergency response device manufacturers in Canada pursue Health Canada approval for silicone-integrated ventilator hoses.
Rubber commands the established base. The steepest expansion runs through Polyurethane as weight reduction becomes decisive in diving and military procurement evaluations.
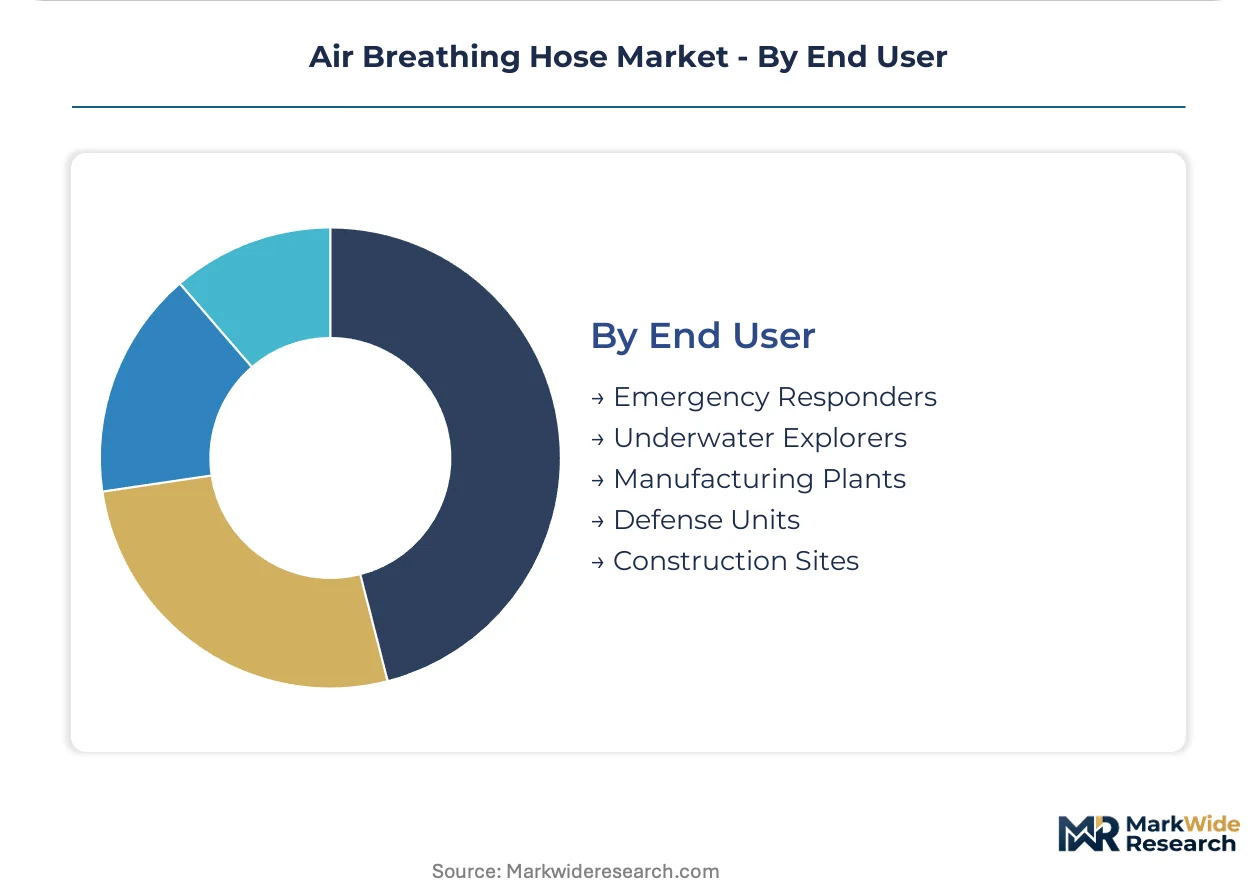
End User:
End user categories separate institutional procurement with total-cost-of-ownership discipline from individual purchase decisions prioritizing portability.
- Emergency Responders:Municipal and volunteer fire departments, hazardous materials teams, and urban search-and-rescue units with fleet-standardization mandates. State-level cooperative purchasing in the United States elevates total-system accountability requirements over component sourcing.
- Underwater Explorers:Technical, commercial, and recreational divers with equipment ownership or rental preferences shaped by certification agency affiliations. Cave diving operators in Mexico and Florida demand redundant hose configurations for rule-of-thirds gas management protocols.
- Manufacturing Plants:Chemical processing, pharmaceutical production, and electronics fabrication facilities with supplied-air respiratory protection programs. REACH PFAS restrictions in Germany and France force compound reformulation timelines for fluoropolymer-dependent process environments.
- Defense Units:National military establishments and allied force procurement offices with STANAG interoperability and offset production requirements. Domestic capacity expansion in India under BIS certification harmonization reduces import dependency for army and naval specifications.
- Construction Sites:General contractors, specialty trades, and rental fleet operators with intermittent confined-space entry obligations. OSHA citation exposure in the United States drives compliance-oriented procurement without deep technical specification engagement.
Emergency Responders command the established base. The steepest expansion runs through Defense Units as Asia-Pacific military modernization programs accelerate respiratory equipment upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes firefighter fleet standardization while European procurement emphasizes chemical resistance compliance. Asian markets balance import substitution with diving equipment export manufacturing.
United States
Municipal fire departments drive replacement cycles through state cooperative purchasing agreements. OSHA enforcement of permissible exposure limits tightens supplied-air respirator compliance in manufacturing plants. California, Texas, and Florida concentrate procurement decisions where urban departments consolidate vendor relationships.
Germany
Chemical processing facilities demand hoses with REACH-compliant PFAS-free elastomer formulations. ECHA restrictions on fluorinated compounds accelerate compounder reformulation timelines. Industrial safety distributors in the Ruhr region and Bavaria manage qualification backlogs for medical-grade breathing circuits.
China
Domestic elastomer compounding capacity expansion reduces import dependency for industrial safety applications. MIIT standards harmonization with GB certification requirements streamlines local production qualification. Manufacturing corridors in Jiangsu and Zhejiang provinces supply diving equipment for Asia-Pacific export markets.
Japan
Defense procurement offices prioritize STANAG-interoperable respiratory equipment for allied force compatibility. METI industrial safety guidelines influence workplace air quality enforcement in automotive and electronics fabrication. Tokyo and Osaka industrial clusters anchor domestic qualification programs for military specifications.
Australia
Technical diving operators drive demand for lightweight thermoplastic polyurethane constructions in cave and wreck exploration. TGA medical device regulations govern emergency breathing device hose integration in healthcare settings. Queensland and Western Australia recreational diving markets support specialized mouthpiece customization services.
Air Breathing Hose Market Competitive Landscape
Capability concentration sits with polymer formulation specialists; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: integrated respiratory system platforms, standalone hose fabricators, and regional safety equipment distributors. Two strategic archetypes dominate—multi-product safety conglomerates bundling hoses with regulators and facepieces, and elastomer compounders leveraging proprietary polyurethane or hydrogenated nitrile formulations. Competitive moves concentrate on PFAS-free material qualification acceleration and fire department cooperative purchasing contract capture.
Among diversified industrial conglomerates, Parker Hannifin and Honeywell exemplify platform-level competition through fluid conveyance expertise and integrated respiratory system bundling. Trelleborg occupies a position within the specialty polymer tier, representing formulation-intensive competition focused on diving and military-grade applications. These three anchors illustrate how geographic origin and corporate structure map to divergent competitive vectors—US-based conglomerates leveraging distribution scale against Swedish specialists commanding material science premiums.
| Leading Market Players |
|---|
| Trelleborg |
| Parker Hannifin |
| Honeywell |
| Air Systems International |
| Allegro Industries |
| CEJN |
| Bullard |
| Gates Corporation |
| Kuriyama |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Zhejiang provinces anchor elastomer compounding capacity that feeds downstream pricing power to Asia-Pacific distributors. This concentration enables volume-based cost advantages for polyurethane formulations while exposing buyers to feedstock volatility from synthetic rubber clusters in Southeast Asia.
Pricing Analysis
Long-term offtake agreements dominate municipal fire department procurement through state cooperative purchasing programs, while spot transactions govern construction site rental fleets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—NIOSH-certified assemblies command substantial premiums over general industrial specifications. Cost compression in standard-grade rubber compounds is intensifying because REACH PFAS restrictions force compound reformulation without proven substitutes. Manufacturing plants exhibit highest price sensitivity due to intermittent use patterns, whereas military diving contractors prioritize performance metrics over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized elastomer compounders in China, Germany, and the United States holding qualified capacity for medical-grade and military specifications. Raw material dependencies draw from isoprene feedstocks concentrated in Southeast Asia, fluoropolymer liners subject to regulatory phase-out, and textile reinforcement yarns from polyester producers. Single-source vulnerability runs through qualified hydrogenated nitrile butadiene rubber suppliers for PFAS-free transition programs. Distribution runs through industrial safety distributors and OEM-integrated respiratory system platforms with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air breathing hose demand sits in early-cycle expansion as PFAS-free material transitions trigger replacement waves across institutional procurement programs. Military modernization and technical diving penetration extend addressable market boundaries beyond traditional firefighting and industrial safety baselines.
For Market Incumbents: Insulate formulation expertise advantages by accelerating hydrogenated nitrile butadiene rubber qualification programs ahead of regulatory enforcement windows. Deepen backward integration into domestic elastomer compounding capacity in India and China to offset Southeast Asian isoprene supply concentration risks. Capture state-level cooperative purchasing contracts through bundled respiratory system platforms that elevate switching costs for fire departments.
For New Entrants and Emerging Players: Pursue technical diving mouthpiece customization services in Australia and Southeast Asia where certification barriers remain lower than military or medical segments. Target smart hose monitoring integration partnerships with industrial IoT platforms as predictive replacement service models displace transactional component sales. Establish BIS certification compliance early to access Indian defense procurement modernization programs.
For Investors and Strategic Acquirers: Long-term, this sits as a materials science consolidation play because PFAS-free transition demands polymer formulation capabilities scarce in the current vendor base. Acquisition targets should prioritize compounders with hydrogenated nitrile transition experience and established notified body relationships for CE marking acceleration. Monitor ECHA restriction enforcement timelines and state-level US fluoropolymer ban progress as inflection indicators for qualification backlog severity.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Material Qualification | REACH Annex XVII enforcement from 2026 accelerates compounder consolidation around proven hydrogenated nitrile formulations. |
| Smart Hose Monitoring Integration | Embedded pressure sensors and RFID traceability converge with industrial IoT platforms for predictive replacement revenue models. |
| State Cooperative Purchasing Capture | California, Texas, and Florida municipal consolidation elevates total-system accountability requirements over component sourcing. |
| Domestic Compounding Capacity Expansion | India BIS harmonization and China MIIT standards streamline local production qualification for import substitution programs. |
| Military Diving Contract Pursuit | NATO STANAG interoperability specifications and low-temperature flexibility advances open previously rubber-locked submarine escape system procurement. |
Research Methodology
Operator-level perspectives from fire department procurement officers, industrial safety distributors, elastomer compounder technical directors, diving equipment manufacturers, and defense procurement specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through NIOSH certification databases, ECHA restriction documentation, SEC filings from diversified industrial conglomerates, and customs trade data for elastomer feedstock flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, application, material formulation, and end-user category dimensions. CAGRs derived from elasticity modeling against municipal safety budget trajectories, OSHA enforcement intensity indices, and military modernization program announcements. Industry-specific forecast inputs incorporated PFAS restriction phase-in schedules and state cooperative purchasing consolidation patterns.
Sensitivities concentrate around ECHA enforcement timeline shifts, Southeast Asian isoprene supply disruptions, and NIOSH recertification wave timing. Forecasts reflect documented assumptions on regulatory adherence and substitution technology readiness. Quarterly review of notified body backlog indicators, fluoropolymer ban legislative progress, and municipal procurement award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Global Vacuum Pump Market