
 Europe Centrifugal Compressor Market | 2026-2036
Europe Centrifugal Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Centrifugal Compressor Market Foresight
A shortage of turbomachinery engineers with magnetic bearing expertise is rotating toward the critical path for European OEM delivery schedules. Siemens Energy leverages its Berlin manufacturing footprint to sustain long-term service contracts across German chemical processing sites. MAN Energy Solutions SE anchors high-capacity compressor development for North Sea carbon capture and storage projects. Atlas Copco Ltd competes through oil-free technology leadership in food-grade and pharmaceutical compressed air applications.
Europe centrifugal compressors are dynamic turbomachines that accelerate gas through an impeller to convert kinetic energy into pressure rise, typically achieving discharge pressures from 1 bar to over 200 bar depending on stage configuration and aerodynamic design. Their primary industrial purpose is continuous-flow gas compression for process industries, power generation, and pipeline transmission where pulsation-free operation and high reliability are mandatory. Oil-free product types command premium positioning due to zero-contamination requirements in pharmaceutical manufacturing and food processing end users. Magnetic bearing technology is displacing conventional oil-lubricated systems in power generation and chemical processing applications where maintenance access is constrained. Multi-stage configurations dominate high-capacity segments for oil and gas transmission, while single-stage units occupy lower-pressure manufacturing and general industrial roles.
EMA machinery safety directives, EU F-Gas Regulation phase-down schedules, and REACH chemical compliance frameworks collectively shape compressor material selection, sealing technology, and aftermarket refrigerant handling protocols across European member states. CE marking requirements enforce harmonized safety standards that filter non-compliant suppliers from industrial procurement channels. Stakeholders must monitor hydrogen blending specifications in pipeline codes and emerging carbon border adjustment mechanisms that will reshape total cost of ownership calculations for imported versus domestically manufactured compressor packages.
Market Dynamics
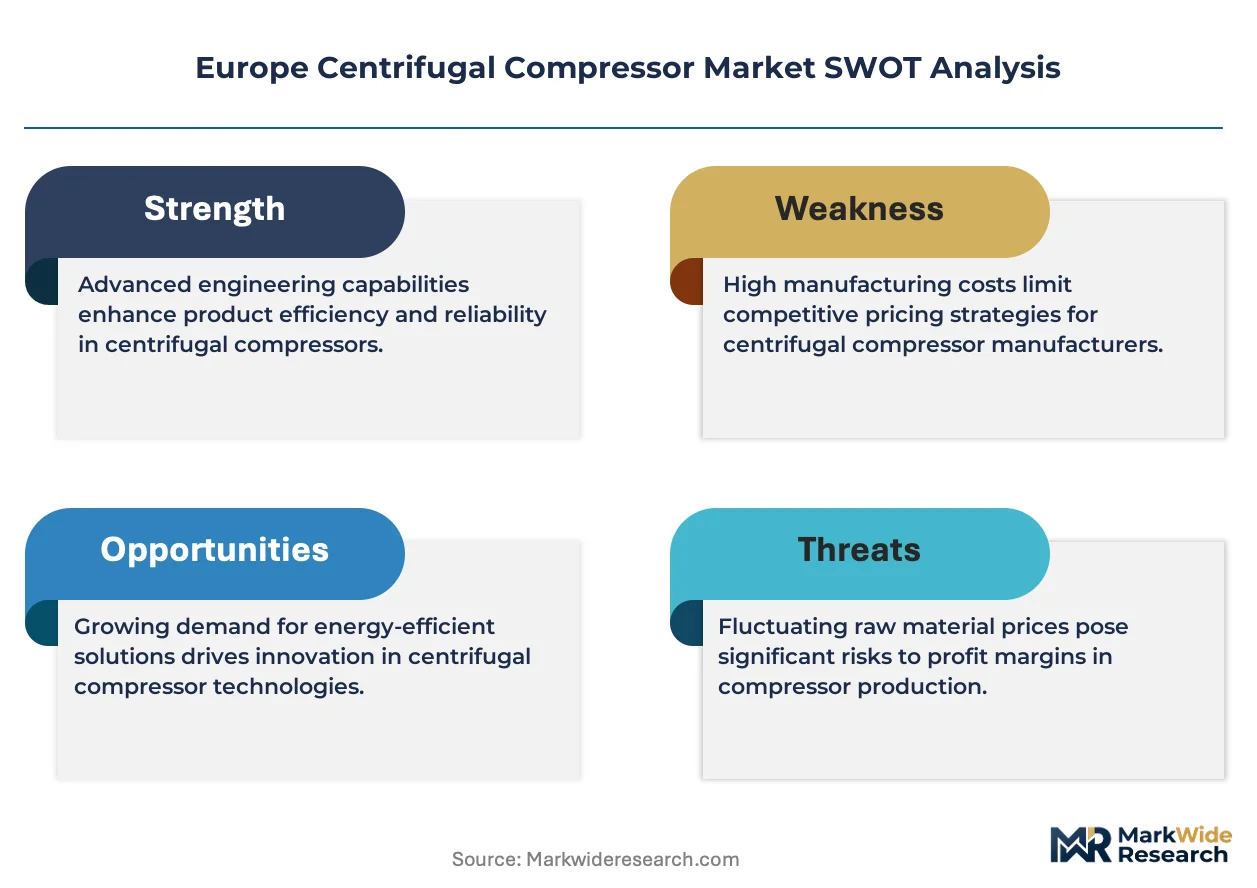
The EU F-Gas Regulation phase-down is compressing demand toward oil-free compressor architectures, forcing OEMs to eliminate fluorinated refrigerant systems from their European product portfolios entirely.
Growth Catalysts
- Biomethane Integration Mandates:Compressed natural gas infrastructure operators across Germany and the Netherlands are expanding centrifugal compressor fleets to handle renewable gas blending requirements in pipeline networks.
- REACH Compliance Frameworks:Chemical processing sites in Belgium and France are retrofitting sealing systems to eliminate hazardous substance leakage, accelerating demand for advanced compressor materials.
- North Sea Carbon Capture:Norwegian and UK offshore platforms are deploying high-capacity multi-stage units for carbon dioxide injection and enhanced oil recovery operations.
Market Restraints
- Specialized Engineering Talent Scarcity:Magnetic bearing expertise sits at critical shortage levels across European turbomachinery labor pools, extending OEM delivery timelines by months.
- Raw Material Concentration Risk:Rare earth magnet supply chains concentrate in Asian processing facilities, exposing European manufacturers to input cost volatility and geopolitical disruption.
- Technical Integration Barriers:Legacy pipeline infrastructure in Eastern Europe lacks instrumentation compatibility with digital compressor monitoring systems, slowing smart technology deployment.
Strategic Opportunities
- Hydrogen Pipeline Readiness:Polish and Czech industrial clusters are pre-positioning compressor specifications for pure hydrogen transmission, creating first-mover equipment installation windows.
- Pharmaceutical Clean Air Demand:Irish and Swiss drug manufacturing facilities are specifying oil-free units with integrated contamination monitoring for sterile process environments.
- EMA Machinery Safety Directives:Updated CE marking requirements for functional safety are filtering non-compliant suppliers from procurement channels, consolidating viable vendor pools.
Industry Challenges
- Certification Timeline Compression:ATEX and PED compliance documentation for hydrogen service applications requires extended validation cycles that delay project commissioning.
- Cross-Border Supply Reconfiguration:Carbon border adjustment mechanism preparations are forcing compressor packagers to requalify steel casting and forging suppliers across multiple member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Centrifugal Compressor Market |
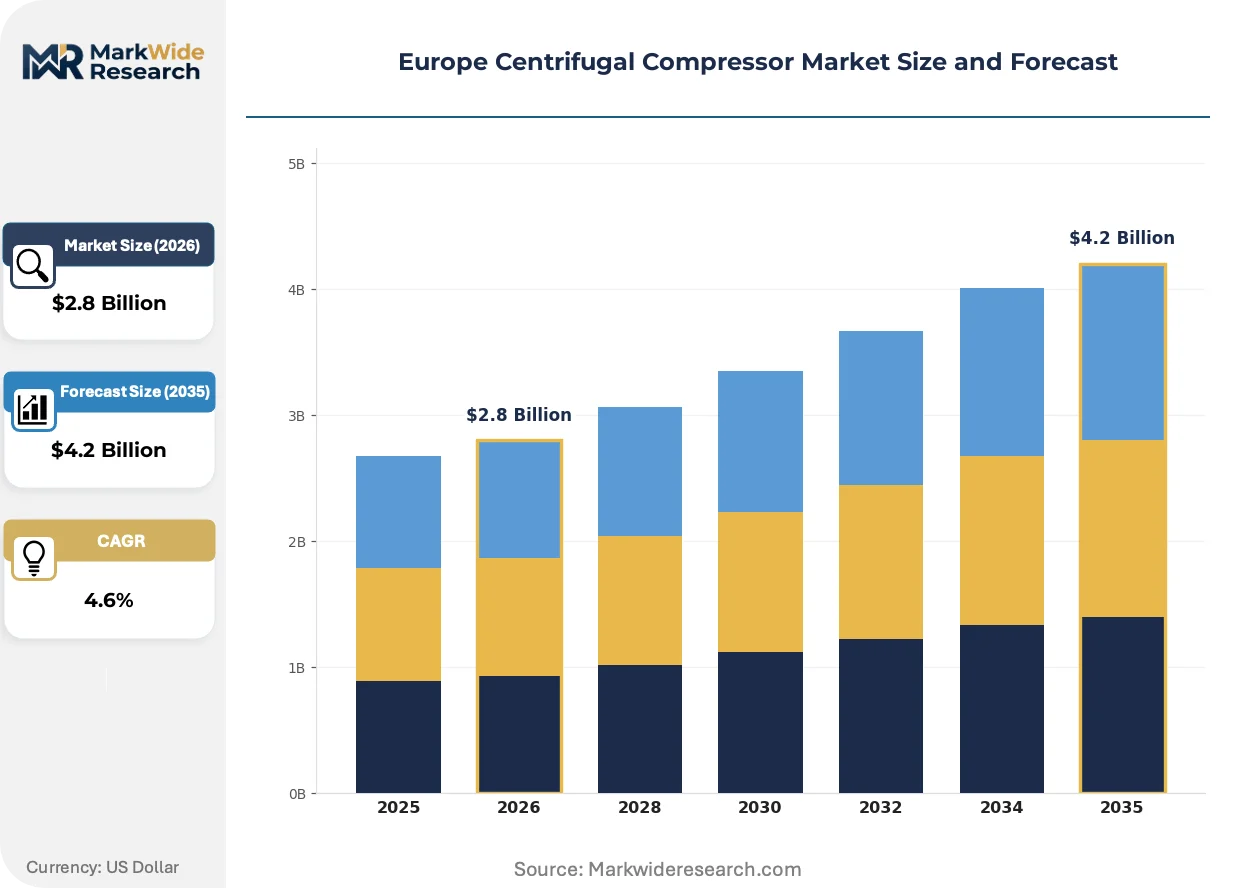
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage, Multi-stage, Oil-injected, Oil-free End User: Manufacturing, Oil & Gas, Power Generation, Chemical Processing Technology: Magnetic Bearing, Variable Speed Drive, Aerodynamic Design, Control Systems Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Capacity |
| Companies Covered | Atlas Copco Ltd, Ingersoll-Rand plc, BAUER Compressors Inc, Hitachi Ltd., Gardner Denver Holdings Inc., Siemens Energy, MAN Energy Solutions SE, Howden Group Ltd., Baker Hughes Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Centrifugal Compressor Market Shifts & Advancements
Active magnetic bearing systems are compressing maintenance intervals and enabling unmanned compressor operation in remote North Sea installations, reshaping operational economics for offshore operators.
Magnetic bearing technology is miniaturizing auxiliary equipment footprints while eliminating oil contamination risks entirely. Food-grade processors in Denmark and pharmaceutical manufacturers in Ireland are adopting these systems at accelerated procurement cycles. The technology is miniaturizing package dimensions for skid-mounted installations, reducing civil works costs and enabling faster site deployment.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon refrigerants in new compressor cooling systems from 2027, forcing OEMs to redesign thermal management architectures. Industrial refrigeration users in Germany and France face accelerated retrofit timelines. Chemical processing sites are responding by specifying air-cooled alternatives and ammonia-based systems for large-capacity applications.
Aftermarket service unbundling is separating maintenance contracts from original equipment procurement, enabling third-party specialists to capture long-term revenue streams. Power generation operators in Spain and Italy are fragmenting vendor relationships, sourcing spare rotors and bearings from independent suppliers. This pattern is most visible in combined-cycle gas turbine auxiliary systems where operational data transparency has eroded OEM information advantages.
Europe Centrifugal Compressor Market Segmentation
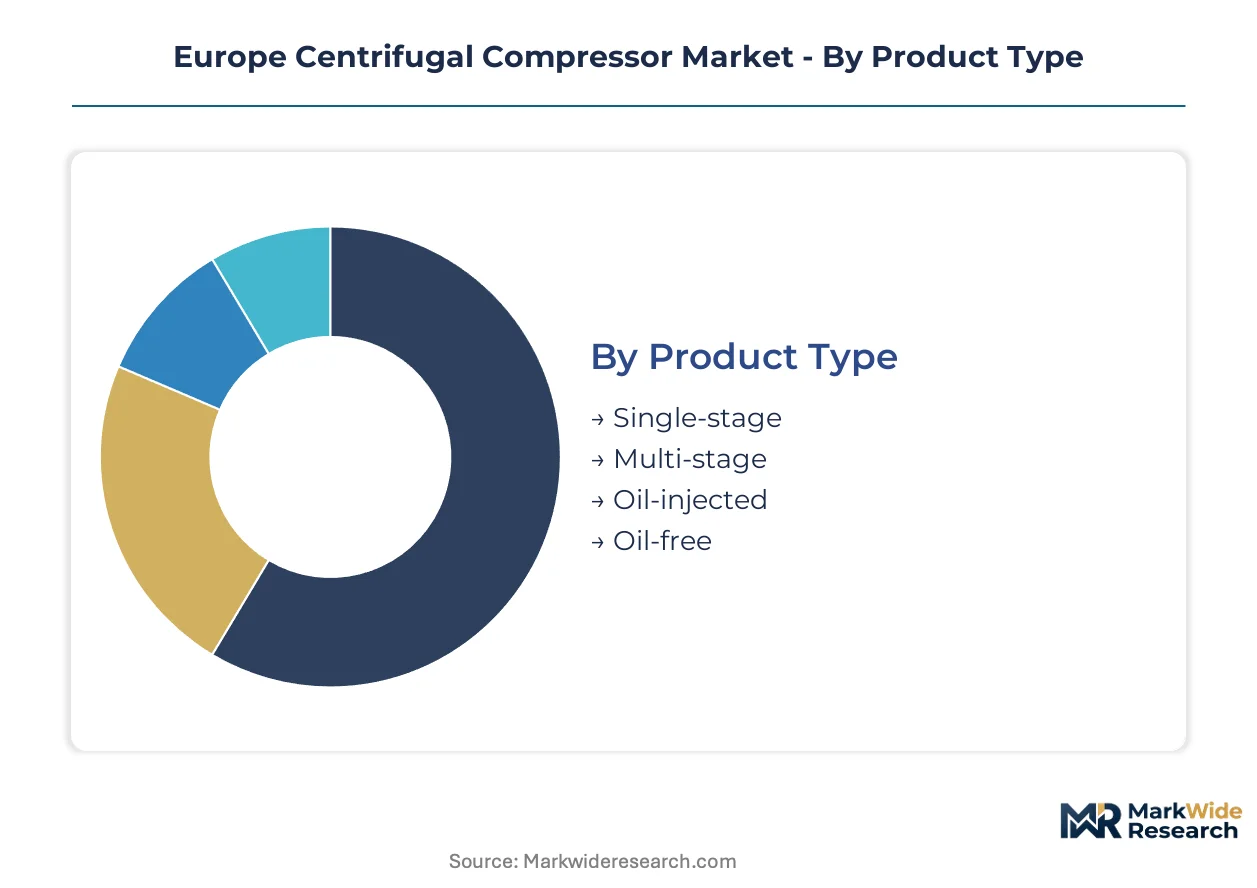
Centrifugal compressor procurement patterns diverge sharply across European industrial clusters. Product specifications, technology preferences, and capacity requirements track closely with end-use regulatory exposure and site-specific operational constraints.
Product Type:
Single-stage configurations dominate domestic manufacturing demand across Germany and France, while multi-stage systems anchor export-led project business into North Sea energy infrastructure.
- Multi-stage:These units stack impeller stages in series to achieve discharge pressures exceeding 200 bar for pipeline transmission and underground gas storage. Norwegian carbon capture operators and Dutch biomethane grid operators are concentrating procurement here, driven by EU F-Gas Regulation mandates for leak-tight sealing architectures. Multi-stage systems command the established base. The steepest expansion runs through oil-free architectures.
- Oil-free:Eliminating lubricant contact with process gas through magnetic bearing or dry gas seal technology, these systems serve pharmaceutical cleanrooms and food-grade compressed air loops. Irish drug manufacturers and Swiss sterile processors are specifying integrated contamination monitoring, responding to EMA machinery safety directives and REACH chemical compliance frameworks. Demand concentrates in high-value manufacturing corridors with zero-tolerance contamination protocols.
- Single-stage:Compact impeller designs deliver moderate pressure ratios for general industrial air compression and manufacturing automation.
- Oil-injected:Conventional lubricated bearings and gearboxes persist in cost-sensitive general industrial applications where process gas purity requirements permit.
Multi-stage and oil-free systems together absorb the majority of new capital allocation across European industrial clusters.
End User:
Cost tier stratification separates maintenance-intensive manufacturing applications from mission-critical energy infrastructure where downtime penalties dwarf equipment purchase price.
- Oil & Gas:Pipeline transmission operators and underground storage facilities require pulsation-free, continuous-duty compression for natural gas, biomethane blends, and emerging hydrogen streams. North Sea platform operators and Dutch gas grid managers are retrofitting for hydrogen readiness, pressured by national decarbonization timelines and EU Green Deal hydrogen backbone initiatives. This segment absorbs premium pricing for redundancy and remote monitoring capability.
- Chemical Processing:Belgian and French petrochemical complexes deploy corrosion-resistant materials and specialized sealing systems for reactive gas handling. REACH compliance deadlines are accelerating sealing system retrofits, with site operators qualifying new compressor packages against hazardous substance leakage thresholds.
- Manufacturing:General industrial compressed air systems serve automotive assembly, metal fabrication, and packaging automation across Central European industrial zones.
- Power Generation:Combined-cycle gas turbine auxiliary systems and energy storage compression for grid balancing applications.
Oil & Gas anchors installed base value. Chemical Processing is climbing the fastest as compliance-driven replacement cycles accelerate.
Technology:
Application maturity separates proven variable speed drives from magnetic bearing systems still navigating certification complexity for hydrogen service.
- Magnetic Bearing:Active magnetic levitation eliminates mechanical contact, enabling unmanned operation and slashing maintenance intervals. North Sea offshore platforms and remote Norwegian installations are adopting these systems aggressively, trading higher capital cost against helicopter-access elimination and personnel reduction. EMA machinery safety directive updates on functional safety are filtering non-compliant vendors from procurement channels.
- Variable Speed Drive:Integrated inverter systems modulate impeller speed to match fluctuating demand profiles, cutting energy consumption versus throttled inlet guide vane control. Spanish and Italian power generators are retrofitting existing assets with VSD packages as electricity price volatility compresses operating margin tolerance.
- Aerodynamic Design:Computational fluid dynamics-optimized impeller profiles maximize polytropic efficiency across operating envelopes.
- Control Systems:Digital monitoring platforms with predictive analytics and cloud-connected diagnostics for fleet management.
Variable Speed Drive commands the established base. Magnetic Bearing is gaining share fastest as remote operation economics improve.
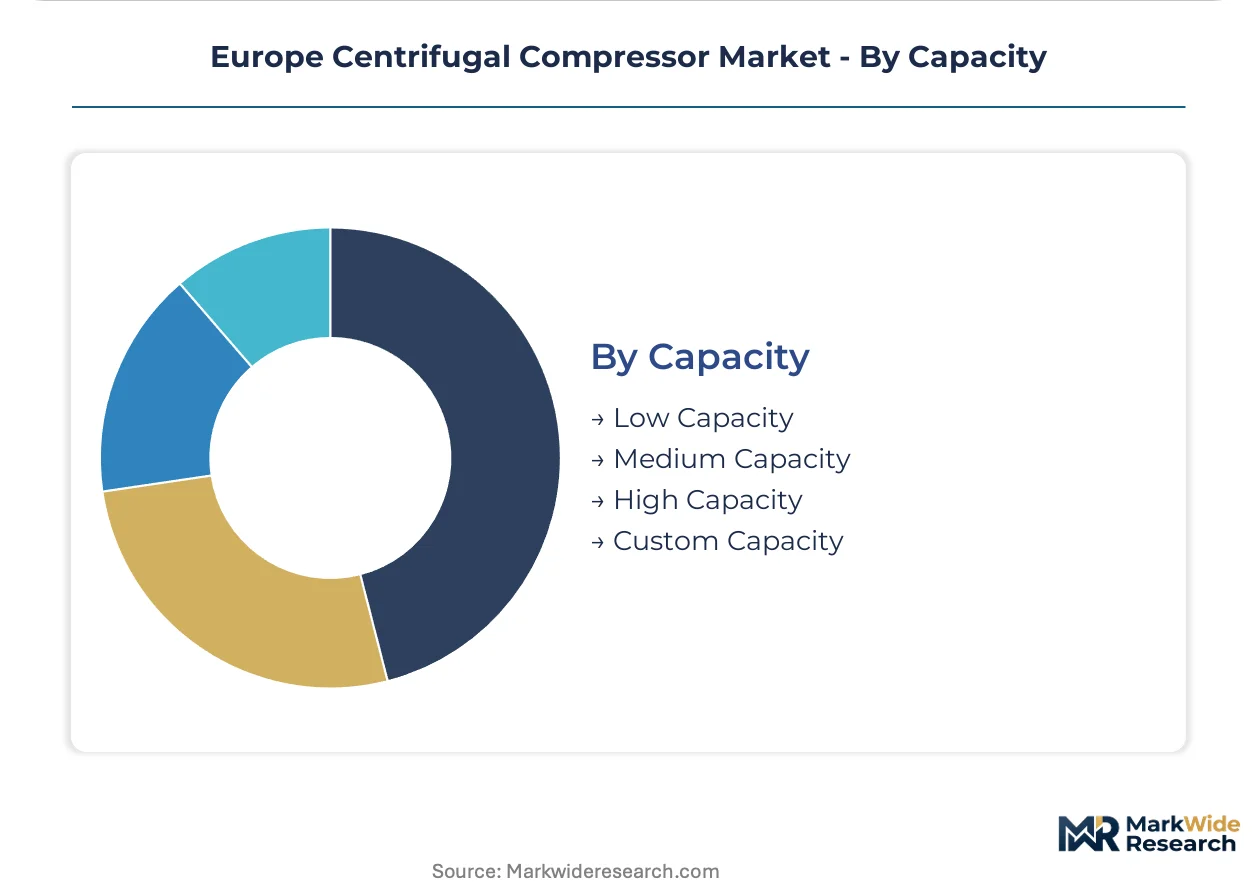
Capacity:
Volume concentration patterns reflect pipeline scale economies versus distributed manufacturing site fragmentation.
- High Capacity:Units exceeding 10 MW drive mainline natural gas transmission and carbon dioxide injection for enhanced oil recovery. UK and Norwegian offshore operators are specifying these packages for North Sea carbon capture scale-up, with project timelines tied to carbon pricing floor mechanisms and storage license awards.
- Custom Capacity:Engineered-to-order systems match unique pressure ratio, flow rate, and gas composition requirements for specialized chemical synthesis and research facilities. Swiss and German pharmaceutical process developers are commissioning bespoke packages for active pharmaceutical ingredient manufacturing, where batch scale and containment protocols defy standardization.
- Medium Capacity:Standardized packages for regional pipeline branches and industrial process gas loops.
- Low Capacity:Compact units for laboratory, pilot plant, and small-scale manufacturing compressed air.
High Capacity commands the established base. Custom Capacity is expanding most quickly as pharmaceutical and hydrogen pilot projects proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors continental demand patterns, compressing procurement timelines toward oil-free architectures across member states with divergent industrial specializations.
Germany
Chemical processing clusters in North Rhine-Westphalia and Bavaria are retrofitting sealing systems to meet REACH compliance deadlines. The EMA machinery safety directive is filtering non-compliant vendors from procurement channels at BASF Ludwigshafen and Bayer Leverkusen sites. Berlin manufacturing anchors long-term service contracts across domestic chemical processing infrastructure.
Netherlands
Biomethane grid operators in Rotterdam and Groningen are expanding centrifugal compressor fleets for renewable gas blending mandates. The EU Green Deal hydrogen backbone initiative is accelerating pipeline retrofit specifications at Gasunia infrastructure nodes. Port of Rotterdam industrial corridors are pre-positioning equipment for pure hydrogen transmission readiness.
Norway
North Sea offshore platforms are deploying high-capacity multi-stage units for carbon dioxide injection and enhanced oil recovery. Norwegian carbon pricing floor mechanisms are tying project timelines to storage license awards at Equinor-operated fields. Stavanger and Bergen engineering clusters are concentrating magnetic bearing expertise for unmanned remote installations.
United Kingdom
UK offshore operators are retrofitting pipeline infrastructure for hydrogen blending specifications in emerging pipeline codes. The carbon border adjustment mechanism is forcing compressor packagers to requalify steel casting suppliers across multiple member states. Aberdeen energy corridors are anchoring North Sea carbon capture scale-up procurement.
France
Belgian and French petrochemical complexes are qualifying new compressor packages against hazardous substance leakage thresholds. ECHA enforcement of REACH chemical compliance frameworks is accelerating sealing system retrofits at TotalEnergies Dunkirk and Arkema Lyon sites. Lyon chemical valley clusters are specifying corrosion-resistant materials for reactive gas handling applications.
Europe Centrifugal Compressor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure compressing around technology differentiation in magnetic bearing systems and oil-free architectures. The vendor base stratifies across full-line turbomachinery houses, precision compressor specialists, and energy infrastructure integrators. Two strategic archetypes dominate: integrated energy technology conglomerates with captive manufacturing footprints, and focused compressor specialists with premium positioning in contamination-critical applications. Competitive moves concentrate on strategic partnerships for hydrogen service certification and portfolio diversification into aftermarket service unbundling.
Among European-anchored turbomachinery houses, Siemens Energy and MAN Energy Solutions SE represent the integrated tier with manufacturing presence in Berlin and German industrial clusters respectively. Atlas Copco Ltd exemplifies the specialist archetype with technology leadership positioning in oil-free compressed air applications. These three anchors demonstrate how geographic manufacturing concentration aligns with long-term service contract capture and regional regulatory compliance specialization.
| Leading Market Players |
|---|
| Atlas Copco Ltd |
| Ingersoll-Rand plc |
| BAUER Compressors Inc |
| Hitachi Ltd. |
| Gardner Denver Holdings Inc. |
| Siemens Energy |
| MAN Energy Solutions SE |
| Howden Group Ltd. |
| Baker Hughes Company |
| Others |
Supply & Pricing Matrix
High-capacity multi-stage compressor manufacturing exhibits pronounced scale economies at German and Norwegian production hubs, concentrating supply-side pricing power among integrated turbomachinery houses while compressing price floors for standardized single-stage units sourced from distributed European fabricators.
Pricing Analysis
Long-term service contracts dominate procurement for North Sea carbon capture and Dutch biomethane infrastructure, locking in predictable revenue streams for Siemens Energy and MAN Energy Solutions against spot-market volatility in general industrial compressed air. Three-tier pricing structure across premium magnetic-bearing systems, standard variable-speed configurations, and economy oil-injected units tracks certification grade and after-sales bundling intensity. Cost compression in economy tiers intensifies because Eastern European packagers compete on stripped-down specifications for price-sensitive manufacturing automation buyers. Pharmaceutical and food-grade processors exhibit lowest price sensitivity, absorbing magnetic-bearing premiums for contamination elimination.
Supply Chain Analysis
China and Vietnam process the majority of rare earth magnet feedstock for European magnetic-bearing compressor production, while German steel forging clusters supply high-pressure impeller castings for multi-stage pipeline units. European OEMs draw from Asian rare earth concentrate for active magnetic levitation systems, Norwegian carbon-fiber composites for lightweight impeller designs, and domestic precision-machined bearing housings. Single-source vulnerability concentrates in neodymium magnet supply chains subject to export licensing disruptions. Distribution runs through authorized service networks for aftermarket parts and direct EPC contractor relationships for greenfield energy infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around EU F-Gas compliance and ATEX hydrogen-service certification creates formidable switching costs for incumbent turbomachinery suppliers.
For Market Incumbents: Consolidate magnetic-bearing engineering talent through targeted acquisition of Stavanger and Bergen specialist firms, preempting capability gaps that delay hydrogen-ready compressor deliveries. Lock in long-term service contracts at German chemical processing clusters before REACH compliance deadlines accelerate competitive retrofit cycles. Vertical integration into rare earth magnet recycling secures input cost stability against Asian supply disruption.
For New Entrants and Emerging Players: Differentiate on integrated contamination monitoring systems for Irish pharmaceutical manufacturing corridors where sterile process requirements outpace incumbent digitalization roadmaps. White-space concentrates in hydrogen-blending retrofit specifications for Polish and Czech industrial clusters pre-positioning for pure hydrogen transmission. Target aftermarket service unbundling at Spanish and Italian power generation operators fragmenting vendor relationships for combined-cycle gas turbine auxiliary systems.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compressor OEMs with captive long-term service contracts at North Sea offshore platforms, where unmanned operation mandates lock in decades of maintenance income. Acquisition targets with established magnetic-bearing expertise and EU F-Gas-compliant oil-free architectures offer superior five-to-ten-year viability against regulatory obsolescence risk. Monitor carbon border adjustment mechanism implementation timelines as inflection signal for domestic European manufacturing requalification spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Certification Investment | EMA machinery safety directive updates filter non-compliant vendors from hydrogen service procurement channels. |
| Rare Earth Magnet Recycling Partnership | Backward integration into magnet recovery reduces exposure to Chinese export licensing volatility. |
| Pharmaceutical Contamination Monitoring Integration | Irish drug manufacturers specify oil-free units with embedded sterile process validation for EMA compliance. |
| North Sea Service Network Expansion | Unmanned platform operation mandates at Equinor-operated fields compress maintenance intervals and anchor long-term contracts. |
| Hydrogen Pipeline Readiness Pre-Positioning | Polish industrial clusters are specifying compressor architectures for pure hydrogen transmission ahead of EU Green Deal backbone deployment. |
Research Methodology
A spread of perspectives from turbomachinery engineering directors, plant maintenance managers at German chemical processing sites, EPC contractors for North Sea carbon capture projects, and aftermarket service heads converged on the working assumptions around magnetic-bearing adoption timelines and hydrogen service certification complexity. Primary fieldwork combined structured interviews with secondary validation against EU F-Gas Regulation implementation schedules, ECHA REACH enforcement patterns, and customs data on rare earth magnet import flows. Bottom-up unit shipment estimates across product type, capacity tier, and end-use segment triangulated against top-down energy infrastructure investment forecasts from national decarbonization program disclosures.
Segmentation dimensions modeled span product architecture (multi-stage, single-stage, oil-free, oil-injected), capacity tier (high, custom, medium, low), technology type (magnetic bearing, variable speed drive), and end-use vertical (oil and gas transmission, chemical processing, pharmaceutical manufacturing, power generation). CAGRs were derived from regression analysis of historical capital expenditure patterns and project pipeline visibility across the analysis window. Industry-specific forecast inputs incorporated carbon pricing floor mechanisms in Norway and the Netherlands, biomethane blending mandate enforcement in Germany, and hydrogen backbone initiative timelines under the EU Green Deal.
Material uncertainties — abrupt rare earth export restrictions, accelerated EU F-Gas phase-down schedules, or hydrogen pipeline code revisions — sit outside the modeled envelope and would compress or extend equipment replacement cycles. Forecasts reflect assumptions around regulatory enforcement continuity and supply chain reconfiguration pace documented in stakeholder interviews. Recalibration cycles align with material shifts in carbon border adjustment mechanism implementation and national hydrogen infrastructure award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Europe Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Turbocompressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Scroll Compressor Market
Compressors
Root Blower Market
Compressors
Automotive Compressors Market
Compressors
Oil Free Compressor Market
Compressors
Axial Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Rental Air Compressors Market
Compressors
CNG Compressor Market
Compressors
Centrifugal Air Compressor Market