
 Compressed Air Lubricators Market | 2026-2036
Compressed Air Lubricators Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Air Lubricators Market Insights
Industrial distribution for compressed air lubricators is narrowing as specialized fluid power distributors consolidate shelf space around technical support capabilities. Festo leverages its captive distribution network to control specification decisions at the OEM level. Parker Hannifin anchors North American availability through its broad industrial distribution partnerships. Norgren competes in Europe via application-engineered modular lubricator configurations.
Compressed air lubricators are precision pneumatic devices that inject controlled oil aerosols into compressed air streams at pressures typically spanning 0.5 to 10 bar, protecting downstream pneumatic cylinders and valves from friction wear. Inline lubricators retain dominant placement in legacy machine tool installations where centralized FRL assemblies remain standard. Modular lubricators are gaining share in packaging equipment lines where rapid reconfiguration demands plug-and-play pneumatic architecture. Digital control technology commands premium positioning as food processing facilities seek traceable oil delivery rates for HACCP documentation.
ISO 8573 air quality classes govern oil content limits in compressed air systems, directly determining lubricator selection and maintenance protocols in manufacturing plants across Germany, Japan, and the United States. OSHA workplace exposure limits and EU machinery directives further constrain allowable oil mist emissions, pushing chemical facilities toward closed-loop lubricator designs with integrated reclamation. Stakeholders must weigh the capital trade-off between precision digital control upgrades and retrofitting existing pneumatic infrastructure as regulatory thresholds tighten without grandfathering provisions.
Market Dynamics
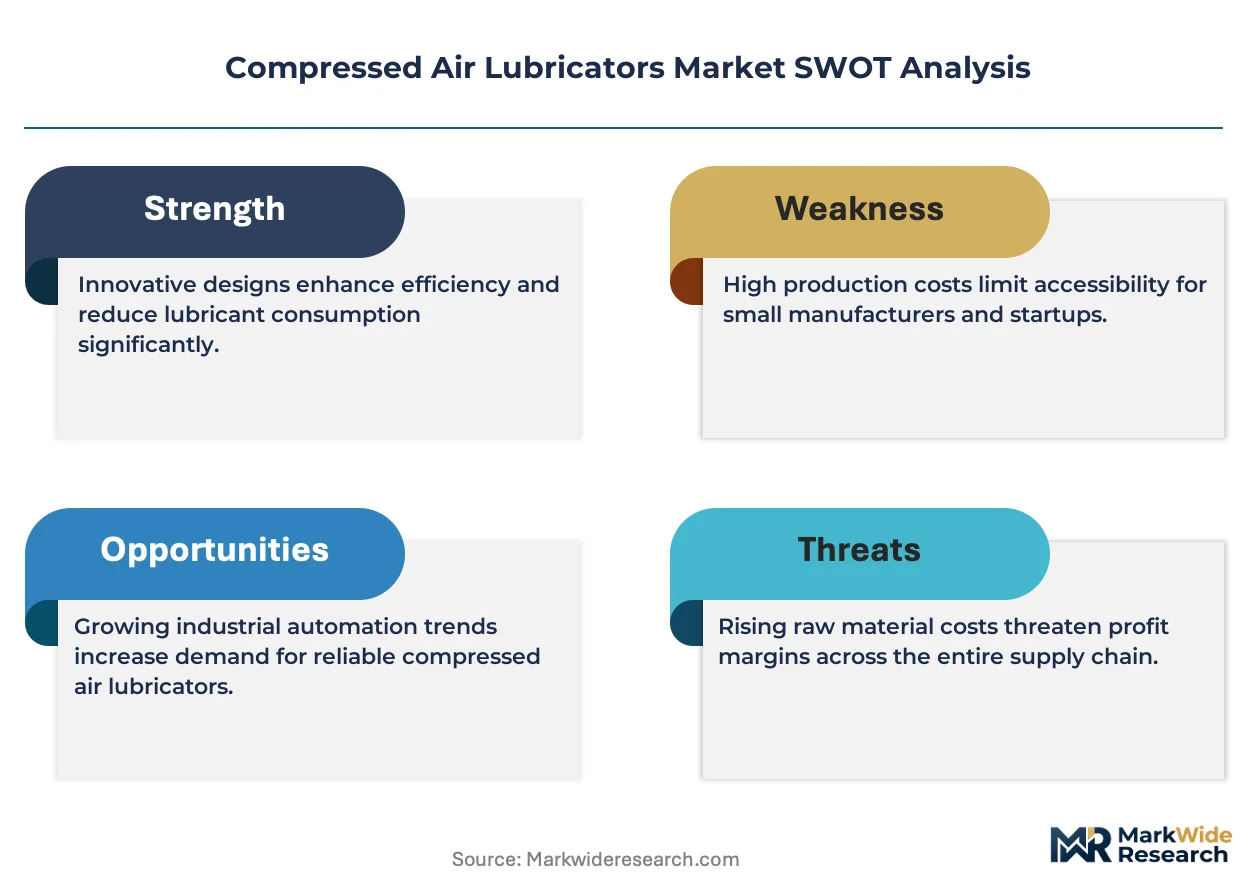
ISO 8573 air quality mandates are compressing specification cycles across food processing and pharmaceutical pneumatic systems, forcing lubricator suppliers to validate oil delivery precision at the component level rather than system level.
Growth Catalysts
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology directives on compressed air system efficiency are accelerating precision lubricator deployments in Yangtze River Delta manufacturing clusters.
- HACCP Documentation Requirements:Food safety protocols in Germany and the United States now demand traceable oil delivery rates, pulling digital control lubricators into packaging and processing lines.
- Pneumatic Cylinder Wear Protection:Extended equipment life requirements in legacy machine tool installations sustain replacement demand for inline lubricator assemblies.
Market Restraints
- Base Oil Price Volatility:Synthetic lubricant feedstock costs fluctuate with petrochemical indices, compressing margin on precision aerosol formulations.
- Supply Concentration in Pneumatic Valves:Critical valve component sourcing clusters in Southern Germany create vulnerability for modular lubricator assembly lines.
- Closed-Loop Substitution:Oil-free compressor technologies with integrated filtration are displacing lubricated pneumatic architectures in cleanroom applications.
Strategic Opportunities
- India's PLI Manufacturing Push:Production-linked incentive schemes for electronics and automotive components are greenfielding pneumatic infrastructure in Pune and Chennai corridors.
- IoT-Enabled Predictive Maintenance:Sensor-integrated lubricators converging with edge computing platforms enable condition-based oil replenishment contracts.
- EU Machinery Directive Updates:Revised CE marking requirements for oil mist containment are opening specification windows for reclamation-integrated lubricator designs.
Industry Challenges
- ISO 8573 Class Validation Timelines:Third-party certification for oil content compliance extends product launch cycles by six to nine months.
- Legacy FRL Integration Friction:Retrofitting modular digital lubricators into centralized filter-regulator-lubricator assemblies requires custom manifold engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Air Lubricators Market |
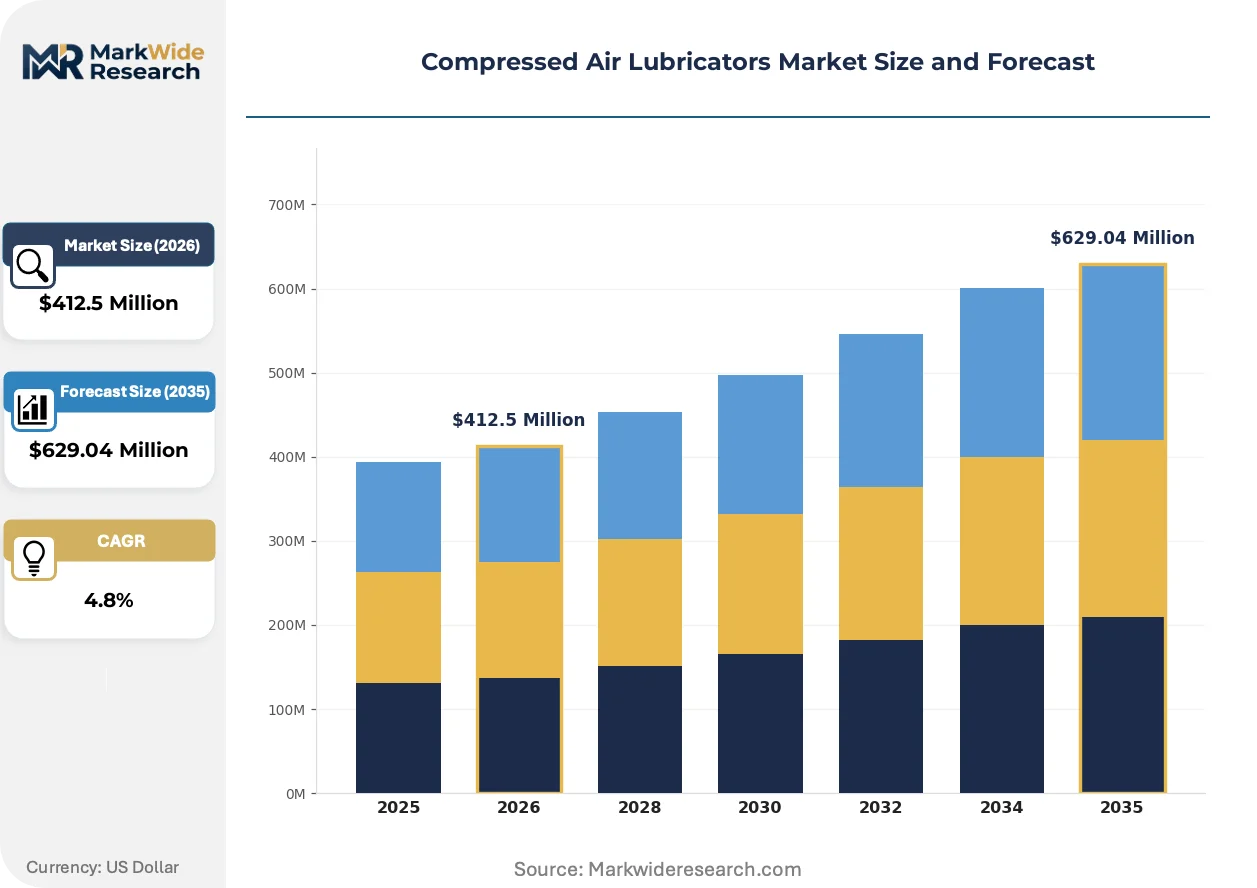
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Lubricators, Modular Lubricators, Drip Type, Mist Type, Metering Type Technology: Manual Adjustment, Automatic Adjustment, Electro-Pneumatic, Digital Control, Pneumatic Control Application: Food Processing, Textile Manufacturing, Packaging Equipment, Machine Tools, Printing Machines End User Industry: Manufacturing Plants, Chemical Facilities, Mining Operations, Construction Sites, Energy Firms |
| Companies Covered | Festo, Parker Hannifin, Norgren, Atlas Copco, Ingersoll Rand, Kaeser Kompressoren, ELGi Equipments, Gardner Denver, Donaldson Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Air Lubricators Market Trends and Innovations
Pneumatic component architecture is fragmenting between precision-controlled digital systems and cost-optimized mechanical designs, with specification authority shifting from maintenance departments to OEM engineering teams.
Micro-dosing lubrication technology is hybridizing mechanical precision with electronic feedback control. Food processing facilities in the Netherlands and Wisconsin are adopting these systems at pilot scale. The technology is hybridizing supplier business models toward performance-based fluid management contracts that bundle hardware with consumable replenishment services.
REACH restrictions on mineral oil aerosols are compelling formulation shifts toward synthetic ester bases. Chemical facilities across Belgium and Northern Italy face reformulation deadlines. Lubricator manufacturers with in-house fluid chemistry capabilities are capturing specification slots previously held by commodity suppliers.
Maintenance departments are unbundling lubricator procurement from compressor service contracts. Industrial distributors in Ohio and Bavaria are building technical specification teams to capture this disaggregated spend. The shift is most pronounced in automotive tier-one supplier plants where compressed air system ownership has transferred from facilities management to production engineering.
Compressed Air Lubricators Market Segmentation
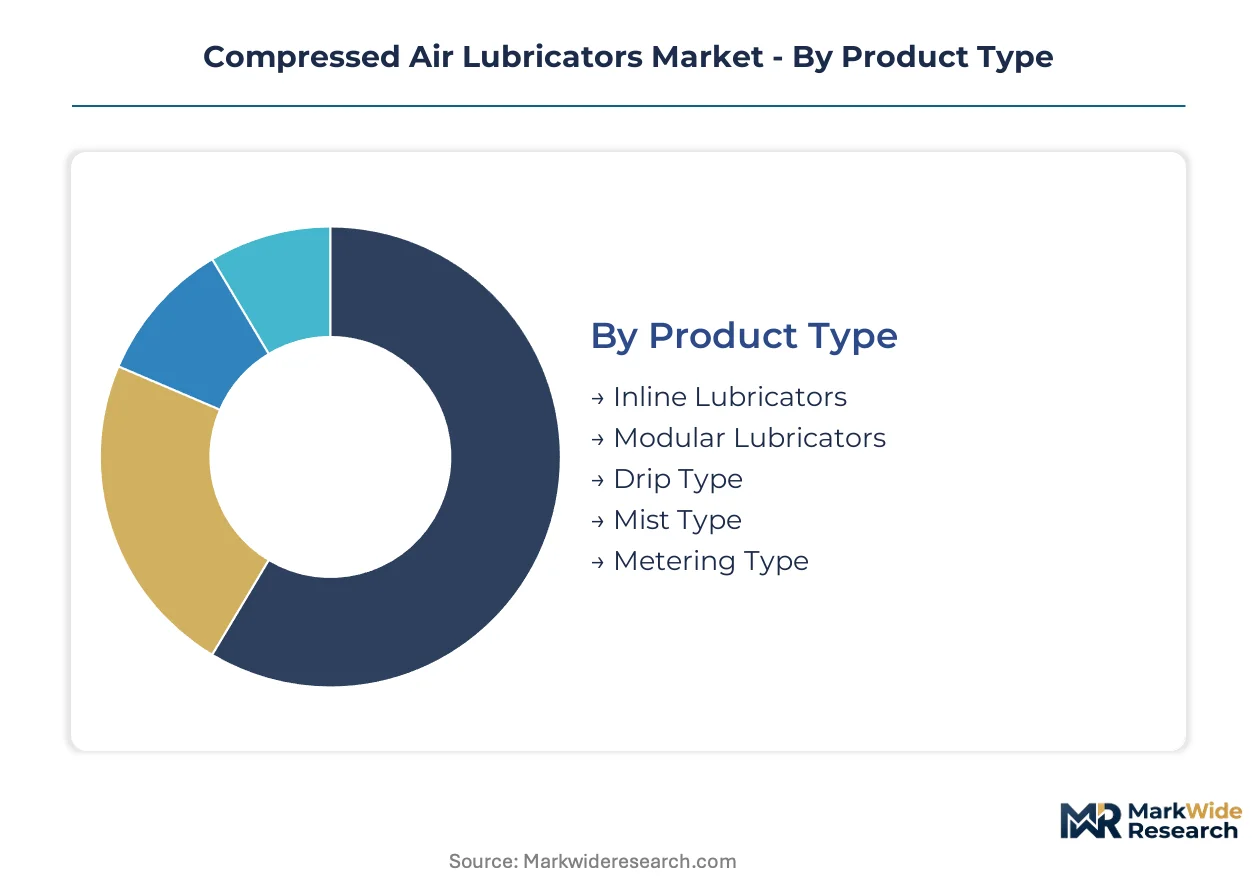
Compressed air lubricator segmentation reveals divergent specification logic across pneumatic system architectures. Product type and technology choices cascade through application requirements and end-user compliance obligations.
Product Type:
Use-case spectrum spans legacy centralized installations to reconfigurable production lines where modularity commands premium positioning.
- Inline Lubricators:These centralized FRL assembly components deliver oil aerosols through fixed manifold configurations at standard operating pressures. Machine tool corridors in Germany and the United States sustain replacement demand as ISO 8573 maintenance protocols tighten without grandfathering provisions.
- Modular Lubricators:Plug-and-play pneumatic architecture enables rapid reconfiguration for packaging equipment lines. China's Yangtze River Delta manufacturing clusters favor these configurations under MIIT efficiency mandates that reward precision-controlled compressed air systems.
- Drip Type:Gravity-fed oil delivery suits low-pressure auxiliary pneumatic circuits in cost-sensitive installations.
- Mist Type:Atomized oil dispersion serves high-flow pneumatic systems requiring uniform lubricant distribution.
- Metering Type:Precision volumetric control addresses chemical facilities facing OSHA exposure limits and EU machinery directive constraints.
Established volume favors Inline Lubricators; emerging adoption favors Modular Lubricators.
Technology:
Cost tier stratification separates mechanical reliability from digital traceability as food safety documentation requirements harden.
- Digital Control:Closed-loop electronic feedback enables HACCP-compliant oil delivery rate logging with sensor-integrated edge computing compatibility. Food processing facilities in Wisconsin and the Netherlands pilot these systems for condition-based replenishment contracts.
- Manual Adjustment:Mechanical needle-valve settings dominate legacy installations where maintenance departments retain specification authority.
- Automatic Adjustment:Flow-responsive mechanisms adapt oil delivery to variable pneumatic demand without operator intervention.
- Electro-Pneumatic:Hybrid actuation bridges mechanical simplicity with electronic feedback for mid-tier packaging equipment.
- Pneumatic Control:Air-piloted regulation persists in explosion-risk environments where electrical components face restrictions.
Specification gravity centers on Digital Control for compliance-driven verticals; Automatic Adjustment captures cost-optimized mechanical demand.
Application:
Volume concentration tracks regulatory intensity across hygiene-critical and precision-manufacturing pneumatic systems.
- Food Processing:HACCP documentation requirements and FDA food contact compliance pull traceable lubricator architectures into packaging and processing lines. Germany's meat processing plants and U.S. dairy facilities lead specification upgrades.
- Packaging Equipment:Rapid format changeover demands drive modular lubricator integration with plug-and-play pneumatic manifolds.
- Machine Tools:Centralized FRL assemblies in legacy metalworking installations sustain inline lubricator replacement cycles.
- Textile Manufacturing:High-velocity pneumatic looms require consistent oil mist delivery to prevent yarn contamination.
- Printing Machines:Precision paper handling cylinders demand controlled friction reduction without ink contamination risk.
Compliance pressure in Food Processing drives technology upgrading; Packaging Equipment offers fastest volume expansion for modular architectures.
End User Industry:
Customer type segmentation reflects divergent procurement authority between facilities management and production engineering departments.
- Manufacturing Plants:Automotive tier-one suppliers in Ohio and Bavaria unbundle lubricator procurement from compressor service contracts, shifting specification authority to production engineering.
- Chemical Facilities:REACH restrictions on mineral oil aerosols and EU machinery directive oil mist containment rules push reclamation-integrated designs.
- Mining Operations:Harsh-environment pneumatic systems favor robust mechanical lubricators with extended maintenance intervals.
- Construction Sites:Mobile compressor-fed pneumatic tools require portable, contamination-resistant lubricator configurations.
- Energy Firms:Pipeline maintenance and power generation auxiliary systems demand explosion-rated pneumatic architectures.
Procurement restructuring in Manufacturing Plants accelerates specification fragmentation; Chemical Facilities face the steepest compliance-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering corridors while Chinese manufacturing clusters compress margins through scale-driven procurement. This asymmetry shapes capital allocation across pneumatic component suppliers.
United States
Food processing facilities in Wisconsin and Ohio drive specification upgrades for HACCP-compliant digital lubricators. OSHA workplace exposure limits on oil mist emissions tighten compliance thresholds without grandfathering provisions. Automotive tier-one suppliers in the Midwest unbundle lubricator procurement from compressor service contracts, shifting authority to production engineering departments.
Germany
Machine tool corridors in Bavaria and Baden-Württemberg sustain replacement demand for inline FRL assemblies. EU machinery directive updates on oil mist containment push reclamation-integrated designs into chemical facilities. REACH restrictions on mineral oil aerosols compel formulation shifts toward synthetic ester bases in Belgium-adjacent industrial zones.
China
MIIT efficiency mandates accelerate precision lubricator deployments in Yangtze River Delta manufacturing clusters. GB standards alignment with ISO 8573 air quality classes determines import substitution timelines for domestic suppliers. Packaging equipment lines in Shenzhen and Suzhou favor modular plug-and-play architectures for rapid reconfiguration.
India
PLI schemes for electronics and automotive components greenfield pneumatic infrastructure in Pune and Chennai corridors. BIS certification requirements extend product validation cycles for imported lubricator assemblies. Textile manufacturing clusters in Gujarat and Tamil Nadu require consistent oil mist delivery for high-velocity pneumatic loom operations.
Japan
Precision manufacturing facilities in Aichi and Osaka prefectures demand traceable oil delivery rates for quality documentation. METI industrial efficiency guidelines reward compressed air system optimization investments. Automotive component suppliers in Toyota City upgrade legacy pneumatic architectures to meet JIS standard harmonization with ISO protocols.
Compressed Air Lubricators Market Competitive Landscape
Captive distribution networks and broad industrial partnerships split the market between specification-control and availability-anchored strategies. The vendor base concentrates around fluid power specialists with integrated pneumatic portfolios. Two archetypes dominate: engineering-driven OEM specification capturers and scale-optimized aftermarket distributors. Competitive moves center on distribution consolidation and modular product platform expansion.
Among German-based engineering specialists, Festo exemplifies the captive distribution archetype through specification control at the OEM level. Parker Hannifin anchors North American availability through broad industrial distribution partnerships. Norgren occupies a position within the application-engineered modular tier, competing via configurable lubricator architectures. These three represent distinct strategic postures rather than overlapping market contests.
| Leading Market Players |
|---|
| Festo |
| Parker Hannifin |
| Norgren |
| Atlas Copco |
| Ingersoll Rand |
| Kaeser Kompressoren |
| ELGi Equipments |
| Gardner Denver |
| Donaldson Company |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Southern German pneumatic valve clusters compresses margin recovery timelines while forcing buyers toward premium-configured digital lubricators with validated component traceability. This concentration dynamic simultaneously widens the spread between standard inline assemblies and application-engineered modular systems while reshaping procurement toward distributor technical specification teams.
Pricing Analysis
The customization-premium spread spans roughly 40-60% above catalog pricing for application-engineered modular configurations with integrated reclamation and digital feedback loops. Three-tier pricing structure across premium, standard, and economy levels separates HACCP-compliant digital systems from automatic-adjustment mechanical units and basic drip-feed alternatives. Pricing pressure stems from base oil feedstock volatility tied to petrochemical indices, particularly compressing margins on synthetic ester formulations required by REACH restrictions. Automotive tier-one suppliers exhibit highest price sensitivity as production engineering departments unbundle procurement from legacy compressor service contracts, while chemical facilities facing OSHA exposure mandates show lowest sensitivity due to compliance-driven specification authority.
Supply Chain Analysis
Upstream feedstock flows from German synthetic ester chemistry specialists and Belgian mineral oil refiners feed precision aerosol formulation lines. Component sourcing draws from Southern German valve machining clusters, Chinese Yangtze River Delta electronics for sensor modules, and Indian Pune corridor aluminum die-casting for housing assemblies. Single-source vulnerability concentrates in high-precision pneumatic valve spools where Southern German specialists maintain process knowledge barriers. Distribution runs through captive OEM specification networks for engineered systems and broad industrial distributors for replacement inline assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house fluid chemistry capabilities have become the scarce asset separating specification-capturing suppliers from commodity competitors, as REACH deadlines and HACCP documentation requirements simultaneously harden formulation and validation demands.
For Market Incumbents: Pre-empt modular platform consolidation by acquiring regional distributors with technical specification teams in Ohio and Bavaria, where automotive tier-one procurement restructuring is disaggregating spend. Deepen backward integration into synthetic ester formulation to capture margin pools escaping commodity mineral oil suppliers facing REACH restrictions. Lock specification authority at OEM level through captive distribution before IoT-enabled predictive maintenance contracts commoditize hardware differentiation. For New Entrants and Emerging Players: Build out India PLI corridor presence targeting greenfield electronics and automotive component plants in Pune and Chennai where pneumatic infrastructure lacks incumbent entrenchment. Penetrate the metering-type segment for chemical facilities facing EU machinery directive oil mist containment deadlines, as reclamation-integrated designs remain undersupplied relative to compliance-driven replacement cycles. Lead with condition-based replenishment service contracts rather than hardware margin capture. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated fluid power specialists with in-house chemistry and captive distribution. Long-term viability hinges on specification control migration from maintenance departments to OEM engineering teams, favoring targets with established Festo-style captive networks. Watch for BIS certification timeline extensions in India as an inflection signal for import substitution acceleration by domestic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Ester Formulation | Captures margin pools from REACH-restricted mineral oil suppliers in Belgium-adjacent zones. |
| IoT Sensor Integration for Predictive Maintenance | Enables condition-based replenishment contracts with food processing facilities in Wisconsin. |
| Regional Distributor Acquisition | Secures specification authority as automotive tier-one procurement shifts to production engineering. |
| Modular Platform Expansion | Addresses rapid reconfiguration demands in Shenzhen packaging equipment corridors. |
| Reclamation-Integrated Design Development | Meets EU machinery directive oil mist containment requirements for chemical facilities. |
Research Methodology
Cross-validation between primary interviews with fluid power distributors, OEM specification engineers, and maintenance directors anchors the qualitative findings against customs data on pneumatic component trade flows and SEC filings from compressed air system suppliers. Bottom-up triangulation incorporates plant-level deployment assessments in Yangtze River Delta manufacturing clusters with top-down market sizing derived from MIIT efficiency mandate compliance timelines and ISO 8573 certification database tracking.
Calibration against historical replacement cycles in German machine tool corridors and forward-looking OEM capex disclosure patterns shapes the projection framework. Segmentation dimensions span product type architecture, control technology tier, application regulatory intensity, and end-user procurement authority structure across the analysis window. CAGRs derive from elasticity modeling of pneumatic system investment against manufacturing output indices and regulatory compliance deadline clustering.
Practitioners should monitor MIIT mandate enforcement intensity, REACH reformulation deadline extensions, and BIS certification backlog durations for early signals of forecast revision. Cross-checking against customs data on pneumatic valve import volumes and OEM specification change order frequencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Bus Compressor Market
Compressors
North America Air Compressor Market
Compressors
Axial Compressor Market
Compressors
Root Blower Market
Compressors
Regenerative Blowers Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Hydrogen Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
PAG Compressor Oil Market