
 Asia-Pacific Booster Compressor Market | 2026-2036
Asia-Pacific Booster Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Booster Compressor Market Insights
API 618-compliant heavy-duty specifications is unwinding legacy procurement patterns across the Asia-Pacific booster compressor landscape. Atlas Copco Ltd leverages its aftermarket service density to anchor recurring revenue streams in Australia's mining corridors. Hitachi Ltd differentiates through integrated motor-compressor packages that dominate Japan's hydrogen mobility trials. Siemens Energy sustains technology leadership in electrically driven centrifugal architectures for Southeast Asian power generation projects.
A booster compressor is a secondary compression stage that elevates discharge pressure from an existing compressed air or gas system, typically achieving final pressures between 150 and 700 bar through reciprocating pistons or multi-stage rotary configurations for industrial gas transfer and process intensification. Oil & gas applications retain the largest installed base across the region, though manufacturing segments are shifting fastest toward rotary screw and centrifugal technologies as plant automation deepens. Electrically driven systems command premium positioning in Japan and South Korea, while diesel driven units still occupy remote mining and agricultural deployments across Indonesia and Mongolia.
China's MIIT enforces GB energy-efficiency standards that filter sub-tier equipment from state-backed industrial parks, while Japan's METI subsidizes hydrogen-compatible compressor retrofits under national decarbonization roadmaps. India's BIS certification mandates and the PLI scheme are tightening market access for imported units while nurturing domestic assembly capacity. Stakeholders must monitor how Australia's TGA-equivalent pressure equipment safety frameworks and evolving ASEAN mutual recognition protocols reshape cross-border equipment qualification timelines.
Market Dynamics
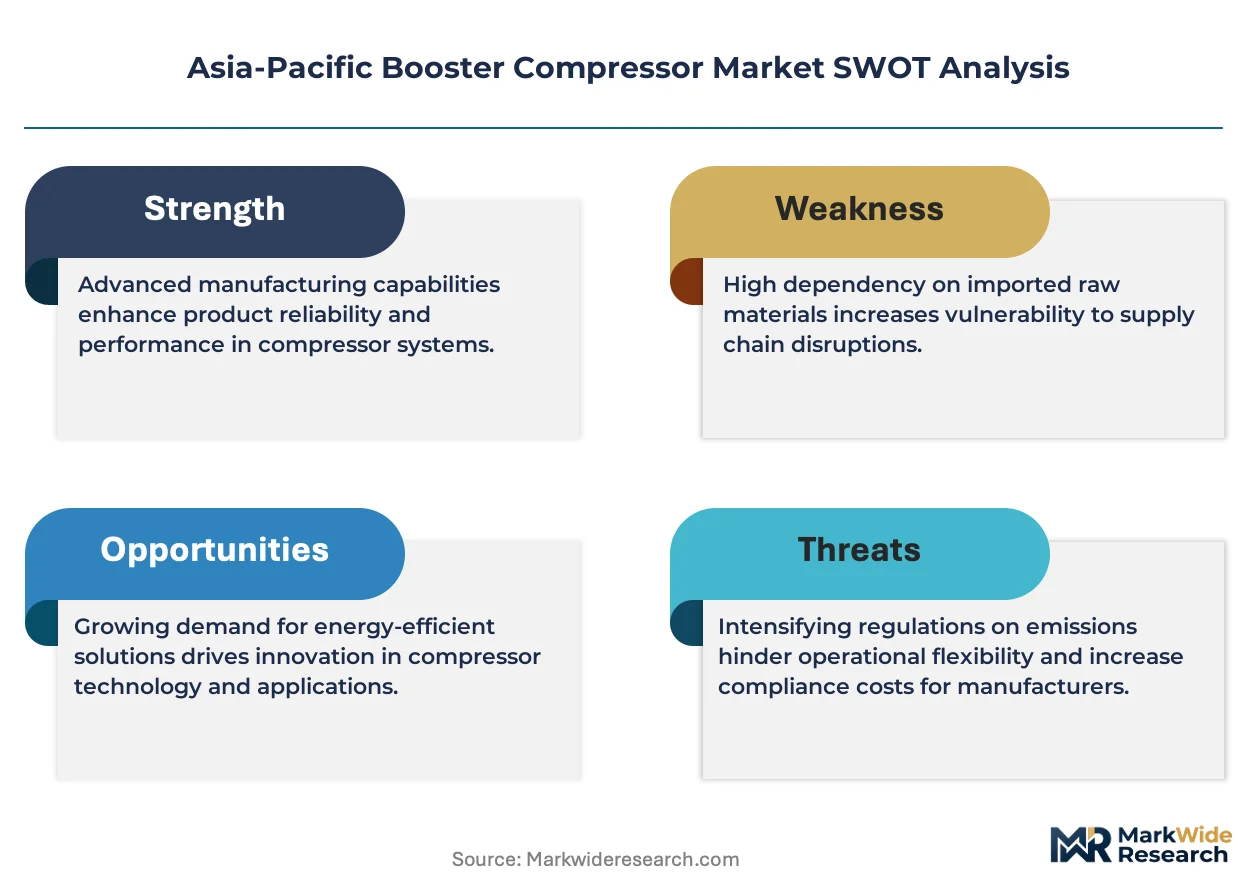
The Asia-Pacific booster compressor market is experiencing structural recalibration as China's MIIT enforces GB energy-efficiency standards that systematically filter sub-tier equipment from state-backed industrial parks. This regulatory pressure is compressing legacy procurement timelines and accelerating technology refresh cycles across manufacturing clusters.
Growth Catalysts
- Hydrogen infrastructure buildout:Japan's METI subsidizes hydrogen-compatible compressor retrofits under national decarbonization roadmaps, lifting demand for high-pressure gas compression systems in mobility trials.
- Domestic manufacturing incentives:India's PLI scheme nurtures assembly capacity while tightening market access for imported units, redirecting procurement toward locally certified equipment.
- Dual carbon compliance:China's dual carbon goals reshape procurement standards toward energy-efficient electrically driven units in Shanghai and Pearl River Delta industrial zones.
Market Restraints
- Specialized alloy input costs:Nickel-based superalloy price volatility constrains margins for high-pressure reciprocating piston manufacturers serving oil and gas applications.
- Core component supply concentration:Precision casting capacity for multi-stage rotary configurations concentrates in select Japanese and German supplier networks, creating single-source vulnerability.
- Technical limitation in electrification:Battery energy density constraints prevent full electrification of mobile booster compressor units above 500 bar discharge pressure.
Strategic Opportunities
- Mongolia mining corridors:Diesel-driven unit demand persists in remote agricultural and mineral extraction sites where grid connectivity remains inadequate.
- ASEAN mutual recognition protocols:Evolving cross-border equipment qualification frameworks create first-mover advantage for manufacturers achieving multi-jurisdictional certification.
- Integrated motor-compressor convergence:Direct-drive permanent magnet motor technology eliminates gearbox maintenance while reducing footprint for hydrogen refueling station deployments.
Industry Challenges
- API 618 certification timelines:Heavy-duty specification compliance for reciprocating compressors extends qualification cycles by 8-14 months, delaying project commissioning.
- Legacy system integration friction:Retrofitting electrically driven architectures into existing pneumatic infrastructure requires custom manifold redesigns and control system synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Booster Compressor Market |
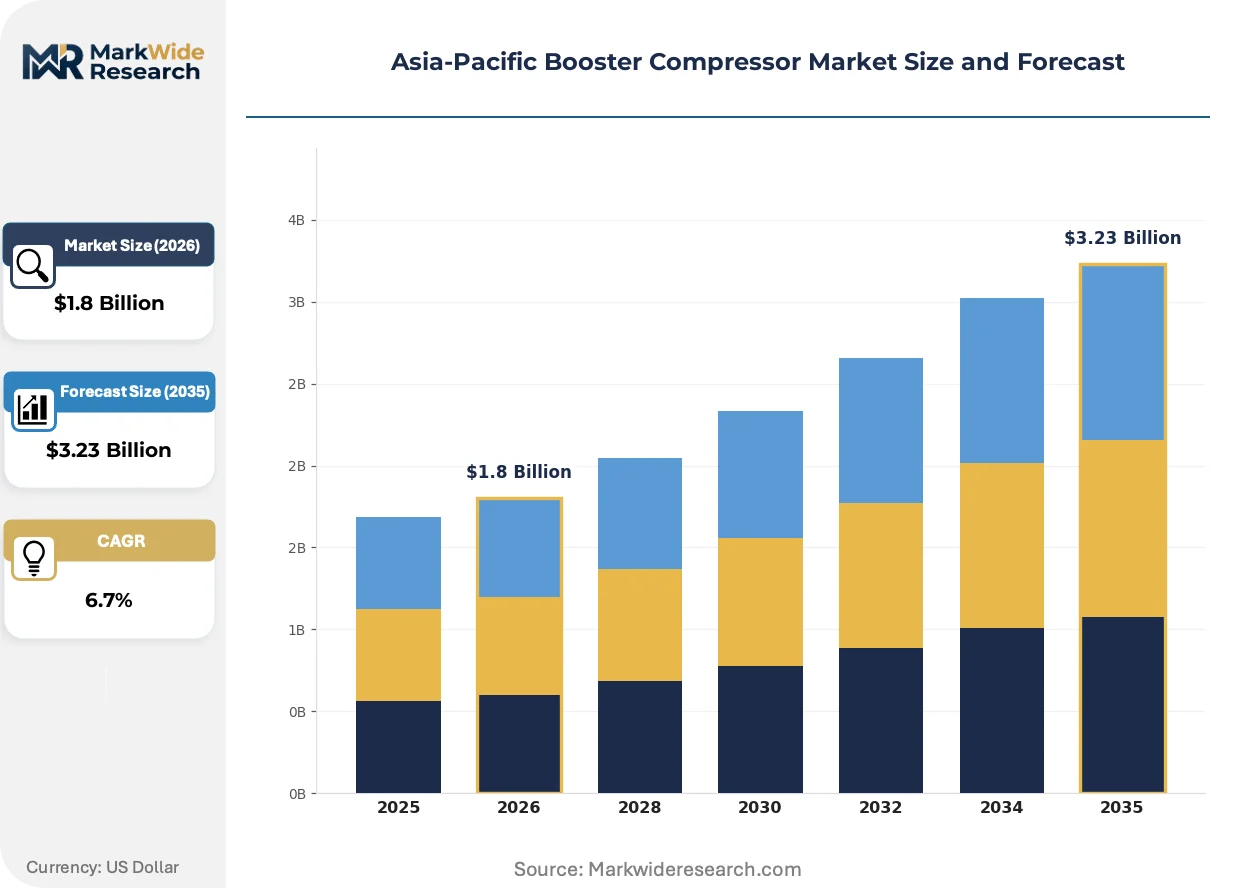
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Axial Application: Oil & Gas, Manufacturing, Power Generation, Mining End User: Industrial, Commercial, Agricultural, Automotive Technology: Electrically Driven, Diesel Driven, Hybrid, Others |
| Companies Covered | Atlas Copco Ltd, Hitachi Ltd, IDEX India Private Ltd, Bauer Kompressoren, Mikuni Kikai Kogyo Co Ltd, Ingersoll Rand PLC, Siemens Energy, Mitsubishi Heavy Industries Ltd, Gardner Denver, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Booster Compressor Market Trends and Innovations
Active reshaping of the Asia-Pacific booster compressor landscape centers on three convergent forces: component miniaturization enabling modular deployment, regulatory efficiency mandates compressing equipment lifecycles, and service model unbundling disrupting traditional aftermarket revenue streams.
Integrated permanent magnet motor-compressor packages are miniaturizing footprint requirements while maintaining discharge pressure ratings above 350 bar. Hydrogen mobility operators in Japan and South Korea are adopting these compact configurations for space-constrained urban refueling stations. The technology is miniaturizing installation footprints from 40 square meters to under 15 square meters, enabling deployment in commercial parking structures previously inaccessible to conventional skid-mounted systems.
China's MIIT GB standards establish tiered efficiency thresholds that disqualify fixed-speed reciprocating units from state-backed procurement. Industrial park operators in Jiangsu and Zhejiang provinces now mandate variable frequency drive compatibility for all new compressor installations. Manufacturers serving these clusters are responding by discontinuing legacy product lines and accelerating development of digitally integrated, condition-monitoring-ready architectures.
After-sales service unbundling is fragmenting traditional maintenance contracts into discrete predictive analytics subscriptions and on-demand technical support tiers. Mining operators in Western Australia and Indonesia are negotiating outcome-based availability guarantees rather than fixed preventive maintenance schedules. This shift is most visible in Australia's iron ore corridors, where remote monitoring infrastructure enables compressor health diagnostics without routine site visits.
Asia-Pacific Booster Compressor Market Segmentation
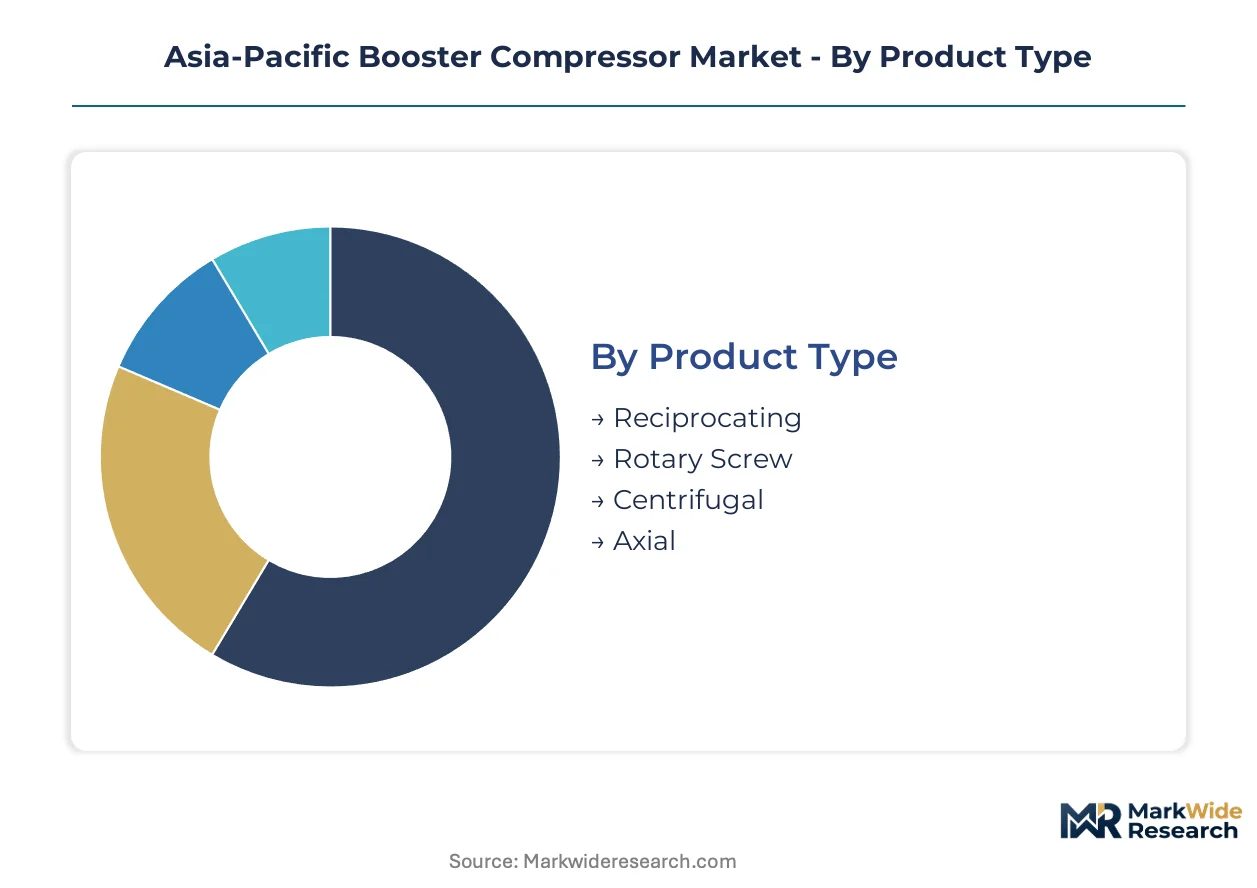
Asia-Pacific booster compressor procurement channels diverge sharply by pressure rating and mobility requirements. Industrial buyers route high-capacity stationary units through direct manufacturer relationships, while mobile applications flow through regional distributor networks with aftermarket service bundling.
Product Type:
Channel mix for product types splits between project-direct sales for heavy-duty reciprocating units and stocking distributors for compact rotary configurations.
- Reciprocating:Piston-based compression architectures achieve discharge pressures exceeding 500 bar through multi-stage cylinder arrangements. Oil and gas operators in Australia's offshore corridors specify these for wellhead gas injection, though API 618 certification timelines extend procurement cycles.
- Rotary Screw:Helical rotor mechanisms deliver continuous compression flow with reduced pulsation versus reciprocating alternatives. Manufacturing clusters in China's Jiangsu province are shifting procurement toward these units as MIIT GB standards disqualify fixed-speed legacy equipment.
- Centrifugal:Dynamic compression via impeller rotation suits high-volume, moderate-pressure process gas applications.
- Axial:Sequential blade rows generate compression in compact flow paths for specialized high-throughput scenarios.
Reciprocating dominates installed base. Rotary screw is where expansion concentrates.
Application:
Cost tier stratification separates oil and gas project budgets from manufacturing capital expenditure constraints.
- Oil & Gas:Upstream, midstream, and downstream hydrocarbon processing demands corrosion-resistant materials and API compliance. Offshore platforms in Australia's Northwest Shelf and Malaysia's Sarawak basin anchor regional demand, though nickel-based superalloy price volatility constrains manufacturer margins.
- Manufacturing:Plant automation and process intensification drive compressed air utility requirements. China's Pearl River Delta electronics assemblers are retrofitting electrically driven architectures to meet dual carbon procurement mandates.
- Power Generation:Gas turbine fuel gas boosting and combined cycle plant auxiliary systems create specification diversity.
- Mining:Remote mineral extraction in Mongolia and Indonesia's Papua province sustains diesel-driven mobile unit demand where grid connectivity remains inadequate.
Oil and gas commands premium pricing tiers. Manufacturing represents the steepest expansion trajectory.
End User:
Customer type fragmentation separates engineered-to-order industrial procurement from standardized commercial transactions.
- Industrial:Petrochemical, refining, and heavy manufacturing operations require continuous-duty compression with predictive maintenance integration. State-backed industrial parks in China filter sub-tier equipment through MIIT GB efficiency standards, compressing supplier qualification.
- Commercial:Hydrogen refueling station operators in Japan and South Korea specify compact integrated motor-compressor packages. METI subsidies for hydrogen-compatible retrofits are redirecting procurement toward high-pressure gas systems.
- Agricultural:Irrigation and processing applications in Indonesia's outer islands favor portable diesel units.
- Automotive:Vehicle assembly paint shops and tire inflation utilities constitute fragmented demand.
Industrial end users anchor manufacturer revenue stability. Commercial hydrogen infrastructure is gaining share fastest.
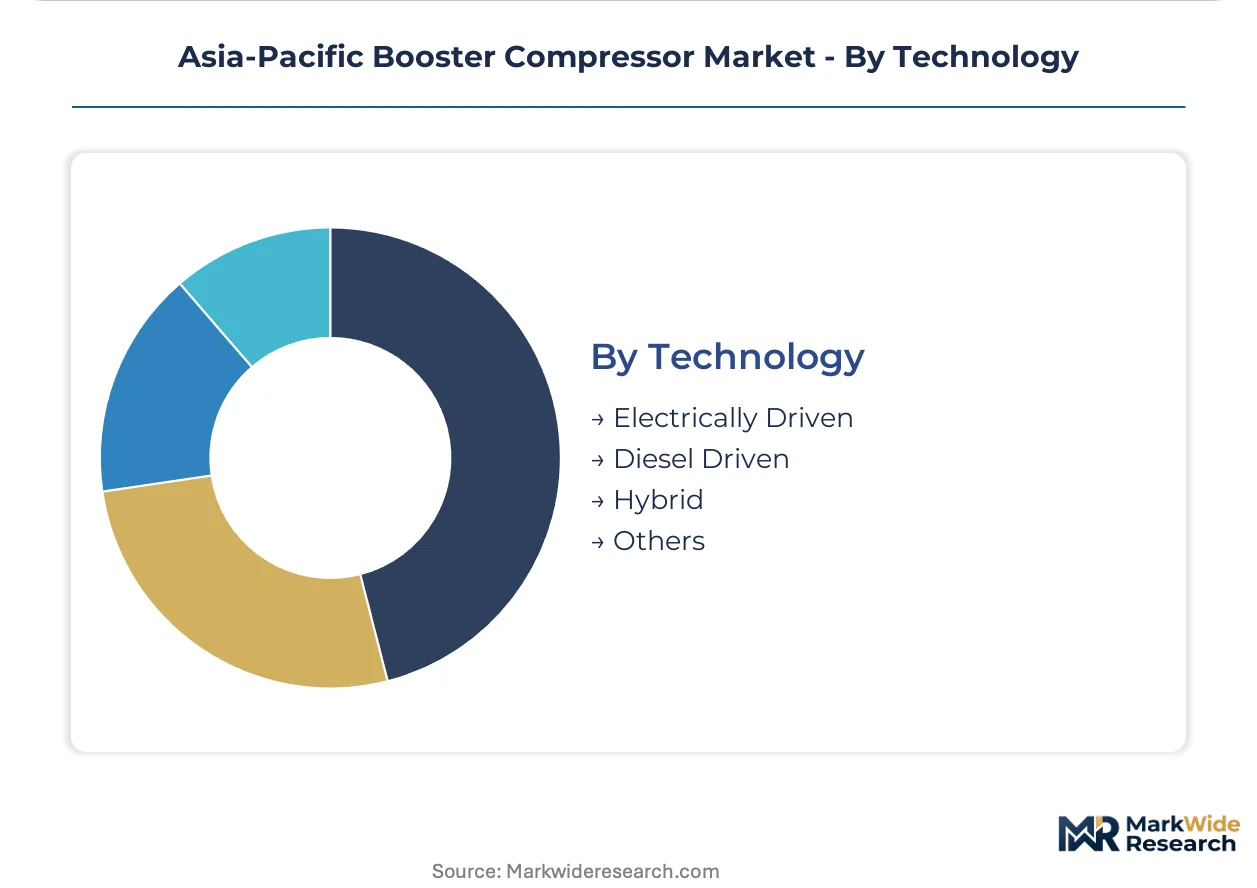
Technology:
Supply concentration for drive systems clusters around Japanese and German precision casting networks for permanent magnet motor components.
- Electrically Driven:Variable frequency drive compatibility enables MIIT GB standard compliance and condition monitoring integration. Japan's hydrogen mobility trials and China's state-backed industrial parks are mandating these configurations.
- Diesel Driven:Internal combustion powertrains retain necessity in Mongolia's mining corridors and Indonesian agricultural hinterlands where electrification infrastructure remains absent.
- Hybrid:Dual-mode architectures switch between grid and onboard generation for operational flexibility.
- Others:Emerging drive technologies including hydraulic and pneumatic power transmission occupy niche applications.
Electrically driven systems dominate technology roadmaps. Diesel driven maintains defensive positioning in remote geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision casting capacity for multi-stage rotary configurations concentrates in select Japanese and German supplier networks, creating single-source vulnerability that shapes procurement timelines across the region. Equipment qualification protocols diverge sharply between state-backed industrial parks and remote mining corridors.
China
MIIT GB energy-efficiency standards filter sub-tier equipment from state-backed industrial parks in Jiangsu and Zhejiang provinces. Dual carbon procurement mandates in Shanghai and the Pearl River Delta electronics clusters are accelerating technology refresh cycles toward variable frequency drive compatibility.
Japan
METI subsidizes hydrogen-compatible compressor retrofits under national decarbonization roadmaps, lifting demand for high-pressure gas compression systems in mobility trials. Kanto region hydrogen refueling station operators specify compact integrated motor-compressor packages for space-constrained urban deployments.
South Korea
MFDS-equivalent pressure equipment safety frameworks govern qualification timelines for hydrogen infrastructure buildout. Seoul Capital Area refueling networks are adopting electrically driven architectures as national hydrogen economy roadmaps tighten procurement standards.
India
BIS certification mandates and the PLI scheme tighten market access for imported units while nurturing domestic assembly capacity. Maharashtra and Gujarat manufacturing clusters are redirecting procurement toward locally certified equipment as the scheme matures.
Australia
TGA-equivalent pressure equipment safety frameworks reshape cross-border equipment qualification timelines for mining operators. Western Australia's iron ore corridors sustain diesel-driven mobile unit demand where remote monitoring infrastructure enables predictive maintenance without routine site visits.
Asia-Pacific Booster Compressor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific booster compressor landscape. Integrated motor-compressor specialists command premium positioning in hydrogen mobility trials, while heavy-duty reciprocating fabricators anchor oil and gas procurement through API compliance. Three strategic archetypes dominate: full-line industrial conglomerates with aftermarket service density, precision component specialists with permanent magnet motor expertise, and regional assembly players leveraging domestic manufacturing incentives. Competitive moves concentrate on portfolio diversification into hydrogen-compatible architectures and geographic expansion through multi-jurisdictional certification achievement.
Among European-origin industrial conglomerates, Atlas Copco Ltd and Siemens Energy occupy positions spanning technology leadership and service network density. Japanese heavy industrial players including Hitachi Ltd exemplify the integrated motor-compressor archetype that dominates hydrogen mobility trials. Bauer Kompressoren represents the precision high-pressure specialization segment serving oil and gas applications.
| Leading Market Players |
|---|
| Atlas Copco Ltd |
| Hitachi Ltd |
| IDEX India Private Ltd |
| Bauer Kompressoren |
| Mikuni Kikai Kogyo Co Ltd |
| Ingersoll Rand PLC |
| Siemens Energy |
| Mitsubishi Heavy Industries Ltd |
| Gardner Denver |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at precision casting foundries in Japan and Germany governs both supply availability and price floors for multi-stage rotary configurations. High-pressure reciprocating piston manufacturers face margin compression when nickel-based superalloy input costs spike, forcing selective pass-through to oil and gas operators in Australia's offshore corridors.
Pricing Analysis
China's MIIT GB energy-efficiency standards dictate the pricing tier structure across the Asia-Pacific booster compressor landscape. Three-tier pricing separates API 618-certified heavy-duty units from variable frequency drive-compatible configurations and fixed-speed legacy equipment now disqualified from state-backed procurement. Price differentiation hinges on certification grade and after-sales service bundling, with mining operators in Western Australia negotiating outcome-based availability guarantees rather than fixed maintenance schedules. Cost compression in mid-tier rotary screw configurations is intensifying because India's PLI scheme redirects procurement toward locally certified equipment with reduced import duty exposure. Manufacturing clusters in China's Pearl River Delta exhibit highest price sensitivity, while hydrogen refueling station operators in Japan's Kanto region absorb premiums for compact integrated motor-compressor packages.
Supply Chain Analysis
Strait of Malacca transit routes underpin component logistics for permanent magnet motor casting networks concentrated in Japan and Germany. Precision forging capacity for multi-stage rotary configurations draws from Japanese metallurgical specialists and German supplier networks, with final assembly gravitating toward China's Jiangsu and Zhejiang industrial parks to satisfy MIIT GB compliance mandates. Raw material dependencies center on nickel-based superalloys for high-pressure reciprocating pistons, rare earth elements for permanent magnet motors, and specialized alloy steels for helical rotor mechanisms. Single-source vulnerability in precision casting capacity creates procurement timeline risk when qualification cycles extend for hydrogen-compatible retrofits. Distribution runs through direct manufacturer relationships for heavy-duty stationary units and regional distributor networks with aftermarket service bundling for compact rotary configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific booster compressor market is recovering from cyclical compression as China's dual carbon procurement mandates force technology refresh cycles across state-backed industrial parks. Capital expenditure timing now favors electrically driven architectures over diesel-driven legacy units.
For Market Incumbents: Shield installed base revenue by embedding predictive analytics subscriptions that fragment traditional maintenance contracts into discrete service tiers. Lock in channel control through multi-jurisdictional certification achievement ahead of evolving ASEAN mutual recognition protocols. Backward integration into permanent magnet motor component supply reduces exposure to Japanese and German precision casting concentration.
For New Entrants and Emerging Players: Lead with hydrogen-compatible compressor retrofits in South Korea's Seoul Capital Area, where MFDS-equivalent pressure equipment frameworks are tightening but certification pathways remain less congested than Japan's METI-subsidized corridor. Target Mongolia's mining corridors with diesel-driven mobile units where grid connectivity gaps persist and incumbent service density remains thin. Pursue joint venture structures with Indian domestic assembly players to leverage PLI scheme procurement redirection.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket service specialists with remote monitoring infrastructure deployed across Australia's iron ore corridors. Long-term viability favors integrated motor-compressor technology holders over pure-play reciprocating fabricators exposed to nickel-based superalloy price volatility. Watch hydrogen refueling station deployment velocity in Japan and South Korea as the primary inflection indicator for high-pressure gas compression system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Compatible Retrofit Program | METI subsidies in Japan accelerate high-pressure gas compression demand for mobility trials. |
| Multi-Jurisdictional Certification Achievement | ASEAN mutual recognition protocols create first-mover advantage for cross-border equipment qualification. |
| Integrated Motor-Compressor R&D Investment | Direct-drive permanent magnet technology eliminates gearbox maintenance for hydrogen refueling stations. |
| Domestic Assembly Capacity Expansion | India's PLI scheme redirects procurement toward locally certified equipment in Maharashtra and Gujarat. |
| Predictive Analytics Platform Deployment | Remote monitoring infrastructure enables compressor health diagnostics without routine site visits in Western Australia. |
Research Methodology
Desk research of customs trade data, MIIT GB standard filings, and SEC 10-K equipment disclosures preceded structured interviews with plant engineers at China's state-backed industrial parks, aftermarket service heads at Australian mining operators, and procurement leads at Japanese hydrogen refueling station developers. Primary fieldwork combined bottom-up unit deployment tracking across Shanghai and Pearl River Delta clusters with top-down validation against BIS certification registries and METI subsidy disbursement records. Analysts triangulated manufacturer capacity announcements, foundry utilization reports, and distributor inventory positions to cross-verify demand signals.
Variance decomposition across product type, pressure rating tier, drive system technology, and end-use application shaped the analytical framework over the projection horizon. CAGRs derived from segment-level unit economics and replacement cycle analysis, with hydrogen infrastructure buildout velocity and dual carbon compliance timelines as industry-specific forecast inputs. Modeling incorporated API 618 certification pipeline status, PLI scheme maturity curves, and rare earth element price trajectories as sensitivity parameters.
The analysis sits within stated boundaries; outcomes outside sustained METI subsidy continuity, stable nickel-based superalloy pricing, and progressive ASEAN regulatory harmonization would require recalibration. Practitioners should keep alternative scenarios live as China's MIIT enforcement intensity and South Korea's hydrogen economy roadmap execution evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Bus Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
USA Scroll Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Tandem Piston Compressors Market
Compressors
Compressed Air Lubricators Market
Compressors
Root Blower Market
Compressors
North America Air Compressor Market