
 Gas Compressors Market | 2026-2036
Gas Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Compressors Market Intelligence
API 618 qualification for reciprocating compressors in heavy-duty process service is rotating the competitive set toward vendors with certified testing infrastructure. General Electric Company leverages its aeroderivative turbine integration to anchor large-frame centrifugal installations across LNG liquefaction trains. Siemens AG competes through digital twin diagnostics bundled with variable-speed drive packages. Atlas Copco AB differentiates via oil-free rotary screw designs that sustain medical and food-grade certification cycles.
Gas compressors are mechanical devices that raise gas pressure through positive displacement or dynamic action, typically achieving discharge pressures from a few bar to over 1,000 bar depending on stage configuration and casing design. They serve critical functions in natural gas transport, chemical synthesis, and industrial refrigeration by overcoming pipeline friction, enabling phase changes, or concentrating gases for storage. Reciprocating compressors dominate high-pressure applications such as hydrogen filling stations and gas injection, where their ability to handle extreme pressure ratios preserves margin pools despite higher maintenance intensity. Centrifugal compressors lead in base-load natural gas processing and large-scale refrigeration, with demand scaling alongside LNG export capacity additions. Oil-free technology across rotary screw and centrifugal formats is capturing preference in medical gas supply and food processing, where contamination risk eliminates oil-flooded alternatives from specification.
The EPA enforces methane performance standards under New Source Performance Standards for compressors, while the EU F-Gas Regulation constrains refrigerant compressor designs with high global warming potential working fluids. OSHA's process safety management rules and the EU's ATEX directives further shape compressor sealing, ventilation, and material specifications for hazardous area deployment. Buyers must monitor how the EU Green Deal's carbon border adjustments and evolving EPA methane monitoring rules will recalibrate total cost of ownership calculations across compressor lifecycles.
Market Dynamics
EPA methane performance standards under New Source Performance Standards are compressing compressor seal and venting specifications, forcing capital retooling across the installed base while hydrogen refueling infrastructure pulls parallel investment into high-pressure reciprocating units.
Growth Catalysts
- Hydrogen refueling infrastructure:Energy transition investments in Texas and the US Gulf Coast petrochemical corridor are accelerating demand for high-pressure reciprocating compressors capable of 350-700 bar discharge pressures.
- EU F-Gas Regulation:Constraints on high global warming potential refrigerants are redirecting compressor design toward low-GWP working fluids in industrial refrigeration applications.
- API 618 qualification:Heavy-duty process service certification requirements are concentrating procurement decisions toward vendors with certified testing infrastructure for reciprocating units.
Market Restraints
- Specialized alloy input costs:Nickel-based superalloys and chromium-molybdenum steels for high-pressure casings exhibit price volatility tied to mining concentration in Indonesia and South Africa.
- Seal technology supply concentration:Dry gas seal manufacturing for centrifugal compressors clusters among a limited set of precision-machining suppliers in Germany and Switzerland.
- Reciprocating maintenance intensity:Valve and packing replacement cycles impose operational downtime that centrifugal alternatives avoid in base-load natural gas processing.
Strategic Opportunities
- Carbon border adjustment mechanics:The EU Green Deal's carbon border adjustment mechanism creates first-mover advantage for compressor manufacturers with lifecycle emissions documentation.
- Medical gas certification cycles:Oil-free rotary screw designs sustaining ISO 8573-1 Class 0 certification are capturing preference in hospital oxygen supply and pharmaceutical nitrogen systems.
- Digital twin diagnostics convergence:Variable-speed drive packages integrated with predictive maintenance algorithms are opening premium service revenue streams in LNG liquefaction train operations.
Industry Challenges
- API 618 certification timeline:Reciprocating compressor qualification for heavy-duty process service requires 12-18 month test cycles that delay revenue recognition.
- Legacy control system integration:Digital twin diagnostics deployment faces friction from existing SCADA architectures in brownfield petrochemical facilities.
- Specialized welding technician scarcity:ASME Section IX-qualified welders for high-pressure casing fabrication are concentrated among aging workforce cohorts in Houston and Rotterdam.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Compressors Market |
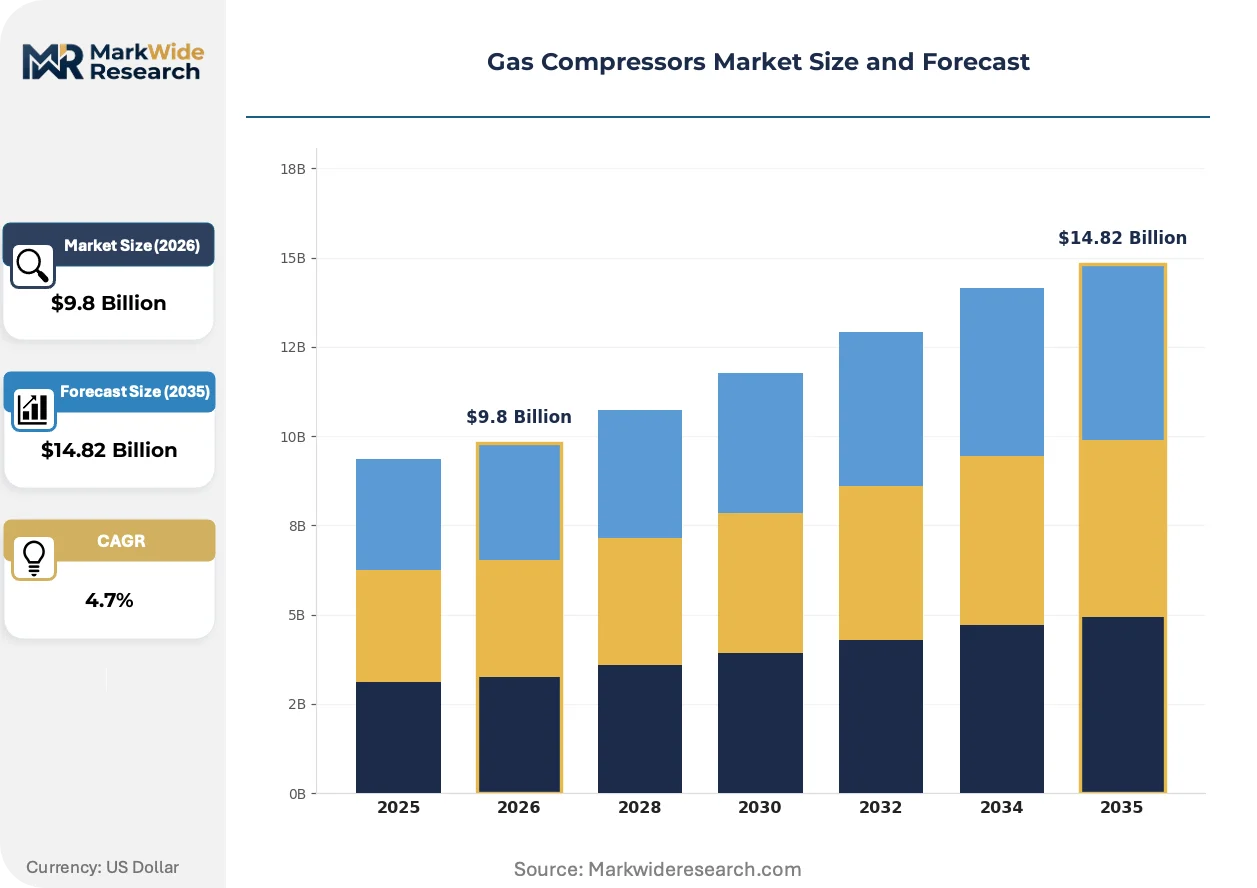
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.82 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating Compressors, Rotary Screw Compressors, Centrifugal Compressors, Diaphragm Compressors End User: Oil & Gas, Chemical Manufacturing, Power Generation, Food & Beverage Technology: Oil-Flooded, Oil-Free, Variable Speed, Fixed Speed Application: Natural Gas Processing, Refrigeration, Medical Gas Supply, Pneumatic Conveyance |
| Companies Covered | Bauer Compressors Inc., General Electric Company, Ariel Corporation, Howden Group Ltd, Siemens AG, Atlas Copco AB, Burckhardt Compression Holding AG, Clean Energy Fuels Corp., Ingersoll Rand PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Compressors Market Strategic Shifts & Innovations
Digital instrumentation and predictive algorithms are reconfiguring compressor lifecycle economics, while regulatory pressure on methane and refrigerant emissions accelerates hardware redesign across both dynamic and positive displacement architectures.
Magnetic bearing technology is fragmenting traditional oil-lubricated bearing maintenance schedules in large-frame centrifugal compressors. LNG liquefaction operators in Qatar and Australia are adopting active magnetic bearing systems to eliminate lube oil systems and extend maintenance intervals. This displacement of conventional bearing architectures is fragmenting aftermarket service revenue pools toward sensor and control module suppliers.
The EPA's methane emissions rules under New Source Performance Standards are tightening compressor seal and venting standards for both new and modified units. Operators must deploy dry gas seals or route rod packing emissions to combustion devices, adding capital cost but enabling permit compliance. The Permian Basin and Bakken shale plays face the most immediate compliance deadlines, compressing procurement cycles for certified equipment.
Service contract unbundling is separating compressor maintenance from original equipment supply in petrochemical and refining sectors. End-users in the US Gulf Coast are fragmenting long-term service agreements into component-level contracts with independent repair shops. This disintermediation of OEM service channels is most visible among ethylene crackers and ammonia plants seeking hourly-rate technicians over fixed-fee coverage.
Gas Compressors Market Segmentation
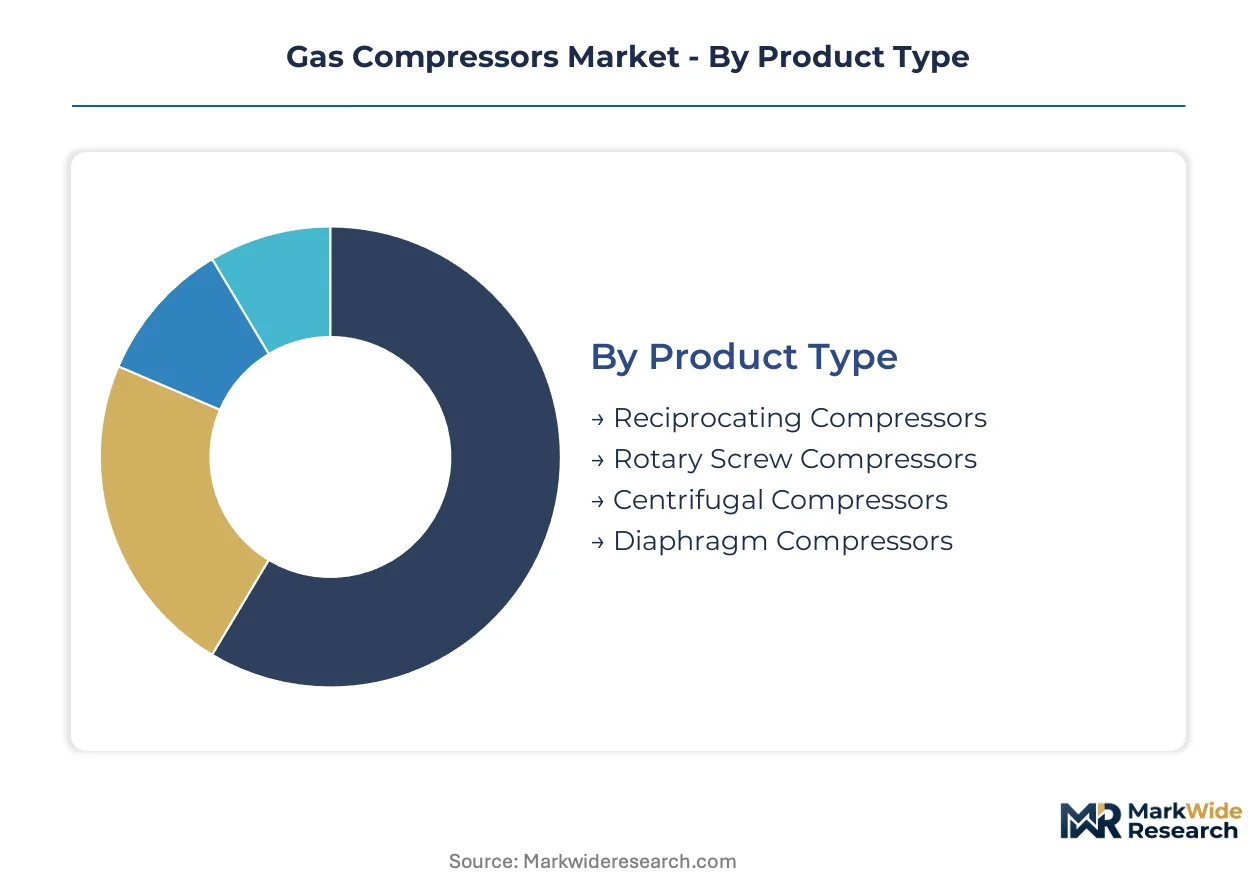
Compressor procurement decisions diverge sharply across product architectures and end-use specifications, with margin pools concentrating in high-pressure reciprocating units for hydrogen infrastructure and oil-free designs for regulated medical applications. Technology choices around lubrication and speed control further stratify lifecycle cost structures, while application-specific certification requirements lock in vendor relationships across decades-long equipment lifecycles.
Product Type:
Margin pools concentrate in high-pressure positive displacement architectures where material specifications and API certification barriers limit supplier entry.
- Reciprocating Compressors:Piston-driven positive displacement units achieve discharge pressures exceeding 700 bar through multi-stage configurations with forged steel crankcases and specialized valve metallurgy. Demand is concentrating in Texas hydrogen refueling stations and US Gulf Coast petrochemical corridors where 350-700 bar compression specifications are mandatory for heavy-duty fuel cell vehicle dispensing.
- Centrifugal Compressors:Dynamic compression via impeller acceleration dominates base-load natural gas processing and LNG liquefaction trains with continuous-duty reliability exceeding 99%. Qatar and Australian LNG operators are adopting active magnetic bearing variants to eliminate lube oil systems and extend maintenance intervals beyond 80,000 operating hours.
- Rotary Screw Compressors:Helical rotor meshing delivers pulsation-free flow for industrial refrigeration and pneumatic systems with compact footprint advantages.
- Diaphragm Compressors:Hydraulically actuated membrane isolation enables ultra-high purity compression for semiconductor process gases and laboratory applications.
The dominant share belongs to centrifugal compressors in base-load processing, while reciprocating units are closing the gap fastest on hydrogen infrastructure pull.
End User:
Application-specific certification cycles and emissions compliance timelines create divergent procurement rhythms across industrial verticals.
- Oil & Gas:Upstream gathering, midstream transmission, and downstream refining operations deploy the full compressor technology spectrum from wellhead gas lift to refinery hydrogen recycle. EPA methane performance standards under New Source Performance Standards are forcing seal retrofits and venting controls across Permian Basin and Bakken shale installations.
- Chemical Manufacturing:Ammonia synthesis, ethylene cracking, and methanol production require corrosion-resistant materials for synthesis gas and process stream handling. Ethylene crackers on the US Gulf Coast are fragmenting long-term service agreements into component-level contracts with independent repair shops.
- Power Generation:Gas turbine fuel gas boosting and combined cycle plant instrument air systems demand high reliability with minimal unplanned outage exposure.
- Food & Beverage:Carbon dioxide recovery and nitrogen inerting operations require oil-free compression to prevent product contamination.
Oil and gas maintains the largest installed base, though chemical manufacturing is expanding most quickly on petrochemical capacity additions.
Technology:
Speed control architectures and lubrication strategies determine maintenance intensity and energy recovery potential across operating profiles.
- Oil-Free:Dry-running rotors and advanced coating technologies eliminate hydrocarbon contamination risk for ISO 8573-1 Class 0 certification. Hospital oxygen supply and pharmaceutical nitrogen systems in Germany and Switzerland mandate oil-free designs.
- Variable Speed:Integrated variable frequency drives match compressor output to fluctuating demand curves, reducing energy consumption during partial-load operation. LNG liquefaction trains in Qatar are pairing variable-speed centrifugal packages with digital twin diagnostics for predictive maintenance revenue streams.
- Oil-Flooded:Lubricant injection provides sealing, cooling, and wear reduction for continuous-duty industrial applications with established maintenance protocols.
- Fixed Speed:Constant-speed motors with load-unload control offer capital simplicity for steady-demand applications where energy efficiency is secondary to acquisition cost.
Oil-flooded technology retains the broadest deployment, while variable speed is gaining share fastest on energy efficiency mandates.
Application:
Process criticality and regulatory exposure vary dramatically across compression duties, from life-sustaining medical systems to bulk commodity gas movement.
- Natural Gas Processing:Acid gas removal, dehydration, and NGL recovery require multi-stage compression with sour gas metallurgy specifications. US Gulf Coast processing plants face compressed procurement cycles for EPA-compliant seal packages.
- Refrigeration:Industrial cold chain and chemical process cooling depend on compressor reliability for temperature-sensitive operations. EU F-Gas Regulation constraints on high global warming potential refrigerants are redirecting designs toward low-GWP working fluids.
- Medical Gas Supply:Hospital oxygen, nitrous oxide, and surgical air systems demand continuous purity verification with regulatory documentation. Oil-free rotary screw designs sustaining certification cycles are capturing preference in European hospital networks.
- Pneumatic Conveyance:Bulk material transport and factory automation rely on oil-free or filtered air supply to prevent product contamination.
Natural gas processing commands the largest equipment value per installation, while medical gas supply shows the steepest expansion trajectory on healthcare infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream operators and hydrogen infrastructure developers concentrate compressor procurement in petrochemical corridors and shale basins where EPA methane rules and energy transition investments intersect. Procurement rhythms diverge sharply between legacy natural gas processing hubs and emerging hydrogen refueling clusters.
United States
Permian Basin and Bakken shale operators face compressed EPA compliance deadlines for methane seal retrofits and venting controls. The EPA's New Source Performance Standards force capital retooling across Texas and Gulf Coast petrochemical corridors. Houston anchors the largest concentration of ASME Section IX-qualified welders for high-pressure casing fabrication.
Germany
Industrial refrigeration demand redirects toward low-GWP working fluids under EU F-Gas Regulation constraints on high global warming potential refrigerants. The country's national chemical regulator enforces ATEX directives for hazardous area compressor deployment. The Rhine-Ruhr industrial cluster concentrates oil-free rotary screw procurement for pharmaceutical nitrogen systems.
China
LNG liquefaction capacity additions in coastal provinces drive centrifugal compressor demand for base-load natural gas processing. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate magnetic bearing adoption to eliminate lube oil systems. Yangtze River Delta petrochemical complexes represent the fastest-growing regional demand for variable-speed drive packages.
Qatar
North Field expansion projects deploy active magnetic bearing centrifugal systems to extend maintenance intervals beyond 80,000 operating hours. The national hydrocarbon regulator mandates emissions documentation aligned with EU Green Deal carbon border adjustment mechanics. Ras Laffan Industrial City concentrates large-frame LNG train compressor installations with integrated digital twin diagnostics.
Australia
Pluto Train 2 and Scarborough LNG developments anchor demand for predictive maintenance-enabled centrifugal packages. The national environmental regulator enforces methane monitoring protocols for offshore gas processing infrastructure. Karratha and Gladstone industrial zones fragment service contract structures toward component-level independent repair shop agreements.
Gas Compressors Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with certified testing infrastructure and precision-machining specialists concentrated in German and Swiss sealing technology. The market exhibits tiered concentration between API 618-qualified reciprocating vendors and aeroderivative-integrated centrifugal suppliers. Two strategic archetypes dominate: full-lifecycle service integrators bundling digital diagnostics with hardware, and component specialists capturing aftermarket revenue through seal and bearing module supply. Competitive moves center on M&A for testing facility expansion and strategic partnerships for hydrogen refueling station qualification.
Within the diversified industrial tier, General Electric Company and Siemens AG exemplify full-system integration capabilities spanning turbine-compressor trains and variable-speed diagnostics. Among precision-machining specialists, Burckhardt Compression Holding AG occupies a position representing Swiss-engineered high-pressure reciprocating expertise. Atlas Copco AB anchors the oil-free rotary screw segment where medical and food-grade certification cycles create vendor lock-in. These three companies represent distinct competitive vectors: aeroderivative integration, precision-engineered positive displacement, and contamination-critical oil-free architectures.
| Leading Market Players |
|---|
| Bauer Compressors Inc. |
| General Electric Company |
| Ariel Corporation |
| Howden Group Ltd |
| Siemens AG |
| Atlas Copco AB |
| Burckhardt Compression Holding AG |
| Clean Energy Fuels Corp. |
| Ingersoll Rand PLC |
| Others |
Cost & Logistics Intelligence
Twelve-to-eighteen-month API 618 certification timelines compress working capital cycles and amplify pricing power for vendors with certified testing infrastructure, while buyers face accelerated procurement deadlines under EPA methane compliance windows.
Pricing Analysis
Cost-plus contracts indexed to nickel and chromium-molybdenum steel price indices dominate high-pressure reciprocating compressor procurement, with API 618 certification tier and dry gas seal specification grade driving price differentiation between qualified and unqualified vendors. Pricing pressure stems from specialized alloy input volatility tied to Indonesian and South African mining concentration. Large-frame centrifugal buyers in LNG liquefaction show lowest price sensitivity due to lifecycle reliability premiums, while independent repair shops in the US Gulf Coast petrochemical corridor exhibit highest sensitivity as they fragment service contract structures toward hourly-rate coverage.
Supply Chain Analysis
Germany and Switzerland anchor dry gas seal manufacturing for centrifugal compressors, while Indonesia and South Africa concentrate nickel-based superalloy mining for high-pressure casings. Supply chains draw from chromium-molybdenum steel mills in Houston and Rotterdam, with ASME Section IX-qualified welding capacity concentrated among aging workforce cohorts. Single-source vulnerability runs through precision-machining suppliers for magnetic bearing control modules. Distribution runs through OEM-direct channels for large-frame LNG train installations and independent repair networks for brownfield petrochemical service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin diagnostics and predictive maintenance algorithms expand service-attach revenue faster than hardware sales, as LNG operators in Qatar and Australia unbundle long-term agreements into component-level subscriptions.
For Market Incumbents: Secure API 618 testing infrastructure expansion to defend against emerging precision-machining specialists from Switzerland and Germany. Deepen backward integration into dry gas seal manufacturing to capture margin pools fragmenting toward sensor and control module suppliers. Lock in exclusive welding technician training pipelines with Houston and Rotterdam fabrication centers to preempt capability scarcity. For New Entrants and Emerging Players: Differentiate on oil-free rotary screw designs for ISO 8573-1 Class 0 medical gas certification cycles in European hospital networks. Target hydrogen refueling infrastructure in Texas and the US Gulf Coast where 350-700 bar compression specifications outpace qualified vendor capacity. Pursue component-level service contracts with ethylene crackers seeking hourly-rate technicians over fixed-fee OEM coverage. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA methane rules and EU F-Gas Regulation constraints permanently expand addressable market for certified equipment. Acquisition candidates include precision-machining specialists with dry gas seal capabilities and digital twin diagnostics platforms with LNG liquefaction train deployment records. Monitor magnetic bearing adoption rates in Qatar North Field expansion projects as inflection signal for maintenance-interval extension demand.| Strategic Initiative | Industry Significance |
|---|---|
| API 618 Testing Infrastructure Expansion | Certified testing capacity locks in procurement decisions for heavy-duty reciprocating units under EPA methane deadlines. |
| Digital Twin Diagnostics Integration | Predictive maintenance algorithms open premium service revenue streams with Qatar and Australian LNG operators. |
| Backward Integration into Dry Gas Seals | In-house precision machining captures margin pools fragmenting from traditional oil-lubricated bearing maintenance schedules. |
| Oil-Free Certification Cycle Investment | ISO 8573-1 Class 0 designs sustain vendor lock-in across European hospital oxygen and pharmaceutical nitrogen systems. |
| Hydrogen Refueling Qualification Partnerships | 350-700 bar compression expertise anchors demand from Texas and US Gulf Coast energy transition investments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, EU ECHA regulatory filings, and customs trade data, with input from maintenance directors at LNG liquefaction facilities, plant engineers in US Gulf Coast petrochemical complexes, aftermarket service heads at centrifugal compressor OEMs, and procurement leads at hydrogen refueling station developers. Bottom-up equipment shipment tracking triangulates against top-down energy infrastructure investment forecasts.
Segmentation dimensions modeled include compressor architecture type, end-use vertical, lubrication technology, speed control configuration, and regional regulatory compliance cluster across the projection horizon. CAGRs derive from installed base replacement cycles, capacity addition pipelines, and emissions compliance deadline clustering. Forecast inputs incorporate magnetic bearing adoption trajectories and API 618 certification queue lengths.
The analysis sits within stated boundaries; outcomes outside sustained EPA methane enforcement, EU F-Gas Regulation stringency, or nickel alloy price stability would require recalibration. Recalibration cycles align with material shifts in regulatory compliance deadlines and energy transition investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Centrifugal Compressors Market
Compressors
Regenerative Blowers Market
Compressors
Root Blower Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Process Gas Compressors Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Axial Compressor Market
Compressors
LNG Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Air Compressor Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Tandem Piston Compressors Market
Compressors
Rotary Air Compressor Market