
 Japan Lithium-Ion Battery Market | 2026-2036
Japan Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Lithium-Ion Battery Market Outlook
Market Context
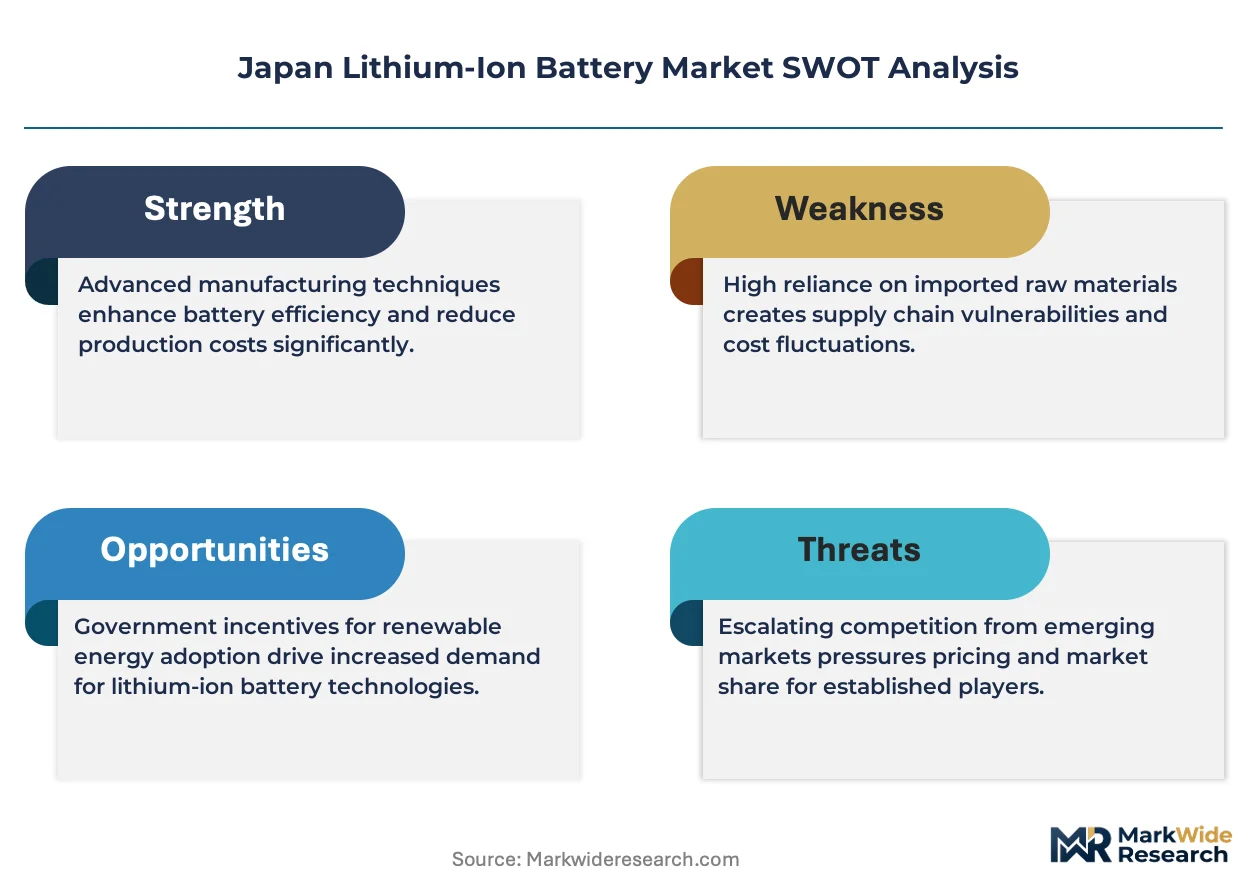
Japan's revised Battery Supply Chain Security Act is broadening the cost-of-entry calculus for foreign cathode and electrolyte suppliers seeking domestic qualification. Panasonic Energy leverages its vertical integration into cylindrical cell formats to sustain premium positioning in automotive contracts. Prime Planet Energy & Solutions anchors Toyota's electrification roadmap through dedicated NMC and LFP supply lines. GS Yuasa International competes in industrial and stationary storage segments where cycle-life requirements exceed energy density priorities.
Technical Definition and Segment Structure
A lithium-ion battery is a rechargeable electrochemical cell employing lithium compounds in the positive electrode and typically graphite in the negative electrode, with energy densities ranging from 150 Wh/kg in LFP systems to over 300 Wh/kg in high-nickel NMC variants, designed to store and discharge electrical energy through reversible lithium-ion intercalation. Its primary commercial purpose centers on portable power, electric traction, and grid-scale energy buffering where weight, volume, and cycle efficiency constrain alternative chemistries. The electric vehicle product type commands the dominant value share as Japanese automotive manufacturers commit platform-level electrification, while renewable energy storage represents the fastest-expanding margin pool driven by utility-scale solar pairing mandates. Within technology tiers, NMC formulations retain leadership in passenger EV applications, though LFP is gaining traction in commercial vehicles and stationary systems where cost-per-cycle economics override gravimetric density.
Regulatory Framework and Outlook
METI enforces domestic content thresholds and recycling recovery rates through its Battery Supply Chain Security Act, while JIS standards govern cell safety testing protocols and PMDA oversight extends to medical device power systems. These frameworks compel manufacturers to localize precursor refining and establish closed-loop material recovery, reshaping supplier qualification timelines and capital deployment patterns. Stakeholders must monitor the trajectory of METI's subsidy recalibration for solid-state R&D and the evolving interoperability standards between Japanese OEMs and European battery passport requirements.
Market Dynamics
Japan's lithium-ion battery sector is undergoing a forced supply chain reconfiguration as METI's domestic content mandates compel cathode precursor localization and closed-loop material recovery investments.
Growth Catalysts
- Automotive electrification mandates:Japanese OEM platform-level commitments to battery-electric drivetrains are pulling high-nickel NMC cell procurement volumes upward through dedicated supply agreements with domestic cell producers.
- METI Battery Supply Chain Security Act:This regulatory framework is accelerating capital deployment into precursor refining and electrolyte manufacturing within Japan's industrial corridors.
- Utility-scale solar pairing requirements:Grid operators in the Kansai region are mandating co-located battery storage for new renewable capacity, expanding stationary storage demand.
Market Restraints
- Cobalt and nickel price volatility:Cathode active material costs fluctuate with London Metal Exchange pricing, compressing cell producer margins during commodity spikes.
- Single-source precursor dependence:Japan's refined lithium supply concentrates among limited overseas converters, creating geographic concentration risk for domestic cell manufacturing.
- Energy density ceiling in LFP systems:Commercial vehicle applications face payload constraints where lithium iron phosphate gravimetric limits restrict range extension.
Strategic Opportunities
- Kyushu industrial corridor expansion:Underutilized port infrastructure and renewable energy access position this sub-region for gigascale cell and pack assembly investments.
- Second-life automotive battery applications:Retired EV cells are finding stationary storage deployment in commercial building backup systems, extending value capture.
- Solid-state electrolyte R&D subsidies:METI's targeted funding for sulfide and oxide solid-state development is compressing commercialization timelines for next-generation formats.
Industry Challenges
- Electrochemical engineering talent scarcity:Domestic universities produce insufficient cell design and manufacturing process specialists to match expansion timelines.
- JIS certification timeline compression:New cell formats face extended safety testing protocols that delay product launches against faster-moving competitors.
- Legacy thermal management integration:Existing automotive platforms require redesign to accommodate high-nickel cell thermal runaway profiles, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Lithium-Ion Battery Market |
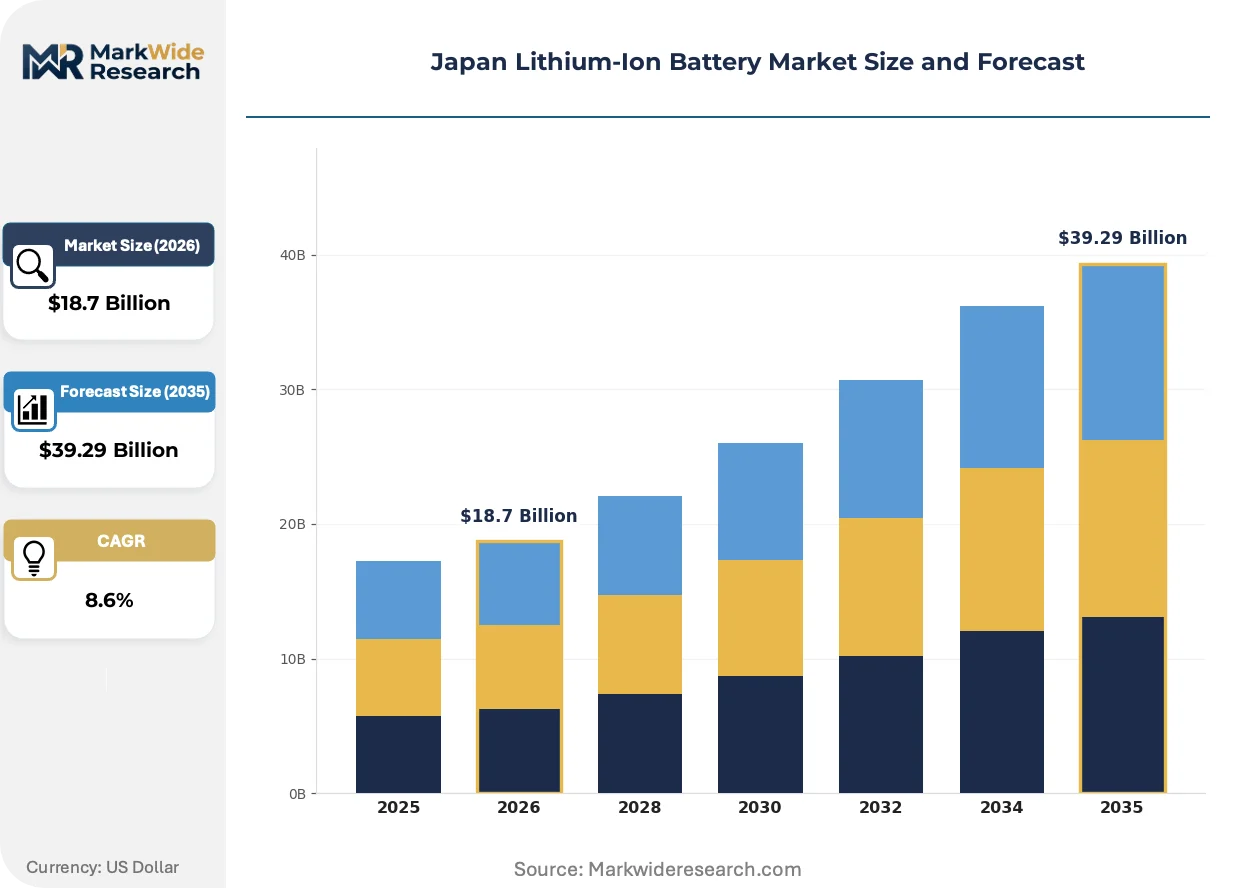
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment End User: Automotive Manufacturers, Electronics Companies, Utilities, Aerospace Technology: LFP, NMC, NCA, LCO Application: Energy Storage Systems, Mobile Devices, Electric Bikes, Power Tools |
| Companies Covered | Envision AESC, LG Energy Solution, Panasonic Energy, CATL, Samsung SDI, Prime Planet Energy & Solutions, Toshiba Corporation, BYD, GS Yuasa International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Lithium-Ion Battery Market Strategic Shifts
Solid-state and silicon-anode technologies are absorbing the bulk of Japanese R&D investment as manufacturers seek to leapfrog incremental liquid electrolyte improvements.
Silicon-composite anodes are absorbing incremental graphite replacement in cylindrical cells designed for premium automotive contracts. Panasonic Energy and Prime Planet Energy & Solutions are qualifying these materials for 2026 platform launches. The technology is absorbing energy density gains of 15-20 percent while compressing cobalt dependence in cathode formulations.
METI's Battery Supply Chain Security Act is forcing domestic qualification of previously imported cathode precursors and electrolyte salts. Cell producers must now source refined materials from Japanese-certified refiners or establish captive refining operations. The Kansai industrial corridor is absorbing the majority of this forced localization investment.
Automotive OEMs are consolidating cell procurement around long-term offtake agreements with volume commitments and price collars. Tier-1 suppliers are losing intermediation role as Toyota, Honda, and Nissan negotiate directly with Panasonic Energy and Prime Planet Energy & Solutions. This disintermediation is most visible in passenger EV contracts where platform-scale volumes justify direct relationships.
Japan Lithium-Ion Battery Market Segmentation
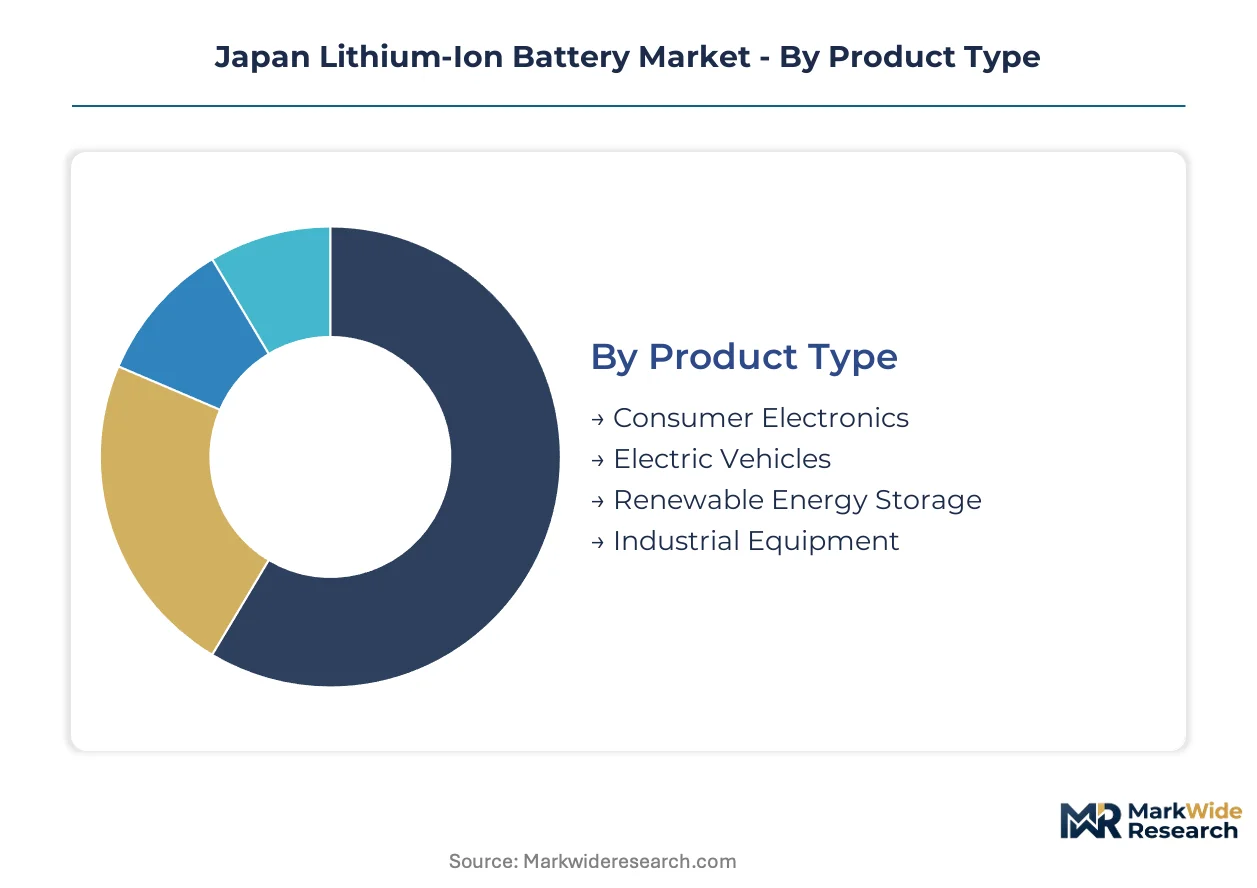
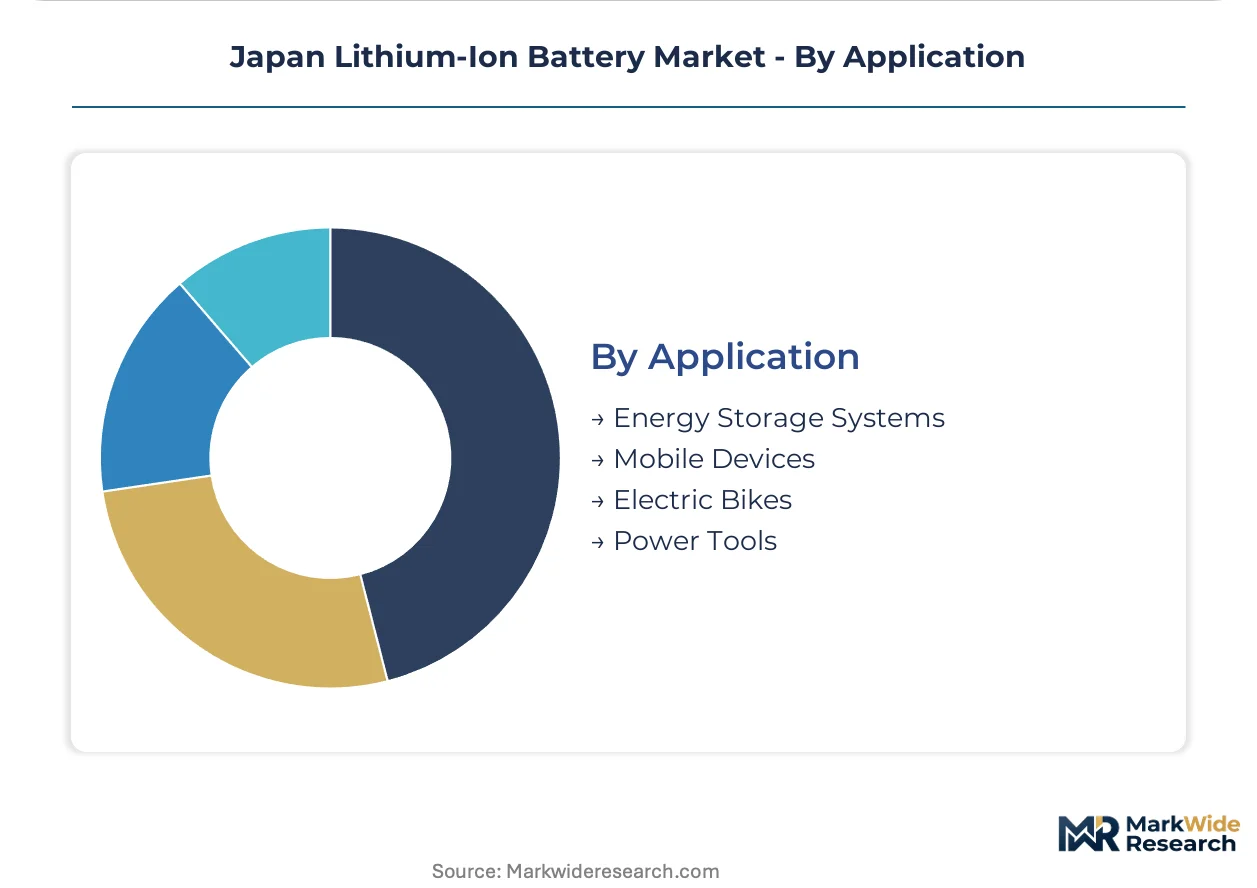
Japan's lithium-ion battery market segments around distinct performance thresholds and procurement cycles. Each dimension reveals how METI mandates and OEM electrification timelines reshape supplier priorities across cell formats and end-use categories.
Product Type:
Replacement cycles vary dramatically across portable, mobility, and stationary applications, compressing or extending payback horizons for buyers.
- Electric Vehicles:High-nickel cylindrical cells dominate platform-level contracts. Toyota, Honda, and Nissan procurement volumes anchor demand in the Kansai industrial corridor where Panasonic Energy and Prime Planet Energy & Solutions operate dedicated supply lines.
- Renewable Energy Storage:Grid-scale solar pairing mandates in the Kansai region are pulling utility-scale lithium-ion installations. Cycle-life economics override energy density in these stationary configurations.
- Consumer Electronics:LCO pouch cells serve smartphone and laptop manufacturers with compressed procurement cycles.
- Industrial Equipment:Forklift and warehouse automation applications favor LFP formats where safety and longevity matter more than gravimetric density.
Volume placements concentrate in Electric Vehicles; the faster expansion belongs to Renewable Energy Storage.
End User:
Procurement sophistication diverges sharply between integrated OEMs and fragmented downstream buyers.
- Automotive Manufacturers:Direct offtake agreements with cell producers now displace tier-1 supplier intermediation. Long-term volume commitments with price collars characterize Toyota and Honda negotiations.
- Utilities:Kansai Electric Power and regional grid operators mandate co-located storage for renewable capacity additions, creating procurement scale.
- Electronics Companies:Sony, Panasonic, and smaller device assemblers compete for cylindrical and pouch cell allocation with shorter contract horizons.
- Aerospace:JAXA and commercial aviation suppliers impose JIS-certified safety protocols that extend qualification timelines.
Contract value concentrates with Automotive Manufacturers; the steepest expansion trajectory is visible in Utilities procurement.
Technology:
Cathode chemistry selection hinges on the trade-off between energy density and supply chain security under METI localization mandates.
- NMC:Nickel-manganese-cobalt formulations retain leadership in passenger EV applications. High-nickel variants exceed 300 Wh/kg but face cobalt price volatility and METI domestic content requirements.
- LFP:Lithium iron phosphate gains traction in commercial vehicles and stationary systems where cost-per-cycle economics override gravimetric density limits.
- NCA:Nickel-cobalt-aluminum variants serve premium cylindrical formats for select automotive contracts.
- LCO:Lithium cobalt oxide remains entrenched in consumer electronics where energy density and form factor flexibility dominate.
Manufacturing scale concentrates in NMC; the fastest share gains are occurring in LFP.
Application:
Use-case thermal and cycling profiles dictate cell format and management system requirements.
- Energy Storage Systems:Containerized grid installations in Kyushu and Kansai absorb LFP and NMC cells with 15-20 year depreciation schedules.
- Mobile Devices:Smartphone and tablet applications drive demand for ultra-thin LCO pouch cells with compressed replacement cycles.
- Electric Bikes:Last-mile delivery and personal mobility applications favor compact cylindrical formats with moderate energy density.
- Power Tools:Professional construction equipment requires high-discharge-rate cells with robust thermal management.
Deployment scale concentrates in Energy Storage Systems; the most rapid volume climb is occurring in Electric Bikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's designated special zones for battery supply chain investment concentrate manufacturing capacity in four industrial corridors. METI's localization mandates and port infrastructure access determine where cell assembly and precursor refining operations settle.
Kansai
Osaka and Kyoto prefectures host the highest concentration of cell and pack assembly facilities serving Toyota and Honda procurement. METI's Battery Supply Chain Security Act requires domestic precursor qualification here. Panasonic Energy and Prime Planet Energy & Solutions operate dedicated supply lines in this corridor.
Kanto
Tokyo and Kanagawa prefectures concentrate R&D headquarters and JIS certification laboratories. The region absorbs engineering talent for solid-state electrolyte development. Chiba port facilities handle lithium carbonate imports for regional converters.
Kyushu
Fukuoka and Saga prefectures offer underutilized port infrastructure and renewable energy access for gigascale investments. METI subsidies target this sub-region for cathode active material localization. Regional utilities mandate co-located storage for solar capacity additions.
Chubu
Aichi and Shizuoka prefectures anchor automotive OEM headquarters pulling cell procurement volumes. Toyota's platform-level electrification commitments drive demand here. Nagoya port logistics support material throughput for regional assembly.
Tohoku
Miyagi and Fukushima prefectures host renewable energy storage deployments paired with utility-scale solar. Grid operators in this sub-region specify long-cycle-life configurations. Industrial land availability accommodates containerized energy storage system installations.
Japan Lithium-Ion Battery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Japan's lithium-ion battery sector. The market structure concentrates around vertically integrated energy divisions of industrial groups and dedicated cell producers serving automotive contracts. Three archetypes dominate: conglomerate-affiliated cell producers with captive OEM relationships, independent specialists in cylindrical formats, and industrial battery manufacturers prioritizing cycle life over energy density. Competitive moves center on long-term offtake negotiations with price collars and backward integration into precursor refining.
Within the conglomerate-affiliated tier, Panasonic Energy and Prime Planet Energy & Solutions occupy positions defined by their automotive supply relationships. GS Yuasa International exemplifies the industrial-specialist archetype serving stationary storage applications. These three entities represent distinct strategic postures: one anchored in premium cylindrical formats, one dedicated to Toyota's electrification roadmap, and one concentrated where longevity economics override gravimetric performance.
| Leading Market Players |
|---|
| Envision AESC |
| LG Energy Solution |
| Panasonic Energy |
| CATL |
| Samsung SDI |
| Prime Planet Energy & Solutions |
| Toshiba Corporation |
| BYD |
| GS Yuasa International |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM platform-level electrification commitments are forcing cell producers to reconfigure procurement timelines, compressing lead-time premiums for high-nickel NMC formats while extending contract durations to lock in cathode precursor supply. This demand-side pressure is reshaping how Panasonic Energy and Prime Planet Energy & Solutions structure offtake agreements with Toyota and Honda.
Pricing Analysis
Lead-time-driven pricing tiers separate urgent procurement from scheduled volume commitments, with short-lead-time orders commanding premiums of 15-25 percent above baseline contract rates. Contract-based long-term offtake agreements dominate automotive procurement, where volume scale and JIS certification tier differentiate pricing bands. Cost compression in LFP cells is intensifying because Chinese producers are expanding export capacity into Japanese utility-scale storage segments. Industrial equipment buyers exhibit highest price sensitivity due to cycle-life economics, while aerospace contractors show least sensitivity given JIS-certified safety requirements.
Supply Chain Analysis
Dual-sourcing mandates from METI's Battery Supply Chain Security Act require cell producers to qualify multiple cathode precursor refiners, fragmenting procurement concentration previously anchored in single-source relationships. Refined lithium supply draws from Chile, Australia, and domestic Japanese converters, while cobalt hydroxide and nickel sulfate rest on South Korean and Chinese processing capacity. Single-source vulnerability persists in electrolyte salt supply where Japanese producers depend on limited qualified importers. Distribution runs through dedicated automotive supply corridors linking Kansai assembly facilities to Chubu OEM headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
METI's domestic content thresholds function as a cost-of-compliance moat, elevating capital requirements for foreign cathode and electrolyte suppliers seeking Japanese qualification and advantaging incumbents with established precursor refining footprints.
For Market Incumbents: Anchor long-term offtake relationships through price collars that absorb cobalt and nickel volatility, while accelerating backward integration into cathode active material production in Kyushu to preempt METI localization mandates. Solid-state R&D subsidies present a defensive lever against emerging Korean and Chinese cell producers with faster format iteration cycles. For New Entrants and Emerging Players: Regional utilities in Tohoku represent the most penetrable demand pool, as grid operators mandate co-located storage for utility-scale solar without entrenched incumbent relationships. Second-life automotive battery refurbishment offers white-space entry with lower JIS certification barriers, enabling go-to-market through commercial building energy management integrators rather than direct OEM competition. For Investors and Strategic Acquirers: The window for entry favors industrial battery specialists with proven cycle-life engineering and established recycling partnerships, as electrification tailwinds extend across a 5-10 year capital deployment horizon. Watch METI's subsidy recalibration for solid-state R&D as the inflection signal determining which technology archetype captures next-generation platform contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Localization | METI mandates force domestic refining investment, reshaping supplier qualification timelines and capital deployment patterns in Kansai. |
| Solid-State Electrolyte R&D Partnership | Targeted METI funding compresses commercialization timelines for sulfide and oxide formats against liquid electrolyte incumbents. |
| Long-term Automotive Offtake Agreement | Direct negotiations between Toyota and Panasonic Energy displace tier-1 supplier intermediation in platform-scale procurement. |
| Second-Life Battery Refurbishment Facility | Retired EV cells from Kansai automotive corridors feed stationary storage demand in commercial building backup systems. |
| Utility-Scale Storage Co-location | Kansai Electric Power mandates pair renewable capacity additions with containerized lithium-ion installations absorbing LFP supply. |
Study Parameters
Multi-period observation of cell procurement volumes, cathode chemistry mix shifts, and METI subsidy disbursement patterns anchored the trend analysis, supplemented by interviews with battery cell manufacturing executives, automotive platform engineers, utility procurement officers, and materials refining specialists. Secondary validation drew from METI regulatory filings, JIS certification databases, customs trade records for lithium carbonate and cobalt imports, and industrial land use permits across designated special zones. Bottom-up cell production estimates and top-down automotive electrification targets were triangulated to constrain forecast variance.
Segment-weighting applied differential growth coefficients across NMC, LFP, NCA, and LCO chemistry tiers, with end-use splits for electric vehicles, renewable energy storage, consumer electronics, and industrial equipment calibrated against OEM platform announcements and utility solar pairing mandates. CAGRs were derived from installed capacity buildout trajectories and replacement cycle assumptions across the projection horizon. Key forecast inputs included METI localization timeline assumptions and solid-state electrolyte commercialization readiness indicators.
Caveats apply where cobalt and nickel price volatility, METI subsidy recalibration, or solid-state technology breakthrough timelines could materially shift the outlook. Deviation in METI's domestic content threshold enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market