
 Russia Reciprocating Compressor Market | 2026-2036
Russia Reciprocating Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Reciprocating Compressor Market Outlook
Russian compressor fabricators are pivoting toward import substitution as Western equipment sourcing channels narrow. Howden Group Ltd. leverages its aftermarket service footprint to sustain long-term contracts with Gazprom-operated facilities across the Yamal-Nenets Autonomous Okrug. Burckhardt Compression AG anchors its position through localized assembly partnerships that navigate customs and certification complexities. Atlas Copco AB competes on portable compressor configurations tailored to remote wellsite logistics.
A reciprocating compressor employs a piston-driven mechanism within a cylinder to compress gases through successive intake, compression, and discharge strokes, typically achieving discharge pressures from 100 to 6,000 bar depending on staging and cylinder configuration. Double-acting designs dominate heavy-process installations in petrochemical processing because simultaneous compression on both piston faces delivers higher throughput per unit footprint than single-acting alternatives. Gas compression applications for pipeline transport represent the fastest-growing segment as Russia expands trunkline capacity toward Eastern markets. Portable configurations occupy a niche role in exploration and workover operations where fixed infrastructure proves uneconomical.
Russia's Federal Service for Environmental, Technological and Nuclear Supervision (Rostekhnadzor) enforces TR TS 032/2013 certification for pressure equipment, while GOST R standards govern mechanical reliability testing protocols that filter out non-compliant imports. The Eurasian Economic Commission harmonizes technical regulations across Belarus, Kazakhstan, and Armenia, creating a unified conformity assessment pathway that reduces redundant testing for manufacturers targeting multiple post-Soviet markets. Stakeholders must monitor how sanctions-driven supply chain restructuring affects spare parts availability and whether domestic producers can scale precision machining capacity for high-pressure cylinder heads and valve assemblies.
Market Dynamics
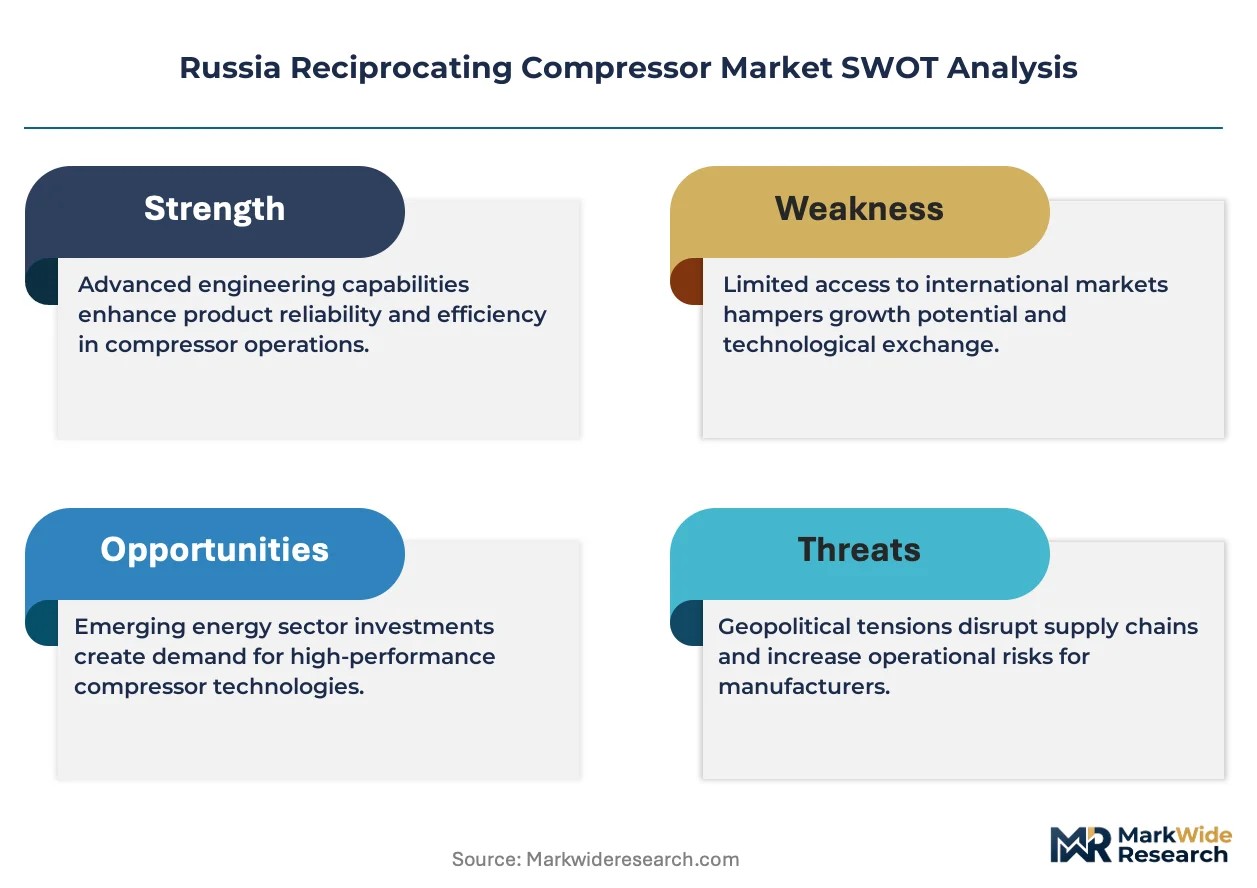
Western sanctions on precision-machined imports are forcing Russian compressor fabricators to requalify domestic cylinder-head foundries and valve-seat grinding operations. This supply-side rupture is compressing certification timelines while elevating procurement risk for high-pressure process operators.
Growth Catalysts
- Enhanced oil recovery mandates:Gazprom Neft and Rosneft are expanding compressor fleets across Western Siberia's mature fields. Operators require higher-pressure injection systems to maintain reservoir pressure.
- TR TS 032/2013 harmonization:The Eurasian Economic Commission's unified conformity assessment reduces redundant testing for manufacturers targeting Belarus, Kazakhstan, and Armenia alongside Russia.
- Eastern pipeline expansion:Trunkline capacity additions toward China and Asia-Pacific markets are accelerating demand for gas compression stations in the Yamal-Nenets Autonomous Okrug.
Market Restraints
- Specialized alloy scarcity:Nickel-based superalloys for high-pressure valve seats face import substitution delays. Domestic metallurgical capacity cannot yet match Western tempering specifications.
- Precision machining concentration:Cylinder-head grinding and honing equipment remains concentrated in German and Swiss supplier networks. Russian machine-tool builders lack five-axis CNC accuracy for critical sealing surfaces.
- Substitution by turbocompressors:Large-scale pipeline operators in the Volga-Ural corridor are evaluating centrifugal alternatives for base-load compression. Turbomachinery offers lower maintenance intensity at continuous-duty setpoints.
Strategic Opportunities
- Arctic LNG fabrication:Novatek's Gydan and Ob Bay projects require modular compressor packages rated for minus-fifty-degree ambient operation. Cold-climate engineering represents unmet white space.
- Refinery hydrogen circulation:Hydrocracker revamps across the Volga-Ural petrochemical corridor are specifying high-pressure hydrogen reciprocating units. Hydrogen embrittlement-resistant materials command premium positioning.
- Aftermarket service unbundling:Independent service providers are capturing valve-overhaul and cylinder-relining contracts previously held by OEMs. Parts-kit standardization enables third-party penetration.
Industry Challenges
- Rotating machinery technician scarcity:Crosshead alignment, bearing clearance measurement, and valve-timing calibration require skills concentrated in aging Soviet-trained cadres. Vocational pipelines have not replenished specialized mechanical fitters.
- Rostekhnadzor certification bottlenecks:Pressure-equipment safety audits face extended backlogs as inspectors prioritize sanctioned-entity compliance reviews. New-model approvals stretch beyond eighteen months.
- Legacy SCADA integration:Soviet-era compressor stations operate on proprietary control architectures. Modern digital monitoring systems require protocol translation layers that introduce cybersecurity exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Reciprocating Compressor Market |
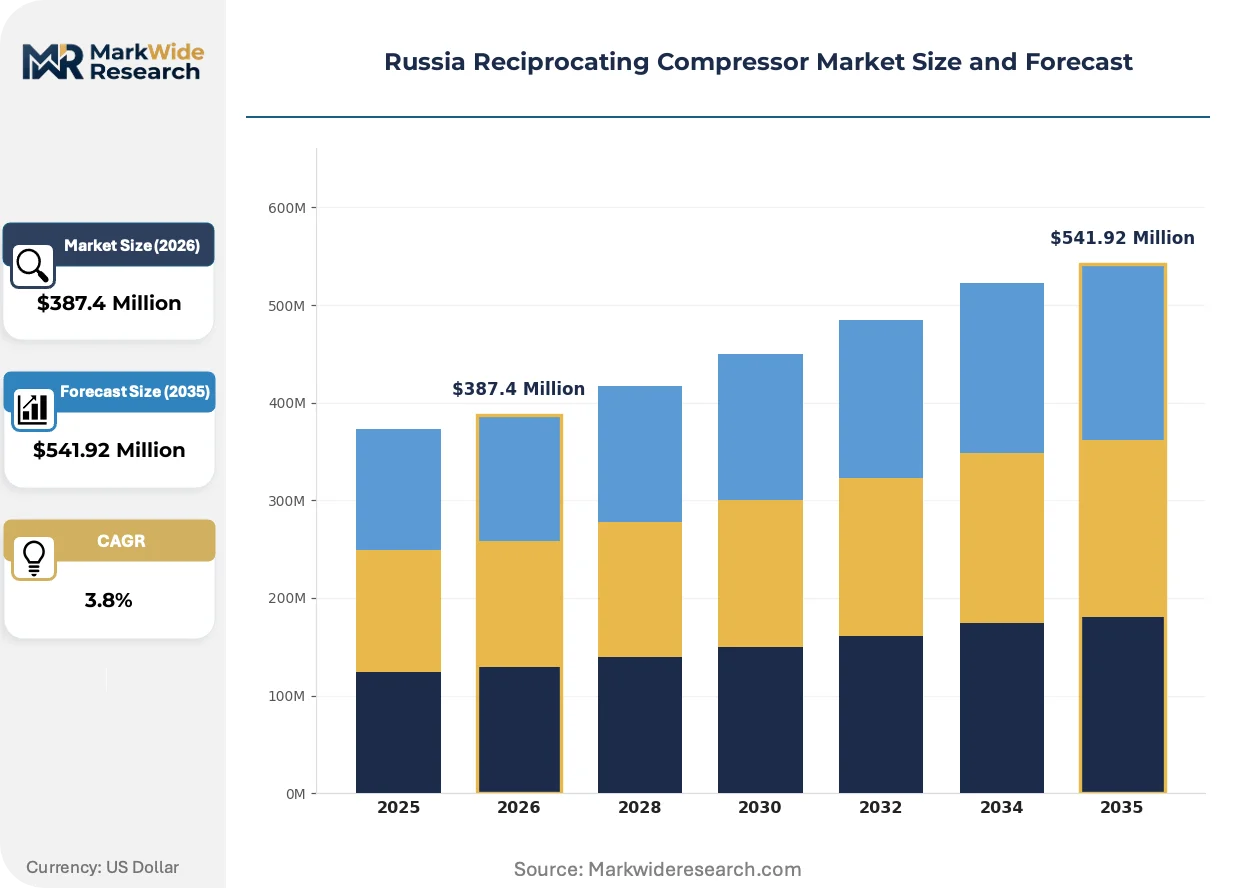
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $541.92 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Acting, Double-Acting, Multi-Stage, Portable Application: Petrochemical Processing, Refrigeration, HVAC, Gas Compression End User: Oil & Gas, Manufacturing, Food & Beverage, Chemical Industry Technology: Reciprocating, Electric Driven, Gas Driven, Hydraulic |
| Companies Covered | Howden Group Ltd., Burckhardt Compression AG, Atlas Copco AB, Ariel Corporation, Neuman & Esser Group, Kobelco Compressors Corporation, General Electric (Oil & Gas) Co., BORSIG ZM Compression GmbH, Dresser Rand Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Reciprocating Compressor Market Strategic Shifts
Digital condition-monitoring architectures and modular package designs are displacing fixed-site installations across Russia's remote hydrocarbon provinces. Fabricators are reconfiguring product lines around transportability and predictive maintenance capability.
Variable-speed drive integration is decentralizing compressor station design across the Yamal-Nenets Autonomous Okrug. Traditionally, operators deployed constant-speed units with recycle valves to manage fluctuating wellhead pressures. VSD-equipped reciprocating compressors now modulate piston stroke frequency directly, eliminating energy losses through bypass piping. Gazprom Dobycha Urengoy is retrofitting existing frames with medium-voltage drives to reduce fuel gas consumption at partial-load operating points.
Rostekhnadzor is tightening documentation requirements for pressure-equipment safety cases under TR TS 032/2013 amendments. Fabricators must now submit finite-element analysis of cylinder fatigue life and valve impact stress for each new model variant. The regulatory burden falls most heavily on small-batch custom builders serving specialty chemical applications in Tatarstan. These shops lack in-house simulation capacity and must outsource computational validation to certified third-party laboratories.
Buyers in Western Siberia are compressing replacement cycles for critical path units. Rather than rebuilding compressors at prescribed hour-intervals, operators now run to failure on non-critical trains while maintaining strategic spares inventory for immediate swap-out. This consumption-pattern shift elevates demand for standardized skid-mounted packages that minimize field installation time. Service providers in Tyumen Oblast are configuring mobile overhaul workshops to execute major repairs at wellpad rather than transporting equipment to central shops.
Russia Reciprocating Compressor Market Segmentation
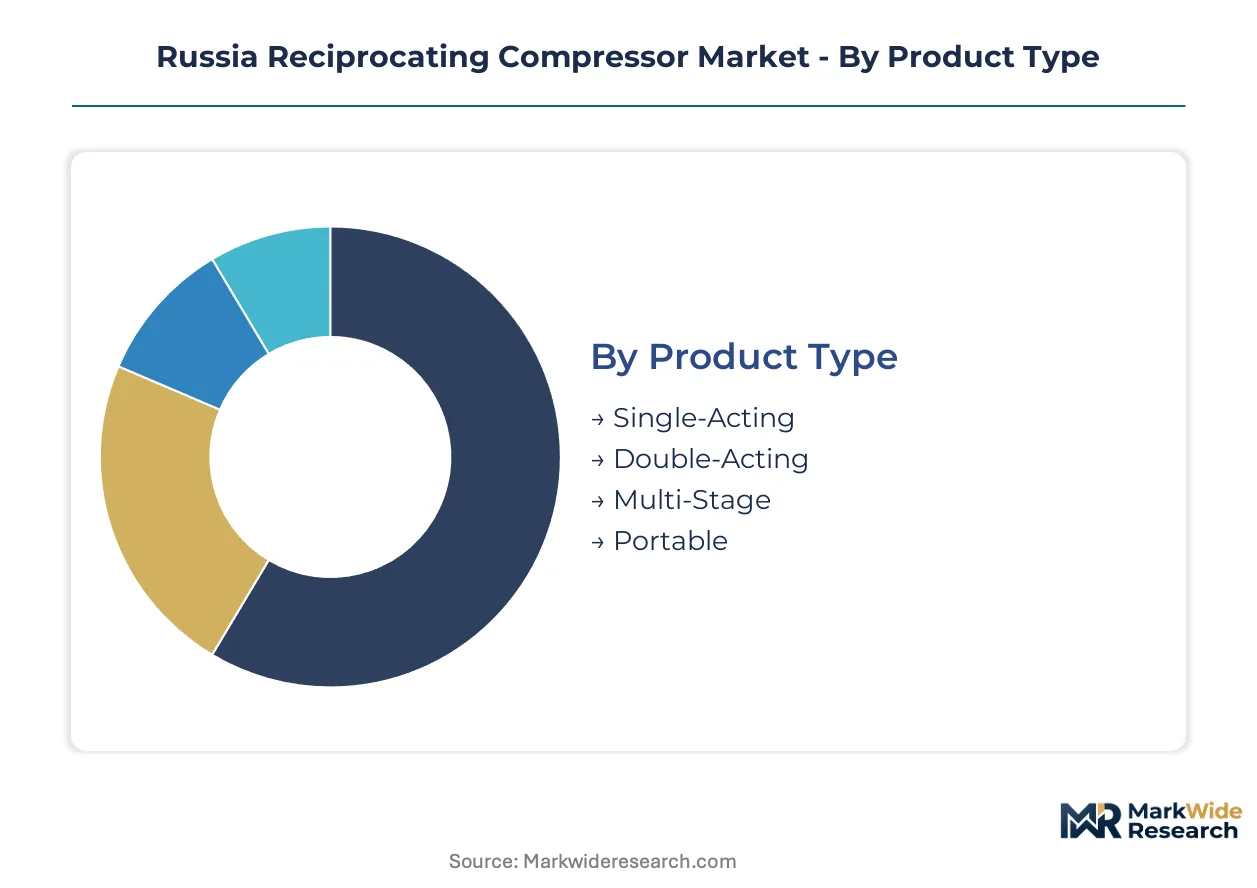
Compressor procurement patterns across Russia diverge sharply by operational intensity and infrastructure maturity. Each segmentation axis reveals distinct supply chain configurations and certification burdens that shape vendor selection criteria.
Product Type:
Domestic fabrication capacity concentrates in double-acting and multi-stage configurations, while single-acting and portable units remain import-dependent.
- Double-Acting:Simultaneous compression on both piston faces delivers higher throughput per unit footprint than single-acting alternatives. Western Siberia's enhanced oil recovery projects specify these for high-pressure injection duties at mature fields.
- Multi-Stage:Sequential compression across intercooled cylinders achieves discharge pressures exceeding 500 bar for trunkline gas transport. Yamal-Nenets operators are expanding fleets for Eastern pipeline export capacity.
- Single-Acting:Lower capital cost suits auxiliary process duties at Volga-Ural refineries where continuous duty cycles are not required.
- Portable:Skid-mounted configurations serve remote wellsite logistics in Tyumen Oblast where fixed infrastructure proves uneconomical.
Double-acting designs absorb the bulk of installed capacity; portable configurations are expanding most quickly.
Application:
Cost tiering separates mission-critical process applications from auxiliary systems, with gas compression commanding premium pricing.
- Gas Compression:Pipeline transport and underground storage injection require API 618-compliant frames with forged steel crankshafts. Gazprom's trunkline expansion toward China sustains order backlogs.
- Petrochemical Processing:Hydrogen circulation and synthesis gas duties specify hydrogen embrittlement-resistant materials. Hydrocracker revamps across Tatarstan and Bashkortostan drive replacement cycles.
- Refrigeration:Ammonia and hydrocarbon refrigerant systems serve cold storage and LNG pre-cooling at Arctic projects.
- HVAC:Industrial climate control at manufacturing plants represents a price-sensitive segment with shorter replacement intervals.
Gas compression dominates capital deployment; petrochemical processing is climbing the fastest.
End User:
Customer type determines procurement sophistication, with oil and gas operators imposing the most stringent qualification protocols.
- Oil & Gas:Upstream and midstream operators mandate TR TS 032/2013 certification plus Rostekhnadzor field inspection. Gazprom Neft and Rosneft account for the majority of high-pressure unit procurement.
- Chemical Industry:Specialty gas producers in Tatarstan require custom cylinder configurations for corrosive process streams.
- Manufacturing:General industrial compressed air systems face budget constraints and favor standardized packages.
- Food & Beverage:Oil-free compression for packaging lines represents a niche specification with limited domestic sourcing.
Oil and gas absorbs the bulk of installed capacity; chemical industry demand is gaining share fastest.
Technology:
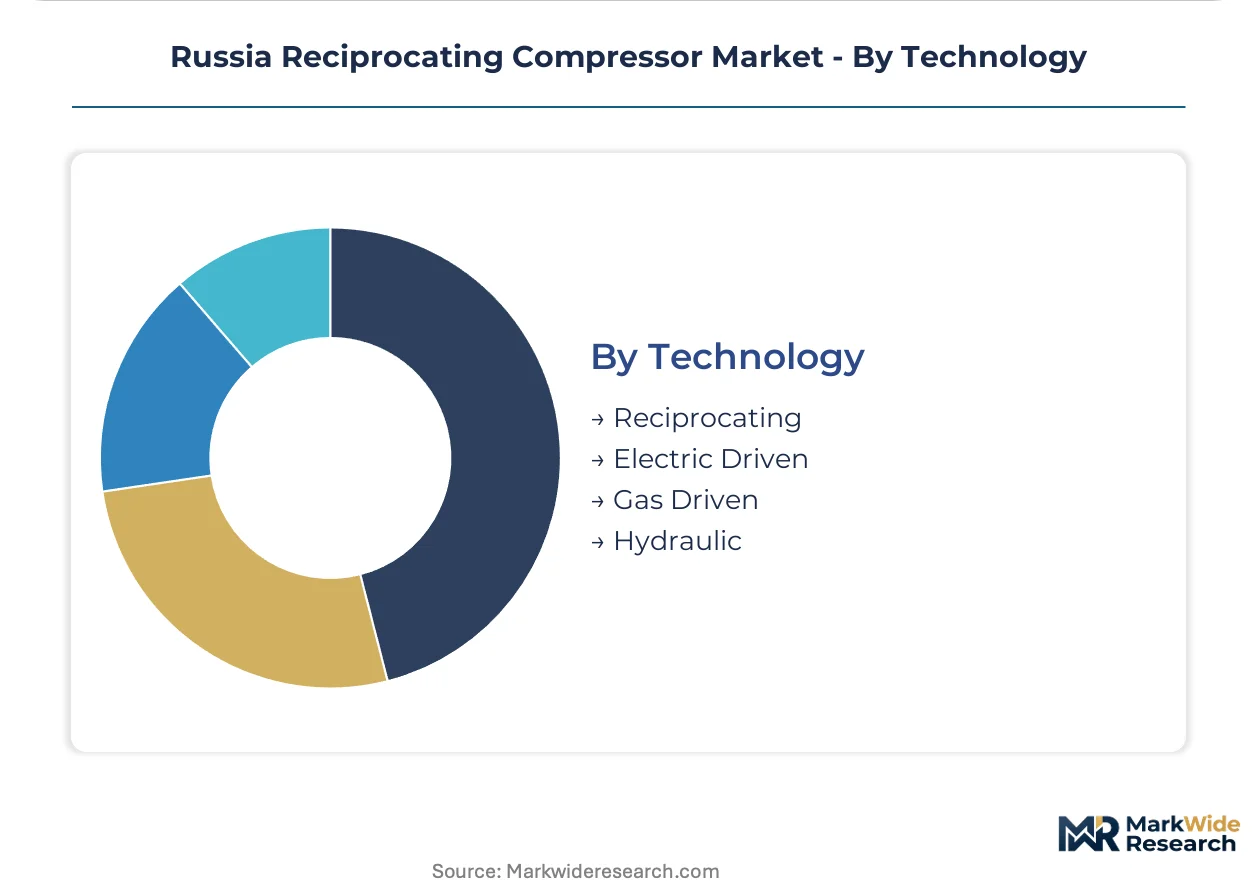
Maturity gradients separate established reciprocating architectures from emerging drive alternatives, with electric integration accelerating.
- Reciprocating:Piston-driven mechanisms remain the baseline for high-pressure applications above 100 bar, with century-proven reliability in Russian operating conditions.
- Electric Driven:Variable-speed medium-voltage motors are displacing constant-speed units with recycle valves. Gazprom Dobycha Urengoy is retrofitting existing frames to reduce fuel gas consumption.
- Gas Driven:Field gas or diesel engines serve remote locations without grid connection, common in greenfield exploration.
- Hydraulic:Oil-hydraulic drive systems offer precise stroke control for specialty chemical applications with variable demand profiles.
Reciprocating architectures absorb the bulk of installed capacity; electric driven configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Siberia's oil and gas basins anchor Russia's reciprocating compressor demand, with the Volga-Ural corridor and Arctic frontiers shaping procurement patterns across distinct operating environments.
Western Siberia
Gazprom Neft and Rosneft are expanding compressor fleets for enhanced oil recovery at mature fields in the Khanty-Mansi Autonomous Okrug. Rostekhnadzor enforces TR TS 032/2013 certification for all new high-pressure injection units. Tyumen Oblast fabricators are scaling modular skid packages to minimize field installation time at remote wellpads.
Volga-Ural Region
Refinery modernization programs across Tatarstan and Bashkortostan sustain replacement cycles for hydrogen circulation compressors. The Eurasian Economic Commission's harmonized conformity assessment reduces redundant testing for equipment serving cross-border petrochemical flows. Kazan-based specialty gas producers require custom cylinder configurations for corrosive process streams.
Yamal-Nenets Autonomous Okrug
Trunkline capacity expansion toward China accelerates demand for gas compression stations in Arctic conditions. Novatek's LNG projects specify modular packages rated for minus-fifty-degree ambient operation. Urengoy and Nadym production clusters anchor the Eastern pipeline export infrastructure.
Northwestern Federal District
Arctic LNG fabrication for Gydan and Ob Bay projects creates cold-climate engineering demand outside traditional hydrocarbon provinces. St. Petersburg machine builders are requalifying domestic cylinder-head foundries to offset Western precision-machining supply disruptions. The region's port infrastructure supports module export logistics.
Southern Federal District
Black Sea refinery and petrochemical investments drive auxiliary compression demand for import substitution programs. Krasnodar Krai industrial zones are absorbing relocated capacity from sanctioned Western supplier networks. Regional operators favor standardized packages to compress procurement timelines amid certification bottlenecks.
Russia Reciprocating Compressor Market Competitive Environment
Global majors compete with regional champions across certification navigation and aftermarket service reach, creating a tiered structure where technical documentation capabilities separate premium positioning from commodity supply. European and North American fabricators anchor the high-pressure process segment through established Rostekhnadzor relationships, while Russian and Asian suppliers capture volume opportunities in standardized configurations. Three archetypes dominate: full-service OEMs with localized assembly partnerships, aftermarket specialists leveraging service footprints for long-term contracts, and portable equipment vendors optimizing for remote logistics. Competitive moves concentrate on strategic partnerships to bypass customs complexity and capacity localization to satisfy domestic content requirements.
Among European-based fabricators, Howden Group Ltd. and Burckhardt Compression AG exemplify the full-service archetype through aftermarket anchoring and localized assembly positioning. Atlas Copco AB occupies a distinct tier focused on portable configurations. These three names from the raw data represent contrasting strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Howden Group Ltd. |
| Burckhardt Compression AG |
| Atlas Copco AB |
| Ariel Corporation |
| Neuman & Esser Group |
| Kobelco Compressors Corporation |
| General Electric (Oil & Gas) Co. |
| BORSIG ZM Compression GmbH |
| Dresser Rand Group Inc. |
| Others |
Value Chain & Pricing Dynamics
Crosshead alignment specialists concentrated in Tyumen Oblast command wage premiums that widen spreads between premium OEM service contracts and third-party overhaul pricing. Labor-cost differentials between aging Soviet-trained mechanical fitters and new vocational graduates translate directly into tiered aftermarket service rates across Western Siberia's compressor fleets.
Pricing Analysis
Warranty bundling separates full-service OEM contracts from unbundled parts-and-labor arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service intensity. Cost compression in economy-tier portable configurations intensifies as domestic fabricators scale standardized skid packages. Chemical industry buyers in Tatarstan exhibit highest price sensitivity due to custom cylinder requirements, while Gazprom-operated trunkline projects absorb premium pricing for TR TS 032/2013-certified frames.
Supply Chain Analysis
Dual-sourcing mandates from Rostekhnadzor-qualified operators require valve-seat grinding capacity from both German-Swiss supplier networks and requalified domestic foundries. Nickel-based superalloy supply draws from German, Austrian, and domestic metallurgical sources. Single-source vulnerability concentrates in five-axis CNC equipment for cylinder-head sealing surfaces. Distribution runs through Tyumen Oblast logistics hubs serving Western Siberian wellpads and Volga-Ural refinery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward control over precision-machining capacity determines who captures certified unit procurement. Players are pursuing captive supply of high-pressure cylinder heads to bypass Western sanctions-driven sourcing ruptures.
For Market Incumbents: To counter turbocompressor substitution threats in Volga-Ural pipeline base-load applications, anchor position through localized assembly partnerships that satisfy domestic content requirements. Deepen control over valve-seat grinding operations to compress certification timelines for TR TS 032/2013 compliance. For New Entrants and Emerging Players: Remote condition-monitoring platforms offer the lowest-friction entry vector. Capture aftermarket service unbundling opportunities in valve-overhaul and cylinder-relining segments previously held by OEMs. Target portable compressor configurations for Tyumen Oblast exploration logistics where fixed infrastructure proves uneconomical. For Investors and Strategic Acquirers: The window for entry favors precision-machining specialists with Rostekhnadzor qualification pathways. Long-term viability rests on domestic content scalability rather than import-dependent component sourcing. Watch Novatek Arctic LNG project timelines as inflection indicators for cold-climate package demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder-Head Foundries | Captive supply of critical sealing surfaces reduces Rostekhnadzor certification delays from Western sourcing ruptures. |
| Variable-Speed Drive Retrofit Programs | Gazprom Dobycha Urengoy deployments demonstrate fuel gas savings at partial-load operating points. |
| Arctic LNG Modular Package Certification | Novatek Gydan and Ob Bay projects specify minus-fifty-degree ambient operation ratings. |
| Aftermarket Service Unbundling | Independent providers capture valve-overhaul contracts through standardized parts-kit penetration. |
| TR TS 032/2013 Compliance Investment | Finite-element analysis submission requirements favor fabricators with in-house simulation capacity. |
Study Parameters
Document review covered customs and trade data, Rostekhnadzor certification registries, and Eurasian Economic Commission harmonization directives, complemented by interviews with plant engineers at Gazprom Neft and Rosneft facilities, aftermarket service heads in Tyumen Oblast, and procurement leads at Volga-Ural refineries. Secondary validation drew from SEC filings of listed compressor fabricators, EIA energy infrastructure databases, and project development tracking for Eastern pipeline capacity additions. Bottom-up unit deployment estimates triangulated against top-down capital expenditure flows across the analysis window.
Segmentation outputs disaggregate by product type, application intensity, end-user sophistication, and drive technology configuration throughout the forecast period. CAGRs derive from installed base replacement cycles, pipeline capacity expansion schedules, and refinery modernization program timelines. Industry-specific inputs include Rostekhnadzor approval backlogs, domestic foundry requalification progress, and Novatek LNG project fabrication milestones.
The model holds under sustained sanctions architecture and stable TR TS 032/2013 enforcement; deviation in metallurgical import substitution timelines or accelerated turbocompressor adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Europe Compressor Market
Compressors
North America Hydrogen Compressor Market
Compressors
North America Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Rental Air Compressors Market
Compressors
Compressor Rental Market
Compressors
Compressed Air Lubricators Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Scroll Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
CNG Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
PAG Compressor Oil Market