
 Middle East and Africa Booster Compressor Market | 2026-2036
Middle East and Africa Booster Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Booster Compressor Market Insights
The Middle East and Africa booster compressor market is repositioning around a widening split between premium engineered systems for offshore platforms and commoditized onshore skid packages. Atlas Copco Group leverages its aftermarket service density across Gulf Cooperation Council energy hubs to sustain recurring revenue streams. Ingersoll Rand PLC anchors its position through rotary screw specialization for chemical processing facilities in South Africa. Baker Hughes Company dominates the high-pressure centrifugal segment for subsea tieback projects off West Africa.
A booster compressor is a mechanical device that increases gas pressure from an intermediate level to a higher discharge pressure, typically operating with pressure ratios between 2:1 and 10:1 and driven by electric motors, gas engines, or steam turbines. These machines serve critical functions in gas reinjection, pipeline transmission, and process gas handling where primary compression falls short of target pressure requirements. The oil and gas application segment leads absolute demand across the region, though water treatment installations represent the fastest-growing category as desalination capacity expands along the Red Sea and Gulf coasts. Reciprocating units occupy the premium tier for high-pressure petrochemical service, while screw compressors capture volume in standard industrial utility roles.
Saudi Arabia's SFDA and the UAE's MOHAP enforce equipment safety standards that shape product certification requirements for compressors used in pharmaceutical and food-contact applications, while the EU F-Gas Regulation indirectly influences regional supply chains through equipment import requirements. The analysis shows that stakeholders must monitor how South Africa's Department of Mineral Resources and Energy updates its pressure equipment regulations to align with evolving SANS standards. Forward-looking buyers should evaluate which suppliers can demonstrate compliance trajectories across multiple national approval frameworks rather than single-jurisdiction certifications.
Market Dynamics
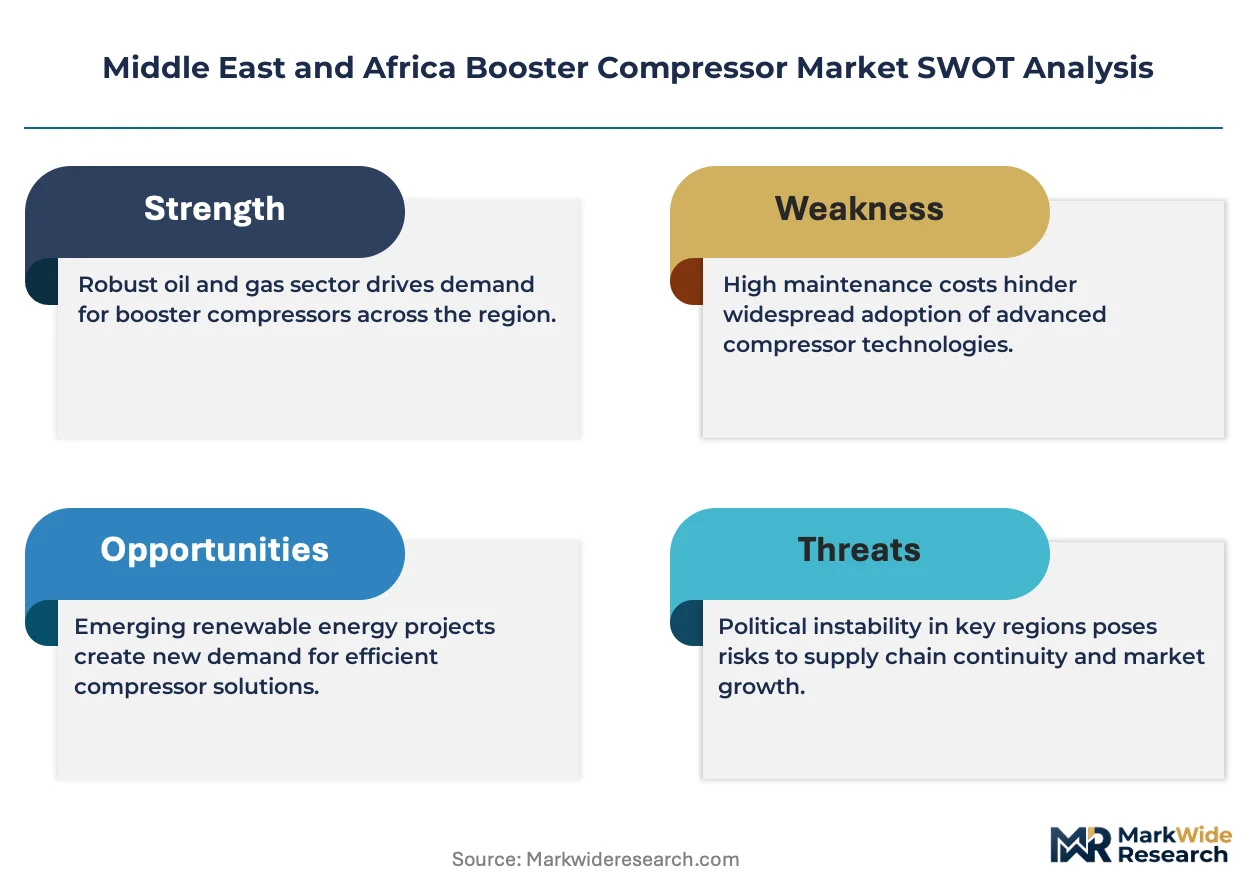
The Middle East and Africa booster compressor market is bifurcating around the pressure differential between offshore high-specification projects and onshore utility-grade installations, with the EU F-Gas Regulation forcing refrigerant chemistry redesigns across imported equipment lines.
Growth Catalysts
- Enhanced Oil Recovery Mandates:Nigeria's Department of Petroleum Resources and Angola's Ministry of Mineral Resources and Petroleum are accelerating gas reinjection compressor deployments to sustain mature field output.
- Desalination Infrastructure Buildout:Reverse osmosis plants along Saudi Arabia's Red Sea coast and the UAE's Gulf coastline are specifying booster compressors for brine pressure management and membrane feed systems.
- F-Gas Compliance Redesign:The European Union's F-Gas Regulation is compelling regional distributors to stock low-GWP refrigerant-compatible compressor models, opening retrofit demand across existing petrochemical installations.
Market Restraints
- Specialized Alloy Supply Concentration:High-pressure vessel-grade steel sourcing concentrates among a limited set of European and East Asian mills, exposing project timelines to raw material allocation delays.
- Skilled Technician Scarcity:Reciprocating compressor overhaul and high-speed balancing expertise remains concentrated in South Africa and the UAE, constraining maintenance response times in West African offshore zones.
- Import Duty Regime Volatility:Nigeria's customs harmonization with the Economic Community of West African States tariff schedule creates landed cost uncertainty for packaged compressor skids.
Strategic Opportunities
- East African Geothermal Expansion:Kenya's Geothermal Development Company and Ethiopia's Ethiopian Electric Power are specifying booster compressors for flash steam pressure augmentation in Rift Valley plants.
- Carbon Capture Retrofit Cycles:Amine-based CO2 capture installations at Saudi Aramco facilities and ADNOC sites in the UAE require intermediate compression stages for solvent regeneration pressure management.
- Digital Twin Integration:Remote monitoring platforms combining vibration analytics with predictive maintenance algorithms are penetrating the aftermarket service contracts of UAE-based petrochemical operators.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Compressor packages for pharmaceutical applications must simultaneously satisfy Saudi Arabia's SFDA, the UAE's MOHAP, and South Africa's SANS pressure equipment directives, extending approval timelines.
- Obsolete Control System Integration:Brownfield installations in Angola's offshore blocks and Egypt's mature Gulf of Suez fields require proprietary protocol bridges to connect modern variable-speed drives with legacy SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Booster Compressor Market |
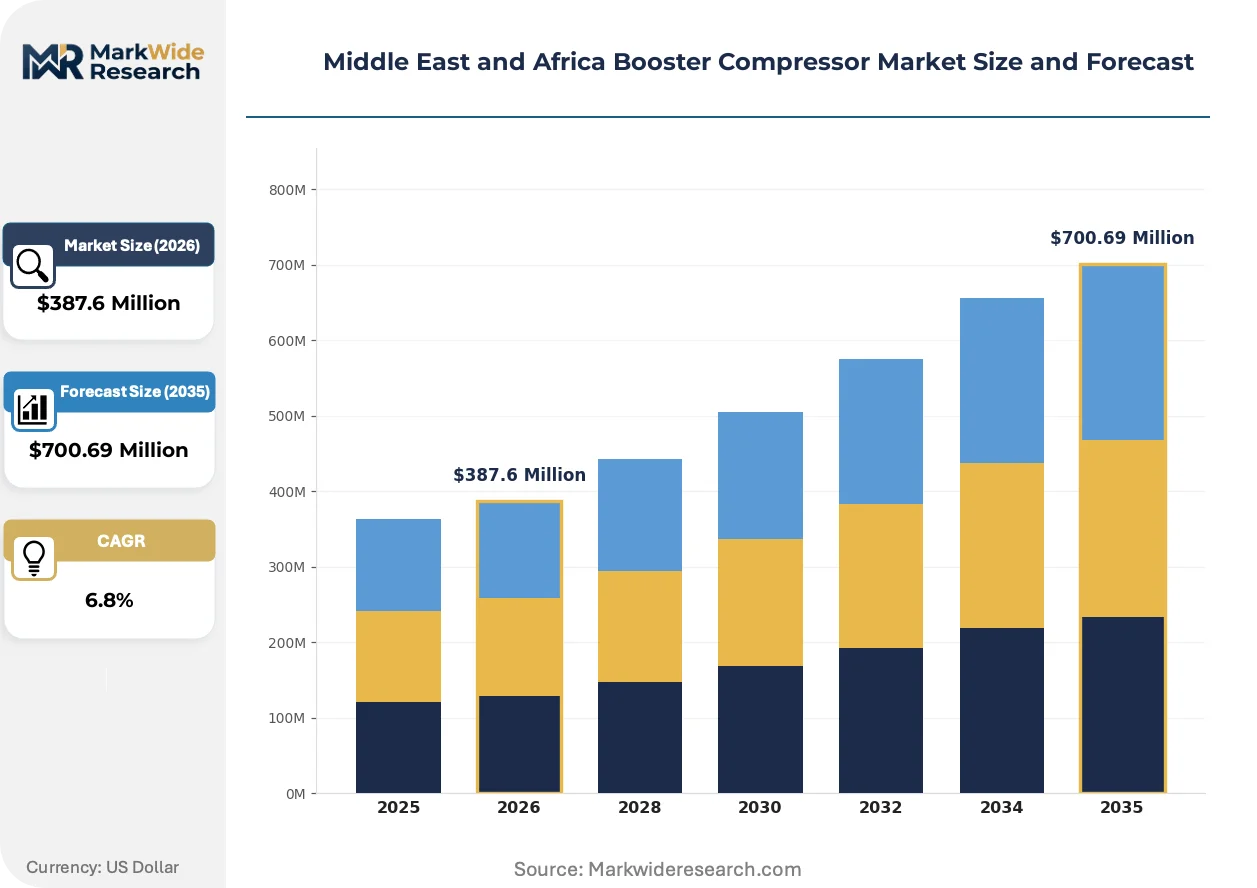
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary, Centrifugal, Screw Application: Oil & Gas, Power Generation, Chemical Processing, Water Treatment End User: Industrial, Commercial, Utilities, Petrochemical Installation: Onshore, Offshore, Mobile, Stationary |
| Companies Covered | Atlas Copco Group, Ingersoll Rand PLC, Baker Hughes Company, Bauer Compressors, Kaeser Kompressoren, Honeywell, MAN Diesel & Turbo, Sauer Compressors, Burckhardt Compression, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Booster Compressor Market Trends and Innovations
Equipment architecture and service delivery models are diverging sharply between high-availability offshore specifications and cost-optimized onshore packages, with regulatory chemistry mandates and digital monitoring capabilities reshaping procurement criteria.
Seal-less magnetic bearing centrifugal compressor technology is modularizing field maintenance procedures by eliminating oil lubrication systems and reducing bearing changeout intervals from annual to five-year cycles. ADNOC and Saudi Aramco are specifying these units for unmanned offshore platforms where helicopter logistics constrain personnel access. The technology is modularizing supplier service revenue models toward remote condition monitoring rather than scheduled physical interventions.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants is forcing compressor manufacturers to validate alternative working fluids including CO2 and ammonia for high-pressure process applications. This chemistry transition requires complete redesign of seal materials and pressure relief systems. Petrochemical buyers in Saudi Arabia's Eastern Province are now demanding factory-witnessed alternative refrigerant compatibility testing before contract award.
After-sales service unbundling is fragmenting traditional OEM maintenance lock-in across South African chemical processing facilities. Independent service providers with laser alignment and rotor balancing capabilities are capturing mid-life overhaul contracts previously held by factory-authorized technicians. This pattern is most visible around Sasol's Secunda complex and the Durban industrial corridor, where procurement teams are separating spare parts supply from technical labor scope.
Middle East and Africa Booster Compressor Market Segmentation
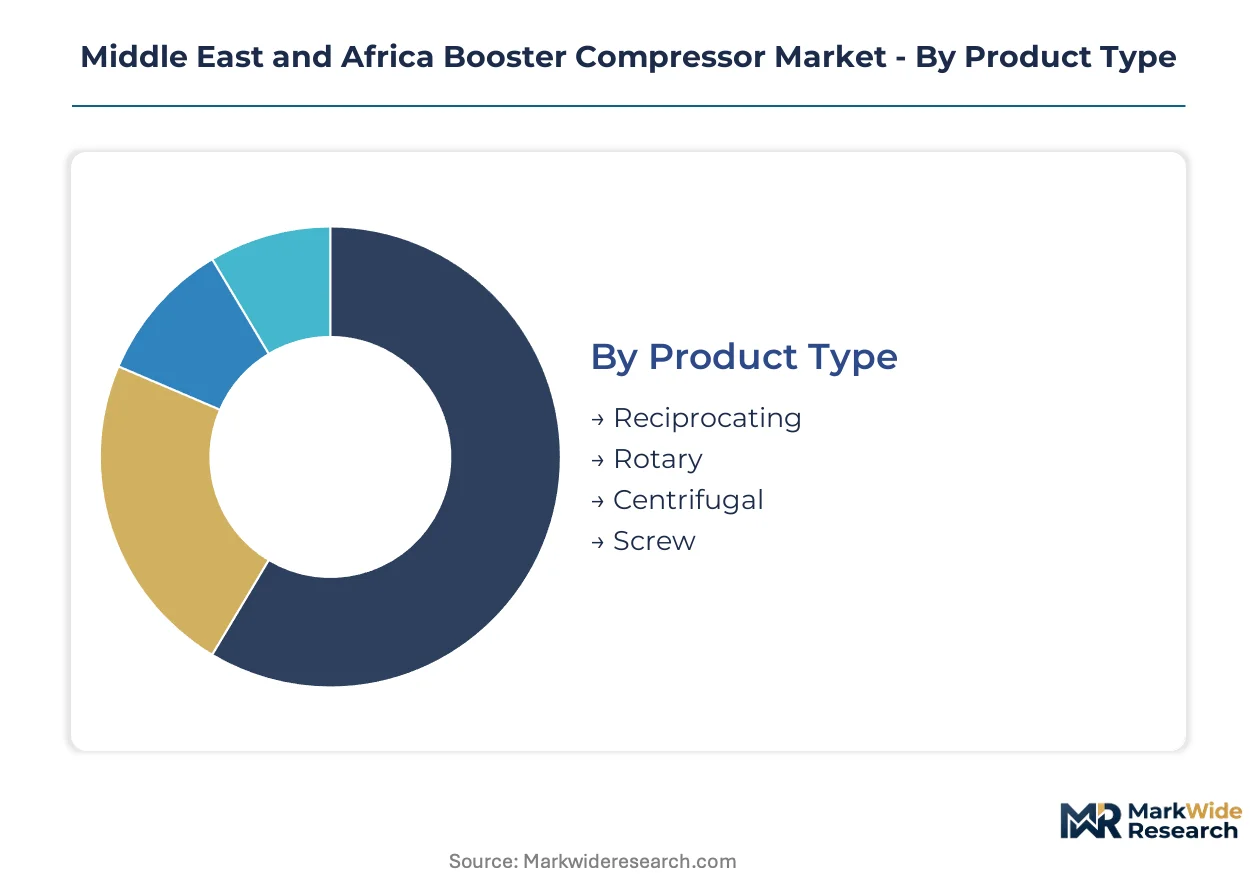
Booster compressor procurement patterns diverge sharply across pressure specifications, duty cycles, and regulatory exposure zones. Understanding these segment boundaries clarifies where technology premiums command pricing power versus where standardization drives cost competition.
Product Type:
Pressure ratio requirements and maintenance accessibility define the technology selection axis across Middle East and African installations.
- Reciprocating:Piston-driven units achieve pressure ratios exceeding 10:1 through staged compression cylinders. Demand concentrates in Saudi Arabia's Eastern Province petrochemical corridor, where high-pressure hydrogen service and gas reinjection applications require metallurgical-grade alloy construction resistant to sour gas corrosion.
- Centrifugal:Dynamic compression through impeller stages delivers continuous flow at moderate pressure ratios. Offshore platform specifications in Angola's Block 15 and Nigeria's Bonga field favor these units for gas lift and export compression, driven by unmanned platform mandates that prioritize seal-less magnetic bearing configurations.
- Rotary:Vane and lobe designs handle contaminated gas streams with minimal pulsation. Compressed natural gas vehicle filling stations in Egypt's Nile Delta specify these for their tolerance to particulate-laden feed gas.
- Screw:Twin-rotor positive displacement mechanisms dominate standard industrial utility roles. South Africa's Sasol Secunda complex deploys oil-flooded variants for process air and nitrogen boosting.
Mature deployment sits with Reciprocating units in legacy petrochemical infrastructure. Newer deployment is concentrated in Centrifugal configurations for remote offshore automation.
Application:
End-use intensity varies with hydrocarbon extraction maturity and water scarcity pressures across regional economies.
- Oil & Gas:Gas reinjection, pipeline transmission, and artificial lift operations consume the largest absolute compressor capacity. Nigeria's Department of Petroleum Resources mandates gas utilization frameworks that accelerate booster deployments at mature onshore fields in the Niger Delta.
- Water Treatment:Reverse osmosis membrane feed systems and brine pressure management represent the steepest expansion trajectory. Saudi Arabia's Red Sea desalination expansion and UAE's Al Taweelah facility specify energy-recovery booster stages to reduce specific energy consumption.
- Chemical Processing:Process gas handling and synthesis loop applications require corrosion-resistant materials. South Africa's KwaZulu-Natal chemical corridor specifies titanium-clad reciprocating units for chlorine and hydrogen chloride service.
- Power Generation:Gas turbine fuel gas pressure boosting and combined cycle applications anchor demand. Egypt's Burullus and New Capital power plants deploy centrifugal trains for natural gas pressure elevation.
Procurement volume clusters in Oil & Gas maintenance cycles. Technology refresh is accelerating fastest in Water Treatment as membrane efficiency targets tighten.
End User:
Capital deployment horizons and technical staffing depth shape equipment specification tiers across customer categories.
- Petrochemical:Integrated refining and chemical complexes demand highest reliability specifications. ADNOC's Ruwais Derivatives Complex specifies API 618-compliant reciprocating frames with five-year uninterrupted run requirements.
- Utilities:Water and power infrastructure operators prioritize lifecycle cost optimization over capital expenditure minimization. Kenya's Geothermal Development Company selects modular screw packages for flash steam pressure augmentation in Olkaria field expansion.
- Industrial:Manufacturing facilities balance first cost against maintenance accessibility. Morocco's OCP phosphates processing plants specify skid-mounted rotary units for sulfuric acid plant air supply.
- Commercial:Smaller-scale applications include CNG stations and food processing refrigeration. Dubai's ENOC retail network deploys compact reciprocating boosters for vehicle refueling pressure stages.
Specification complexity peaks with Petrochemical operators. Standardization pressure is most acute in Commercial installations where distributor inventory turns drive model consolidation.
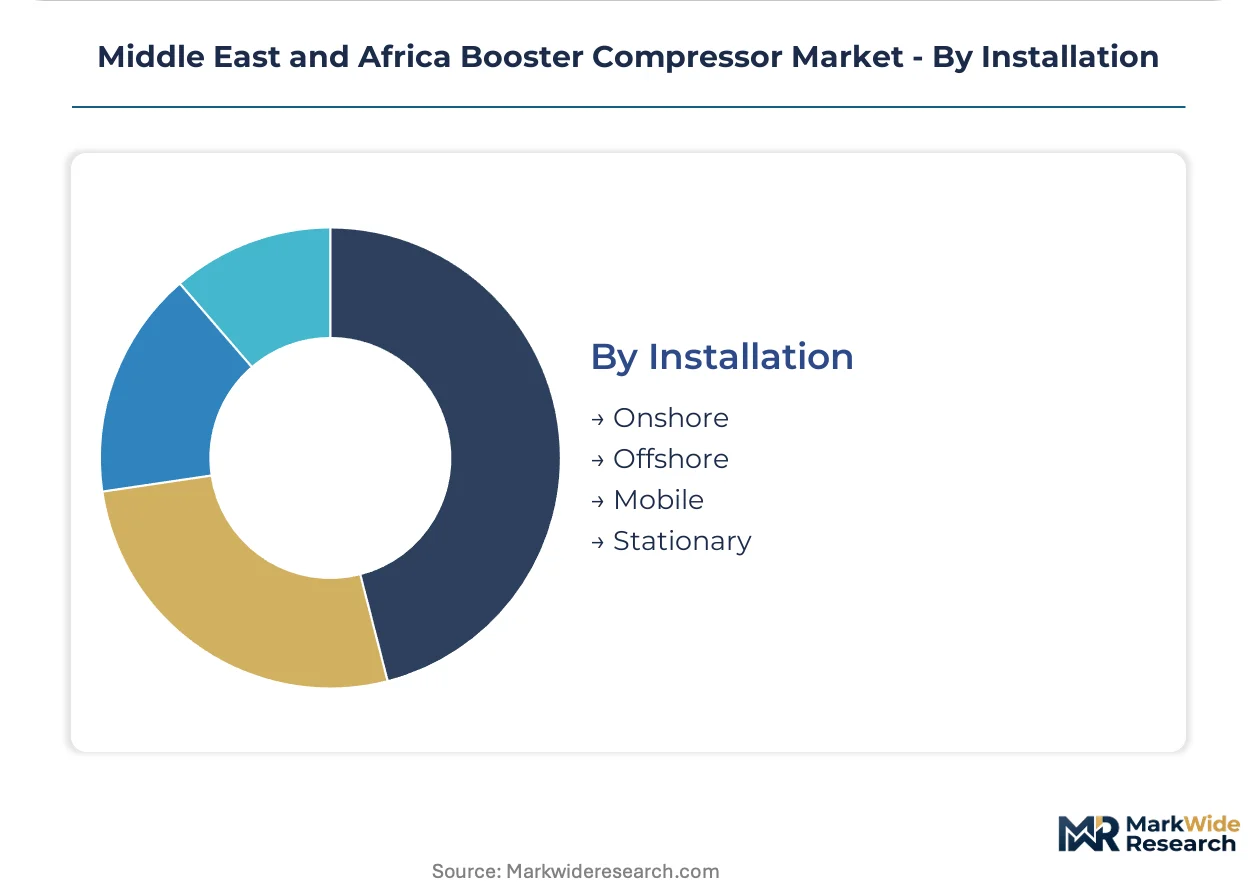
Installation:
Physical siting determines corrosion protection grades, maintenance logistics, and automation depth.
- Offshore:Platform and subsea tieback applications demand explosion-proof enclosures and helicopter-transportable modules. Baker Hughes dominates high-pressure centrifugal supply for TotalEnergies' Angola deepwater projects.
- Onshore:Desert environments in Saudi Arabia's Empty Quarter and Algeria's Hassi Messaoud require sand filtration and cooling system hardening against ambient temperatures exceeding 50°C.
- Stationary:Permanent plant installations support continuous process duty. UAE's Borouge 4 expansion specifies fixed-base reciprocating trains for polyethylene reactor feed pressure.
- Mobile:Trailer-mounted packages serve drilling rig air supply and temporary pipeline commissioning. Libya's Waha Oil operations deploy rental screw compressors for well workover gas lifting.
Engineering intensity concentrates in Offshore specifications. Volume manufacturing economies align with Stationary onshore packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Eastern Province industrial corridor concentrates the region's densest booster compressor procurement, with Jubail and Yanbu petrochemical complexes driving specification standards for high-pressure hydrogen and gas reinjection service.
Saudi Arabia
Gas reinjection mandates from the Ministry of Energy and ADNOC's Ruwais Derivatives Complex sustain demand for API 618-compliant reciprocating frames. SFDA equipment safety standards shape certification requirements for pharmaceutical and food-contact compressor applications. Jubail's integrated refining and chemical facilities specify five-year uninterrupted run requirements for critical compression trains.
United Arab Emirates
Reverse osmosis membrane feed systems at Al Taweelah and Borouge 4 expansion projects specify energy-recovery booster stages. MOHAP enforces equipment safety standards parallel to Saudi Arabia's SFDA framework. Abu Dhabi's industrial zones concentrate procurement for unmanned offshore platforms requiring seal-less magnetic bearing configurations.
Nigeria
The Department of Petroleum Resources mandates gas utilization frameworks accelerating booster deployments at mature Niger Delta fields. Customs harmonization with ECOWAS tariff schedules creates landed cost uncertainty for packaged compressor skids. Onshore enhanced oil recovery projects in the Niger Delta specify skid-mounted rotary units for gas lift operations.
South Africa
Sasol's Secunda complex and Durban industrial corridor drive demand for oil-flooded screw compressors in process air and nitrogen boosting. The Department of Mineral Resources and Energy updates pressure equipment regulations to align with evolving SANS standards. Independent service providers with laser alignment capabilities capture mid-life overhaul contracts from factory-authorized technicians.
Angola
Deepwater subsea tieback projects off Block 15 specify high-pressure centrifugal trains for gas export compression. The Ministry of Mineral Resources and Petroleum accelerates gas reinjection compressor deployments to sustain mature field output. Offshore platform specifications favor unmanned automation mandates prioritizing seal-less magnetic bearing technology.
Middle East and Africa Booster Compressor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across engineering intensity and aftermarket service density. The market structure consolidates around three tiers: full-service OEMs with Gulf Cooperation Council service hubs, specialized centrifugal fabricators for offshore specifications, and regional packagers of standardized skid systems. Strategic archetypes include technology licensors with magnetic bearing IP, alloy-forging-integrated manufacturers controlling high-pressure vessel supply, and independent service providers unbundling aftermarket contracts. Dominant competitive moves span backward integration into specialized alloy sourcing and predictive maintenance platform licensing to anchor recurring revenue streams.
Within the full-service OEM tier, Atlas Copco Group exemplifies aftermarket service density strategies across Gulf Cooperation Council energy hubs, while Ingersoll Rand PLC occupies a position anchored through rotary screw specialization. Baker Hughes Company represents the high-pressure centrifugal archetype for subsea tieback specifications. These three entities collectively illustrate how geographic origin and company structure correlate with strategic positioning: Swedish-incorporated Atlas Copco, Irish-domiciled Ingersoll Rand, and US-headquartered Baker Hughes each exemplify distinct approaches to regional market penetration without overlapping segment focus.
| Leading Market Players |
|---|
| Atlas Copco Group |
| Ingersoll Rand PLC |
| Baker Hughes Company |
| Bauer Compressors |
| Kaeser Kompressoren |
| Honeywell |
| MAN Diesel & Turbo |
| Sauer Compressors |
| Burckhardt Compression |
| Others |
Pricing and Supply Chain Analysis
Seal-less magnetic bearing centrifugal technology is displacing oil-lubricated legacy systems across Saudi Aramco and ADNOC offshore specifications, simultaneously elevating engineering premiums and concentrating procurement among European and US OEMs with captive bearing IP. This transition compresses margins for standardized skid packages while amplifying pricing power for high-availability configurations where five-year mean time between overhauls commands value-based premiums.
Pricing Analysis
Mean-time-between-overhaul guarantees anchor value-based pricing for offshore platform specifications, with seal-less magnetic bearing units commanding premiums tied to unmanned platform uptime commitments. Price differentiation separates API 618-certified reciprocating frames for hydrogen service from commodity screw compressors for utility air duty. Cost compression in onshore skid packages is intensifying because South African and UAE-based packagers are unbundling aftermarket service scopes. Commercial CNG station operators exhibit highest price sensitivity, while ADNOC and Saudi Aramco petrochemical complexes prioritize lifecycle reliability over capital expenditure minimization.
Supply Chain Analysis
Saudi Arabia's In-Kingdom Total Value Add program and Nigeria's local content mandates under the Department of Petroleum Resources are reshaping sourcing patterns for pressure vessel forgings and control system integration. High-grade alloy steel draws from German, Japanese, and Austrian specialty mills, while magnetic bearing assemblies rest on US and Swiss component suppliers. Single-source vulnerability concentrates in European-sourced impeller forgings for high-pressure centrifugal trains. Distribution runs through Dubai's Jebel Ali industrial zone for Gulf Cooperation Council markets and Johannesburg for sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The booster compressor market is transitioning from lubricated bearing systems to seal-less magnetic configurations, with EU F-Gas Regulation refrigerant chemistry mandates simultaneously forcing working fluid redesigns across legacy installed bases.
For Market Incumbents: Extend aftermarket service density through predictive maintenance platform licensing to anchor recurring revenue against independent service provider encroachment in South Africa's Durban corridor. Deepen backward integration into specialized alloy sourcing to secure pressure vessel forging allocation from European mills. Magnetic bearing IP licensing represents the priority defensive lever against emerging centrifugal specialists. For New Entrants and Emerging Players: Capture white-space in East African geothermal booster specifications where Kenya's Geothermal Development Company and Ethiopia's Ethiopian Electric Power are expanding flash steam pressure augmentation capacity. Modular screw packages for membrane feed systems in Red Sea desalination plants offer the most penetrable entry point. Partner with UAE-based EPC contractors for integrated skid supply to bypass established OEM maintenance lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with independent service providers possessing laser alignment and rotor balancing capabilities given aftermarket contract unbundling trends across Sasol's Secunda complex. Long-term viability favors specialists with multi-jurisdiction certification trajectories spanning Saudi Arabia's SFDA, UAE's MOHAP, and South Africa's SANS frameworks. Watch ADNOC and Saudi Aramco procurement specifications for seal-less magnetic bearing mandates as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Licensing | ADNOC unmanned platform specifications are accelerating seal-less configuration adoption across Gulf offshore projects. |
| Backward Integration into Alloy Forging | Captive supply of high-pressure vessel-grade steel mitigates European mill allocation delays for Nigerian EOR deployments. |
| Predictive Maintenance Platform Deployment | Vibration analytics contracts with UAE petrochemical operators are displacing scheduled physical intervention revenue models. |
| Alternative Refrigerant Compatibility Certification | EU F-Gas Regulation compliance is becoming a gatekeeper for Saudi Eastern Province petrochemical contract awards. |
| Independent Service Capability Buildout | Laser alignment specialists in South Africa are capturing mid-life overhaul contracts from factory-authorized technicians. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with maintenance directors at Saudi Aramco and ADNOC facilities, aftermarket service heads at Gulf Cooperation Council energy hubs, and procurement leads at South Africa's Sasol Secunda complex. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level volume estimates. Secondary sources included SEC filings from listed compressor OEMs, EU F-Gas Regulation implementation reports, and customs records from Saudi Arabia's General Authority for Statistics.
Data-stream reconciliation across product type, application, end user, and installation configuration dimensions produced consistent volume and value outputs across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns against announced capital expenditure cycles in desalination and enhanced oil recovery. Industry-specific forecast inputs incorporated Ministry of Energy gas reinjection mandates and Geothermal Development Company expansion timelines.
The model holds under stable alloy supply allocation and continued F-Gas Regulation phasedown schedules; deviation in European mill capacity utilization or refrigerant chemistry transition delays would shift equipment availability timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Rotary Air Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Turbocompressor Market
Compressors
Air Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Rotary Lobe Compressor Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Compressor Rental Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
CNG Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
Oil Filled Air Compressor Market
Compressors
Booster Compressor Market