
 Process Gas Compressors Market | 2026-2036
Process Gas Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Process Gas Compressors Market Analytics
Multi-source procurement for critical rotating equipment is restructuring supply relationships across the process gas compressor value chain. Siemens Energy AG leverages its turbomachinery heritage to anchor large-scale centrifugal contracts in energy transition projects. Atlas Copco Group competes through aftermarket service density and global parts distribution networks. MAN Energy Solutions specializes in reciprocating units for high-pressure hydrogen and carbon capture applications.
Process gas compressors are mechanical devices that raise the pressure of gases used in industrial processes, typically achieving discharge pressures from a few bar to over 1,000 bar through dynamic or positive displacement principles. These machines serve essential functions in gas transportation, chemical synthesis, refrigeration cycles, and carbon capture systems where process integrity depends on precise pressure ratios and contamination-free compression. Reciprocating compressors dominate hydrogen and high-pressure specialty gas applications where leakage tolerance approaches zero. Centrifugal compressors lead in base-load petrochemical and LNG service where continuous flow and energy efficiency govern total cost of ownership. Screw compressors occupy intermediate pressure ranges in refrigeration and fuel gas boosting where compact footprint and oil-free operation command premium positioning.
EPA emissions standards and the EU F-Gas Regulation are tightening allowable leakage rates from compressor seals and driving retrofit demand across existing process installations. ISO 10494 and API 617 establish mechanical integrity benchmarks that determine market access for OEMs supplying refinery and chemical plant operators. OSHA process safety management requirements in the United States mandate documented maintenance protocols that expand aftermarket service contracts. Stakeholders must weigh hydrogen compatibility against legacy hydrocarbon service when allocating R&D budgets and capacity investments across compressor architectures.
Market Dynamics
Process gas compressor markets are restructuring around hydrogen infrastructure buildout, with chemical producers and energy utilities pulling capacity toward high-pressure reciprocating architectures and away from legacy hydrocarbon-optimized centrifugal platforms.
Growth Catalysts
- EU Green Deal mandates:Tighter emissions rules under EU F-Gas Regulation are forcing compressor seal upgrades across German and Dutch chemical corridors, accelerating replacement cycles for aging refinery equipment.
- Hydrogen hub investments:Germany, the United States, and China are anchoring new hydrogen production clusters that require specialized high-pressure compression for ammonia synthesis and pipeline injection.
- API 617 certification alignment:Mechanical integrity benchmarks are expanding addressable market access for OEMs supplying carbon capture installations and blue hydrogen facilities.
Market Restraints
- Specialized alloy supply concentration:Superalloy forgings for high-pressure hydrogen service concentrate among a limited supplier base in Germany and Japan, creating input bottlenecks for reciprocating compressor manufacturers.
- EPA compliance friction:OSHA process safety management documentation requirements extend procurement timelines for US refinery operators, compressing project windows and delaying equipment awards.
- Centrifugal platform substitution limits:Dynamic compression technologies face technical barriers below 50 bar discharge pressure in hydrogen service, ceding ground to positive displacement architectures.
Strategic Opportunities
- Carbon capture retrofits:Post-combustion capture installations at existing coal and gas plants in China and India are creating demand for CO2 compression trains optimized for pipeline-grade purity.
- Modular hydrogen fueling stations:Distributed mobility infrastructure in California and South Korea requires compact, skid-mounted compression packages with rapid deployment cycles.
- EU taxonomy alignment:Sustainable finance classification for green hydrogen projects is channeling institutional capital toward certified low-leakage compressor technologies.
Industry Challenges
- Hydrogen embrittlement metallurgy expertise:Shortage of materials engineers capable of specifying compatible seals and pressure vessels for 700-bar hydrogen service is constraining OEM development timelines.
- ISO 10494 certification backlog:Testing queue congestion at accredited laboratories is extending time-to-market for new centrifugal compressor designs targeting LNG and petrochemical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Gas Compressors Market |
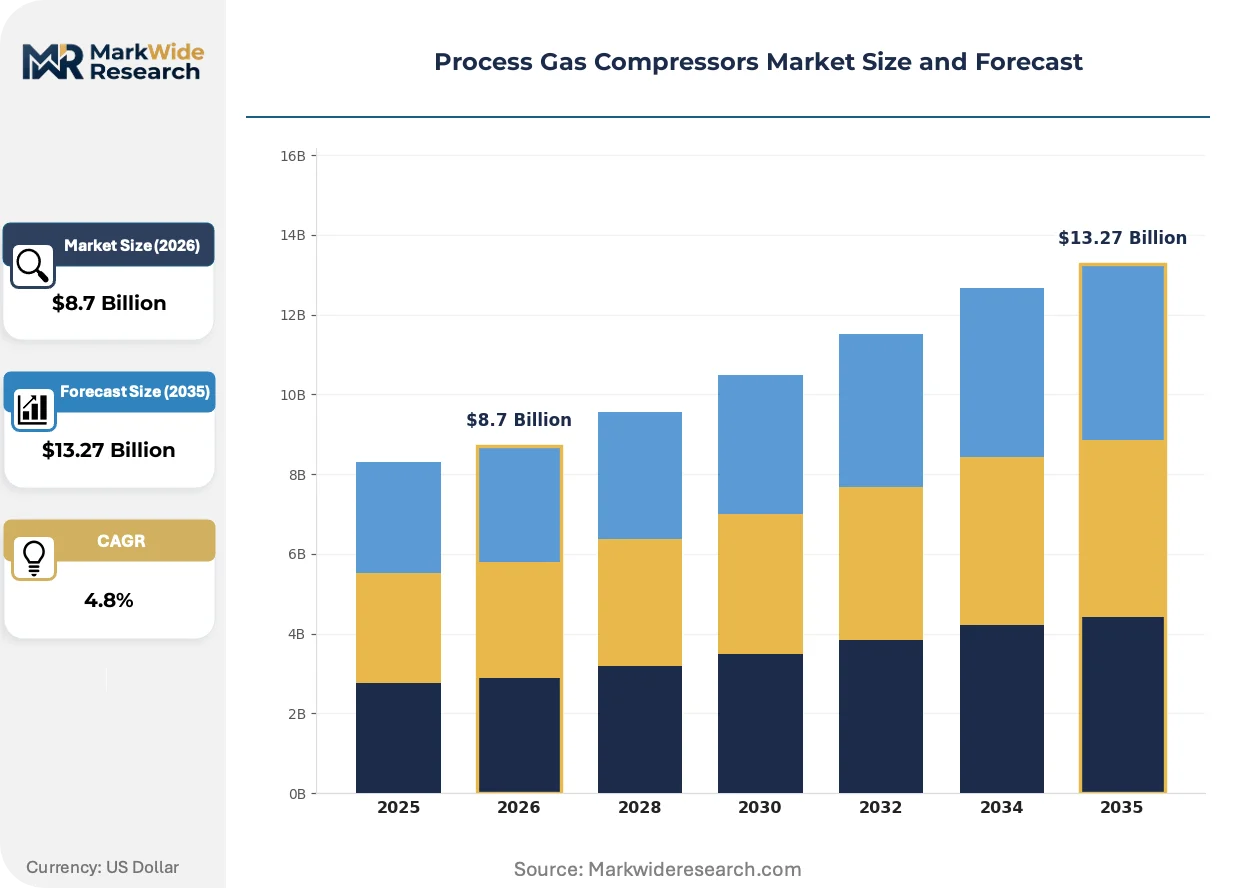
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Compressors, Reciprocating Compressors, Screw Compressors, Diaphragm Compressors End User: Chemical Industry, Oil & Gas, Power Generation, Food Processing Installation Type: Onshore, Offshore, Mobile, Fixed Technology: Electromechanical, Pneumatic, Thermal, Hydraulic |
| Companies Covered | Atlas Copco Group, Ingersoll Rand Inc., Siemens Energy AG, General Electric, Burckhardt Compression AG, Howden Group, MAN Energy Solutions, Ariel Corporation, Sundyne LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Gas Compressors Market Evolving Landscape
Equipment architectures are converging around digital monitoring integration and materials science advances that enable higher pressure ratios with reduced maintenance intervals.
Dry gas seal technology is consolidating as the dominant sealing solution for centrifugal compressors in hydrocarbon and hydrogen service. LNG exporters and refinery operators are specifying non-contacting seal designs to eliminate oil contamination risk and extend mean time between overhauls. This transition is consolidating supplier relationships around specialized seal OEMs with hydrogen compatibility testing capabilities.
EPA emissions standards and the EU F-Gas Regulation are tightening allowable leakage rates from compressor seals and driving retrofit demand. Refinery operators in Texas and Louisiana are budgeting for seal upgrade packages to avoid penalty structures under state-level methane rules. High-pressure hydrogen applications face the most stringent leakage tolerance requirements, pushing end-users toward API 618 reciprocating designs with distance piece venting.
Aftermarket service unbundling is fragmenting traditional OEM maintenance contracts. Chemical plant operators in the US Gulf Coast are separating parts procurement from technical service, sourcing consumables through independent distributors while retaining OEM specialists for critical overhauls. This pattern is most pronounced in mature petrochemical clusters where in-house maintenance capabilities have deepened over decades of operation.
Process Gas Compressors Market Segmentation
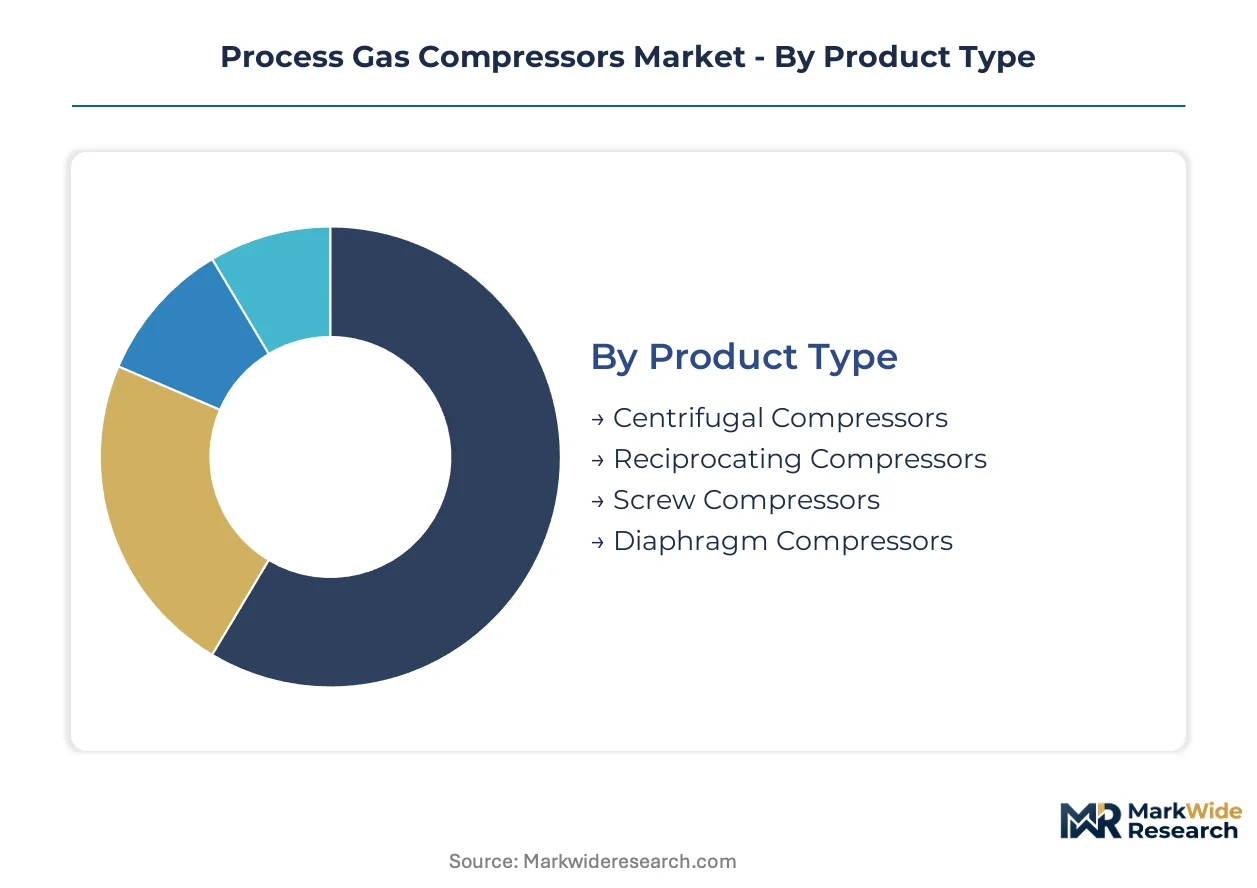
Segmentation in process gas compressors reveals divergent capital deployment patterns across product architectures and installation environments. Equipment selection directly determines project economics, with high-pressure hydrogen service commanding premium metallurgy investments while base-load petrochemical applications prioritize energy efficiency over upfront cost.
Product Type:
Capital intensity varies sharply across compressor architectures, with high-pressure positive displacement units requiring specialized alloy forgings that multiply unit costs relative to dynamic compression platforms.
- Centrifugal Compressors:Dynamic compression platforms achieve continuous flow through rotating impellers, optimizing energy efficiency in base-load LNG and petrochemical service. Demand concentrates in Texas and Louisiana refinery corridors where API 617 certification governs procurement specifications and total cost of ownership calculations dominate vendor selection.
- Reciprocating Compressors:Positive displacement architectures with piston-cylinder arrangements deliver discharge pressures exceeding 700 bar for hydrogen and carbon capture applications. German chemical producers and US Gulf Coast ammonia synthesis projects anchor demand, with superalloy material specifications creating supply bottlenecks from specialized forging suppliers.
- Screw Compressors:Rotary positive displacement designs with intermeshing helical rotors occupy intermediate pressure ranges in refrigeration and fuel gas boosting.
- Diaphragm Compressors:Zero-leakage compression through flexible metal diaphragms serves ultra-high-purity specialty gas and nuclear applications where contamination tolerance approaches absolute zero.
Centrifugal compressors absorb the bulk of installed capacity in hydrocarbon processing; reciprocating compressors are expanding most quickly on hydrogen infrastructure pull.
End User:
Application requirements dictate compression specifications, with chemical synthesis demanding precise pressure ratios and power generation prioritizing operational flexibility over peak efficiency.
- Chemical Industry:Ammonia, methanol, and ethylene production require contamination-free compression with tight pressure control across synthesis loops. German and Chinese chemical corridors anchor demand, with EU F-Gas Regulation leakage limits forcing seal upgrade investments across existing installations.
- Oil & Gas:Upstream production, midstream transportation, and downstream refining span pressure ranges from wellhead gas lift to refinery hydrocracking. US Permian Basin operators and Middle East NOCs concentrate procurement, with EPA methane rules accelerating replacement cycles for aging reciprocating units.
- Power Generation:Fuel gas boosting for gas turbines and fuel cell systems requires rapid response compression with wide turndown ratios.
- Food Processing:CO2 recovery and refrigeration systems demand oil-free compression with food-grade certification compliance.
Oil and gas applications retain the largest installed base; chemical industry demand is climbing the fastest on green hydrogen and carbon capture project commitments.
Installation Type:
Deployment environment shapes equipment packaging, with offshore platforms demanding compact modularization and onshore installations accommodating larger maintenance footprints.
- Onshore:Fixed installations at refineries, chemical plants, and pipeline compressor stations accommodate larger frame sizes and extended maintenance access corridors. US Gulf Coast and Rotterdam-Antwerp chemical clusters concentrate procurement, with modular construction trends standardizing skid packages for faster field assembly.
- Offshore:Platform and subsea installations require weight-optimized designs with corrosion-resistant coatings and minimal manned maintenance access. North Sea operators and Brazilian pre-salt developments anchor demand, with space constraints favoring centrifugal architectures over reciprocating alternatives.
- Mobile:Trailer-mounted and containerized compression serves temporary production, pipeline maintenance, and emergency response applications.
- Fixed:Permanent installations with dedicated foundations and utility connections dominate industrial process applications.
Onshore fixed installations command the majority of capital deployment; mobile configurations are gaining share fastest on distributed hydrogen fueling infrastructure.
Technology:
Drive mechanism selection determines efficiency profiles and grid integration requirements, with electromechanical systems consolidating share on energy transition alignment.
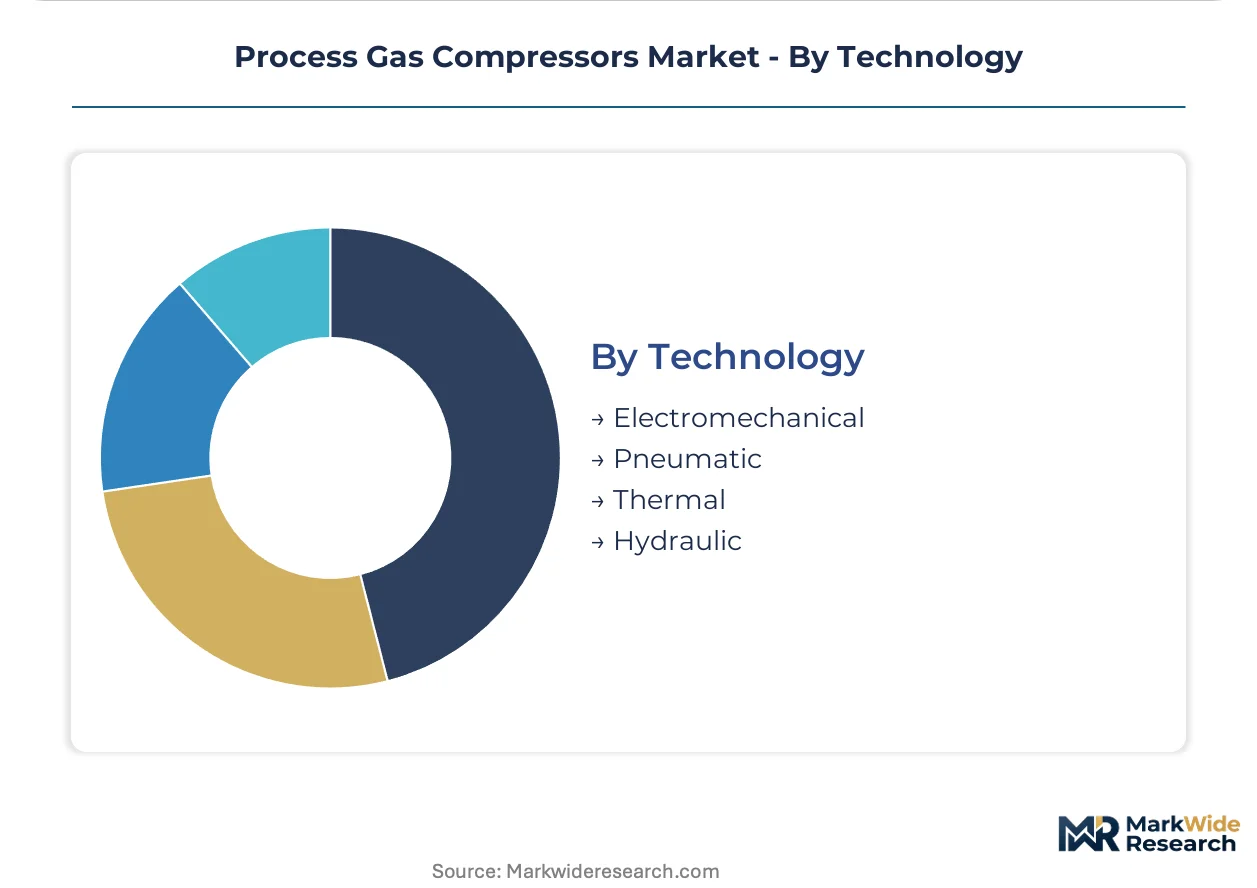
- Electromechanical:Electric motor drives with variable frequency control deliver precise speed modulation and grid-synchronized operation. German and Chinese hydrogen hub projects prioritize electromechanical compression for renewable energy integration, with efficiency advantages over gas turbine drivers in carbon-constrained environments.
- Pneumatic:Compressed air or process gas-driven systems serve hazardous area applications where electrical ignition risks preclude motor drives.
- Thermal:Gas turbine and engine drives retain relevance in remote locations without grid access and for waste heat recovery integration.
- Hydraulic:Fluid power drives offer high power density for specialized high-force compression applications.
Electromechanical drives account for the dominant share of new orders; thermal drive demand is contracting most rapidly outside remote upstream installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized alloy supply chains for high-pressure hydrogen service concentrate in German and Japanese forging centers, while final equipment assembly clusters near demand corridors in Texas, Rotterdam, and Shanghai.
United States
Gulf Coast ammonia synthesis projects and Permian Basin gas lift operations anchor compressor procurement volumes. EPA methane rules under the IRA are accelerating replacement cycles for aging reciprocating units across Texas and Louisiana refineries. Houston-area fabrication yards are expanding modular skid capacity to serve carbon capture retrofits at coal and gas plants.
Germany
Green hydrogen hub investments in the Rhineland and northern coastal regions are pulling demand for 700-bar reciprocating compression systems. EU F-Gas Regulation leakage limits are forcing seal upgrades across BASF and Covestro chemical corridors. Ruhr Valley compressor OEMs face superalloy input bottlenecks from specialized forging suppliers in Essen and Düsseldorf.
China
Dual carbon goals under MEE directives are expanding carbon capture installations at coal-fired plants in Shandong and Shanxi provinces. Yangtze River Delta chemical producers are importing API 617-certified centrifugal designs for ethylene expansion projects. Sinopec and PetroChina are anchoring domestic reciprocating compressor development for hydrogen pipeline injection.
Japan
High-pressure diaphragm compressor demand from semiconductor and specialty gas producers concentrates in Osaka-Kobe industrial zones. METI hydrogen roadmap targets are stimulating investment in 700-bar fueling infrastructure for Tokyo and Nagoya corridors. Japanese forging specialists in Hiroshima and Kobe control critical superalloy supply for global reciprocating OEMs.
Saudi Arabia
Blue ammonia export projects at Jubail and Yanbu are specifying large-scale centrifugal compression trains for carbon capture integration. Aramco hydrogen pilot programs are testing high-pressure reciprocating units for pipeline injection at Eastern Province facilities. Saudi Industrial Development Fund financing is channeling capital toward certified low-leakage compressor technologies.
Process Gas Compressors Market Competitive Landscape
Global majors compete with regional champions across hydrogen-compatible metallurgy and aftermarket service density. Turbomachinery heritage groups anchor large-scale centrifugal contracts in energy transition projects, while specialized reciprocating fabricators capture high-pressure hydrogen and carbon capture applications. Strategic moves concentrate on superalloy supply security and digital monitoring integration rather than pure scale expansion.
Among European turbomachinery groups, Siemens Energy AG and MAN Energy Solutions exemplify divergent specialization paths—one leveraging rotating equipment heritage for base-load applications, the other concentrating on positive displacement architectures for extreme pressure ratios. Atlas Copco Group occupies a position defined by aftermarket service network density and global parts distribution reach rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Atlas Copco Group |
| Ingersoll Rand Inc. |
| Siemens Energy AG |
| General Electric |
| Burckhardt Compression AG |
| Howden Group |
| MAN Energy Solutions |
| Ariel Corporation |
| Sundyne LLC |
| Others |
Value Network & Pricing Analysis
Sovereign-backed hydrogen hub investments in Germany and the United States are concentrating procurement power among state-anchored offtakers, compressing margin structures for OEMs while elevating metallurgy costs as the dominant price driver. This ownership pattern tightens pricing discipline across the value chain, forcing fabricators to absorb superalloy volatility or cede share to integrated forging-to-assembly specialists.
Pricing Analysis
Warranty and service bundling now separates premium-tier OEMs from stripped-down equipment vendors across the process gas compressor market. Project-based contracting dominates large hydrogen and carbon capture installations, with price differentiation resting on API 617 certification status and aftermarket service density. Cost compression in standard centrifugal units is intensifying because chemical plant operators are unbundling parts procurement from technical service. Refinery operators in the US Gulf Coast demonstrate the highest price sensitivity, while German hydrogen hub developers prioritize leakage tolerance and pay premiums for certified low-emission architectures.
Supply Chain Analysis
Refurbishment and remanufacturing flows for high-pressure reciprocating compressors are expanding as German and Japanese forging centers extend asset life cycles through requalified superalloy components. Superalloy forgings for hydrogen service concentrate in Germany, Japan, and select US specialty metals producers, with nickel-chromium-molybdenum bar stock and precision castings as critical inputs. Single-source vulnerability around aerospace-grade forging capacity creates supply chain risk during hydrogen infrastructure ramp-ups. Distribution runs through OEM-direct channels for large project orders and independent distributors for aftermarket consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The process gas compressor market functions as a cost-of-compliance arena where EU F-Gas Regulation leakage limits and EPA methane rules erect certification barriers that shelter compliant incumbents from price-only competition.
For Market Incumbents: Lock in superalloy supply through captive forging partnerships or long-term offtake agreements with German and Japanese specialists. Deepen digital monitoring integration to extend aftermarket service contracts beyond traditional overhaul cycles. The threat of independent parts distributors unbundling maintenance relationships demands channel control through proprietary IoT platforms and predictive analytics offerings. For New Entrants and Emerging Players: Launch via modular skid-mounted compression packages targeting distributed hydrogen fueling infrastructure in California and South Korea. White-space concentration sits with compact 700-bar reciprocating units for mobility applications, where rapid deployment cycles and standardized designs offset incumbent scale advantages. A direct-to-plant sales model bypassing EPC markups offers the most penetrable go-to-market angle for capital-constrained developers. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized reciprocating fabricators with proven hydrogen embrittlement metallurgy expertise in German industrial clusters. Long-term viability hinges on exposure to green hydrogen and carbon capture project pipelines rather than legacy hydrocarbon maintenance cycles. The signal to watch is ISO 10494 certification queue congestion, which indicates demand outstripping accredited testing capacity and foreshadows pricing power shifts toward certified OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Superalloy Supply Security | Backward integration into German and Japanese forging centers insulates margin structures from nickel volatility. |
| Digital Monitoring Integration | Proprietary IoT platforms from Siemens Energy and Atlas Copco extend aftermarket contract renewal rates. |
| Hydrogen Compatibility Certification | API 618 reciprocating designs with distance piece venting capture premium positioning in 700-bar service. |
| Modular Skid Standardization | Pre-assembled compression packages accelerate field deployment for distributed fueling stations in California corridors. |
| Carbon Capture Retrofit Positioning | CO2 compression trains optimized for pipeline-grade purity anchor equipment awards at Chinese coal plant retrofits. |
Research Methodology
Trade flow databases, API certification registries, and hydrogen hub project announcements formed the secondary backbone for this analysis. Primary interviews with maintenance directors at US Gulf Coast refineries, procurement leads at German chemical producers, aftermarket service heads at major OEMs, and EPC contractors specializing in carbon capture installations combined with secondary validation. Bottom-up and top-down triangulation cross-checked equipment shipment data against announced project capacities.
Bottom-up modeling anchored forecasts in unit-level economics across compressor architectures, while top-down verification against announced hydrogen hub investments and refinery modernization budgets calibrated aggregate demand. Segmentation dimensions included product type, end-use industry, installation environment, and drive mechanism technology. CAGRs were derived from slope analysis of announced project pipelines and historical replacement cycle patterns, with superalloy cost trajectories and regulatory compliance timelines as industry-specific forecast inputs.
Policy acceleration, hydrogen infrastructure delays, and superalloy supply disruptions are the dominant revision risks to these projections. Forecasts reflect assumptions about regulatory enforcement consistency and project financing availability. Practitioners should monitor EU F-Gas Regulation implementation pace and ISO 10494 laboratory queue lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Compressor Wheel Market
Compressors
Hydrogen Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Axial Compressor Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
North America Hydrogen Compressor Market
Compressors
Automotive Compressors Market
Compressors
USA Scroll Compressor Market
Compressors
Compressor Rental Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
North America Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Rotary Lobe Compressor Market