
 USA Scroll Compressor Market | 2026-2036
USA Scroll Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
USA Scroll Compressor Market Analytics
A widening capability gap between fully integrated scroll compressor manufacturers and assembly-dependent competitors is unwinding traditional competitive stability in the US market. Emerson Electric Co. leverages captive motor and inverter production to control cost architecture across variable speed lines. Copeland sustains dominant channel access through its long-standing OEM relationships with residential HVAC original equipment manufacturers. Danfoss Group anchors its position with deep refrigeration application expertise and oil-less system integration.
The USA scroll compressor is a positive-displacement compression device employing two interleaved spiral-shaped scroll members—one orbiting, one fixed—to compress refrigerant vapor through progressive volume reduction, typically achieving discharge pressures of 150–450 psig depending on refrigerant and application. Its primary purpose is to provide efficient, quiet, and reliable gas compression for climate control and cooling systems across commercial, industrial, and residential installations. Variable speed scroll compressors are capturing disproportionate growth as building electrification mandates and efficiency codes tighten, while single-stage units retain volume leadership in cost-sensitive replacement markets. Oil-less operation modes command premium positioning in medical, pharmaceutical, and food processing environments where contamination risks override first-cost considerations.
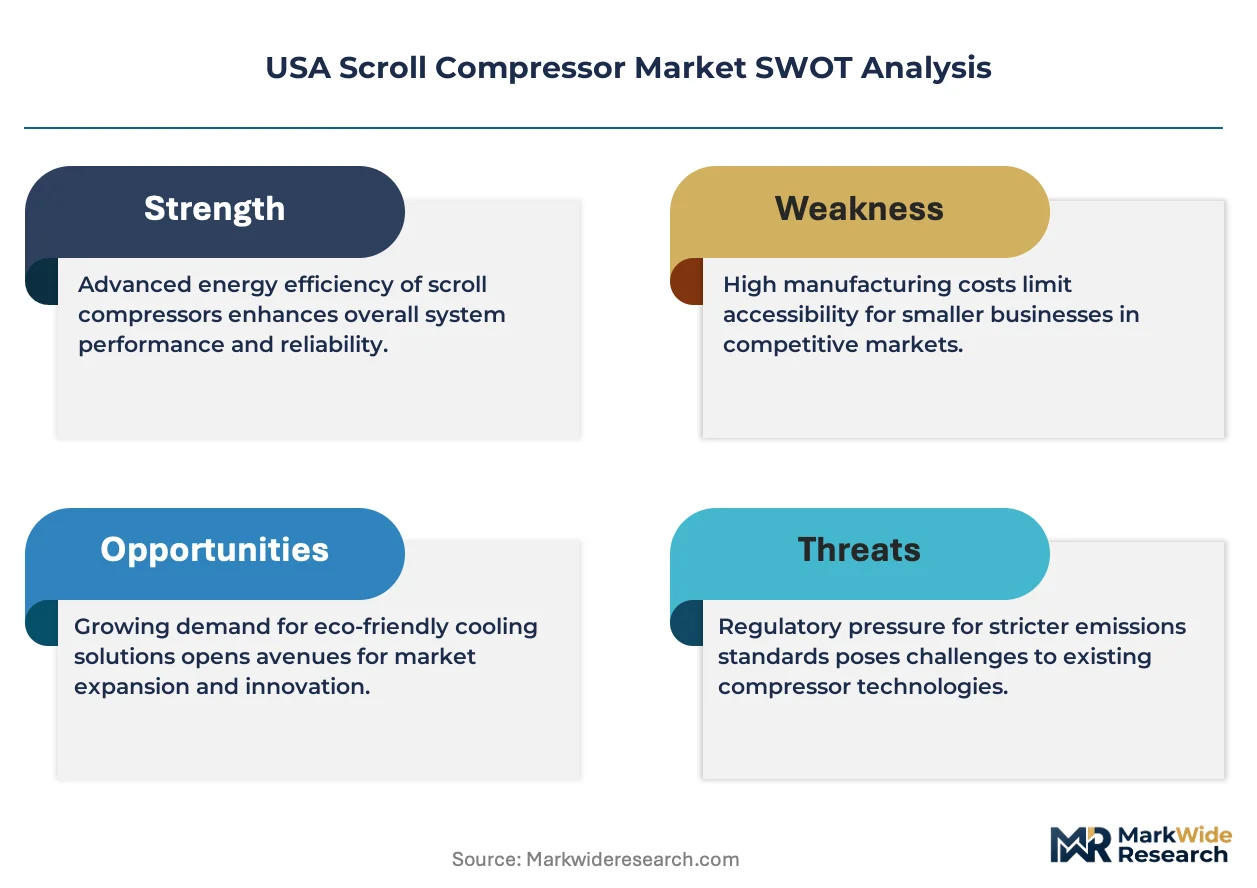
EPA refrigerant management rules under the AIM Act and DOE appliance efficiency standards are reshaping product qualification requirements and accelerating obsolescence of fixed-speed, high-GWP refrigerant systems. NHTSA thermal management standards for electric vehicle battery cooling create incremental demand pull from automotive sector suppliers. Stakeholders must monitor state-level building performance standards in California, Washington, and New York for early signals of scroll compressor specification shifts that will propagate through national distribution channels.
Market Dynamics
Variable speed inverter technology is compressing replacement cycles across the US scroll compressor market as efficiency mandates tighten and electrification codes propagate from California and Washington through national building codes.
Growth Catalysts
- EPA AIM Act refrigerant phase-down:The HFC reduction schedule is forcing premature retirement of fixed-speed R-410A systems, creating replacement pull across Sun Belt commercial and residential installations.
- Cooling-degree-day concentration:Texas, Florida, and California account for disproportionate compressor demand as building stock expands and heat intensification extends cooling seasons.
- Electric vehicle battery thermal management:NHTSA thermal runaway standards are creating incremental demand from automotive suppliers for compact, high-reliability scroll compressors in battery cooling loops.
Market Restraints
- Copper and rare-earth magnet cost volatility:Motor winding materials and permanent magnet inputs expose manufacturers to commodity price swings that compress margin on variable speed units.
- Integrated manufacturer supply concentration:Captive motor and inverter production capabilities concentrate among vertically integrated producers, raising barriers for assembly-dependent competitors.
- R-454B and R-32 flammability protocols:A2L refrigerant safety classifications impose equipment redesign costs and technician retraining burdens that slow product rollout.
Strategic Opportunities
- Medical and pharmaceutical oil-less systems:Contamination-sensitive environments command premium positioning for hermetic, oil-free scroll compressors in US drug manufacturing and laboratory applications.
- State building performance standard propagation:California's Title 24 and Washington's Clean Buildings Performance Standards are creating specification templates that will migrate through national distribution channels.
- Heat pump deployment acceleration:DOE cold-climate heat pump challenge programs are expanding scroll compressor addressable market into northern states previously served by fossil heating.
Industry Challenges
- A2L refrigerant technician certification timelines:EPA Section 608 program expansion to cover mildly flammable refrigerants is creating workforce bottlenecks that constrain installation capacity.
- Legacy control system integration friction:Variable speed compressors require inverter-integrated controls that often conflict with existing building automation protocols, complicating retrofit specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Scroll Compressor Market |
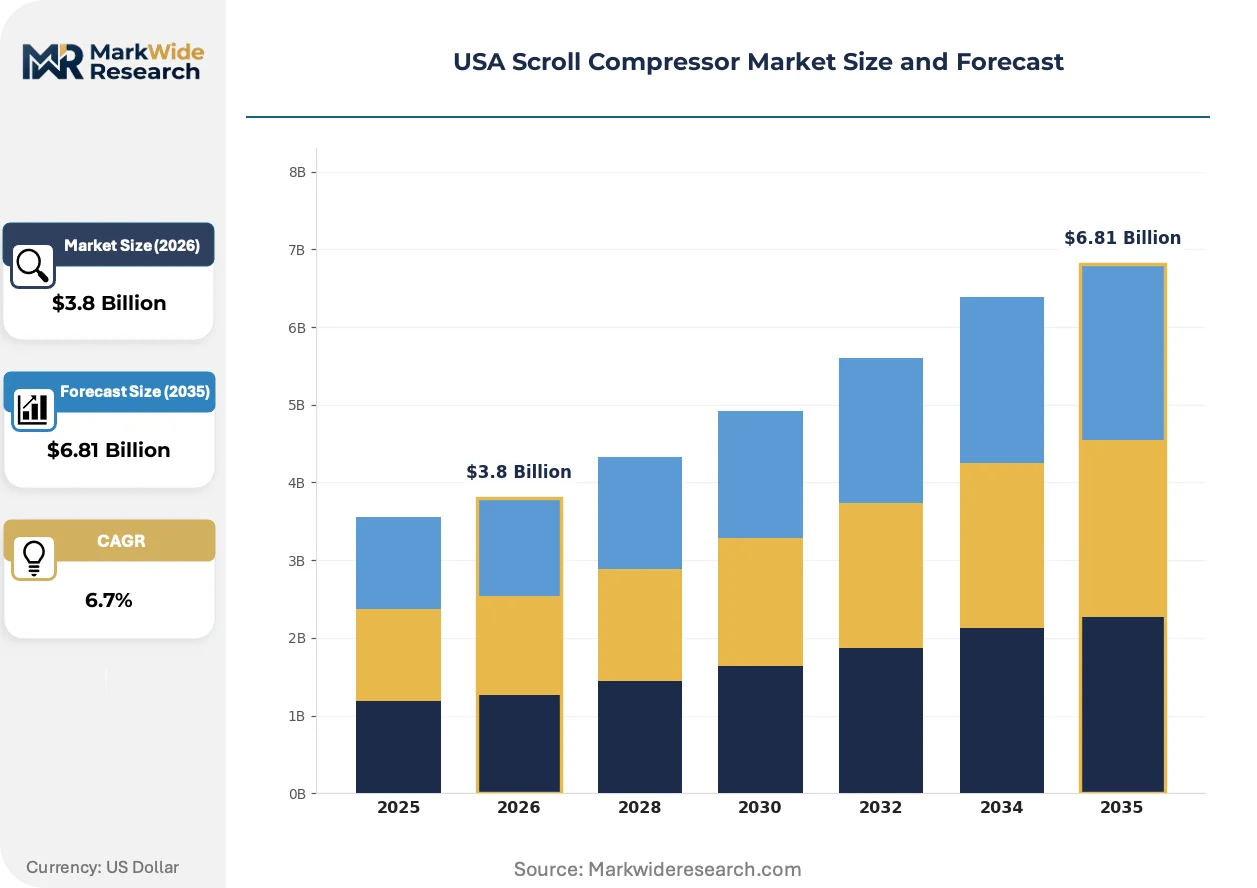
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Two-Stage, Multi-Stage, Variable Speed End Use Industry: HVAC, Refrigeration, Industrial, Automotive Operation Mode: Oil-Less, Lubricated, Modulated, Fixed Speed Application: Chillers, Air Conditioners, Heat Pumps, Refrigerators |
| Companies Covered | Emerson Electric Co., Danfoss Group, Copeland, Mitsubishi Electric Corporation, LG Electronics Inc., Bitzer US, Inc., Hitachi Global Air Power US, Panasonic North America, Tecumseh Products Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Scroll Compressor Market Evolving Landscape
Digital compressor controls and refrigerant chemistry shifts are restructuring product qualification requirements and accelerating obsolescence of established equipment categories across the US market.
Permanent magnet synchronous motors paired with field-oriented control algorithms are supplanting induction motor drives in mid-to-high tonnage commercial applications. Large retail and healthcare facility operators are specifying these systems for chiller and rooftop unit replacements on 7-10 year cycles rather than traditional 15-year intervals. The technology is supplanting fixed-speed scroll dominance in premium commercial segments where part-load efficiency determines total cost of ownership.
EPA SNAP program approvals for R-454B and R-32 under AIM Act authority are mandating equipment redesigns across OEM supply chains. The refrigerant transition is compressing product development timelines and forcing simultaneous updates to safety standards, installation practices, and service protocols. Residential and light commercial segments are absorbing the bulk of compliance costs as manufacturers dual-certify product lines for the 2025-2028 transition window.
Performance contracting and energy-as-a-service models are restructuring how building owners acquire compression equipment. Third-party ownership structures are displacing traditional capital purchase decisions in multi-site retail and hospitality portfolios, particularly across Texas and Florida markets where cooling loads dominate operating expenditures. Equipment specification authority is shifting from facility managers to specialized energy service companies with standardized technical requirements.
USA Scroll Compressor Market Segmentation
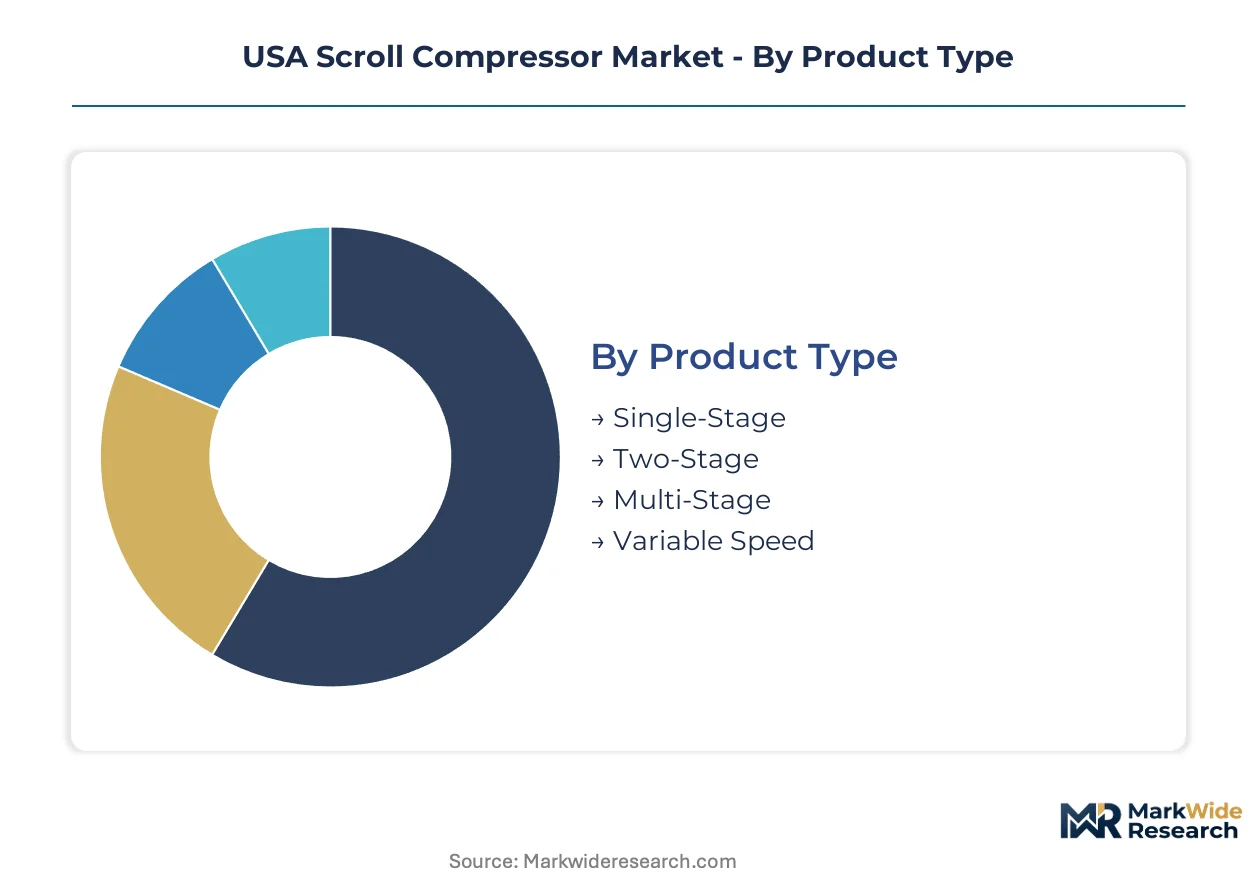
Scroll compressor segmentation reveals how technology specialization and end-use requirements fragment manufacturing priorities. Product architecture, operational demands, and regulatory compliance create distinct margin pools across configuration categories.
Product Type:
Margin concentration sits with variable speed architectures where inverter integration and motor control sophistication command pricing premiums over fixed-displacement alternatives.
- Variable Speed:Permanent magnet synchronous motors paired with field-oriented control algorithms enable part-load efficiency optimization. Texas and Florida commercial HVAC contractors specify these for rooftop unit retrofits where cooling-degree-day loads justify premium first costs through operating savings.
- Single-Stage:Fixed displacement compression at constant speed dominates residential replacement volumes with simpler manufacturing economics. California Title 24 efficiency mandates are compressing its addressable market share in new construction specifications.
- Two-Stage:Dual capacity modulation bridges efficiency and cost positioning for mid-tier commercial applications.
- Multi-Stage:Sequential compression chambers serve specialized industrial process cooling with precise pressure staging requirements.
The dominant share belongs to Single-Stage, while Variable Speed is closing the gap fastest.
End Use Industry:
Application-specific performance requirements and certification burdens create divergent cost structures across vertical markets.
- HVAC:Building climate control systems account for the largest equipment volume, with commercial rooftop units and split systems driving specification activity. EPA AIM Act refrigerant phase-down rules are accelerating replacement cycles across Sun Belt states where R-410A obsolescence forces equipment turnover.
- Refrigeration:Cold chain infrastructure and food retail applications demand hermetic reliability under continuous operation. Oil-less scroll configurations command substantial premiums in pharmaceutical distribution centers where contamination protocols override capital cost sensitivity.
- Industrial:Process cooling and compressed air applications require heavy-duty bearing systems and extended maintenance intervals.
- Automotive:NHTSA thermal runaway standards for electric vehicle battery cooling are creating incremental demand for compact, high-reliability units in automotive supplier channels.
HVAC maintains volume leadership, though Automotive is expanding most quickly from a smaller base.
Operation Mode:
Contamination risk tolerance and maintenance access determine technology selection and pricing power across operational configurations.
- Oil-Less:Hermetic, oil-free compression eliminates lubricant contamination risks in medical device manufacturing and laboratory environments. FDA-regulated pharmaceutical production facilities in Massachusetts and North Carolina specify these for sterile process cooling despite substantial cost premiums.
- Lubricated:Conventional oil-flooded bearings serve general commercial HVAC where maintenance access is routine and contamination risks are minimal.
- Modulated:Digital capacity control enables precise matching of cooling output to variable thermal loads.
- Fixed Speed:Constant RPM operation retains cost-sensitive replacement market positioning where efficiency penalties are acceptable.
Lubricated systems hold the largest installed base, yet Oil-Less is gaining share fastest in premium verticals.
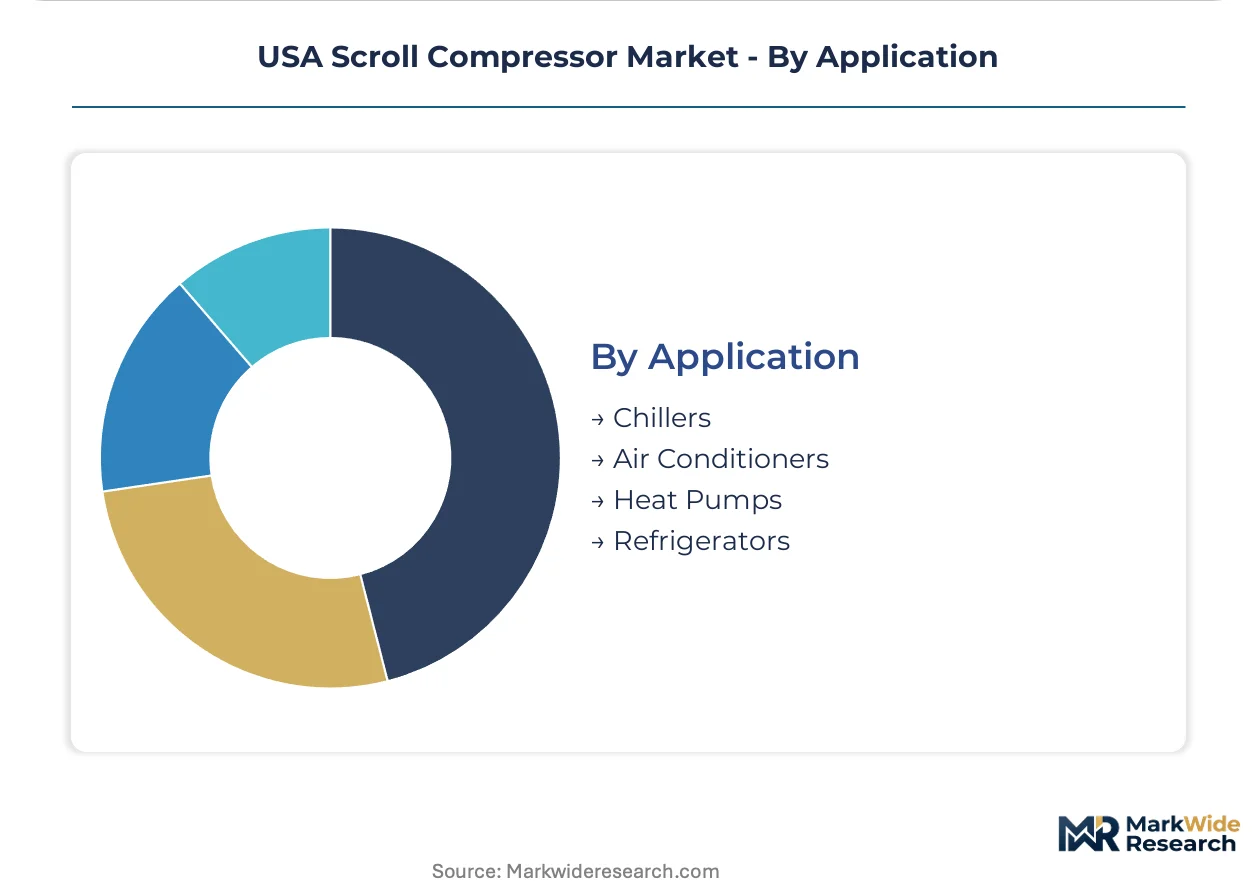
Application:
Equipment form factor and thermal load characteristics dictate compressor sizing, refrigerant selection, and control integration requirements.
- Air Conditioners:Residential and light commercial cooling systems represent the highest unit volume segment. DOE appliance efficiency standards and state-level building codes in California and Washington are mandating variable speed adoption for new installations.
- Heat Pumps:Reversible heating-cooling operation expands addressable market into northern states previously served by fossil fuel heating. DOE cold-climate heat pump challenge programs are extending scroll compressor applicability below traditional temperature limits.
- Chillers:Central plant cooling for large commercial and institutional buildings requires higher tonnage configurations with sophisticated control integration.
- Refrigerators:Domestic and commercial cold storage applications utilize smaller displacement units with specialized refrigerant charge optimization.
Air Conditioners command the dominant position, while Heat Pumps show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Texas and Florida exceeds California by 12-18% due to cooling-degree-day intensity and contractor consolidation. The Sun Belt states generate disproportionate equipment pull as heat intensification extends compressor replacement cycles.
Texas
Houston and Dallas-Fort Worth metro areas drive commercial rooftop unit demand as corporate relocation accelerates building stock expansion. Texas Commission on Environmental Quality enforcement of EPA AIM Act timelines compresses R-410A system retirement schedules. San Antonio's military and healthcare facility clusters specify variable speed oil-less configurations for contamination-sensitive cooling loads.
Florida
Miami-Dade and Broward counties absorb hurricane-season equipment replacement surges alongside steady new construction pull. Florida Building Code efficiency amendments align with DOE appliance standards to mandate inverter-ready compressors in coastal zones. Orlando's hospitality corridor deploys performance-contracting models that standardize variable speed specifications across multi-site portfolios.
California
Title 24 building standards and CARB refrigerant regulations force premature retirement of fixed-speed equipment in Los Angeles and San Diego metro areas. Sacramento's state procurement protocols propagate efficiency specifications through institutional channels. Central Valley agricultural processing facilities create specialized demand for heavy-duty scroll configurations in cold chain infrastructure.
Arizona
Phoenix-Mesa-Scottsdale cooling loads exceed national averages by 40%, compressing equipment lifecycles and accelerating replacement frequency. Arizona Corporation Commission rate structures incentivize demand-responsive HVAC systems with variable speed compressors. Tucson's semiconductor fabrication plants specify oil-less scroll units for cleanroom environmental control.
Georgia
Atlanta's logistics and data center construction sustains chiller and rooftop unit demand across commercial segments. Georgia Environmental Protection Division refrigerant management rules enforce EPA Section 608 compliance timelines. Savannah's port expansion drives cold chain infrastructure investment requiring hermetic refrigeration compressors.
USA Scroll Compressor Market Competitive Landscape
Concentration sits with vertically integrated manufacturers controlling captive motor and inverter supply chains. The vendor base stratifies across three tiers: full-system integrators with in-house power electronics, assembly-dependent OEMs sourcing subsystems externally, and regional specialists serving niche contamination-sensitive applications. Strategic moves center on refrigerant transition product certification and state-level building code pre-positioning.
Within the integrated manufacturing tier, Emerson Electric Co. and Danfoss Group occupy positions defined by upstream control over motor winding and inverter production. Copeland exemplifies channel-dominant positioning through long-standing OEM relationships. Mitsubishi Electric Corporation represents the Japanese industrial conglomerate archetype with diversified thermal management portfolios spanning HVAC and automotive applications.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Danfoss Group |
| Copeland |
| Mitsubishi Electric Corporation |
| LG Electronics Inc. |
| Bitzer US, Inc. |
| Hitachi Global Air Power US |
| Panasonic North America |
| Tecumseh Products Company |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Texas commercial HVAC contractors and integrated manufacturers lock in copper winding allocations and inverter module access while capping price escalation exposure across the 2025-2028 refrigerant transition window. These contracts bind volume commitments to fixed pricing bands that shelter buyers from rare-earth magnet cost swings while securing supply priority during A2L refrigerant equipment rollout bottlenecks.
Pricing Analysis
Configured-to-order pricing for variable speed scroll compressors commands 25-35% premiums over standard single-stage catalog pricing, with permanent magnet motor specifications and field-oriented control integration driving differentiation. Pricing stratifies across premium, standard, and economy tiers where oil-less hermetic configurations for pharmaceutical applications sit atop the structure and fixed-speed residential replacement units anchor the bottom. Cost compression in the standard tier is intensifying because assembly-dependent competitors struggle to match integrated manufacturers' captive motor economics. Residential replacement contractors in Florida and Arizona exhibit highest price sensitivity, while Massachusetts pharmaceutical facility operators accept substantial premiums for contamination-risk mitigation.
Supply Chain Analysis
Inventory buffers for copper windings and rare-earth permanent magnets have compressed to 6-8 weeks from historical 12-week levels as OEMs synchronize procurement to EPA AIM Act equipment transition schedules. Manufacturing concentration centers on Mexico, China, and domestic US facilities for final scroll set machining and hermetic housing assembly, with motor laminations and inverter power modules drawing from Taiwan and South Korea. Single-source vulnerability in neodymium magnet supply from Chinese processors creates tariff exposure risk that manufacturers hedge through strategic stockpiling. Distribution runs through authorized wholesaler networks serving Sun Belt HVAC contractors, with direct OEM relationships dominating large commercial and industrial account procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USA scroll compressor market sits at an inflection where EPA AIM Act refrigerant mandates and DOE efficiency standards are compressing replacement cycles while reshaping competitive advantage toward integrated power electronics capabilities.
For Market Incumbents: Shield channel position in Texas and Florida by accelerating A2L refrigerant product certification ahead of state-level adoption timelines, while securing captive rare-earth magnet supply through backward integration into permanent magnet sourcing or long-term offtake partnerships. Compressor manufacturers lacking inverter production capabilities face margin erosion as variable speed specifications displace fixed-speed volumes in commercial segments. For New Entrants and Emerging Players: Aftermarket service and remanufacturing capabilities represent an underserved layer where incumbent OEMs under-invest, creating entry pathways for specialists offering compressor rebuild and control retrofit services to extend equipment life in cost-sensitive residential replacement markets. Target Georgia and Arizona logistics and data center construction corridors with oil-less scroll configurations for cleanroom and battery cooling applications, leveraging performance contracting models that shift specification authority from facility managers to energy service companies. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive motor winding and inverter assembly capabilities that can capture margin pools escaping assembly-dependent competitors during the refrigerant transition wave. Five-to-ten year viability hinges on positioning for heat pump deployment acceleration into northern states and electric vehicle battery thermal management demand expansion. Monitor NHTSA thermal runaway standard enforcement timelines as the critical signal for automotive supplier channel inflection.| Strategic Initiative | Industry Significance |
|---|---|
| A2L Refrigerant Product Certification | EPA SNAP program approvals for R-454B and R-32 equipment designs determine competitive eligibility across OEM supply chains. |
| Permanent Magnet Supply Security | Captive rare-earth sourcing or long-term offtake agreements insulate margin structures from commodity volatility in variable speed production. |
| Oil-Less System Portfolio Expansion | FDA-regulated pharmaceutical and medical device manufacturing facilities command substantial pricing premiums for contamination-free compression. |
| Heat Pump Cold-Climate Performance Investment | DOE challenge program specifications extend addressable market into northern states previously served by fossil fuel heating systems. |
| Performance Contracting Channel Development | Third-party ownership structures in Texas and Florida hospitality portfolios shift specification authority toward standardized technical requirements. |
Research Methodology
Cross-validation between primary interviews with commercial HVAC contractors, refrigeration system integrators, and OEM procurement directors and secondary analysis of EPA regulatory filings, DOE appliance efficiency standards, and AHRI certification databases anchors the qualitative findings. Bottom-up equipment shipment data from Texas, Florida, and California distribution channels triangulates against top-down cooling-degree-day load modeling and building stock expansion projections. Conversations with state environmental regulators in California, Washington, and Texas informed compliance timeline assumptions for AIM Act implementation.
Sensitivity analysis across refrigerant transition pace scenarios, copper and rare-earth price bands, and state building code adoption rates tests forecast robustness across the projection horizon. Segmentation modeling incorporates product architecture tiers, end-use industry verticals, operational mode configurations, and application categories with geographic demand clustering. CAGRs derive from equipment replacement cycle compression analysis, electrification mandate propagation patterns, and heat pump deployment trajectory modeling informed by cold-climate performance challenge program specifications.
Material uncertainties — EPA Section 608 technician certification bottlenecks, A2L refrigerant safety protocol adoption delays, and copper supply disruption events — sit outside the modeled envelope and could accelerate or compress projected equipment turnover timelines. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and state-level code propagation patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Oil-Free Air Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Gas Compressors Market
Compressors
PAG Compressor Oil Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Oil Filled Air Compressor Market
Compressors
Air Compressor Market
Compressors
Hydrogen Compressor Market
Compressors
Booster Compressor Market
Compressors
Root Blower Market
Compressors
CNG Compressor Market
Compressors
Rental Air Compressors Market
Compressors
Compressor Rental Market
Compressors
Asia-Pacific Booster Compressor Market