
 Oil and Gas Industry Gas Compressor Market | 2026-2036
Oil and Gas Industry Gas Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Industry Gas Compressor Market Analytics
The EPA's updated methane performance standards for new and modified oil and gas sources is decoupling compressor procurement from pure horsepower economics, embedding emissions intensity into capital planning. Ingersoll Rand leverages its centrifugal portfolio to anchor positions in large-scale gas processing facilities. Baker Hughes Company competes through integrated compression trains that bundle turbomachinery with digital monitoring systems.
Oil and gas industry gas compressors are mechanical devices that raise the pressure of natural gas or process vapors through positive displacement or dynamic compression principles, typically achieving discharge pressures from 100 psig to over 10,000 psig depending on stage configuration and service. These machines enable pipeline transport, gas injection, and process separation by overcoming pressure drops across gathering networks and treatment facilities. Centrifugal compressors dominate baseload transmission roles where continuous flow and high volume define operational requirements. Reciprocating compressors retain structural importance in high-pressure applications such as enhanced oil recovery where variable speed and staged compression deliver precise injection profiles.
FERC interstate pipeline safety regulations and EPA New Source Performance Standards jointly dictate material specifications, seal technologies, and leak detection protocols for compressors operating in US interstate commerce. OSHA process safety management requirements further constrain maintenance intervals and spare parts traceability for units above threshold quantities. Buyers must weigh total cost of ownership against evolving emissions accounting standards as carbon intensity metrics penetrate supplier scorecards and offtake agreements.
Market Dynamics
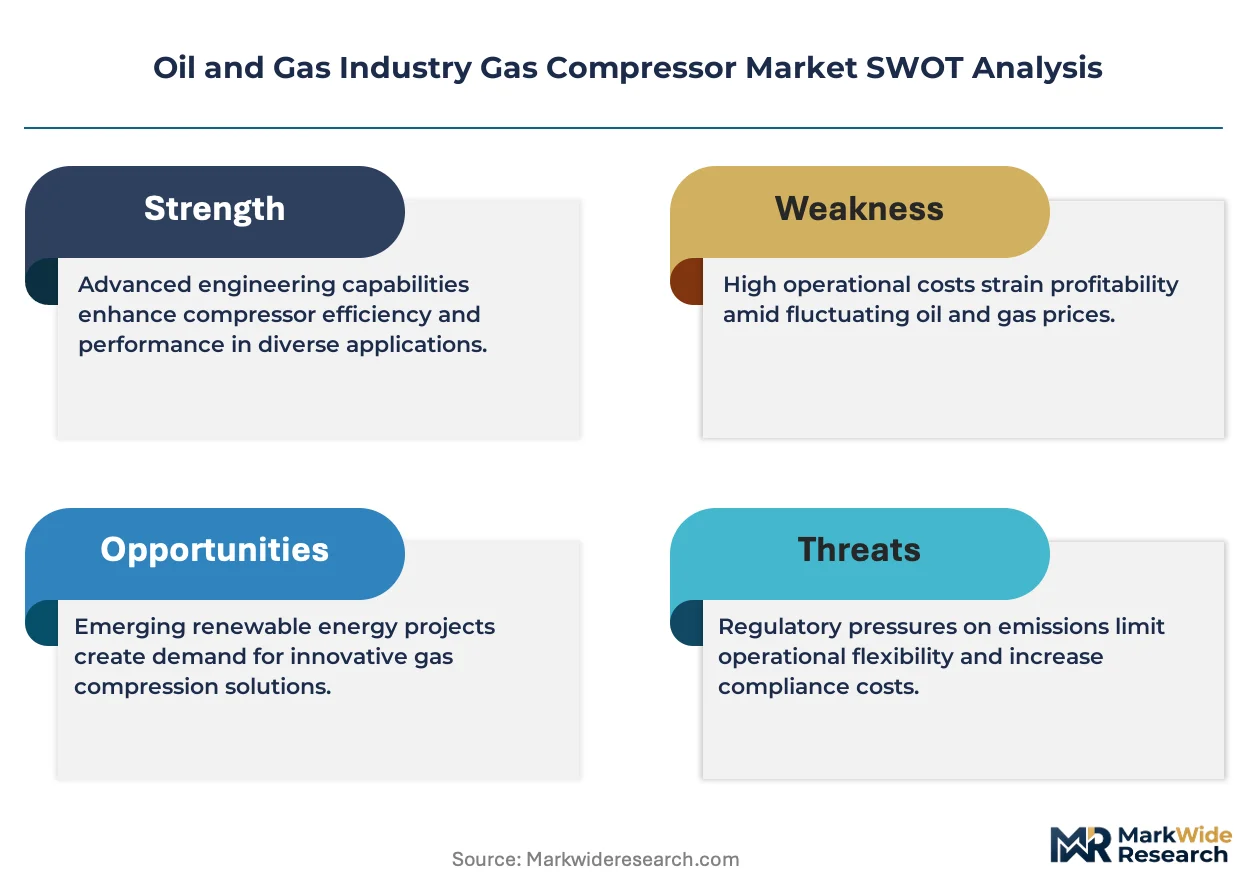
EPA methane performance standards under the Clean Air Act are decoupling compressor procurement from pure horsepower economics, embedding emissions intensity into capital planning across upstream and midstream operations. This regulatory pressure is restructuring supplier relationships and equipment specifications faster than historical replacement cycles.
Growth Catalysts
- Shale basin gas lift expansion:Upstream operators in the Permian Basin are expanding compressor fleets to handle associated gas volumes that outpace pipeline takeaway capacity.
- FERC interstate pipeline safety rules:Material specifications and seal technology mandates under federal pipeline regulations are forcing equipment refresh cycles in US interstate commerce.
- Digital monitoring integration:Real-time leak detection and predictive maintenance systems are extending compressor runtimes and reducing unplanned outages in gas processing facilities.
Market Restraints
- Specialized alloy supply concentration:High-nickel steel forgings for pressure vessels concentrate among a limited supplier base, creating input cost volatility and extended lead times.
- Reciprocating compressor technical ceiling:Mechanical valve losses and pulsation management limits constrain efficiency gains in high-pressure enhanced oil recovery applications.
- OSHA process safety management compliance:Maintenance interval mandates and spare parts traceability requirements add administrative overhead above threshold quantity thresholds.
Strategic Opportunities
- Associated gas monetization in the Permian:Stranded gas volumes in Texas and New Mexico create demand for modular compression solutions ahead of pipeline infrastructure buildout.
- Carbon intensity accounting penetration:Supplier scorecards and offtake agreements are creating premium positioning for low-leakage compressor designs certified to emerging protocols.
- Electrification and variable speed drive convergence:Grid-connected compression trains paired with advanced motor controls are opening new site configurations previously constrained by engine exhaust emissions.
Industry Challenges
- Rotating equipment specialist shortage:Experienced field technicians capable of centrifugal compressor overhaul and alignment are retiring faster than apprenticeship programs replace them.
- Legacy control system integration:Brownfield installations with pneumatic or early digital control architectures face complex retrofit paths for emissions monitoring connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Industry Gas Compressor Market |
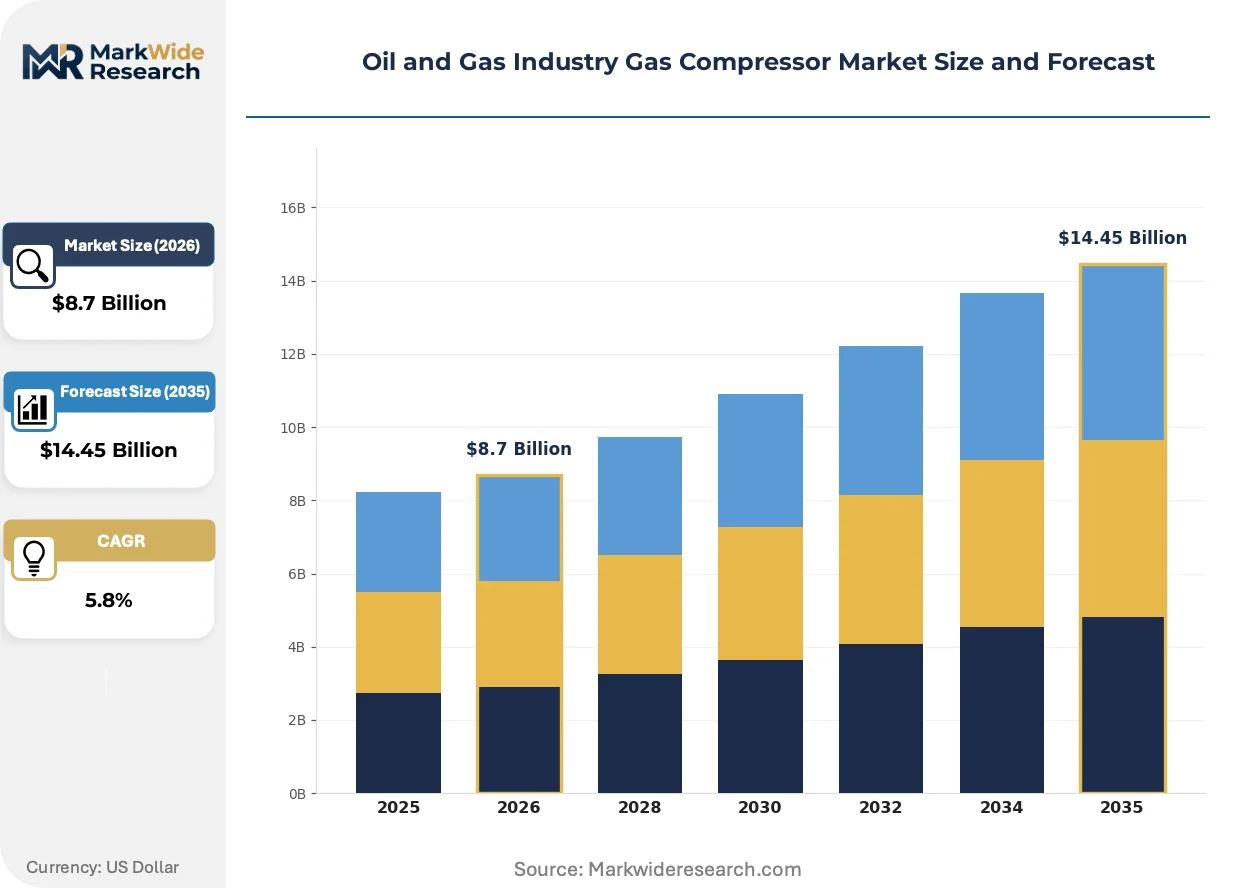
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating Compressors, Rotary Screw Compressors, Centrifugal Compressors, Diaphragm Compressors Application: Natural Gas Processing, Petrochemical Production, Oil Refining, Enhanced Oil Recovery Installation Type: Onshore, Offshore, Modular, Portable End User: Exploration Companies, Production Firms, Midstream Operators, Industrial Users |
| Companies Covered | Ingersoll Rand, Howden Group, Baker Hughes Company, Mitsubishi Heavy Industries, Burckhardt Compression, Siemens Energy, Ariel Corporation, General Electric, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Industry Gas Compressor Market Evolving Landscape
Compression technology is converging with emissions accountability and digital infrastructure, reshaping how operators specify, procure, and operate gas handling equipment across the value chain.
Electric-driven centrifugal compression is electrifying field operations previously dominated by gas engine or turbine prime movers. Midstream operators in gas processing facilities are adopting grid-connected and solar-hybrid configurations at accelerating pace. This shift is compressing the addressable market for conventional engine-driven units while expanding demand for high-voltage motor controls and power conditioning equipment.
EPA New Source Performance Standards for methane from new and modified oil and gas sources are mandating lower-leakage packing, seals, and compressor rod emissions controls. Equipment fabricators must now certify assemblies to quantified emissions rates rather than prescriptive design standards. Large-scale gas processing facilities in Texas and Louisiana are responding by bundling compressor procurement with third-party emissions verification services.
Service contracting is fragmenting from bundled maintenance agreements toward unbundled component-level subscriptions and performance guarantees. Aftermarket providers are displacing original equipment manufacturer service arms in routine maintenance and spare parts logistics. This pattern is most visible in the Permian Basin, where independent compression fleet operators prioritize unit availability over brand loyalty in vendor selection.
Oil and Gas Industry Gas Compressor Market Segmentation
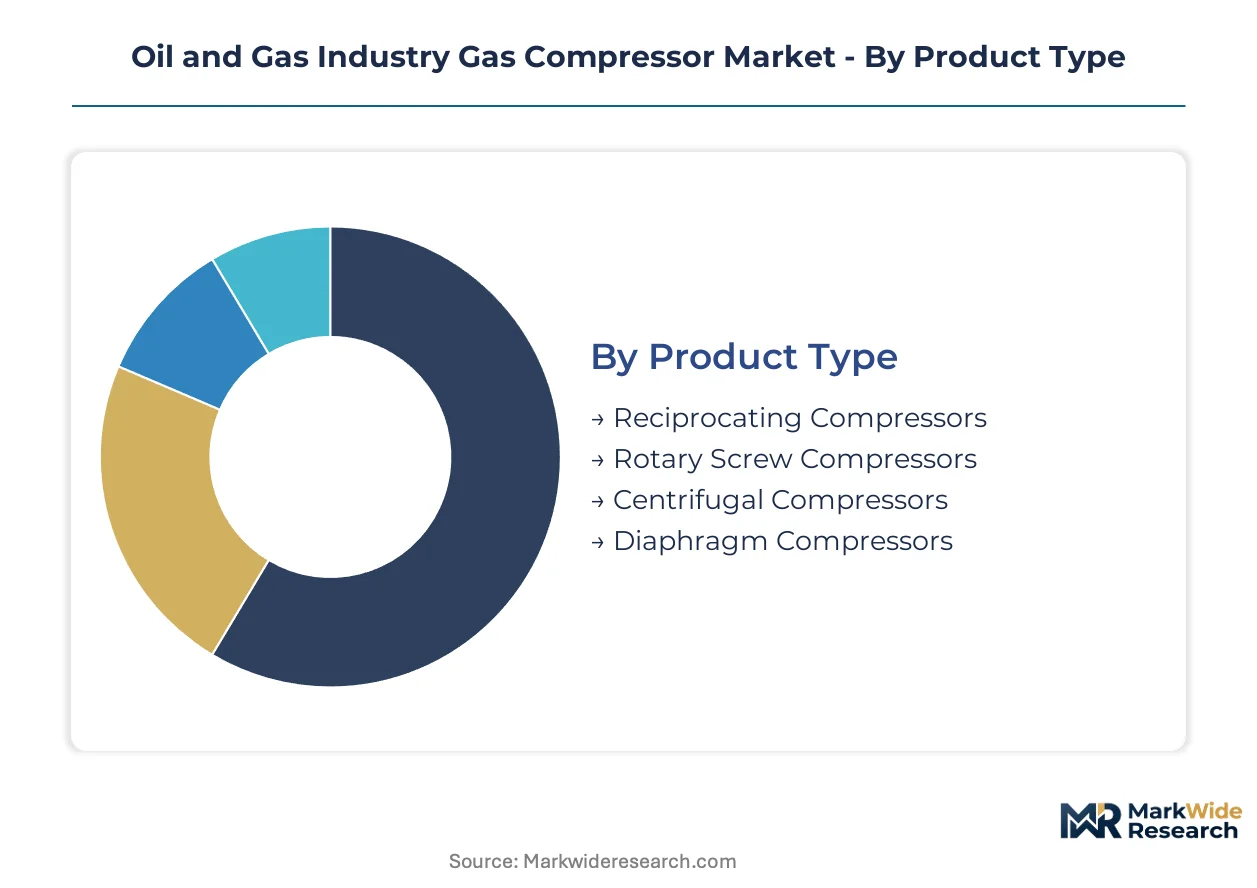
Equipment specification in the Oil and Gas Industry Gas Compressor Market hinges on pressure ratio requirements, gas composition, and duty cycle intensity. Procurement patterns diverge sharply between baseload transmission infrastructure and intermittent field operations, with EPA methane rules now filtering choices through emissions intensity rather than capital cost alone.
Product Type:
Upgrade cycles across the installed base favor equipment categories with the clearest pathways to lower-leakage seal and packing technologies.
- Reciprocating Compressors:Positive displacement machines utilizing piston-cylinder arrangements achieve discharge pressures exceeding 10,000 psig through multi-stage configurations. Demand concentrates in Permian Basin enhanced oil recovery operations where high-pressure gas injection profiles require precise flow control. Mechanical valve losses and pulsation management constraints limit efficiency gains in these high-pressure applications.
- Centrifugal Compressors:Dynamic compression principles employing impeller rotation generate continuous flow suitable for large-volume gas processing. Texas and Louisiana baseload facilities anchor demand as midstream operators electrify field operations previously dominated by gas engine prime movers. Grid-connected configurations are compressing the addressable market for conventional engine-driven alternatives.
- Rotary Screw Compressors:Helical rotor meshing delivers oil-flooded or dry compression for lower-pressure gathering and vapor recovery duties.
- Diaphragm Compressors:Hydraulically actuated membrane isolation provides hermetic sealing for toxic or ultra-high-purity process gases in specialized refinery units.
Centrifugal compressors sit at the top of the volume ranking, with rotary screw configurations climbing the fastest in associated gas monetization applications.
Application:
Cost tier differentiation separates capital-intensive greenfield processing facilities from maintenance-driven replacement spending in mature production basins.
- Natural Gas Processing:Large-scale facilities require compression trains for dehydration, sweetening, and NGL extraction with discharge pressures typically 1,000-1,500 psig. Gulf Coast infrastructure expansion drives procurement as associated gas volumes outpace pipeline takeaway capacity. Third-party emissions verification services are increasingly bundled with compressor procurement under EPA New Source Performance Standards.
- Enhanced Oil Recovery:CO2 and hydrocarbon gas injection mandates precise pressure control across variable reservoir conditions. Permian Basin operators expanding compressor fleets for gas lift operations face mechanical constraints on reciprocating unit efficiency ceilings.
- Petrochemical Production:Ethylene crackers and ammonia synthesis units demand compression for feedstock preparation and recycle gas handling.
- Oil Refining:Fluid catalytic cracking and hydroprocessing units utilize compressors for hydrogen circulation and flare gas recovery.
Natural gas processing commands the largest equipment spend, while enhanced oil recovery exhibits the steepest expansion trajectory as shale operators prioritize reservoir pressure maintenance.
Installation Type:
Customer type stratification distinguishes integrated majors with permanent infrastructure from independent operators seeking deployment flexibility.
- Onshore:Fixed installations at well pads, gathering stations, and processing plants constitute the majority of unit deployments. Texas and New Mexico shale basins anchor demand as stranded gas volumes create urgency for modular solutions ahead of pipeline buildout. FERC interstate pipeline safety regulations dictate material specifications and seal technologies for units in US interstate commerce.
- Modular:Skid-mounted compression packages enable rapid redeployment across multiple well pads or temporary processing sites. Independent compression fleet operators in the Permian Basin prioritize unit availability over brand loyalty, fragmenting service contracting toward unbundled component-level subscriptions.
- Offshore:Platform-based and subsea compression systems serve deepwater production with space-weight constraints and salt corrosion exposure.
- Portable:Trailer-mounted units address emergency backup, maintenance bypass, and short-term production testing requirements.
Onshore installations dominate unit volume, with modular configurations gaining share fastest among capital-constrained independents.
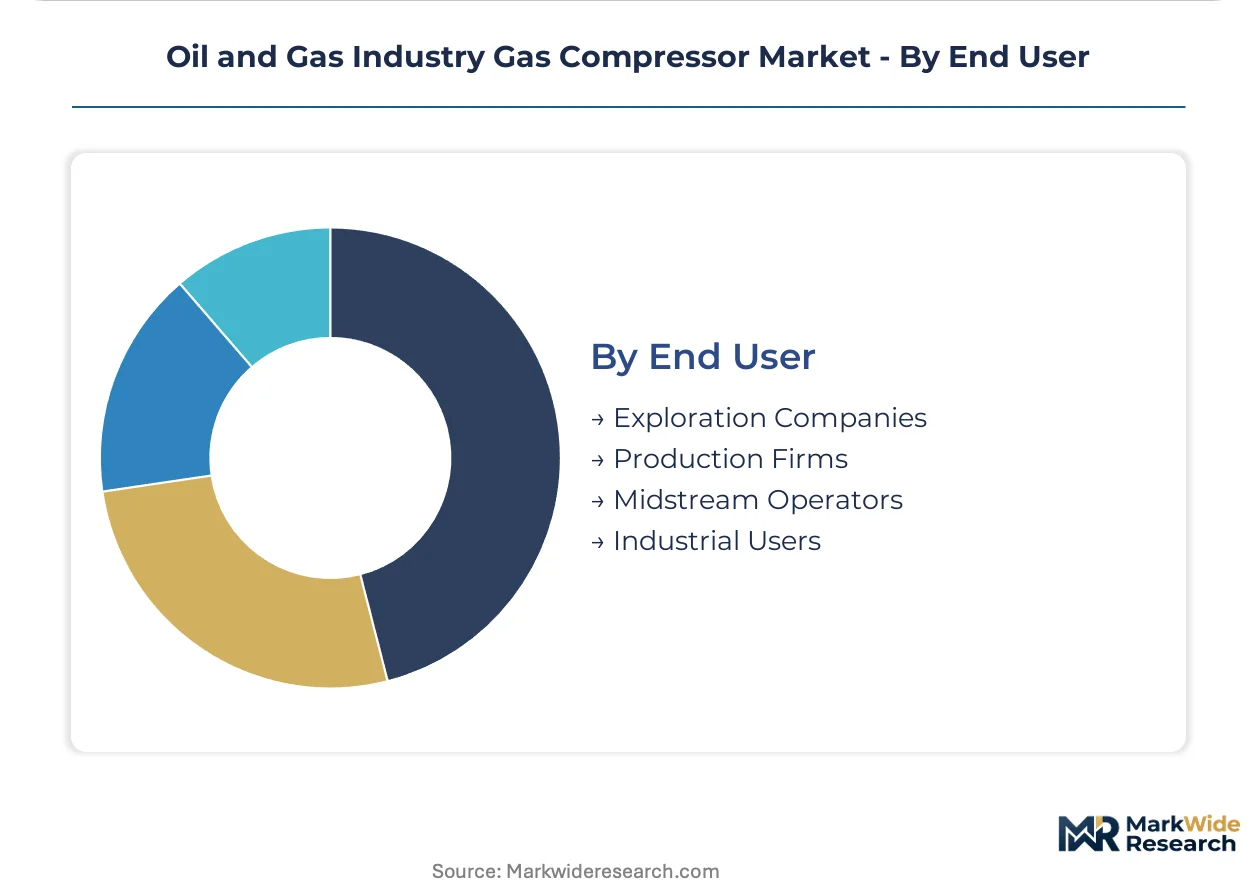
End User:
Supply concentration in high-nickel steel forgings creates procurement leverage disparities between volume buyers and fragmented demand.
- Midstream Operators:Pipeline and gas processing companies specify large centrifugal trains with decades-long service horizons. Louisiana and Texas facility operators are adopting electric-driven configurations at accelerating pace, expanding demand for high-voltage motor controls. Aftermarket providers are displacing original equipment manufacturer service arms in routine maintenance.
- Production Firms:Upstream companies operating shale wells require compression for gas lift, gathering, and field processing with high utilization demands. OSHA process safety management requirements constrain maintenance intervals and spare parts traceability for units above threshold quantities.
- Exploration Companies:Early-stage operators prioritize portable and rental compression for appraisal drilling and initial production testing.
- Industrial Users:Refineries and petrochemical plants integrate compressors into continuous process trains with stringent reliability requirements.
Midstream operators represent the largest equipment purchaser segment, with production firms expanding most quickly as associated gas volumes rise across shale basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rotating equipment technicians concentrate in Houston, Calgary, and Aberdeen, anchoring regional service capabilities. These talent clusters shape where compressor OEMs locate technical centers and where midstream operators source overhaul expertise.
United States
Permian Basin operators expand compressor fleets for gas lift and gathering as associated gas volumes exceed pipeline capacity. EPA methane performance standards under the Clean Air Act mandate lower-leakage packing and seal technologies for new installations. Texas and New Mexico shale plays anchor demand, with Midland-Odessa serving as the primary procurement hub for modular compression packages.
Canada
Montney and Duvernay shale operators require compression for sour gas handling and cryogenic gas processing. Alberta's provincial regulator enforces Directive 060 for fugitive emissions management, dictating leak detection and repair protocols. Calgary hosts the dominant concentration of compression fleet operators and technical service providers serving western Canadian sedimentary basins.
Saudi Arabia
Aramco's gas processing expansion and master gas system upgrades drive demand for large centrifugal trains. The national oil company mandates Saudi Aramco Engineering Standards for rotating equipment procurement, embedding local content requirements. The Eastern Province industrial cluster around Jubail anchors domestic fabrication and maintenance capabilities.
China
Sinopec and PetroChina expand pipeline compression capacity for west-east gas transmission and shale gas development. MIIT energy efficiency standards and MEE emissions regulations constrain equipment specifications for domestic suppliers. The Sichuan-Chongqing shale basin concentrates demand for high-pressure reciprocating units in tight gas operations.
Germany
Ruhr industrial corridor operators modernize compression assets for hydrogen blending and carbon capture integration. REACH chemical regulations and CE machinery directives govern material specifications and emissions certification. North Rhine-Westphalia's chemical parks anchor demand for hermetic diaphragm compressors in process gas applications.
Oil and Gas Industry Gas Compressor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the compressor value chain. Integrated turbomachinery OEMs with captive casting and forging capabilities dominate large-scale project procurement. Three archetypes define competitive positioning: full-stream integrators bundling compression with digital services, component specialists focused on seal and valve technologies, and independent fleet operators prioritizing unit availability over brand specifications. Market consolidation proceeds through selective acquisition of aftermarket service networks and regional fabrication assets.
Within the full-stream integrator tier, Ingersoll Rand and Baker Hughes Company exemplify equipment-digital bundling strategies. Siemens Energy occupies a position bridging European utility-scale projects with hydrogen infrastructure development. Burckhardt Compression represents the Swiss specialist archetype, anchoring high-pressure reciprocating applications through focused engineering depth.
| Leading Market Players |
|---|
| Ingersoll Rand |
| Howden Group |
| Baker Hughes Company |
| Mitsubishi Heavy Industries |
| Burckhardt Compression |
| Siemens Energy |
| Ariel Corporation |
| General Electric |
| Atlas Copco |
| Others |
Value Network & Pricing Analysis
Electrification of compression trains is compressing margins on engine-driven units while concentrating procurement leverage among buyers with grid access. This technology transition simultaneously elevates motor control costs and fragments the supplier base for conventional gas-engine packages, reshaping how midstream operators negotiate long-term service agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with differentiation anchored in emissions certification grade and aftermarket service bundling. Premium tiers command positioning through EPA-compliant low-leakage seal packages and predictive maintenance subscriptions, while economy tiers compete on upfront capital cost for non-regulated basins. Cost compression in the standard tier is intensifying because independent fleet operators prioritize unit availability over brand specifications, eroding OEM service margins. Production firms exhibit highest price sensitivity due to capital constraints in marginal shale economics, whereas midstream operators with decades-long infrastructure horizons absorb premium positioning for reliability guarantees.
Supply Chain Analysis
Freight costs for oversized pressure vessel forgings from Japan, South Korea, and Germany elevate landed costs for North American fabricators by 15-25% relative to domestic sourcing. High-nickel steel forgings, precision-machined impellers, and hermetic seal assemblies draw from concentrated metallurgical suppliers in Osaka, Pohang, and Essen. Single-source vulnerability concentrates in specialized alloy mills capable of meeting FERC interstate pipeline safety specifications. Distribution runs through OEM-direct channels for large centrifugal trains and independent fleet operators for modular reciprocating packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA methane performance standards under the Clean Air Act create recurring equipment replacement demand regardless of commodity price cycles.
For Market Incumbents: Anchor positions in large-scale gas processing facilities by deepening backward integration into high-nickel steel forging supply. Independent aftermarket providers threaten OEM service revenues through unbundled component subscriptions; defend by certifying integrated emissions monitoring systems that third parties cannot replicate. Prioritize electrification-ready compressor architectures to capture midstream grid-connection projects displacing engine-driven alternatives.
For New Entrants and Emerging Players: Independent compression fleet operators represent the most penetrable channel partner type for modular skid-mounted packages. White-space exists in emissions verification services bundled with equipment procurement, and in electrification retrofit kits for brownfield engine-driven installations. Target the Permian Basin through rental fleet partnerships that bypass incumbent OEM distribution.
For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service networks because technician scarcity and retiring specialist populations prevent organic talent replication. The 5-10 year viability window favors platforms consolidating Permian Basin maintenance capabilities. Acquisition target archetype: independent compression fleet operators with established customer relationships and unbundled service contracts. Watch EPA enforcement intensity as the inflection signal for upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Program | Grid-connected compression trains open site configurations previously constrained by engine exhaust emissions under EPA rules. |
| Emissions Verification Partnership | Third-party certification services bundled with compressor procurement satisfy EPA New Source Performance Standards mandates. |
| Aftermarket Service Consolidation | Regional maintenance network acquisitions capture retiring technician populations and fragmenting service contracts. |
| Modular Fleet Expansion | Skid-mounted packages address stranded gas volumes in Texas and New Mexico ahead of pipeline infrastructure buildout. |
| Low-Leakage Seal Certification | Quantified emissions rate certification embeds premium positioning into supplier scorecards and offtake agreements. |
Research Methodology
Multiple input streams — executive interviews with midstream planning officers and production firm procurement leads, maintenance director surveys, and regulatory filing analysis — were reconciled against secondary validation. Primary fieldwork engaged compression fleet operators, aftermarket service heads, and OEM product managers across Texas, Louisiana, and New Mexico. Secondary sources included FERC interstate pipeline safety filings, EPA enforcement databases, and equipment procurement records from gas processing facility expansions. Bottom-up unit deployment estimates and top-down capital expenditure triangulation anchored volume and value outputs.
Data-stream reconciliation applied across product type, application, installation configuration, and end-user archetype dimensions throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadlines, and shale production growth trajectories. Industry-specific inputs incorporated associated gas-to-oil ratios in the Permian Basin, pipeline takeaway capacity constraints, and electrification adoption curves in Gulf Coast processing facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement variability, natural gas price volatility, and pipeline infrastructure completion schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Booster Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Rental Air Compressors Market
Compressors
Turbocompressor Market
Compressors
Rotary Air Compressor Market
Compressors
Centrifugal Air Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Reciprocating Air Compressor Market
Compressors
Gas Compressors Market
Compressors
Regenerative Blowers Market
Compressors
Portable Compressor Market
Compressors
North America Compressor Market
Compressors
Air and Gas Compressor Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Air Compressor Market