
 Chlorine Compressors Market | 2026-2036
Chlorine Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorine Compressors Market Intelligence
The end-use application base for chlorine compressors is broadening beyond traditional chemical manufacturing into specialized pharmaceutical and advanced water treatment segments. Sundyne leverages its expertise in high-speed centrifugal technology to serve demanding applications. Gardner Denver Nash LLC sustains its market position through a focus on liquid ring compressor designs, which are valued for their reliability. Meanwhile, Mayekawa Mfg. Co., Ltd. competes by offering customized solutions for specific industrial gas processes.
A chlorine compressor is a specialized gas handling machine designed to safely increase the pressure of dry chlorine gas. These units must feature corrosion-resistant materials like nickel alloys and employ specific sealing technologies to prevent hazardous leaks, primarily serving to transport or liquefy chlorine for industrial processes. Within product types, centrifugal compressors are gaining share in large-scale chemical plants, while reciprocating types remain dominant in smaller, intermittent-duty applications. The chemical manufacturing end-user segment constitutes the largest share, though the water treatment segment represents the fastest-growing application area.
Safety and operational standards are dictated by regulations like the US EPA's Risk Management Program rule for facilities handling hazardous substances. In parallel, compliance with Europe's Pressure Equipment Directive (PED) and adherence to ISO 9001 quality management standards are critical for market access in many regions. Stakeholders must now decide whether to invest in developing oil-free magnetic bearing technologies or focus on enhancing the efficiency of mature lubricated designs.
Market Dynamics
The chlorine compressor market is defined by a fundamental tension between robust demand from essential sectors like water treatment and chemical manufacturing, and the stringent safety protocols required for handling a highly corrosive and hazardous gas.
Growth Catalysts
- Wastewater Regulation:Stricter effluent discharge standards in Europe, particularly for industrial wastewater, compel investment in advanced purification systems that rely on chlorine, boosting compressor demand.
- Infrastructure Expansion:Rapid industrialization in Asia fuels the construction of new chemical plants and municipal water treatment facilities, particularly in nations like India and Vietnam.
- Process Optimization:The adoption of high-capacity centrifugal compressors in large-scale polyvinyl chloride (PVC) production facilities improves efficiency and throughput, justifying new equipment purchases.
Market Restraints
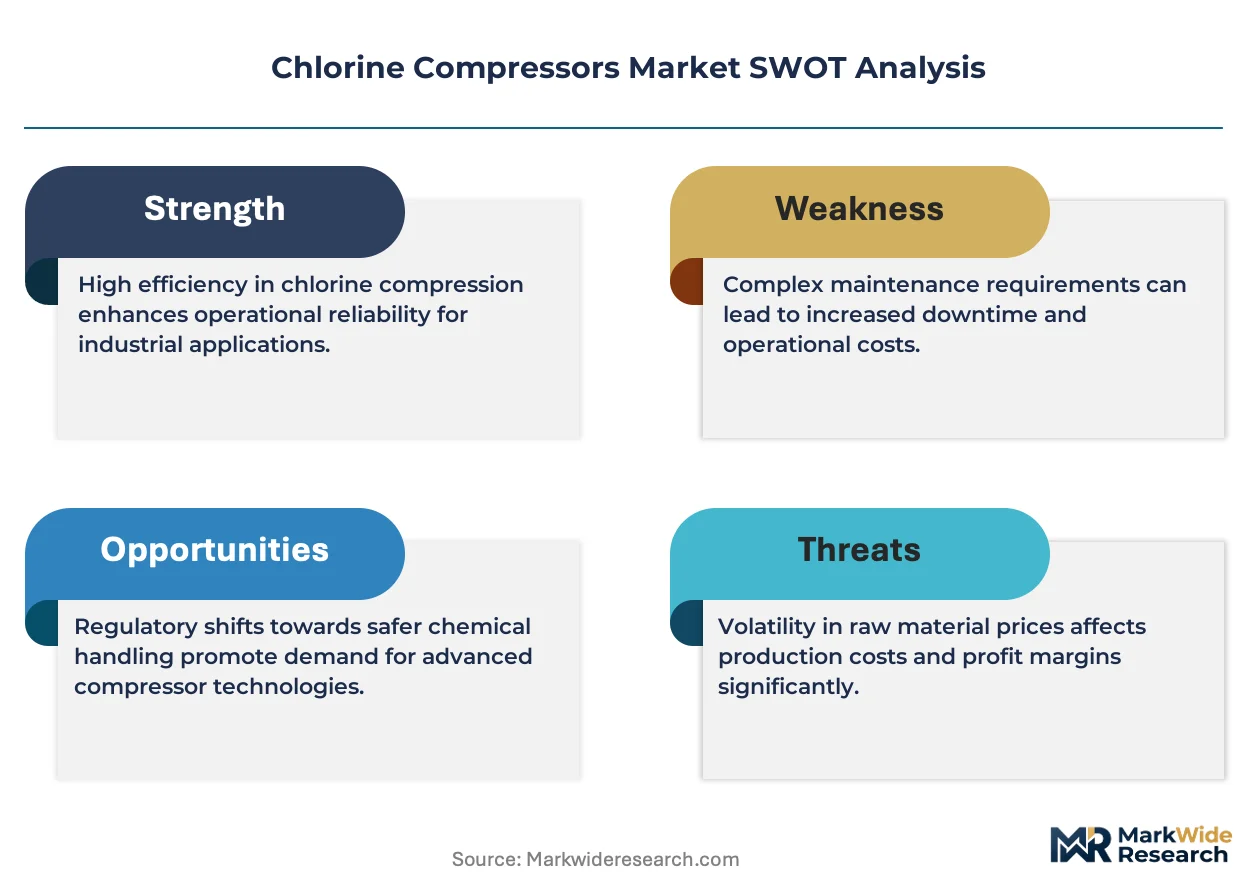
- High Capital Cost:The mandatory use of expensive, corrosion-resistant materials such as nickel alloys and specific sealing technologies significantly increases the initial purchase price of chlorine compressors.
- Substitution Threat:Alternative water disinfection technologies, including ultraviolet (UV) treatment and ozonation, present viable, chlorine-free options for some new water treatment plant constructions.
- Technical Complexity:The intricate design and maintenance requirements for these machines limit the number of qualified manufacturers and service providers, creating potential supply-side constraints.
Strategic Opportunities
- Pharmaceutical Applications:A niche exists for smaller, high-purity compressors in specialized pharmaceutical synthesis processes where chlorine is used as a reagent, representing an untapped application segment.
- Technology Integration:Combining oil-free magnetic bearing technology with centrifugal compressor designs presents an opportunity to create premium products with lower maintenance and higher operational safety.
- Retrofit Market:Aging water treatment infrastructure in regions like Eastern Europe requires upgrades to meet modern safety and efficiency standards, creating a significant market for replacement compressors.
Industry Challenges
- Specialized Skills Shortage:A deficit of technicians and engineers trained in the maintenance and operation of high-pressure, hazardous gas compression systems poses an operational risk for end-users.
- Certification Hurdles:Securing compliance with multiple international standards, such as Europe's Pressure Equipment Directive (PED) and ISO 9001, is a time-consuming and costly barrier to market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorine Compressors Market |
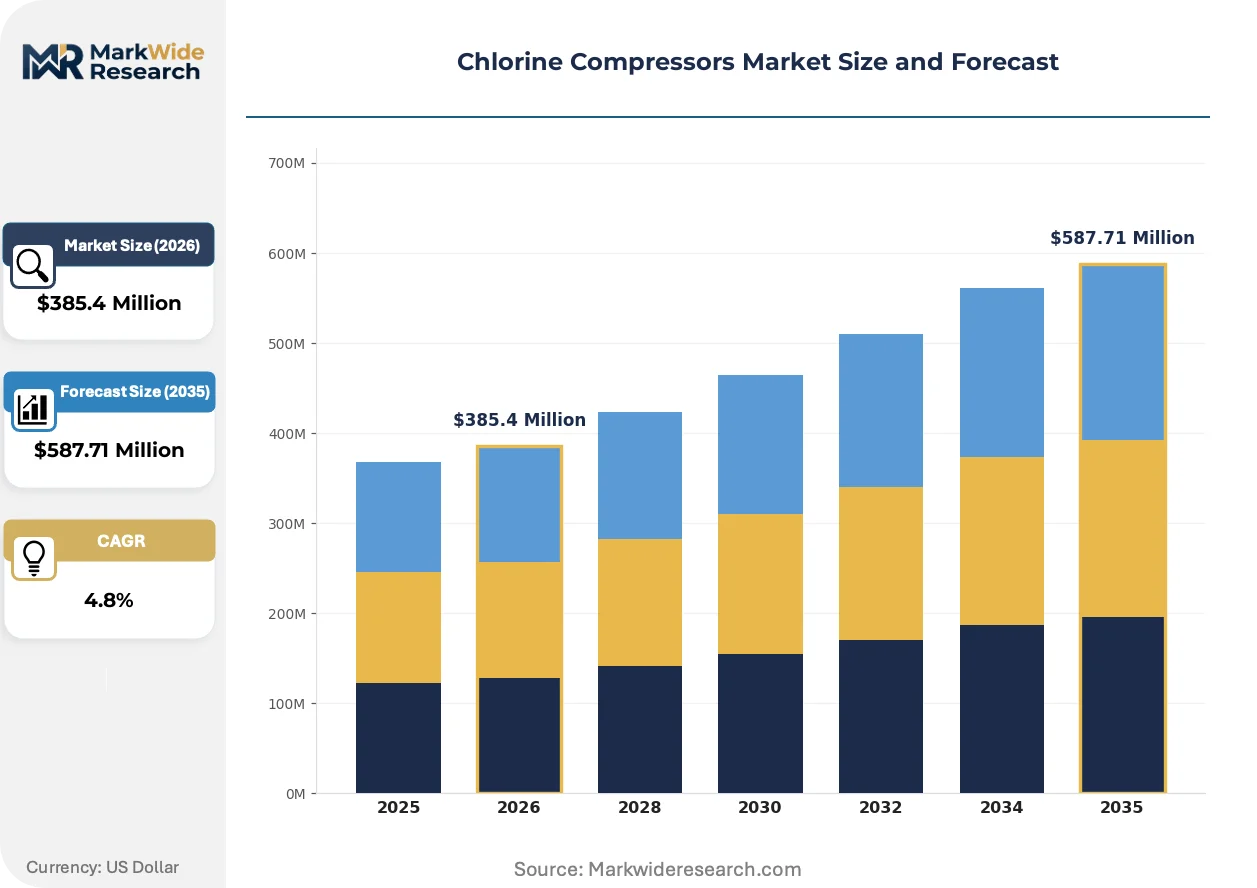
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Reciprocating, Screw, Centrifugal End User: Chemical Manufacturing, Water Treatment, Pharmaceuticals, Pulp & Paper Technology: Oil-Free, Lubricated, Magnetic Bearing, Direct Drive Installation: Stationary, Mobile, Skid-Mounted, Package |
| Companies Covered | Devi Hitech Engineers Pvt. Ltd., Sundyne, Gardner Denver Nash LLC, Elliott Group, RefTec International Systems LLC, Mayekawa Mfg. Co., Ltd., Mikuni Kikai Kogyo Co., Ltd., Charam Techno Chemical & Equipment Ltd., M. H. Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorine Compressors Market Strategic Shifts & Innovations
The evolution of chlorine compressors is guided by a dual focus on enhancing operational safety and improving total cost of ownership. Innovations center on material science, bearing technology, and integrated system monitoring to meet stricter regulatory demands and end-user efficiency targets.
Oil-free magnetic bearing technology provides a non-contact support system for the compressor's rotating assembly, eliminating the need for traditional lubrication. Large-scale chemical plants and advanced water treatment facilities are adopting this technology to prevent process contamination and reduce maintenance downtime. This innovation is rewriting total cost of ownership calculations, shifting the purchasing decision from initial capital cost toward long-term operational reliability and safety.
Heightened regulatory scrutiny, exemplified by the US EPA's Risk Management Program (RMP) rule, imposes strict requirements on facilities handling hazardous substances like chlorine. This directly influences compressor design, mandating features like advanced leak detection, automated shutdown systems, and robust material traceability. Chemical manufacturers in the United States are consequently upgrading their fleets to ensure compliance, favoring systems that offer superior containment and process monitoring capabilities.
A shift from purchasing standalone components to procuring fully integrated gas handling skids is altering procurement patterns. This trend challenges traditional component suppliers while benefiting system integrators who can deliver a pre-assembled, tested, and certified package including the compressor, motor, and controls. This model is particularly prevalent in new infrastructure projects in Southeast Asia, where accelerated project timelines in industrial zones in Vietnam and Thailand favor turnkey solutions.
Chlorine Compressors Market Segmentation
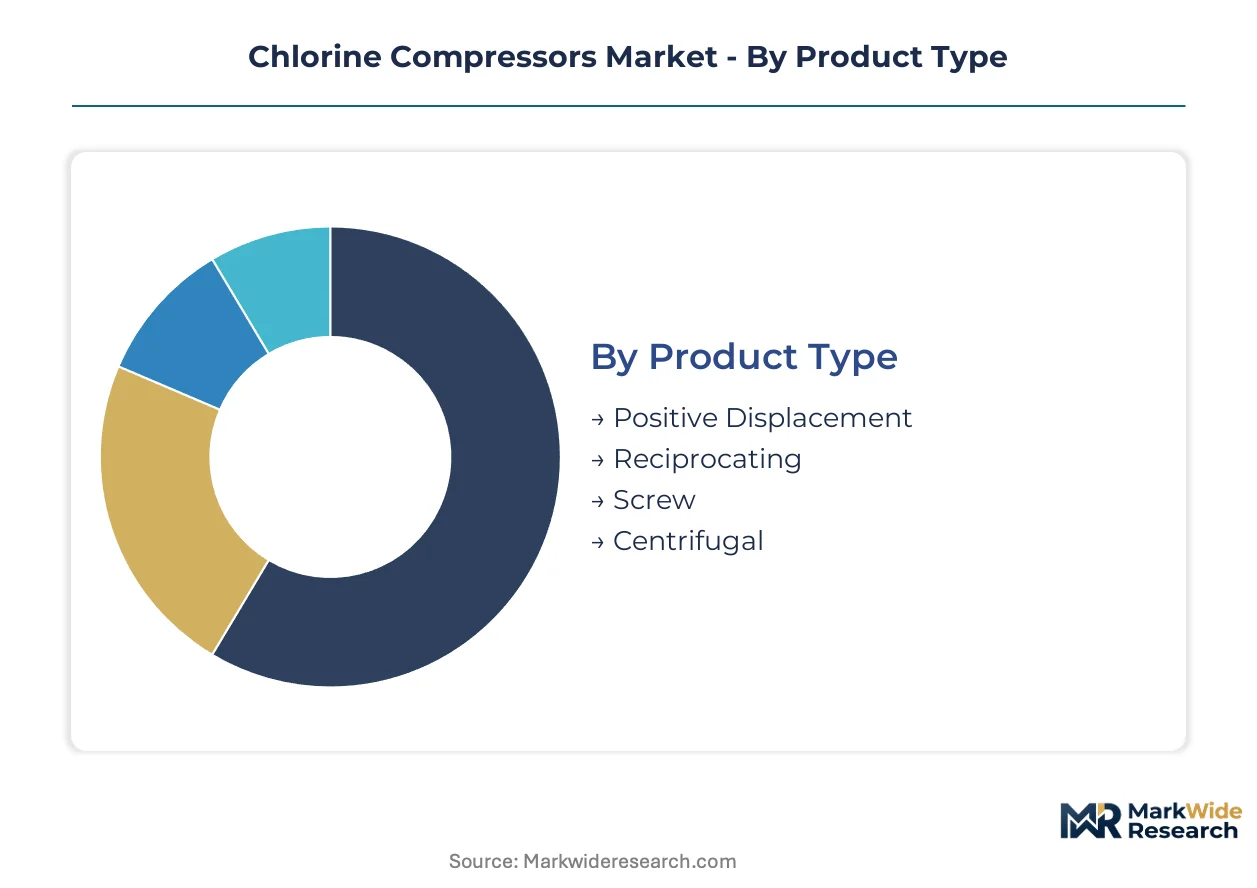
Market segmentation for chlorine compressors highlights the diverse operational demands and regulatory landscapes influencing purchasing decisions. End-user requirements for safety, efficiency, and specific gas handling capabilities drive the differentiation across product types and technologies. Understanding these distinct segments allows manufacturers to tailor solutions for optimal performance in hazardous environments.
Product Type:
Buyers often prioritize specific compressor designs based on operational scale, gas flow requirements, and desired pressure ratios.
- Reciprocating:These piston-driven, positive displacement compressors are well-suited for intermittent duty cycles and applications requiring precise pressure control. Smaller industrial facilities and specific chemical processes frequently utilize reciprocating units due to their robust performance.
- Centrifugal:Dynamic, high-speed compressors designed for continuous, high-volume gas flow, centrifugal units are non-positive displacement machines. Large-scale chemical plants, particularly in polyvinyl chloride (PVC) production, adopt centrifugal compressors for their superior efficiency and throughput.
- Positive Displacement:This broad category encompasses designs that trap and reduce gas volume, suitable for applications requiring consistent flow rates and high-pressure differentials.
- Screw:Utilizing rotating helical screws to compress gas, screw compressors offer continuous flow and are often employed in medium-scale industrial applications requiring reliable operation.
Centrifugal compressors lead on momentum; reciprocating types maintain a significant installed base.
End User:
End-user segments dictate compressor specifications based on process criticality, regulatory compliance, and gas purity needs.
- Chemical Manufacturing:This segment represents the core application for chlorine compressors, used extensively for gas liquefaction, transport, and various synthesis reactions. Petrochemical operations and industrial gas producers demand high-volume, continuous operation for their critical processes.
- Water Treatment:Chlorine compressors are essential for municipal and industrial wastewater disinfection, ensuring compliance with environmental regulations and public health standards. Municipal utilities and industrial effluent treatment facilities require reliable systems for continuous purification.
- Pharmaceuticals:This niche segment requires high-purity chlorine for specialized synthesis processes, demanding stringent material and operational standards to prevent contamination.
- Pulp & Paper:The pulp and paper industry utilizes chlorine for bleaching processes, requiring robust compressors capable of handling corrosive environments and ensuring consistent gas delivery.
Chemical manufacturing dominates the market share; water treatment exhibits the steepest expansion trajectory.
Technology:
Technological choices significantly influence operational safety, maintenance costs, and process contamination risks.
- Magnetic Bearing:This advanced technology provides non-contact support for the compressor's rotating assembly, eliminating the need for lubrication and reducing maintenance. Advanced water treatment facilities and large chemical plants adopt magnetic bearing compressors for their reduced contamination risk and long-term reliability.
- Lubricated:Traditional compressor designs rely on oil-based lubrication systems for bearing and seal operation, representing a mature and widely adopted technology. Established industrial sites and cost-sensitive applications favor lubricated designs for their proven reliability and lower initial capital expenditure.
- Oil-Free:These compressors prevent process contamination by completely avoiding lubricant contact with the gas stream, crucial for sensitive applications like pharmaceutical synthesis.
- Direct Drive:This configuration connects the motor directly to the compressor shaft, reducing power losses and mechanical complexity compared to belt-driven systems.
Magnetic bearing technology offers superior long-term cost benefits; lubricated designs provide a lower entry barrier.
Installation:
Installation types are determined by facility layout, portability requirements, and integration complexity.
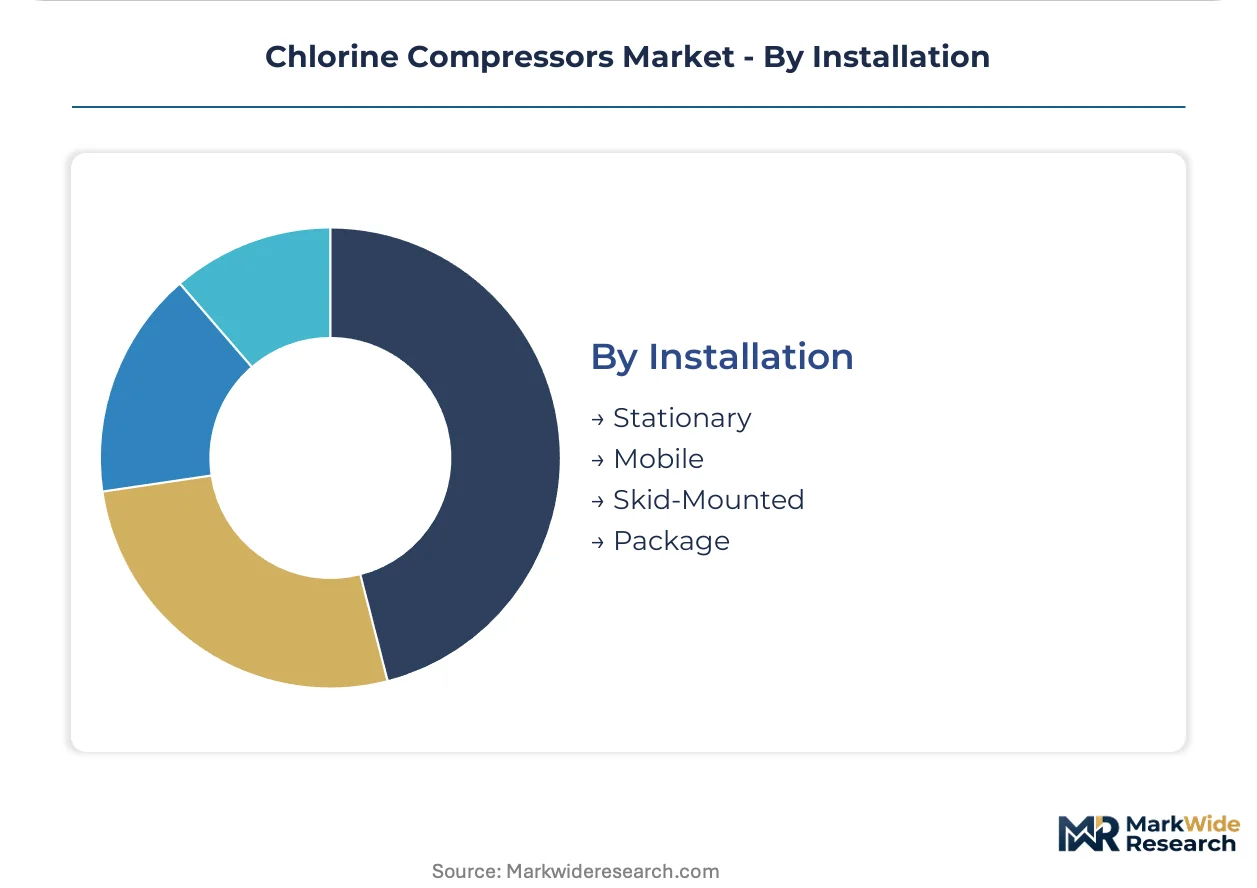
- Stationary:These compressors are fixed in place and permanently integrated into plant infrastructure, designed for long-term, high-capacity operation. Large chemical complexes and municipal water treatment plants typically employ stationary units for their continuous process needs.
- Skid-Mounted:Pre-assembled, tested, and integrated systems mounted on a common frame, skid-mounted units offer rapid deployment and turnkey solutions. New infrastructure projects in Southeast Asia, particularly those with accelerated timelines, favor these integrated packages.
- Mobile:Designed for temporary or flexible applications, mobile compressors allow relocation for varying operational needs or emergency response scenarios.
- Package:A complete system including the compressor, motor, and controls, often enclosed for protection and ease of deployment, simplifying procurement and installation.
Stationary installations represent the foundational deployment; skid-mounted units are gaining adoption for rapid project delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage significantly influences the global chlorine compressors market, as stringent environmental and safety standards in developed nations often drive manufacturing and certain chemical processes to regions with less restrictive oversight. This dynamic impacts where new compressor demand originates and where technological advancements are prioritized for compliance. Such shifts are particularly visible in the water treatment and chemical sectors.
India
India's rapid industrialization and urban development drive strong demand for chlorine compressors in municipal and industrial water treatment. The country's PLI scheme for chemicals promotes domestic manufacturing, increasing the need for robust gas handling systems. Major chemical and pharmaceutical clusters in Gujarat and Maharashtra are expanding, requiring advanced compressor solutions.
Vietnam
Vietnam's expanding manufacturing base and infrastructure projects, particularly in chemical and water treatment, necessitate new chlorine compressor installations. The Environmental Protection Law of Vietnam mandates improved wastewater quality, propelling investment in purification systems. Industrial zones near Ho Chi Minh City and Hanoi are experiencing significant growth in chemical production capacity.
United States
The United States market sees demand from upgrades to aging water infrastructure and strict compliance with hazardous substance regulations. The US EPA's Risk Management Program (RMP) rule compels facilities to enhance safety features in chlorine handling. Chemical manufacturing hubs along the Gulf Coast and in the Midwest are investing in modern, safer compressor technologies.
Germany
Germany's highly regulated industrial landscape and advanced chemical sector sustain a consistent demand for high-performance chlorine compressors. Compliance with Europe's Pressure Equipment Directive (PED) ensures a focus on safety and material integrity for all new installations. The Rhine-Ruhr region, a prominent chemical industry cluster, consistently requires specialized gas compression equipment.
China
China's massive chemical industry and ongoing urbanization projects fuel substantial demand for chlorine compressors, particularly for large-scale water treatment and industrial processes. The country's dual carbon goals and MEE regulations push for more efficient and environmentally compliant industrial equipment. Industrial clusters in the Yangtze River Delta and Pearl River Delta are continuously expanding their chemical production capabilities.
Chlorine Compressors Market Key Industry Players
Technology integration dominates the current landscape, with manufacturers focusing on advanced materials and bearing systems to meet stringent safety and efficiency standards. The market structure is characterized by a mix of established industrial equipment providers and specialized engineering firms. Key archetypes include high-speed centrifugal specialists, liquid ring compressor experts, and providers of customized gas handling solutions. Strategic partnerships for integrated skid-mounted systems and continuous innovation in oil-free technologies are prevalent competitive moves.
Specialists in advanced compressor technologies, such as Sundyne, represent firms leveraging expertise in high-speed centrifugal designs for demanding applications. Gardner Denver Nash LLC occupies a position among companies known for reliable liquid ring compressor designs, valued for their robust performance in corrosive environments. Mayekawa Mfg. Co., Ltd. sits within the segment offering customized solutions tailored for specific industrial gas processes, emphasizing bespoke engineering for complex client needs.
| Leading Market Players |
|---|
| Devi Hitech Engineers Pvt. Ltd. |
| Sundyne |
| Gardner Denver Nash LLC |
| Elliott Group |
| RefTec International Systems LLC |
| Mayekawa Mfg. Co., Ltd. |
| Mikuni Kikai Kogyo Co., Ltd. |
| Charam Techno Chemical & Equipment Ltd. |
| M. H. Industries |
| Others |
Cost & Logistics Intelligence
Large chemical manufacturers and municipal water treatment facilities often drive a project-based pricing model for chlorine compressors, reflecting the bespoke engineering and installation requirements of each application. The procurement of these specialized units frequently involves long-term contracts, balancing initial capital outlay with ongoing operational reliability and safety mandates.
Pricing Analysis
Direct-to-customer discounts are common, particularly for large-volume orders or integrated skid-mounted solutions where manufacturers engage directly with end-users or system integrators. Pricing stratifies across premium, standard, and economy tiers based on factors like corrosion-resistant material selection and adherence to certifications such as Europe's Pressure Equipment Directive (PED). Pricing pressure stems from the high capital cost of specialized materials, though the long-term operational savings of advanced technologies like magnetic bearings support premium pricing. Smaller industrial facilities requiring intermittent-duty reciprocating compressors demonstrate higher price sensitivity compared to large chemical plants prioritizing continuous operation and safety.
Supply Chain Analysis
Regional distribution centers facilitate the delivery of chlorine compressors and their specialized components to industrial zones globally. The supply chain relies heavily on key manufacturing hubs in the United States, Germany, and Japan, where advanced engineering capabilities reside. Raw material dependencies include nickel alloys for corrosion resistance and specialized sealing technologies critical for hazardous gas containment. Single-source vulnerability for these highly specialized components poses a structural risk, potentially impacting lead times and costs. Downstream, the distribution model often involves direct sales teams and a network of specialized engineering firms capable of providing installation and long-term maintenance support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chlorine compressors market functions as a regulatory compounder, with the US EPA's Risk Management Program rule driving significant demand for safer, more advanced equipment upgrades.
For Market Incumbents: Extend expertise in oil-free magnetic bearing technology to new applications, particularly in advanced water treatment and pharmaceutical synthesis, to counter substitution threats from alternative disinfection methods. Pursue strategic partnerships with system integrators to offer fully integrated skid-mounted solutions, addressing the demand for turnkey projects in rapidly industrializing regions. Invest in continuous R&D for material science advancements and enhanced sealing technologies to maintain a competitive edge against emerging entrants.
For New Entrants and Emerging Players: Capture niche opportunities in specialized pharmaceutical synthesis processes requiring high-purity chlorine compressors, leveraging smaller-scale, high-precision designs. Target the retrofit market in Eastern Europe, where aging water treatment infrastructure needs upgrades to meet modern safety and efficiency standards. A focused go-to-market angle involves offering customized solutions for specific industrial gas processes, emphasizing bespoke engineering and rapid deployment for smaller, specialized applications.
For Investors and Strategic Acquirers: Specialized industrial equipment providers are the most active acquirers in this space, seeking to consolidate technology and market share. The long-term viability of the market remains strong, anchored by essential infrastructure sectors like water treatment and chemical manufacturing. Acquisition target archetypes include specialized engineering firms with proprietary sealing technologies or unique expertise in oil-free magnetic bearing systems. The adoption rate of integrated gas handling skids in new infrastructure projects serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Integration (Magnetic Bearings) | Enhances operational safety and reduces maintenance, lowering total cost of ownership for end-users. |
| Green Manufacturing Transition | Improves energy efficiency and reduces environmental impact, aligning with global sustainability mandates. |
| Long-term Supply Agreement (Nickel Alloys) | Secures critical corrosion-resistant materials, mitigating supply chain risks and ensuring production continuity. |
| Certification Investment (PED, ISO 9001) | Ensures market access and demonstrates adherence to stringent quality and safety standards for critical applications. |
| Joint Venture (Skid-Mounted Solutions) | Accelerates market entry and project delivery in high-growth regions like Southeast Asia, meeting local demand for turnkey systems. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the market landscape. The analysis combines insights from in-depth interviews with industry stakeholders such as plant managers, procurement leads, R&D directors, and regulatory compliance officers, validated against extensive secondary research. Secondary data sources include EPA reports, European Commission directives, national industrial statistics, and company annual reports. This approach ensures robust bottom-up and top-down triangulation of market data.
The rate-of-change decomposition framework was applied to project market dynamics across the analysis window, modeling key segmentation dimensions. Segmentation modeled included product type, end-user, technology, and installation, alongside regional regulatory frameworks. Compound annual growth rates were derived from historical trends, projected industrialization rates in Asia, and forecasted water treatment infrastructure spending. This comprehensive framework offers a detailed understanding of market evolution.
Underlying measurement precision varies by segment; chemical manufacturing and water treatment carry tighter precision than others due to established infrastructure. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption. Geopolitical shifts affecting material supply or rapid adoption of alternative disinfection technologies could revise these projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Portable Air Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Europe Compressor Market
Compressors
Turbocompressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Automotive Compressors Market
Compressors
Rotary Air Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Stationary Air Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Scroll Compressor Market
Compressors
Air and Gas Compressor Market
Compressors
Hydrogen Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Tandem Piston Compressors Market