
 North America Air Compressor Market | 2026-2036
North America Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Air Compressor Market Analysis
Buyer concentration among large manufacturing groups is rebalancing toward mid-sized food processing and specialty chemical operators seeking distributed compressed air systems. Atlas Copco leverages its rotary screw technology leadership to anchor premium positions across automated packaging lines. Ingersoll Rand sustains broad channel control through integrated service contracts that lock in replacement part revenue streams. Kaeser Kompressoren differentiates via energy recovery systems that appeal to facilities pursuing LEED certification pathways.
An air compressor is a mechanical device that converts power into potential energy stored in pressurized air, typically achieving discharge pressures from 100 to 175 psi in industrial rotary screw configurations, and serves as the central pneumatic utility for automation, material handling, and process control across manufacturing environments. Rotary screw compressors occupy the dominant margin pool in North America due to continuous-duty reliability demands from automotive and food processing end users. Reciprocating units retain structural importance in intermittent-duty construction and small-shop applications where capital constraints limit scroll or centrifugal adoption. The portable installation segment competes intensely among rental fleets serving oilfield and infrastructure projects across Texas and Alberta.
EPA Clean Air Act enforcement shapes compressor emissions compliance through National Emission Standards for Hazardous Air Pollutants affecting oil-flooded systems, while DOE minimum efficiency regulations under the Energy Policy and Conservation Act tighten allowable power consumption curves for new equipment placements. OSHA workplace noise exposure limits further constrain reciprocating compressor deployment in indoor manufacturing settings, tilting specification toward enclosed rotary designs. Stakeholders must monitor how impending refrigerant phase-down rules and state-level decarbonization mandates reshape lifecycle cost calculations for compressed air infrastructure investments.
Market Dynamics
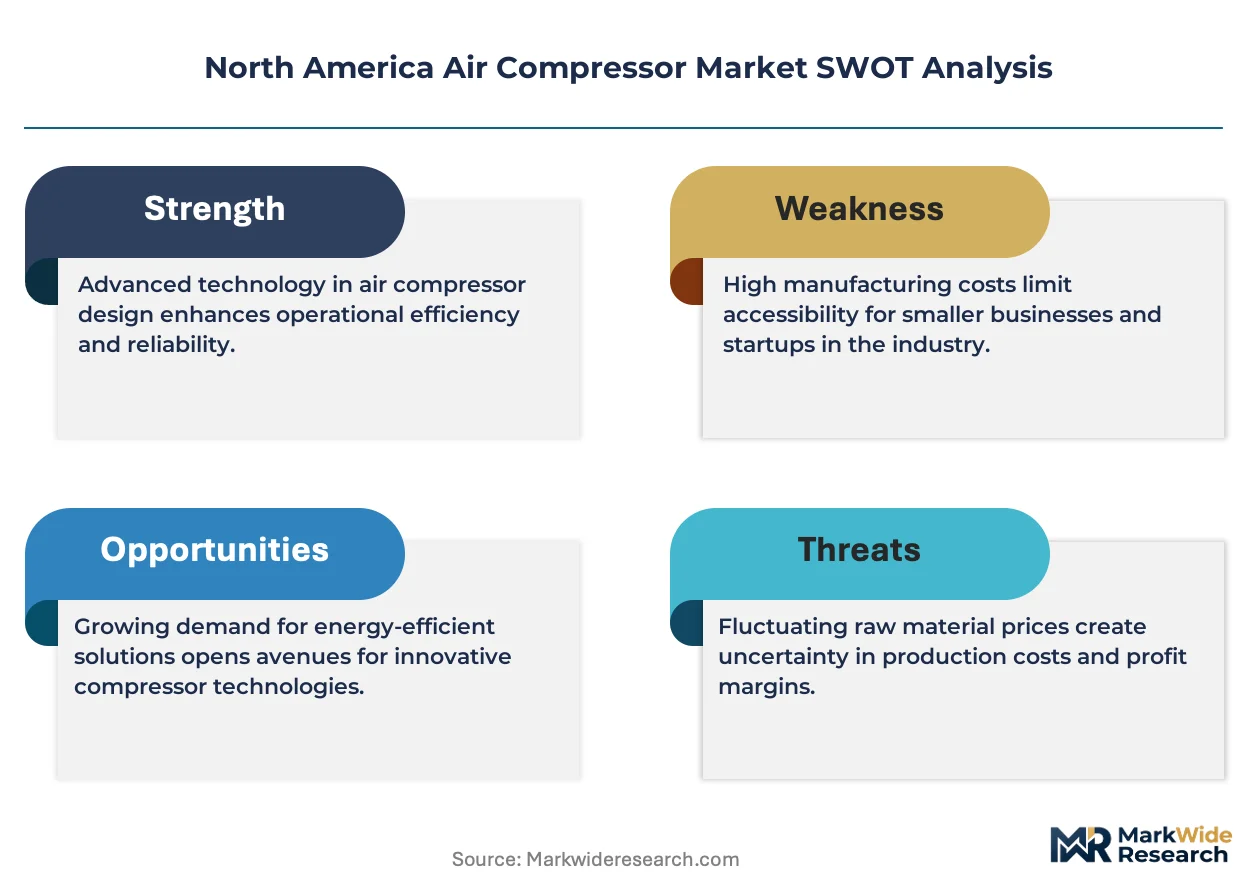
DOE efficiency mandates under the Energy Policy and Conservation Act are compressing allowable power consumption curves for new rotary screw placements, forcing manufacturers to redesign compression stages and thermal management systems ahead of 2027 compliance deadlines.
Growth Catalysts
- Food Processing Automation:USDA-inspected facilities across the U.S. Great Lakes corridor are expanding pneumatic packaging lines, requiring continuous-duty compressed air systems that rotary screw configurations deliver.
- LEED Certification Pathways:Energy recovery systems are capturing waste heat for facility HVAC integration, appealing to specialty chemical operators pursuing green building credentials.
- EPA NESHAP Compliance:Oil-flooded system operators are replacing aging equipment to meet National Emission Standards for Hazardous Air Pollutants, accelerating replacement cycles in automotive metalworking clusters.
Market Restraints
- Steel and Aluminum Input Volatility:Cast iron airend housings and aluminum heat exchangers face commodity price swings that compress OEM margin structures on mid-range equipment.
- Reciprocating System Obsolescence:OSHA workplace noise exposure limits constrain piston compressor deployment in indoor manufacturing settings, eliminating a low-capital entry path for small-shop buyers.
- Scroll Compressor Substitution:Oil-free scroll systems are capturing medical and electronics assembly applications where air purity requirements exceed rotary screw capabilities.
Strategic Opportunities
- Alberta Oilfield Rental Fleets:Portable diesel-driven compressors serving hydraulic fracturing and pipeline construction face upgrade demand as provincial emissions rules tighten.
- State Decarbonization Mandates:California and New York building performance standards are creating specification pull for variable-speed drive systems with embedded energy monitoring.
- Predictive Maintenance Convergence:IoT vibration sensors and edge analytics are unifying with compressor control systems to enable condition-based service scheduling.
Industry Challenges
- Compressed Air System Auditing Expertise:Facilities lack in-house capability to map demand profiles and identify artificial demand from leaks, slowing efficiency upgrade justification.
- Refrigerant Phase-Down Integration:EPA rules on hydrofluorocarbon reduction are forcing redesign of compressed air dryer cooling circuits, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Air Compressor Market |
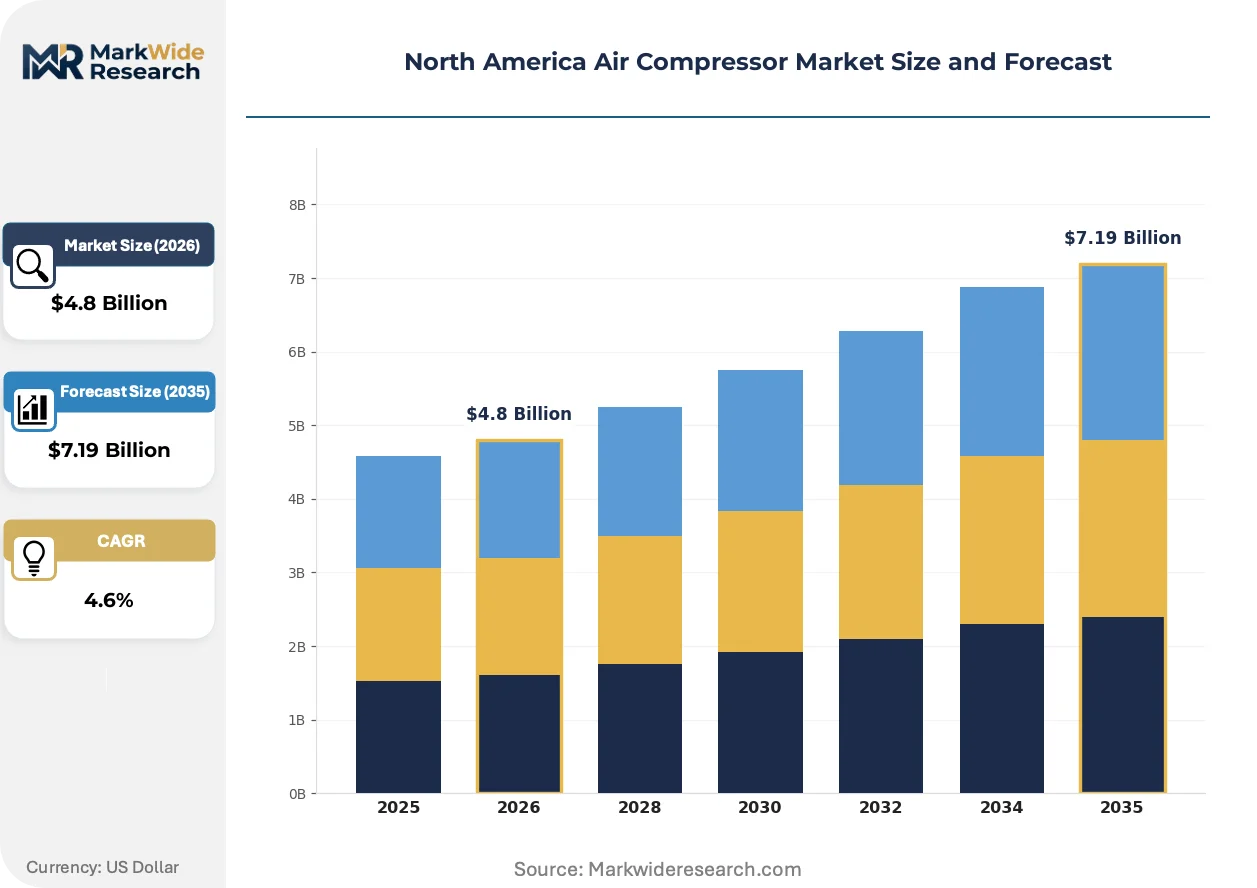
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Screw, Reciprocating, Scroll, Centrifugal End User: Manufacturing, Construction, Automotive, Food & Beverage Installation: Portable, Stationary, Compact, Heavy-Duty Power Rating: Below 10 HP, 10-25 HP, 25-50 HP, Above 50 HP |
| Companies Covered | Sullair, FS-Curtis, Atlas Copco, Chicago Pneumatic, Kaeser Kompressoren, Ingersoll Rand, Quincy Compressor, Doosan Portable Power, Gardner Denver, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Air Compressor Market Emerging Trajectories
Permanent magnet motor technology and integrated variable frequency drives are collapsing the efficiency gap between fixed-speed and modulating compressor architectures, reshaping how facilities size and stage compressed air capacity.
Variable-speed drive rotary screw systems are unifying compression and motor control into single-envelope designs that eliminate mechanical unloading losses. Food processing operators in Wisconsin and Michigan are specifying these configurations for packaging automation lines running 6,000+ annual hours. The technology is unifying what were separate capital decisions for compressor and demand-side storage into integrated system procurements.
EPA Clean Air Act enforcement through NESHAP Subpart ZZZZ is compelling oil-flooded compressor operators to retrofit or replace equipment exceeding benzene and formaldehyde emission thresholds. Metalworking job shops in Ohio and Indiana face the steepest compliance timelines, with many accelerating replacement schedules to avoid monitoring and reporting burdens.
Mid-sized manufacturing groups are consolidating compressed air procurement through integrated service contracts that bundle equipment, maintenance, and energy monitoring. Distributor channels serving the U.S. Southeast are restructuring compensation to emphasize lifecycle revenue over unit margins. The shift is most visible among automotive tier-one suppliers renegotiating multi-site agreements.
North America Air Compressor Market Segmentation
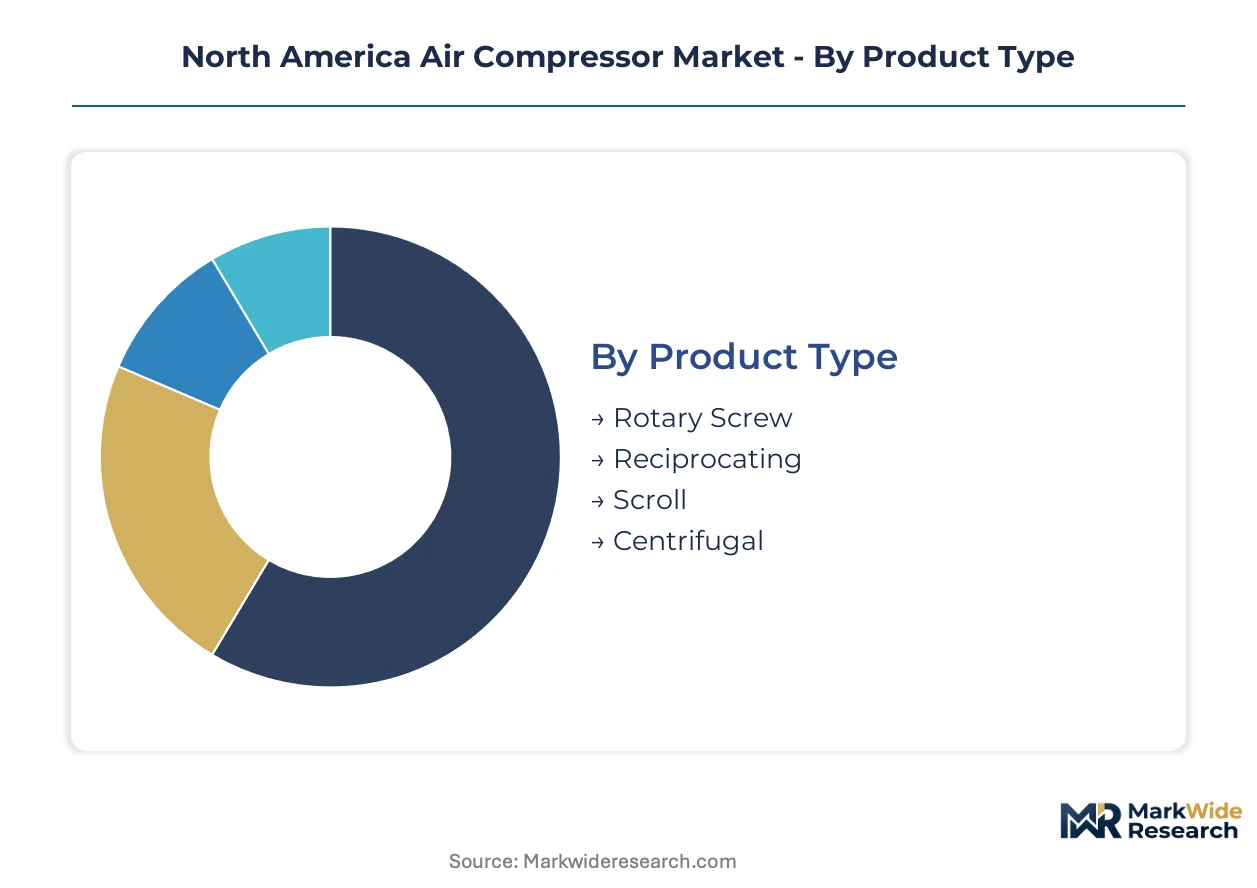
Air compressor segmentation in North America tracks how technology choices align with duty cycles, facility footprints, and regulatory compliance timelines. Distinct product architectures serve discrete pressure, flow, and purity requirements across manufacturing verticals.
Product Type:
Replacement cycles dominate purchasing decisions as EPA NESHAP deadlines and DOE efficiency mandates force equipment turnover across installed bases.
- Rotary Screw:Positive-displacement compression using intermeshing helical rotors delivers continuous-duty operation at 100-175 psi discharge pressures. Automotive stamping plants and food packaging lines across Michigan and Ohio specify these for 6,000+ annual operating hours under tightening OSHA noise limits.
- Reciprocating:Piston-driven intermittent-duty systems achieve higher pressure ratios in compact footprints. Small metalworking job shops in Indiana and Pennsylvania retain these where capital constraints outweigh efficiency penalties, though indoor deployment faces OSHA permissible exposure limit constraints.
- Scroll:Orbiting and fixed scroll elements provide oil-free compression for medical device and electronics assembly requiring ISO 8573-1 Class 0 air purity.
- Centrifugal:Dynamic compression using impeller arrays serves large-scale petrochemical and power generation facilities with 500+ HP demand profiles.
Rotary Screw sits at the top of the volume ranking, with Scroll climbing the fastest on air purity specification pull.
End User:
Facility automation intensity and pneumatic system criticality determine specification grade and service contract attachment rates.
- Manufacturing:General industrial fabrication and assembly operations constitute the foundational demand layer. Tier-one automotive suppliers across the U.S. Great Lakes corridor consolidate multi-site compressed air procurement through integrated service agreements.
- Construction:Mobile pneumatic tool power and shotcrete spraying drive portable diesel compressor deployment. Rental fleets serving Texas and Alberta oilfield infrastructure face provincial emissions upgrade cycles.
- Automotive:Stamping, painting, and final assembly lines require continuous-duty systems with embedded redundancy. EPA NESHAP compliance deadlines are accelerating replacement schedules at metalworking clusters in Ohio.
- Food & Beverage:USDA-inspected packaging and processing facilities specify oil-free or food-grade lubricated systems. Wisconsin dairy processing plants are expanding pneumatic automation lines under FSMA preventive controls requirements.
Manufacturing commands the largest installed base, while Food & Beverage demonstrates the steepest specification upgrade trajectory.
Installation:
Mobility requirements and facility permanence shape capital deployment patterns and aftermarket service logistics.
- Portable:Trailer-mounted or skid-mounted diesel or gasoline engines serve construction, mining, and emergency backup applications. Alberta hydraulic fracturing operators face provincial emissions rules tightening rental fleet upgrade timelines.
- Stationary:Fixed electric-motor systems anchor permanent manufacturing infrastructure. Great Lakes automotive plants specify these for centralized compressed air utilities with demand-side storage integration.
- Compact:Reduced-footprint rotary screw and scroll units fit constrained mechanical rooms in urban food processing facilities.
- Heavy-Duty:Reinforced airend housings and enhanced cooling systems withstand continuous operation in foundry and primary metal environments.
Stationary systems anchor revenue stability, with Portable gaining share fastest on infrastructure project cycles.
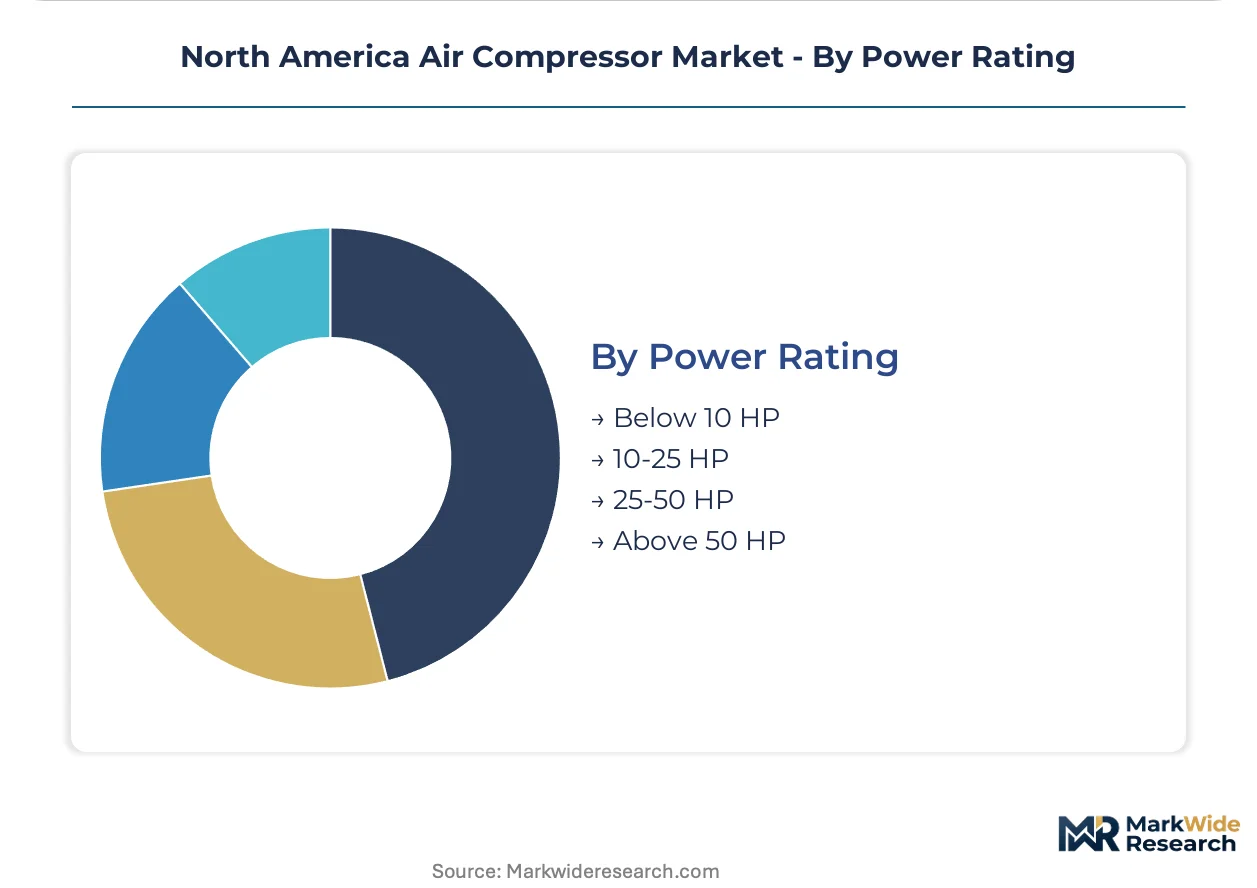
Power Rating:
Motor sizing decisions cascade through electrical infrastructure requirements, demand-side storage economics, and DOE efficiency compliance tiers.
- Below 10 HP:Single-phase electric or gasoline engines serve small machine shops and light assembly. OSHA workplace noise limits are constraining piston compressor deployment in these indoor settings.
- 10-25 HP:Three-phase rotary screw systems dominate mid-sized manufacturing and automotive tier-two supplier facilities. California Title 24 building efficiency standards are pulling variable-speed drive specification in this range.
- 25-50 HP:Continuous-duty industrial compressors with integrated dryers and receivers serve multi-line food processing plants. DOE minimum efficiency regulations are compressing allowable power consumption curves for new placements.
- Above 50 HP:Large-frame rotary screw and centrifugal systems anchor centralized plant air utilities. DOE compliance deadlines are forcing redesign of compression stages and thermal management systems ahead of 2027.
The 10-25 HP band holds the broadest unit volume, with Above 50 HP expanding most quickly on facility consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant installed base for industrial compressed air systems, while Canada concentrates portable rental fleet demand around Alberta energy infrastructure. Mexico's manufacturing expansion along the northern border states is pulling specification-grade compressor placements for automotive and electronics assembly.
United States
Automotive stamping plants and food packaging lines across Michigan and Ohio specify continuous-duty rotary screw systems for 6,000-plus annual operating hours. EPA NESHAP Subpart ZZZZ enforcement is compelling oil-flooded compressor operators in metalworking clusters to accelerate replacement schedules ahead of compliance deadlines. The Great Lakes manufacturing corridor sustains the heaviest concentration of demand-side storage integration and multi-site service contract consolidation.
Canada
USDA-inspected dairy processing facilities in Quebec and Ontario are expanding pneumatic automation lines under federal food safety modernization requirements. Provincial emissions rules in Alberta are tightening upgrade timelines for diesel-driven portable compressors serving hydraulic fracturing and pipeline construction. Toronto-area automotive tier-one suppliers are consolidating procurement through integrated agreements bundling equipment and predictive maintenance services.
Mexico
Maquiladora assembly plants in Nuevo León and Baja California are specifying oil-free scroll and rotary screw systems for electronics and medical device manufacturing. Mexican federal energy efficiency standards are beginning to align with DOE minimum performance regulations, reshaping import specification for U.S. and European OEMs. The Bajío automotive cluster around Guanajuato is attracting compressed air infrastructure investment from multinational suppliers serving export-oriented assembly lines.
North America Air Compressor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates premium positions among technology leaders while fragmenting mid-range supply through distributor networks. The vendor base organizes into three strategic archetypes: integrated industrial conglomerates with broad motion and fluid technology portfolios, dedicated compressor specialists emphasizing energy recovery and oil-free systems, and regional fabricators serving price-sensitive construction and small-shop segments. Dominant competitive moves include backward integration into airend manufacturing and service contract bundling that locks in replacement part revenue streams.
Among the integrated industrial tier, Atlas Copco exemplifies technology leadership anchored in rotary screw innovation, while Ingersoll Rand occupies a position defined by channel breadth and lifecycle service penetration. Kaeser Kompressoren represents the specialist archetype, with German engineering heritage informing energy recovery system development. These three companies collectively illustrate how competitive positioning stratifies across premium technology differentiation, integrated service scale, and regional application expertise.
| Leading Market Players |
|---|
| Sullair |
| FS-Curtis |
| Atlas Copco |
| Chicago Pneumatic |
| Kaeser Kompressoren |
| Ingersoll Rand |
| Quincy Compressor |
| Doosan Portable Power |
| Gardner Denver |
| Others |
Supply Flow & Price Mechanics
EPA Clean Air Act enforcement gates qualified supply and premium-tier pricing access by compelling oil-flooded compressor operators to retrofit or replace equipment ahead of NESHAP Subpart ZZZZ compliance deadlines. DOE efficiency mandates under the Energy Policy and Conservation Act further stratify pricing tiers by compressing allowable power consumption curves for new rotary screw placements.
Pricing Analysis
Capacity additions in the U.S. Great Lakes manufacturing corridor are reshaping price floors for mid-range rotary screw systems as OEMs compete for automotive and food processing contracts. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by DOE efficiency certification tier and integrated service bundling. Pricing pressure stems from steel and aluminum input volatility compressing margin structures on cast iron airend housings. Small metalworking job shops exhibit highest price sensitivity due to capital constraints, while tier-one automotive suppliers prioritize lifecycle cost over unit acquisition cost.
Supply Chain Analysis
Workforce availability constraints in Ohio, Michigan, and Wisconsin manufacturing clusters are tightening production schedules for rotary screw airend assemblies. Component manufacturing concentrates in the United States, Germany, and China, with final assembly anchored in North American facilities to serve regional demand. Raw material dependencies center on cast iron for housings, aluminum for heat exchangers, and rare earth elements for permanent magnet motors. Single-source vulnerability for precision-machined rotors from German suppliers creates bottleneck risk. Distribution runs through authorized dealer networks that bundle equipment with predictive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through permanent magnet motor adoption collapsing efficiency gaps and enabling premium-tier positioning. Energy recovery system integration creates additional value capture for facilities pursuing LEED certification pathways.
For Market Incumbents: Hedge against scroll compressor substitution in medical and electronics assembly by accelerating oil-free rotary screw development. Backward integration into airend manufacturing secures supply continuity amid precision-machining capacity constraints. Lock in replacement part revenue streams through multi-site integrated service contracts with automotive tier-one suppliers across the Great Lakes corridor.
For New Entrants and Emerging Players: Mid-sized food processing operators in the U.S. Southeast represent an underserved buyer archetype consolidating procurement through lifecycle service agreements. Alberta oilfield rental fleets face provincial emissions upgrade cycles for portable diesel compressors. Target distributed compressed air system demand with variable-speed drive configurations and embedded IoT monitoring as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for regional compressor distributors because multi-site service contract consolidation is accelerating among manufacturing groups seeking procurement efficiency. The five-to-ten year viability window favors acquisition of specialist firms with energy recovery system expertise and established LEED certification consulting relationships. Monitor California and New York state decarbonization mandate implementation timelines as inflection indicators for variable-speed drive specification pull.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Airend Manufacturing | Captive supply of precision-machined rotors reduces German single-source dependency for Ohio and Michigan assembly plants. |
| Energy Recovery System Development | Waste heat capture for HVAC integration appeals to Wisconsin dairy processors pursuing LEED certification pathways. |
| Predictive Maintenance Platform Launch | IoT vibration sensors unified with compressor controls enable condition-based service scheduling for Great Lakes automotive clusters. |
| Oil-Free Rotary Screw Expansion | ISO 8573-1 Class 0 air purity specification captures medical device and electronics assembly applications from scroll competitors. |
| Alberta Rental Fleet Emissions Upgrade | Provincial rules tightening diesel compressor standards create replacement demand for hydraulic fracturing and pipeline construction. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads with secondary validation. Secondary sources included DOE efficiency regulation filings, EPA NESHAP compliance databases, SEC 10-K disclosures from diversified industrial conglomerates, and customs trade data for compressor component imports. Bottom-up unit shipment modeling triangulated against top-down manufacturing value-added estimates.
Segment-weighting approaches applied differential growth assumptions across product type, end user, installation configuration, and power rating bands throughout the forecast period. Analytical frameworks incorporated duty cycle intensity, regulatory compliance timelines, and facility automation trajectories as industry-specific forecast inputs. CAGRs derived from installed base replacement cycles and greenfield capacity expansion patterns.
Underlying measurement precision varies by segment; rotary screw and stationary installation categories carry tighter precision than reciprocating and portable alternatives due to more transparent OEM reporting channels. Forecasts reflect documented assumptions regarding EPA enforcement intensity and state-level decarbonization mandate adoption. Material deviation in DOE efficiency regulation implementation timelines or steel and aluminum commodity price trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Chlorine Compressors Market
Compressors
Process Gas Compressors Market
Compressors
Centrifugal Compressors Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Rental Air Compressors Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Compressor Wheel Market
Compressors
Liquid Ring Compressors Market
Compressors
CNG Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Europe Compressor Market
Compressors
Axial Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Oil Filled Air Compressor Market