
 Porous Ceramic Market | 2026-2036
Porous Ceramic Market Size, Share, and Industry Trends Forecast 2026-2036
Porous Ceramic Market Intelligence
Japanese silicon carbide capacity is hardening as domestic producers scale specialty-grade output for semiconductor fabs. Morgan Advanced Materials leverages its fused-cast expertise to anchor European supply for molten-metal filtration. Kyocera Corp. dominates fine-pore zirconia architectures for biomedical implants. NGK Spark Plug Co., Ltd. specializes in honeycomb substrates that sustain automotive catalytic converter demand.
Porous ceramics are engineered materials with controlled pore sizes ranging from nanometers to millimeters, formed through sintering of oxides, carbides, or nitrides to create permeable structures for fluid separation, thermal management, or biological scaffolding. Foam ceramics lead filtration applications where open-cell structures handle aggressive chemical environments at elevated temperatures. Honeycomb ceramics concentrate margin pools in automotive catalytic support as emission standards tighten. Granular ceramics compete in fixed-bed reactor applications where tunable porosity determines catalytic efficiency.
EPA emission mandates and REACH substance restrictions in Europe shape product formulation and market access for catalytic-grade ceramics. Japan's METI guides domestic R&D priorities through industrial technology roadmaps for advanced materials. Stakeholders must monitor how evolving semiconductor fabrication standards in the United States and Asia redirect demand toward ultra-high-purity alumina substrates.
Market Dynamics
Semiconductor fabrication purity mandates are compressing supplier qualification timelines while concentrating procurement among certified alumina and silicon carbide substrate producers with established cleanroom supply chains.
Growth Catalysts
- EPA Tier 4 and Euro 7 emission standards:Honeycomb ceramic substrate demand from automotive OEMs is hardening as catalytic converter cell density requirements tighten.
- Japan's METI advanced materials roadmap:Domestic R&D funding for specialty-grade silicon carbide is accelerating capacity expansion for semiconductor fab filtration.
- Fixed-bed reactor optimization:Chemical processors are specifying tunable granular ceramics to maximize catalytic surface area in petrochemical and pharmaceutical synthesis.
Market Restraints
- High-purity alumina feedstock concentration:Bayer process alumina supply from Australian and Guinean bauxite regions creates input cost volatility for substrate manufacturers.
- Sintering energy intensity:Natural gas and electricity costs for continuous kiln operations compress margins at European ceramic producers facing ETS carbon pricing.
- Technical pore-size limitations:Sub-micron filtration applications remain constrained by grain boundary control challenges in oxide ceramics below 50 nanometer thresholds.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic catalytic ceramic demand is emerging as process industry localization accelerates fixed-bed reactor deployment.
- Additive manufacturing convergence:Binder jet printing of complex ceramic lattices is opening biomedical scaffolding applications previously inaccessible to conventional forming.
- REACH authorization timelines:Ceramic catalyst support substitution for zeolite and precious metal systems is creating specification windows as hazardous substance restrictions tighten.
Industry Challenges
- Cleanroom-qualified technician scarcity:Semiconductor-grade ceramic production requires specialized contamination control expertise that outpaces vocational training pipeline output.
- Multi-standard certification complexity:Simultaneous ISO 9001, IATF 16949, and semiconductor fab-specific audits extend customer qualification cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porous Ceramic Market |
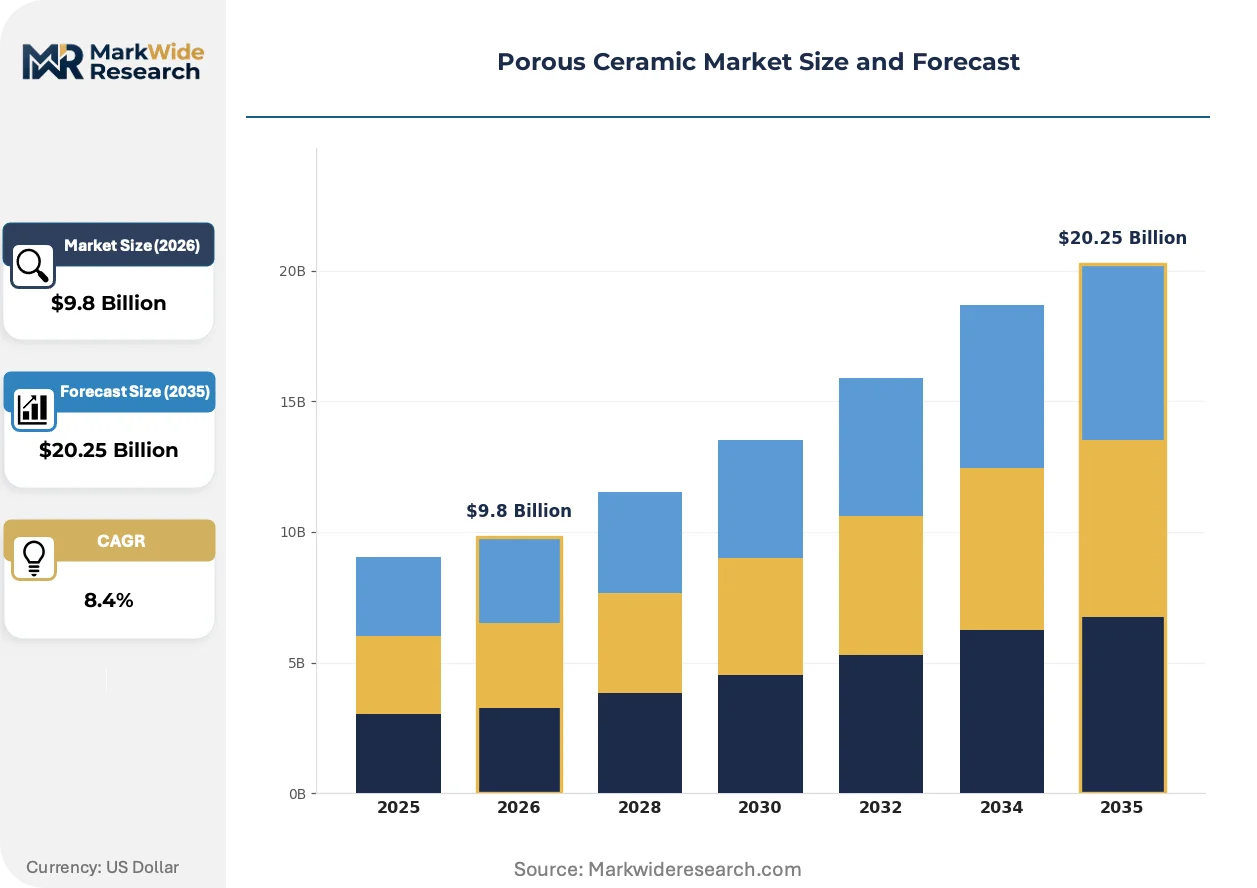
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Ceramics, Honeycomb Ceramics, Granular Ceramics, Filter Ceramics Application: Filtration, Heat Insulation, Catalytic Support, Biomedical End User: Aerospace, Automotive, Healthcare, Electronics Material: Silicon Carbide, Alumina, Zirconia, Others |
| Companies Covered | Morgan Advanced Materials, Nishimura Advanced Ceramics Co., Ltd., CoorsTek, Inc., Rauschert GmbH, Noritake Co. Limited, Innovacera, NGK Spark Plug Co., Ltd., Selee Corporation, Kyocera Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porous Ceramic Market Strategic Shifts & Innovations
Process intensification in chemical manufacturing and biomedical device miniaturization are redirecting ceramic engineering priorities toward precision pore architecture control and hybrid material systems.
Additive manufacturing of technical ceramics is consolidating design freedom for patient-specific biomedical implants and complex heat exchanger geometries. Orthopedic device manufacturers in Germany and Switzerland are adopting binder jet silicon nitride scaffolds with gradient porosity that matches bone ingrowth mechanics. This capability is compressing traditional isostatic pressing and machining supply chains for low-volume, high-complexity components.
REACH substance restriction expansions are forcing ceramic catalyst support producers to eliminate chromium and cobalt stabilizers from alumina formulations. ECHA's 2024 candidate list updates have triggered automotive exhaust system suppliers to accelerate qualification of rare-earth-doped alternatives. Japanese and Korean catalyst manufacturers are responding fastest due to earlier METI and K-environment ministry alignment with EU chemical policy trajectories.
Semiconductor fabs are unbundling filtration cartridge procurement from equipment OEM service contracts and establishing direct qualification programs with ceramic membrane suppliers. Taiwan Semiconductor Manufacturing and Samsung Foundry are leading this disintermediation to secure supply continuity for 3nm and 2nm process node ramp-ups. Direct sourcing is most advanced in Hsinchu and Pyeongtaek clusters where substrate purity documentation requirements exceed standard distributor capabilities.
Porous Ceramic Market Segmentation
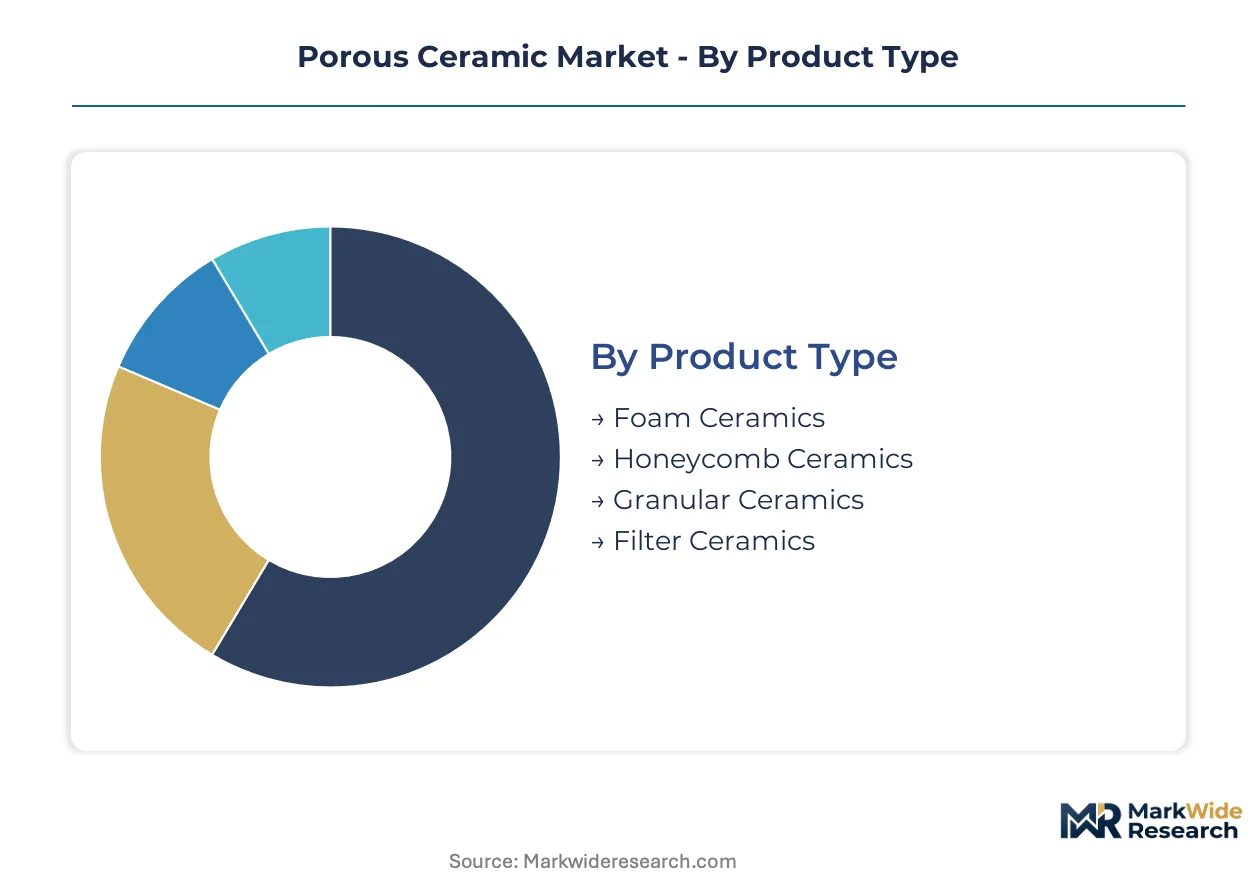
Porous ceramic engineering demands precise alignment between pore architecture and functional requirements. Segmentation reveals how material selection and forming method determine addressable end-use economics across semiconductor, automotive, and biomedical value chains.
Product Type:
Standardization dominates high-volume automotive substrates while foam and granular formats retain customization latitude for chemical process engineering.
- Foam Ceramics:Open-cell structures with interconnected porosity ranging from 10 to 100 pores per inch. Molten-metal filtration in German and Japanese foundries drives specification tightening for thermal shock resistance. REACH substance restrictions on chromium-based stabilizers are forcing alumina-foam reformulation toward rare-earth-doped alternatives.
- Honeycomb Ceramics:Extruded cellular architectures with channel densities from 100 to 900 cells per square inch. EPA Tier 4 and Euro 7 mandates concentrate procurement among automotive OEMs in Detroit, Stuttgart, and Toyota City. Cell geometry standardization limits supplier differentiation to thermal expansion coefficients and washcoat adhesion properties.
- Granular Ceramics:Sintered particulate beds with tunable interparticle void fractions. Fixed-bed reactor optimization in Indian petrochemical complexes under PLI scheme incentives is accelerating demand for particle size distribution precision.
- Filter Ceramics:Membrane and depth-filter configurations for liquid and gas separation. Semiconductor fabs in Hsinchu and Pyeongtaek are unbundling cartridge procurement from equipment OEM contracts to establish direct supplier qualification programs.
Most installed capacity flows through Honeycomb Ceramics. Expansion is steepest in Foam Ceramics.
Application:
Margin concentration shifts from emission control toward biomedical scaffolding as additive manufacturing matures.
- Filtration:Fluid separation across liquid and gas phases using membrane, depth, and surface filtration mechanisms. Semiconductor fabrication purity mandates in the United States and Taiwan are compressing supplier qualification timelines to 18-24 month cycles.
- Heat Insulation:Thermal barrier applications in aerospace propulsion and industrial furnace linings. Reusable launch vehicle programs in California and Texas specify lightweight ceramic tiles with gradient porosity for hypersonic re-entry protection.
- Catalytic Support:High-surface-area substrates for automotive exhaust and chemical process catalysts. ECHA candidate list updates are eliminating cobalt and chromium stabilizers from alumina formulations faster in Japanese and Korean supply chains due to earlier METI and K-environment ministry alignment.
- Biomedical:Orthopedic and dental implants exploiting osseointegration-friendly surface topographies. German and Swiss device manufacturers are adopting binder jet silicon nitride scaffolds with patient-specific gradient porosity that matches bone ingrowth mechanics.
Revenue concentration remains heaviest in Catalytic Support. Share gains are most pronounced in Biomedical.
End User:
Procurement sophistication varies sharply: automotive and electronics enforce certification-heavy supply chains while healthcare and aerospace tolerate longer development cycles.
- Aerospace:Thermal protection and lightweight structural applications. NASA and ESA programs specify ceramic matrix composites for propulsion components where pore architecture controls ablation rates.
- Automotive:Catalytic converters, diesel particulate filters, and exhaust system components. Detroit Three and German premium OEMs are consolidating substrate procurement among IATF 16949-certified suppliers with demonstrated Euro 7 compliance pathways.
- Healthcare:Implantable devices and diagnostic filtration. FDA and EMA biocompatibility requirements for permanent implants restrict zirconia sourcing to ISO 13485-certified producers with validated cleanroom operations.
- Electronics:Semiconductor wafer processing and cleanroom environments. Samsung Foundry and Taiwan Semiconductor Manufacturing are leading disintermediation of filtration cartridge procurement to secure supply continuity for 3nm and 2nm process node ramp-ups.
Volume leadership sits with Automotive. Value expansion is strongest in Electronics.
Material:
Supply security concerns are reshaping procurement priorities as bauxite concentration and energy costs destabilize alumina economics.
- Silicon Carbide:Covalent ceramic with exceptional thermal conductivity and chemical inertness. Japanese producers are scaling specialty-grade capacity for semiconductor fab filtration under METI advanced materials roadmap funding.
- Alumina:Cost-engineered oxide ceramic dominating catalytic and filtration applications. Bayer process feedstock dependence on Australian and Guinean bauxite regions creates input cost volatility that European producers face with additional ETS carbon pricing exposure.
- Zirconia:Transformation-toughened oxide with biomedical and high-wear applications. Kyocera Corp. dominates fine-pore architectures for dental and orthopedic implants where tetragonal phase stability determines clinical longevity.
- Others:Silicon nitride, cordierite, and emerging rare-earth-doped formulations. ECHA authorization timelines are accelerating ceramic catalyst support substitution for zeolite systems as hazardous substance restrictions tighten.
Production scale favors Alumina. Technology investment is concentrating in Silicon Carbide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting porous ceramic capacity toward jurisdictions with lower carbon compliance costs and concentrated feedstock access. Producers are optimizing location decisions around energy pricing, emission trading systems, and proximity to high-specification end-users.
United States
Semiconductor fabs in Hsinchu and Pyeongtaek are unbundling filtration cartridge procurement from equipment OEM contracts. EPA Tier 4 emission standards harden honeycomb substrate demand from Detroit automotive OEMs. Texas and California clusters concentrate molten-metal filtration capacity serving aerospace propulsion programs.
Germany
Automotive catalytic converter cell density requirements tighten procurement among Stuttgart premium OEMs. ETS carbon pricing compresses margins at European ceramic producers operating continuous kiln operations. Bavaria and North Rhine-Westphalia host precision ceramics clusters supplying IATF 16949-certified substrates.
Japan
METI advanced materials roadmap funding accelerates specialty-grade silicon carbide capacity expansion for semiconductor fab filtration. Domestic producers scale output for 3nm and 2nm process node ramp-ups. Nagoya and Kyushu industrial corridors concentrate fine-pore zirconia architecture production for biomedical applications.
China
Dual carbon goals reshape energy-intensive sintering operations toward renewable-powered kiln facilities. Domestic chemical processors specify tunable granular ceramics for fixed-bed reactor optimization. Yangtze River Delta and Pearl River Delta clusters serve process industry localization under national industrial policy.
India
PLI scheme incentives for specialty chemicals accelerate fixed-bed reactor deployment in petrochemical complexes. Domestic catalytic ceramic demand emerges as process industry localization deepens. Gujarat and Maharashtra industrial corridors concentrate emerging capacity for alumina and silicon carbide substrates.
Porous Ceramic Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing and patient-specific biomedical scaffolding. The vendor base stratifies across three tiers: integrated material-science conglomerates with fused-cast expertise, mid-scale specialists in honeycomb extrusion, and regional fabricators serving foundry filtration. Dominant competitive moves include backward integration into high-purity alumina feedstock and strategic partnerships with semiconductor fab equipment OEMs.
Within the integrated-materials tier, Morgan Advanced Materials and Kyocera Corp. exemplify archetypes with fused-cast and fine-pore architecture capabilities respectively. Among Japanese specialists, NGK Spark Plug Co., Ltd. occupies a position representing honeycomb substrate concentration for automotive emission control. These anchors illustrate how geographic clustering around regulatory stringency and end-user qualification requirements shapes competitive positioning.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Nishimura Advanced Ceramics Co., Ltd. |
| CoorsTek, Inc. |
| Rauschert GmbH |
| Noritake Co. Limited |
| Innovacera |
| NGK Spark Plug Co., Ltd. |
| Selee Corporation |
| Kyocera Corp. |
| Others |
Cost & Logistics Intelligence
Additive manufacturing convergence in biomedical scaffolding and semiconductor-grade filtration substrates is compressing traditional forming costs while concentrating procurement power among cleanroom-qualified producers with captive high-purity feedstock access.
Pricing Analysis
Distributor margins in ceramic membrane supply chains are compressing as semiconductor fabs in Hsinchu and Pyeongtaek unbundle cartridge procurement from equipment OEM service contracts. Pricing stratifies across premium, standard, and economy tiers based on ISO 14644 cleanroom certification grade and volume scale. Cost compression in standard-grade alumina substrates is intensifying because Australian and Guinean bauxite feedstock volatility feeds through Bayer process economics. Automotive OEMs in Stuttgart and Detroit exhibit lowest price sensitivity due to Euro 7 compliance mandates, while Indian petrochemical processors under PLI scheme incentives drive hardest bargaining on granular ceramic fixed-bed reactor media.
Supply Chain Analysis
Single-source vulnerability sits with Australian and Guinean bauxite regions for Bayer process alumina feedstock that European and Asian substrate manufacturers draw from. Japanese silicon carbide capacity and German precision ceramics clusters in Bavaria and North Rhine-Westphalia anchor specialty-grade supply for semiconductor and automotive OEMs. Supply chain risk centers on ETS carbon pricing exposure for continuous kiln operations at European producers. Distribution runs through IATF 16949-certified tiered supplier networks serving automotive catalytic converter programs, with direct qualification programs emerging for semiconductor fab filtration procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
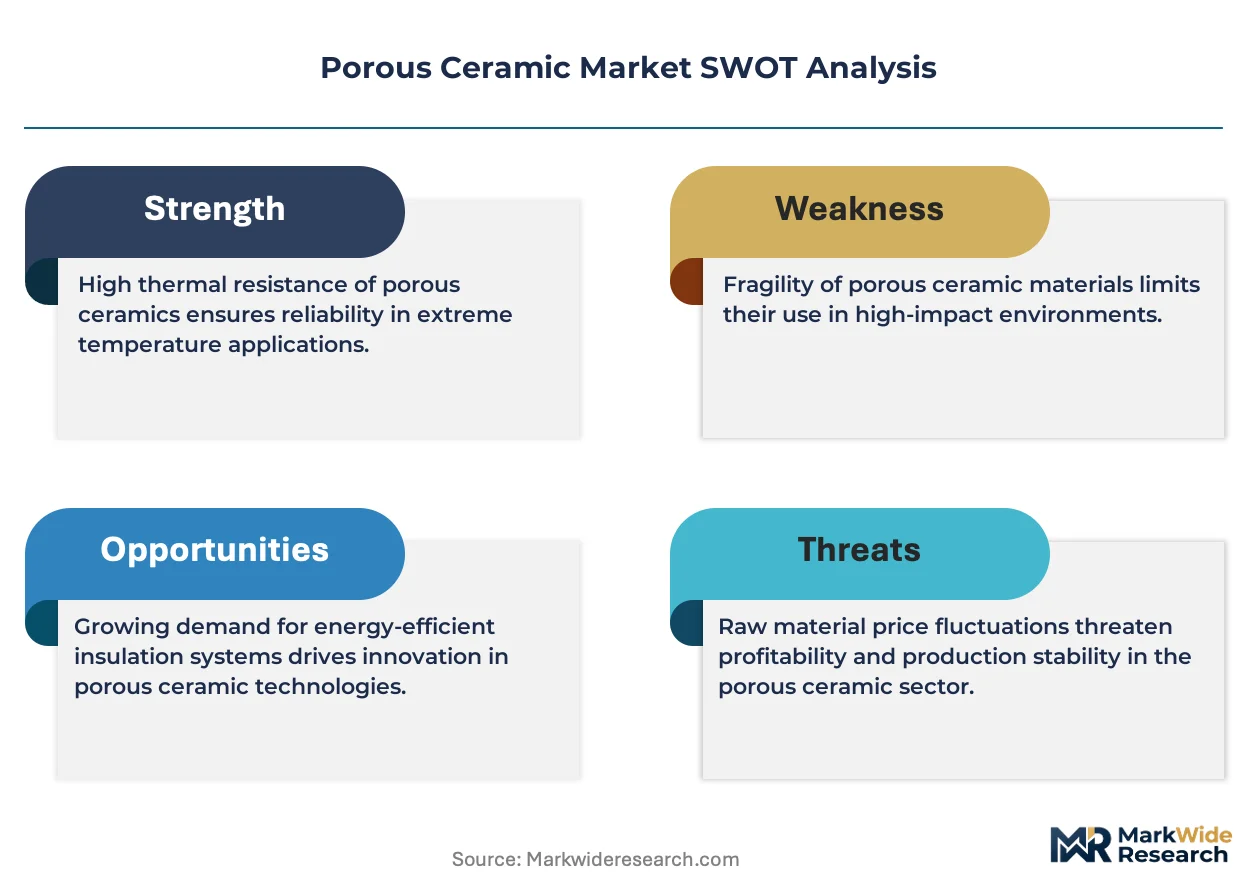
The porous ceramic market functions as a stable compounder where emission standard ratcheting and semiconductor node advancement generate sustained specification upgrades across automotive and electronics value chains.
For Market Incumbents: Deepen backward integration into high-purity alumina feedstock to offset Australian and Guinean bauxite concentration risk. Expand cleanroom-qualified technician training pipelines to outpace the scarcity that threatens semiconductor-grade production ramps. Prioritize METI and EPA pre-alignment on rare-earth-doped stabilizer formulations ahead of REACH authorization timelines. For New Entrants and Emerging Players: Binder jet printing of patient-specific silicon nitride scaffolds offers a technology-first wedge into German and Swiss orthopedic device supply chains where gradient porosity specifications exceed conventional forming capabilities. Target India's PLI scheme-supported petrochemical complexes for fixed-bed reactor granular ceramic qualification. Pursue direct semiconductor fab engagement in Pyeongtaek and Hsinchu clusters where disintermediation creates qualification windows outside established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional ceramic fabricators serving foundry filtration with undifferentiated foam geometries and limited certification depth. Five-to-ten year viability hinges on successful navigation of cleanroom infrastructure investment and multi-standard audit consolidation. Watch for inflection in semiconductor fab direct procurement program announcements as signal of supplier consolidation phase initiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Alumina | Captive Bayer process feedstock secures margin stability against Australian and Guinean supply volatility. |
| Cleanroom Infrastructure Certification | ISO 14644 and IATF 16949 qualification opens direct procurement channels with TSMC and Samsung Foundry. |
| Additive Manufacturing Scale-Up | Binder jet silicon nitride capacity captures German orthopedic OEM demand for gradient porosity implants. |
| Rare-Earth Stabilizer Formulation Pivot | ECHA REACH pre-compliance eliminates cobalt and chromium from automotive catalytic support ceramics. |
| India PLI Scheme Localization | Gujarat and Maharashtra production footprint captures fixed-bed reactor demand from domestic petrochemical expansion. |
Research Approach
Multiple input streams — technical ceramic plant managers, semiconductor fab procurement officers, automotive OEM substrate buyers, and biomedical device regulatory affairs leads — were reconciled against customs trade data, SEC filings from integrated material-science conglomerates, METI industrial technology roadmaps, and ECHA substance restriction updates. Primary fieldwork across German precision ceramics clusters, Japanese silicon carbide producers, and Indian PLI scheme beneficiaries was validated through bottom-up capacity modeling and top-down end-use demand estimation.
Data-stream reconciliation anchored volume and value projections across the analysis window through segmented modeling of material type, product format, application function, and end-user industry. Modeled dimensions included pore architecture specifications, cleanroom certification tiers, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted demand curves incorporating semiconductor fabrication node roadmaps and automotive emission standard phase-in schedules.
The model holds under sustained EPA Tier 4 and Euro 7 enforcement, Japanese METI funding continuity, and REACH substance restriction expansion; deviation in bauxite supply disruption, ETS carbon price spikes, or cleanroom technician training pipeline collapse would shift trajectory bands. Forecasts embed assumptions about additive manufacturing cost curves and rare-earth stabilizer qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Colloidal Alumina Market
Ceramics
China Ceramic Tiles Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Thermal Spray Powder Market
Ceramics
Cerium Carbonate Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Ceramic Ware Market
Ceramics
Zeolite 4A Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Ceramic Lining Market
Ceramics
Calcite Market
Ceramics
ME K-Feldspar Market