
 Cerium Carbonate Market | 2026-2036
Cerium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Cerium Carbonate Market Analysis
Long-term supply contracts with embedded technical service tiers is restructuring how cerium carbonate moves from refiners to downstream processors. Ganzhou Rare Earth Group Co., Ltd. leverages its integrated southern China mining-to-oxide pipeline to control feedstock quality for carbonate derivatives. Solvay SA anchors European demand through its specialized rare earth formulations for catalyst and glass applications. American Elements competes on custom synthesis capabilities, offering specification-tight cerium carbonate for research and industrial clients requiring non-standard purity grades.
Cerium carbonate is a hydrated salt of tetravalent cerium, typically formulated as Ce2(CO3)3 with variable hydration states, produced through precipitation from cerium chloride or nitrate solutions using alkali carbonate reagents; it serves primarily as a precursor for cerium oxide polishing compounds, automotive exhaust catalysts, and ceramic colorants. Light grade material dominates volume flows into glass polishing, where margin pools remain stable despite processing intensity, while ultrafine grade commands premium positioning in electronics applications requiring sub-micron particle consistency. Catalyst applications across automotive manufacturing represent the fastest-expanding demand vector as emission standards tighten across multiple jurisdictions.
China's SAMR enforces GB standards on rare earth product classification and environmental compliance, directly conditioning export volumes and pricing accessibility for international buyers. The EU REACH framework and RoHS directives constrain impurity thresholds in cerium carbonate destined for electronics and catalyst applications, filtering market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between China's dual carbon goals and European F-Gas Regulation extensions to anticipate which product grades and purity specifications will face supply constraints or preferential market access.
Market Dynamics
China's SAMR export licensing regime for rare earth carbonates is tightening feedstock access for non-domestic refiners, forcing downstream processors to restructure procurement around long-term offtake agreements with embedded technical service tiers rather than spot-market purchasing.
Growth Catalysts
- Automotive catalyst mandates:Euro 7 emission standards and China's Stage 6b regulations are expanding cerium-zirconium solid solution demand for three-way catalysts, pulling carbonate precursor volumes upward.
- GB standard alignment:China's updated rare earth product classification under SAMR supervision is standardizing purity benchmarks, reducing quality arbitrage and accelerating contract formalization.
- Inner Mongolia processing corridor:Baotou's integrated oxide-to-carbonate refining cluster concentrates technical expertise and environmental compliance infrastructure, lowering unit processing costs for export-grade material.
Market Restraints
- Lanthanum substitution in glass polishing:Lower-cost rare earth alternatives are capturing share in automotive windshield finishing applications where optical precision requirements permit grade relaxation.
- Feedstock concentration risk:Southern China's ionic clay deposits supply over 80% of global cerium-rich rare earth concentrates, creating single-source vulnerability for carbonate derivatives.
- REACH compliance cost escalation:ECHA registration requirements and RoHS impurity thresholds are elevating testing and documentation burdens for EU-bound shipments.
Strategic Opportunities
- India catalyst manufacturing:The country's PLI scheme for automotive components is attracting exhaust system integrators seeking localized rare earth supply chains outside China direct control.
- Solid oxide fuel cell electrolytes:Cerium-doped gadolinium oxide formulations for intermediate-temperature SOFCs represent an emerging demand vector with premium purity requirements.
- Direct refiner-to-processor platforms:Blockchain-traceable carbonate procurement is enabling specification-tight buyers to bypass traditional trader intermediaries and secure batch-level provenance documentation.
Industry Challenges
- Rare earth separation chemistry expertise:The specialized solvent extraction knowledge required for high-purity cerium isolation is concentrated among retiring technical cadres in China's state-owned refining complex.
- MEE environmental audit timelines:China's Ministry of Ecology and Environment compliance verification for carbonate production facilities is extending certification cycles and delaying capacity expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerium Carbonate Market |
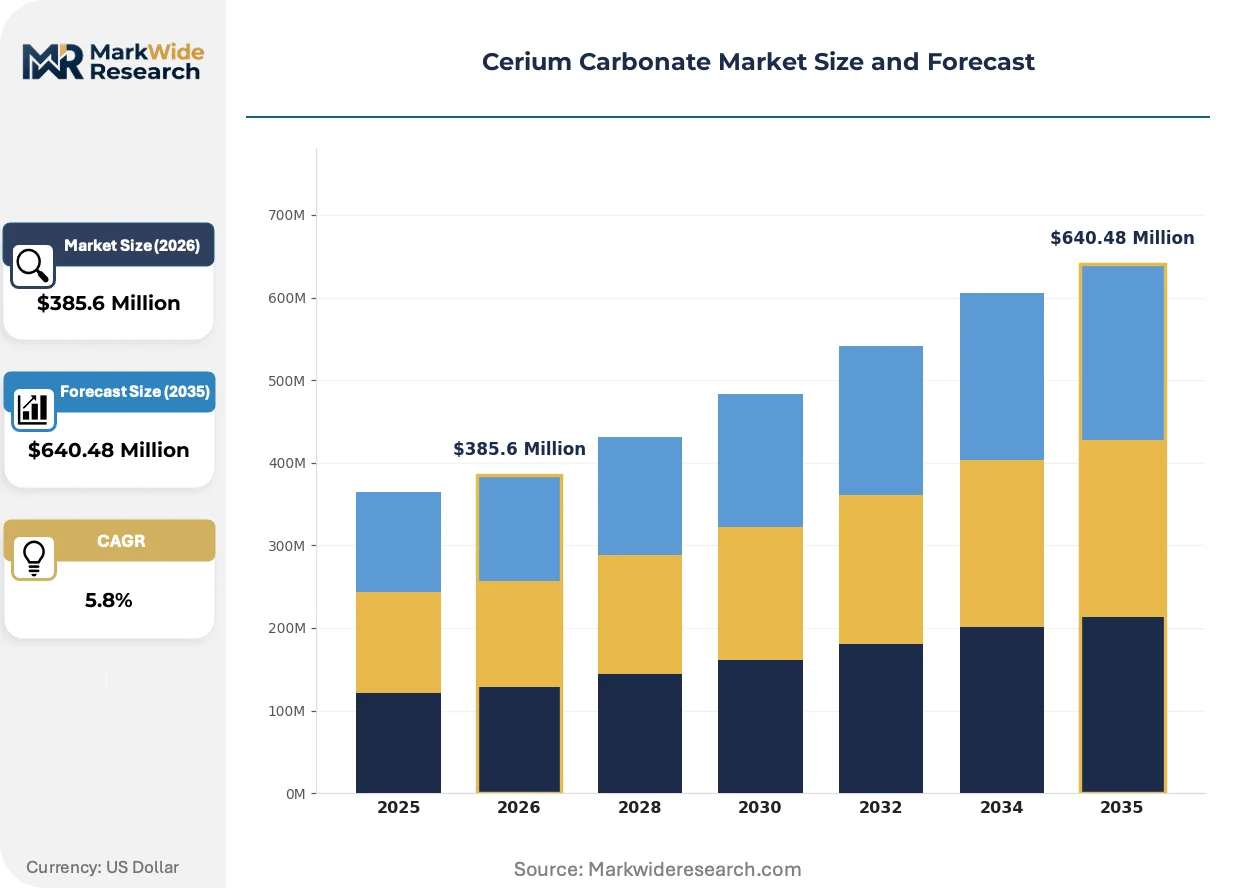
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Grade, Medium Grade, Heavy Grade, Ultrafine Grade Application: Glass Polishing, Catalysts, Ceramics, Electronics, Pigments End User Industry: Automotive Manufacturing, Electronics Production, Glass Industry, Chemical Processing Packaging Type: Powder Bags, Bulk Powder, Loose Powder, Fiber Drums |
| Companies Covered | Stanford Materials Corporation, ESPI Metals, China Minmetals Rare Earth Co., Ltd., Baotou Huaxing Rare Earth Technology Co., Ltd., Longyi Heavy Rare-Earth Technology Co., Ltd., Ganzhou Rare Earth Group Co., Ltd., American Elements, Solvay SA, Chenguang Rare Earths New Material Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerium Carbonate Market Emerging Trajectories
Continuous precipitation reactor technology is displacing batch processing in carbonate refining, enabling real-time particle size distribution control that reduces downstream oxide milling energy intensity.
Closed-loop solvent recovery systems are automating the capture and regeneration of organic phase reagents used in rare earth separation circuits. Ganzhou Rare Earth Group and similar integrated operators are deploying these systems to meet MEE wastewater discharge limits. The technology is compressing variable processing costs and extending reagent campaign life from weeks to months.
EU F-Gas Regulation extensions are tightening fluorinated greenhouse gas controls in rare earth processing, indirectly elevating cerium carbonate demand as a lower-emission polishing alternative to fluorine-based optical finishing compounds. German automotive glass suppliers are reformulating slurry compositions to reduce perfluorinated substance content. The regulatory pressure is accelerating qualification timelines for carbonate-derived oxide grades in precision optics.
Specification-tight buyers are consolidating vendor panels around dual-source contracts with embedded technical service tiers, replacing fragmented spot purchasing. Japanese catalyst manufacturers are leading this shift, negotiating multi-year offtake agreements that include embedded particle morphology optimization support. The procurement model change is most visible in automotive exhaust catalyst supply chains where formulation stability requirements dominate sourcing decisions.
Cerium Carbonate Market Segmentation
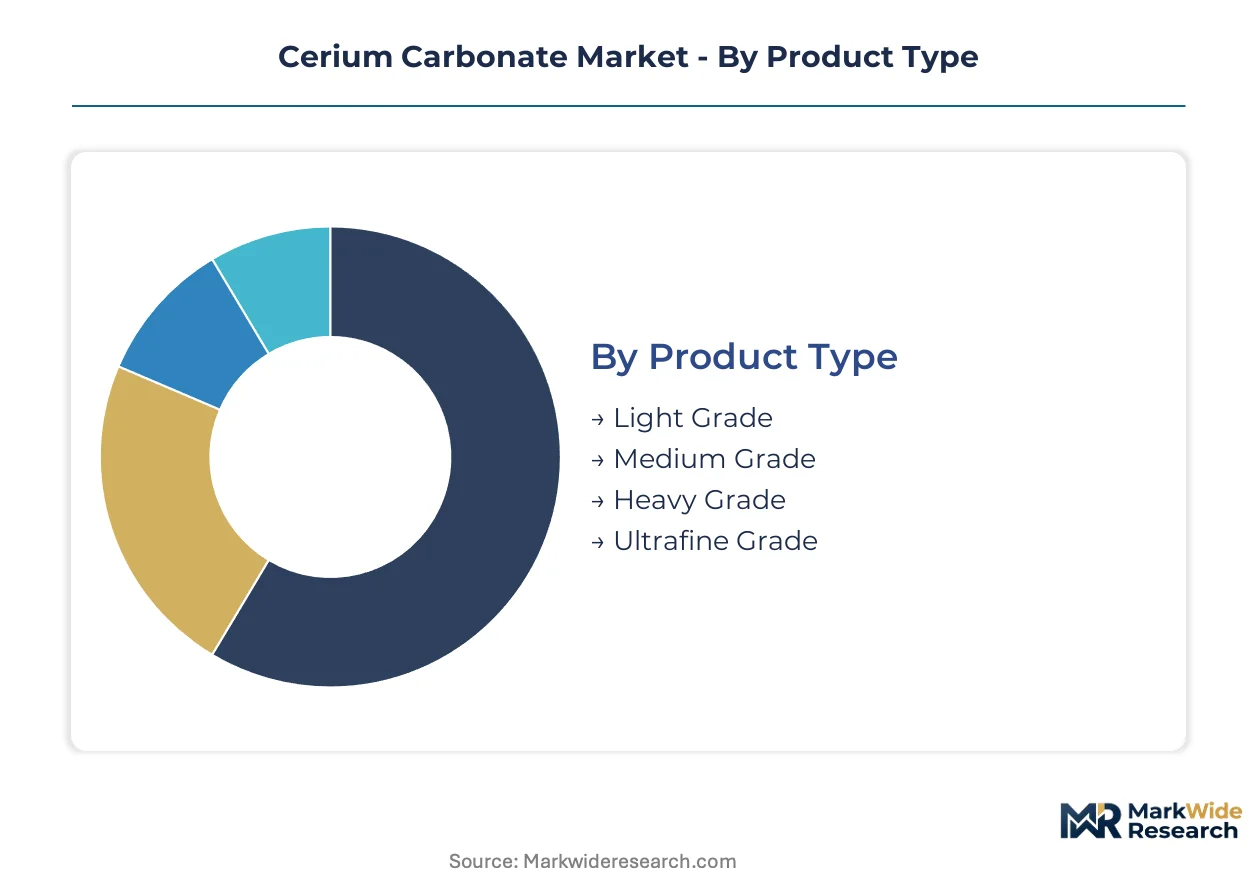
Cerium carbonate specifications diverge sharply across downstream applications, with automotive catalyst manufacturers and precision optics suppliers driving incompatible purity requirements. Buyers segment procurement by particle morphology, chemical specification, and batch-to-batch consistency rather than commodity-grade pricing alone.
Product Type:
Cost tier determines specification access, with ultrafine grades commanding premiums that reflect solvent extraction campaign intensity and precipitation control infrastructure.
- Light Grade:Hydrated cerium carbonate with moderate purity specifications serves glass polishing slurries where optical finish requirements permit broader particle distribution. Demand concentrates in German and Japanese automotive glass finishing facilities seeking REACH-compliant alternatives to fluorine-based compounds.
- Ultrafine Grade:Sub-micron particle consistency with tight morphology control enables electronics applications including CMP slurries and ceramic capacitor precursors. Japanese semiconductor material suppliers anchor demand, with formulation stability requirements driving multi-year offtake contracts.
- Medium Grade:Intermediate purity positioning serves ceramic colorant applications where thermal stability matters more than optical precision.
- Heavy Grade:Dense precipitate morphology targets catalyst substrate applications with lower surface area requirements.
Volume sits with Light Grade; growth tilts toward Ultrafine Grade.
Application:
Application selection maps directly to regulatory compliance burden, with automotive and electronics end-uses imposing the strictest impurity documentation requirements.
- Glass Polishing:Cerium oxide precursor demand from automotive windshield and precision optics manufacturers represents established volume. Euro 7 and China Stage 6b emission standards are indirectly elevating carbonate demand as fluorine-based polishing alternatives face F-Gas Regulation pressure.
- Catalysts:Cerium-zirconium solid solution precursors for three-way automotive exhaust catalysts are expanding most quickly as emission mandates tighten across multiple jurisdictions. Catalyst integrators in India and Mexico are localizing supply chains outside China direct control.
- Ceramics:Thermal barrier coating and structural ceramic applications consume consistent volumes with moderate purity thresholds.
- Electronics:CMP slurry and passive component applications require ultrafine grades with documented batch provenance.
- Pigments:Ceramic glaze and decorative applications tolerate broader specification ranges.
Catalyst applications are climbing the fastest; glass polishing retains volume dominance.
End User Industry:
Customer type dictates contract structure, with automotive OEMs imposing embedded technical service tiers that smaller electronics buyers cannot negotiate.
- Automotive Manufacturing:Exhaust system integrators and glass suppliers represent the largest consolidated demand pool. Tier 1 catalyst manufacturers in Germany, Japan, and the United States are restructuring procurement around dual-source contracts with specification-tight suppliers.
- Electronics Production:Semiconductor and passive component manufacturers require ultrafine grades with sub-micron consistency and full batch traceability.
- Glass Industry:Architectural and automotive glass finishing applications consume light and medium grades with moderate purity requirements.
- Chemical Processing:Diversified industrial applications including water treatment and specialty chemical synthesis.
Automotive Manufacturing commands volume concentration; Electronics Production shows steepest specification escalation.
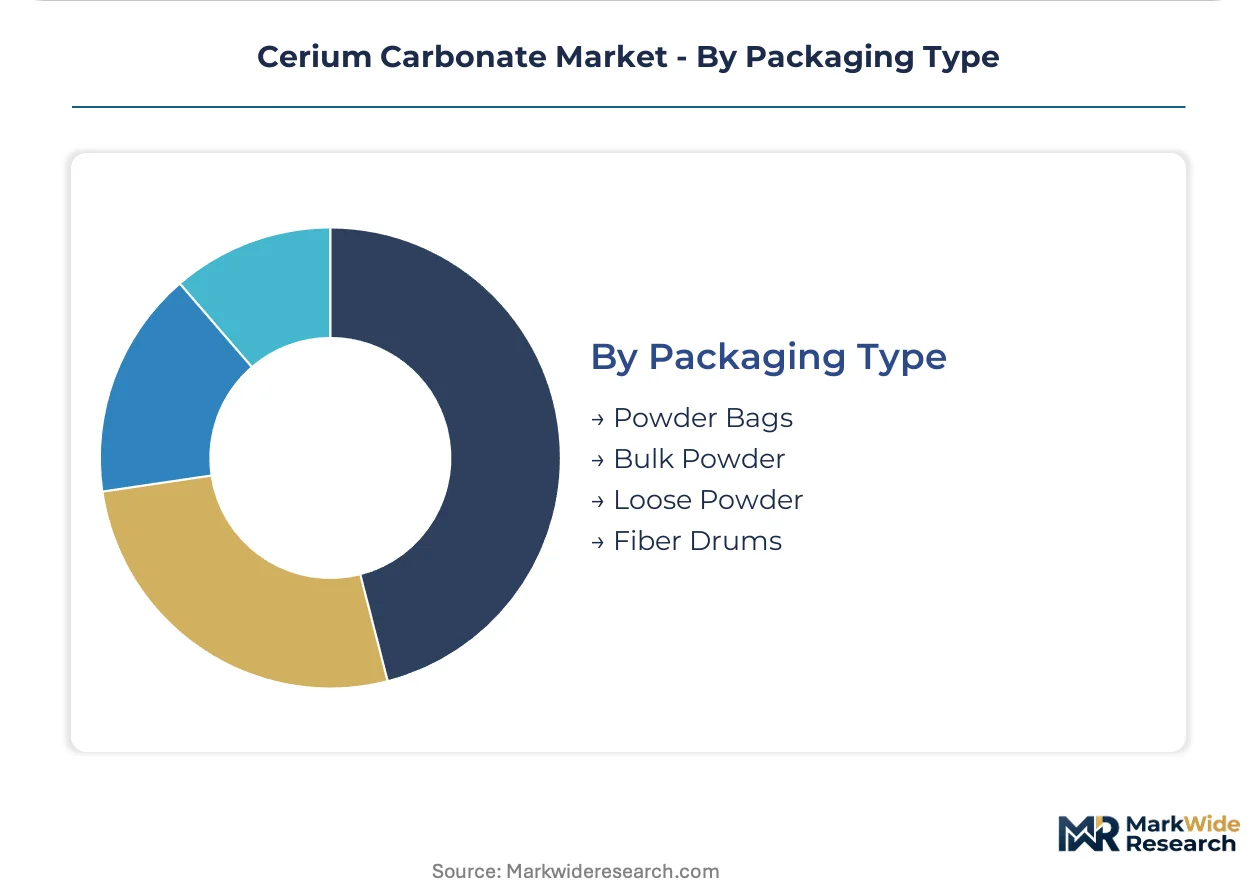
Packaging Type:
Packaging selection reflects supply chain security requirements, with high-value ultrafine grades demanding contamination-controlled handling.
- Powder Bags:Standard multi-layer polymer packaging for light and medium grade shipments to glass and ceramic processors.
- Bulk Powder:Tanker and silo delivery for high-volume catalyst precursor contracts with integrated automotive suppliers.
- Loose Powder:Specialty handling for small-batch electronics and research applications requiring minimal packaging residue.
- Fiber Drums:Rigid containment for ultrafine grades and international shipments requiring enhanced structural protection.
Bulk Powder dominates catalyst supply chains; Fiber Drums align with ultrafine grade security protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baotou anchors the cerium carbonate supply chain through its integrated rare earth refining corridor in Inner Mongolia. The city's oxide-to-carbonate processing cluster concentrates technical expertise and environmental compliance infrastructure for export-grade material.
China
Automotive catalyst mandates and glass polishing demand pull carbonate volumes upward across domestic manufacturing. SAMR export licensing for rare earth carbonates tightens feedstock access for international refiners. Baotou's processing corridor lowers unit costs through shared environmental infrastructure and concentrated solvent extraction expertise.
United States
Automotive exhaust system integrators and precision optics manufacturers drive specification-tight procurement from domestic compounders. EPA emission standards and NHTSA fuel economy rules indirectly elevate cerium-zirconium catalyst demand. Southwestern research corridors anchor custom synthesis demand for non-standard purity grades.
Germany
Euro 7 standards expand cerium-zirconium solid solution demand for three-way catalysts across automotive manufacturing. ECHA REACH registration and RoHS impurity thresholds elevate testing burdens for carbonate shipments. Bavarian automotive glass suppliers reformulate slurry compositions to reduce fluorine content under F-Gas Regulation pressure.
Japan
Semiconductor material suppliers and catalyst manufacturers anchor ultrafine grade demand with formulation stability requirements. METI industrial standards and JIS specifications constrain batch-to-batch variation tolerance. Kansai region electronics clusters negotiate multi-year offtake agreements with embedded particle morphology optimization support.
India
PLI scheme incentives for automotive components attract exhaust system integrators seeking localized rare earth supply chains. BIS standards alignment and DGFT import regulations shape procurement structures for carbonate precursors. Gujarat and Maharashtra manufacturing corridors concentrate emerging catalyst substrate processing capacity.
Cerium Carbonate Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the cerium carbonate value chain. State-backed Chinese refiners with integrated mining-to-oxide pipelines dominate feedstock access, while Western compounders compete on custom synthesis and specification-tight delivery. Three archetypes structure competition: integrated state-owned rare earth groups, specialized inorganic chemical formulators, and research-oriented custom synthesis houses. Capacity expansion through precipitation reactor upgrades and strategic partnerships for technical service tier embedding represent the dominant competitive moves.
Among integrated state-owned operators, Ganzhou Rare Earth Group Co., Ltd. and Baotou Huaxing Rare Earth Technology Co., Ltd. exemplify the upstream-controlled archetype with captive concentrate supply. Solvay SA occupies a position within the specialized formulation tier, anchoring European demand through rare earth chemical expertise. American Elements represents the custom synthesis vector, serving research and industrial clients requiring non-standard purity grades with specification-tight delivery capabilities.
| Leading Market Players |
|---|
| Stanford Materials Corporation |
| ESPI Metals |
| China Minmetals Rare Earth Co., Ltd. |
| Baotou Huaxing Rare Earth Technology Co., Ltd. |
| Longyi Heavy Rare-Earth Technology Co., Ltd. |
| Ganzhou Rare Earth Group Co., Ltd. |
| American Elements |
| Solvay SA |
| Chenguang Rare Earths New Material Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Continuous precipitation reactor technology is compressing unit processing costs while concentrating technical expertise among operators with capital to deploy real-time particle size control systems. This production-method transition simultaneously reshapes cost economics and supply concentration by elevating batch-to-batch consistency premiums for specification-tight buyers while marginalizing batch-process competitors.
Pricing Analysis
Yield-optimized formulation support anchors value-based pricing for ultrafine grades, with Japanese semiconductor material suppliers paying premiums tied to CMP slurry performance outcomes rather than input weight. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered ultrafine material from medium-grade ceramic precursors and light-grade glass polishing feedstock. Cost compression in light-grade segments is intensifying because lanthanum substitution captures share in automotive windshield applications where optical precision requirements permit grade relaxation. Catalyst manufacturers show least price sensitivity due to formulation stability requirements, while ceramic glaze processors tolerate broader specification ranges and drive hardest bargain.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese automotive Tier 1s are forcing qualification of secondary suppliers outside China's direct control, reshaping procurement structures. Supply concentrates in China, with over 80% of cerium-rich rare earth concentrates originating from southern China's ionic clay deposits and Inner Mongolia's Baotou processing corridor. Feedstock draws from cerium chloride and nitrate solutions, alkali carbonate reagents, and organic solvent extraction circuits. Single-source vulnerability concentrates in southern China's mining-to-oxide pipeline. Distribution runs through long-term offtake agreements with embedded technical service tiers rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH registration and RoHS impurity thresholds erect barrier-to-entry moats favoring incumbent compounders with established testing infrastructure and documentation capabilities.
For Market Incumbents: Lock in multi-year offtake agreements with embedded particle morphology optimization support before retiring solvent extraction technical cadres exit China's state-owned refining complex. Backward integration into southern China ionic clay concentrate access secures feedstock priority against SAMR export licensing tightening. Ganzhou Rare Earth Group's integrated mining-to-oxide pipeline demonstrates the defensive value of captive supply. For New Entrants and Emerging Players: The price-point gap between premium ultrafine grades and economy light-grade material creates white-space opportunity for medium-purity carbonate targeting India's PLI-incentivized catalyst manufacturing corridor. Localized supply chain positioning outside China direct control attracts exhaust system integrators in Gujarat and Maharashtra. Technical service tier partnerships with established rare earth separation specialists accelerate qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated state-owned rare earth groups seeking Western formulation expertise and REACH-compliant distribution infrastructure. Long-term viability hinges on positioning within automotive emission standard tightening trajectories across multiple jurisdictions. Watch for MEE environmental audit timeline extensions as inflection indicator for Chinese capacity expansion delays and export volume constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Dual-source contracts with Japanese catalyst manufacturers secure volume commitments through embedded technical service tiers. |
| Backward Integration | Captive concentrate supply from southern China ionic clay deposits insulates against SAMR export licensing volatility. |
| Green Manufacturing Transition | Closed-loop solvent recovery systems meet MEE wastewater discharge limits while compressing variable processing costs. |
| Capacity Expansion | Precipitation reactor upgrades in Inner Mongolia's Baotou corridor enable real-time particle size distribution control. |
| Joint Venture | India catalyst manufacturing partnerships localize supply chains outside China direct control under PLI scheme incentives. |
Methodological Framework
Independent corroboration across rare earth refinery technical directors, automotive catalyst procurement leads, and glass polishing compound formulators underwrites the qualitative findings. Primary interviews with solvent extraction specialists, MEE compliance officers, and semiconductor material suppliers combined with secondary validation from customs trade data, GB standards documentation, SEC 10-K filings from listed rare earth groups, and ECHA registration databases. Bottom-up grade-by-grade volume estimates triangulate against top-down rare earth oxide consumption models.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window. Segmentation dimensions include product grade tier, end-use application, packaging format, and regional production hub. CAGRs derive from iterative reconciliation of supply-side capacity expansion schedules against demand-side emission standard implementation timelines. Forecast inputs incorporate automotive production forecasts and F-Gas Regulation extension trajectories.
Inputs from ECHA registration databases and SAMR export licensing records were available through the study window; gaps in real-time Chinese domestic inventory data introduce uncertainty bands around near-term price elasticity assumptions. Deviation in MEE environmental audit certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Wollastonite Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Ceramic Lining Market
Ceramics
Strontium Carbonate Market
Ceramics
Calcined Bauxite Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Stoneware Market
Ceramics
Methyl Silicate Market
Ceramics
High Temperature Ceramics Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Glazed Bricks Market
Ceramics
Thermal Spray Powder Market