
 Ceramic Matrix Composites Market | 2026-2036
Ceramic Matrix Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Matrix Composites Market Intelligence
Supply chain architecture for high-temperature ceramic components is tilting toward captive fiber production and long-term offtake agreements. GE Aerospace leverages in-house SiC fiber capability to secure material access for next-generation turbine blades. Rolls-Royce anchors its CMC strategy through partnerships with specialty precursor suppliers in the United Kingdom. Safran competes by concentrating R&D investment on oxide-oxide systems for lower-temperature engine sections.
Ceramic matrix composites combine ceramic fibers embedded within a ceramic matrix, typically silicon carbide or alumina, yielding materials that withstand temperatures exceeding 1200°C while maintaining structural integrity under oxidative stress. Their primary purpose centers on replacing superalloy components in gas turbine hot sections, enabling higher operating temperatures and improved fuel efficiency. Ceramic fibers dominate material value capture due to manufacturing complexity and limited qualified suppliers. Thermal protection systems represent the fastest-growing application segment, driven by hypersonic vehicle programs and reusable spacecraft development. Structural components remain the most mature application, with established qualification pathways in commercial aviation.
FAA airworthiness standards and EASA certification requirements govern CMC adoption timelines in commercial propulsion systems, extending qualification periods and elevating barriers to new entrants. EPA emissions regulations and EU Green Deal decarbonization targets directly incentivize CMC penetration by rewarding higher turbine inlet temperatures and reduced fuel burn. REACH compliance for precursor chemicals and OSHA silica exposure limits add manufacturing cost and site selection constraints. Stakeholders must monitor qualification progress for alternative fiber chemistries and assess geographic concentration risks in the precursor supply base.
Market Dynamics
Procurement concentration among aerospace engine OEMs is consolidating qualified supplier bases and extending qualification timelines for new CMC entrants. Tier-1 manufacturers now demand captive fiber supply and multi-year offtake commitments before component approval.
Growth Catalysts
- FAA emissions mandates:Tighter NOx and CO2 standards for commercial propulsion systems are forcing turbine inlet temperature upgrades that only CMC hot-section components can deliver.
- Hypersonic vehicle programs:Defense agencies across the United States, Australia, and Japan are funding thermal protection system development for Mach 5+ flight envelopes.
- SiC fiber chemistry advances:Third-generation polycarbosilane precursors are reducing oxygen content in finished fibers, extending service life in oxidative environments.
Market Restraints
- Precursor supply concentration:High-purity chlorosilane feedstock production clusters in Germany and Japan, creating single-source vulnerability for Western CMC manufacturers.
- REACH compliance costs:ECHA registration requirements for organosilicon precursors add EUR 200,000-400,000 per substance, elevating barriers for European entrants.
- Superalloy incumbent advantage:Established casting and forging infrastructure for nickel-based alloys preserves cost competitiveness below 1050°C operating regimes.
Strategic Opportunities
- India defense localization:DRDO indigenization mandates for gas turbine components create first-mover advantage for CMC suppliers establishing local qualification pathways.
- EU Green Deal industrial heat:Cement and steel sector decarbonization targets are opening CMC applications in waste heat recovery and hydrogen combustion systems.
- Additive manufacturing convergence:Ceramic 3D printing of complex lattice structures is enabling topology-optimized CMC components previously impossible with conventional layup.
Industry Challenges
- Non-destructive evaluation expertise:Industrial CT scanning and ultrasonic inspection of CMC components requires specialized technicians scarce outside GE Aerospace and Safran facilities.
- FAA/EASA concurrent certification:Dual airworthiness validation for new CMC turbine blades extends development timelines by 18-24 months versus superalloy equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Matrix Composites Market |
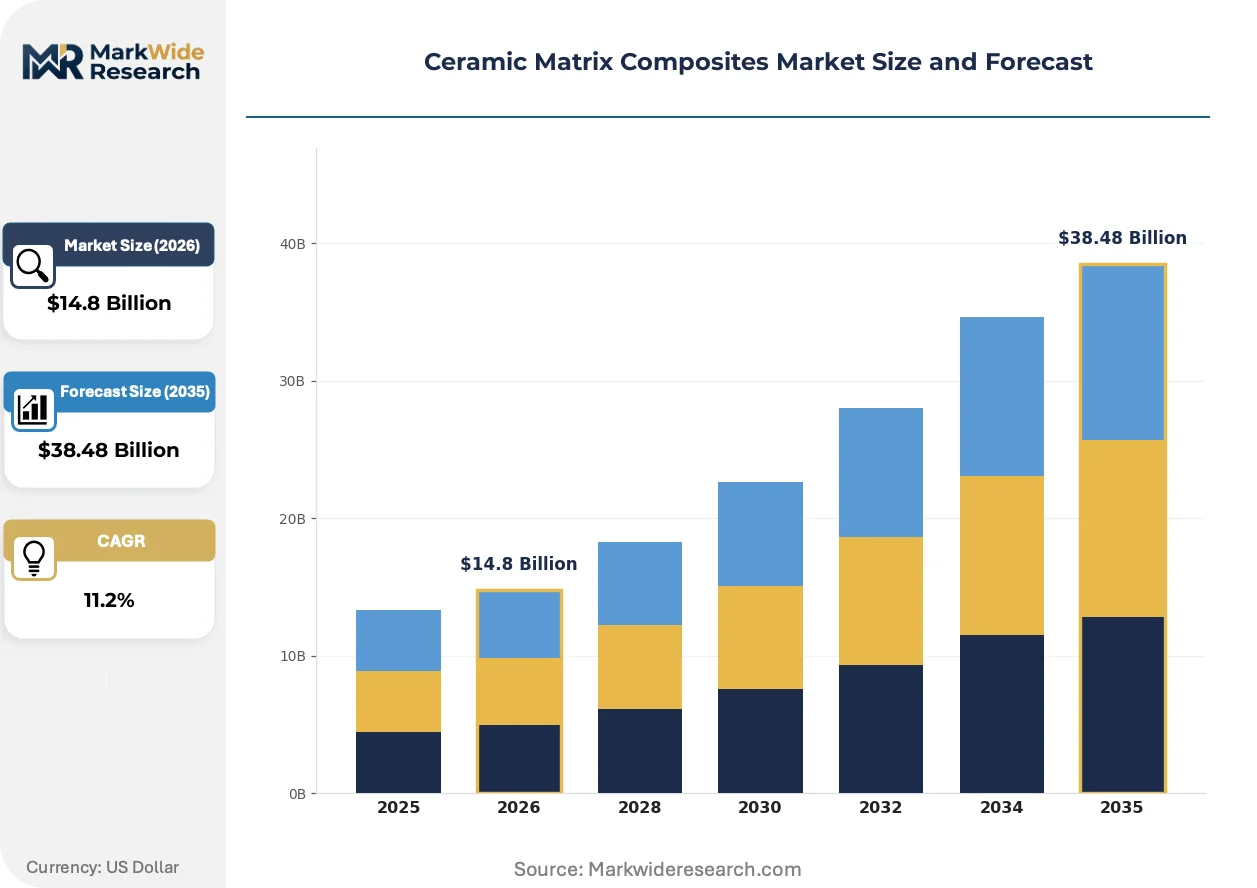
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $38.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Fibers, Ceramic Matrices, Precursor Fibers, Reinforcements End User: Aerospace, Defense, Automotive, Industrial Technology: CVD, Plasma Spraying, Tape Casting, Pulping Application: Thermal Protection Systems, Engines, Structural Components, Brake Systems |
| Companies Covered | GE Aerospace, Rolls-Royce, Safran, CoorsTek Inc., SGL Carbon, Axiom Materials, Ultramet, KYOCERA Corporation, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Matrix Composites Market Strategic Shifts & Innovations
Digital thread integration across CMC design, manufacturing, and qualification is compressing development cycles and enabling predictive life modeling. Real-time fiber placement monitoring and AI-driven defect detection are replacing manual inspection protocols.
Process analytics software is digitizing quality assurance for SiC fiber preform manufacturing. GE Aerospace and Rolls-Royce now deploy machine vision systems during chemical vapor infiltration to detect matrix density variations in real time. This capability is digitizing the feedback loop between production parameters and component performance, reducing scrap rates and accelerating design iteration.
EPA greenhouse gas standards for commercial aircraft engines are tightening disclosure requirements for lifecycle emissions. Manufacturers must now document supply chain carbon intensity from precursor synthesis through component retirement. This transparency mandate is forcing CMC suppliers to quantify energy consumption in fiber production and driving investment in renewable-powered precursor facilities.
Long-term service agreements are displacing transactional component sales in commercial aviation procurement. Engine OEMs now bundle CMC hot-section parts with performance guarantees covering fuel efficiency and time-on-wing. This shift concentrates risk with component suppliers and rewards those with predictive maintenance capabilities and distributed repair networks.
Ceramic Matrix Composites Market Segmentation
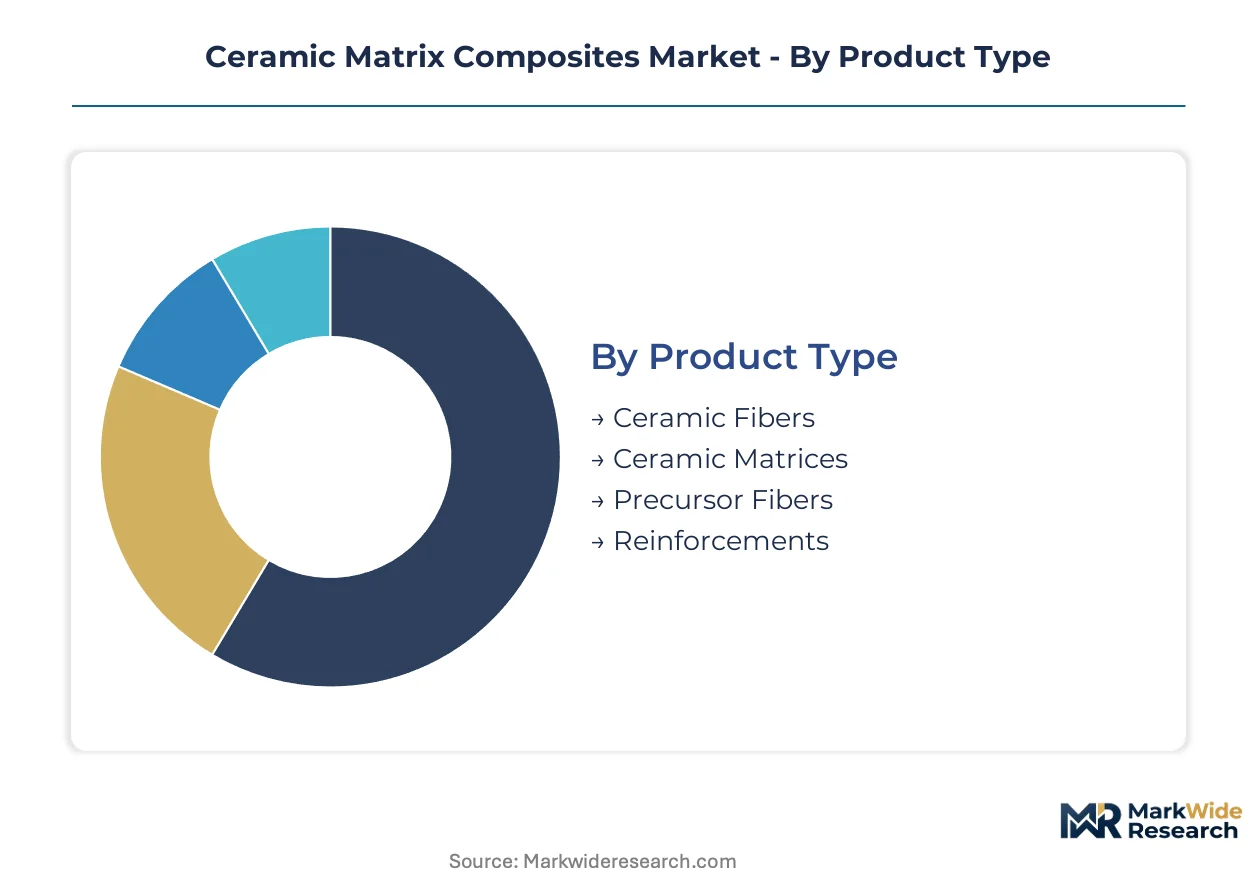
Ceramic matrix composites demand diverges sharply across end-use applications, with aerospace procurement cycles spanning years while defense programs prioritize rapid qualification. Component geometry, thermal exposure profiles, and regulatory certification pathways create distinct supply requirements within each segment.
Product Type:
After-sales service intensity concentrates in fiber replacement and matrix repair operations, driving supplier investment in technical field support networks.
- Ceramic Fibers:Silicon carbide filaments spun from polycarbosilane precursors constitute the highest-value input, with oxygen content below 0.5 percent extending oxidative service life. GE Aerospace and Rolls-Royce have established captive production in the United States and United Kingdom to secure supply for turbine blade programs.
- Ceramic Matrices:Chemical vapor infiltration of silicon carbide or alumina phases encapsulates fiber preforms, creating damage-tolerant architectures. Matrix densification cycles run 200-400 hours per component, limiting throughput and elevating work-in-process inventory requirements.
- Precursor Fibers:Polymer-derived ceramic filaments require controlled pyrolysis to achieve ceramic conversion without structural collapse.
- Reinforcements:Woven fabrics and 3D preforms tailor mechanical anisotropy to component-specific load paths.
By volume, ceramic matrices lead due to mass fraction in finished components. By growth pace, ceramic fibers are expanding most quickly as OEMs internalize supply.
End User:
Customer procurement sophistication ranges from performance-guaranteed long-term agreements in commercial aerospace to cost-plus development contracts in defense applications.
- Aerospace:Commercial engine OEMs specify CMC hot-section components for turbine vanes and combustor liners, with FAA certification requirements extending qualification timelines. GE Aerospace's LEAP engine program has established the dominant reference architecture for SiC-SiC turbine blades.
- Defense:Hypersonic vehicle thermal protection systems and missile exhaust components drive demand for ultra-high-temperature oxide-oxide composites. The United States, Australia, and Japan have accelerated funding for Mach 5+ flight envelopes.
- Automotive:Brake disc applications leverage CMC friction stability at elevated temperatures.
- Industrial:Waste heat recovery and hydrogen combustion systems in cement and steel decarbonization projects.
Aerospace captures the largest revenue share. Defense programs are gaining share fastest as hypersonic budgets expand.
Technology:
Process selection determines capital intensity, cycle time, and geometric complexity limits, with equipment utilization rates varying tenfold across methods.
- CVD:Chemical vapor deposition builds ceramic matrices through gas-phase precursor decomposition, achieving near-theoretical density with minimal fiber damage. Equipment costs exceed USD 10 million per reactor line, concentrating capability at GE Aerospace and Safran facilities.
- Plasma Spraying:Molten ceramic particle impingement creates environmental barrier coatings and matrix layers for oxide-oxide systems, with deposition rates enabling larger component scales.
- Tape Casting:Slurry-based forming produces flat or gently curved preforms with controlled thickness.
- Pulping:Fiber slurry processing for complex-shaped preform manufacturing.
CVD dominates high-value aerospace applications. Plasma spraying is climbing fastest as oxide-oxide systems penetrate defense thermal protection.
Application:
Component function dictates thermal exposure severity, mechanical loading mode, and regulatory scrutiny intensity.
- Thermal Protection Systems:Reusable spacecraft heat shields and hypersonic leading edges require ablation-resistant surfaces with dimensional stability across repeated thermal shock cycles. NASA and defense agencies in the United States and Japan are qualifying CMC alternatives to carbon-carbon for next-generation vehicles.
- Engines:Turbine hot-section components replace nickel superalloys above 1050°C, with FAA and EASA airworthiness standards governing adoption timelines in commercial propulsion.
- Structural Components:Mature qualification pathways exist for commercial aviation secondary structures.
- Brake Systems:Automotive and aircraft braking applications exploit CMC friction characteristics and weight reduction.
Engines command the highest unit values. Thermal protection systems show the steepest expansion trajectory as hypersonic programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness standards anchor the United States as the dominant geography, with emissions mandates from EPA tightening turbine inlet temperature requirements that only CMC components can satisfy.
United States
GE Aerospace and Rolls-Royce operate captive SiC fiber production facilities in Ohio and Virginia to secure supply chains for next-generation turbine blades. EPA greenhouse gas disclosure requirements now mandate lifecycle emissions documentation from precursor synthesis through component retirement. Cincinnati and Huntsville clusters concentrate chemical vapor infiltration capability for LEAP engine programs.
United Kingdom
Rolls-Royce anchors its CMC strategy through partnerships with specialty precursor suppliers near Bristol and Derby manufacturing centers. REACH compliance costs for organosilicon precursors add regulatory burden for ECHA registration. Oxfordshire and South West England host defense thermal protection development for hypersonic vehicle programs.
Japan
METI funding accelerates third-generation polycarbosilane precursor research to reduce oxygen content in finished SiC fibers. JIS standards govern qualification pathways for aerospace component exports to Western markets. Nagoya and Tokyo metropolitan areas concentrate Mitsubishi Chemical Group precursor manufacturing and Kyocera structural ceramic operations.
Germany
SGL Carbon maintains chlorosilane feedstock production that supplies Western CMC manufacturers, creating single-source vulnerability concerns. ECHA registration requirements and OSHA-aligned silica exposure limits constrain site selection for new entrants. Bavaria and North Rhine-Westphalia cluster carbon-carbon and ceramic composite expertise from automotive and aerospace supply chains.
India
DRDO indigenization mandates for gas turbine components create first-mover opportunities for CMC suppliers establishing local qualification pathways. BIS standards adoption for aerospace materials accelerates domestic certification timelines. Bangalore and Hyderabad defense research clusters drive hypersonic thermal protection system development with Australian and Japanese partnership funding.
Ceramic Matrix Composites Market Key Industry Players
Vertically integrated engine OEMs and specialty materials suppliers split the market between captive production and merchant supply. The vendor base concentrates around qualified fiber chemistries and FAA-certified component architectures. Three archetypes dominate: aerospace engine manufacturers with in-house CMC capability, European and Asian carbon-carbon specialists diversifying into ceramics, and defense-focused thermal protection fabricators. Competitive moves center on backward integration into precursor supply and multi-year offtake agreements locking qualified supplier capacity.
Among aerospace-integrated manufacturers, GE Aerospace, Rolls-Royce, and Safran exemplify the dominant competitive position. GE Aerospace represents the vertically integrated archetype with captive SiC fiber production securing material access. Rolls-Royce occupies a partnership-dependent position anchoring supply through UK-based precursor relationships. Safran sits within the diversified European aerospace tier concentrating oxide-oxide system development for lower-temperature engine sections.
| Leading Market Players |
|---|
| GE Aerospace |
| Rolls-Royce |
| Safran |
| CoorsTek Inc. |
| SGL Carbon |
| Axiom Materials |
| Ultramet |
| KYOCERA Corporation |
| Mitsubishi Chemical Group Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific container freight corridors from Yokohama to Long Beach carry chlorosilane precursors and SiC fiber spools at rates that amplify cost differentials between captive supply and merchant procurement. GE Aerospace absorbs these logistics premiums through in-house fiber production, while smaller CMC fabricators face margin compression when sourcing from Japanese precursor suppliers.
Pricing Analysis
The customization-premium spread separates standard-grade SiC-SiC turbine vanes from configured-to-order thermal protection systems with complex 3D-woven preforms. Contract-based long-term offtake agreements dominate commercial aerospace, with price differentiation driven by FAA certification tier and fiber oxygen content grade. Pricing pressure stems from REACH compliance costs elevating European precursor registration burdens. Defense agencies show least price sensitivity due to performance-guaranteed procurement mandates, while industrial heat recovery buyers negotiate aggressively on volume scale.
Supply Chain Analysis
Export-control regimes under the Wassenaar Arrangement restrict third-generation polycarbosilane precursor technology flows to non-member states, constraining supply expansion. Raw material dependencies center on high-purity chlorosilane feedstock from Germany and Japan, polycarbosilane polymers from Japanese specialty chemical producers, and pyrolysis furnaces from European equipment builders. Single-source vulnerability concentrates in SGL Carbon's German chlorosilane production. Distribution runs through captive pipelines at GE Aerospace and Rolls-Royce facilities, with merchant supply fragmented among qualified fiber specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic matrix composites occupy an early-cycle expansion phase as FAA emissions mandates force turbine inlet temperature upgrades beyond superalloy limits. This regulatory tailwind accelerates CMC penetration from demonstrator engines to full production programs.
For Market Incumbents: Insulate qualified supplier status by deepening backward integration into precursor synthesis and securing multi-year offtake agreements with defense agencies. Threats from oxide-oxide system competitors in lower-temperature segments demand expanded R&D investment in environmental barrier coatings. Captive SiC fiber capacity represents the critical lever for margin defense against merchant supply price volatility.
For New Entrants and Emerging Players: Pursue DRDO indigenization pathways in India as the most penetrable geography, where local qualification requirements exclude established Western suppliers. Target thermal protection systems for hypersonic vehicles as the fastest-expanding application with less entrenched incumbent control. A go-to-market angle through Australian-Japanese defense partnership funding offers accelerated qualification timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core composite divisions amid portfolio rationalization. Long-term viability centers on suppliers with FAA-certified component architectures and predictive maintenance capabilities. The signal to watch is LEAP engine program expansion rates, which indicate CMC adoption velocity across commercial aviation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | GE Aerospace's captive SiC fiber production secures supply chain resilience against Japanese feedstock concentration. |
| FAA Certification Pathway Investment | EASA concurrent validation extends timelines but creates dual-market access for qualified turbine blade suppliers. |
| Defense Partnership Structuring | Australian-Japanese hypersonic funding accelerates thermal protection system qualification outside commercial aviation cycles. |
| Additive Manufacturing Convergence | Ceramic 3D printing enables lattice geometries impossible with tape casting, compressing design iteration cycles. |
| Long-term Service Agreement Bundling | Performance guarantees on fuel efficiency shift risk to suppliers with predictive maintenance and distributed repair networks. |
Research Approach
Initial hypotheses were tested against primary input from turbine blade procurement directors, chemical vapor infiltration plant managers, FAA certification engineers, and defense thermal protection program officers and refined through secondary validation. Sources included SEC 10-K filings from aerospace-integrated manufacturers, ECHA REACH registration databases, NASA Small Business Innovation Research awards, and customs trade data on chlorosilane imports. Bottom-up fiber production capacity estimates and top-down engine program content assumptions were triangulated to anchor volume forecasts.
Demand-supply balance framing structured the analytical approach across the analysis window, with segmentation modeled by fiber chemistry generation, matrix densification technology, end-use application, and geographic regulatory cluster. CAGRs derived from installed base replacement cycles and new program penetration curves incorporated hypersonic vehicle budget trajectories and EPA greenhouse gas disclosure mandate implementation pace as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed ceramic composite programs would shift outcomes. Material shifts in FAA emissions standard stringency or REACH precursor registration requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Brown Fused Alumina Market
Ceramics & Fibers
Global Rice Husk Ash Market
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Silicon Carbide Fiber Market
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Synthetic Quartz Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Rutile Market
Ceramics & Fibers
Feldspar Market
Ceramics & Fibers
Hollow Fiber Ceramic Membrane Market
Ceramics & Fibers
Fluorite Pellets Market
Ceramics & Fibers
Zabuyelite Market
Ceramics & Fibers
Global Zircon Sand Market