
 Pyrolytic Boron Nitride Market | 2026-2036
Pyrolytic Boron Nitride Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrolytic Boron Nitride Market Analytics
A shift from single-source to multi-source ceramic supply is pivoting procurement strategies across the pyrolytic boron nitride value chain. Momentive Performance Materials leverages captive chemical vapor deposition capacity to anchor North American supply security. Shin-Etsu Chemical Co., Ltd. sustains dominant positions in ultra-high-purity grades through integrated precursor manufacturing. Morgan Advanced Materials competes via specialized aerospace qualification programs that extend its defense channel control.
Pyrolytic boron nitride denotes a hexagonal boron nitride ceramic synthesized via chemical vapor deposition at temperatures exceeding 1,800°C, yielding anisotropic thermal conductivity with basal-plane values reaching 60 W/m·K and through-plane values near 2 W/m·K, purpose-built for semiconductor crucibles and thermal barrier applications. Ceramics formulations capture the dominant margin pool owing to crucible replacement cycles in silicon epitaxy reactors, while coatings segments attract fastest-growing interest from gallium nitride device manufacturers seeking diffusion barriers. Spheres remain a nascent category concentrated in specialty research applications with limited volume scale.
FDA scrutiny of healthcare device biocompatibility and EPA emissions thresholds for boron trichloride precursors shape product certification pathways and plant siting decisions in the United States. REACH registration requirements and RoHS substance restrictions in Europe constrain feedstock sourcing flexibility while elevating documentation burdens for importers. Stakeholders must monitor evolving semiconductor export control frameworks and precursor chemical licensing regimes to anticipate supply disruptions and qualification delays.
Market Dynamics
Semiconductor foundries are accelerating pyrolytic boron nitride crucible replacement cycles as silicon epitaxy reactor throughput demands intensify, compressing supply lead times and amplifying chemical vapor deposition capacity scarcity.
Growth Catalysts
- Dual Carbon Policy Framework:China's MEE emissions mandates and SAMR industrial standards are redirecting ceramic production toward low-carbon chemical vapor deposition methods, stimulating domestic capacity expansion for pyrolytic boron nitride.
- Gallium Nitride Device Proliferation:Power electronics manufacturers are adopting pyrolytic boron nitride diffusion barriers for GaN-on-Si heteroepitaxy, creating incremental demand streams beyond traditional silicon processing.
- REACH Registration Compliance:European ECHA substance documentation requirements are elevating qualification barriers for imported ceramics, advantaging certified regional suppliers with established precursor traceability systems.
Market Restraints
- Boron Trichloride Feedstock Volatility:EPA emissions thresholds for boron trichloride precursors constrain plant siting flexibility in the United States, elevating capital intensity for new chemical vapor deposition facilities.
- East Asian Supply Concentration:Overreliance on South Korean and Taiwanese chemical vapor deposition capacity creates systemic exposure to semiconductor export control disruptions and precursor licensing delays.
- Isotropic Ceramic Substitution:Hot-pressed hexagonal boron nitride competes for thermal management applications where anisotropic conductivity is non-critical, pressuring pricing in lower-specification segments.
Strategic Opportunities
- Indian Semiconductor Mission:India's PLI scheme for compound semiconductors and BIS standardization initiatives are opening qualification pathways for pyrolytic boron nitride crucible suppliers in emerging foundry clusters.
- Aerospace Thermal Barrier Expansion:Hypersonic vehicle programs are specifying pyrolytic boron nitride for leading-edge thermal protection, extending addressable demand beyond electronics into defense channels.
- Precursor Recycling Integration:Closed-loop boron trichloride recovery systems are reducing feedstock waste and qualifying suppliers for EU Green Deal circular economy procurement preferences.
Industry Challenges
- Chemical Vapor Deposition Technician Scarcity:Specialized reactor operation expertise for 1,800°C+ deposition environments is concentrated among legacy semiconductor equipment specialists, constraining capacity scaling.
- Multi-Jurisdictional Qualification Timelines:Simultaneous FDA biocompatibility reviews for medical device applications and EPA facility permits extend product commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrolytic Boron Nitride Market |
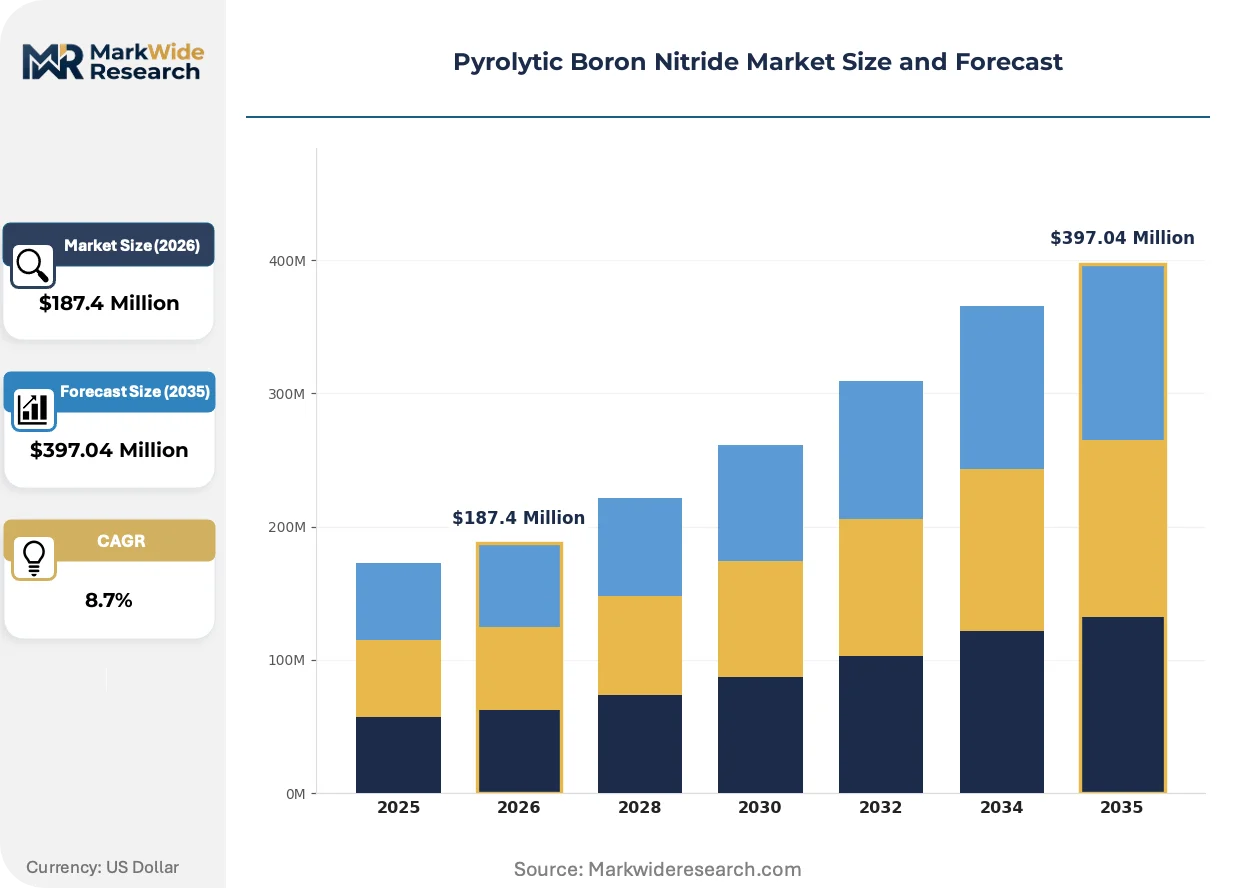
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Coatings, Spheres, Ceramics Application: Semiconductors, Thermal Management, Insulation, Aerospace End User: Electronics, Defense, Healthcare, Research Form: Flexible, Rigid, Composite, Bulk |
| Companies Covered | Momentive Performance Materials, Shin-Etsu Chemical Co., Ltd., Morgan Advanced Materials, Beijing Boyu Semiconductor, Saint-Gobain Ceramics & Plastics, Inc., H.C. Starck Solutions, 3M Company, Denka Company Limited, Precision Ceramics USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrolytic Boron Nitride Market Evolving Landscape
Pyrolytic boron nitride manufacturing is undergoing process intensification as chemical vapor deposition reactor designs evolve to accommodate larger-diameter crucibles for 300mm silicon wafer epitaxy.
Advanced reactor architectures with multi-zone temperature control are expanding into 450mm wafer preparation tooling, enabling single-crucible processing of larger silicon substrates. Memory and logic foundries in South Korea are piloting these systems for next-generation node development. This equipment transition is expanding into thermal management specifications previously served by isotropic ceramics, compressing traditional material substitution windows.
Europe's F-Gas Regulation and associated ECHA restrictions on fluorinated precursor emissions are forcing boron trichloride purification process redesigns across chemical vapor deposition operations. Industrial consequence includes elevated documentation burdens for importers and accelerated investment in precursor recycling infrastructure. Coating segments for gallium nitride device manufacturing are most affected, with suppliers restructuring European supply chains to maintain REACH registration compliance.
Semiconductor procurement teams are consolidating qualified supplier lists from twelve-plus vendors to four-to-six strategic partners, compressing vendor onboarding timelines and elevating certification-driven preference formation. Distributors serving mid-tier foundries are being displaced by direct manufacturer relationships with volume commitments. This concentration is most visible in Taiwan's Science Park clusters, where crucible replacement contracts now bundle multi-year chemical vapor deposition capacity reservations.
Pyrolytic Boron Nitride Market Segmentation
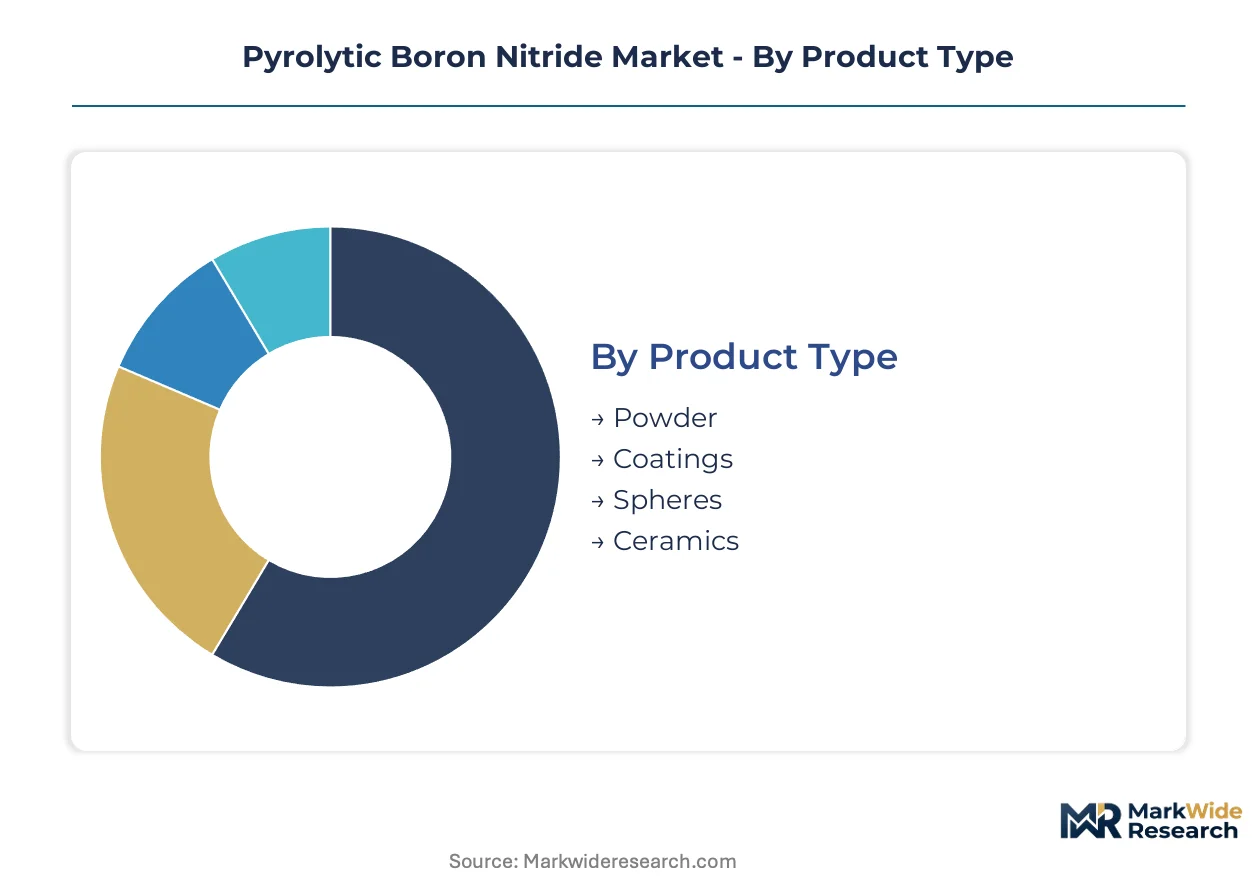
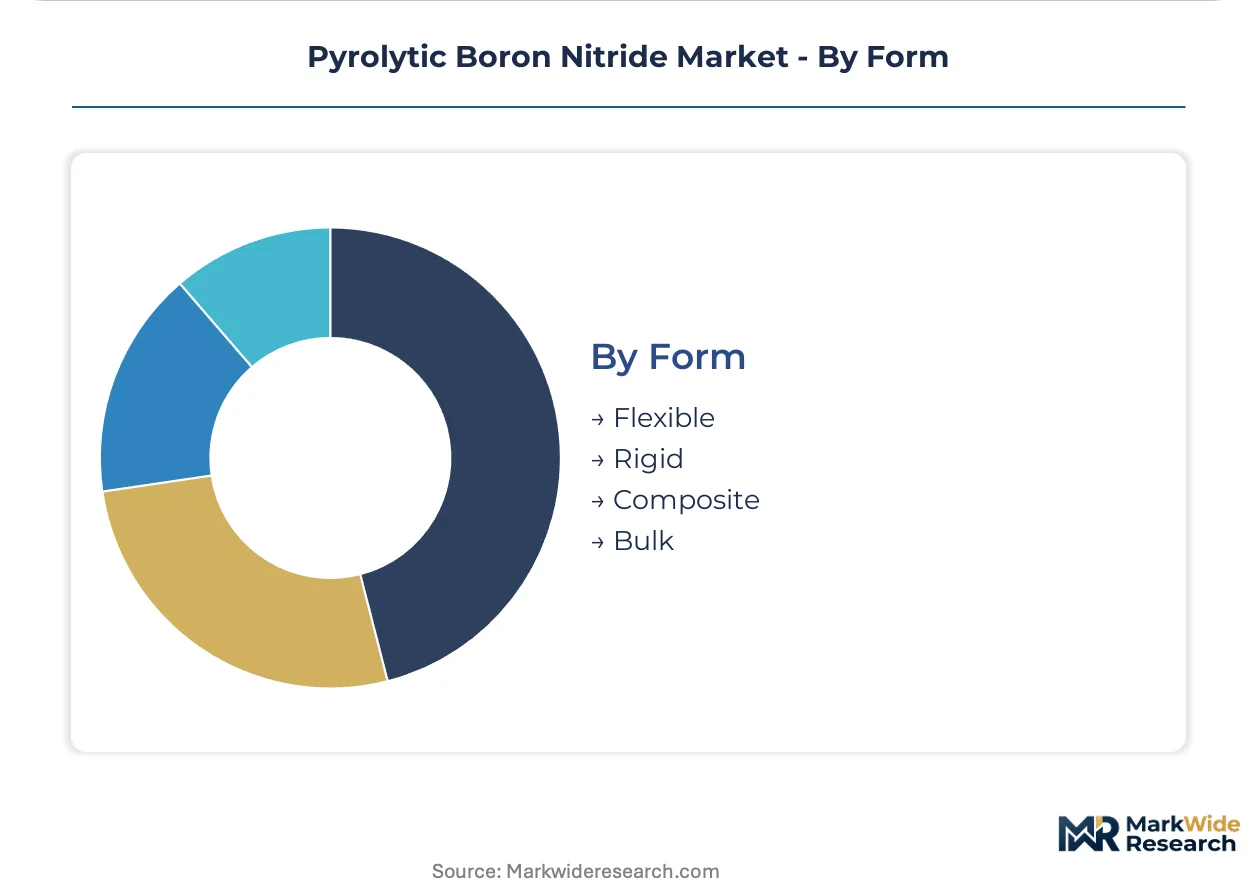
Pyrolytic boron nitride's anisotropic thermal properties create distinct value pools across physical forms and end-use specifications. Segmentation reveals how chemical vapor deposition capacity allocates across crucible manufacturing, diffusion barriers, and emerging aerospace applications.
Product Type:
Ceramics formulations dominate procurement volumes through crucible replacement cycles, while coating technologies capture emerging specifications from compound semiconductor epitaxy.
- Ceramics:Hexagonal boron nitride structures synthesized via chemical vapor deposition at 1,800°C+ yield anisotropic thermal conductivity purpose-built for silicon epitaxy reactor crucibles. Taiwan's Science Park foundries and South Korean memory manufacturers drive replacement demand through intensified wafer throughput requirements.
- Coatings:Thin-film diffusion barriers deposited via chemical vapor deposition protect gallium nitride heterostructures during GaN-on-Si epitaxy. Power electronics manufacturers in East Asian semiconductor clusters specify these layers for high-frequency device fabrication.
- Powder:Finely divided pyrolytic boron nitride serves as feedstock for hot-pressed ceramic composites and specialized lubricant formulations.
- Spheres:Precision spherical particles remain concentrated in academic research applications and neutron detection instrumentation with limited commercial volume scale.
Ceramics leads on scale; coatings leads on momentum.
Application:
End-use demand clusters around thermal performance specifications, with semiconductor processing requirements setting the baseline for purity and dimensional tolerance.
- Semiconductors:Silicon epitaxy reactors consume pyrolytic boron nitride crucibles for 300mm wafer processing, with 450mm tooling pilots underway in South Korea. Chemical vapor deposition capacity scarcity compresses supply lead times as foundries accelerate replacement cycles.
- Thermal Management:Anisotropic conductivity profiles—60 W/m·K basal plane versus 2 W/m·K through-plane—enable directional heat spreading in power module substrates. Electric vehicle inverter manufacturers specify these properties for silicon carbide device packaging.
- Insulation:Ultra-high-purity grades serve vacuum furnace linings and crystal growth environments where metallic contamination must register below parts-per-billion thresholds.
- Aerospace:Hypersonic vehicle thermal protection systems specify pyrolytic boron nitride for leading-edge applications exceeding 1,600°C operational temperatures.
Semiconductors commands volume concentration; aerospace climbs the fastest.
End User:
Customer procurement patterns diverge between qualification-intensive defense channels and price-sensitive research institutions.
- Electronics:Foundry operators in Taiwan, South Korea, and China specify crucible geometries through direct manufacturer relationships with multi-year capacity reservations.
- Defense:Aerospace qualification programs require extended certification timelines, extending supplier control through specialized thermal barrier specifications for hypersonic programs.
- Healthcare:FDA biocompatibility reviews for implantable device applications extend commercialization cycles by 18-24 months for medical-grade pyrolytic boron nitride.
- Research:National laboratories and university facilities purchase small-batch quantities through distributors displaced from foundry procurement channels.
Electronics anchors demand scale; defense sustains margin premiums.
Form:
Physical configuration determines manufacturing yield and installation methodology across deposition reactor designs.
- Rigid:Monolithic crucibles and plates dominate silicon epitaxy applications with standardized dimensional tolerances for 300mm wafer processing.
- Flexible:Thin-film sheets conform to complex geometries in thermal barrier applications where rigid ceramics fracture under mechanical stress.
- Composite:Pyrolytic boron nitride layers deposited on graphite or silicon carbide substrates combine thermal properties with structural reinforcement.
- Bulk:Thick-walled components serve high-duration furnace applications requiring extended thermal cycling resistance.
Rigid forms dominate unit economics; flexible configurations gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting pyrolytic boron nitride capacity toward jurisdictions with streamlined precursor licensing and lower emissions compliance costs, fragmenting traditional East Asian supply concentration as new qualification pathways emerge.
China
Domestic foundry expansion and compound semiconductor self-sufficiency targets are accelerating chemical vapor deposition capacity buildout. MEE emissions mandates and SAMR industrial standards enforce low-carbon production methods, elevating capital requirements for new facilities. Yangtze River Delta clusters around Shanghai and Suzhou concentrate crucible manufacturing for silicon epitaxy reactor supply.
United States
Defense hypersonic programs and silicon carbide device packaging are sustaining demand for thermal barrier specifications. EPA emissions thresholds for boron trichloride precursors constrain greenfield chemical vapor deposition siting, extending permitting timelines. Arizona and Texas semiconductor manufacturing corridors attract qualified suppliers with established precursor traceability systems.
South Korea
Memory and logic foundries are piloting 450mm wafer preparation tooling, compressing crucible replacement cycles and amplifying chemical vapor deposition scarcity. MFDS chemical licensing frameworks govern precursor import documentation. Pyeongtaek and Hwaseong industrial complexes anchor high-purity grade consumption for next-generation node development.
Germany
Automotive power module manufacturers specify anisotropic thermal management substrates for silicon carbide inverter packaging. ECHA REACH registration requirements and RoHS substance restrictions constrain feedstock sourcing flexibility for importers. Bavaria and Baden-Württemberg automotive supplier networks drive qualification programs for thermal barrier coatings.
India
Compound semiconductor foundry initiatives under the PLI scheme are opening first-mover qualification pathways for crucible suppliers. BIS standardization initiatives establish domestic certification benchmarks for ceramic purity grades. Karnataka and Telangana emerging fab clusters attract precursor distributors establishing regional technical service presence.
Pyrolytic Boron Nitride Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue compound semiconductor qualification and aerospace thermal protection specifications. Market structure consolidates around three to four dominant chemical vapor deposition operators with captive precursor supply, while mid-scale fabricators compete on regional certification speed. Two strategic archetypes predominate: integrated chemical conglomerates with backward control over boron trichloride refining, and specialized ceramic engineers focused on reactor geometry optimization. Competitive intensity centers on multi-year capacity reservation contracts and simultaneous FDA-EPA qualification timelines.
Among integrated chemical producers, Momentive Performance Materials and Shin-Etsu Chemical Co., Ltd. exemplify the precursor-integrated archetype with established semiconductor channel presence. Morgan Advanced Materials occupies a position within the specialized ceramic engineering tier, representing defense-aerospace qualification specialists. Beijing Boyu Semiconductor anchors the emerging China-based supplier category pursuing domestic foundry qualification pathways. These three company profiles illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors.
| Leading Market Players |
|---|
| Momentive Performance Materials |
| Shin-Etsu Chemical Co., Ltd. |
| Morgan Advanced Materials |
| Beijing Boyu Semiconductor |
| Saint-Gobain Ceramics & Plastics, Inc. |
| H.C. Starck Solutions |
| 3M Company |
| Denka Company Limited |
| Precision Ceramics USA |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers and family-owned mid-caps anchor capacity decisions in East Asian chemical vapor deposition clusters, compressing margin flexibility for Western importers facing extended qualification timelines and precursor traceability costs.
Pricing Analysis
Distributor margins have collapsed as Taiwan Science Park foundries and South Korean memory manufacturers consolidate procurement around direct manufacturer relationships with multi-year capacity reservations. Three-tier pricing structure across aerospace-qualified, semiconductor-grade, and industrial-standard levels separates defense channel premiums from foundry volume discounts. Cost compression in lower-specification tiers intensifies because hot-pressed hexagonal boron nitride substitutes erode differentiation for non-critical thermal management. Research institutions exhibit highest price sensitivity due to small-batch purchasing power, while defense programs tolerate premium positioning for extended certification timelines.
Supply Chain Analysis
REACH registration compliance and FDA biocompatibility reviews gate European and North American market access, advantaging suppliers with established precursor traceability systems. Production concentrates in Taiwan, South Korea, and China where Yangtze River Delta and Pyeongtaek industrial complexes host chemical vapor deposition capacity. Feedstock supply rests on boron trichloride refining, high-purity ammonia, and specialized graphite substrate manufacturing. Single-source vulnerability runs through East Asian precursor licensing regimes controlled by MFDS and SAMR frameworks. Distribution runs through direct OEM contracts displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pyrolytic boron nitride functions as a stable compounder anchored by irreplaceable crucible demand in silicon epitaxy reactors with replacement cycles compressing rather than elongating.
For Market Incumbents: Anchor defensive positioning through captive boron trichloride refining and 450mm wafer tooling qualification ahead of next-generation node transitions. Isotropic ceramic substitution threatens lower-tier thermal management applications; prioritize aerospace thermal barrier certification to sustain margin premiums. Capacity expansion in Arizona and Texas semiconductor corridors captures reshoring procurement preferences. For New Entrants and Emerging Players: India's PLI scheme for compound semiconductors opens a window for crucible suppliers establishing BIS-certified production ahead of Karnataka and Telangana fab cluster ramp. Target gallium nitride diffusion barrier coatings as the most penetrable segment given European F-Gas Regulation compliance burdens on incumbent supply chains. Pursue direct technical service partnerships with emerging foundry engineering teams rather than distributor channel dependence. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized ceramic engineers lacking backward integration into precursor supply. Five-to-ten year viability hinges on chemical vapor deposition technician pipeline development and multi-jurisdictional qualification infrastructure. Watch for semiconductor export control framework expansions as inflection indicators for geographic supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Captive boron trichloride supply secures margin control against EPA emissions threshold constraints. |
| 450mm Wafer Tooling Qualification | South Korean memory foundries pilot next-generation crucible geometries for node advancement. |
| Aerospace Thermal Barrier Certification | Hypersonic vehicle programs specify pyrolytic boron nitride for leading-edge protection exceeding 1,600°C. |
| European Precursor Recycling Infrastructure | Closed-loop boron trichloride recovery qualifies suppliers for EU Green Deal procurement preferences. |
| Indian PLI Scheme Qualification Pathway | BIS standardization initiatives establish domestic certification benchmarks for emerging compound semiconductor foundries. |
Research Methodology
Multiple input streams — primary interviews with chemical vapor deposition reactor operators, semiconductor foundry procurement directors, and aerospace qualification engineers; secondary validation through SEC filings, customs trade data, and ECHA REACH registration databases; plus patent landscape analysis — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, application, end user, and form dimensions produced volume and value estimates throughout the forecast period. CAGRs were derived from segment-level growth trajectory analysis incorporating silicon wafer diameter transition timelines and gallium nitride device manufacturing expansion rates.
Revisions become necessary when semiconductor export control frameworks expand, EPA boron trichloride emissions thresholds tighten, or chemical vapor deposition technician scarcity intensifies beyond modeled constraints. A model refresh is warranted upon material change in dual carbon policy enforcement intensity across Chinese ceramic production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Ceramic Balls Market
Ceramics
White Fused Alumina Market
Ceramics
Barium Carbonate Powder Market
Ceramics
United States Ceramic Tiles Market
Ceramics
ME K-Feldspar Market
Ceramics
Traditional Ceramic Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Ceramic Kilns Market
Ceramics
India Kaolin Market
Ceramics
Calcium Silicate Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Potassium Feldspar Market
Ceramics
Ceramic Pigments Market
Ceramics
Sodium Aluminum Silicate Market
Ceramics
Ceramic Frit Glass Market