
 China Ceramic Tiles Market | 2026-2036
China Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
China Ceramic Tiles Market Outlook
Property developer consolidation in China's tier-two and tier-three cities is repositioning procurement volumes toward fewer buyers with stricter material specifications. Dongpeng Ceramic leverages its vertical kiln network to anchor supply contracts with these consolidated developers. Marco Polo Holdings competes through specialized large-format glazing lines that dominate premium residential specifications. Monalisa Group sustains R&D intensity in thin-body porcelain, differentiating its output for high-rise cladding projects.
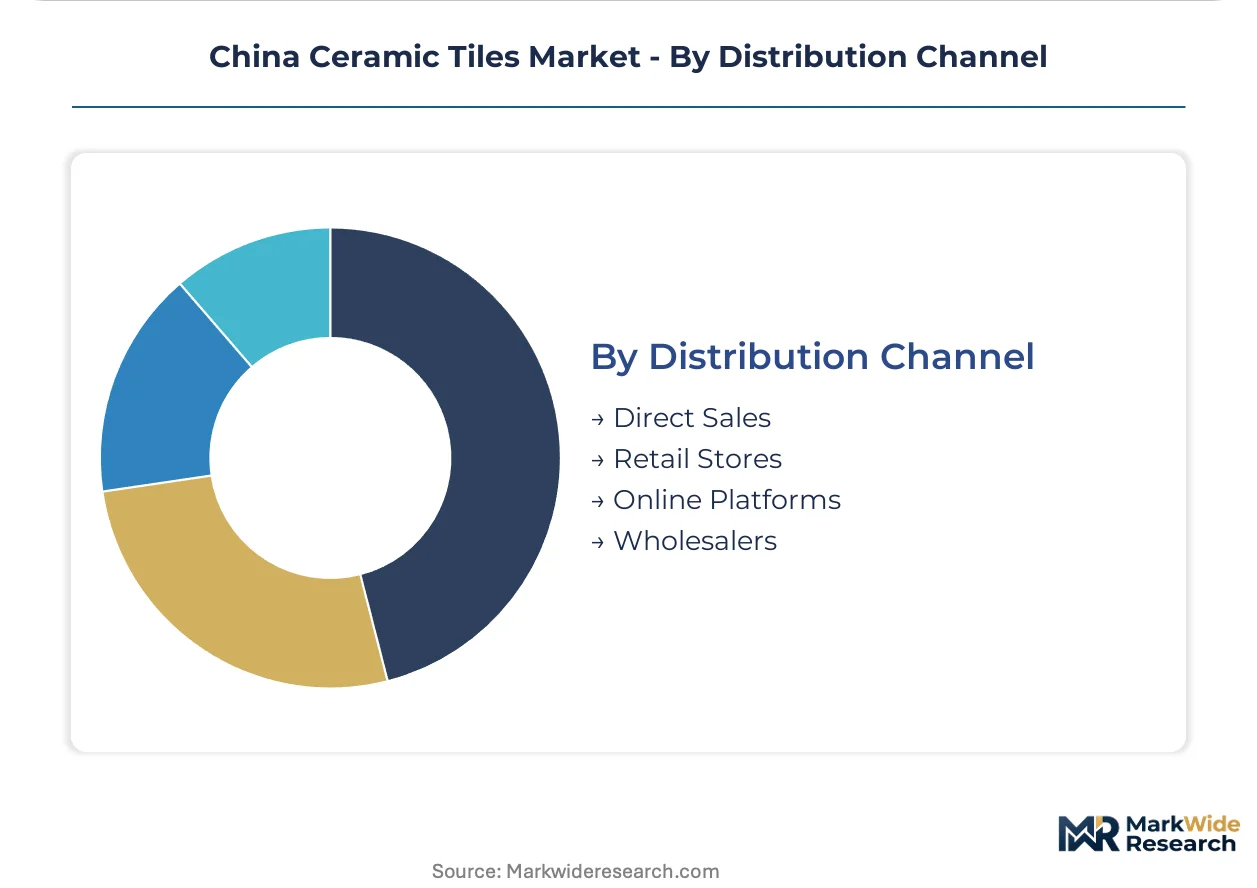
China ceramic tiles are sintered clay-based surfacing materials, typically fired at 1,000–1,300°C, with water absorption rates below 0.5% for porcelain grades and up to 10% for traditional earthenware; they serve as structural finishes for floors, walls, and exterior envelopes across construction verticals. Porcelain tiles command the dominant margin pool due to density and frost resistance specifications that outperform standard glazed alternatives in commercial applications. Vitrified tiles represent the fastest-growing product category as full-body color consistency reduces pattern-matching waste on large flooring contracts. The wholesale distribution channel still occupies the largest volume share, though direct sales to mega-developers are accelerating.
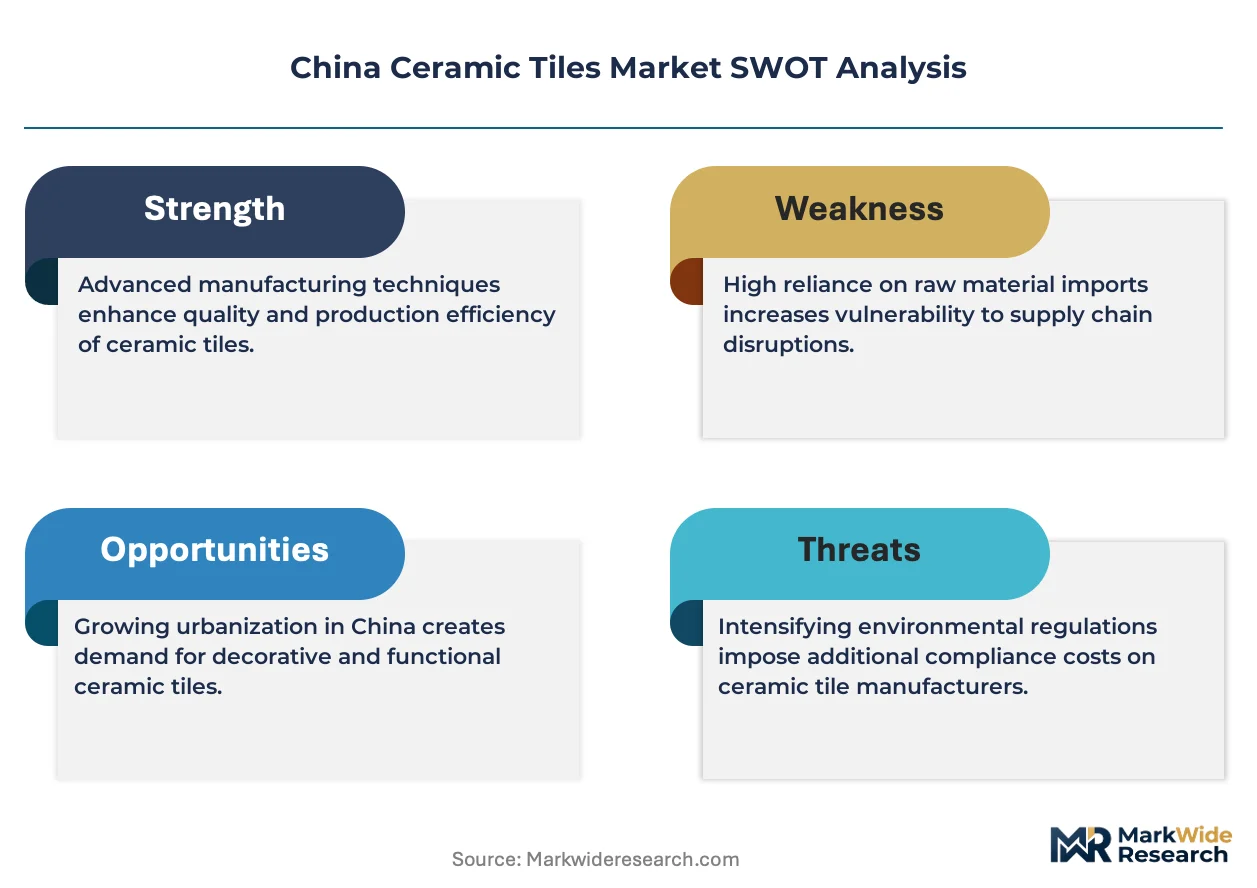
China's SAMR enforces GB/T 4100 standards for ceramic tile dimensional tolerance and breaking strength, while MEE regulations on kiln emissions are forcing fuel-switching investments across Foshan manufacturing clusters. The country's dual carbon goals are reshaping energy-intensive production, with natural gas substitution mandates altering cost structures for producers in Guangdong and Fujian. Stakeholders must monitor how provincial emission quota allocations will redistribute manufacturing capacity between coastal hubs and inland zones.
Market Dynamics
China's dual carbon goals are compressing kiln fuel economics across Guangdong and Fujian manufacturing clusters, forcing producers to absorb natural gas switching costs while tier-two city developers consolidate procurement into fewer, larger contracts.
Growth Catalysts
- MEE emission mandates:Provincial emission quotas are accelerating dry-press technology adoption, rewarding early movers with continued operating licenses in coastal hubs.
- Tier-two residential vertical:Developer consolidation in cities like Chengdu and Xi'an is concentrating demand for large-format porcelain into standardized specification packages.
- Thin-body porcelain R&D:High-rise cladding applications are absorbing lighter tile substrates as structural load requirements tighten for super-tall buildings.
Market Restraints
- Natural gas price volatility:Fuel-switching compliance under dual carbon policy has exposed Foshan producers to spot market fluctuations that erode margin stability.
- Guangdong supply concentration:Overreliance on the Pearl River Delta for high-end glazed output creates vulnerability to provincial emission quota reallocations.
- Ceramic slab substitution:Sintered stone surfaces are capturing premium kitchen and bathroom specifications previously held by vitrified tiles.
Strategic Opportunities
- Central China manufacturing migration:Hubei and Hunan provinces offer untapped kiln capacity with lower emission stringency and proximity to inland construction growth.
- SAMR green building certification:GB/T 50378 compliance requirements for public projects are creating specification pull for low-carbon tile products.
- Direct developer channel expansion:Mega-developers are bypassing wholesale distributors for volume contracts, enabling margin capture previously lost to distribution tiers.
Industry Challenges
- Dry-press technician scarcity:The shift from wet to dry forming processes has outpaced vocational training pipeline output in traditional ceramic engineering programs.
- GB/T 4100 recertification timelines:Updated dimensional tolerance standards are forcing inventory write-downs for non-compliant legacy stock.
- Kiln retrofit integration complexity:Natural gas burner conversions in legacy tunnel kilns require extended downtime that conflicts with just-in-time developer delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Ceramic Tiles Market |
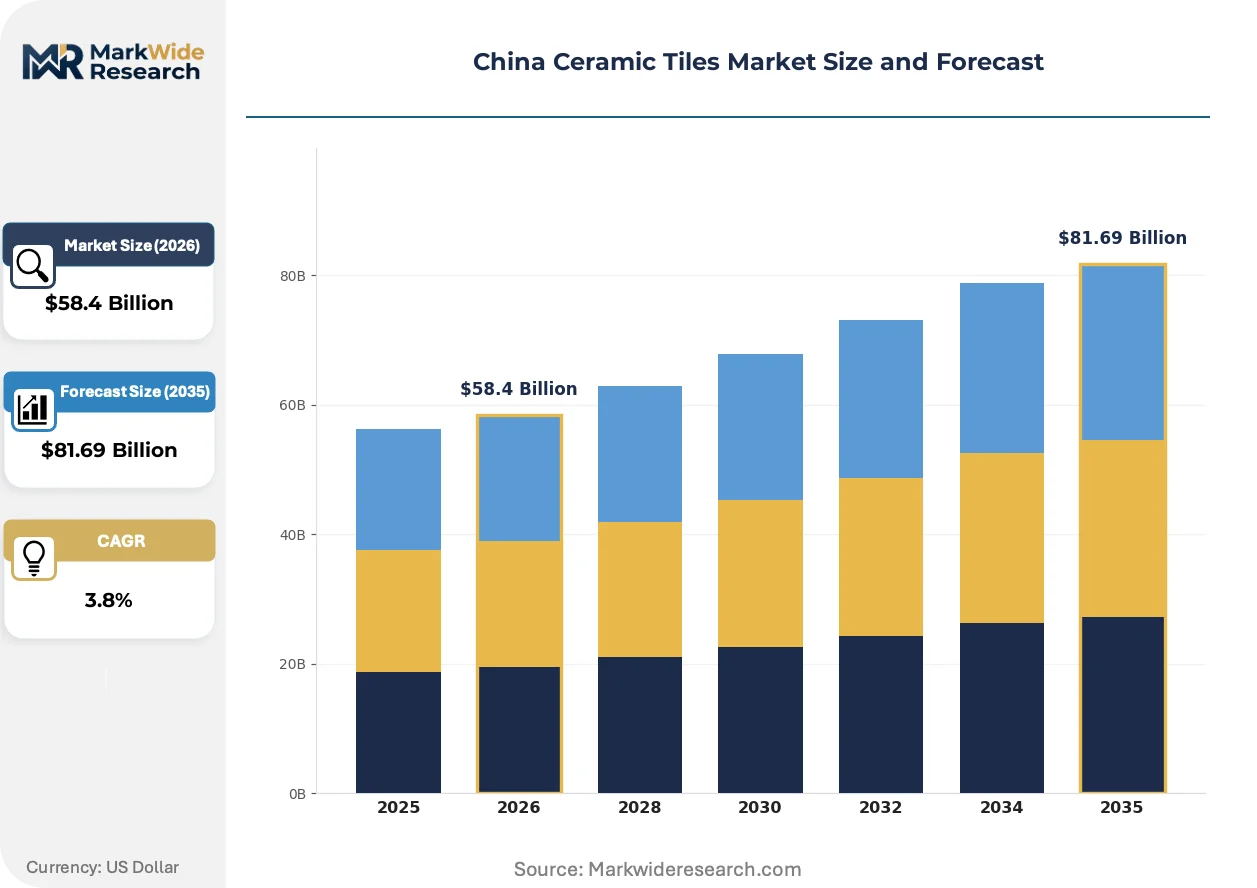
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $81.69 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Porcelain Tiles, Vitrified Tiles, Terracotta Tiles Application: Flooring, Wall Cladding, Roof Covering, Countertops End User: Residential Projects, Commercial Buildings, Industrial Facilities, Institutional Spaces Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesalers |
| Companies Covered | Guangdong Newpearl Ceramic Group, New Zhongyuan Ceramics, Dongpeng Ceramic, Kito Ceramics, Eagle Ceramics, Marco Polo Holdings, Guanzhu Ceramics, Nabel Ceramics, Monalisa Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Ceramic Tiles Market Strategic Shifts
Digital inkjet decoration and full-body vitrification are collapsing the traditional premium-mass market segmentation, enabling mid-tier producers to specification-match high-end aesthetics at scale.
Single-pass digital inkjet printing is rewriting color consistency economics by eliminating multiple decoration firings. Tier-two developers now specify photorealistic stone and wood grain surfaces for entire residential towers. This compression of decoration cost structures is eroding the historical premium commanded by specialized glazing houses.
GB standards for building materials are tightening emission thresholds under SAMR oversight, with new volatile organic compound limits affecting glaze formulation chemistry. Manufacturers in Foshan are reformulating frit compositions to maintain surface hardness while meeting MEE air quality benchmarks. The compliance burden falls heaviest on small-batch artisanal producers lacking in-house testing laboratories.
Consolidated procurement departments at major developers are unbundling after-sales service from product supply, forcing tile manufacturers to warranty installation quality or lose specification status. This risk transfer is most visible in Chongqing and Tianjin, where developer procurement teams now mandate five-year performance bonds for large-format porcelain in high-traffic common areas.
China Ceramic Tiles Market Segmentation
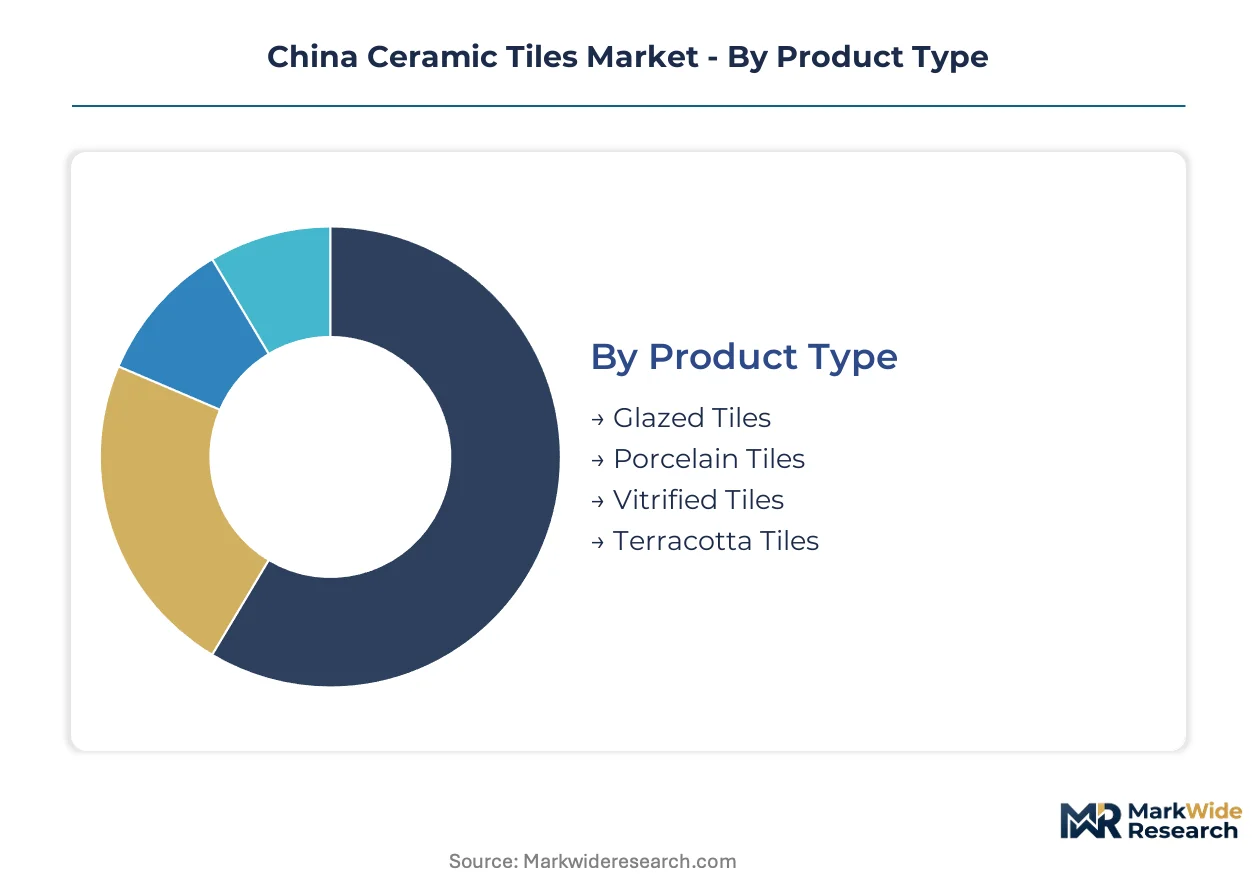
Product architecture in China's ceramic tile sector determines margin capture, kiln utilization, and compliance exposure. Specification differentiation across formats and applications creates distinct competitive arenas with divergent capital intensity requirements.
Product Type:
Standardization dominates commodity-grade output while premium specifications demand proprietary formulation control.
- Glazed Tiles:Clay bodies receive surface glass coatings fired at 1,000–1,150°C, creating decorative finishes with water absorption between 3–10%. Chengdu and Xi'an residential towers specify these for interior walls where frost resistance is non-critical. SAMR's tightening VOC limits on glaze chemistry are forcing reformulation investments among Foshan producers.
- Porcelain Tiles:Kaolin-rich compositions fired above 1,200°C achieve sub-0.5% water absorption and density suitable for high-traffic flooring. Tier-two city developers consolidate procurement around large-format porcelain for common areas, prioritizing breaking strength compliance with GB/T 4100.
- Vitrified Tiles:Full-body color consistency eliminates pattern-matching waste on expansive flooring contracts. Natural gas switching costs in Guangdong kilns compress margins for producers lacking scale.
- Terracotta Tiles:Low-fire earthenware with 5–10% water absorption serves heritage restoration and specialized architectural accents. Hunan province maintains artisanal production clusters for this category.
Leading the category by volume: Porcelain Tiles. Growing fastest: Vitrified Tiles.
Application:
Structural load requirements and exposure conditions segment demand by performance tier rather than aesthetic preference alone.
- Flooring:Abrasion resistance testing under GB/T 4100 separates commercial-grade specifications from residential alternatives. Direct developer contracts concentrate volume here.
- Wall Cladding:Thin-body porcelain substrates reduce structural load for super-tall buildings in Chongqing and Shenzhen. Monalisa Group's R&D intensity targets this specification tier.
- Roof Covering:Frost-cycle durability and interlocking geometry dominate technical requirements. Northern China climates drive demand for specialized vitrified formats.
- Countertops:Sintered stone substitution is displacing traditional ceramic surfaces in premium kitchen specifications previously held by vitrified tiles.
Dominant by contract value: Flooring. Expanding most quickly: Wall Cladding.
End User:
Procurement concentration varies sharply across verticals, with consolidated developers wielding specification power unavailable to fragmented buyers.
- Residential Projects:Tier-two and tier-three city developers like those in Xi'an and Tianjin consolidate procurement into standardized packages with strict material specifications. Dongpeng Ceramic anchors supply contracts through vertical kiln network coverage.
- Commercial Buildings:High-traffic specifications demand enhanced breaking strength and stain resistance. Five-year performance bonds now accompany large-format porcelain specifications in Chongqing developments.
- Industrial Facilities:Chemical resistance and load-bearing capacity prioritize functional performance over surface decoration. Direct sales channels bypass wholesale markups for these volume buyers.
- Institutional Spaces:GB/T 50378 green building certification requirements for public projects create specification pull for low-carbon tile products with documented emission profiles.
Maximum volume concentration: Residential Projects. Steepest specification upgrade trajectory: Institutional Spaces.
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, with mega-developers eroding traditional wholesale dominance.
- Direct Sales:Mega-developers bypass distribution tiers for volume contracts, enabling margin capture previously lost to wholesale intermediaries. Procurement departments in consolidated developers unbundle after-sales service from product supply.
- Retail Stores:Individual homeowners and small contractors access inventory with immediate availability. Showroom-dependent specifications persist in renovation markets.
- Online Platforms:Digital catalogs with technical documentation serve specification-conscious buyers in secondary cities. Logistics networks limit large-format delivery feasibility.
- Wholesalers:Traditional volume channel retains relevance for fragmented construction subcontractors and regional distributors. Margin compression from direct sales migration pressures this tier.
Highest volume throughput: Wholesalers. Gaining share fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's ceramic tile demand concentrates in coastal manufacturing belts where developer procurement consolidation intersects with tightening emission controls. Provincial policy divergence is redistributing capacity between established hubs and emerging inland zones.
Guangdong Province
Pearl River Delta developers in Shenzhen and Foshan specify large-format porcelain for high-rise residential towers. SAMR emission quotas under dual carbon goals force natural gas switching in legacy kiln networks. Foshan manufacturing clusters absorb compliance costs while defending premium glazed tile output.
Fujian Province
Quanzhou and Xiamen construction markets drive vitrified tile absorption for commercial flooring contracts. MEE air quality benchmarks accelerate dry-press technology adoption among coastal producers. Jinjiang industrial zones host specialized thin-body porcelain lines targeting wall cladding specifications.
Sichuan-Chongqing Region
Chengdu and Chongqing tier-two developers consolidate procurement into standardized packages with strict GB/T 4100 compliance requirements. Provincial emission stringency lags coastal benchmarks, attracting capacity migration from Guangdong. Deyang manufacturing bases expand kiln capacity to serve western China construction growth.
Shandong Province
Qingdao and Jinan institutional projects generate specification pull for low-carbon tile products under GB/T 50378 green building mandates. Zibo ceramic engineering clusters supply technical talent for dry-press process transitions. Northern climate frost-cycle requirements differentiate roof covering demand from southern markets.
Hubei Province
Wuhan mega-developers bypass wholesale channels for direct volume contracts on large-format flooring specifications. Central China location offers logistics advantages to inland construction zones with lower emission quota pressure. Yichang emerging kiln capacity targets developers consolidating procurement across central provinces.
China Ceramic Tiles Market Competitive Environment
Guangdong producers anchor the premium tier; inland specialists hold cost-advantaged positions for commodity-grade output. Market structure bifurcates between consolidated coastal fabricators with vertical kiln networks and fragmented inland operators scaling dry-press capacity. Three archetypes dominate: emission-compliant scale players, thin-body porcelain R&D specialists, and developer-direct contract anchors. Competitive moves center on natural gas kiln retrofits and direct sales channel expansion bypassing wholesale tiers.
Within the scale-driven tier, Guangdong Newpearl Ceramic Group and New Zhongyuan Ceramics occupy positions defined by coastal manufacturing concentration and emission quota access. Dongpeng Ceramic exemplifies the developer-direct archetype through supply contract anchoring with consolidated tier-two city procurement departments. Marco Polo Holdings and Monalisa Group represent specialized differentiation vectors—large-format glazing capabilities and thin-body porcelain R&D intensity respectively—each capturing distinct specification tiers in residential and high-rise cladding verticals.
| Leading Market Players |
|---|
| Guangdong Newpearl Ceramic Group |
| New Zhongyuan Ceramics |
| Dongpeng Ceramic |
| Kito Ceramics |
| Eagle Ceramics |
| Marco Polo Holdings |
| Guanzhu Ceramics |
| Nabel Ceramics |
| Monalisa Group |
| Others |
Value Chain & Pricing Dynamics
Vertical kiln integration across Guangdong and Fujian manufacturing clusters anchors both supply security and pricing power for established producers, while unintegrated competitors absorb margin erosion from natural gas switching costs and spot fuel volatility. This integration choice separates emission-compliant scale players capable of honoring direct developer contracts from fragmented operators forced through wholesale channels with compressed terms.
Pricing Analysis
Volume concentrates in commodity-grade glazed tiles where price differentiation rests on batch scale and logistics proximity, while margins pool in large-format porcelain specifications where GB/T 4100 certification and five-year performance bonds command premium positioning. Pricing pressure stems from sintered stone substitution in premium kitchen and bathroom verticals, eroding vitrified tile price floors. Tier-two city developers exhibit highest price sensitivity through consolidated procurement packages, whereas institutional buyers under GB/T 50378 mandates prioritize documented emission profiles over unit cost.
Supply Chain Analysis
Freight economics from Pearl River Delta kilns to inland construction zones favor regional manufacturing migration, with Hubei and Hunan emerging as alternative supply nodes. Raw material draws from local clay deposits, imported kaolin, and natural gas feedstock. Single-source vulnerability concentrates in Guangdong emission quota allocations, where MEE regulatory shifts could force capacity redistribution. Distribution runs through direct sales channels for mega-developers, while wholesalers retain fragmented subcontractor volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream kiln control and downstream developer-direct relationships determine specification access and margin retention. Players lacking captive firing capacity face displacement as procurement consolidates around fewer suppliers with emission-compliant infrastructure.
For Market Incumbents: To counter sintered stone substitution in premium surfaces, anchor specification status through thin-body porcelain R&D partnerships with super-tall cladding developers and deepen backward integration into kaolin beneficiation to secure formulation consistency under SAMR tightening. For New Entrants and Emerging Players: Capture white-space in central China manufacturing by establishing dry-press capacity in Hubei emission zones with logistics access to Chengdu and Xi'an procurement consolidation, leveraging provincial quota advantages to undercut coastal pricing on standardized large-format contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by emission-compliant scale players seeking regional diversification; long-term viability favors targets with natural gas kiln retrofits complete and direct developer relationships active. Watch MEE provincial quota reallocation announcements as inflection signals for capacity value repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Gas Kiln Retrofit | Secures operating licenses under MEE emission mandates in Guangdong and Fujian clusters. |
| Direct Developer Contract Anchoring | Bypasses wholesale margin compression for tier-two city consolidated procurement volumes. |
| Thin-Body Porcelain R&D Scale-Up | Captures high-rise cladding specifications as structural load requirements tighten. |
| Central China Capacity Migration | Exploits Hubei and Hunan emission quota slack with proximity to inland construction growth. |
| GB/T 50378 Certification Investment | Unlocks institutional specification pull under green building mandates for public projects. |
Study Parameters
Document review covered SAMR regulatory filings, MEE emission quota disclosures, and developer procurement contract structures, complemented by interviews with plant managers at Foshan manufacturing clusters, procurement leads at tier-two city developers, technical R&D directors specializing in dry-press processes, and wholesale distribution channel heads. Secondary validation drew from customs trade data, provincial industrial output statistics, and GB standards documentation. Bottom-up capacity assessments and top-down construction demand projections were triangulated against primary field intelligence.
Cross-referencing historical kiln utilization patterns with panel input from emission compliance officers and natural gas procurement specialists shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type architecture, application performance tier, end-user procurement concentration, and distribution channel structure. CAGRs were derived from slope analysis of capacity-addition timelines against developer pipeline visibility, with specific inputs from provincial dual carbon policy implementation schedules and GB/T 4100 recertification wave impacts.
The model holds under stable MEE enforcement intensity and continued tier-two developer consolidation; deviation in provincial quota reallocation timing or sintered stone cost curves would shift capacity value distributions. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
2N High Purity Alumina Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Mullite Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Technical Ceramics Market
Ceramics
Calcium Silicate Market
Ceramics
Graphite Crucibles Market
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Sodium Aluminum Silicate Market
Ceramics
Global Industrial Clay Market
Ceramics
Construction Ceramics Market
Ceramics
USA and Canada Alumina Market
Ceramics
Ceramic Solid End Mills Market