
 Global Ceramic Membrane Market | 2026-2036
Global Ceramic Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Membrane Market Foresight
The ceramic membrane market is decoupling into two distinct tiers. High-purity pharmaceutical and biotech applications command premium pricing based on validation protocols and material traceability. Pall Corporation leverages its filtration heritage to dominate life-science validation tiers. TAMI Industries anchors European supply through proprietary isostatic pressing capabilities. GEA Group Aktiengesellschaft competes on integrated process-engineering bundles that reduce client commissioning risk.
A ceramic membrane is an inorganic filtration barrier, typically composed of alumina, zirconia, titania, or silicon carbide sintered at temperatures exceeding 1600°C, engineered to separate particles, macromolecules, or ions from fluid streams under thermal and chemical stress that degrades polymer alternatives. Tubular configurations retain the largest installed base in heavy-industrial water treatment due to mechanical durability and backwash tolerance, though flat-sheet formats are gaining share in compact municipal retrofits where footprint constraints dominate project economics. Ultrafiltration and microfiltration technologies represent the mature revenue core, while nanofiltration ceramic systems are emerging as the fastest-growing margin pool for specialty chemical and pharmaceutical purification.
EPA effluent guidelines under the Clean Water Act, EU REACH substance restrictions on persistent chemicals, and China's MEE discharge standards for industrial wastewater collectively tighten compliance thresholds that ceramic membranes reliably satisfy. FDA process-validation requirements and EMA GMP annexes further reinforce adoption in pharmaceutical manufacturing where polymeric extractables pose contamination risks. Stakeholders must monitor evolving PFAS treatment mandates and carbon-border adjustment mechanisms that could redirect capital toward regenerable, thermally stable filtration infrastructure.
Market Dynamics
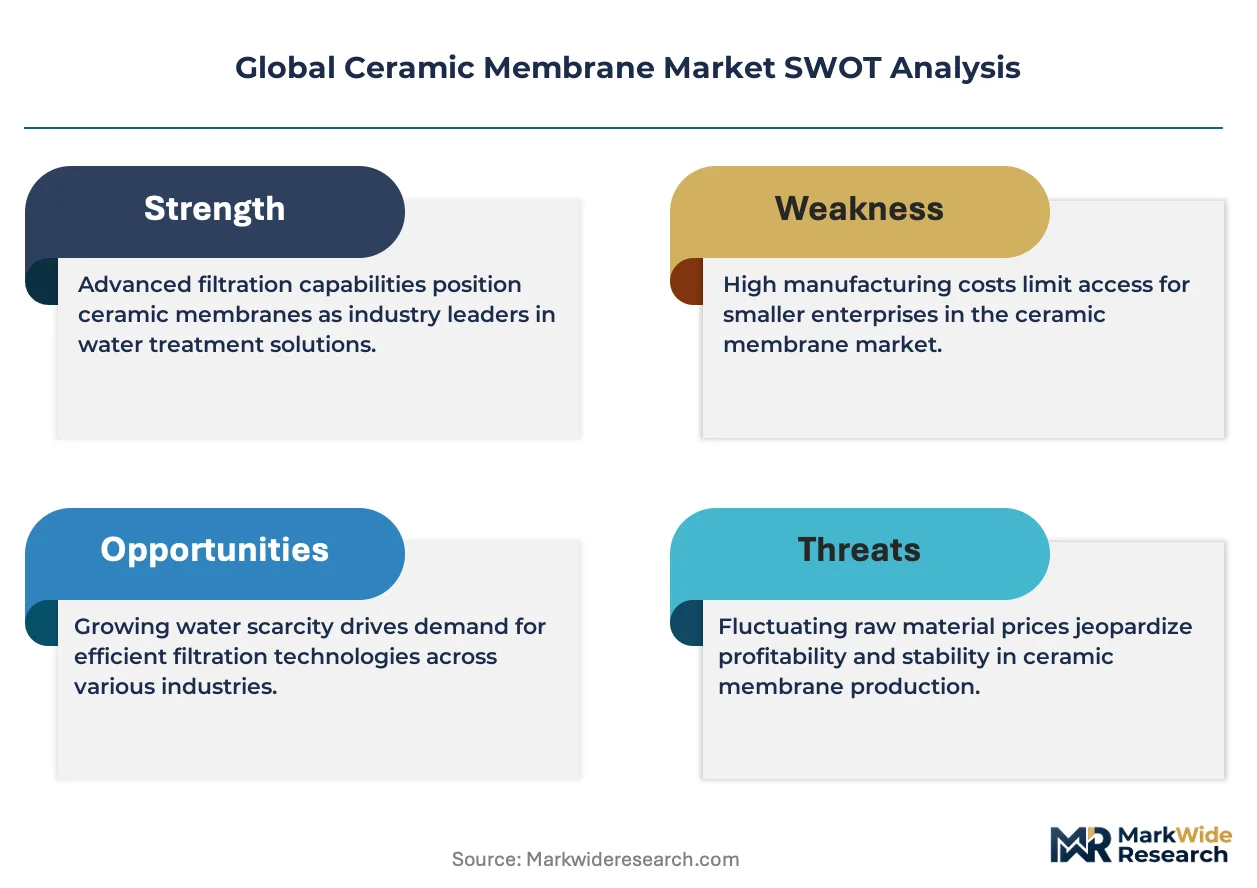
REACH substance restrictions and EPA effluent standards are compressing polymeric membrane lifecycles, forcing utilities and process industries toward thermally regenerable ceramic alternatives despite higher upfront capital requirements.
Growth Catalysts
- MEE discharge standards:China's Ministry of Ecology and Environment mandates near-zero liquid discharge from chemical processing corridors, accelerating ceramic membrane deployment for heavy-metal recovery and brine concentration.
- Pharmaceutical extractables scrutiny:FDA process-validation protocols now explicitly flag polymeric leachables risks in biologics manufacturing, redirecting sterile filtration capital toward alumina and zirconia barrier systems.
- PFAS destruction mandates:Thermal stability requirements for destroying per- and polyfluoroalkyl substances in concentrated waste streams exceed polymer tolerance thresholds, creating pull for silicon carbide membrane concentrators.
Market Restraints
- Energy-intensive sintering:Firing temperatures exceeding 1600°C require natural gas or electricity inputs that fluctuate with European and Asian energy markets, compressing manufacturer margins unpredictably.
- Isostatic press concentration:Large-diameter tubular membrane production depends on cold isostatic pressing capacity concentrated in Germany and Japan, creating supply bottlenecks during demand surges.
- Capital intensity gap:Installed ceramic systems cost three to five times equivalent polymeric area on a membrane-only basis, extending payback periods beyond municipal budget cycles.
Strategic Opportunities
- India's pharmaceutical corridor:CDSCO's alignment with ICH Q5A viral safety guidelines creates validation-ready demand for ceramic virus filtration in Hyderabad and Ahmedabad biologics clusters.
- Hydrogen economy electrolyte purification:Alkaline and PEM electrolyzer manufacturers require ultrapure KOH and water loops where ceramic nanofiltration eliminates ionic contaminants that poison catalyst layers.
- EU Carbon Border Adjustment Mechanism:CBAM scope expansion to embodied process emissions rewards durable, regenerable filtration infrastructure over disposable polymer cartridges in import-competing industries.
Industry Challenges
- Commissioning complexity:Ceramic membrane skids require specialized start-up protocols for flux stabilization and chemical cleaning optimization that exceed typical water treatment contractor capabilities.
- Cross-contamination documentation:Multi-product biopharma facilities face extended validation timelines when switching ceramic membrane trains between monoclonal antibody and vaccine campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Membrane Market |
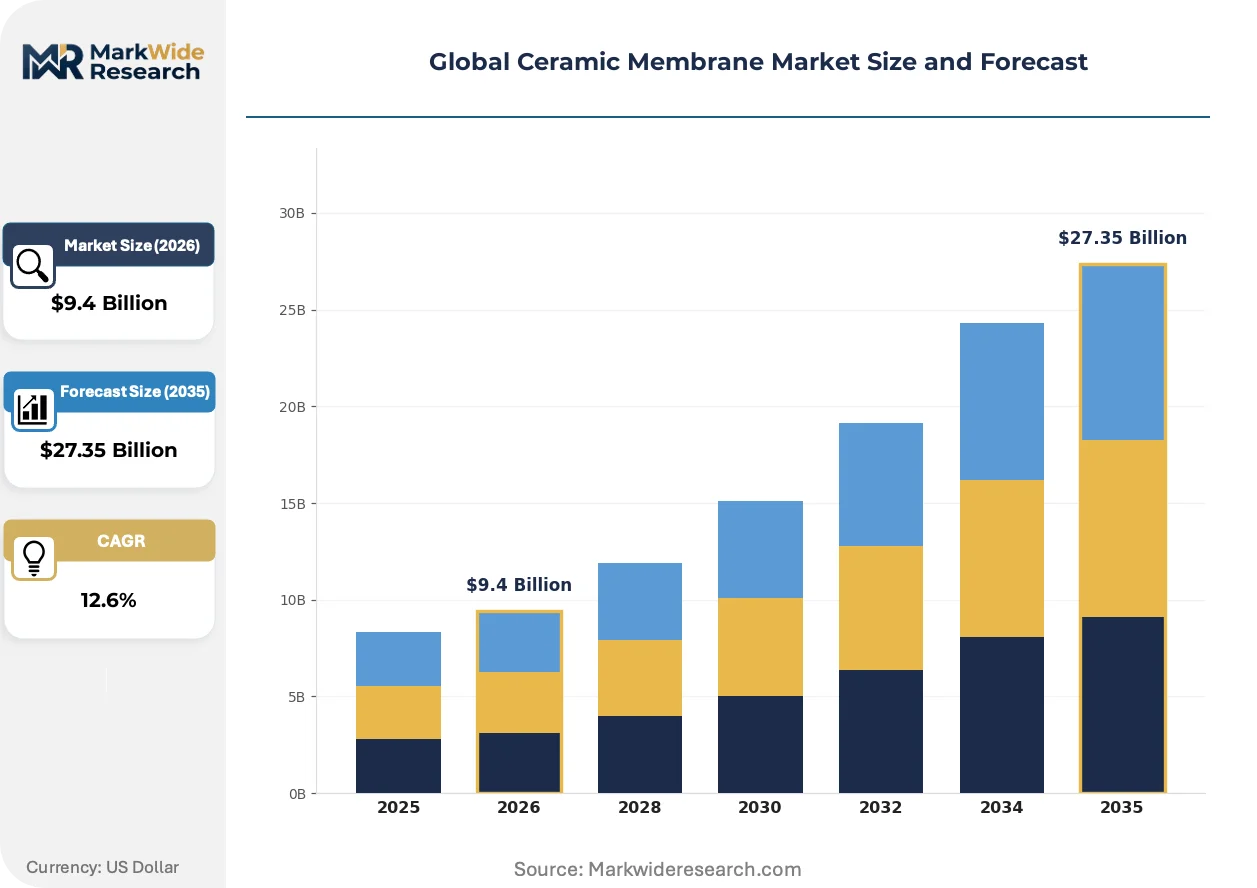
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $27.35 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubular, Flat Sheet, Hollow Fiber, Capillary Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis, Forward Osmosis Application: Water Treatment, Food & Beverage Processing, Pharmaceuticals, Chemical Processing, Pulp & Paper End User: Municipal Suppliers, Beverage Producers, Biotech Companies, Specialty Chemical Makers, Paper Manufacturers |
| Companies Covered | Pall Corporation, TAMI Industries, GEA Group Aktiengesellschaft, Veolia, LiqTech Holding A/S, JIUWU HI-TECH Membrane Technology, METAWATER Co., Ltd., atech innovations GmbH, Nanostone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Membrane Market Shifts & Advancements
Digital layer deposition and hybrid organic-inorganic surface modification are compressing the performance gap between ceramic durability and polymer selectivity, while regulatory chemistry restrictions accelerate material substitution timelines.
Atomic layer deposition of titanium dioxide and alumina nano-layers onto porous ceramic substrates is integrating molecular sieving precision with mechanical robustness. Biopharma manufacturers in Switzerland and Massachusetts are piloting these modified membranes for continuous monoclonal antibody capture. The technology is integrating chromatography and filtration unit operations into single-step intensified processes that reduce facility footprint by half.
EU REACH Annex XVII restrictions on perfluorinated substances are eliminating PTFE and PVDF membrane options from semiconductor and chemical process applications. German and Dutch wafer fabrication facilities now specify silicon carbide ultrafiltration for CMP slurry recovery to preempt supply disruption. Equipment suppliers are responding with standardized modular skids that accelerate regulatory compliance documentation.
Performance-based service contracts are displacing capital purchase models in municipal water treatment. French and Singaporean utilities now procure treated water volumes rather than membrane assets, transferring operational risk to technology providers. This restructuring concentrates procurement authority among engineering firms with integrated lifecycle capabilities, marginalizing component-only vendors.
Global Ceramic Membrane Market Segmentation
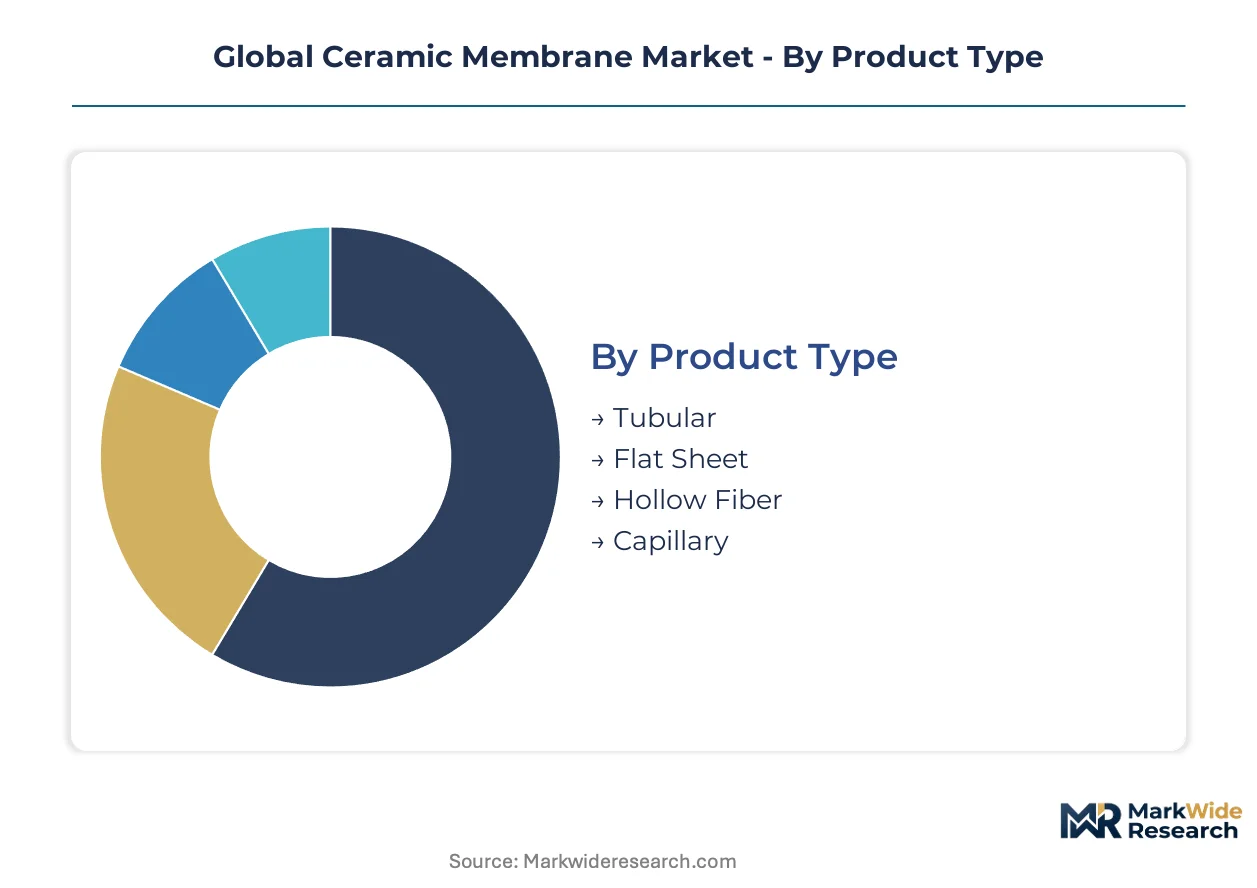
Ceramic membrane procurement decisions pivot on thermal tolerance requirements, footprint constraints, and validation protocols that vary sharply across industrial verticals. Segmentation reveals where capital concentrates versus where technology shifts are accelerating.
Product Type:
Tubular configurations demand the highest upfront engineering investment due to isostatic pressing requirements and specialized sintering infrastructure.
- Tubular:Cylindrical channels extruded from alumina or silicon carbide withstand aggressive backwash cycles and high suspended solids loading. Germany's Rhine-Ruhr water utilities and Singapore's NEWater facilities specify large-diameter tubular arrays for tertiary filtration reliability under continuous operation.
- Flat Sheet:Thin planar membranes stacked in plate-and-frame modules minimize footprint for municipal retrofits where building envelope constraints dominate project economics. Japanese semiconductor fabs in Kumamoto and Hiroshima deploy flat-sheet silicon carbide for CMP slurry recovery to satisfy REACH precursor restrictions on fluorinated polymers.
- Hollow Fiber:Self-supporting filament bundles offer high surface-area-to-volume ratios for compact bioprocessing skids. Biotech manufacturers in Basel and Boston pilot these for continuous monoclonal antibody capture.
- Capillary:Fine-bore tubular variants bridge hollow fiber selectivity with tubular mechanical durability for specialty chemical separations.
Tubular absorbs the bulk of installed capacity; flat sheet is expanding most quickly.
Technology:
Filtration precision directly correlates with membrane manufacturing complexity and end-use validation requirements.
- Microfiltration:Pore sizes of 0.1 to 10 micrometers target bacteria and suspended solids removal in food and beverage clarification. Italian prosecco producers and California wineries deploy alumina microfiltration to replace diatomaceous earth filtration and eliminate powder handling hazards.
- Ultrafiltration:1 to 100 nanometer separation thresholds retain viruses, proteins, and macromolecules. China's Ministry of Ecology and Environment mandates ultrafiltration pretreatment for zero-liquid-discharge chemical corridors in Jiangsu and Shandong provinces.
- Nanofiltration:Divalent ion and small organic rejection capabilities address pharmaceutical solvent recovery and lithium brine concentration. Swiss and Massachusetts biopharma facilities pilot atomic-layer-deposited nanofiltration for integrated capture-chromatography processes.
- Reverse Osmosis:Dense ceramic layers for desalination remain developmental due to flux limitations relative to polyamide thin-film composites.
- Forward Osmosis:Osmotic pressure-driven concentration for high-salinity brines exploits ceramic chemical stability where polymer draw solutes would degrade.
Ultrafiltration dominates current revenue contribution; nanofiltration climbs the fastest as pharmaceutical validation protocols mature.
Application:
Regulatory chemistry restrictions and discharge standards are redirecting capital across application verticals at unequal rates.
- Water Treatment:Municipal and industrial tertiary filtration, brine concentration, and heavy-metal recovery. Singapore's PUB and Germany's municipal utilities standardize ceramic membranes for regenerable, thermally stable barrier performance.
- Pharmaceuticals:Sterile filtration, virus removal, and continuous bioprocessing under FDA process-validation protocols. CDSCO alignment with ICH Q5A in Hyderabad and Ahmedabad biologics clusters validates ceramic adoption.
- Food & Beverage Processing:Clarification, concentration, and microbial stabilization without thermal degradation. Japanese sake brewers and French dairy cooperatives specify zirconia barriers for flavor preservation.
- Chemical Processing:Solvent recovery, catalyst retention, and aggressive media separation. Dutch and German semiconductor fabs specify silicon carbide for CMP slurry loops ahead of EU REACH Annex XVII enforcement.
- Pulp & Paper:Whitewater clarification and coating recovery in closed-loop mill systems.
Water treatment commands the largest installed base; pharmaceuticals is gaining share fastest on extractables scrutiny.
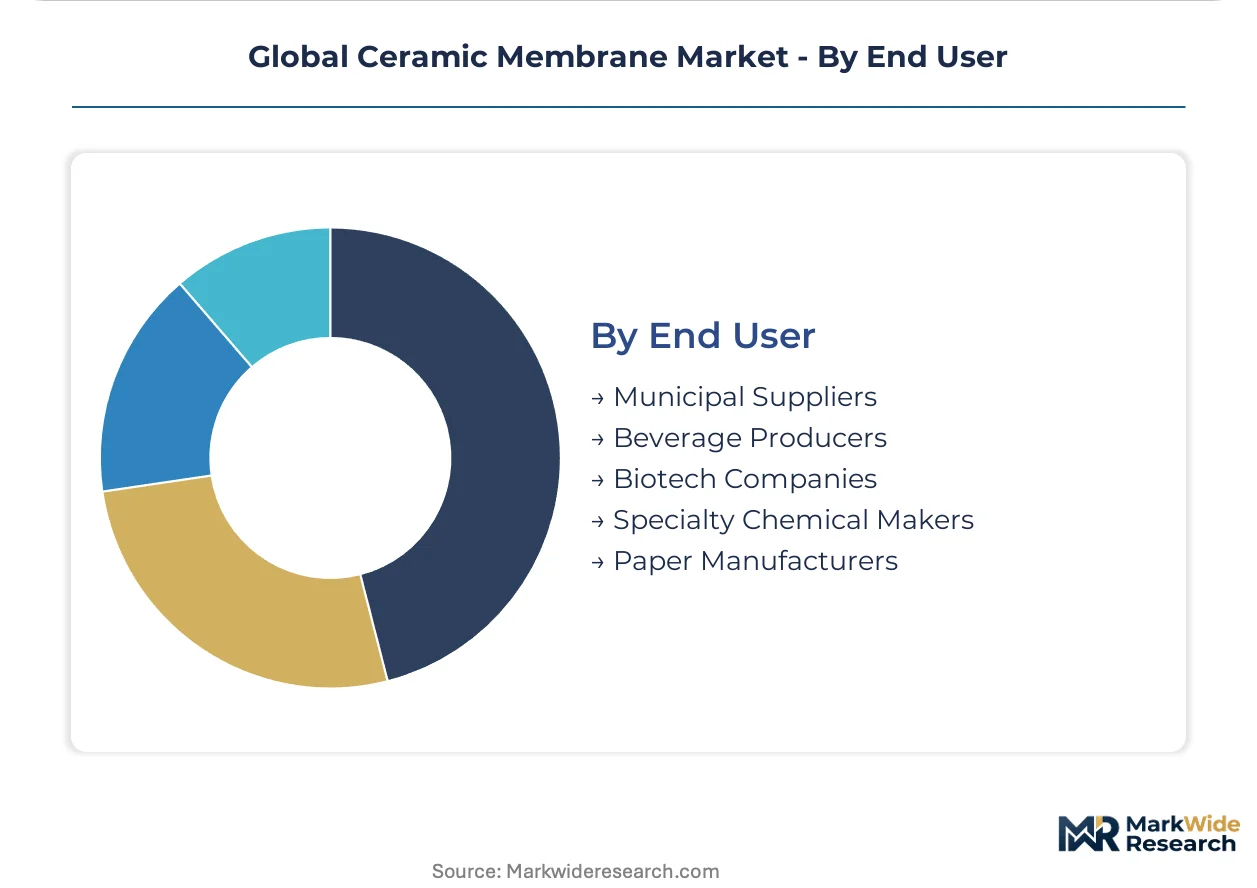
End User:
Procurement authority concentrates among engineering firms with integrated lifecycle capabilities as performance-based contracts displace component sales.
- Municipal Suppliers:Water and wastewater utilities procuring treated water volumes rather than membrane assets. French and Singaporean operators transfer operational risk to technology providers through long-term service agreements.
- Biotech Companies:Monoclonal antibody and vaccine manufacturers under FDA and EMA GMP annexes. Extended validation timelines challenge multi-product facilities switching membrane trains between campaigns.
- Beverage Producers:Wineries, breweries, and spirits distillers seeking clarification without fining agents or thermal processing.
- Specialty Chemical Makers:Fine chemical and electronic materials manufacturers requiring corrosion-resistant filtration for high-purity process streams.
- Paper Manufacturers:Integrated mills recovering coating pigments and clarifying whitewater in closed-loop systems.
Municipal suppliers anchor procurement volume; biotech companies are expanding most quickly on viral safety validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's NEWater facilities anchor municipal ceramic membrane deployment, while Germany's Rhine-Ruhr utilities and China's Jiangsu chemical corridor drive industrial adoption under tightening discharge mandates.
Germany
Rhine-Ruhr municipal utilities specify large-diameter tubular membranes for tertiary filtration reliability. ECHA REACH Annex XVII restrictions on perfluorinated substances eliminate PTFE alternatives from semiconductor applications. Wafer fabrication facilities in Dresden and Munich now standardize silicon carbide ultrafiltration for CMP slurry recovery.
China
MEE discharge standards mandate near-zero liquid discharge from chemical processing corridors in Jiangsu and Shandong provinces. GB standards for industrial wastewater tighten compliance thresholds that ceramic membranes reliably satisfy. Zhengzhou and Xi'an industrial clusters deploy ultrafiltration pretreatment for heavy-metal recovery and brine concentration.
United States
EPA effluent guidelines under the Clean Water Act compress polymeric membrane lifecycles in municipal utilities. FDA process-validation protocols redirect sterile filtration capital toward alumina barriers in Boston and San Francisco biologics clusters. Massachusetts facilities pilot atomic-layer-deposited nanofiltration for continuous monoclonal antibody capture.
India
CDSCO alignment with ICH Q5A viral safety guidelines validates ceramic virus filtration demand. Hyderabad and Ahmedabad biologics clusters expand sterile filtration capacity under GMP annex requirements. Maharashtra and Gujarat pharmaceutical corridors commission validation-ready membrane trains for multi-product facilities.
Switzerland
Swissmedic process-validation requirements reinforce adoption where polymeric extractables pose contamination risks. Basel biotech manufacturers deploy hollow fiber configurations for continuous bioprocessing skids. Swiss atomic layer deposition expertise integrates molecular sieving precision with mechanical robustness for chromatography-filtration integration.
Global Ceramic Membrane Market Competitive Landscape
Capital-heavy isostatic pressing specialists compete with asset-light membrane designers and integrated engineering bundlers. The vendor base stratifies across three tiers: premium validation-grade suppliers serving FDA-regulated biopharma, mid-tier water treatment specialists, and regional fabricators competing on delivered cost. Dominant competitive moves include backward integration into sintering capacity and performance-based service contracts that displace component sales.
Within the premium validation tier, Pall Corporation and TAMI Industries occupy positions defined by heritage filtration expertise and proprietary pressing capabilities respectively. GEA Group Aktiengesellschaft exemplifies the integrated-engineering archetype, bundling process design with membrane supply to reduce client commissioning risk. JIUWU HI-TECH Membrane Technology and METAWATER Co., Ltd. anchor Asian supply positions, while atech innovations GmbH and Nanostone represent specialized regional fabricators with concentrated geographic footprints.
| Leading Market Players |
|---|
| Pall Corporation |
| TAMI Industries |
| GEA Group Aktiengesellschaft |
| Veolia |
| LiqTech Holding A/S |
| JIUWU HI-TECH Membrane Technology |
| METAWATER Co., Ltd. |
| atech innovations GmbH |
| Nanostone |
| Others |
Supply & Pricing Matrix
Atomic layer deposition adoption for nanofiltration surface modification simultaneously compresses manufacturing yields and concentrates premium-tier supply among German and Swiss coating specialists with captive ALD infrastructure. This dual effect reshapes cost economics for validation-grade membranes while tightening procurement options for pharmaceutical end-users.
Pricing Analysis
Throughput-guarantee contracts now anchor ceramic membrane pricing, with municipal utilities in Singapore and France procuring treated water volumes rather than membrane assets. Pricing stratifies across FDA-validated biopharma tiers, REACH-compliant industrial grades, and standard water treatment specifications. Cost compression in municipal segments intensifies because polymeric alternatives compete on upfront capital, while pharmaceutical buyers show lowest price sensitivity due to extractables liability exposure.
Supply Chain Analysis
China's domestic-content mandates for zero-liquid-discharge infrastructure are reshaping sourcing patterns for Jiangsu and Shandong chemical corridors. Cold isostatic pressing capacity draws from Germany and Japan, while high-purity alumina and zirconia feedstocks rest on Australian and Chinese mining outputs. Single-source vulnerability concentrates in large-diameter tubular production, where isostatic press utilization rates exceed 85%. Distribution runs through integrated engineering firms bundling process design with membrane supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceramic membrane market is becoming a vertical-integration race, with sintering capacity and isostatic press control as the decisive upstream lever separating premium validation suppliers from component-only vendors.
For Market Incumbents: Extend backward into isostatic pressing capacity to secure large-diameter tubular supply during demand surges from China's MEE discharge mandates. Consolidate around performance-based service contracts that transfer operational risk from municipal buyers, neutralizing price competition from polymeric alternatives in water treatment segments. For New Entrants and Emerging Players: Launch via modular skid partnerships with hydrogen electrolyzer manufacturers requiring ultrapure KOH loops, bypassing entrenched positions in municipal water. India's pharmaceutical corridor offers the most penetrable white space, where CDSCO alignment with ICH Q5A creates validation-ready demand without incumbent lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated engineering conglomerates seeking membrane capabilities for bundled process offerings. Five-to-ten-year viability favors specialists with captive sintering and ALD surface modification infrastructure. Watch PFAS destruction mandate implementation as the signal for silicon carbide concentrator demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isostatic Pressing | Captive large-diameter tubular capacity secures supply during China MEE-driven demand surges. |
| Atomic Layer Deposition Scale-Up | Swiss and German ALD expertise enables nanofiltration premium pricing in biopharma validation tiers. |
| Performance-Based Service Contracts | French and Singaporean utilities transfer operational risk, concentrating procurement among integrated engineering firms. |
| Hydrogen Economy Electrolyte Partnerships | Alkaline and PEM electrolyzer manufacturers require ceramic nanofiltration for catalyst-layer protection. |
| India Pharmaceutical Corridor Entry | Hyderabad and Ahmedabad biologics clusters validate ceramic virus filtration under CDSCO-ICH Q5A alignment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving water utility procurement directors, pharmaceutical process engineers, ceramic membrane plant managers, and semiconductor fab facilities managers. ECHA REACH Annex XVII updates, EPA effluent guideline revisions, and China's MEE discharge standard notifications provided regulatory trajectory inputs. Bottom-up capacity assessments triangulated against top-down spend analysis across municipal, pharmaceutical, and chemical processing verticals.
Segmentation granularity modeled product type, filtration technology, application vertical, and end-user procurement authority across the projection horizon. CAGRs derived from installed base expansion rates, replacement cycle compression, and regulatory-driven substitution elasticities. Hydrogen electrolyzer deployment schedules and EU Carbon Border Adjustment Mechanism scope expansion served as demand-side forecast inputs.
Energy price volatility, isostatic press capacity bottlenecks, and polymeric membrane cost breakthroughs are the dominant revision risks to modeled outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Global Membrane Filters Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Membranes Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Global Membrane Separation Technology Market