
 Thermal Spray Powder Market | 2026-2036
Thermal Spray Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Spray Powder Market Outlook
Aftermarket service revenue is narrowing as powder suppliers integrate closer to end-user coating operations. Oerlikon Metco leverages its vertical equipment-powder-service portfolio to capture lifecycle value. Praxair Surface Technologies anchors North American aerospace demand through captive gas supply and powder formulation expertise. Kennametal Inc competes on carbide chemistry leadership for erosion-resistant industrial applications.
Thermal spray powder comprises engineered particulate feedstock, typically 10-150 microns in diameter, manufactured via atomization, sintering, or fusion-crushing routes for deposition onto substrates via high-velocity thermal streams. These powders form protective coatings against wear, corrosion, and thermal fatigue in rotating machinery and structural components. Metal powders occupy the largest volume share across aerospace and industrial machinery applications where ductility and thermal conductivity prove critical. Ceramic powders, particularly yttria-stabilized zirconia, command premium positioning in turbine hot-section coatings where thermal barrier performance dictates engine efficiency. HVOF technology segments are gaining traction for carbide deposition in oilfield and pump applications demanding dense, low-porosity coatings.
EPA emissions standards and OSHA workplace exposure limits constrain powder handling and spray booth operations in the US, while REACH registration requirements govern chemical composition disclosure across European supply chains. FAA airworthiness directives and EASA certification protocols shape material qualification timelines for aerospace-grade powders, creating barrier-to-entry effects for non-approved suppliers. Stakeholders must monitor evolving dual-carbon regulations in China and the EU Green Deal's embodied-carbon tracking requirements, as these frameworks will increasingly determine powder sourcing decisions and coating process eligibility in cross-border equipment trade.
Market Dynamics
REACH compliance deadlines and EPA emissions rules are compressing formulation timelines while OEMs demand extended component life cycles, forcing powder suppliers to requalify chemistries under tighter toxicology standards without disrupting aerospace certification schedules.
Growth Catalysts
- HVOF carbide deposition:Oilfield equipment operators in Texas and Alberta specify dense tungsten carbide coatings for pump plungers and valve gates, extending mean time between overhauls in abrasive drilling mud environments.
- FAA airworthiness directives:Turbine hot-section refurbishment mandates drive yttria-stabilized zirconia consumption for thermal barrier coatings on legacy engine fleets requiring compliance with updated blade life limits.
- Germany's precision engineering belt:Industrial clusters around Stuttgart and Munich source specialized cermet powders for tool and die refurbishment, concentrating demand for high-purity feedstock with tight particle size distributions.
Market Restraints
- Cobalt and nickel price volatility:Carbide matrix binders fluctuate with battery sector competition for Class I nickel, squeezing margin stability for erosion-resistant coating formulations.
- Plasma spray equipment oligopoly:Three European and Japanese OEMs control high-throughput torch architecture, limiting buyer negotiating leverage for production line expansions.
- Substitution by laser cladding:Directed energy deposition systems achieve comparable wear resistance with thicker single-pass deposits, threatening HVOF market share in shaft repair applications.
Strategic Opportunities
- India's defense indigenization:The country's PLI scheme for aerospace components creates captive coating demand for helicopter transmission gears and turbine blades under import substitution mandates.
- EU Green Deal embodied-carbon tracking:Coatings qualifying for low-carbon process certification gain preferential sourcing in cross-border wind turbine component trade.
- Cold spray convergence with robotics:Portable deposition systems enable in-situ repair of aluminum helicopter gearboxes without disassembly, opening field service revenue streams.
Industry Challenges
- Certification timeline compression:EASA and FAA material qualification protocols require 18-36 months for new alloy chemistries, lagging OEM product development cycles for next-generation turbine architectures.
- Feedstock contamination control:Ceramic powder moisture absorption during ocean freight degrades plasma spray deposit porosity, demanding nitrogen-purged container investments and port-side testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Spray Powder Market |
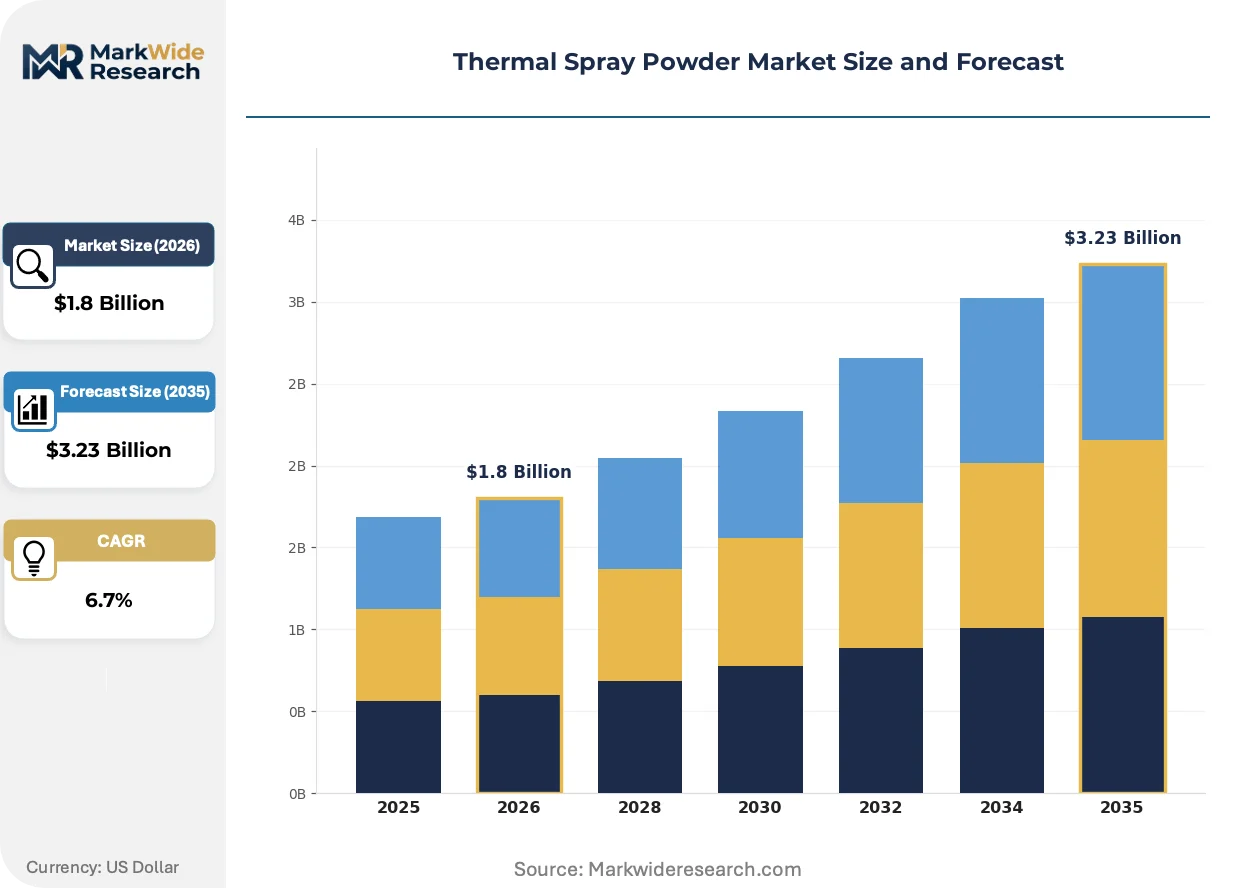
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Powders, Metal Powders, Composite Powders, Carbide Powders Application: Aerospace Coatings, Industrial Machinery, Automotive Components, Medical Devices Technology: Plasma Spraying, Flame Spraying, HVOF, Cold Spraying End User: Manufacturing, Defense, Energy, Electronics |
| Companies Covered | Oerlikon Metco, Praxair Surface Technologies, Kennametal Inc, H.C. Starck GmbH, Höganäs AB, Sulzer Ltd, Saint-Gobain, Wall Colmonoy, Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Spray Powder Market Strategic Shifts
Formulation chemistry and deposition control systems are converging to enable thinner, functionally graded coatings that substitute for solid superalloy components in rotating machinery.
Hypersonic flame spray technology is migrating from experimental turbine blade repair toward production-scale oilfield pump coating, as Baker Hughes and Schlumberger specifications now accept HVOF tungsten carbide for rod couplings previously requiring chrome plating. Equipment OEMs Sulzer Metco and GTV are shipping multi-axis robotic cells to Permian Basin service shops, compressing the technician-to-coating ratio from three operators per booth to one per two cells.
REACH Annex XIV authorization requirements for cobalt compounds are forcing reformulation of WC-Co cermets toward iron-based matrices, with ECHA's 2025 sunset date for uncontrolled cobalt use accelerating R&D spending across European powder producers. The regulatory friction hits aerospace suppliers hardest, as FAA qualification of new binder chemistries requires engine test cell runs that add fourteen months to product launch timelines.
Buying committees at major airlines now unbundle coating procurement from OEM engine overhaul contracts, directly negotiating powder supply agreements with Praxair and Oerlikon to capture material cost transparency previously hidden in lump-sum shop visit pricing. This disintermediation concentrates in North American and Middle Eastern MRO facilities where engine leasing companies exert procurement leverage over independent overhaul shops.
Thermal Spray Powder Market Segmentation
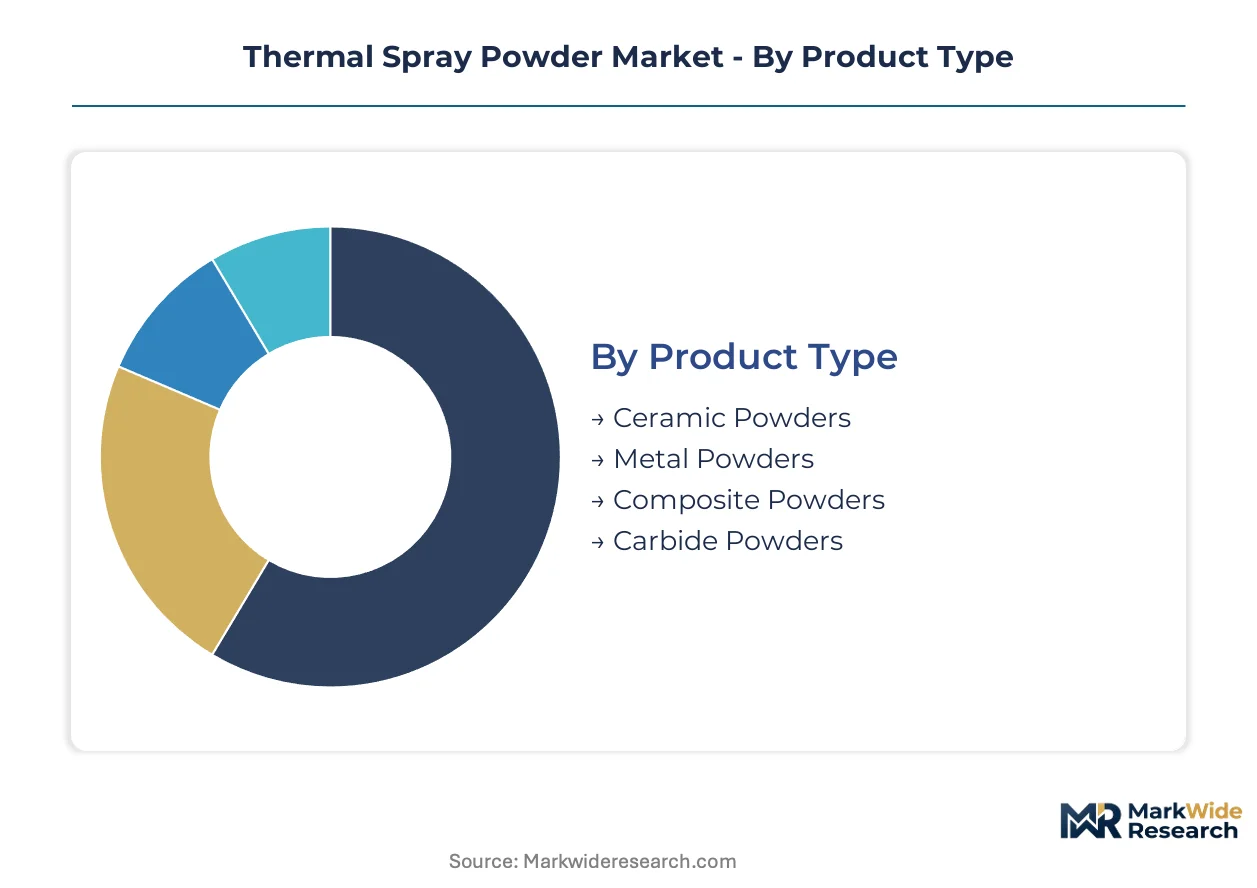
Thermal spray powder segmentation reveals how material properties, deposition physics, and end-use certification requirements create distinct commercial battlegrounds. Each dimension carries different margin profiles, qualification timelines, and supply chain complexity that shape supplier strategy.
Product Type:
Cost tier determines formulation complexity and regulatory exposure across the four material families.
- Metal Powders:Nickel, cobalt, and aluminum alloys offer ductility and thermal conductivity for dimensional restoration and corrosion barriers. Demand concentrates in aerospace engine refurbishment where FAA airworthiness directives mandate specific alloy chemistries for blade and vane repair, creating long qualification backlogs for new suppliers.
- Ceramic Powders:Yttria-stabilized zirconia and alumina variants provide thermal insulation and dielectric properties. German precision engineering clusters around Stuttgart source high-purity ceramic feedstock with tight particle size distributions for turbine hot-section coatings where thermal barrier performance dictates engine efficiency.
- Carbide Powders:Tungsten carbide-cobalt composites dominate erosion-resistant industrial applications in oilfield equipment.
- Composite Powders:Cermet blends combine ceramic hardness with metallic toughness for intermediate wear scenarios.
Metal powders hold installed capacity. Ceramic powders are rotating up the share rankings.
Application:
Application scope maps directly to certification burden and aftermarket service attach rates.
- Aerospace Coatings:Thermal barrier, abradable seal, and wear-resistant deposits on turbine blades, combustors, and landing gear. North American and Middle Eastern MRO facilities now unbundle powder procurement from OEM overhaul contracts, with airlines negotiating direct supply agreements to capture material cost transparency.
- Industrial Machinery:Pump plungers, valve gates, and shaft restoration in abrasive process environments. Texas and Alberta oilfield operators specify dense tungsten carbide coatings for drilling mud exposure, extending mean time between overhauls.
- Automotive Components:Piston ring coatings and transmission part restoration for thermal and friction management.
- Medical Devices:Hydroxyapatite and biocompatible metal coatings for orthopedic implants requiring FDA and EMA device master file cross-referencing.
Aerospace coatings hold installed capacity. Industrial machinery is rotating up the share rankings.
Technology:
Deposition velocity and flame temperature separate the four process families into distinct equipment and powder specification ecosystems.
- HVOF:High-velocity oxy-fuel combustion achieves supersonic particle velocities for dense, low-porosity carbide deposits. Baker Hughes and Schlumberger specifications now accept HVOF tungsten carbide for rod couplings previously requiring chrome plating, expanding from experimental repair to production-scale oilfield deployment.
- Plasma Spraying:Electric arc-generated plasma streams melt ceramic and refractory materials for thermal barrier coatings. Three European and Japanese OEMs control high-throughput torch architecture, limiting buyer negotiating leverage for production line expansions.
- Flame Spraying:Combustion-based deposition for lower-cost metallic and polymer coatings on non-critical components.
- Cold Spraying:Solid-state particle acceleration without melting enables in-situ repair of aluminum helicopter gearboxes without disassembly, opening field service revenue streams through portable robotic systems.
Plasma spraying holds installed capacity. HVOF is rotating up the share rankings.
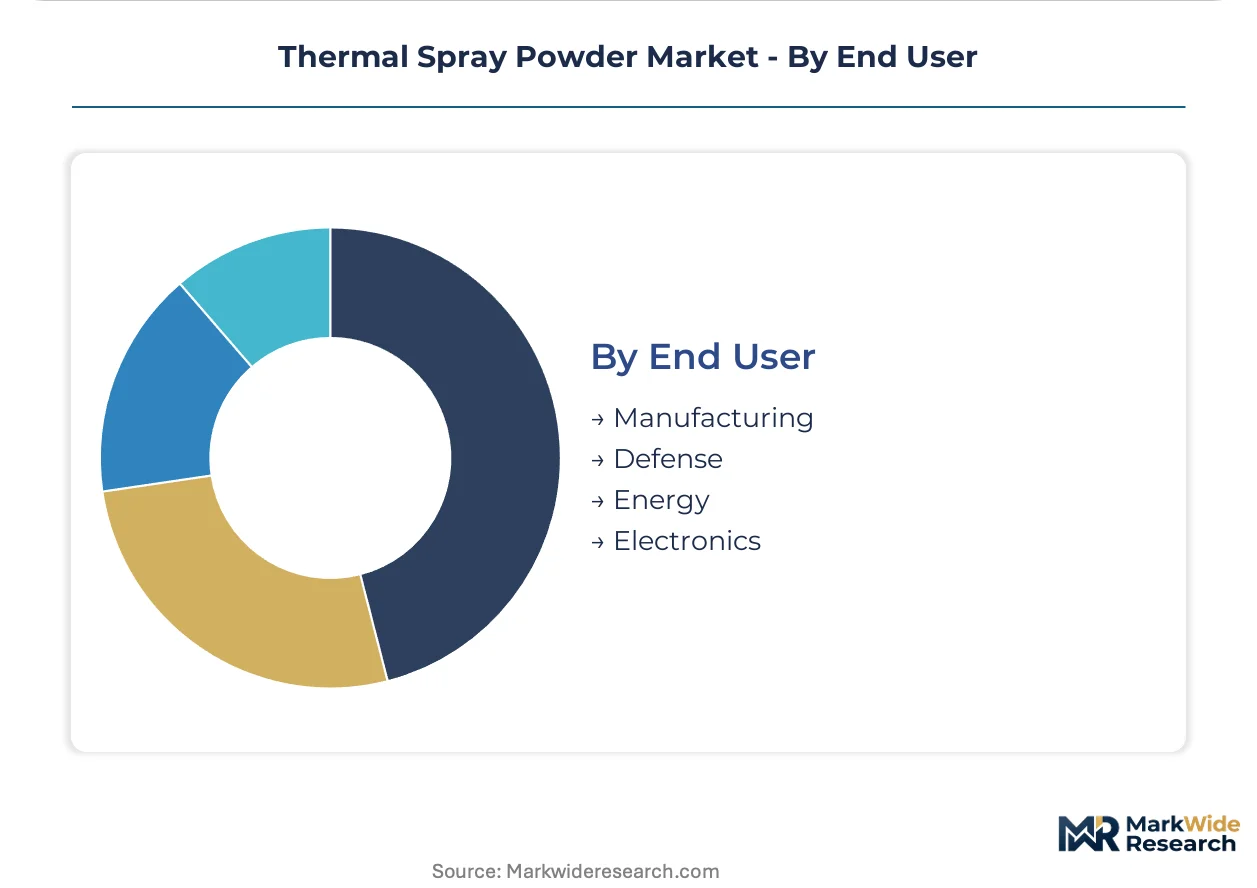
End User:
Customer type dictates procurement centralization, specification authority, and lifecycle service integration depth.
- Defense:Military aviation and naval propulsion systems require ITAR-controlled supply chains and long-term strategic stockpiles. India's PLI scheme for aerospace components creates captive coating demand for helicopter transmission gears and turbine blades under import substitution mandates.
- Energy:Gas turbine power generation and wind turbine drivetrain protection drive recurring refurbishment demand. EU Green Deal embodied-carbon tracking gives preferential sourcing to low-carbon process certification in cross-border wind component trade.
- Manufacturing:General industrial maintenance and OEM component production across fragmented tooling and machinery bases.
- Electronics:Semiconductor fabrication equipment and electromagnetic shielding applications with extreme purity requirements.
Manufacturing holds installed capacity. Defense is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal spray powder consumption patterns diverge sharply across geographies: German industrial clusters prioritize precision-engineered cermet formulations for tool refurbishment, while North American aerospace MROs drive yttria-stabilized zirconia volumes through direct procurement unbundling.
United States
FAA airworthiness directives on turbine blade life limits sustain yttria-stabilized zirconia demand for thermal barrier coatings. EPA emissions standards and OSHA workplace exposure limits constrain powder handling operations in spray booth environments. Texas oilfield service shops around Midland-Odessa specify dense HVOF tungsten carbide for pump plungers exposed to abrasive drilling mud.
Germany
Precision engineering clusters near Stuttgart and Munich source specialized carbide powders with tight particle size distributions for turbine refurbishment. REACH Annex XIV authorization deadlines for cobalt compounds force WC-Co cermet reformulation toward iron-based matrices before ECHA's 2025 sunset date. The country's industrial belt concentrates demand for high-purity feedstock serving tool and die restoration.
China
Dual-carbon regulations and embodied-carbon tracking requirements under the EU Green Deal reshape powder sourcing decisions for wind turbine component exports. MIIT industrial standards govern thermal spray process certification for domestic gas turbine refurbishment. Yangtze River Delta manufacturing hubs integrate coating operations closer to end-user production lines.
India
The PLI scheme for aerospace components generates captive coating demand for helicopter transmission gears and turbine blades under import substitution mandates. DGFT trade policies regulate powder feedstock imports for defense aviation applications. Bangalore-Hyderabad aerospace clusters develop indigenous qualification protocols parallel to FAA and EASA timelines.
Saudi Arabia
Gas turbine power generation expansion in the Eastern Province drives recurring refurbishment demand for thermal barrier coatings. SFDA and national industrial regulators align powder import specifications with international aviation standards. Jubail industrial city hosts coating service operations tied to petrochemical rotating machinery maintenance.
Thermal Spray Powder Market Competitive Environment
Capability concentration sits with specialized powder chemists; scale advantage sits with diversified materials conglomerates. The vendor base stratifies across three tiers: integrated equipment-powder-service portfolios, captive gas supply with formulation expertise, and carbide chemistry specialists for erosion-resistant industrial applications. Dominant competitive moves include backward integration into atomization capacity and strategic partnerships with robotic deposition system OEMs.
Within the integrated portfolio tier, Oerlikon Metco exemplifies vertical control spanning torch equipment, feedstock formulation, and coating services. Praxair Surface Technologies anchors North American aerospace positioning through captive industrial gas supply chain integration. Kennametal Inc occupies the carbide chemistry specialist archetype, with tungsten carbide-cobalt composite expertise serving oilfield and industrial machinery wear applications.
| Leading Market Players |
|---|
| Oerlikon Metco |
| Praxair Surface Technologies |
| Kennametal Inc |
| H.C. Starck GmbH |
| Höganäs AB |
| Sulzer Ltd |
| Saint-Gobain |
| Wall Colmonoy |
| Linde plc |
| Others |
Value Chain & Pricing Dynamics
Chinese atomization capacity for nickel and cobalt-based superalloy powders concentrates upstream margin capture, while North American and European coating service providers retain downstream pricing power through FAA-qualified formulation expertise and captive gas supply integration.
Pricing Analysis
Long-term offtake contracts dominate aerospace-grade powder procurement, with airlines and engine MROs negotiating direct supply agreements to unbundle material costs from OEM overhaul pricing. Price differentiation separates FAA-qualified chemistries from industrial-grade feedstock, with certification timelines and REACH compliance costs widening the premium gap. Pricing pressure stems from cobalt and nickel volatility driven by battery sector competition, squeezing margin stability for carbide matrix formulations. Industrial machinery buyers exhibit highest price sensitivity, while defense and aerospace procurement committees prioritize qualification status over unit cost.
Supply Chain Analysis
Upstream feedstock for thermal spray powders draws from Chinese atomization plants, German sintering facilities, and North American fusion-crushing operations, with tungsten carbide feedstock anchored in Chinese and Russian mining concentration. Critical dependencies include cobalt from the DRC, nickel from Indonesia and the Philippines, and yttria from Chinese rare earth processing. Supply chain risk centers on single-source vulnerability for aerospace-qualified atomization capacity and ECHA authorization timelines for cobalt compound restrictions. Distribution runs through regional coating service hubs in Texas, Germany's industrial belt, and the Yangtze River Delta, with powder suppliers integrating closer to end-user deposition operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating service revenue layers are expanding faster than hardware sales as powder suppliers integrate deposition operations and field repair capabilities, transforming transactional feedstock supply into recurring lifecycle contracts.
For Market Incumbents: Pre-empt laser cladding substitution in shaft repair applications by accelerating HVOF robotics deployment and qualifying thinner, functionally graded coating architectures. Defend aerospace margin pools through backward integration into atomization capacity and exclusive long-term offtake agreements with nickel and cobalt refiners. Lock in certification timelines with FAA and EASA for next-generation binder chemistries before REACH sunset dates force reformulation.
For New Entrants and Emerging Players: India's defense indigenization under the PLI scheme offers the most penetrable white-space target, with captive demand for helicopter transmission gear and turbine blade coatings outpacing domestic qualification capacity. Target cold spray convergence with robotics for in-situ aluminum gearbox repair, where portable deposition systems bypass established plasma spray infrastructure. Partner with regional robotic OEMs to sidestep the European-Japanese equipment oligopoly controlling high-throughput torch architecture.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized carbide chemists with tungsten carbide-cobalt formulation expertise and established oilfield specification relationships, as industrial machinery coatings rotate up share rankings faster than aerospace. Long-term viability hinges on regulatory navigation capabilities across REACH, EPA, and emerging dual-carbon frameworks. Watch for EASA and FAA acceleration of material qualification protocols as the inflection signal enabling new chemistry entrants to compress 18-36 month timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Atomization Capacity | Captive powder production secures margin control against cobalt-nickel volatility and REACH supply disruptions. |
| Cold Spray Robotics Partnership | Portable deposition systems enable field service revenue from in-situ helicopter gearbox repair without disassembly. |
| REACH-Compliant Binder Reformulation | Iron-based matrix development ahead of ECHA cobalt sunset dates preserves aerospace qualification pipelines. |
| Direct Airline Procurement Unbundling | Long-term offtake contracts with North American and Middle Eastern MROs capture material cost transparency. |
| India PLI Scheme Localization | Indigenous qualification protocols for defense aviation components align with import substitution mandates. |
Study Parameters
A standing panel of coating service operations managers, powder formulation chemists, FAA certification specialists, and aftermarket procurement directors at major airlines provided ongoing calibration across the study period. Primary interviews with equipment OEM technical directors and thermal spray booth operators were cross-referenced against secondary validation from ECHA authorization databases, FAA airworthiness directive filings, SEC 10-K disclosures from listed materials conglomerates, and customs trade data for nickel and tungsten carbide feedstock flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Scenario-bracketing framed the analytical approach, with volume and value outputs reflecting segmentation across material type, deposition technology, end-use certification tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical aerospace MRO cycle patterns and industrial machinery refurbishment demand. Industry-specific forecast inputs included engine fleet age distributions, oilfield rig count trajectories, and defense procurement budget allocations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed powder producers or accelerated laser cladding adoption would shift outcomes. Material shifts in REACH authorization timelines, FAA qualification protocol reforms, or cobalt supply chain restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Nanoceramic Powder Market
Ceramics
Zeolite 4A Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Potassium Silicate Market
Ceramics
Transparent Ceramics Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Spain Ceramic Tiles Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Methyl Silicate Market
Ceramics
Calcium Silicate Market
Ceramics
Engineering Ceramics Market
Ceramics
Stoneware Market
Ceramics
Cement Castables Market