
 Nomex Honeycomb Market | 2026-2036
Nomex Honeycomb Market Size, Share, and Industry Trends Forecast 2026-2036
Nomex Honeycomb Market Analysis
Fire-resistant specification tiers for commercial aircraft interiors is collapsing the gap between legacy phenolic systems and advanced aramid honeycomb solutions. DuPont leverages its integrated aramid fiber supply chain to control raw material quality from polymer to core. Hexcel Corporation anchors North American aerospace demand through long-term OEM qualification programs. Euro-Composites differentiates via specialized fabrication capabilities serving European rotorcraft and defense platforms.
Nomex honeycomb consists of aramid paper impregnated with phenolic resin, expanded into hexagonal cell structures with densities typically ranging from 32 to 192 kg/m³, engineered to deliver high stiffness-to-weight ratios with inherent flame resistance. Structural honeycomb dominates current value generation through its entrenched position in aircraft flooring and bulkhead applications. Acoustic panels represent the fastest-growing product type as airlines retrofit cabins to meet stricter noise regulations. OEM manufacturing leads installation mode volumes, though retrofit applications are expanding as aging fleets undergo interior modernization cycles.
FAA flammability standards under 14 CFR Part 25 and EASA CS-25 certification requirements mandate specific burn-through and smoke-toxicity thresholds that only aramid-based cores consistently satisfy. REACH chemical compliance in the European Union and EPA phenolic emission guidelines in the United States further constrain formulation choices and supplier qualification. Stakeholders must monitor evolving OEM sustainability mandates and alternative bio-based resin developments that could disrupt established material specifications.
Market Dynamics
FAA and EASA flammability mandates are compressing qualification timelines for cabin interior materials while Airbus and Boeing procurement consolidation intensifies supplier performance requirements.
Growth Catalysts
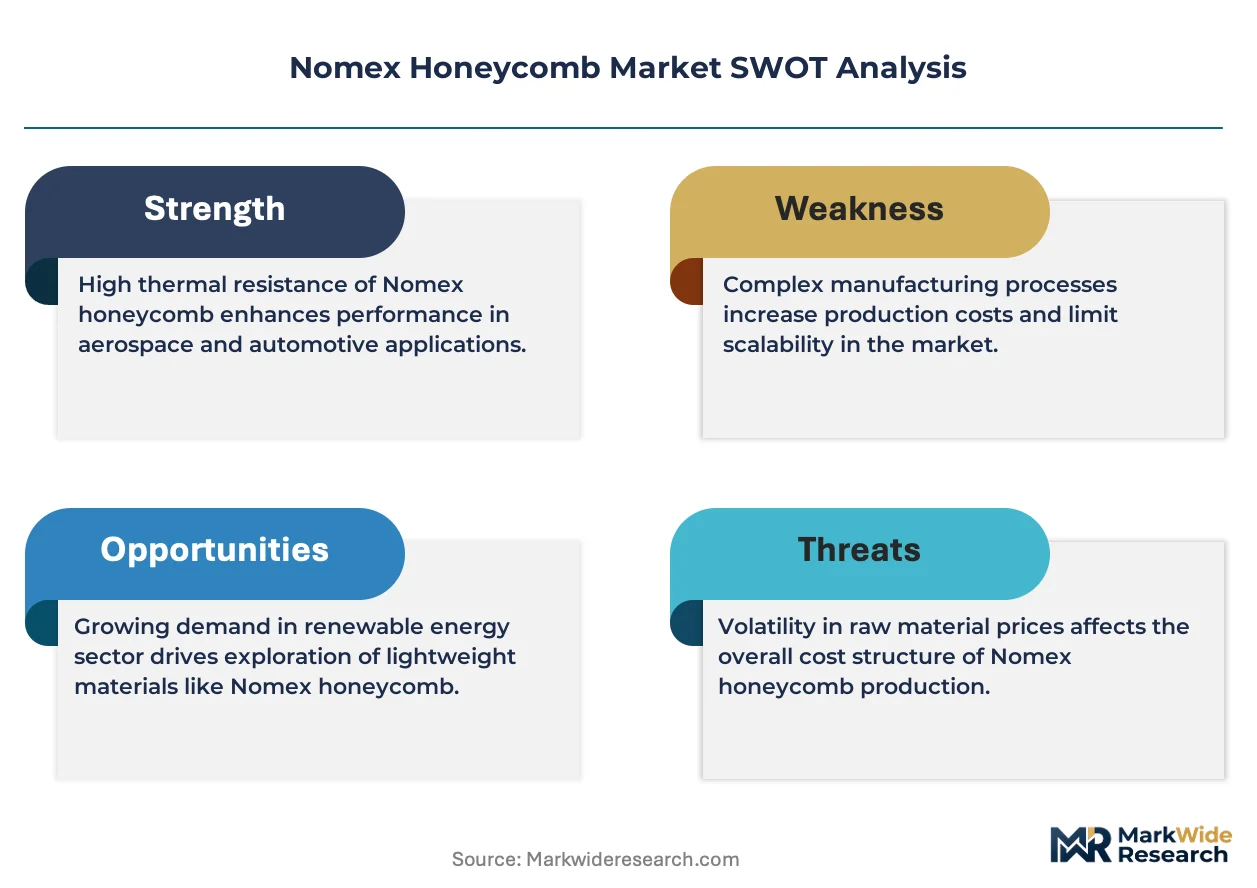
- 14 CFR Part 25 burn-through standards:FAA mandates for commercial aircraft flooring and bulkhead assemblies eliminate phenolic foam alternatives from qualification pools.
- Acoustic retrofit cycles:Airlines in Germany and France are accelerating cabin noise reduction programs ahead of stricter EASA CS-25 amendments.
- Aramid fiber supply security:DuPont's polymer-to-core integration ensures batch consistency for aerospace OEM qualification programs.
Market Restraints
- Phenolic resin price volatility:Petrochemical feedstock fluctuations compress core manufacturer margins without commensurate pass-through mechanisms.
- Single-source aramid paper concentration:Specialty paper mills in the United States and Japan control substrate supply for qualified aerospace grades.
- Aluminum honeycomb substitution:Lower-cost metallic cores retain share in non-fire-critical structural applications.
Strategic Opportunities
- Urban air mobility platforms:Electric vertical take-off aircraft manufacturers in Germany and the United States require certified lightweight cabin structures.
- Bio-based resin convergence:Furan and lignin-derived thermosets paired with aramid substrates could satisfy emerging OEM sustainability mandates.
- Defense rotorcraft modernization:European military upgrade programs specify fire-rated composite panels for troop transport interiors.
Industry Challenges
- Certification timeline compression:EASA and FAA parallel qualification processes demand redundant testing protocols that extend product launch cycles.
- Specialized lamination technician scarcity:Automated core potting and film adhesive application require skills concentrated in Toulouse, Hamburg, and Wichita fabrication clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nomex Honeycomb Market |
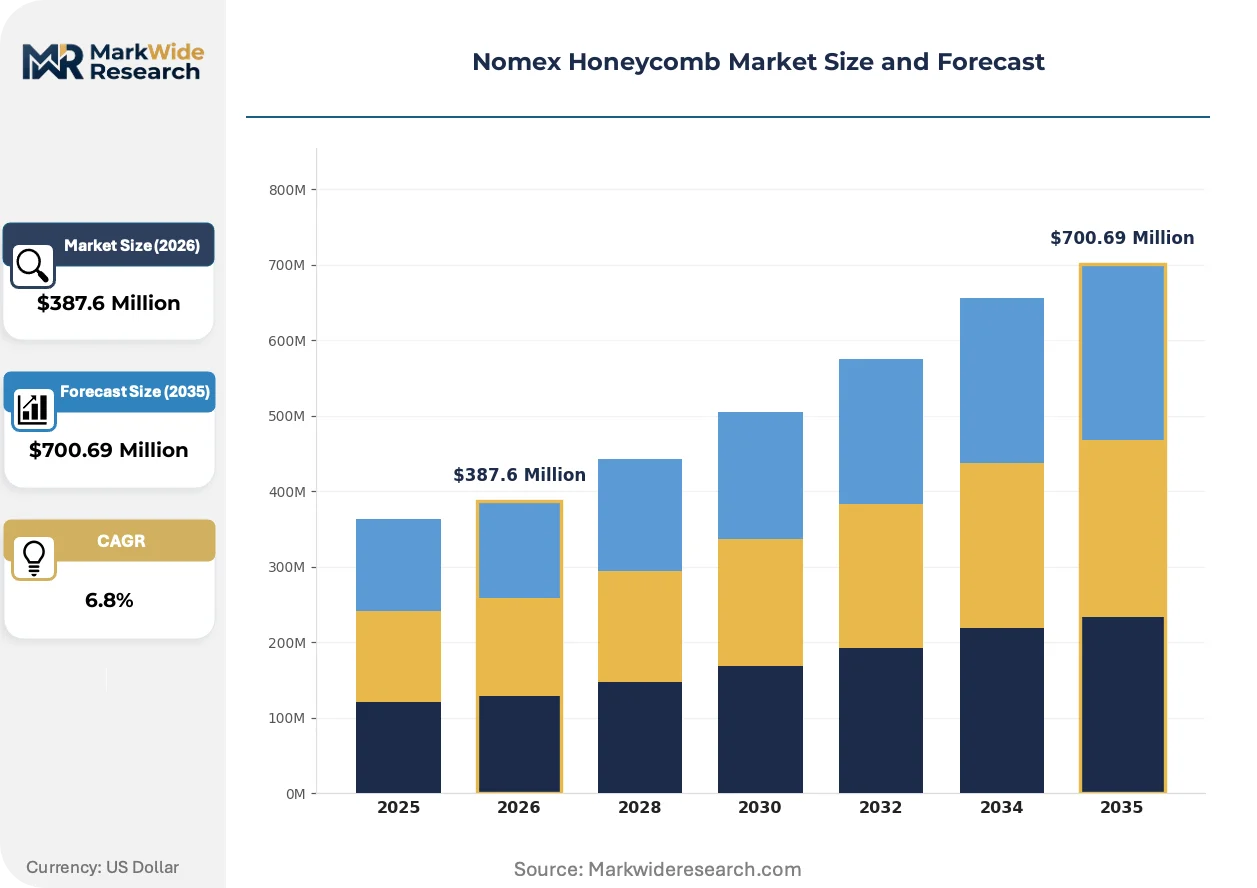
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Honeycomb, Thermal Insulation, Acoustic Panels, Fabricated Solutions End User: Aerospace, Automotive, Marine, Construction Application: Aircraft Interiors, Wind Energy Blades, Train Interiors, Industrial Equipment Installation: OEM Manufacturing, Retrofit Applications, On-site Assembly, Prefabricated Systems |
| Companies Covered | DuPont, Hexcel Corporation, Plascore, Euro-Composites, The Gill Corporation, Toray Industries, Advanced Honeycomb Technologies, Gurit, TenCate Advanced Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nomex Honeycomb Market Emerging Trajectories
Material science advances and regulatory stringency are fragmenting established supply relationships while creating entry points for specialized fabricators with differentiated process capabilities.
Thermoplastic film adhesive systems are bifurcating traditional phenolic-impregnated core bonding methods. Tier-1 aerostructures suppliers in Toulouse and Hamburg are piloting PEEK and PEI hot-melt adhesives for secondary bonding of aramid honeycomb to carbon fiber face sheets. This displacement of legacy epoxy-phenolic wet layup is compressing cycle times and enabling automated tape placement integration.
REACH chemical restrictions under ECHA authorization lists are constraining phenol-formaldehyde resin formulations used in core impregnation. European composite fabricators must reformulate with reduced free phenol content or source pre-registered alternatives. German and French Tier-2 suppliers are absorbing compliance costs while awaiting ECHA guidance on bio-based resin equivalency recognition.
Airline procurement consolidation through airframe OEM direct-buy programs is disintermediating traditional distributor channels. Lufthansa Technik and Air France Industries now specify qualified core fabricators rather than accepting airline-specified alternatives. This channel compression concentrates volume with Hexcel, Euro-Composites, and DuPont-qualified specialists while marginalizing independent converters.
Nomex Honeycomb Market Segmentation
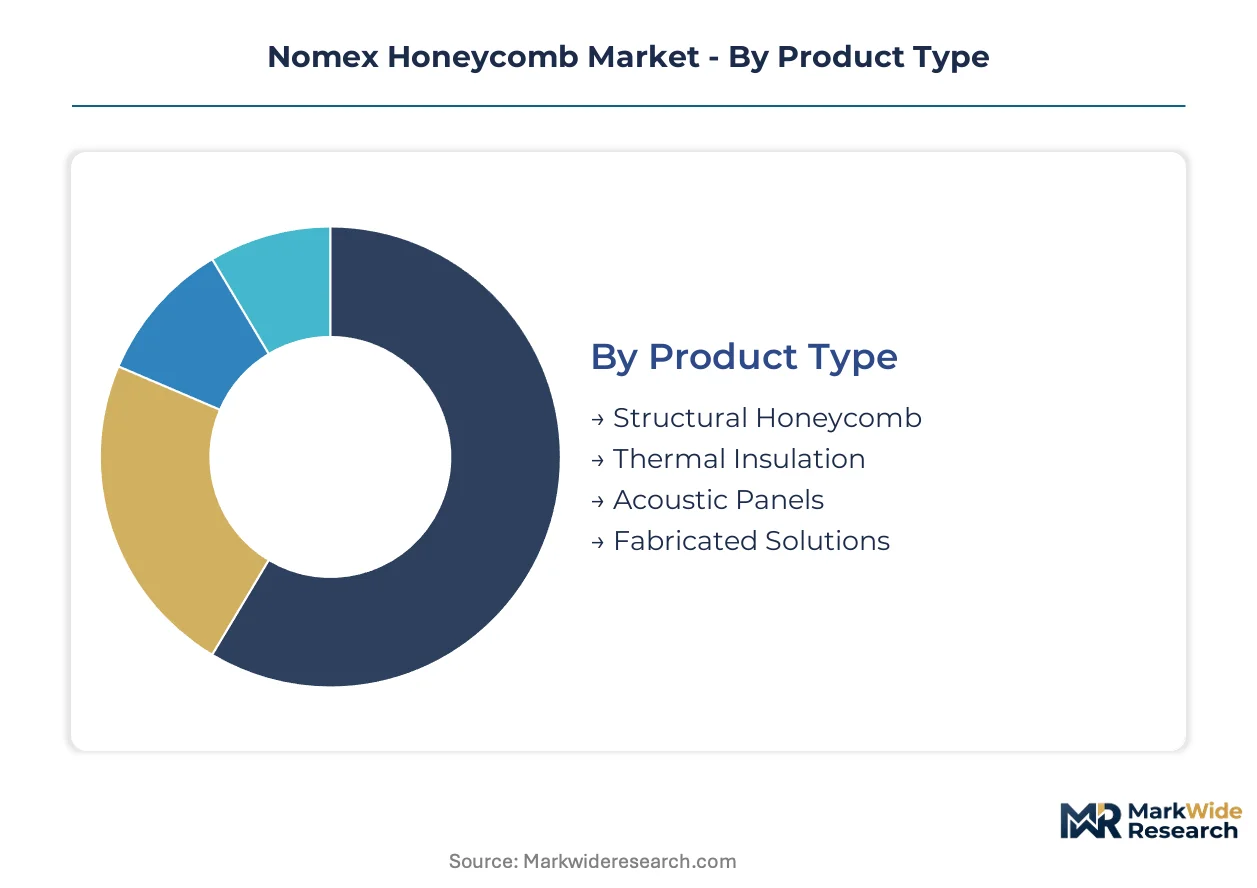
Segmentation in the Nomex honeycomb market reflects divergent certification requirements across fire-rated and non-fire-rated applications. Product architecture, end-use specifications, and installation protocols each create distinct competitive arenas with unique margin profiles and qualification barriers.
Product Type:
FAA and EASA flammability tiers separate qualified aerospace grades from industrial alternatives, with resin formulation and fiber density determining regulatory access.
- Structural Honeycomb:Aramid paper impregnated with phenolic resin, expanded into hexagonal cell structures with densities from 32 to 192 kg/m³. Aircraft flooring and bulkhead assemblies in Germany and France consume the majority of qualified volume, driven by 14 CFR Part 25 burn-through mandates that eliminate foam substitutes.
- Acoustic Panels:Perforated face sheets bonded to tuned honeycomb cores for broadband noise attenuation. Airlines in Germany are accelerating retrofit programs ahead of stricter EASA CS-25 amendments, compressing procurement timelines for certified suppliers.
- Thermal Insulation:Lower-density cores for industrial ovens and process equipment, typically falling outside aerospace qualification pools.
- Fabricated Solutions:CNC-machined core assemblies with pre-bonded edge closeouts for complex geometries.
Established volume favors structural honeycomb; emerging adoption favors acoustic panels.
End User:
Cost-to-weight sensitivity and fire-safety exposure determine penetration depth across mobility sectors.
- Aerospace:Commercial aircraft OEMs and MRO providers specify qualified cores for cabin interiors, cargo liners, and galleys. Boeing and Airbus procurement consolidation in North America and Europe concentrates demand with pre-qualified fabricators.
- Automotive:Electric vehicle battery enclosures and motor sport applications leverage aramid cores for crash energy management and thermal runaway protection.
- Marine:Superyacht interiors and naval vessels require IMO-compliant fire ratings, though aluminum honeycomb retains share in non-structural applications.
- Construction:Curtain wall panels and architectural features exploit lightweight properties where fire codes permit phenolic-impregnated aramid solutions.
Aerospace commands premium pricing; automotive represents the steepest expansion trajectory as electrification intensifies lightweighting pressures.
Application:
Performance specifications fragment across mobility modes with distinct regulatory regimes and lifecycle cost structures.
- Aircraft Interiors:Flooring, sidewalls, ceilings, and monuments require FAA/EASA-certified cores with documented burn-through resistance. German and French supply chains anchor fabrication capacity for single-aisle and wide-body programs.
- Wind Energy Blades:Spar caps and shear webs employ high-density aramid honeycomb for stiffness-to-weight optimization in longer blade designs.
- Train Interiors:EN 45545 fire safety standards for rail applications mandate smoke toxicity thresholds that aramid cores satisfy, particularly in German and French high-speed fleets.
- Industrial Equipment:Semiconductor manufacturing tools and cleanroom infrastructure exploit electrostatic discharge properties of aramid substrates.
Aircraft interiors dominate current value; wind energy blades are climbing the fastest as turbine scaling accelerates.
Installation:
Supply chain configuration separates factory-integrated solutions from field-responsive service models.
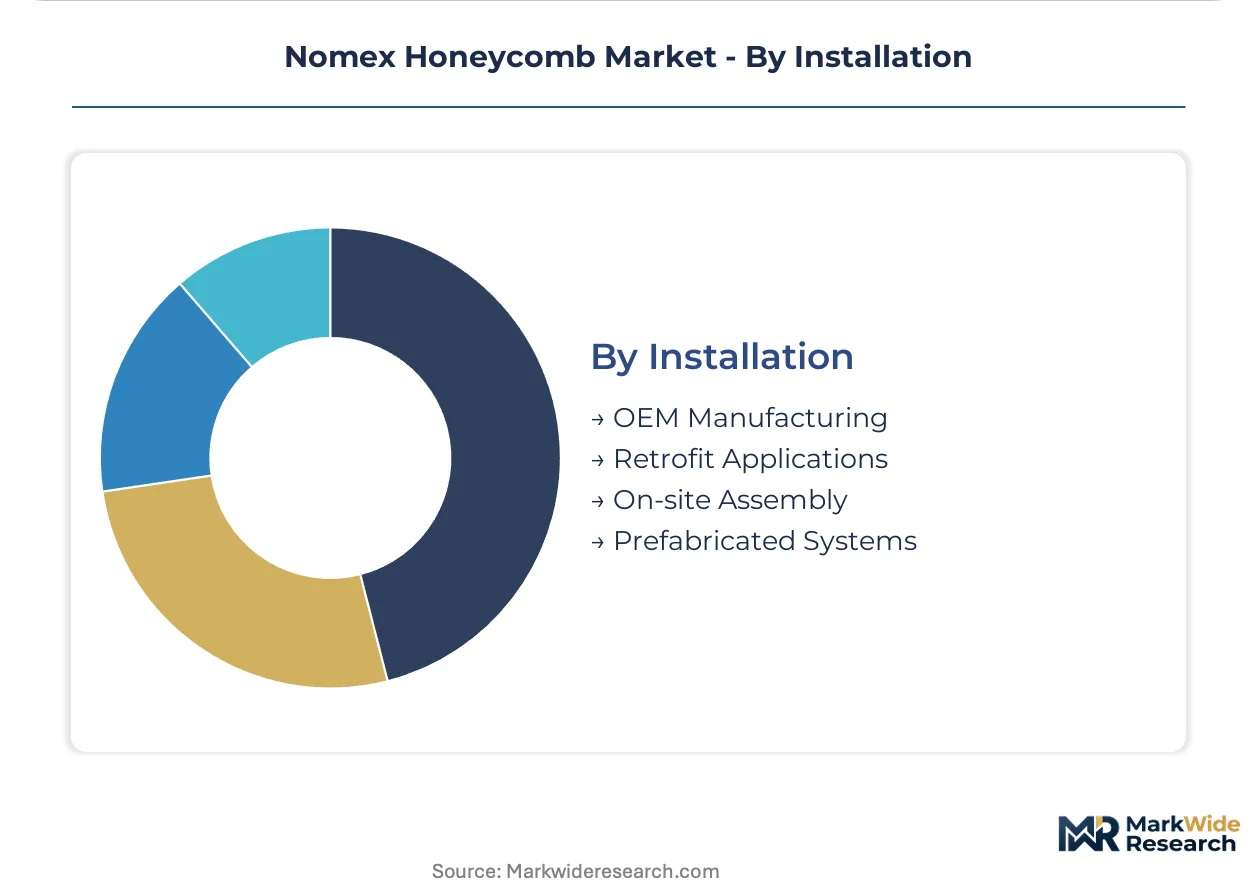
- OEM Manufacturing:Tier-1 aerostructures suppliers in Toulouse, Hamburg, and Wichita bond honeycomb cores to face sheets during primary assembly. Long-term qualification programs lock in supplier relationships across aircraft development cycles.
- Retrofit Applications:Airlines and MRO providers replace worn flooring and upgrade acoustic treatments during scheduled maintenance intervals. Lufthansa Technik and Air France Industries increasingly specify qualified fabricators directly.
- On-site Assembly:Construction and marine projects require adhesive bonding and machining capabilities at installation locations.
- Prefabricated Systems:Modular cabin monuments and architectural panels arrive ready for mechanical fastening, compressing field labor requirements.
OEM manufacturing captures volume concentration; retrofit applications are gaining share fastest as aging fleet modernization cycles intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aramid fiber production and aerospace composite fabrication cluster in three distinct geographies. Germany, the United States, and France concentrate qualified manufacturing capacity. Japan and China supply substrate materials while building indigenous core fabrication capabilities.
United States
Boeing procurement consolidation and defense rotorcraft modernization drive demand. FAA 14 CFR Part 25 burn-through standards eliminate non-aramid alternatives from commercial aircraft interiors. Wichita and Seattle fabrication clusters process qualified cores for OEM assembly lines.
Germany
Airbus supply chain integration and acoustic retrofit programs accelerate procurement timelines. REACH chemical restrictions under ECHA constrain phenolic resin formulations. Hamburg and Augsburg house specialized lamination facilities serving single-aisle and wide-body programs.
France
Air France Industries direct-buy specifications and urban air mobility startup activity expand addressable demand. EASA CS-25 amendments tighten smoke-toxicity thresholds. Toulouse aerostructures suppliers bond honeycomb cores during primary aircraft assembly.
Japan
Toray Industries anchors aramid paper substrate supply for qualified aerospace grades. METI industrial standards support composite material qualification. Nagoya fabrication clusters serve regional aerospace OEMs and export markets.
China
COMAC C919 interior certification and wind turbine blade scaling create dual demand vectors. GB standards for aircraft materials align with FAA/EASA flammability benchmarks. Shanghai and Xi'an develop indigenous core fabrication for domestic aerospace programs.
Nomex Honeycomb Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. The market exhibits tiered consolidation with DuPont controlling upstream aramid fiber supply and specialized fabricators competing on qualification breadth. Three archetypes dominate: integrated polymer-to-core suppliers, qualified aerospace fabricators, and regional conversion specialists. Competitive moves center on backward integration into aramid paper production and geographic expansion into emerging aerospace clusters.
Among integrated material suppliers, DuPont exemplifies the polymer-to-core archetype through captive aramid fiber production. Hexcel Corporation and Euro-Composites occupy positions as qualified aerospace fabricators with established OEM relationships. These three companies represent distinct strategic postures spanning raw material control, qualification depth, and regional market access.
| Leading Market Players |
|---|
| DuPont |
| Hexcel Corporation |
| Plascore |
| Euro-Composites |
| The Gill Corporation |
| Toray Industries |
| Advanced Honeycomb Technologies |
| Gurit |
| TenCate Advanced Composites |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between aerospace OEMs and qualified core fabricators lock in both aramid fiber supply access and price visibility across multi-year aircraft development cycles. These contracts insulate Tier-1 suppliers from phenolic resin feedstock volatility while embedding volume commitments that sustain dedicated production lines in Germany and the United States.
Pricing Analysis
FAA 14 CFR Part 25 burn-through standards dictate the pricing tier structure across aerospace-qualified and industrial-grade Nomex honeycomb. Pricing stratifies across aerospace-certified, automotive-qualified, and industrial-standard tiers, with certification depth and batch traceability as primary differentiation drivers. Cost compression in industrial-grade segments intensifies as aluminum honeycomb substitutes retain share in non-fire-critical applications. Automotive battery enclosure buyers exhibit highest price sensitivity, while commercial aircraft OEMs prioritize qualification breadth over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM manufacturing clusters in Toulouse and Hamburg, while strategic stockpiling of aramid paper substrate persists among qualified fabricators managing single-source concentration risk. Supply concentrates in the United States, Germany, and Japan, with specialty paper mills in Japan and the United States controlling aerospace-grade substrate production. The chain draws from phenolic resin feedstocks, aramid fiber polymers, and precision expansion equipment. Single-source vulnerability in qualified aramid paper supply presents structural exposure. Distribution runs through direct OEM procurement channels with disintermediated airline MRO specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized lamination technician scarcity in Toulouse, Hamburg, and Wichita fabrication clusters constrains capacity expansion regardless of capital availability. This capability gap rewards incumbents with established training pipelines and long-term qualification relationships.
For Market Incumbents: Secure backward integration into aramid paper production or binding offtake agreements with Japanese and United States substrate mills to defend against single-source supply disruption. Expand automated core potting and film adhesive application capacity in Wichita and Augsburg to capture urban air mobility platform demand before certification timelines compress further. For New Entrants and Emerging Players: Anchor in acoustic panel retrofit programs serving German and French airline MRO providers, where direct-buy specifications from Lufthansa Technik and Air France Industries bypass entrenched distributor relationships. Target bio-based resin qualification pathways as ECHA guidance on furan and lignin-derived thermoset equivalency creates first-mover advantage for sustainable alternatives. For Investors and Strategic Acquirers: Qualified aerospace fabricators with established OEM relationships and REACH-compliant formulation capabilities represent the priority acquisition archetype for portfolio exposure to commercial aircraft interior modernization cycles. Long-term viability hinges on sustained Airbus and Boeing procurement consolidation and defense rotorcraft upgrade program continuity. Watch for EASA CS-25 amendment finalization as inflection indicator for acoustic retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Paper | Captive substrate supply secures batch consistency for FAA qualification programs. |
| Automated Core Potting Deployment | Compression of cycle times enables integration with Boeing and Airbus tape placement systems. |
| Bio-Based Resin Qualification | Furan-derived thermoset pathways anticipate ECHA equivalency recognition for REACH compliance. |
| Urban Air Mobility Certification | Electric vertical take-off aircraft cabin structures expand addressable demand beyond commercial aviation. |
| Direct Airline MRO Specifications | Disintermediation of distributor channels concentrates volume with qualified fabricators. |
Methodological Framework
Initial hypotheses were tested against primary input from aerospace procurement executives, composite fabrication plant managers, airline MRO specification engineers, and phenolic resin technical directors and refined through secondary validation against FAA type certificate data, EASA CS-25 amendment documentation, customs trade records for aramid fiber imports, and SEC filings from Tier-1 aerostructures suppliers. Bottom-up volume modeling across product types, end-user segments, and installation modes was triangulated against top-down aerospace production forecasts.
Variance decomposition across the projection horizon isolates drivers by product architecture, regulatory compliance tier, and geographic fabrication cluster. Segmentation dimensions modeled include structural versus acoustic product types, aerospace versus automotive end-use specifications, and OEM manufacturing versus retrofit installation modes. CAGRs were derived from regression analysis of historical procurement patterns and projected aircraft delivery schedules. Industry-specific inputs encompass phenolic resin feedstock price indices and EASA certification timeline data.
Material uncertainties — phenolic resin volatility, ECHA bio-based resin guidance timing, and urban air mobility platform certification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Airbus and Boeing production rate stability and REACH chemical restriction implementation phasing. Revision becomes warranted when aramid fiber supply disruption or alternative core material qualification crosses commercial aircraft interior penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Artificial Marble Products Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
2D Materials Market
Advanced Materials
Global Core Materials Market