
 3D Printing Resin Market | 2026-2036
3D Printing Resin Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Resin Market Insights
Aftermarket resin formulation licensing is rewriting margin economics across the value chain. Carbon sustains technology leadership in continuous liquid interface production with proprietary programmable resins. Formlabs dominates desktop stereolithography through tight control over resin-cartridge pairing and calibration profiles. UnionTech anchors industrial-grade vat photopolymerization systems across China's automotive tooling sector.
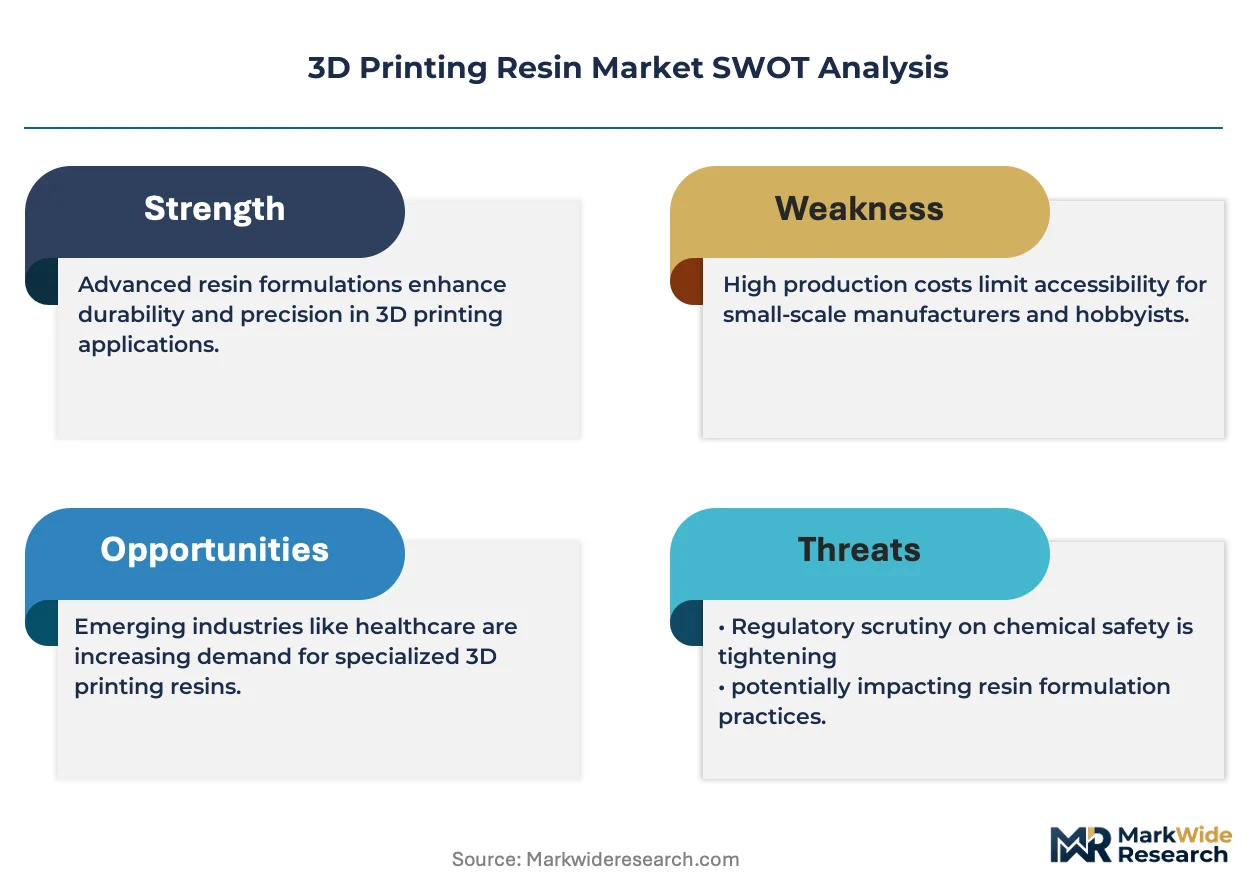
3D printing resin comprises photopolymer formulations that cure under ultraviolet or visible light through free-radical or cationic polymerization, achieving layer resolutions below 50 microns for functional prototypes and end-use parts. Engineering resin commands premium positioning due to thermal resistance and mechanical properties required for aerospace component validation. Dental applications represent the fastest-growing demand pool as OEMs and dental labs shift from milling to additive restoration workflows. Jewelry manufacturing retains strong castable resin consumption despite growing direct precious-metal printing alternatives.
EPA oversees volatile organic compound emissions from resin handling facilities in the United States, while ECHA enforces REACH registration for imported photopolymer monomers entering European manufacturing channels. FDA 510(k) clearance pathways determine market access for biocompatible resins used in permanent dental restorations and surgical guides. Stakeholders must monitor evolving biocompatibility certification tiers as regulatory divergence between major jurisdictions complicates formulation standardization strategies.
Market Dynamics
Aftermarket resin licensing is fragmenting proprietary control across the value chain, forcing incumbent suppliers to defend formulation exclusivity through cartridge-pairing enforcement and calibration-lock mechanisms.
Growth Catalysts
- REACH and RoHS compliance deadlines:European formulation mandates are accelerating R&D investment in low-monomer photopolymer chemistry. ECHA registration requirements for imported raw materials tighten supply chain accountability.
- Dental restoration workflow migration:Crown and bridge laboratories are displacing subtractive milling with vat photopolymerization for permanent restorations. Biocompatibility certification under FDA 510(k) pathways unlocks chairside production.
- Stuttgart-Munich industrial corridor concentration:Germany's automotive tooling sector sustains demand for engineering-grade resins with thermal resistance above 150°C. Tool validation workflows require sub-50-micron layer resolution.
Market Restraints
- Acrylate monomer price volatility:Epoxy and urethane acrylate feedstock costs fluctuate with crude oil derivatives and specialty chemical supply constraints. Formulators lack pricing power to pass through input spikes.
- Photoinitiator supply concentration:Chinese and German specialty chemical producers dominate radical-generating compound manufacturing. Geographic concentration creates single-source vulnerability for regional formulators.
- Post-cure dimensional instability:Residual stress accumulation in thick-section parts limits adoption for structural aerospace validation. Thermal post-processing requirements extend lead times beyond machined alternatives.
Strategic Opportunities
- India's medical device PLI scheme:Domestic manufacturing incentives for surgical guides and dental appliances attract resin formulators seeking tariff-advantaged production bases. CDSCO regulatory harmonization with ISO 10993 accelerates market entry.
- Continuous liquid interface production convergence:Programmable resin chemistry paired with oxygen-permeable membranes enables isotropic mechanical properties. Jewelry and dental segments adopt the technology for burn-out casting and permanent restorations.
- Direct-to-laboratory distribution platforms:E-commerce channels bypass traditional dental distributor markups for biocompatible resin cartridges. Formlabs and Carbon deploy subscription replenishment models capturing lifetime value.
Industry Challenges
- Photopolymer chemistry expertise scarcity:Formulation science combining free-radical kinetics, pigment dispersion, and biocompatibility testing resides in a limited talent pool. Universities produce insufficient polymer chemists with additive manufacturing specialization.
- FDA 510(k) clearance timelines:Permanent dental restoration resins require 12-18 month regulatory review cycles. Premarket notification costs and clinical data requirements strain mid-cap formulator resources.
- Legacy ERP integration friction:Dental laboratories adopting resin-based workflows face data migration challenges from milling-machine job management systems. Software interoperability gaps delay production ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Resin Market |
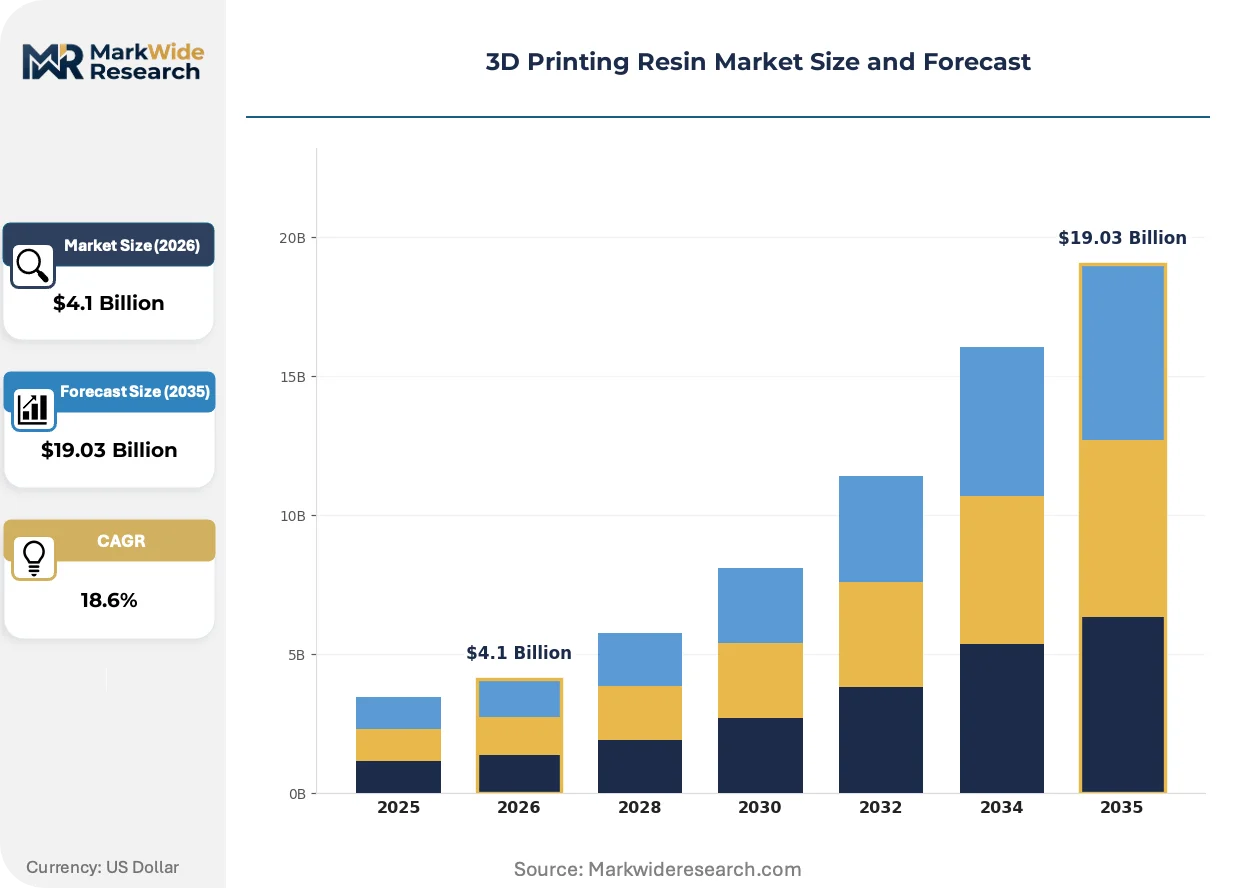
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $19.03 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Resin, Engineering Resin, Castable Resin, Flexible Resin Application: Prototyping, Jewelry Making, Dentistry, Aerospace Components End User: OEMs, Dental Labs, Jewelry Manufacturers, Educational Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Formlabs, HP, Carbon, Stratasys, 3D Systems, Envisiontec, UnionTech, Bambu Lab, Prusa Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Resin Market Trends and Innovations
Formulation science and hardware control systems are converging to enable process-specific resin tuning, compressing the traditional separation between material supplier and equipment OEM.
Dual-cure resin chemistry is hybridizing free-radical and cationic polymerization mechanisms to achieve through-cure in opaque or pigmented formulations. Automotive lighting manufacturers adopt these materials for prototype lens validation requiring both clarity and impact resistance. The technology is compressing iteration cycles from weeks to days for headlamp housing development.
EPA volatile organic compound enforcement is tightening emissions reporting for resin handling facilities across US manufacturing zones. Formulators invest in closed-loop dispensing systems and activated carbon filtration to maintain operating permits. Small-batch dental laboratories face disproportionate compliance costs relative to production volume.
Subscription-based resin replenishment is displacing spot purchasing in high-throughput dental laboratories. Formlabs and Carbon deploy IoT-enabled cartridge monitoring to trigger automatic shipments before depletion. The model concentrates in North American and European markets where laboratory management software integration reduces procurement friction.
3D Printing Resin Market Segmentation
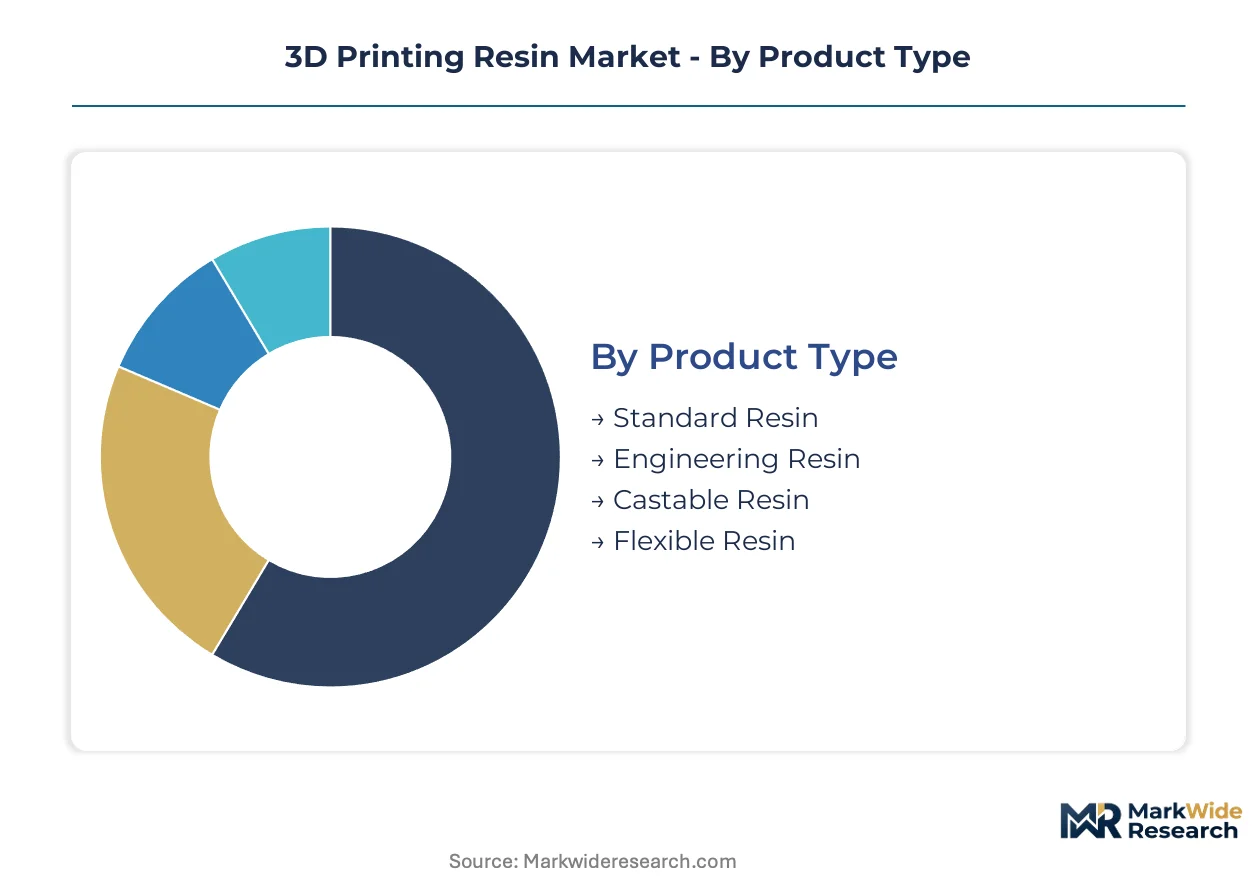
Resin formulation diversity enables precise matching between photopolymer chemistry and hardware specifications across desktop and industrial systems. Segmentation reveals how dental restoration workflows concentrate demand for biocompatible grades while jewelry casting sustains specialized burn-out formulations. Understanding these partitions clarifies where formulation R&D investment yields margin protection versus commodity exposure.
Product Type:
Mature segments dominate current revenue, though emerging categories are capturing share through application-specific performance validation.
- Standard Resin:General-purpose acrylate formulations deliver sub-50-micron layer resolution for visual prototypes and concept models. Demand concentrates in educational institutions and entry-level prototyping shops across Germany and the United States where cost-per-liter sensitivity exceeds mechanical property requirements. Price compression from aftermarket suppliers erodes margin for incumbent formulators.
- Engineering Resin:Urethane and epoxy acrylate blends achieve thermal resistance above 150°C and tensile strength comparable to injection-molded ABS. Stuttgart-Munich automotive tooling corridors sustain premium positioning for validation-grade jigs and fixtures requiring dimensional stability under thermal cycling. REACH-compliant low-monomer variants command formulation premiums in European industrial channels.
- Castable Resin:Ash-free burn-out chemistry enables direct investment casting of precious metal jewelry without wax pattern intermediates. Jewelry manufacturers in India and Italy adopt these formulations for complex filigree geometries unattainable through traditional carving.
- Flexible Resin:Elastomeric photopolymers with Shore A hardness ranging 30-90 simulate rubber gaskets and ergonomic grips for wearable device prototyping. Medical device OEMs evaluate these materials for patient-specific surgical models requiring tissue-like compliance.
Standard resin retains volume leadership; engineering resin holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity prototyping from certified end-use production requiring regulatory validation.
- Prototyping:Functional form-and-fit validation consumes the majority of resin volume through iterative design cycles. General manufacturing and consumer product development teams in the United States prioritize speed over mechanical certification.
- Jewelry Making:Castable resin workflows displace hand-carved wax patterns for custom bridal and fashion jewelry production. Italian and Indian manufacturing clusters sustain specialized formulation demand despite emerging direct metal printing alternatives.
- Dentistry:Permanent crown and bridge restorations require FDA 510(k) cleared biocompatible formulations with cytotoxicity validation under ISO 10993. Dental laboratories in Germany and the United States are displacing subtractive milling with vat photopolymerization for chairside production workflows. ECHA REACH registration for monomer imports complicates European supply chain qualification.
- Aerospace Components:Structural validation parts demand engineering resins with flame-retardant certification and outgassing compliance per ASTM E595. Post-cure dimensional instability in thick sections limits adoption for flight-critical hardware.
Prototyping captures the largest volume base; dentistry is climbing the fastest as laboratories convert from milling to additive restoration workflows.
End User:
Customer type determines procurement sophistication, with subscription replenishment models penetrating high-throughput segments while spot purchasing persists in fragmented channels.
- OEMs:Automotive and medical device manufacturers integrate resin-based prototyping into stage-gate development processes. Internal print farms require formulation consistency across multi-site deployment.
- Dental Labs:Crown and bridge specialists represent the fastest-scaling demand pool as biocompatibility certification unlocks permanent restoration production. North American and European laboratories lead software-integrated procurement adoption.
- Jewelry Manufacturers:Artisan workshops and mid-scale casting houses balance castable resin precision against traditional wax carving labor economics. Italian districts maintain strong consumption despite metal printing emergence.
- Educational Institutions:University design programs and technical colleges train additive manufacturing competency on standard resin formulations. Budget constraints favor open-material systems over proprietary cartridge lock-in.
Dental labs are expanding most quickly; educational institutions remain price-sensitive with limited loyalty to specific suppliers.
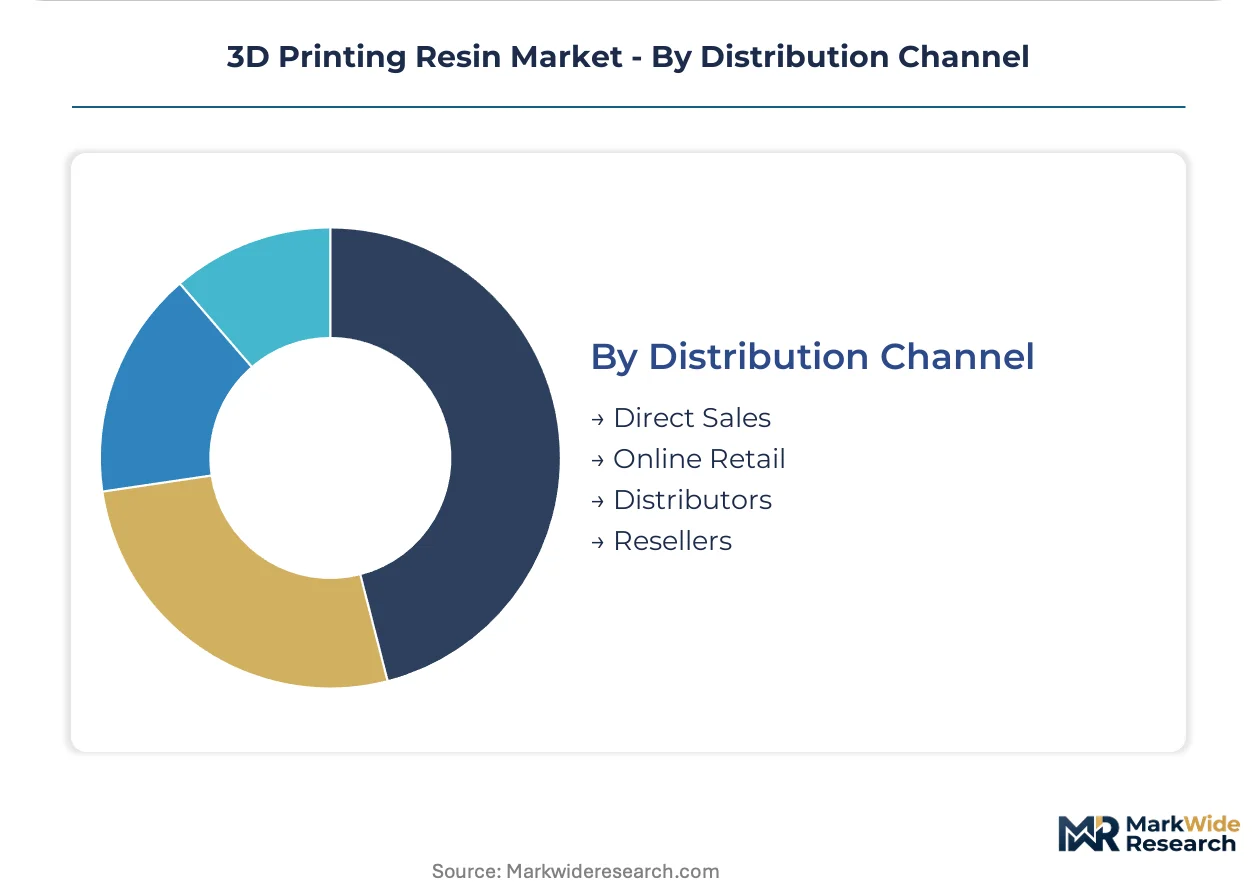
Distribution Channel:
Supply concentration in direct manufacturer relationships contrasts with fragmentation in third-party reseller networks.
- Direct Sales:Formlabs and Carbon deploy field application engineers for dental laboratory onboarding and calibration profile optimization. Enterprise accounts receive dedicated technical support for workflow integration.
- Online Retail:E-commerce platforms capture aftermarket resin sales for open-material printer ecosystems. Amazon and specialized additive manufacturing marketplaces serve hobbyist and small business segments with rapid replenishment.
- Distributors:Regional dental and industrial supply houses maintain inventory for same-day fulfillment in metropolitan manufacturing corridors. German distributors anchor European logistics for REACH-compliant formulation lines.
- Resellers:Value-added resellers bundle resin cartridges with hardware service contracts and training programs. Educational channel specialists negotiate volume discounts for institutional procurement.
Direct sales commands premium positioning; online retail is gaining share fastest among price-sensitive open-system users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates engineering-grade resin demand in automotive tooling corridors, while the United States dominates dental restoration workflows and China anchors industrial-scale manufacturing systems. This consumption-mix differential shapes formulation priorities across geographies.
United States
Dental laboratories in California and Texas drive biocompatible resin consumption for crown and bridge production workflows. FDA 510(k) clearance pathways determine market access for permanent restoration materials, creating regulatory bottlenecks for mid-cap formulators. The Boston-Cambridge corridor sustains photopolymer chemistry R&D concentration alongside venture-backed hardware startups.
Germany
Stuttgart-Munich automotive tooling clusters sustain premium demand for thermal-resistant engineering resins above 150°C validation thresholds. ECHA REACH registration requirements for imported monomers tighten supply chain accountability across European formulation channels. Bavarian industrial parks host concentrated vat photopolymerization deployment for jig and fixture production.
China
Domestic automotive and consumer electronics OEMs scale resin-based prototyping across Shenzhen and Dongguan manufacturing zones. MIIT standards for industrial additive manufacturing equipment shape hardware-resin compatibility requirements. Yangtze River Delta chemical producers dominate photoinitiator compound manufacturing, creating upstream supply concentration.
India
Jewelry manufacturers in Surat and Mumbai adopt castable resin workflows for precious metal casting of complex filigree geometries. CDSCO regulatory harmonization with ISO 10993 accelerates biocompatible resin market entry for surgical guide applications. The medical device PLI scheme attracts formulators seeking tariff-advantaged production bases for export-oriented dental appliance manufacturing.
Japan
Precision component manufacturers in Nagoya and Osaka integrate resin-based validation into automotive and optical device development cycles. METI industrial technology roadmaps prioritize photopolymer chemistry advancement for micro-fabrication applications. Kanto region dental laboratories cautiously evaluate chairside additive restoration workflows amid conservative regulatory interpretation.
3D Printing Resin Market Competitive Landscape
Capability concentration sits with hardware-integrated formulators; scale advantage sits with open-material suppliers and aftermarket chemists. The vendor base separates into three functional tiers: proprietary ecosystem guardians locking resin-cartridge pairings, industrial system anchors supplying validation-grade formulations, and aftermarket chemists exploiting calibration-profile workarounds. Consolidation pressure runs through M&A activity targeting photopolymer chemistry talent pools, while geographic expansion targets India's PLI-advantaged manufacturing zones.
Within the proprietary ecosystem tier, Formlabs and Carbon occupy positions exemplifying hardware-resin integration strategies, with the former anchoring desktop stereolithography deployment and the latter representing programmable resin chemistry convergence. UnionTech sits within the industrial-grade vat photopolymerization segment, anchoring Chinese automotive tooling sector penetration. These three entities illustrate how formulation science and hardware control systems compress traditional separations between material supplier and equipment OEM.
| Leading Market Players |
|---|
| Formlabs |
| HP |
| Carbon |
| Stratasys |
| 3D Systems |
| Envisiontec |
| UnionTech |
| Bambu Lab |
| Prusa Research |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta freight corridors transmit acrylate monomer cost volatility directly into European formulation premiums, concentrating margin pressure on mid-tier suppliers while rewarding integrated producers with captive photoinitiator supply. Contract structures stratify pricing power across the value chain.
Pricing Analysis
Long-term offtake agreements dominate engineering-grade resin procurement in Germany's automotive corridor, insulating Tier 1 suppliers from spot market acrylate swings. Three-tier pricing structure across biocompatible dental, industrial validation, and commodity prototyping levels reflects certification burden and volume scale. Cost compression in standard resin intensifies because aftermarket chemists exploit open-system compatibility. Educational institutions exhibit highest price sensitivity; dental laboratories locked into subscription replenishment show lowest.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for photoinitiator compounds and specialty acrylate monomers. Manufacturing concentrates in China, Germany, and the United States for radical-generating chemicals and oligomer synthesis. Formulation draws from epoxy acrylates, urethane acrylates, and photoinitiator packages. Single-source vulnerability persists for TPO and BAPO photoinitiators from Yangtze River Delta producers. Distribution runs through direct manufacturer relationships for dental OEMs and regional industrial distributors for open-system channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous liquid interface production convergence with programmable resin chemistry constitutes a high-growth disruption, amplified by FDA 510(k) pathway acceleration for permanent dental restorations.
For Market Incumbents: Entrench formulation exclusivity through cartridge-pairing enforcement and calibration-lock firmware updates. Acquire photopolymer chemistry talent pools in Boston-Cambridge and Stuttgart corridors. Carbon and Formlabs demonstrate hardware-resin integration moats that aftermarket chemists struggle to replicate. For New Entrants and Emerging Players: Pursue India's medical device PLI scheme for tariff-advantaged surgical guide production. Target CDSCO-fast-tracked biocompatible segments where incumbent certification lags. Deploy direct-to-laboratory e-commerce platforms bypassing traditional dental distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant photopolymer divisions lacking additive manufacturing specialization. Five-to-ten-year viability hinges on regulatory certification depth rather than commodity volume scale. Watch for ECHA REACH registration deadline compliance failures as forced divestiture triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Production | Captive TPO supply insulates formulators from Yangtze River Delta concentration risk. |
| FDA 510(k) Dual Submission Pathway | Simultaneous dental restoration and surgical guide clearance compresses time-to-market. |
| Subscription Replenishment Platform Launch | IoT-enabled cartridge monitoring locks dental laboratories into recurring revenue. |
| REACH-Compliant Low-Monomer Formulation | ECHA registration alignment unlocks premium positioning in Stuttgart-Munich corridor. |
| Direct-to-Laboratory E-Channel Expansion | Bypassing distributor markups captures lifetime value in North American dental markets. |
Research Methodology
Initial hypotheses were tested against primary input from photopolymer chemists, dental laboratory operations managers, automotive tooling procurement leads, and aftermarket resin distributors and refined through secondary validation. FDA 510(k) filings, ECHA REACH registration databases, customs trade data for acrylate monomer flows, and SEC filings from listed additive manufacturing OEMs anchored quantitative baselines. Bottom-up resin consumption modeling triangulated against top-down hardware installation forecasts.
Demand-supply-balance framing anchored volume projections across the analysis window, with segmentation across resin chemistry type, application certification tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from elasticity-adjusted penetration curves for dental restoration workflows and automotive validation demand. Forecast inputs incorporated photoinitiator supply concentration risk and REACH compliance cost pass-through assumptions.
Sensitivities concentrate around ECHA registration timeline slippage, FDA 510(k) review cycle extension, and acrylate monomer price spike persistence. Forecasts assume documented regulatory pathways and feedstock supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
3D Printing Photopolymers Market