
 Barium Carbonate Powder Market | 2026-2036
Barium Carbonate Powder Market Size, Share, and Industry Trends Forecast 2026-2036
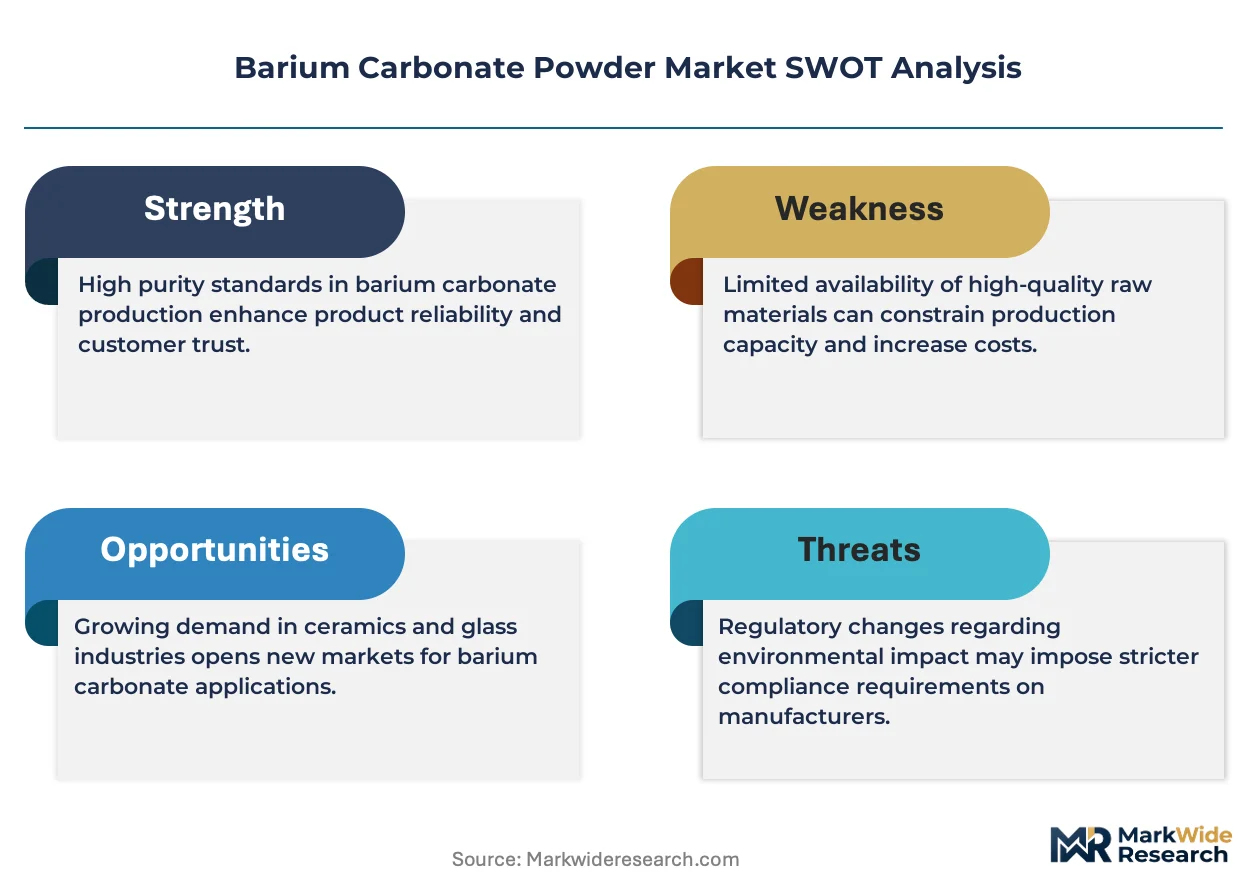
Barium Carbonate Powder Market Analysis
Strontium carbonate is realigning cost structures in select glass and ceramic formulations where manufacturers seek partial barium substitution. Solvay leverages its integrated specialty chemicals platform to sustain consistent pharmaceutical-grade supply across European and North American channels. Sakai Chemical Industry anchors its position through deep vertical integration into electronic-grade barium compounds for display glass substrates. Hubei Jingshan Chutian Barium Salt Corporation competes on raw material access, controlling mine-to-powder production within China's central chemical belt.
Barium carbonate powder is an inorganic salt with the chemical formula BaCO₃, typically produced through the reduction of barite ore with coke followed by carbonation or via direct precipitation methods yielding purities from 98% to 99.9% depending on end-use requirements. The compound serves primarily as a fluxing agent in glass and ceramic manufacture, a precursor to other barium chemicals, and a crystallization modifier in specialty optical materials. Industrial grade dominates volume flows into ceramics and glass manufacturing, while pharmaceutical grade commands concentrated margin pools given stringent purity thresholds and limited qualified suppliers. Technical grade applications in water treatment represent a maturing segment with stable offtake, whereas food grade remains restricted by regulatory scope and carries the smallest addressable base.
China's MEE enforces wastewater and air emission limits on barium salt production facilities, directly elevating capital requirements for domestic processors and reshaping regional supply availability. REACH registration obligations in Europe and EPA hazardous substance reporting in the United States constrain market access for non-compliant producers while favoring established chemical houses with regulatory infrastructure. Stakeholders must monitor evolving purity standards for electronic-grade material as display panel manufacturers advance substrate specifications without assuming automatic specification convergence across geographic demand centers.
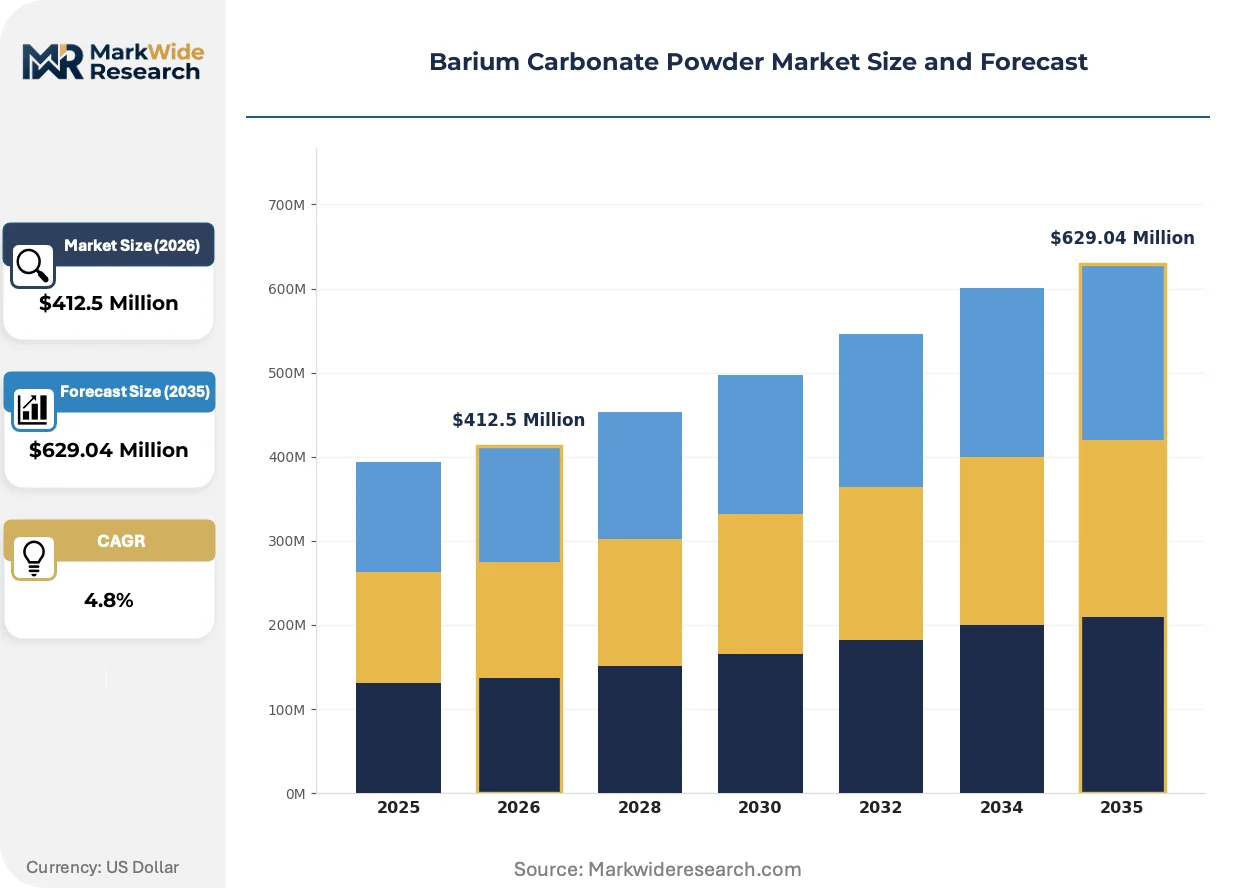
Market Dynamics
China's dual carbon goals and tightening MEE emissions standards are forcing barium salt processors to adopt cleaner production technologies, elevating capital requirements and consolidating supply around Shaanxi Province's integrated mining-chemical corridor.
Growth Catalysts
- Electronic substrate demand:Specialty ceramics manufacturers in Japan and South Korea are expanding procurement of high-purity barium carbonate for display glass and semiconductor packaging applications.
- REACH compliance infrastructure:European chemical houses with established registration obligations capture preferential market access as non-compliant producers face exclusion from EU supply chains.
- Optical material innovation:Crystallization modifier applications in specialty lenses and laser components are pulling technical-grade material into precision manufacturing workflows.
Market Restraints
- Barite ore cost volatility:Energy-intensive reduction processes tie production economics to coke and natural gas input prices, compressing margins during commodity spikes.
- Strontium carbonate substitution:Glass and ceramic formulators in cost-sensitive segments are partial substituting barium with strontium where optical performance tolerances permit.
- Shaanxi supply concentration:Mine-to-powder integration within China's central chemical belt creates geographic single-point vulnerability for global industrial-grade flows.
Strategic Opportunities
- Pharmaceutical-grade white space:Limited qualified suppliers for USP-grade material create margin expansion potential for processors investing in GMP-compliant production lines.
- Water treatment channel expansion:Municipal and industrial wastewater alkalinity adjustment applications represent stable offtake with lower purity barriers to entry.
- EPA hazardous substance reporting:Compliance infrastructure investments by North American distributors are creating preferential access pathways for transparent supply chain documentation.
Industry Challenges
- Electronic-grade purity certification:Display panel manufacturers are advancing substrate specifications faster than qualified supplier capacity expansion, creating specification-supply mismatches.
- Legacy process retooling:China's MEE wastewater and air emission limits require substantial capital deployment for wet-process carbonation facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Carbonate Powder Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Technical Grade Application: Ceramics, Glass Manufacturing, Chemicals, Water Treatment End User: Manufacturers, Pharmaceuticals, Chemical Industries, Educational Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Solvay, Sakai Chemical Industry Co., Ltd., Shaanxi Ankang Jianghua Group Co., Ltd., Honeywell International Inc., Hebei Xinji Chemical Group Co., Ltd., Hubei Jingshan Chutian Barium Salt Corporation Limited, American Elements, Nippon Chemical Industrial Co., Ltd., Chemical Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Carbonate Powder Market Emerging Trajectories
Production technology and procurement patterns are diverging across purity grades, with electronic and pharmaceutical segments demanding traceability infrastructure that industrial-grade supply chains struggle to replicate cost-effectively.
Direct precipitation methods yielding 99.9% purity are unifying previously separate electronic and optical material supply chains. Japanese display glass substrate manufacturers are consolidating vendor lists around processors with demonstrated batch-to-batch consistency. This technology compression is collapsing the historical premium between technical-grade and electronic-grade pricing tiers.
REACH registration obligations are constraining European market access for non-compliant barium salt importers while favoring established chemical houses with regulatory infrastructure. ECHA substance evaluation workflows are extending lead times for new market entrants. Specialty ceramics buyers in Germany and France are responding by tightening supplier qualification criteria to pre-registered sources.
Buyer concentration among East Asian electronics manufacturers is compressing procurement cycles and demanding just-in-time delivery guarantees. Long-term offtake agreements are displacing spot market transactions for high-purity material. South Korean display panel producers are most visibly advancing this contractual standardization.
Barium Carbonate Powder Market Segmentation
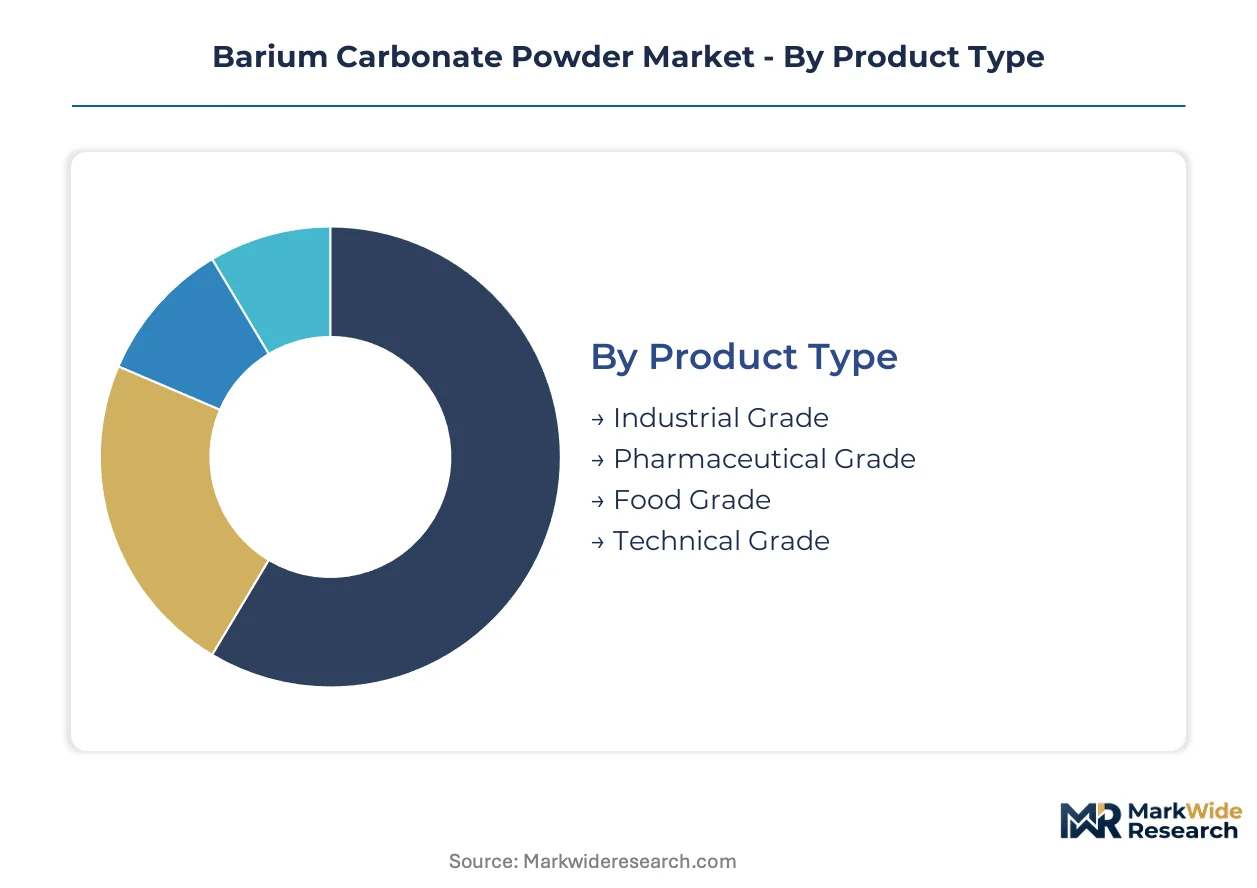
Barium carbonate powder segments diverge sharply by purity threshold and regulatory burden, with capital requirements escalating tenfold from industrial to pharmaceutical grades. Manufacturers must align facility investments with precise end-use specifications rather than pursuing scale economies across all tiers simultaneously.
Product Type:
Industrial grade demands the heaviest upfront capital for ore processing infrastructure and emissions control systems, while pharmaceutical grade requires GMP-compliant cleanroom investments that dwarf raw material costs.
- Industrial Grade:Purity ranges from 98% to 99.2%, produced through coke reduction of barite ore followed by wet carbonation. Demand concentrates in Shaanxi Province's integrated mining-chemical corridor, where MEE emissions standards are forcing facility consolidation and cleaner technology adoption.
- Pharmaceutical Grade:Requires 99.5%+ purity with stringent heavy metal limits, manufactured via direct precipitation under GMP conditions. USP-grade supply chains in North America and Europe face FDA and EMA inspection regimes that limit qualified producers to established chemical houses with dedicated regulatory infrastructure.
- Food Grade:Restricted additive applications under FDA and EFSA frameworks constrain addressable demand to specialty food processing segments.
- Technical Grade:Intermediate purity specifications serve optical material and water treatment applications with lower certification barriers.
Industrial grade absorbs the bulk of installed capacity; pharmaceutical grade is expanding most quickly.
Application:
Glass manufacturing commands the steepest volume requirements, while ceramics applications pull the highest-margin electronic-grade material through specialized procurement channels.
- Ceramics:Electronic substrate manufacturers in Japan and South Korea specify 99.9% purity for display glass and semiconductor packaging, consolidating vendor lists around processors with demonstrated batch-to-batch consistency. REACH-registered European suppliers capture preferential access as qualification criteria tighten.
- Glass Manufacturing:Optical and specialty glass formulators use barium carbonate as a fluxing agent to modify refractive index and thermal expansion coefficients. Strontium carbonate substitution pressures cost-sensitive segments where optical tolerances permit partial replacement.
- Chemicals:Precursor applications for barium chloride, barium nitrate, and other derivatives maintain stable offtake from integrated chemical processors.
- Water Treatment:Municipal and industrial wastewater alkalinity adjustment represents maturing demand with lower purity barriers and transparent supply chain documentation requirements.
Glass manufacturing retains the largest volume share; ceramics applications are climbing the fastest.
End User:
Procurement patterns split between high-volume manufacturers seeking long-term offtake agreements and fragmented buyers requiring distributor intermediation.
- Manufacturers:Specialty ceramics and glass producers in East Asia are displacing spot market transactions with just-in-time delivery guarantees and consolidated vendor lists.
- Pharmaceuticals:Drug manufacturers source USP-grade material through qualified chemical houses with FDA and EMA registration infrastructure.
- Chemical Industries:Integrated processors consume industrial-grade powder as feedstock for downstream barium compounds.
- Educational Institutions:Research laboratories procure small-batch technical-grade material through distributor channels with minimal volume concentration.
Manufacturers dominate procurement volume; pharmaceuticals are gaining share fastest.
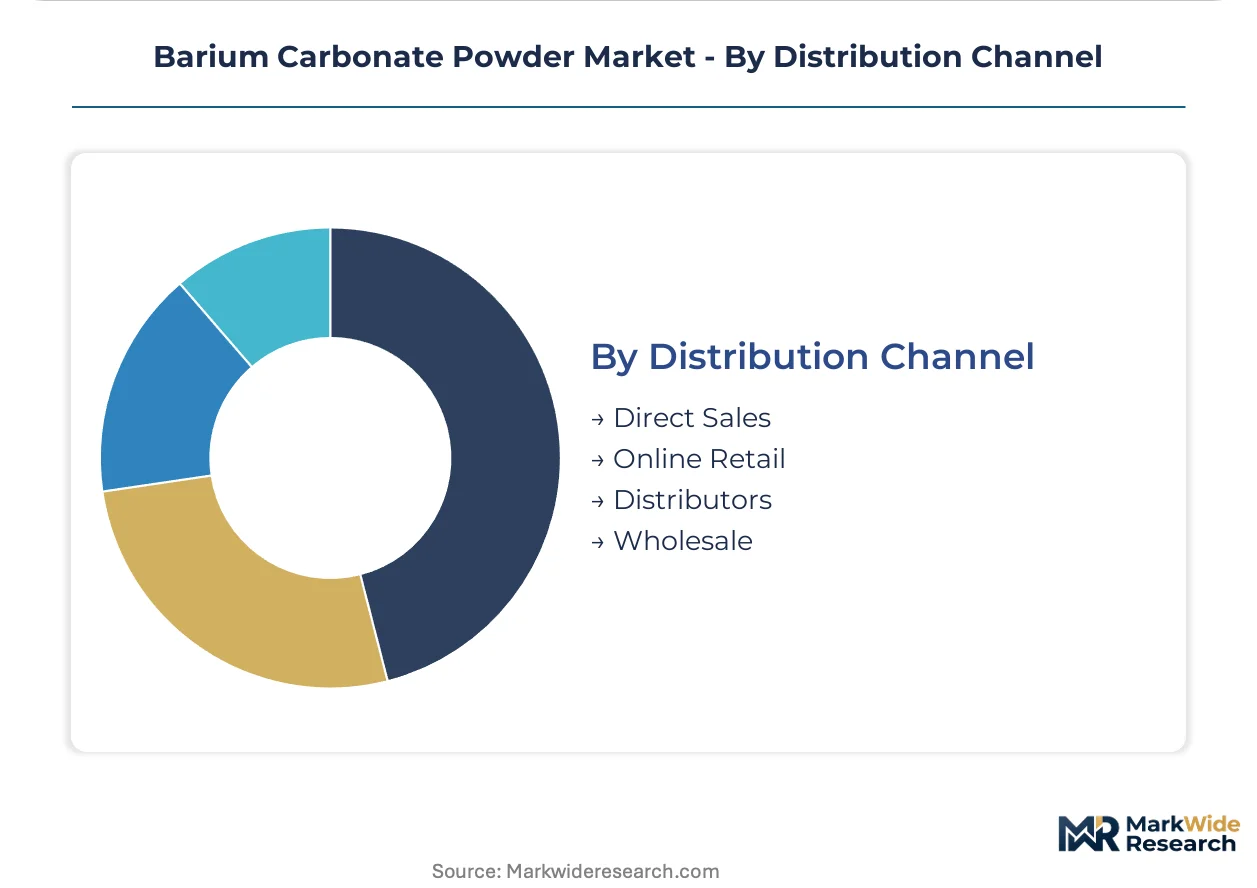
Distribution Channel:
Channel selection tracks buyer scale and regulatory documentation requirements, with direct sales capturing concentrated electronic-grade flows.
- Direct Sales:Long-term offtake agreements between high-purity processors and East Asian display panel manufacturers eliminate intermediary margins.
- Distributors:Regional chemical distributors with REACH and EPA compliance infrastructure serve mid-tier manufacturers requiring documented supply chain transparency.
- Wholesale:Industrial-grade volume flows through bulk wholesalers serving ceramics and glass manufacturers with established credit relationships.
- Online Retail:Small-batch technical and laboratory-grade transactions occur through specialized chemical supply platforms with limited market share.
Direct sales channel captures the highest value concentration; distributor networks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian electronics manufacturers concentrate demand for high-purity barium carbonate powder, while Chinese processors in Shaanxi Province control the bulk of industrial-grade supply. Regulatory pressure from emissions standards and carbon reduction targets is reshaping production economics across major supply corridors.
China
Shaanxi Province's integrated mining-chemical corridor processes the majority of global industrial-grade barium carbonate output. The Ministry of Ecology and Environment enforces wastewater and air emission limits that force facility consolidation and cleaner technology adoption. Domestic processors in the central chemical belt face elevated capital requirements for wet-process carbonation upgrades.
Japan
Specialty ceramics manufacturers in Osaka and Nagoya prefectures drive procurement of 99.9% purity material for display glass substrates. The Ministry of Economy, Trade and Industry supports advanced materials supply chain security through domestic qualification programs. Electronic-grade processors in the Kansai region consolidate vendor lists around demonstrated batch-to-batch consistency.
South Korea
Display panel producers in the Seoul Capital Area and Busan-Ulsan corridor advance long-term offtake agreements with just-in-time delivery requirements. The Ministry of Food and Drug Safety and national standards bodies enforce purity documentation for imported high-grade material. Samsung and LG supply chain affiliates dominate procurement concentration for semiconductor packaging applications.
United States
Pharmaceutical manufacturers source USP-grade material through chemical houses with FDA registration infrastructure. The Environmental Protection Agency's hazardous substance reporting requirements constrain market access for non-compliant importers. Specialty chemical distributors in the Gulf Coast and Northeast corridor invest in compliance documentation to capture preferential access pathways.
Germany
Glass and ceramic formulators in Bavaria and North Rhine-Westphalia specify REACH-registered barium carbonate for optical material applications. The European Chemicals Agency substance evaluation workflows extend lead times for new market entrants. BASF and Merck supply chain affiliates tighten supplier qualification criteria to pre-registered sources.
Barium Carbonate Powder Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated supply in pharmaceutical-grade material contrasting fragmented industrial-grade production. Three strategic archetypes dominate: integrated chemical houses with regulatory infrastructure, mine-to-powder processors controlling raw material access, and specialty distributors bridging compliance documentation gaps. Competitive moves center on backward integration into barite ore supply and capacity expansion for electronic-grade purification lines.
Among European integrated chemical houses, Solvay exemplifies the regulatory infrastructure archetype through its specialty chemicals platform. Sakai Chemical Industry Co., Ltd. and Nippon Chemical Industrial Co., Ltd. represent Japanese processors with deep upstream control over electronic-grade barium compounds. Hubei Jingshan Chutian Barium Salt Corporation Limited occupies a position within China's mine-to-powder tier, anchoring supply from Shaanxi Province's central chemical belt.
| Leading Market Players |
|---|
| Solvay |
| Sakai Chemical Industry Co., Ltd. |
| Shaanxi Ankang Jianghua Group Co., Ltd. |
| Honeywell International Inc. |
| Hebei Xinji Chemical Group Co., Ltd. |
| Hubei Jingshan Chutian Barium Salt Corporation Limited |
| American Elements |
| Nippon Chemical Industrial Co., Ltd. |
| Chemical Products Corporation |
| Others |
Supply Flow & Price Mechanics
East Asian display panel manufacturers concentrate procurement power through long-term offtake agreements, compressing spot market liquidity and anchoring contract-based pricing as the dominant commercial structure across high-purity grades.
Pricing Analysis
Volume flows concentrate in industrial-grade material at compressed margins, while pharmaceutical and electronic-grade tiers capture expanded margin pools through certification barriers. Price differentiation rests on purity thresholds and REACH/FDA registration status rather than brand identity alone. Cost compression in industrial-grade supply stems from strontium carbonate substitution in cost-sensitive glass formulations. Water treatment buyers exhibit highest price sensitivity due to commoditized specifications, whereas pharmaceutical manufacturers prioritize qualified supplier security over unit cost minimization.
Supply Chain Analysis
Direct-to-manufacturer channels handle concentrated demand from Japanese and South Korean electronics producers, while distributor networks serve fragmented pharmaceutical and water treatment buyers. Supply concentrates in China's Shaanxi Province for industrial-grade material, with Japan and Germany anchoring high-purity processing. Raw material flows draw from barite ore deposits, coke reduction inputs, and precipitating agent chemicals. Single-source vulnerability runs through Shaanxi's mine-to-powder corridor, where MEE emissions compliance upgrades could constrain regional export capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration obligations and China's MEE emissions standards erect compliance moats that favor established chemical houses with dedicated regulatory infrastructure over opportunistic traders.
For Market Incumbents: To counter strontium carbonate substitution in optical glass applications, Solvay and Sakai Chemical Industry should deepen upstream control over electronic-grade barite ore sources while accelerating GMP-compliant capacity additions in North America. Certification investments in USP-grade production lines will defend margin position against commodity-grade price erosion. For New Entrants and Emerging Players: Enter via water treatment alkalinity adjustment applications, where purity barriers remain lowest and transparent supply chain documentation requirements favor nimble regional distributors over integrated chemical houses. Municipal procurement channels in the United States offer the most penetrable entry point through EPA hazardous substance reporting compliance. For Investors and Strategic Acquirers: Distressed-cycle entries favor mine-to-powder processors in Shaanxi Province with existing MEE-compliant infrastructure, as domestic consolidation forces subscale competitors toward distressed asset sales. Watch for electronic-grade purity specification advancement by Samsung and LG supply chain affiliates as the signal for qualified supplier capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Ore | Secures captive raw material supply for Shaanxi processors facing MEE compliance costs. |
| Electronic-Grade Purification Line Expansion | Captures specification premiums from Japanese display glass substrate manufacturers. |
| REACH Registration Investment | Unlocks preferential EU market access as ECHA evaluation workflows extend lead times. |
| Long-Term Supply Agreement | Displaces spot market exposure for South Korean display panel producers. |
| GMP-Compliant Production Certification | Qualifies processors for USP-grade pharmaceutical supply chains under FDA inspection. |
Methodological Framework
Trade databases, SEC 10-K filings, and ECHA registration records formed the secondary backbone, cross-referenced with primary interviews involving barium salt plant managers, specialty ceramics procurement leads, pharmaceutical regulatory affairs directors, and chemical distribution channel partners. Bottom-up and top-down triangulation validated volume estimates across purity grades and end-use applications.
Bottom-up modeling tracked grade-specific production capacity and utilization rates, while top-down analysis anchored aggregate demand to glass manufacturing output and electronics substrate build plans. Segmentation dimensions included purity tier, end-use industry, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement patterns and capacity expansion announcements, with coke and natural gas input cost sensitivity integrated as scenario variables.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE enforcement acceleration or display panel demand contraction. Forecasts reflect assumptions regarding strontium substitution elasticity and electronic-grade specification stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Technical Ceramics Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Spain Ceramic Tiles Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
White Fused Alumina Market
Ceramics
Aragonite Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
2N High Purity Alumina Market
Ceramics
Fire Clay Market
Ceramics
Cerium Carbonate Market
Ceramics
Cement Castables Market
Ceramics
Ceramic Setter Plate Market