
 Europe Ceramic Tiles Market | 2026-2036
Europe Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ceramic Tiles Market Intelligence
Aftermarket service revenue for tile restoration and surface treatment is fragmenting as manufacturers build captive service networks. Marazzi Group extends its technical advisory capabilities across specification channels. Iris Ceramica Group anchors its position through in-house digital printing technology for custom surface finishes. Villeroy & Boch competes on heritage brand equity in premium hospitality projects.
Ceramic tiles are clay-based surfacing materials fired at temperatures exceeding 1,000°C, forming dense, vitrified bodies with specified water absorption rates below 0.5% for porcelain grades. Their primary commercial purpose spans protective and decorative envelope applications in built environments. Porcelain commands the dominant margin pool due to superior durability metrics and through-body color consistency. The slabs category within form segmentation is capturing specification share from traditional formats in commercial facade systems. Residential end-use sustains volume leadership while commercial installation gravitates toward large-format thin panels.
CE marking under the Construction Products Regulation governs structural performance declarations for tile systems placed on the European market. ECHA REACH restrictions on heavy metal glazes and the EU Green Deal carbon border adjustments are redirecting formulation chemistry and fuel sources. EMAS-registered facilities in Italy and Spain are capturing specification preference from public procurement frameworks. Stakeholders must calibrate capital allocation between digital manufacturing upgrades and compliance infrastructure as regulatory thresholds tighten on embodied carbon disclosure.
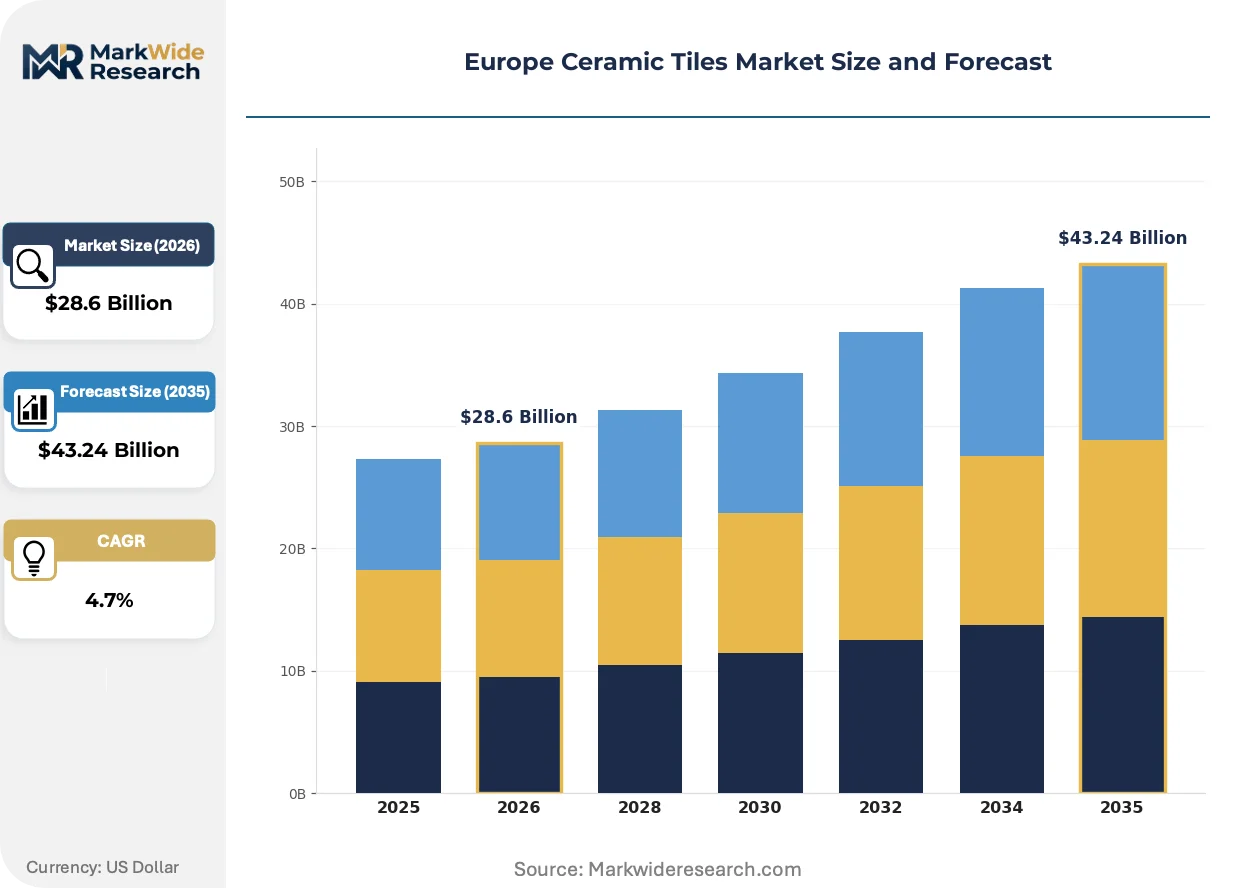
Market Dynamics
EU Green Deal carbon border adjustments are forcing kiln operators across Italy and Spain to restructure fuel sourcing and embodied carbon disclosure protocols. This regulatory pressure concentrates capital allocation toward compliance infrastructure rather than capacity expansion.
Growth Catalysts
- Residential renovation pipelines:Spain and Italy are accelerating porcelain tile specification in heritage building upgrades. Public procurement frameworks in these markets now prioritize EMAS-registered suppliers.
- Large-format thin panel technology:Commercial facade systems are displacing traditional cladding materials with ceramic slabs. Architects specify these for reduced structural load and faster installation cycles.
- REACH compliance differentiation:ECHA restrictions on heavy metal glazes are redirecting formulation chemistry toward clean-label products. Early adopters capture specification preference from sustainability-conscious developers.
Market Restraints
- Natural gas price volatility:Kiln operations depend on concentrated pipeline supply from North African and Russian sources. Energy input swings compress margin predictability for continuous firing processes.
- Italian manufacturing cluster concentration:Sassuolo and Modena districts control disproportionate technical capacity. Geographic single-point risk amplifies disruption exposure from logistics or labor events.
- Thin-panel installation skill scarcity:Large-format specification requires specialized handling and substrate preparation. Contractor capability gaps limit penetration in mid-market residential segments.
Strategic Opportunities
- Eastern European construction acceleration:Poland and Romania exhibit underpenetrated specification rates for porcelain in multi-family housing. Local distribution partnerships could capture first-mover positioning.
- Digital printing convergence:Inkjet decoration combined with surface texture replication enables batch-size-one customization. This technology pairing opens specification channels for boutique hospitality interiors.
- EU taxonomy alignment:Green Deal sustainable finance criteria create preferential lending for low-carbon building materials. Manufacturers with verified embodied carbon data access cheaper project finance.
Industry Challenges
- CE marking timeline compression:Construction Products Regulation declarations require extended third-party testing for new formats. Product launch cycles stretch as certification bottlenecks accumulate.
- Legacy kiln asset stranding:Existing natural gas infrastructure faces accelerated obsolescence under decarbonization mandates. Retooling decisions demand capital commitment before regulatory clarity solidifies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ceramic Tiles Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glazed, Unglazed, Stoneware Form: Tiles, Slabs, Mosaics, Shapes End User: Residential, Commercial, Industrial, Institutional Installation: Flooring, Wall, Countertops, Decorative |
| Companies Covered | Ceramiche Atlas Concorde, Lasselsberger Group, Porcelanosa Grupo, Novoceram, AGROB BUCHTAL, Iris Ceramica Group, Villeroy & Boch, Pamesa Grupo Empresarial, Marazzi Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ceramic Tiles Market Strategic Shifts & Innovations
Digital manufacturing architectures are compressing batch economics and enabling surface customization at industrial scale. Three concurrent developments are restructuring competitive capability requirements.
Industrial inkjet decoration systems are digitizing tile surface design workflows. Hospitality and luxury residential specifiers now demand photographic reproduction of natural materials with zero minimum order quantities. This capability is digitizing the traditional role of glaze chemists and hand-finishing artisans.
EU Green Deal carbon border adjustment mechanisms are tightening embodied carbon tracking requirements for imported ceramics. Manufacturers must document kiln fuel sources and transport emissions across supply chains. Italian and Spanish producers with EMAS-registered facilities are capturing public procurement preference as verification burdens intensify.
Specification channels are fragmenting as architects and developers consolidate vendor relationships around full-service technical advisory capabilities. Traditional distributor networks face disintermediation from manufacturer-direct specification teams. This consolidation is most visible in premium commercial projects across Germany and the Netherlands where single-source accountability reduces interface risk.
Europe Ceramic Tiles Market Segmentation
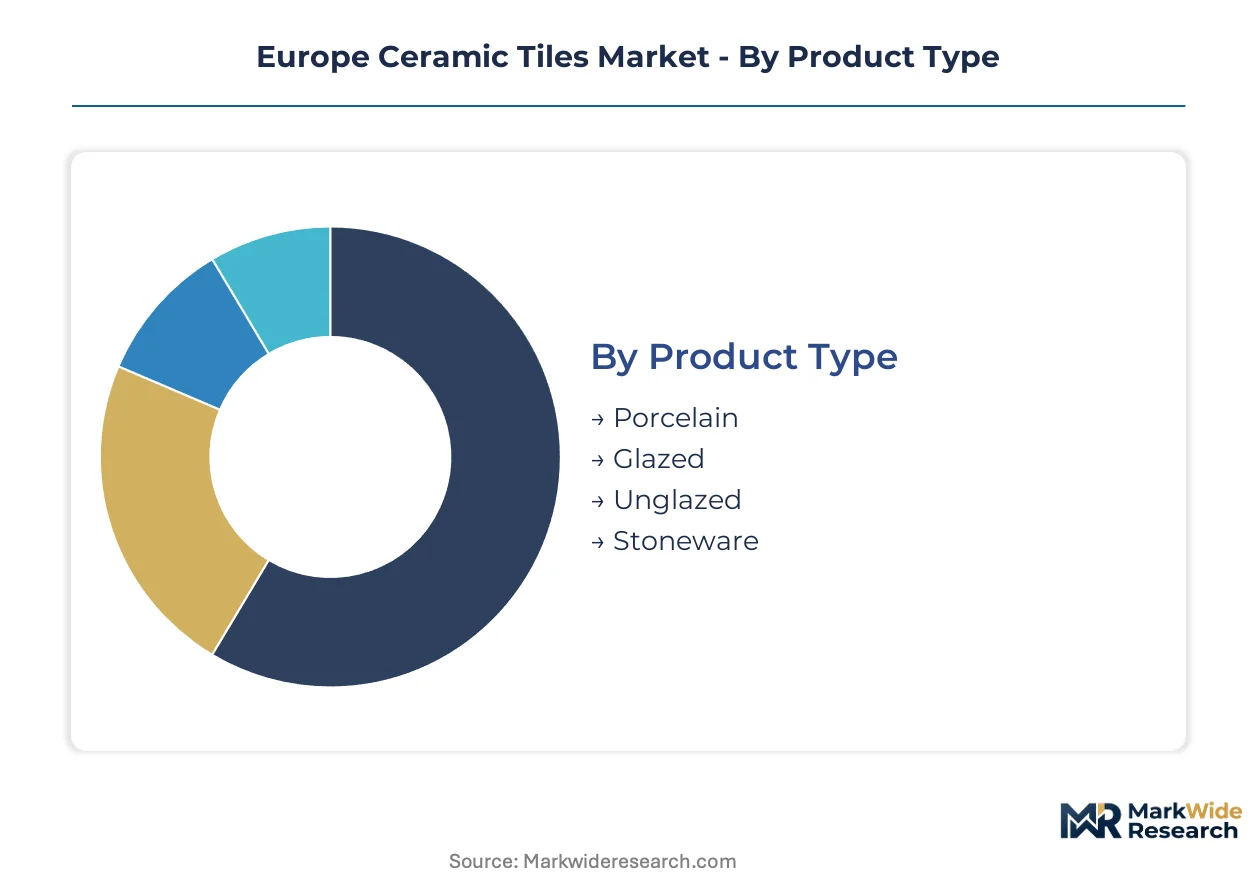
Segmentation in the Europe Ceramic Tiles Market reveals how specification requirements diverge across performance tiers, architectural applications, and procurement channels. Understanding these fault lines enables manufacturers to align capital deployment with margin concentration zones.
Product Type:
Cost tier differentiation separates commodity surfacing from engineered performance materials.
- Porcelain:Fired above 1,200°C to achieve vitrified bodies with sub-0.5% water absorption. Italian and Spanish heritage renovation projects specify porcelain for through-body color consistency and freeze-thaw resistance. EU Green Deal embodied carbon disclosure favors EMAS-registered producers with verified low-carbon kiln protocols.
- Glazed:Surface-applied glass coatings enable aesthetic variation at moderate cost points. Residential flooring across Poland and Romania concentrates demand for glazed ceramic where budget constraints dominate over durability premiums.
- Unglazed:Natural clay bodies without surface coating suit high-traffic commercial environments. Slip resistance ratings drive specification in institutional wet areas.
- Stoneware:Intermediate density between earthenware and porcelain serves cost-conscious wall cladding. Modena manufacturing clusters specialize in stoneware for mid-market hospitality retrofits.
Porcelain commands the established base. The steepest expansion runs through glazed variants penetrating Eastern European multi-family housing.
Form:
Application geometry dictates installation economics and structural load calculations.
- Slabs:Large-format thin panels exceeding one meter dimensions displace traditional cladding on commercial facades. German and Dutch architects specify slabs for reduced substrate weight and accelerated construction schedules.
- Tiles:Standard modular dimensions dominate residential flooring and wall coverage. Sassuolo producers optimize batch economics for tile formats across mass-market distribution.
- Mosaics:Small tesserae enable curved surface adaptation and intricate patterning. Boutique hospitality interiors in France and Italy drive specification for custom mosaic installations.
- Shapes:Non-rectilinear formats including hexagons and chevrons serve decorative accent applications. Digital cutting technology has reduced minimum order thresholds for shaped production.
Tiles retain volume leadership. Slabs are climbing the fastest as commercial envelope specification shifts toward lightweight ceramic systems.
End User:
Customer type determines performance certification requirements and procurement route complexity.
- Residential:Single-family and multi-family housing accounts for the majority of square-meter consumption. Renovation pipelines in Spain and Italy concentrate demand for porcelain and large-format glazed products.
- Commercial:Office, retail, and hospitality projects require extended durability warranties and CE-marked structural declarations. Specification teams bypass traditional distributors for manufacturer-direct technical advisory relationships.
- Industrial:Manufacturing and logistics facilities prioritize chemical resistance and load-bearing capacity. Unglazed heavy-duty formats dominate this specification channel.
- Institutional:Healthcare, education, and government procurement operates under public tender frameworks with EMAS registration prerequisites. Italian and Spanish registered facilities capture preference in EU-funded construction.
Residential end-use anchors volume. Commercial specification offers the steepest margin expansion trajectory through direct manufacturer relationships.
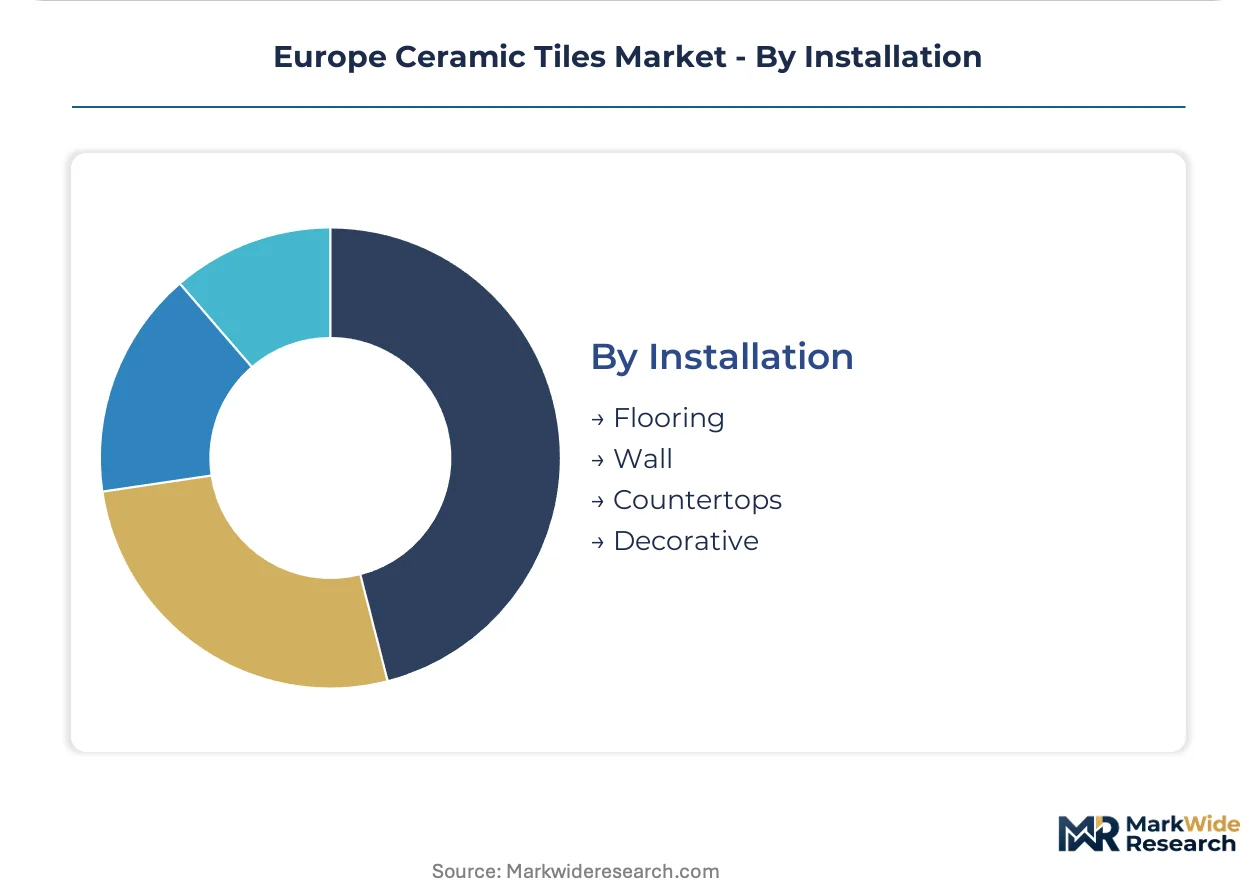
Installation:
Surface placement determines technical performance thresholds and installer skill requirements.
- Flooring:Abrasion resistance and slip coefficient ratings govern specification. Residential renovation across Southern Europe drives replacement cycles for existing floor coverings.
- Wall:Vertical applications emphasize weight limits and adhesive compatibility. Large-format thin panels reduce structural load in high-rise commercial facades.
- Countertops:Work surface applications require stain resistance and edge fabrication capability. Porcelain slabs displace natural stone in premium kitchen specification.
- Decorative:Non-structural accent applications prioritize aesthetic replication and digital printing fidelity. Hospitality interiors specify decorative ceramic for brand differentiation.
Flooring maintains the installed base. Wall applications are expanding most quickly as facade specification shifts toward lightweight ceramic cladding systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fractures across the continent. Southern European renovation markets absorb premium porcelain margins, while Eastern European new-build segments prioritize cost-efficient glazed alternatives. The divergence shapes regional investment priorities for kiln capacity and distribution infrastructure.
Italy
Heritage building restoration drives porcelain specification across Lombardy and Veneto. EMAS registration under EU environmental management standards filters public procurement eligibility. The Sassuolo-Modena corridor concentrates global technical capacity for large-format thin panel production.
Spain
Residential renovation pipelines in Catalonia and Valencia accelerate demand for through-body color consistency. REACH compliance on heavy metal glaze restrictions redirects formulation chemistry toward clean-label outputs. Castellón manufacturing clusters specialize in digital printing integration for custom hospitality finishes.
Germany
Commercial facade specification favors lightweight ceramic slabs for structural load reduction. CE marking under the Construction Products Regulation mandates extended third-party testing for new formats. Technical advisory relationships consolidate around manufacturer-direct channels in Berlin and Munich specification offices.
Poland
Multi-family housing construction exhibits underpenetrated porcelain adoption relative to Western benchmarks. EU Green Deal carbon border adjustments intensify documentation burdens for imported materials. Local distribution partnerships in Warsaw and Kraków capture first-mover positioning for mid-market glazed products.
Netherlands
High-rise commercial development specifies thin panels for accelerated installation cycles. EU taxonomy alignment on sustainable finance criteria enables preferential project lending for low-carbon materials. Rotterdam and Amsterdam architectural practices consolidate vendor relationships around single-source accountability models.
Europe Ceramic Tiles Market Key Industry Players
Capability concentration sits with heritage Italian specialists; scale advantage sits with diversified European groups. The vendor base stratifies across three tiers: EMAS-registered premium specialists, mid-market format standardizers, and regional cost optimizers. Two dominant competitive moves are reshaping positioning: captive technical advisory networks that disintermediate traditional distributors, and backward integration into digital printing equipment to compress batch economics.
Within the heritage specialist tier, Marazzi Group and Iris Ceramica Group exemplify capability-driven positioning. Marazzi anchors manufacturer-direct specification relationships across German and Dutch commercial channels. Iris Ceramica occupies a position defined by in-house digital decoration technology. Porcelanosa Grupo represents the diversified scale archetype, spanning multiple geographies with integrated production and distribution assets.
| Leading Market Players |
|---|
| Ceramiche Atlas Concorde |
| Lasselsberger Group |
| Porcelanosa Grupo |
| Novoceram |
| AGROB BUCHTAL |
| Iris Ceramica Group |
| Villeroy & Boch |
| Pamesa Grupo Empresarial |
| Marazzi Group |
| Others |
Cost & Logistics Intelligence
Road freight corridors connecting the Sassuolo manufacturing cluster to Rotterdam and Hamburg ports transmit fuel surcharge volatility directly into landed cost differentials for porcelain shipments. This logistics cost structure amplifies pricing power for EMAS-registered Italian producers while compressing margins for distributors dependent on spot trucking rates.
Pricing Analysis
Aftermarket service revenue from tile restoration and surface treatment contracts extends lifetime value per specification. Three-tier pricing structure across premium, standard, and economy levels separates EMAS-registered porcelain with verified embodied carbon data from mid-market glazed products and commodity stoneware. Pricing pressure stems from natural gas input volatility forcing continuous kiln operators toward shorter-term contract structures. Residential renovation buyers in Southern Europe show lowest price sensitivity; multi-family developers in Poland exhibit highest.
Supply Chain Analysis
Upstream feedstock sourcing for ceramic bodies draws from kaolin deposits in Ukraine and Turkey, feldspar from Scandinavian pegmatite operations, and clay from sedimentary basins across Spain and Italy. Italian and Spanish manufacturing clusters control disproportionate technical capacity for large-format thin panel production. Single-source vulnerability concentrates in North African pipeline gas supplying continuous firing processes. Distribution runs through manufacturer-direct specification teams displacing traditional wholesale networks in German and Dutch commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon border adjustments are forcing a high-growth disruption across kiln technology investments and embodied carbon verification protocols. This regulatory inflection compresses launch timelines for clean-label products while opening preferential procurement channels for early compliance adopters.
For Market Incumbents: Pre-empt distributor disintermediation by extending captive technical advisory capabilities across specification channels in Germany and the Netherlands. Accelerate EMAS registration for Castellón and Sassuolo facilities to capture public procurement preference before carbon disclosure mandates tighten. Backward integration into digital printing equipment preserves margin control against inkjet decoration commoditization.
For New Entrants and Emerging Players: Build out distribution partnerships in Warsaw and Kraków to capture underpenetrated porcelain specification in Polish multi-family housing construction. Target mid-market glazed ceramic segments where brand equity requirements remain lower than premium porcelain tiers. Lead with REACH-compliant clean-label formulation chemistry as specification differentiator against legacy glaze portfolios.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors EMAS-registered specialists with verified low-carbon kiln protocols and in-house digital decoration capabilities. Long-term viability across the projection horizon rests on manufacturers with documented supply chain emissions data and direct specification relationships. Monitor CE marking timeline compression for new large-format products as inflection indicator for certification bottleneck severity.
| Strategic Initiative | Industry Significance |
|---|---|
| EMAS Registration Acceleration | Unlocks public procurement preference under EU Green Deal tender frameworks in Italy and Spain. |
| Digital Printing Backward Integration | Compresses batch economics for batch-size-one customization in boutique hospitality interiors. |
| Manufacturer-Direct Specification Teams | Disintermediates traditional distributors in German and Dutch commercial facade projects. |
| Clean-Label Glaze Reformulation | Captures specification preference from REACH-compliant developers ahead of heavy metal restrictions. |
| Eastern European Distribution Partnerships | Establishes first-mover positioning in underpenetrated Polish and Romanian multi-family housing. |
Research Approach
Desk research of trade flow databases, EMAS facility registries, and EU construction procurement frameworks preceded structured interviews with kiln operations managers, specification architects, ceramic glaze chemists, and distributor procurement leads. Primary fieldwork across Sassuolo, Castellón, and Modena manufacturing clusters validated secondary data on capacity utilization and technology adoption curves. Bottom-up volume modeling triangulated against top-down construction spending forecasts.
Assumptions held fixed include EU Green Deal carbon border adjustment implementation timelines and REACH heavy metal glaze restriction enforcement patterns. Segmentation modeling spanned product type, form geometry, end-user category, and installation application across the projection horizon. CAGRs derived from regression analysis against residential renovation permit data and commercial construction floor space additions. Industry-specific inputs incorporated kiln fuel switching cost curves and digital printing equipment depreciation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Asian producers or alternative cladding material innovators would shift outcomes beyond modeled ranges. Quarterly review of EMAS registration filings, CE marking approval backlogs, and natural gas forward contract pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Global Functional Ceramics Market
Ceramics
Boiler Refractory Material Market
Ceramics
Cerium Carbonate Market
Ceramics
Wollastonite Market
Ceramics
Ceramic Pigments Market
Ceramics
Transparent Ceramics Market
Ceramics
Automotive Ceramics Market
Ceramics
Global Alumina Market
Ceramics
China Ceramic Market
Ceramics
Ceramic Kilns Market
Ceramics
Ceramic Proppant Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Diatomite Market
Ceramics
Solid-Ion Conductors Market