
 ME K-Feldspar Market | 2026-2036
ME K-Feldspar Market Size, Share, and Industry Trends Forecast 2026-2036
ME K-Feldspar Market Foresight
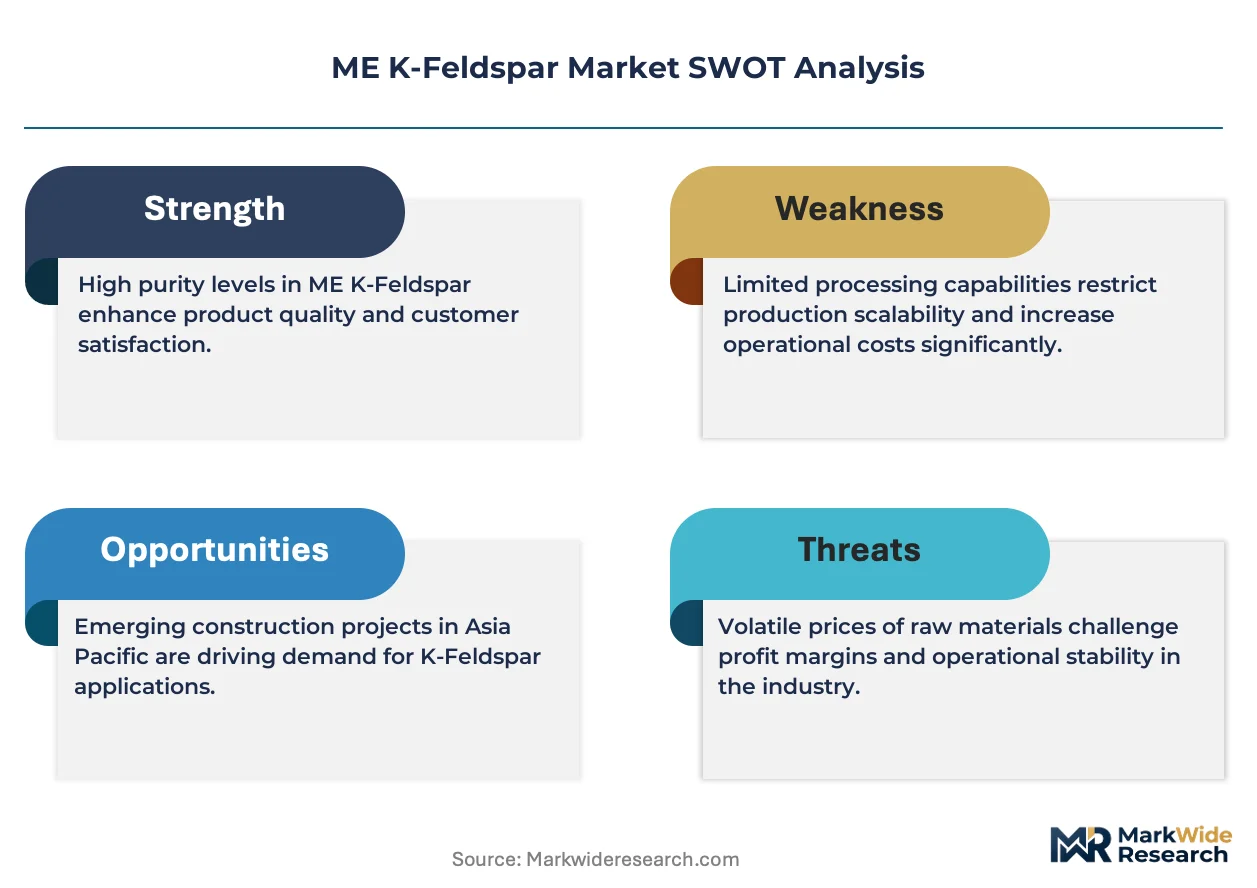
Specialty ceramics buyers are collapsing their historical reliance on commodity-grade feldspar suppliers. Imerys leverages integrated beneficiation assets across Anatolia to sustain long-term concentrate supply. Sibelco anchors its regional position through controlled access to high-potassium deposits in the Arabian-Nubian Shield. Eczacibasi Esan differentiates via vertical feldspar-to-sanitaryware operations that bypass spot market volatility.
ME K-Feldspar comprises potassium-rich aluminosilicate minerals with K2O content typically ranging between ten and fourteen percent, processed through froth flotation, magnetic separation, or dry grinding to achieve iron and titanium specifications below 0.1 percent for premium ceramic glaze applications. Ground Feldspar commands the dominant value share as tile and sanitaryware producers demand tightly controlled particle size distributions below 45 microns. Filtered Feldspar represents the fastest-expanding product tier, driven by electronics-grade substrate manufacturers requiring ultra-low trace element contamination. The Ceramics end-use segment occupies the deepest margin pools, particularly for producers serving Saudi Arabia's giga-project construction pipeline.
Turkey's Ministry of Energy and Natural Resources enforces mining license compliance tied to downstream processing commitments, while Saudi Arabia's Industrial Development Fund channels capital toward integrated feldspar beneficiation under Vision 2030 localization mandates. Egypt's Mineral Resources Authority imposes export duty structures that privilege domestic value-added processing over raw ore shipments. Stakeholders must monitor how regulatory enforcement across these three jurisdictions reshapes concentrate availability and pricing power for independent processors without captive mine supply.
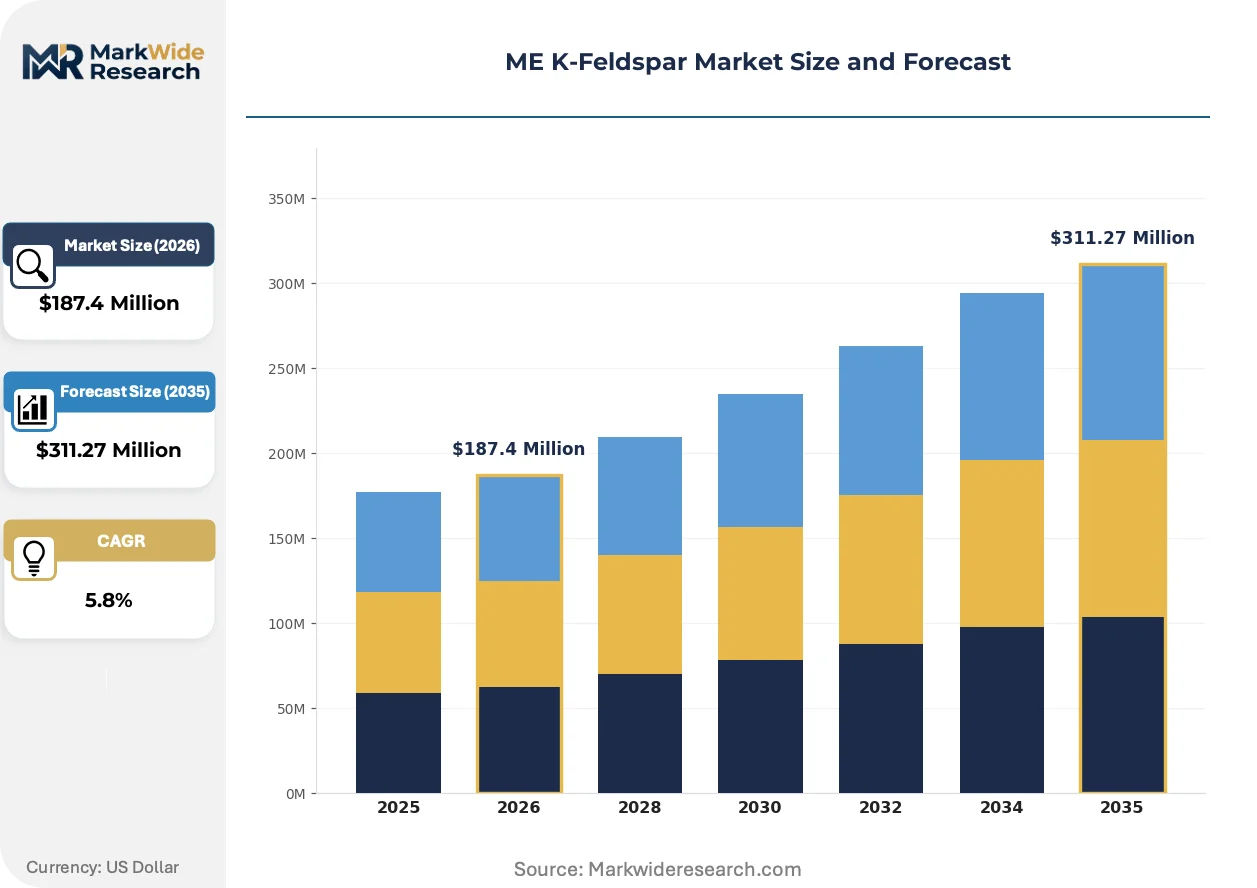
Market Dynamics
Turkey's mining royalty recalibration and Saudi Arabia's downstream localization mandates are compressing margins for independent processors lacking captive mine assets. These policy instruments redirect capital toward integrated beneficiation corridors while fragmenting spot market liquidity.
Growth Catalysts
- Vision 2030 Localization Mandates:Saudi Arabia's Industrial Development Fund channels concessionary financing toward feldspar-to-ceramics operations in the Eastern Province, locking in long-term concentrate offtake for integrated producers.
- High-Purity Ground Feldspar Demand:Specialty ceramics manufacturers are collapsing procurement from commodity-grade suppliers, creating premium pricing tiers for processors achieving sub-0.1% iron and titanium specifications.
- Egyptian Export Duty Restructuring:The Mineral Resources Authority privileges domestic value-added processing through differentiated duty structures, incentivizing beneficiation investment over raw ore shipments.
Market Restraints
- Energy Cost Volatility:Dry grinding and froth flotation operations face margin compression from natural gas and electricity price swings across Turkish processing corridors.
- Deposit Access Concentration:Controlled access to high-potassium reserves in the Arabian-Nubian Shield limits independent processor feedstock security.
- Technical Substitution Pressure:Synthetic aluminosilicate alternatives are penetrating premium glaze applications where trace element tolerance thresholds permit reformulation.
Strategic Opportunities
- Electronics-Grade Substrate Manufacturing:Filtered feldspar demand from semiconductor packaging and advanced ceramic substrate producers is creating ultra-low contamination specification tiers.
- Cappadocia Processing Corridor Expansion:Turkey's Ministry of Energy and Natural Resources links mining license renewal to downstream processing commitments, opening integrated investment pathways.
- Sanitaryware Vertical Integration:Tile and sanitaryware producers are acquiring beneficiation assets to bypass concentrate spot market volatility and secure particle size distribution below 45 microns.
Industry Challenges
- Beneficiation Engineering Talent Scarcity:Froth flotation optimization and magnetic separation process design expertise concentrates among legacy state mining enterprises, constraining operational ramp rates for new entrants.
- License Compliance Timeline Compression:Turkish downstream processing commitments and Egyptian value-add requirements impose concurrent capital deployment obligations that strain project finance structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ME K-Feldspar Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Feldspar, Filtered Feldspar, Ground Feldspar, Feldspar Powder End Use Industry: Ceramics, Glass, Electronics, Paints Form: Granules, Powder, Slurry, Crystals Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Imerys, Sibelco, Eczacibasi Esan, Quarzwerke Group, The Quartz Corp, Micronized Group, Minerali Industriali, Pacer Minerals, EL Waha Mining & Fertilizers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ME K-Feldspar Market Shifts & Advancements
Beneficiation technology evolution and procurement model restructuring are redrawing competitive boundaries between integrated mining-ceramics groups and independent concentrate processors.
Dry magnetic separation circuits with rare-earth roll configurations are displacing conventional wet flotation for intermediate-grade feldspar beneficiation. Saudi tile manufacturers are adopting these systems to reduce water consumption compliance costs. The technology is compressing capital recovery timelines for processors serving giga-project construction pipelines.
Turkey's updated mining royalty framework ties license continuity to demonstrated downstream processing capacity. The regulation forces raw ore exporters to pivot toward concentrate production or surrender extraction rights. Independent processors in Anatolia are responding through joint venture structures with ceramics manufacturers.
Long-term concentrate offtake contracting is displacing spot market procurement for specialty ceramics buyers. Saudi sanitaryware producers are negotiating five-year supply agreements with fixed potassium oxide content bands and penalty clauses for iron contamination excursions. This pattern is most visible in the Eastern Province industrial zones where Vision 2030 construction demand concentrates.
ME K-Feldspar Market Segmentation
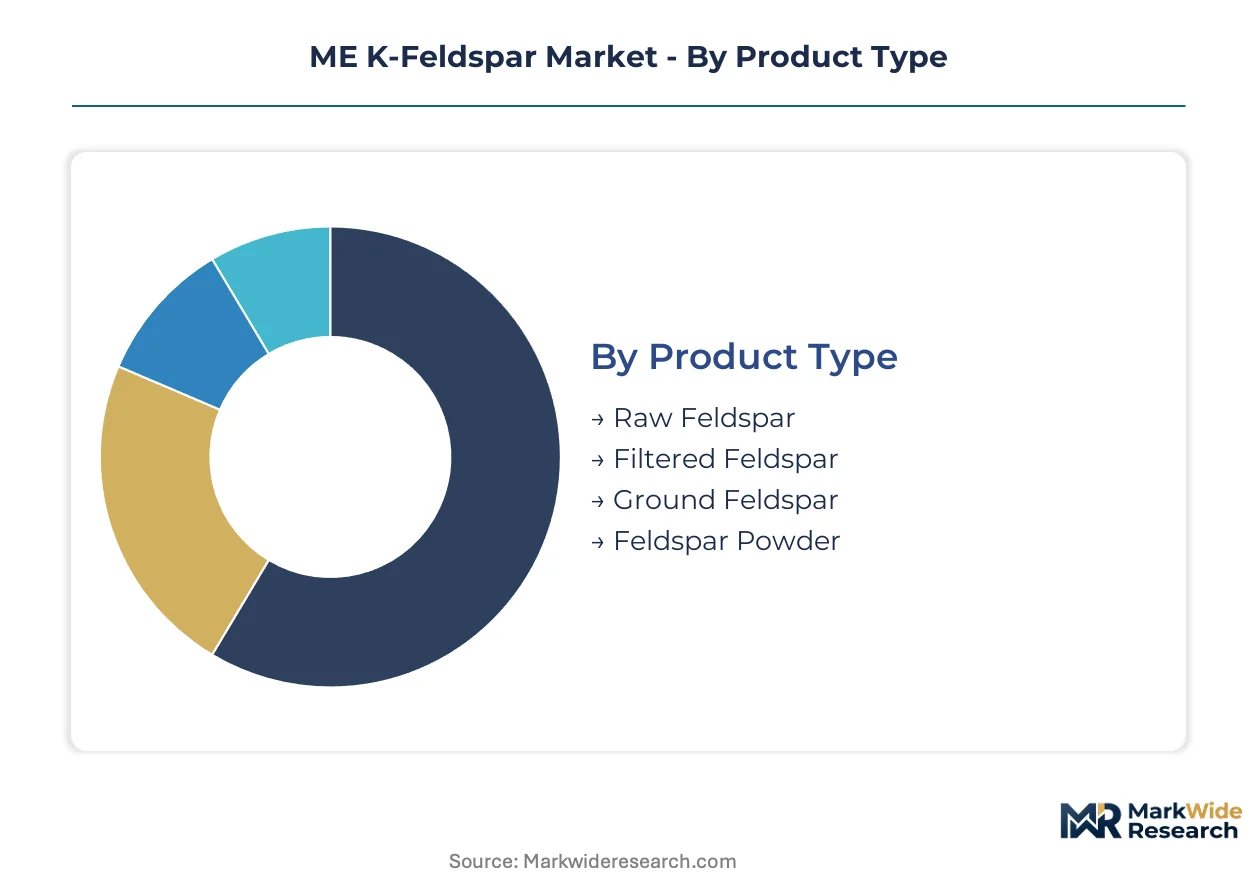
Segmentation reveals how substitution pressure and beneficiation complexity fragment pricing power across the value chain. Turkish and Saudi processors are restructuring procurement models around specification tiers that separate captive supply from spot market exposure.
Product Type:
Ground feldspar faces the most acute synthetic aluminosilicate substitution threat in mid-tier glaze applications, while filtered grades maintain technical moats through ultra-low contamination thresholds.
- Ground Feldspar:Processed through dry grinding to achieve particle size distributions below 45 microns, this grade dominates tile and sanitaryware formulations. Saudi Arabia's Eastern Province giga-project pipeline locks in long-term offtake for integrated producers meeting sub-0.1% iron specifications.
- Filtered Feldspar:Electronics-grade substrate manufacturers drive demand for this ultra-purified tier requiring froth flotation and magnetic separation to eliminate trace element contamination. Cappadocia processing corridor investments target this specification band to bypass commodity pricing volatility.
- Raw Feldspar:Unprocessed ore shipments face Egyptian export duty penalties that privilege domestic beneficiation.
- Feldspar Powder:Intermediate grinding product serves paint manufacturers seeking controlled alkali release.
Ground feldspar anchors the volume base while filtered feldspar gains share at the steepest rate.
End Use Industry:
Ceramics commands the deepest margin pools through Vision 2030 construction demand, whereas glass applications compete with synthetic flux alternatives on cost.
- Ceramics:Tile, sanitaryware, and tableware producers in Saudi Arabia's Eastern Province industrial zones negotiate five-year concentrate supply agreements with fixed potassium oxide content bands. This segment absorbs the highest premium for particle size precision below 45 microns.
- Electronics:Semiconductor packaging and advanced ceramic substrate manufacturers impose ultra-low trace element specifications that filter out commodity-grade suppliers. Filtered feldspar procurement concentrates among integrated mining-ceramics groups with captive beneficiation assets.
- Glass:Container and flat glass manufacturers optimize alkali ratios using intermediate-grade feldspar where synthetic alternatives penetrate on price.
- Paints:Architectural coatings demand fine-ground powder grades for opacity and durability enhancement.
Ceramics retains the largest revenue footprint as electronics climbs fastest on specification premiums.
Form:
Slurry delivery models are displacing dry bulk in water-stressed Turkish processing corridors, while crystal forms retain niche technical applications.
- Powder:Dominates ceramic glaze preparation and paint formulation through controlled particle size distribution. Anatolia's dry grinding corridors ship this form to Saudi sanitaryware producers under long-term contracts.
- Granules:Intermediate crushing product feeds glass furnace flux requirements where alkali release kinetics matter more than fineness.
- Slurry:Water-based transport reduces dust compliance costs for Turkish processors near Cappadocia beneficiation hubs.
- Crystals:High-purity monoclinic specimens serve specialized electronics substrate research applications.
Powder commands shipment volumes while slurry expands most quickly on environmental compliance advantages.
Distribution Channel:
Direct sales concentrate among integrated mining-ceramics groups, fragmenting spot market liquidity for independent processors.
- Direct Sales:Captive mine-to-plant supply agreements lock in five-year potassium oxide specification bands between Saudi sanitaryware producers and Turkish beneficiation assets. This channel bypasses distributor margins for volume buyers.
- Distributors:Independent processors in Anatolia rely on regional traders for spot market access, facing margin compression from royalty recalibration and downstream processing mandates.
- Online Sales:Emerging procurement pathway for small-batch specialty ceramics buyers seeking certificate-of-analysis transparency.
- Retailers:Minimal presence; limited to artisan ceramic supply chains.
Direct sales anchor contractual volume while distributor channels face steepest share erosion from integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Industrial Port in Dammam anchors Saudi Arabia's feldspar-to-ceramics logistics corridor. This maritime infrastructure underwrites the Eastern Province's emergence as the region's dominant beneficiation hub.
Turkey
Cappadocia's dry grinding corridors supply Saudi sanitaryware producers under long-term contracts. The Ministry of Energy and Natural Resources ties mining license renewal to demonstrated downstream processing capacity. Anatolia's beneficiation assets face margin compression from royalty recalibration.
Saudi Arabia
Vision 2030 construction demand concentrates in the Eastern Province industrial zones. The Industrial Development Fund channels concessionary financing toward integrated feldspar-to-ceramics operations. NEOM's advanced materials cluster is negotiating ultra-purity concentrate supply agreements.
Egypt
The Arabian-Nubian Shield hosts high-potassium deposits coveted by specialty ceramics buyers. The Mineral Resources Authority imposes export duty structures that privilege domestic value-added processing over raw ore shipments. Red Sea processing corridors attract joint venture investment from Turkish beneficiation groups.
United Arab Emirates
Jebel Ali's free zone infrastructure positions Dubai as a regional trading node for filtered feldspar grades. MOHAP industrial safety protocols shape warehouse handling standards for concentrate shipments. The emirate's ceramics distributors serve as intermediaries for spot market access.
Israel
Dead Sea Works' chemical processing expertise informs magnetic separation technology adoption. The national mining regulator enforces environmental compliance standards for beneficiation wastewater discharge. Negev Desert deposits supply domestic glass manufacturers seeking controlled alkali ratios.
ME K-Feldspar Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility. The market structure concentrates around integrated mining-ceramics groups with captive beneficiation assets, while independent processors fragment across spot market tiers. Three archetypes dominate: Anatolian integrated miners with downstream sanitaryware operations, Arabian-Nubian Shield deposit holders leveraging controlled access, and European technical specialists licensing separation technology. Competitive moves center on joint venture structures linking mine assets to ceramics manufacturers, and backward integration into concentrate production.
Among integrated mining-ceramics groups, Imerys and Sibelco exemplify the scale-driven archetype through Anatolian beneficiation corridor control. Eczacibasi Esan occupies a position within the vertical integration tier, representing captive supply strategies that bypass spot market exposure. These three entities anchor the competitive landscape through differentiated access to high-potassium reserves and downstream processing commitments.
| Leading Market Players |
|---|
| Imerys |
| Sibelco |
| Eczacibasi Esan |
| Quarzwerke Group |
| The Quartz Corp |
| Micronized Group |
| Minerali Industriali |
| Pacer Minerals |
| EL Waha Mining & Fertilizers |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Saudi sanitaryware producers and Turkish beneficiation assets lock in multi-year potassium oxide specification bands while eliminating spot market exposure for integrated operators. This contract structure concentrates pricing power among captive mine holders and fragments liquidity for independent processors across Anatolia.
Pricing Analysis
Volume-discount tiering separates premium filtered grades for electronics substrate manufacturers from standard ground feldspar serving tile producers and economy raw ore shipments facing Egyptian export penalties. Price differentiation rests on iron specification achievement below 0.1 percent and particle size precision under 45 microns. Cost compression in mid-tier ground feldspar is intensifying as synthetic aluminosilicate alternatives penetrate glaze applications. Commodity-grade buyers exhibit highest price sensitivity while semiconductor packaging manufacturers absorb premium tiers for ultra-low contamination thresholds.
Supply Chain Analysis
Port congestion at King Fahd Industrial Port and container availability constraints on Red Sea trade lanes are elevating inbound logistics costs for Egyptian beneficiation groups serving Turkish processors. Supply concentrates in Turkey, Saudi Arabia, and Egypt with raw material dependencies spanning high-potassium ore from the Arabian-Nubian Shield, rare-earth magnetic separation media, and natural gas for dry grinding operations. Single-source vulnerability concentrates among processors lacking captive mine access. Distribution runs through direct sales channels linking integrated mining-ceramics groups to Eastern Province industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vision 2030 localization mandates and beneficiation technology evolution are disrupting historical procurement patterns, creating asymmetric opportunities across integrated and independent operator archetypes.
For Market Incumbents: Shield concentrate supply positions through backward integration into Cappadocia processing corridors before Turkish license renewal deadlines compress. Secure five-year offtake extensions with Eastern Province sanitaryware producers to lock in volume commitments against emerging synthetic flux substitution threats. Prioritize rare-earth magnetic separation capacity additions that reduce water consumption compliance costs for Saudi giga-project pipelines. For New Entrants and Emerging Players: Anchor in electronics-grade filtered feldspar specifications where ultra-low trace element requirements filter out commodity-grade competition. Target Red Sea processing corridor joint ventures with Egyptian deposit holders seeking Turkish beneficiation expertise. Pursue certificate-of-analysis transparency as the primary go-to-market angle for small-batch specialty ceramics buyers bypassing distributor channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated mining-ceramics groups with captive Arabian-Nubian Shield access over independent spot-market processors. Long-term viability across the analysis window hinges on demonstrated downstream processing commitments tied to license continuity. Monitor Turkish Ministry of Energy enforcement actions on raw ore export restrictions as the signal indicating accelerated captive supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beneficiation Assets | Captive supply of high-potassium concentrate bypasses spot market volatility for Saudi sanitaryware producers. |
| Long-term Supply Agreement with Fixed Specifications | Five-year potassium oxide bands with penalty clauses secure offtake for Cappadocia grinding corridors. |
| Joint Venture with Deposit Holders | Red Sea partnerships combine Egyptian Arabian-Nubian Shield access with Turkish separation expertise. |
| Technology Licensing for Dry Magnetic Separation | Rare-earth roll configurations reduce water compliance costs for Vision 2030 construction demand. |
| Capacity Expansion in Eastern Province Industrial Zones | Proximity to NEOM advanced materials cluster captures electronics-grade substrate procurement growth. |
Research Methodology
Initial hypotheses were tested against primary input from beneficiation plant managers, ceramic glaze formulators, mining license compliance officers, and Industrial Development Fund portfolio directors and refined through secondary validation. Customs data from Turkish Mineral Exporters Association, Saudi Industrial Development Fund disbursement records, Egyptian Mineral Resources Authority export duty filings, and beneficiation technology patent databases anchored supply-side modeling. Bottom-up capacity assessments across Cappadocia and Eastern Province corridors triangulated against top-down construction demand projections.
Variance decomposition across product type, end-use industry, form, and distribution channel dimensions structured the analytical framework. CAGRs were derived from segmented volume trajectories calibrated to Vision 2030 infrastructure commitment timelines and Turkish downstream processing mandate enforcement patterns. Rare-earth magnetic separation adoption curves and synthetic aluminosilicate substitution elasticities informed technology-transition assumptions throughout the projection horizon.
Decision-makers should treat outputs as directional under sustained Saudi construction demand and Turkish license compliance enforcement; material deviation in either would warrant model refresh. Beneficiation engineering talent scarcity and energy cost volatility constitute primary risk factors that could compress ramp rates and margin structures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Clay Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Ceramics Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
North America Barium Carbonate Market
Ceramics
Ceramic Frit Market
Ceramics
Vaterite Market
Ceramics
Ceramic Injection Molding Market
Ceramics
High Temperature Ceramics Market
Ceramics
Nanoceramic Powder Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Ceramic Ware Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Calcium Silicate Market