
 Europe Aluminum Oxide Market | 2026-2036
Europe Aluminum Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aluminum Oxide Market Foresight
Specialized metallurgical engineering talent is bifurcating the European supply base as traditional alumina refiners compete for process chemists against battery-material startups. BASF SE leverages its Ludwigshafen integrated complex to sustain captive alumina supply for catalyst and polishing applications. Norsk Hydro ASA anchors Nordic production through its Norwegian smelter network, while Alteo specializes in high-purity calcined grades from its French manufacturing footprint.
Aluminum oxide, commonly alumina, consists of alpha-phase Al₂O₃ crystals produced via the Bayer process with purity grades spanning 99.3% to 99.99% depending on calcination temperature and duration. Its primary industrial purpose centers on serving as feedstock for primary aluminum smelting, abrasive media, and advanced ceramic substrates requiring thermal stability above 1,600°C. Specialty alumina commands the widest margin pools as European aerospace OEMs specify ultra-low soda content for thermal barrier coatings. Refractory applications dominate volume absorption across the continent's steel and cement sectors. Tabular alumina exhibits the fastest growth trajectory among product categories as electric arc furnace operators upgrade lining durability.
REACH compliance through ECHA governs chemical registration and restricts hazardous impurities in alumina destined for consumer-contact applications. The EU Green Deal's carbon border adjustment mechanism shapes competitive positioning by penalizing imports from high-emission refineries outside the trading bloc. CE marking requirements under the Construction Products Regulation filter non-conforming abrasive and refractory materials from infrastructure projects. Stakeholders must monitor the F-Gas Regulation's phase-down trajectory, as aluminum smelting's PFC emissions intensity becomes a decisive procurement criterion for European OEMs.
Market Dynamics
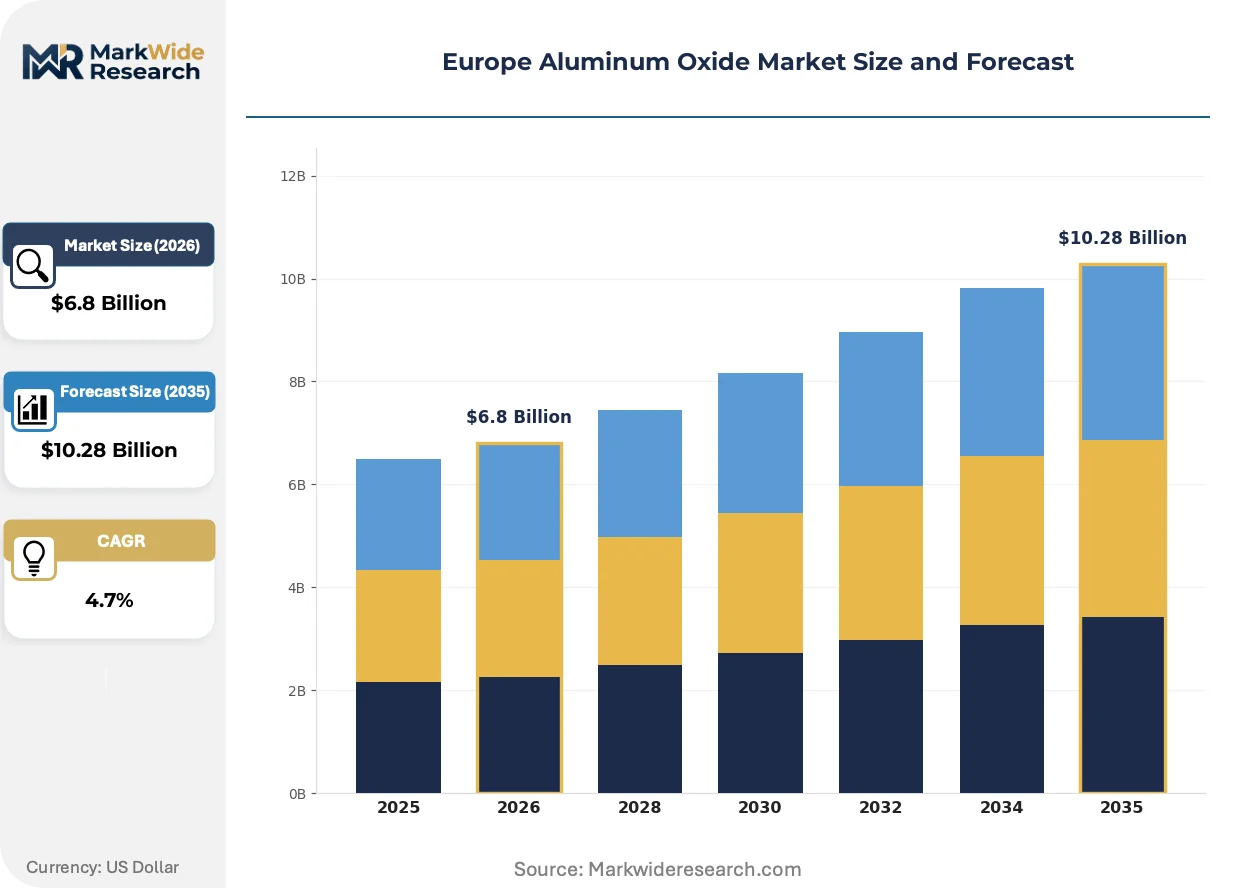
The EU Green Deal's carbon border adjustment mechanism is redirecting procurement toward low-carbon Nordic smelters while specialty alumina purity requirements from aerospace OEMs bifurcate the European supply base between commodity refiners and high-purity specialists.
Growth Catalysts
- EU Green Deal carbon border adjustment:The mechanism penalizes high-emission imports, pulling procurement toward Norwegian and Icelandic low-carbon smelters with hydroelectric power.
- Aerospace thermal barrier coatings:European OEMs specify ultra-low soda alumina for turbine blades, creating premium demand pools that refiners in France and Germany are expanding capacity to capture.
- Electric arc furnace upgrades:Steel producers across the Ruhr Valley and northern Italy are replacing traditional refractories with tabular alumina to extend lining life.
Market Restraints
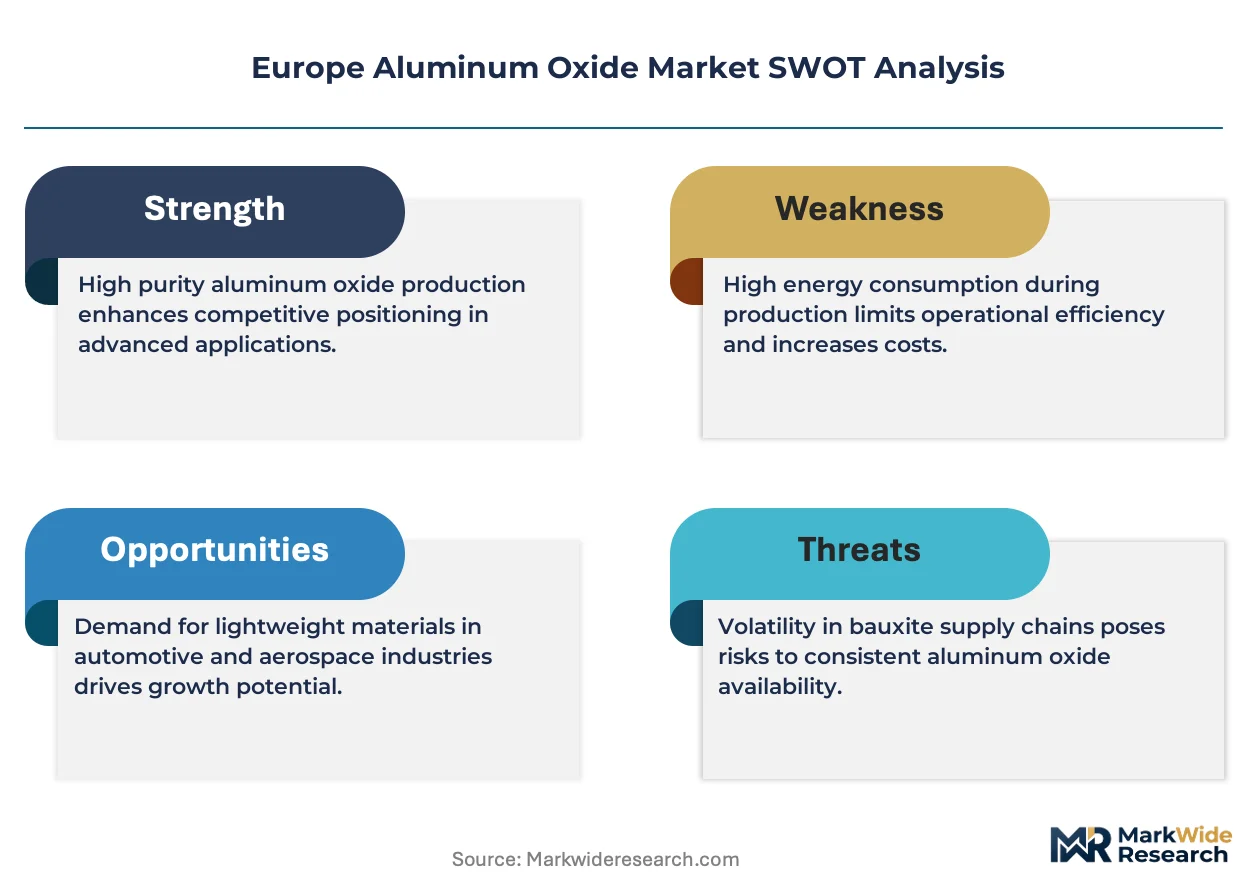
- Bauxite import dependency:European refiners source 90% plus of raw bauxite from Guinea, Australia, and Brazil, exposing margins to seaborne freight volatility and geopolitical disruption.
- Natural gas price sensitivity:Calcination energy costs consume 35-40% of specialty alumina production expenses, linking profitability directly to TTF benchmark fluctuations.
- REACH registration burden:ECHA compliance costs for new purity grades and particle size variants deter mid-tier refiners from entering high-margin specialty segments.
Strategic Opportunities
- Battery ceramic separator films:Solid-state lithium-ion development in Germany and Sweden requires high-purity alpha-alumina substrates, opening adjacent demand outside traditional metallurgical and abrasive channels.
- Poland and Czech Republic industrial corridors:Greenfield steel and cement capacity in Central Europe lacks established refractory supply relationships, creating first-mover positioning for integrated alumina-refractory players.
- F-Gas Regulation phase-down:Aluminum smelting PFC emissions intensity becomes a decisive procurement filter, rewarding Nordic and French smelters with verified low-carbon credentials.
Industry Challenges
- Process chemist scarcity:Traditional alumina refiners compete against battery-material startups for metallurgical engineering talent, inflating compensation and extending recruitment cycles.
- CE marking timeline compression:The Construction Products Regulation requires extensive testing for abrasive and refractory materials, delaying product launches by 12-18 months.
- Legacy calciner retrofit complexity:Converting rotary kilns to meet EU industrial emissions directive limits requires capital outlays that strain mid-tier refiner balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aluminum Oxide Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Alumina, Tabular Alumina, Activated Alumina, Specialty Alumina Application: Refractory, Ceramics, Polishing, Coatings End User: Aerospace, Automotive, Electrical, Construction Distribution Channel: Direct Sales, Distributors, Online Retail, B2B Platforms |
| Companies Covered | Huber Engineered Materials, BASF SE, Hindalco Industries, Alcoa Corporation, Evonik Industries AG, Norsk Hydro ASA, Alteo, Rio Tinto Group, Sasol Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aluminum Oxide Market Shifts & Advancements
Digital process control and low-carbon process chemistry are converging to reshape how European refiners differentiate output, while procurement patterns shift toward verified emissions documentation.
Additive manufacturing feedstock qualification is fragmenting the specialty alumina landscape. Powder bed fusion and binder jetting systems require spherical, narrow-distribution alumina powders with controlled morphology. German and French aerospace suppliers are qualifying domestic sources for 3D-printed ceramic cores and tooling, compressing the addressable market for traditional crushed and ground abrasives.
REACH restrictions on hazardous impurities are tightening specifications for alumina destined for consumer-contact applications. ECHA's 2023-2025 substance evaluation work program targets heavy metal traces in polishing compounds and catalyst supports. Cosmetic and pharmaceutical end-users in Switzerland and the Netherlands are demanding third-party purity certifications that exceed baseline regulatory thresholds.
Buyers are consolidating supplier relationships around integrated emissions reporting. Automotive OEMs in Stuttgart and Munich now require Scope 3 aluminum verification from Tier 1 foundries, pushing refractory and abrasive distributors to source exclusively from smelters with certified low-carbon output. This preference shift favors Norsk Hydro's Norwegian network and Alteo's French manufacturing footprint over Mediterranean imports.
Europe Aluminum Oxide Market Segmentation
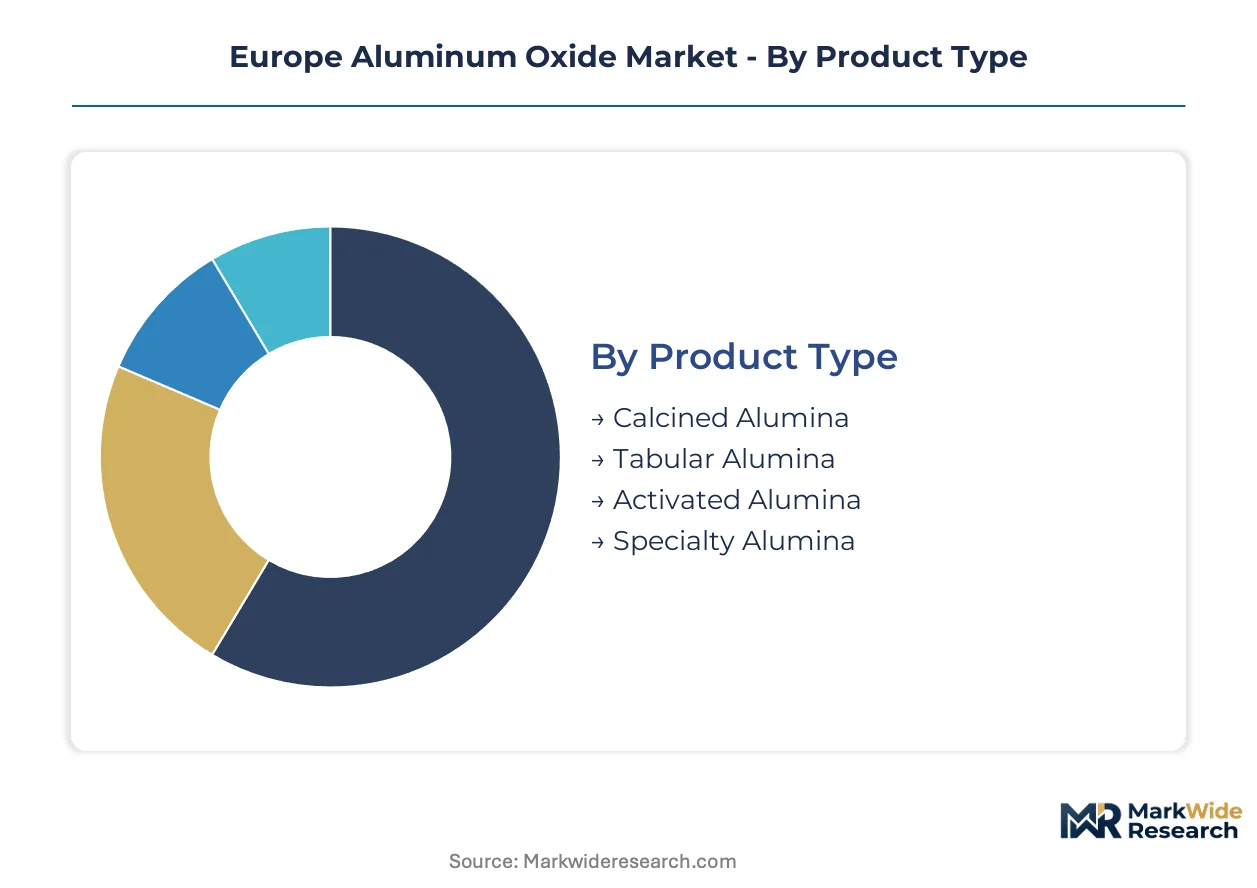
European aluminum oxide demand fragments across purity grades and thermal specifications, with regulatory thresholds under REACH and the EU Green Deal creating distinct commercial tiers that reward certified low-carbon output and ultra-high purity.
Product Type:
REACH substance evaluation work programs and ECHA impurity thresholds stratify product categories by certification burden and end-use eligibility.
- Specialty Alumina:Ultra-high purity grades spanning 99.99% alpha-Al₂O₃ with controlled soda content below 0.05%. European aerospace OEMs in Toulouse and Hamburg specify these grades for thermal barrier coatings on turbine blades, with procurement contingent on verified emissions documentation under the EU Green Deal.
- Tabular Alumina:Dense, fully recrystallized alpha-alumina produced above 1,800°C delivers exceptional thermal shock resistance. Steel producers across Germany's Ruhr Valley and northern Italy adopt tabular alumina for electric arc furnace linings, extending refractory campaign life.
- Calcined Alumina:Standard Bayer-process output serves metallurgical feedstock and general abrasive applications across Central European manufacturing.
- Activated Alumina:High-surface-area gamma-phase material functions in catalyst supports and desiccant applications for chemical processing.
Established volume favors calcined alumina; emerging adoption favors specialty alumina.
Application:
End-use thermal requirements and CE marking obligations under the Construction Products Regulation segment demand by infrastructure exposure and performance certification.
- Refractory:Monolithic and shaped linings for steel, cement, and glass furnaces dominate European volume absorption. German steelworks and Italian ceramic kiln operators specify alumina contents above 90% for slag resistance, with CE marking mandatory for infrastructure-adjacent installations.
- Coatings:Plasma-sprayed thermal barrier systems and wear-resistant layers require narrow particle distributions. French aerospace suppliers qualify domestic alumina sources for turbine blade protection, displacing imported feedstock.
- Ceramics:Technical ceramic substrates for electronics and structural components utilize high-purity grades from French and German refiners.
- Polishing:Precision finishing compounds for semiconductor wafers and optical glass face tightening ECHA heavy metal restrictions.
Refractory commands the largest volume position; coatings capture the steepest expansion trajectory.
End User:
Scope 3 emissions verification requirements from automotive and aerospace OEMs are bifurcating supply relationships around certified low-carbon credentials.
- Aerospace:European OEMs mandate ultra-low soda alumina for engine hot-section components. Stuttgart and Munich-based Tier 1 suppliers source exclusively from smelters with verified hydroelectric power.
- Automotive:Foundries and casting operations require refractory alumina for die-cooling systems and investment casting shells, with F-Gas Regulation phase-down favoring low-PFC smelter networks.
- Construction:Infrastructure refractory and abrasive applications fall under CE marking requirements, filtering non-conforming imports from Mediterranean suppliers.
- Electrical:Ceramic substrates for power electronics and LED thermal management demand high-purity grades from specialized French refiners.
Automotive absorbs the widest volume; aerospace commands the premium tier.
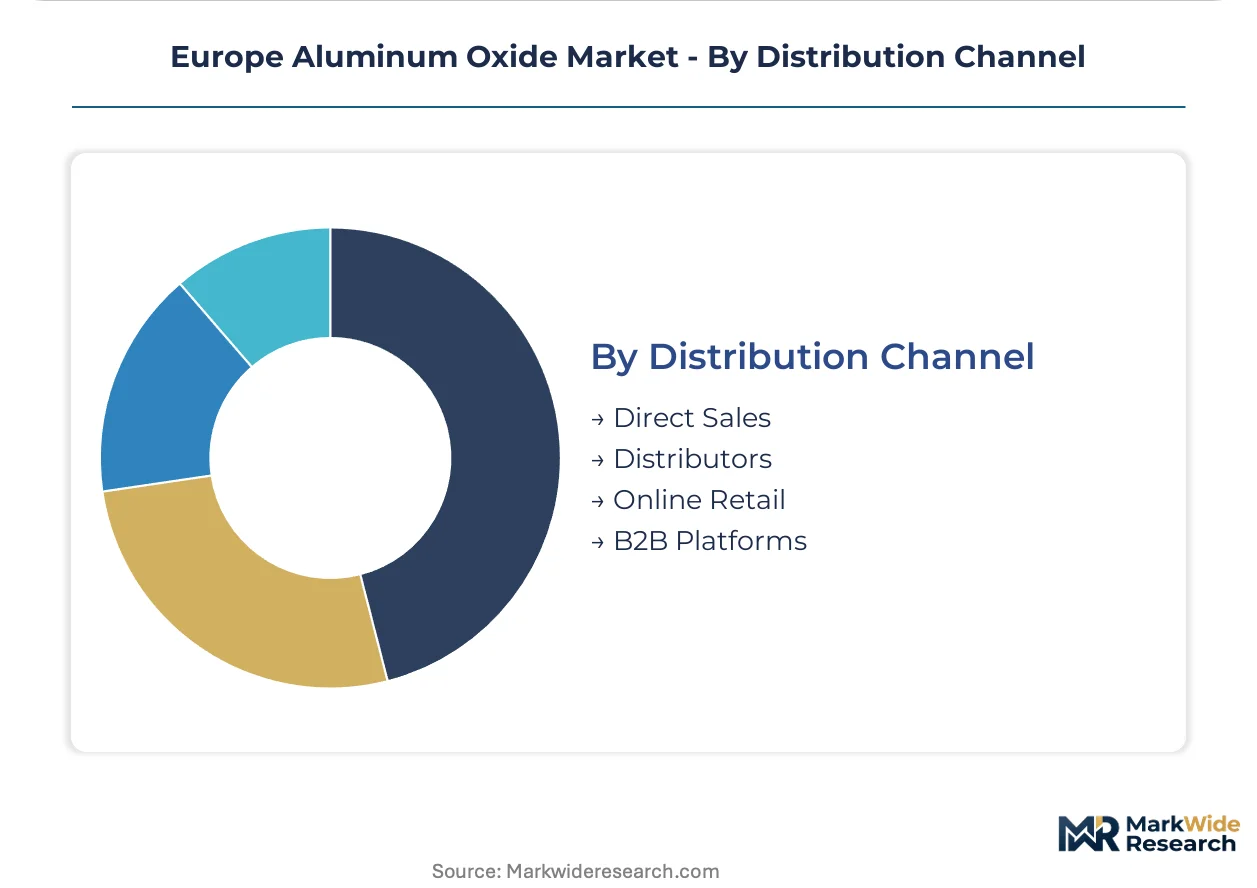
Distribution Channel:
Customer scale and technical service requirements determine channel selection, with integrated refractory producers favoring direct relationships.
- Direct Sales:Large refractory manufacturers and aerospace Tier 1 suppliers contract directly with alumina refiners for specification-matched volumes. BASF SE's Ludwigshafen complex and Norsk Hydro's Norwegian network maintain captive supply arrangements.
- Distributors:Regional abrasive and ceramic raw material distributors serve mid-tier foundries and polishing compound blenders across Poland and the Czech Republic.
- B2B Platforms:Industrial procurement marketplaces facilitate spot purchases for standardized calcined grades.
- Online Retail:Small-volume specialty alumina for research and prototyping flows through chemical supply e-commerce.
Direct sales anchor high-value specialty volumes; distributor networks penetrate emerging Central European industrial corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework governs chemical registration across the continent, anchoring regulatory compliance in the European aluminum oxide trade. National industrial policies and carbon border mechanisms now determine competitive positioning within each market.
Germany
Ruhr Valley steelworks drive refractory alumina consumption for electric arc furnace linings. The country's national emissions trading system tightens calciner operations, raising compliance costs for mid-tier refiners. Ludwigshafen's chemical corridor hosts integrated complexes serving catalyst and polishing applications.
France
Aerospace OEMs in Toulouse specify ultra-low soda alumina for turbine blade thermal barriers. CE marking requirements under the Construction Products Regulation filter non-conforming abrasive imports. Southern manufacturing clusters specialize in high-purity calcined grades for technical ceramics.
Norway
Hydroelectric-powered smelters supply low-carbon feedstock favored by automotive OEMs in Stuttgart and Munich. The EU Green Deal's carbon border adjustment mechanism rewards Norwegian producers with verified emissions credentials. Nordic production networks anchor premium-tier supply relationships.
Italy
Northern ceramic kiln operators and steel producers absorb tabular alumina for refractory upgrades. REACH registration burdens deter new entrants from high-margin specialty segments. Emilia-Romagna's industrial districts concentrate abrasive manufacturing for European export markets.
Poland
Greenfield steel and cement capacity in Silesia lacks established refractory supply relationships. The EU industrial emissions directive pressures legacy calciner retrofits. Central European distributors penetrate emerging corridors with standardized calcined grades for foundry applications.
Europe Aluminum Oxide Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. German and French chemical conglomerates maintain captive alumina supply for downstream catalyst and polishing operations. Nordic smelter networks exploit hydroelectric power to capture carbon-conscious procurement. Specialist refiners concentrate on purity grades that commodity producers cannot replicate. Competitive moves center on emissions certification partnerships and specialty capacity expansion near aerospace clusters.
Among the integrated chemical leaders, BASF SE anchors its Ludwigshafen complex with in-house production of high-purity grades. Norsk Hydro ASA exemplifies the Nordic low-carbon archetype through its Norwegian smelter network. Alteo occupies a position within the French specialist tier, representing high-purity calcined production from its domestic manufacturing footprint. These three entities illustrate how geographic positioning and energy sourcing now determine competitive advantage under EU carbon border mechanisms.
| Leading Market Players |
|---|
| Huber Engineered Materials |
| BASF SE |
| Hindalco Industries |
| Alcoa Corporation |
| Evonik Industries AG |
| Norsk Hydro ASA |
| Alteo |
| Rio Tinto Group |
| Sasol Limited |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day bauxite shipping schedules from Guinea and Australia compress inventory buffers for European refiners, concentrating pricing power with Nordic hydroelectric smelters that bypass carbon border penalties and command premium placement in automotive and aerospace procurement.
Pricing Analysis
Geographic price spreads between Norwegian hydroelectric smelters and Mediterranean gas-powered producers now exceed the freight differential itself. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified specialty grades from commodity calcined alumina and unregistered imports. Price differentiation hinges on verified Scope 3 emissions documentation and soda content certification. Pricing pressure stems from TTF natural gas benchmark volatility eroding calciner margins. Mid-tier foundries in Central Europe exhibit highest price sensitivity; aerospace Tier 1 suppliers in Toulouse and Hamburg demonstrate lowest.
Supply Chain Analysis
Bauxite import chokepoints through Guinea's Conakry port and Australian bulk terminals expose European refiners to seaborne freight volatility and geopolitical disruption. Supply concentrates in Norway, France, and Germany for high-purity grades, while commodity calcined alumina feeds from Spain and Italy. Raw material dependencies rest on Guinean bauxite, Australian metallurgical-grade alumina, and Icelandic hydroelectric power. Single-source vulnerability runs through Atlantic shipping lanes. Distribution runs through integrated refractory manufacturers and regional distributors serving Poland and Czech Republic foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for refractory lining optimization and emissions compliance consulting now expand faster than commodity alumina tonnage, creating recurring-revenue layers that integrated producers are bundling with long-term supply agreements.
For Market Incumbents: Consolidate around captive hydroelectric power and REACH certification depth. BASF SE's Ludwigshafen complex and Norsk Hydro's Norwegian network demonstrate how backward integration into low-carbon smelting insulates margin structures from EU carbon border adjustment penalties. Capacity expansion in French aerospace corridors captures thermal barrier coating demand. Defend against battery-material startups poaching process chemists through compensation benchmarking and technical career ladders. For New Entrants and Emerging Players: Differentiate on emissions verification services and Central European geographic proximity. Poland and Czech Republic greenfield steel capacity lacks established refractory supply relationships, representing the most penetrable corridor. Target tabular alumina for electric arc furnace upgrades where incumbent relationships remain unsettled. Go-to-market through technical sales teams embedded with Silesian steelworks procurement. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-credentials infrastructure play because verified low-carbon output becomes a procurement filter across automotive, aerospace, and construction end-uses. Acquisition targets include mid-tier French and German refiners with REACH registration portfolios and retrofittable calciner assets. Watch Nordic hydroelectric capacity expansion announcements as the inflection signal for premium-tier supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Trading | Guinea and Australian offtake agreements reduce freight volatility exposure for European calciners. |
| Green Manufacturing Transition | Hydroelectric calcination investments qualify output for EU Green Deal carbon border adjustment preferences. |
| Long-term Supply Agreement | Automotive OEMs in Stuttgart mandate Scope 3 verification from Tier 1 foundry networks. |
| Joint Venture | French aerospace clusters partner with Alteo for domestic thermal barrier coating feedstock qualification. |
| Capacity Expansion | Ruhr Valley refractory demand drives tabular alumina kiln investments near steelworks. |
Research Methodology
Initial hypotheses were tested against primary input from alumina refinery plant managers, procurement leads at German steelworks and French aerospace Tier 1 suppliers, refractory distribution channel partners, and ECHA regulatory affairs specialists, then refined through secondary validation against customs and trade data, European Chemical Industry Council reports, SEC 10-K filings from listed producers, and national emissions trading system disclosures. Bottom-up volume estimates from individual facility capacities and top-down demand modeling from end-use consumption patterns were triangulated.
Variance decomposition across purity grade, end-use industry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation. Forecast inputs included electric arc furnace upgrade cycles in European steelworks and solid-state lithium-ion ceramic separator film development timelines in Germany and Sweden.
The analysis sits within stated boundaries; outcomes outside sustained EU carbon border adjustment enforcement or abrupt bauxite supply disruption would require recalibration. Forecasts reflect documented assumptions regarding REACH substance evaluation timelines and F-Gas Regulation phase-down trajectories. Practitioners should keep alternative scenarios live as Nordic hydroelectric capacity availability and Atlantic shipping lane security evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Potassium Silicate Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
Earthenware Market
Ceramics
Construction Ceramics Market
Ceramics
Dielectric Ceramics Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
White Fused Alumina Market
Ceramics
Automotive Ceramics Market
Ceramics
Titanates Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
North America Barium Carbonate Market
Ceramics
Pottery Ceramics Market
Ceramics
Calcined Alumina Market