
 Malaysia Ceramic Tiles Market | 2026-2036
Malaysia Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Ceramic Tiles Market Foresight
Malaysia's Green Building Index certification is expanding its coverage to interior finishes, compelling developers across the Klang Valley to specify tiles with verified recycled content and lower firing emissions. White Horse Ceramic Industries Sdn Bhd leverages its integrated clay-to-distribution pipeline to secure large hospitality contracts in Penang and Malacca. Kim Hin Industry Berhad anchors its position through specialized vitrified tile production for industrial flooring applications. Seacera Group Berhad differentiates via controlled channel presence in East Malaysia, where logistics complexity limits competitor reach.
Ceramic tiles are flat, thin slabs formed from refined clay, silica, and flux minerals, then fired at temperatures exceeding 1,000 degrees Celsius to achieve hardness, water resistance, and dimensional stability; they serve primarily as protective and decorative surfacing for floors and walls in built environments. Porcelain variants command premium positioning due to lower water absorption rates below 0.5 percent, making them specification-critical for commercial and hospitality wet areas. Large Format tiles are gaining fastest in residential high-rise developments where fewer grout lines reduce maintenance labor and accelerate installation timelines. The Glazed segment sustains volume leadership across retail and mass housing channels where cost sensitivity dominates procurement decisions.
BIS and SIRIM QAS International standards govern product safety and performance labeling for ceramic tiles sold in Malaysia, while CIDB registration requirements shape contractor eligibility for public infrastructure tile supply. The Department of Standards Malaysia actively harmonizes local test methods with ISO 13006 benchmarks to facilitate cross-border trade with ASEAN neighbors. Stakeholders must monitor enforcement timelines for embodied carbon disclosure rules under the National Low Carbon Cities Framework, as these will reshape supplier qualification criteria and procurement specifications ahead of the next planning cycle.
Market Dynamics
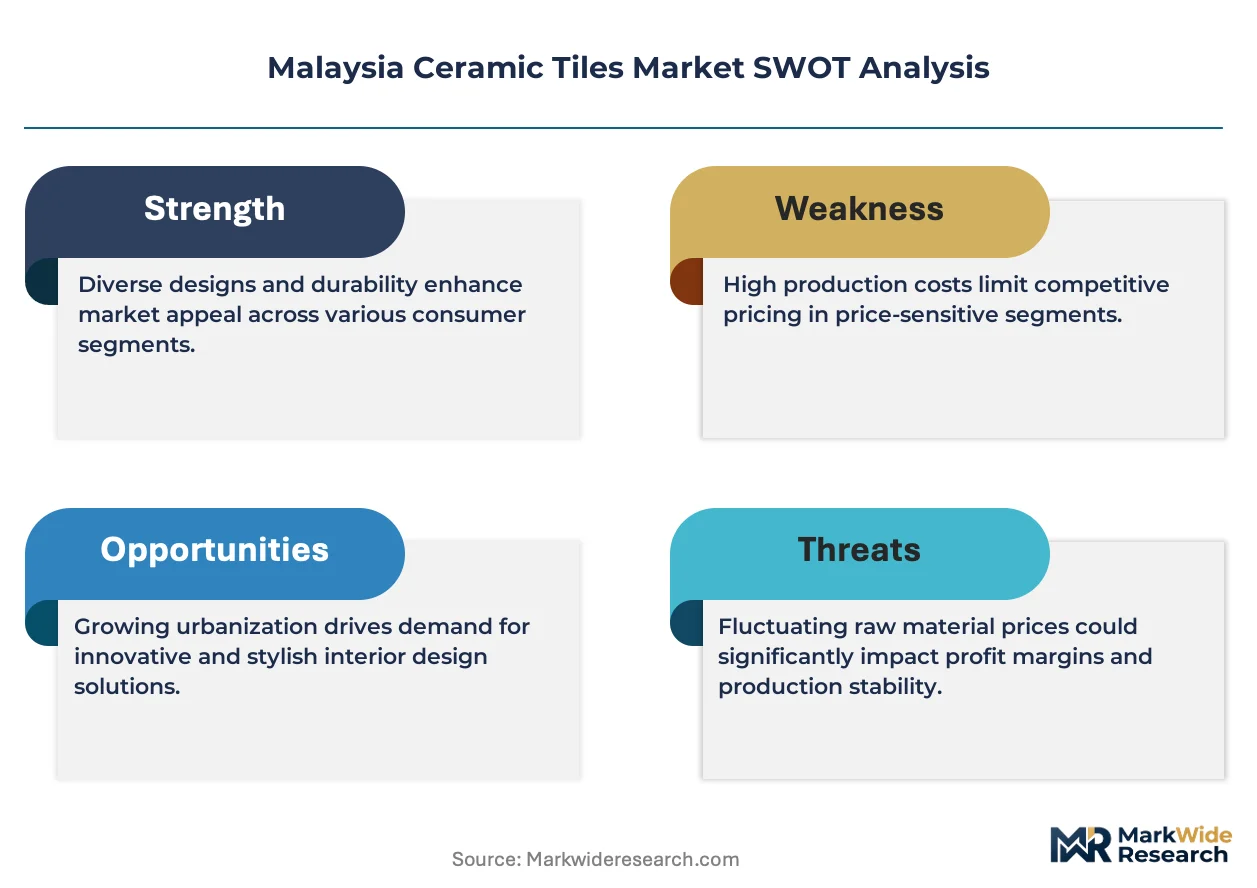
CIDB Green Building Index certification expansion into interior finishes is restructuring procurement specifications across Malaysian construction, forcing developers to validate recycled content claims and firing emission profiles before contract award.
Growth Catalysts
- CIDB Green Building Index:Interior finish coverage mandates now require verified recycled content documentation, pulling specification-grade porcelain into mass housing developments across Selangor and Johor.
- Industrial Flooring:Vitrified tile demand from electronics manufacturing parks in Penang and Kulim is accelerating specification volumes for chemical-resistant, heavy-load surface solutions.
- Large-Format Technology:Digital printing and continuous roller kilns are reducing grout-line counts in high-rise residential towers, compressing installation timelines and maintenance labor contracts.
Market Restraints
- Natural Gas Price Volatility:Firing costs for porcelain production fluctuate with Malaysia's piped gas tariff adjustments, squeezing margin stability for continuous-operation kiln operators.
- Import Concentration Risk:Specialized glaze pigments and digital printer inks concentrate sourcing from concentrated Asian supply bases, exposing finished goods producers to shipping disruption.
- Technical Limitation:Large-format tile installation requires certified thin-bed adhesive systems and skilled labor pools that remain thin outside Klang Valley and Penang Island.
Strategic Opportunities
- East Malaysia Logistics Gap:Sabah and Sarawak construction markets remain underserved due to inter-island shipping complexity, rewarding controlled distribution investments in Kota Kinabalu and Kuching.
- National Low Carbon Cities Framework:Embodied carbon disclosure rules scheduled for enforcement will disqualify high-emission suppliers from public infrastructure tenders, creating first-mover advantage for verified low-carbon producers.
- Digital Specification Platforms:Architect and contractor procurement is fragmenting toward BIM-integrated material libraries that bypass traditional distributor relationships.
Industry Challenges
- Thin-Bed Installation Certification:CIDB-registered contractor pools qualified for large-format adhesive systems remain insufficient for projected high-rise completion rates.
- SIRIM QAS Harmonization Timeline:ISO 13006 alignment delays are creating dual-testing burdens for exporters seeking ASEAN market access.
- Kiln Retrofit Capex:Low-emission firing technology upgrades require capital commitments that mid-scale producers struggle to finance against compressed contract margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Ceramic Tiles Market |
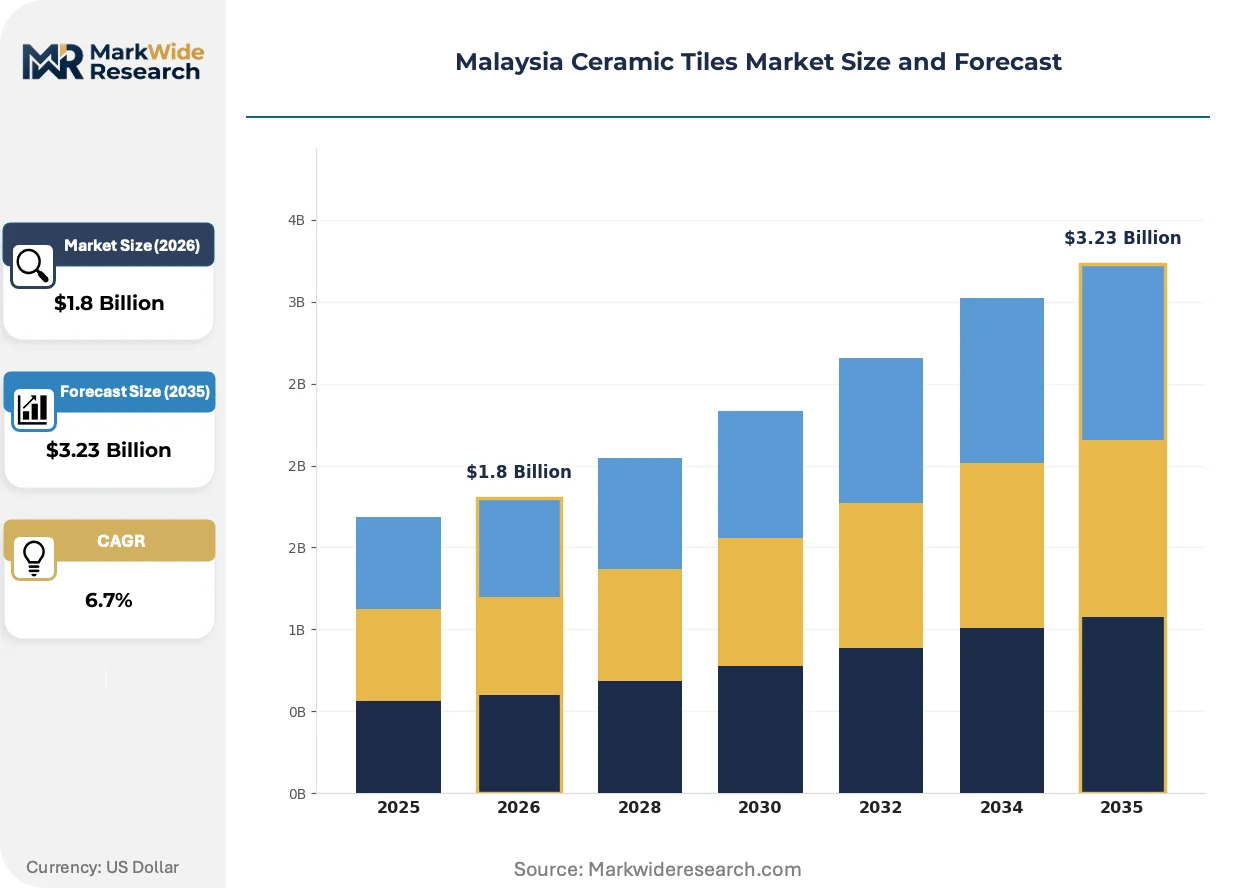
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
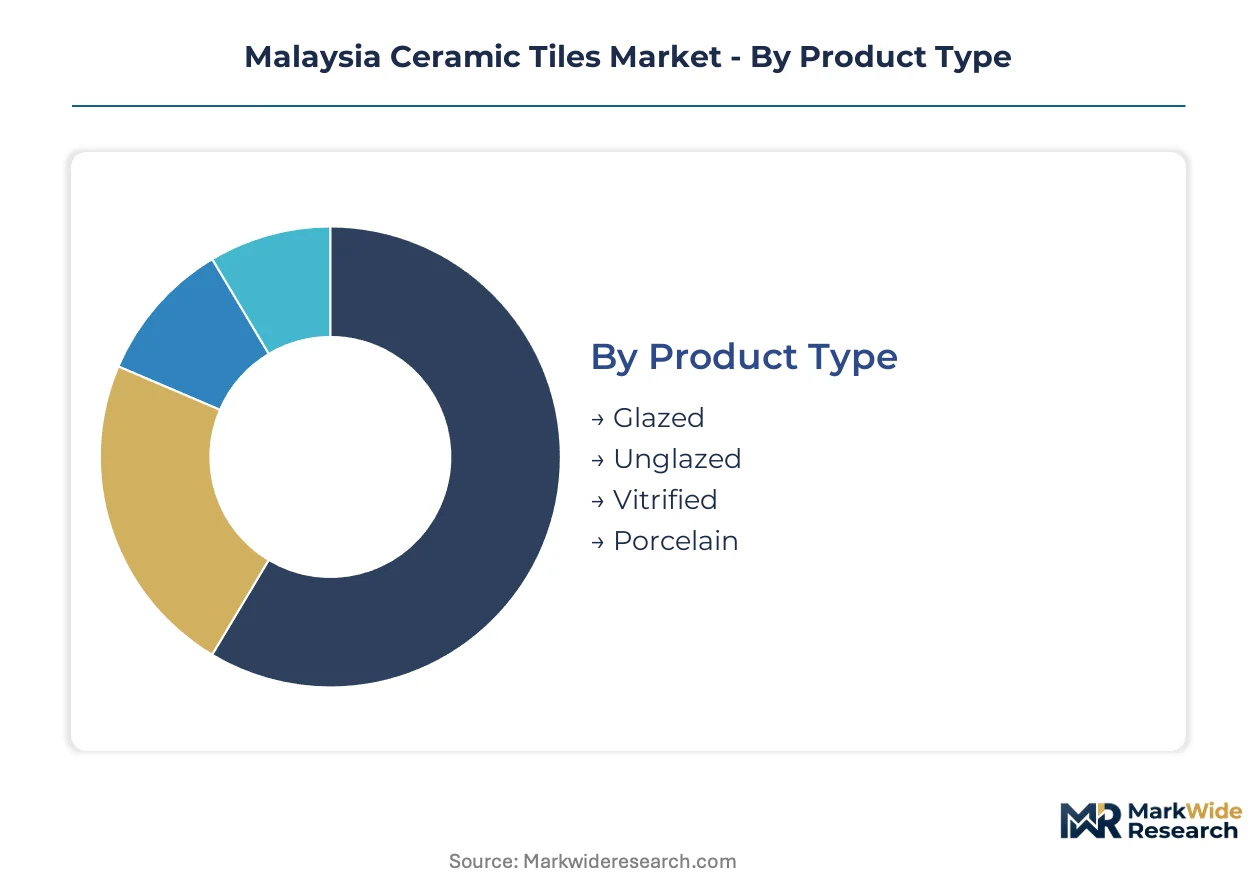
| Segmentation | Product Type: Glazed, Unglazed, Vitrified, Porcelain Application: Residential, Commercial, Industrial, Hospitality Material: Ceramic, Stone, Glass, Composite Size: Small Format, Medium Format, Large Format, Mosaic |
| Companies Covered | White Horse Ceramic Industries Sdn Bhd, Kim Hin Industry Berhad, Venus Ceramic Industry Sdn Bhd, Niro Ceramic Group, Malaysia Mosaic Sdn Bhd, Seacera Group Berhad, Yi-Lai Industry Berhad, Deer Tiles, Guocera Holdings Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Ceramic Tiles Market Shifts & Advancements
Digital manufacturing and sustainability verification are compressing traditional specification cycles while fragmenting procurement channels across Malaysian construction. Three active shifts are restructuring competitive position.
Large-format porcelain production is consolidating market share in residential high-rise developments. These slabs reduce grout-line maintenance burden while accelerating installation speed. Developers in the Klang Valley corridor are specifying 600x1200mm and 800x1600mm formats as standard, compressing demand for conventional 300x300mm glazed ceramic in premium residential towers.
SIRIM QAS International is harmonizing local test methods with ISO 13006 benchmarks to streamline cross-border trade with Indonesia, Thailand, and Vietnam. This alignment reduces duplicate certification costs for Malaysian exporters. Tile producers serving ASEAN markets are restructuring quality control protocols to meet unified performance labeling standards ahead of full enforcement.
Architects and main contractors are fragmenting procurement toward BIM-integrated material specification platforms that embed performance data directly into design workflows. Traditional distributor relationships face disintermediation pressure in commercial and hospitality verticals. This channel shift concentrates in Penang and Kuala Lumpur, where design-build contracts dominate project delivery.
Malaysia Ceramic Tiles Market Segmentation
Malaysian tile procurement splits sharply between specification-grade products for certified green buildings and commodity-grade ceramics for mass housing. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume flows.
Product Type:
Standardization dominates glazed and unglazed production, while vitrified and porcelain lines require tighter technical control and firing precision.
- Glazed:Clay bodies receive glass-forming mineral coatings before single-firing, delivering cost-efficient water resistance for retail and mass housing channels across Selangor and Johor. Specification volumes here track CIDB Green Building Index adoption curves, with developers now demanding verified recycled content documentation before contract award.
- Porcelain:Higher-density kaolin formulations fired above 1,200 degrees Celsius achieve water absorption below 0.5 percent, making these tiles mandatory for commercial wet areas and hospitality kitchens in Penang and Kuala Lumpur. Klang Valley high-rises specify these for podium-level pools and spa facilities where failure carries liability exposure.
- Unglazed:Through-body color consistency suits industrial flooring where surface wear reveals identical substrate tones. Chemical resistance specifications from electronics manufacturing parks in Kulim drive quality requirements.
- Vitrified:Full-body glass formation creates near-zero porosity surfaces for heavy-load environments. Demand concentrates in Penang's industrial corridors where semiconductor fabrication facilities require static-dissipative flooring systems.
Leading the category by volume: Glazed. Growing fastest: Porcelain.
Application:
End-use differentiation separates project-scale procurement from maintenance-driven replacement cycles.
- Residential:Klang Valley high-rise developers specify large-format porcelain to compress installation timelines and reduce grout-line maintenance in service charge calculations. Digital printing technology enables wood-grain and stone visual replication at ceramic cost points.
- Commercial:Office tower lobbies and retail podiums demand slip-resistant surfaces with aesthetic flexibility. BIM-integrated specification platforms in Kuala Lumpur and Penang are fragmenting traditional distributor relationships for this vertical.
- Industrial:Electronics manufacturing parks require chemical-resistant, heavy-load vitrified systems. Kim Hin Industry Berhad anchors supply relationships through specialized technical service capabilities.
- Hospitality:Resort developments in Malacca and Penang prioritize stain resistance and design differentiation. White Horse Ceramic Industries leverages integrated clay-to-distribution pipelines for large contract execution.
Residential commands absolute volume. Hospitality shows steepest specification upgrade trajectory.
Material:
Cost tiers separate ceramic dominance from premium alternatives serving design-driven verticals.
- Ceramic:Refined clay, silica, and flux mineral formulations fire above 1,000 degrees Celsius to achieve hardness and dimensional stability. This substrate underpins volume production for mass housing and retail replacement markets throughout Peninsular Malaysia.
- Stone:Natural marble and granite alternatives command premium positioning in hospitality lobbies and executive residential towers where authentic material narratives justify cost multiples.
- Glass:Recycled content formulations serve backsplash and accent wall applications in commercial kitchens and boutique retail. SIRIM QAS certification requirements shape import sourcing patterns.
- Composite:Engineered stone-polymer blends target renovation markets where weight constraints limit natural stone specification. East Malaysia shipping complexity limits competitive supply for this niche.
Ceramic holds volume leadership. Composite materials are gaining specification traction fastest.
Size:
Format selection directly determines installation labor requirements and long-term maintenance economics.
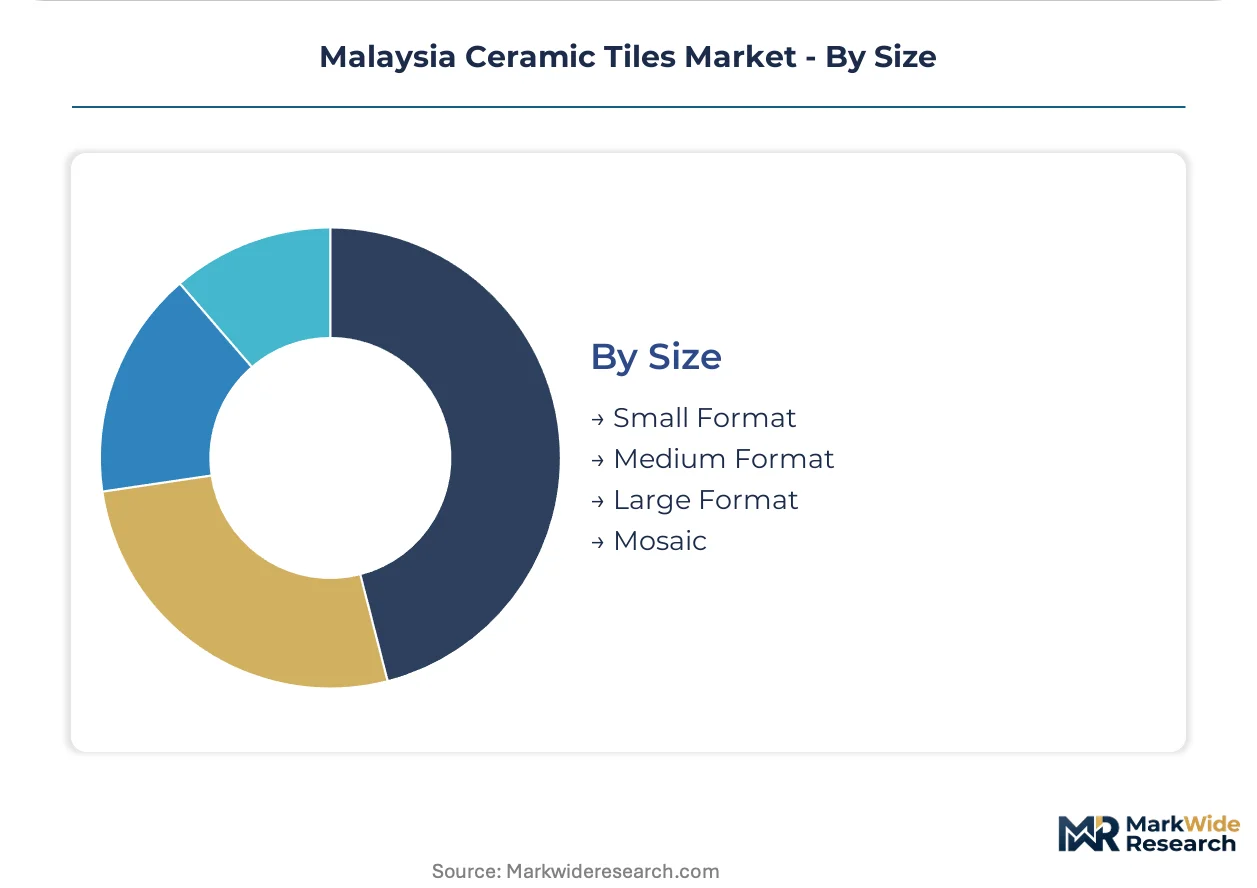
- Large Format:Slabs exceeding 600x1200mm reduce grout-line counts and accelerate installation in Klang Valley high-rises where skilled labor pools remain thin. Continuous roller kiln technology enables cost-efficient production at scale.
- Medium Format:300x600mm and 400x800mm dimensions balance installation speed with handling logistics for mid-market residential developments across Selangor and Johor.
- Small Format:300x300mm and smaller dimensions persist in renovation markets and budget housing where existing adhesive beds limit upgrade options. Volume concentrates in replacement cycles rather than new construction.
- Mosaic:Mesh-mounted small pieces enable complex pattern execution for hospitality feature walls and swimming pool waterlines. Seacera Group Berhad controls distribution reach for this segment in East Malaysia.
Medium Format maintains volume dominance. Large Format is climbing the fastest as high-rise completion rates accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian ceramic tile production concentrates in Peninsular Malaysia's industrial corridors while consumption spreads across both Peninsular and East Malaysian construction markets. This geographic split creates logistics-driven competitive boundaries that favor regionally anchored distributors.
Selangor
Klang Valley high-rise developers specify large-format porcelain for residential towers in Petaling Jaya and Shah Alam, compressing installation timelines. CIDB Green Building Index certification requirements now mandate verified recycled content documentation for interior finishes. Subang Jaya industrial zones host continuous roller kiln operations serving mass housing procurement across the corridor.
Johor
Iskandar Malaysia economic zone drives bulk tile procurement for industrial park infrastructure and mass housing estates. The National Low Carbon Cities Framework disclosure rules are reshaping supplier qualification criteria for public tenders. Johor Bahru construction markets absorb volume shipments through Port of Tanjung Pelepas logistics channels.
Penang
Electronics manufacturing parks in Kulim and Bayan Lepas generate specialized vitrified tile demand for chemical-resistant industrial flooring. SIRIM QAS International harmonization with ISO 13006 benchmarks streamlines export certification for ASEAN market access. Georgetown hospitality developments specify premium porcelain for resort and heritage hotel renovations.
Sabah
Kota Kinabalu construction markets remain underserved due to inter-island shipping complexity from Peninsular supply bases. The country's national standards body maintains local test method alignment with regional benchmarks. Controlled distribution investments in East Malaysia reward operators who overcome logistics fragmentation.
Sarawak
Kuching and Miri development projects face extended lead times for specialized tile formats sourced from western production centers. CIDB contractor registration requirements shape eligibility for public infrastructure supply contracts. Local distributors with captive warehousing occupy defensive positions against Peninsular competitors.
Malaysia Ceramic Tiles Market Competitive Landscape
The competitive structure tilts toward integrated clay-to-distribution specialists with captive logistics networks. Mid-scale producers cluster around standardized glazed ceramic output for mass housing channels, while premium-tier operators concentrate on porcelain and vitrified specifications for commercial and industrial verticals. Two archetypes dominate: vertically integrated manufacturers with owned quarry resources, and regional distributors with controlled East Malaysia reach. Competitive moves center on kiln technology upgrades for emission compliance and logistics investments to close the Sabah-Sarawak coverage gap.
Among Malaysia-based fabricators, White Horse Ceramic Industries Sdn Bhd, Kim Hin Industry Berhad, and Seacera Group Berhad exemplify distinct strategic positions. White Horse represents the integrated production archetype with quarry-to-distribution pipeline control. Kim Hin anchors the industrial flooring specialization vector through technical service capabilities. Seacera occupies the geographic differentiation position with controlled channel presence in East Malaysia where shipping complexity limits competitor reach.
| Leading Market Players |
|---|
| White Horse Ceramic Industries Sdn Bhd |
| Kim Hin Industry Berhad |
| Venus Ceramic Industry Sdn Bhd |
| Niro Ceramic Group |
| Malaysia Mosaic Sdn Bhd |
| Seacera Group Berhad |
| Yi-Lai Industry Berhad |
| Deer Tiles |
| Guocera Holdings Sdn Bhd |
| Others |
Supply & Pricing Matrix
Natural gas tariffs for continuous roller kiln operations cascade through three distinct pricing tiers, with firing cost volatility compressing margins for mid-scale glazed ceramic producers while integrated porcelain manufacturers absorb fluctuations through captive clay quarry access.
Pricing Analysis
Value-based pricing for vitrified industrial flooring anchors on chemical resistance performance and static-dissipative certification, with Kim Hin Industry Berhad commanding premium positioning through technical service bundling. Three-tier pricing structure across premium porcelain, standard glazed, and economy ceramic levels separates specification-grade products from mass housing commodities. Pricing pressure stems from compressed contract margins in Selangor mass housing tenders, where developers prioritize procurement cost over lifecycle durability. Mass housing contractors exhibit highest price sensitivity, while electronics manufacturing parks in Penang demonstrate lowest sensitivity due to failure liability exposure.
Supply Chain Analysis
CIDB Green Building Index interior finish mandates are reshaping domestic sourcing requirements, with verified recycled content documentation now prerequisite for public infrastructure eligibility. Clay deposits concentrate in Perak and Kedah, while specialized glaze pigments and digital printer inks draw from concentrated Asian supply bases in China and India. Single-source vulnerability for high-performance ink formulations exposes finished goods producers to shipping disruption through the Strait of Malacca. Distribution runs through vertically integrated manufacturers with captive logistics networks, supplemented by regional distributors controlling East Malaysia warehouse positions in Kota Kinabalu and Kuching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-bed adhesive installation certification scarcity constrains large-format porcelain deployment velocity, propping specification premiums for qualified contractors and kiln operators with emission-compliant firing technology.
For Market Incumbents: Hedge natural gas tariff exposure through long-term TNB gas supply agreements or biomass co-firing retrofit investments. Secure CIDB Green Building Index pre-certification for porcelain lines ahead of National Low Carbon Cities Framework enforcement. Prioritize captive warehousing in Sabah and Sarawak to defend channel position against Peninsular competitors facing inter-island logistics complexity. For New Entrants and Emerging Players: Digital printing technology for wood-grain and stone visual replication offers entry into Klang Valley high-rise residential specification, where aesthetic flexibility commands premium positioning over commodity glazed ceramic. Target Kota Kinabalu and Kuching construction markets through controlled distribution investments, exploiting logistics fragmentation that limits incumbent reach. Pursue BIM-integrated material library partnerships with Kuala Lumpur and Penang design-build contractors to bypass traditional distributor gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated clay-to-distribution specialists with captive quarry resources in Perak and Kedah, where backward integration insulates margin compression from raw material volatility. Long-term viability centers on emission-compliant kiln technology and East Malaysia logistics infrastructure capable of serving underserved Sabah-Sarawak construction markets. Monitor CIDB contractor registration timelines for large-format adhesive systems as inflection indicator for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Roller Kiln Upgrade | Low-emission firing technology enables CIDB Green Building Index compliance for Selangor public tenders. |
| East Malaysia Distribution Expansion | Captive warehousing in Kota Kinabalu closes logistics gap for Sabah construction market access. |
| Digital Printing Capability Investment | Wood-grain visual replication penetrates Klang Valley high-rise residential specification channels. |
| Thin-Bed Adhesive Certification Program | CIDB-registered contractor pools accelerate large-format porcelain installation throughput. |
| Biomass Co-Firing Retrofit | Alternative fuel sourcing hedges natural gas tariff volatility for continuous kiln operations. |
Research Methodology
Multi-period observation of CIDB Green Building Index adoption curves, SIRIM QAS certification volumes, and Klang Valley high-rise completion rates anchored the trend analysis, supplemented by interviews with ceramic plant operations directors, construction procurement managers at Selangor developers, and East Malaysia distribution channel partners. Secondary validation drew from Department of Standards Malaysia harmonization bulletins, CIDB contractor registration databases, and customs trade data for glaze pigment imports. Bottom-up tile production capacity estimates triangulated against top-down construction sector material intensity benchmarks.
Segment-weighting across product type, application, and regional demand clusters shaped the analytical framework, with porcelain specification growth, vitrified industrial flooring penetration, and East Malaysia logistics gap closure modeled as distinct trajectory inputs. CAGRs were derived from elasticity-adjusted demand projections tied to housing completion schedules and electronics manufacturing park expansion timelines. Firing technology emission profiles and thin-bed adhesive certification scarcity factored as supply-constraint modifiers.
Several conditions sit outside the modeled scope, including abrupt natural gas tariff rebalancing, Strait of Malacca shipping disruption severity, and CIDB enforcement timeline acceleration for embodied carbon disclosure. Forecasts reflect documented assumptions regarding housing policy continuity and industrial park investment commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
UAE Ceramic Tiles Market
Ceramics
Refractories Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Active Calcium Silicate Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Methyl Silicate Market
Ceramics
North America Ceramic Coatings Market
Ceramics
2N High Purity Alumina Market
Ceramics
Ball Clay Market
Ceramics
Earthenware Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Clay Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Zeolite 4A Market