
 Ceramic Substrate Market | 2026-2036
Ceramic Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Substrate Market Intelligence
A capital-intensity divergence between integrated material producers and specialized substrate fabricators is unwinding the market's traditional value chain. KYOCERA Corporation leverages its extensive in-house production of raw ceramic powders to control costs and quality. CoorsTek Inc. specializes in advanced technical ceramics for high-stress applications in aerospace and defense. Murata Manufacturing Co., Ltd. dominates specific niches with its multilayer ceramic technologies for telecommunication devices.
A ceramic substrate is a flat sheet of fired ceramic material, such as alumina or aluminum nitride, engineered for its high thermal conductivity and electrical insulation properties. It serves as a foundational base for mounting electronic components in high-power or high-frequency circuits, effectively dissipating heat. Alumina substrates remain the volume leader due to cost-effectiveness, but aluminum nitride and silicon nitride represent the fastest-growing product segments for demanding applications. Thick film technology is a mature process, while demand for low temperature cofired ceramic (LTCC) is accelerating for integrated RF devices.
Product standards are influenced by frameworks like the EU's RoHS directive, which restricts hazardous substances in electronics, and ISO standards for material quality. In the automotive sector, reliability testing protocols mandated by bodies like Germany's KBA and compliance with GB standards in China shape material selection. Suppliers must navigate this complex regulatory landscape while deciding whether to invest in capacity for next-generation materials like silicon nitride or optimize existing alumina production lines.
Market Dynamics
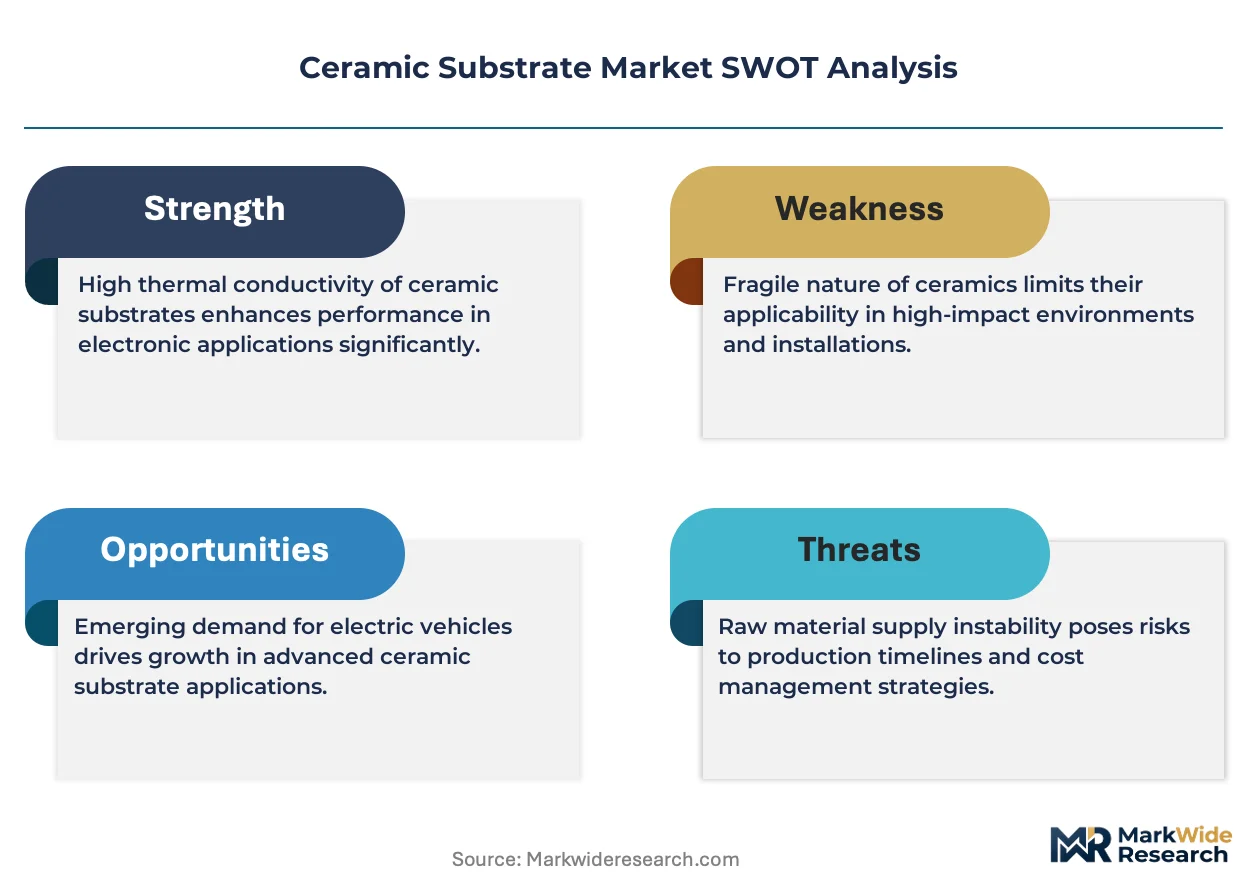
The central dynamic shaping the ceramic substrate market is the performance-cost tension between legacy alumina substrates and next-generation nitride ceramics. This divergence is driven by the acute thermal management requirements of power electronics in electric vehicles and advanced semiconductor packaging.
Growth Catalysts
- Electric Vehicle Power Modules:The expansion of the electric vehicle market propels demand for substrates with high thermal conductivity, such as silicon nitride, to manage heat in power inverters and on-board chargers, ensuring component reliability and longevity.
- Electronic Component Miniaturization:Demand for smaller, more powerful electronic devices, particularly in telecommunications and consumer electronics, accelerates the adoption of multilayer technologies like low temperature cofired ceramic (LTCC) for integrated modules.
- Semiconductor Industry Expansion:Concentrated investment in semiconductor fabrication facilities in geographies like South Korea and Japan creates sustained demand for high-purity alumina and aluminum nitride substrates used in chip manufacturing equipment and packaging.
Market Restraints
- High Manufacturing Costs:The production of non-oxide ceramics like aluminum nitride and silicon nitride requires high-purity raw materials and energy-intensive sintering processes at extreme temperatures, resulting in significantly higher costs compared to traditional alumina.
- Raw Material Supply Concentration:The global supply of high-quality ceramic powders, a critical input for advanced substrates, is concentrated among a few producers, creating price volatility and potential supply chain bottlenecks for substrate fabricators.
- Competition from Alternative Materials:In certain mid-power applications, insulated metal substrates (IMS) and advanced polymer-based circuit boards offer a lower-cost alternative with competitive thermal performance, posing a substitution threat to ceramic substrates.
Strategic Opportunities
- High-Frequency RF Devices:The rollout of 5G and future 6G telecommunication infrastructure presents a significant opportunity for low temperature cofired ceramic (LTCC) substrates, which offer the low signal loss required for integrated RF front-end modules.
- Medical Device and Aerospace Sectors:Underpenetrated markets such as implantable medical devices and aerospace electronics offer growth potential for biocompatible and high-reliability ceramic substrates, particularly those made from zirconia and specialized alumina.
- Localized Semiconductor Supply Chains:Policy initiatives in the United States and the European Union to onshore semiconductor manufacturing create opportunities for regional substrate suppliers to serve new fabrication plants, reducing reliance on Asian supply lines.
Industry Challenges
- Capital-Intensive Capacity Expansion:Investing in new production lines for advanced materials like silicon nitride requires substantial capital expenditure for specialized furnaces and cleanroom facilities, creating a high barrier to entry and constraining supply response.
- Navigating Divergent Standards:Suppliers must manage a complex web of regional and industry-specific compliance requirements, from automotive reliability protocols like Germany's KBA to hazardous substance rules like the EU's RoHS directive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Substrate Market |
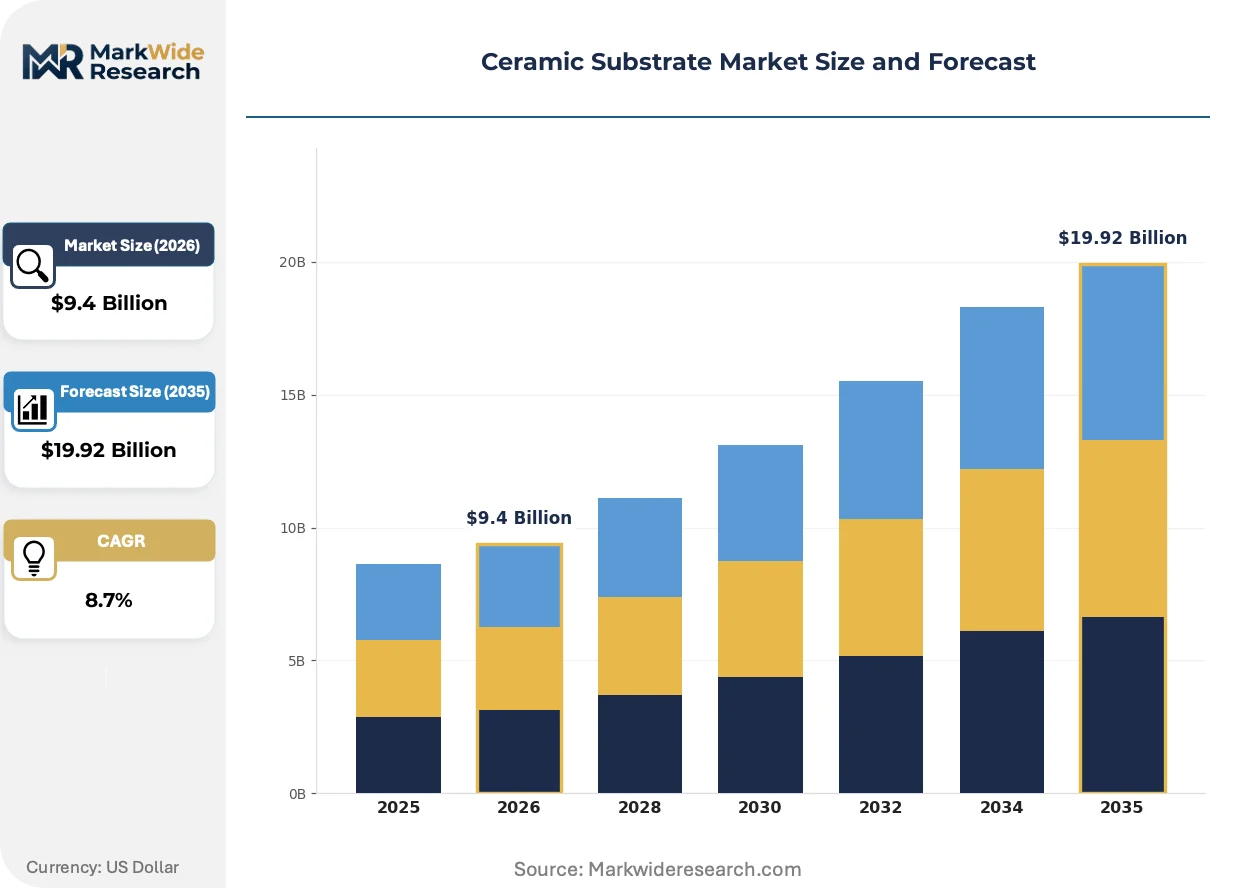
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $19.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Aluminum Nitride, Silicon Nitride, Cordierite, Zirconia Technology: Thick Film, Thin Film, Low Temperature Cofired Ceramic, High Temperature Cofired Ceramic, Multilayer Ceramic Application: Power Modules, LED Lighting, RF Devices, Medical Equipment, Telecommunication Devices End User: Consumer Electronics, Semiconductor Manufacturers, Renewable Energy Firms, Aerospace Engineers, Defense Contractors |
| Companies Covered | KYOCERA Corporation, Murata Manufacturing Co., Ltd., CoorsTek Inc., CeramTec GmbH, Rogers Corporation, NGK Insulators Ltd., MARUWA Co., Ltd., Toshiba Materials Co., Ltd., CTS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Substrate Market Strategic Shifts & Innovations
Material science advancements are enabling ceramic substrates to meet increasingly specific performance requirements from end-markets. Innovations focus on enhancing thermal conductivity, mechanical strength, and high-frequency performance to support next-generation electronics in automotive, telecommunications, and industrial applications.
Silicon nitride substrates provide superior fracture toughness and thermal shock resistance compared to other ceramics. Automotive manufacturers are adopting them for power modules in electric vehicle inverters, where rapid temperature changes create extreme mechanical stress. This advanced material is displacing direct bonded copper (DBC) on alumina substrates in high-reliability applications where thermal cycling performance is paramount.
Environmental regulations, including the EU's RoHS directive, limit the use of lead and other hazardous materials in electronic assemblies. This mandate compels a shift to lead-free solders, which require higher processing temperatures during component assembly. Substrate materials, especially alumina and aluminum nitride, must demonstrate compatibility and maintain structural integrity at these elevated temperatures, driving material and process innovations.
A notable shift in buyer behavior prioritizes substrates with proven compliance and extensive reliability data tied to specific industry standards. This trend favors suppliers capable of providing comprehensive documentation for certifications like the automotive AEC-Q100 or global ISO quality standards. This is most visible in the automotive and aerospace sectors, where procurement choices are increasingly influenced by documented performance rather than cost alone.
Ceramic Substrate Market Segmentation
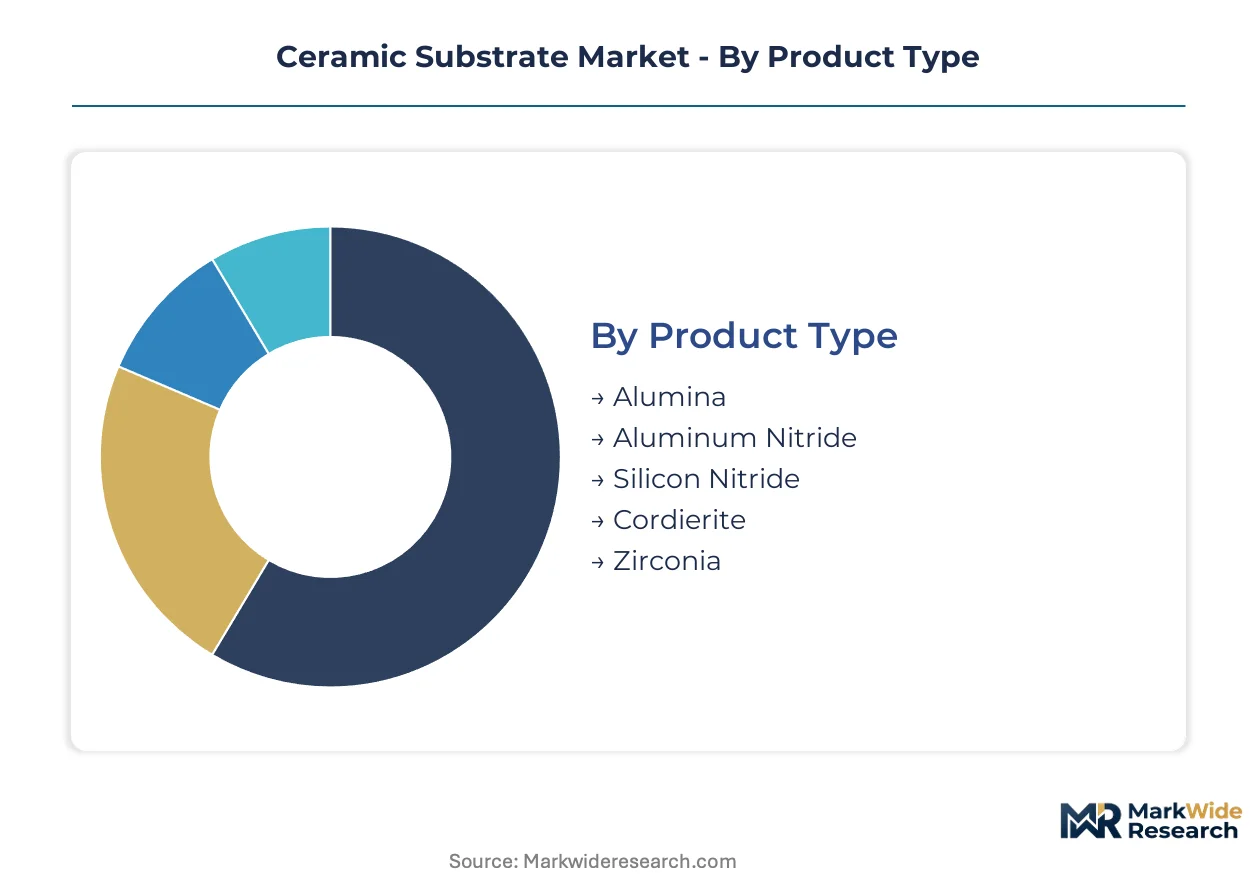
Understanding the ceramic substrate market through segmentation reveals the diverse performance requirements and evolving material preferences across various end-use sectors. This granular view highlights the specific material and technological advancements driving adoption in high-growth applications, while also identifying segments facing competitive pressures.
Product Type:
The product type segmentation highlights areas where material innovation creates substitution pressure, particularly as advanced ceramics displace traditional options in high-performance applications.
- Alumina:A cost-effective ceramic material offering good electrical insulation and thermal conductivity. Alumina remains the volume leader in general electronics, automotive sensors, and industrial power applications.
- Aluminum Nitride:Characterized by high thermal conductivity and excellent electrical insulation, making it suitable for demanding thermal management. Demand concentrates in semiconductor manufacturing equipment and advanced packaging in Japan and South Korea, where heat dissipation is critical.
- Silicon Nitride:Provides superior fracture toughness, thermal shock resistance, and mechanical strength, crucial for extreme environments. Demand concentrates in electric vehicle power modules for high-reliability inverters and on-board chargers, displacing traditional direct bonded copper on alumina.
- Cordierite:Known for its low thermal expansion coefficient and good dielectric properties. It finds application in catalytic converters and specific microwave components.
- Zirconia:Offers high mechanical strength, wear resistance, and biocompatibility. Zirconia is increasingly used in implantable medical devices and specialized industrial wear parts.
Alumina anchors the volume base while silicon nitride gains share at the steepest rate.
Technology:
The technology segmentation differentiates substrate manufacturing processes based on integration complexity and target application requirements.
- Thick Film:A mature manufacturing process involving the screen printing of conductive, resistive, and dielectric pastes onto a ceramic substrate. Thick film technology is widely used in automotive sensors, hybrid circuits, and power resistors due to its cost-effectiveness.
- Thin Film:Utilizes precise deposition techniques like sputtering or evaporation to create fine line circuits and high-density interconnects. Thin film technology is critical for high-frequency applications, medical devices, and optical components requiring superior precision.
- Low Temperature Cofired Ceramic (LTCC):Enables the integration of passive components like resistors, capacitors, and inductors within a multilayer ceramic structure. Demand accelerates for integrated RF devices in 5G telecommunication infrastructure and compact wireless modules due to its low signal loss.
- High Temperature Cofired Ceramic (HTCC):Sintered at high temperatures, creating robust and hermetic packages for harsh environments. HTCC is applied in high-power electronics, sensors, and aerospace applications.
- Multilayer Ceramic:Allows for high-density component integration and miniaturization by stacking multiple ceramic layers. This technology is essential for telecommunication devices and consumer electronics requiring compact and complex modules.
Thick film technology remains foundational, but multilayer ceramic and LTCC drive innovation for miniaturized electronic systems.
Application:
The application segmentation highlights where ceramic substrates offer critical performance advantages, particularly in thermal management and signal integrity.
- Power Modules:These applications require exceptional thermal conductivity and electrical insulation to dissipate heat generated by high-power semiconductors. Demand concentrates in electric vehicles and renewable energy inverters, ensuring component reliability and longevity.
- LED Lighting:Ceramic substrates provide efficient thermal management for high-brightness light-emitting diodes, extending device lifespan and improving performance. This application is crucial for automotive headlights and industrial illumination systems.
- RF Devices:Demands low signal loss, stable dielectric properties, and precise impedance control at high frequencies. Demand concentrates in 5G infrastructure, satellite communication systems, and radar technology.
- Medical Equipment:Requires biocompatibility, high reliability, and miniaturization for sensitive and often implantable devices. This includes applications in pacemakers, diagnostic tools, and surgical instruments.
- Telecommunication Devices:Supports high-frequency signal transmission, component integration, and compact designs. Ceramic substrates are essential for smartphones, base stations, and other network equipment.
Power modules represent a significant growth area, while RF devices drive demand for specialized high-frequency substrate solutions.
End User:
The end-user segmentation reflects varying investment intensity and regulatory requirements across industries adopting ceramic substrate technologies.
- Consumer Electronics:This volume-driven segment requires cost-effective and miniaturized substrate solutions for mass-market products. Ceramic substrates are found in smartphones, tablets, and wearable devices for thermal management and integration.
- Semiconductor Manufacturers:Requires high-purity, thermally stable, and electrically insulating substrates for advanced chip packaging and manufacturing equipment. Demand concentrates in manufacturing hubs in South Korea and Taiwan for advanced process nodes.
- Renewable Energy Firms:Utilizes ceramic substrates for power inverters, converters, and control modules in solar and wind energy systems. This sector drives demand for high thermal conductivity materials to manage power electronics.
- Aerospace Engineers:Demands extreme reliability, radiation resistance, and lightweight solutions for critical avionics, radar systems, and satellite communication. This sector focuses on specialized materials and rigorous certification.
- Defense Contractors:Requires robust, high-performance substrates for radar systems, electronic warfare, and secure communication devices. This end-user segment prioritizes secure supply chains and advanced material capabilities.
Semiconductor manufacturers and aerospace engineers prioritize performance, while consumer electronics focuses on cost and volume efficiencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between Asian manufacturing hubs and European high-performance application centers. South Korea and Japan command significant influence in semiconductor substrate production, while Germany drives demand for advanced silicon nitride in automotive power modules.
Germany
Demand for silicon nitride substrates is strong in Germany, driven by electric vehicle power modules and industrial electronics. Reliability testing protocols mandated by Germany's KBA influence material selection for automotive components. The Stuttgart region, home to major automotive manufacturers, concentrates advanced ceramic substrate procurement for EV inverters.
Japan
Japan experiences sustained demand for high-purity alumina and aluminum nitride substrates from its robust semiconductor manufacturing equipment sector. METI policies support domestic material science innovation and high-tech component production. Kyoto and Osaka are key centers for advanced ceramic material development and fabrication, serving global electronics supply chains.
South Korea
Advanced semiconductor packaging and telecommunication infrastructure drive demand for aluminum nitride and LTCC substrates in South Korea. The MFDS influences medical device material standards, expanding specialized ceramic use. Pyeongtaek and Gyeonggi Province, major semiconductor hubs, require high-volume, high-performance ceramic substrates for chip fabrication and assembly.
United States
Aerospace and defense sectors, alongside localized semiconductor supply chain initiatives, create demand for specialized, high-reliability ceramic substrates in the United States. Policy initiatives like the CHIPS Act encourage domestic manufacturing capacity for advanced materials. Silicon Valley and the Boston corridor, technology and biotech clusters, foster innovation in thin film and LTCC applications.
China
China's expanding electric vehicle market and telecommunication infrastructure fuel demand for both cost-effective alumina and advanced nitride ceramics. Compliance with GB standards for electronic components shapes material specifications for domestic suppliers. The Yangtze River Delta region, a major electronics manufacturing base, sees significant investment in ceramic substrate production for diverse applications.
Ceramic Substrate Market Key Industry Players
Concentration sits with diversified material producers possessing extensive in-house capabilities, alongside specialized fabricators focusing on niche, high-performance applications. The market structure exhibits a tiered approach, with volume leaders in alumina and innovation-driven players in advanced nitrides. Dominant competitive moves include strategic partnerships for raw material supply and targeted capacity expansion for next-generation materials like silicon nitride.
Among diversified material producers, KYOCERA Corporation exemplifies a vertically integrated model, leveraging its extensive raw ceramic powder production. Murata Manufacturing Co., Ltd. represents a global leader in multilayer ceramic technologies, anchoring the telecommunication devices segment with its specialized offerings. CoorsTek Inc. occupies a position as a specialist in advanced technical ceramics, serving high-stress applications in aerospace and defense sectors.
| Leading Market Players |
|---|
| KYOCERA Corporation |
| Murata Manufacturing Co., Ltd. |
| CoorsTek Inc. |
| CeramTec GmbH |
| Rogers Corporation |
| NGK Insulators Ltd. |
| MARUWA Co., Ltd. |
| Toshiba Materials Co., Ltd. |
| CTS Corporation |
| Others |
Cost & Logistics Intelligence
Silicon nitride displacing alumina substrates simultaneously reshapes supply geography towards specialized producers and alters pricing economics due to higher manufacturing complexities. This material substitution drives a performance-cost tension across the market.
Pricing Analysis
Configured-to-order pricing for specialized nitride substrates commands a premium over standard alumina components. The dominant pricing model remains per-unit transactional, often under long-term contracts for high-volume buyers. Price differentiation stems from material quality grade, adherence to ISO standards, and customization for specific application requirements. Pricing pressure intensifies for alumina substrates due to alternative material competition, while advanced nitrides maintain premium pricing due to high manufacturing costs. Consumer electronics buyers exhibit the highest price sensitivity, whereas aerospace and defense sectors prioritize performance over cost.
Supply Chain Analysis
Strategic-stockpile preferences are evident for critical high-purity ceramic powders, while just-in-time practices manage finished substrate inventory for high-volume orders. Geographic supply concentrates in Japan, South Korea, and China for advanced ceramic substrates. The market sources high-purity alumina, aluminum nitride, and silicon nitride powders from a few key producers. Raw material supply concentration creates commodity price volatility and potential bottlenecks for fabricators. Distribution runs through direct sales channels to large OEMs and specialized distributors serving niche application segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceramic substrate market presents a significant service-attach opportunity. Specialized material consulting and reliability testing services are expanding faster than physical substrate sales, driven by complex application requirements.
For Market Incumbents: Fortify existing market leadership by investing heavily in next-generation silicon nitride production capacity. Strengthen long-term raw material supply agreements to mitigate price volatility and supply chain risks. This defends against competition from alternative materials like insulated metal substrates in mid-power applications. Prioritize R&D in advanced material formulations and secure critical certifications like automotive AEC-Q100 for high-reliability applications.
For New Entrants and Emerging Players: Specialized material characterization and rapid prototyping services represent a significant service-layer gap where incumbents under-serve. Target underpenetrated markets like implantable medical devices and specialized aerospace electronics with high-reliability zirconia and alumina. The most penetrable segment involves high-frequency RF devices requiring custom low temperature cofired ceramic (LTCC) modules. Offer integrated design-to-manufacturing solutions to accelerate customer product development cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier specialized substrate fabricators focusing on advanced nitrides or LTCC technologies. The market demonstrates strong long-term viability over the next 5-10 years, driven by electric vehicle and 5G infrastructure expansion. Target acquisition profiles include companies with proprietary silicon nitride intellectual property or advanced multilayer ceramic manufacturing capabilities. Increased capital expenditure announcements for next-generation material production lines serve as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Silicon Nitride | Addresses growing demand from electric vehicle power modules, enhancing thermal management in critical automotive components. |
| Raw Material Supply Chain Vertical Integration | Secures access to high-purity ceramic powders, mitigating price volatility for advanced substrate manufacturers. |
| Investment in LTCC Technology R&D | Supports miniaturization and integration of RF devices, crucial for 5G telecommunication infrastructure development. |
| Partnerships for Automotive Certification | Ensures compliance with rigorous standards like Germany's KBA, accelerating adoption in high-reliability automotive electronics. |
| Geographic Expansion into Semiconductor Hubs | Establishes proximity to major semiconductor manufacturers in South Korea and Japan, serving advanced packaging requirements. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and comprehensive secondary research. Primary insights came from R&D directors, procurement managers, product development engineers, and regulatory compliance officers across the value chain. Secondary data sources included industry association reports, government publications from METI and KBA, company financial statements, and technical journals. This approach enabled robust bottom-up and top-down triangulation of market data.
The forecasting framework established clear boundaries for market projections across the analysis window. A quantitative model integrated historical data with identified growth drivers and restraints. Market segmentation covered product type, technology, application, and end user. Compound annual growth rates derived from regression analysis of historical trends and projected future demand, using electric vehicle production and 5G infrastructure deployment as key inputs.
Underlying assumptions cover global economic stability and adherence to current technological roadmaps, with deviation risk concentrated in geopolitical shifts. Forecasts reflect these assumptions. Raw material supply disruptions or significant regulatory changes could impact market trajectories. Revision becomes warranted when these conditions cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Colloidal Alumina Market
Ceramics
Strontium Carbonate Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Ceramics Packaging Market
Ceramics
White Fused Alumina Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Zeolite 4A Market
Ceramics
High Temperature Ceramics Market
Ceramics
Kaolin Market
Ceramics
Automotive Ceramics Market
Ceramics
India Kaolin Market
Ceramics
Global Ceramic Foams Market