
 Colloidal Alumina Market | 2026-2036
Colloidal Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
Colloidal Alumina Market Outlook
Technical service contracts for particle-size calibration and slurry reformulation is rebalancing how buyers procure colloidal alumina, shifting value from commodity tonnage to performance guarantees. Sasol Limited leverages its integrated alumina refining network to sustain supply security for European coating customers. Nippon Light Metal Co., Ltd. anchors its position through proprietary hydrothermal synthesis routes that yield narrow particle distributions. Nissan Chemical Corporation differentiates via dedicated biotech application laboratories in Japan.
Colloidal alumina consists of sub-micron aluminum oxide particles dispersed in aqueous or organic media, typically manufactured through controlled hydrolysis of aluminum alkoxides or precipitation from aluminum salt solutions, with particle sizes ranging from 2 to 500 nanometers depending on end-use requirements. The material functions primarily as a polishing abrasive, ceramic binder, and coating additive where surface finish precision determines product performance. High purity grades command premium positioning in electronics applications where trace metal contamination degrades semiconductor yield, while coated variants are gaining structural share in biotechnology as diagnostic substrate demand rises. Ceramics remains the mature volume anchor, though electronics applications carry disproportionate margin contribution due to qualification barriers and technical service intensity.
REACH registration requirements in Europe, EPA chemical data reporting in the United States, and China's GB standards for nanomaterial classification collectively elevate compliance costs and favor suppliers with dedicated regulatory affairs capabilities. Japan's METI guidelines on chemical substance management add another layer of documentation burden for imported colloidal alumina formulations. Stakeholders must monitor how evolving nanomaterial disclosure rules across multiple jurisdictions reshape product labeling obligations and customer qualification timelines.
Market Dynamics
Semiconductor fabrication clusters are consolidating procurement authority around performance-guaranteed slurry formulations rather than commodity alumina tonnage, compressing supplier margins while elevating technical service intensity as the primary competitive battleground.
Growth Catalysts
- REACH registration tiering:ECHA's differentiated data requirements for nanomaterial volumes below 100 tons annually reduce entry barriers for specialty colloidal alumina grades targeting European coating applications.
- Memory chip foundry expansion:South Korea's Pyeongtaek and Yongin corridors are commissioning new polishing lines that specify sub-50 nanometer particle distributions for 3D NAND wafer planarization.
- Hydrothermal synthesis advancement:Continuous flow reactor designs are narrowing particle size coefficient of variation from 15% to below 8%, enabling direct qualification for logic device CMP processes previously reserved for fumed silica alternatives.
Market Restraints
- High-purity aluminum alkoxide feedstock concentration:Three German chemical producers control over 70% of electronics-grade precursor supply, creating vulnerability for formulated slurry manufacturers.
- Energy cost asymmetry:Natural gas price differentials between European hydrothermal processing facilities and Middle Eastern competitors exceed 40%, eroding margin sustainability for EU-based alumina refiners.
- Fumed silica substitution in shallow trench isolation:Cabot Microelectronics and Fujifilm have secured design-in status for select 28nm node polishing steps, displacing colloidal alumina in one high-volume application.
Strategic Opportunities
- Biotech diagnostic substrate penetration:Uncoated colloidal alumina nanoparticles are displacing gold colloids in lateral flow immunoassay manufacturing, with Japan's diagnostic reagent houses leading formulation partnerships.
- China GB/T nanomaterial disclosure alignment:Early compliance with SAMR's 2025 labeling requirements positions foreign suppliers for preferred vendor status with state-owned semiconductor foundries.
- Reformulation-as-a-service contracts:Slurry optimization subscriptions tied to wafer yield outcomes are capturing 15-20% price premiums over spot alumina purchases in Taiwan's packaging substrate sector.
Industry Challenges
- Particle metrology talent scarcity:Dynamic light scattering and disk centrifuge operation expertise concentrates among retired semiconductor process engineers, constraining quality control scaling for mid-tier suppliers.
- Dual-use export control alignment:BIS Entity List restrictions on certain high-purity chemical precursors complicate supply chain documentation for US-based formulators serving Chinese foundry customers.
- Legacy slurry qualification lock-in:Established CMP process recipes at Intel and TSMC require 18-24 month requalification cycles, delaying adoption of improved alumina particle morphologies despite demonstrated performance gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colloidal Alumina Market |
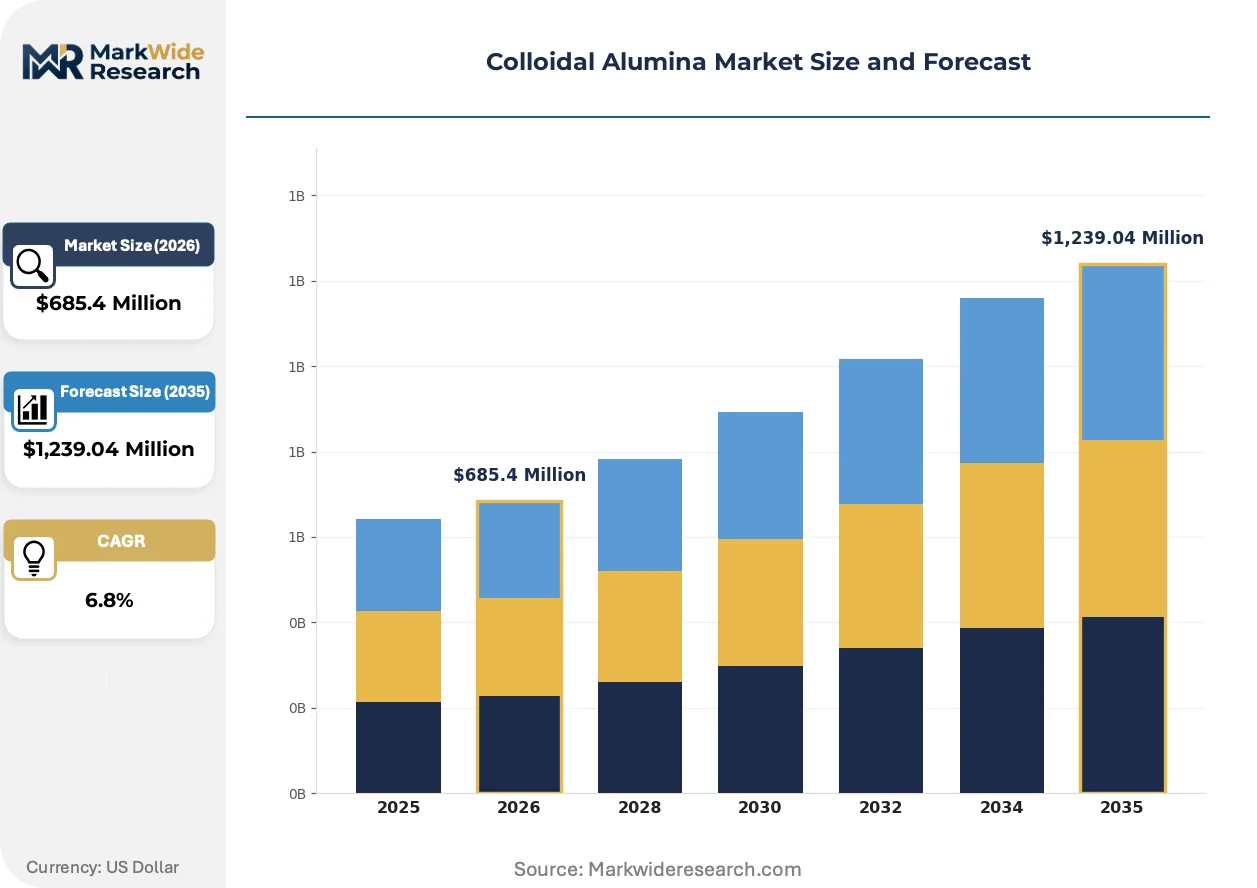
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Low Purity, Coated, Uncoated Application: Ceramics, Coatings, Biotechnology, Electronics End User: Aerospace, Automotive, Healthcare, Petrochemical Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Sasol Limited, Cabot Corporation, Almatis, Nippon Light Metal Co., Ltd., W.R. Grace & Co., Nabaltec AG, Nissan Chemical Corporation, BASF SE, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colloidal Alumina Market Strategic Shifts
Colloidal alumina manufacturing is pivoting from batch hydrothermal synthesis toward continuous processing architectures, while regulatory nanomaterial classifications and buyer procurement centralization are simultaneously reshaping competitive positioning across electronics and life science verticals.
Surface-functionalized alumina particles with tailored zeta potentials are converging with advanced CMP slurry delivery systems that modulate abrasive concentration in real-time during wafer polishing. Samsung Electronics and SK Hynix are piloting these integrated process control architectures at their Pyeongtaek campuses. The technology is converging with yield management software platforms, compressing the traditional separation between abrasive suppliers and semiconductor equipment vendors into unified process solutions.
Japan's METI revised its Chemical Substances Control Law guidance in 2024 to mandate nanomaterial-specific safety data sheets for colloidal alumina imports exceeding 1 ton annually. The regulation forces foreign suppliers to establish in-country analytical testing partnerships or face 90-day customs delays. Electronics-grade alumina importers are responding by pre-positioning inventory at Yokohama bonded warehouses and accelerating JIS-compliant particle characterization investments.
Consolidated procurement desks at Taiwan Semiconductor Manufacturing and GlobalFoundries are unbundling technical service contracts from base chemical supply agreements. Formerly integrated slurry formulations are now sourced as separable components—alumina abrasive, dispersant chemistry, and application engineering—with distinct vendor selection criteria. This restructuring is most visible in Singapore's wafer fabrication park, where foundry procurement teams maintain parallel qualification tracks for commodity alumina suppliers and specialized CMP process consultants.
Colloidal Alumina Market Segmentation
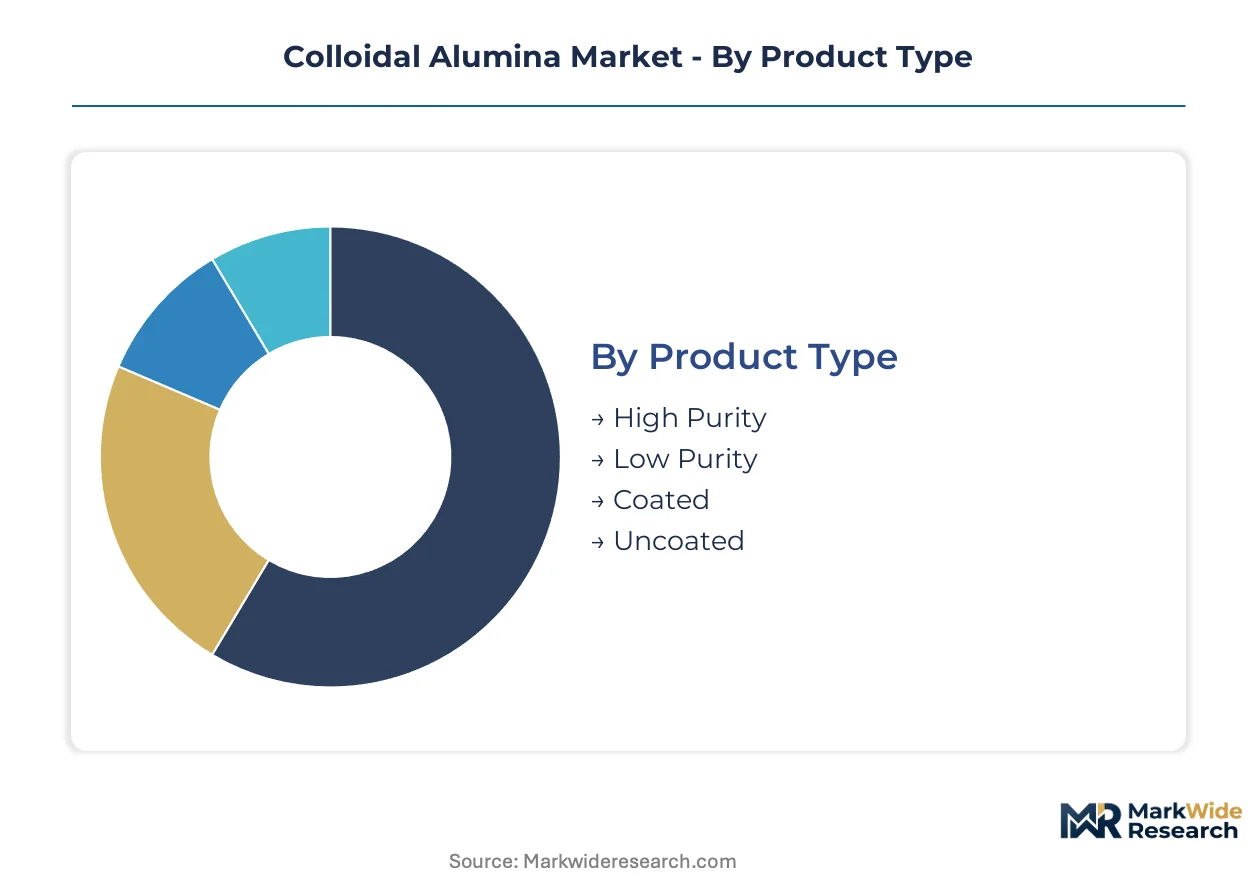
Colloidal alumina procurement patterns diverge sharply between commodity-grade volume plays and specification-driven premium tiers. Semiconductor foundries and biotech diagnostic houses now source through entirely separate qualification tracks, fragmenting what once operated as a unified chemical market.
Product Type:
Volume concentration rests with standard purity grades, while margin capture concentrates in electronics-certified and surface-modified variants.
- High Purity:Sub-100 ppm total trace metal content, manufactured via aluminum alkoxide hydrolysis under cleanroom conditions. South Korea's memory foundry corridor commands the dominant share, driven by 3D NAND planarization specifications that reject particle contamination above 50 parts per billion.
- Coated:Surface-functionalized with silanes or phosphonates to control zeta potential in biological buffers. Japan's diagnostic reagent manufacturers are expanding coated alumina procurement for lateral flow immunoassay substrates, displacing legacy gold colloid labels on cost-performance grounds.
- Low Purity:Technical grades serving ceramic binders and refractory applications where trace metal tolerance exceeds 500 ppm. Standard industrial coatings and structural ceramics absorb steady tonnage at compressed margins.
- Uncoated:Bare nanoparticle dispersions requiring end-user stabilization. Research laboratories and specialty coating formulators represent the primary demand nodes.
Mature deployment sits with Low Purity grades in industrial ceramics. Newer deployment is concentrated in High Purity segments for semiconductor polishing.
Application:
End-use economics separate legacy material consumption from emerging specification markets.
- Electronics:Chemical mechanical planarization slurries for wafer polishing, requiring sub-50 nanometer particle distributions with coefficient of variation below 8%. Taiwan's packaging substrate sector is pioneering outcome-based slurry subscriptions tied to die yield metrics.
- Biotechnology:Diagnostic substrates, chromatography media, and drug delivery vectors. Uncoated alumina nanoparticles are climbing the fastest in lateral flow assay manufacturing as Japanese reagent houses reformulate away from precious metal labels.
- Ceramics:Binder applications for structural alumina and refractory shapes. Traditional ceramic processing absorbs baseline volume through established distributor relationships.
- Coatings:Hardcoat and anti-corrosive surface treatments. Automotive and aerospace finishing lines specify colloidal alumina for scratch resistance in clearcoat formulations.
Established revenue anchors in Ceramics face margin compression. Biotechnology applications are gaining share fastest on diagnostic substrate demand.
End User:
Customer sophistication determines whether procurement flows through commodity distributors or technical service partnerships.
- Healthcare:Diagnostic device manufacturers and pharmaceutical formulation houses. Regulatory compliance with FDA and EMA nanomaterial disclosure rules elevates supplier documentation burdens.
- Aerospace:Thermal barrier coating applicators and precision finishing operations. Stringent lot traceability requirements favor qualified supplier relationships over spot purchasing.
- Automotive:Clearcoat formulators and ceramic component suppliers. Volume procurement concentrates through integrated coating chemical distributors.
- Petrochemical:Catalyst support manufacturing and refinery process applications. Standard industrial grades dominate with price-sensitive tender processes.
Contractual stability characterizes Healthcare procurement. Automotive purchasing patterns show the steepest shift toward technical service bundling.
Distribution Channel:
Channel selection reflects customer scale and formulation complexity requirements.
- Direct Sales:Foundry-qualified slurry formulations and high-volume ceramic contracts. Samsung Electronics and SK Hynix maintain dedicated technical service agreements with primary alumina refiners.
- Distributors:Mid-tier coating houses and regional ceramic processors. Inventory pre-positioning at Yokohama bonded warehouses accelerates Japanese customs clearance.
- Online:Research-grade samples and small-batch specialty formulations. Academic laboratories and pilot-scale biotech operations source through e-commerce portals.
- Retail:Limited to hobbyist ceramics and educational supply channels. Negligible commercial relevance for industrial-grade material.
Direct relationships dominate semiconductor procurement. Distributor intermediation persists in fragmented coating and ceramic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and Japan, while consumption gravity sits with South Korean and Taiwanese semiconductor foundries. Chinese ceramic processors absorb steady industrial-grade tonnage. This geographic split creates freight-cost arbitrage and regulatory compliance layering across supply chains.
South Korea
Memory chip foundries at Pyeongtaek and Yongin specify sub-50 nanometer colloidal alumina for 3D NAND planarization. The Ministry of Trade, Industry and Energy enforces nanomaterial reporting under K-REACH amendments. Samsung Electronics maintains dedicated technical service agreements with primary alumina refiners for slurry qualification.
Japan
Diagnostic reagent manufacturers in Osaka and Tokyo reformulate lateral flow immunoassays using coated alumina nanoparticles. METI revised Chemical Substances Control Law guidance in 2024 to mandate nanomaterial-specific safety data sheets. Importers pre-position inventory at Yokohama bonded warehouses to accelerate customs clearance.
Germany
Three chemical producers near Ludwigshafen control over 70% of electronics-grade aluminum alkoxide precursor supply. ECHA's REACH registration tiering reduces entry barriers for specialty colloidal alumina grades below 100 tons annually. Bayer and BASF legacy sites anchor European hydrothermal processing capacity despite energy cost pressures.
United States
EPA chemical data reporting elevates documentation burdens for formulated slurry manufacturers serving Intel and GlobalFoundries. BIS Entity List restrictions on high-purity precursors complicate supply chain documentation for US-based formulators. Arizona and Oregon fabrication clusters drive specification-grade demand.
China
State-owned semiconductor foundries prioritize suppliers with early SAMR GB/T nanomaterial disclosure alignment. GB standards for nanomaterial classification reshape product certification requirements. Yangtze River Delta ceramic processors absorb baseline industrial-grade tonnage at compressed margins.
Colloidal Alumina Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the colloidal alumina value chain. Integrated alumina refiners with captive precursor supply command supply security premiums, while specialized slurry formulators capture technical service margins. Three strategic archetypes dominate: integrated chemical conglomerates with backward control over aluminum alkoxide supply, dedicated colloidal material specialists with proprietary synthesis routes, and formulated slurry vendors bundling abrasive supply with process engineering. Competitive moves concentrate on continuous flow reactor investments and reformulation-as-a-service contract structures.
Among integrated chemical conglomerates, BASF SE and Solvay SA represent the scale-driven archetype with diversified material portfolios. Sasol Limited anchors the integrated refining position with European coating customer relationships. Nippon Light Metal Co., Ltd. and Nissan Chemical Corporation exemplify the dedicated specialist tier, occupying positions defined by synthesis route specialization and application laboratory investments. These five entities collectively illustrate the competitive tension between commodity tonnage and performance-guaranteed procurement models reshaping buyer-supplier relationships.
| Leading Market Players |
|---|
| Sasol Limited |
| Cabot Corporation |
| Almatis |
| Nippon Light Metal Co., Ltd. |
| W.R. Grace & Co. |
| Nabaltec AG |
| Nissan Chemical Corporation |
| BASF SE |
| Solvay SA |
| Others |
Value Chain & Pricing Dynamics
Backward integration into aluminum alkoxide precursor production anchors supply security for European refiners while simultaneously insulating pricing power against feedstock volatility. German chemical producers leverage captive hydrothermal processing capacity to command premium positioning in electronics-grade colloidal alumina, whereas non-integrated formulators absorb margin compression from concentrated precursor supply.
Pricing Analysis
Margin tightening in high-purity grades reflects the 70% supply concentration of electronics-grade aluminum alkoxide among three German producers. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-certified material from industrial ceramic grades. Pricing pressure intensifies in commodity tonnage as South Korean foundries consolidate procurement around performance-guaranteed slurry subscriptions. Petrochemical and standard ceramic buyers exhibit highest price sensitivity, while memory chip fabricators prioritize yield outcomes over unit cost.
Supply Chain Analysis
Return flows of spent polishing slurry for metal recovery and alumina reclamation are emerging at Taiwan packaging substrate facilities, creating reverse logistics infrastructure. Manufacturing gravity centers on Germany and Japan for hydrothermal synthesis capacity, while consumption concentrates in South Korea and Taiwan. Feedstock supply draws from aluminum alkoxide hydrolysis and aluminum salt precipitation routes. Single-source vulnerability pervades electronics-grade precursor supply. Distribution runs through direct technical service agreements for foundry-qualified slurry and bonded warehouse intermediation for Japanese diagnostic reagent houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration tiering and nanomaterial disclosure mandates across Europe, Japan, and China erect compliance moats that favor incumbents with dedicated regulatory affairs capabilities and in-country testing partnerships.
For Market Incumbents: To counter fumed silica substitution in shallow trench isolation applications, BASF and Solvay should deepen captive aluminum alkoxide supply through Ludwigshafen corridor capacity protection, while accelerating continuous flow reactor investments to narrow particle size coefficient of variation below 8% for logic device CMP qualification. For New Entrants and Emerging Players: Biotech diagnostic substrate formulators in Japan represent the most penetrable buyer archetype, as lateral flow immunoassay manufacturers actively displace gold colloid labels with coated alumina nanoparticles on cost-performance grounds. New entrants should pursue formulation partnerships with Osaka and Tokyo reagent houses, leveraging surface-functionalization expertise to secure initial qualification slots. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking backward integration into colloidal material synthesis. Long-term viability hinges on qualification lock-in at Samsung Electronics and SK Hynix, with reformulation-as-a-service contract penetration serving as the critical inflection signal for technical service margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Investment | Narrowing particle size distribution below 8% coefficient of variation enables logic device CMP qualification previously reserved for fumed silica alternatives. |
| Reformulation-as-a-Service Contracts | Outcome-based slurry subscriptions tied to wafer yield metrics capture 15-20% price premiums over spot alumina purchases in Taiwan. |
| Backward Integration into Precursor Supply | Captive aluminum alkoxide production insulates margin sustainability against the 70% supply concentration among German chemical producers. |
| GB/T Nanomaterial Disclosure Alignment | Early compliance with SAMR labeling requirements positions foreign suppliers for preferred vendor status with Chinese state-owned foundries. |
| Biotech Application Laboratory Investment | Dedicated facilities in Japan accelerate coated alumina qualification for lateral flow immunoassay substrates displacing gold colloids. |
Study Parameters
Document review covered ECHA REACH registration databases, METI Chemical Substances Control Law guidance, and SAMR GB/T nanomaterial standards, complemented by interviews with hydrothermal process engineers, semiconductor slurry procurement managers at Samsung Electronics and TSMC, diagnostic reagent formulation scientists in Osaka, and European coating chemical distributors. Secondary validation drew from SEC 10-K filings of listed chemical producers, Japanese customs trade statistics, and Korean Ministry of Trade import records. Bottom-up capacity modeling triangulated against top-down consumption estimates from foundry wafer start projections.
Segment-level outputs across the analysis window reflect discrete modeling of high purity, coated, low purity, and uncoated product tiers intersecting with electronics, biotechnology, ceramics, and coatings applications. CAGRs were derived from elasticity-adjusted demand functions incorporating semiconductor capital expenditure cycles and diagnostic substrate reformulation timelines. Forecast inputs included 3D NAND layer count trajectories, lateral flow assay manufacturing growth, and REACH registration tier evolution.
Revisions become necessary when semiconductor node transition timelines accelerate, nanomaterial disclosure thresholds tighten unilaterally, or fumed silica technical advances displace colloidal alumina in additional CMP steps. Forecasts embed assumptions regarding K-REACH enforcement consistency, energy cost differentials between European and Middle Eastern processing facilities, and qualification cycle durations at Intel and TSMC. Practitioners should monitor South Korean memory foundry capital expenditure announcements, METI guidance updates on nanomaterial safety data sheet requirements, and BIS Entity List expansion for precursor export controls as early signals warranting forecast reassessment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Potassium Feldspar Market
Ceramics
Pottery Ceramics Market
Ceramics
Ceramic Ware Market
Ceramics
Ceramic Kilns Market
Ceramics
Ceramic Frit Market
Ceramics
Alumina Slurry Market
Ceramics
Global Ceramic Balls Market
Ceramics
Porous Ceramic Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Kaolin Market
Ceramics
Spain Ceramic Tiles Market
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
Europe Activated Alumina Market
Ceramics
Southeast Asia Melamine Market